
 Embedded Power Generation Market | 2026-2036
Embedded Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Power Generation Market Insights
Aftermarket service revenue is tilting toward predictive maintenance contracts and remote monitoring platforms as OEMs seek recurring income streams. Caterpillar leverages its dealer network density to sustain long-term service agreements across mining and data center installations. Siemens anchors its position through digital twin integration for embedded gas turbine fleets. Wärtsilä differentiates via energy storage hybridization, pairing reciprocating engines with battery systems for frequency regulation.
Embedded power generation denotes self-contained electricity production systems integrated directly at the point of consumption, typically employing reciprocating engines, gas turbines, fuel cells, or photovoltaic arrays rated from sub-kilowatt to multi-megawatt output, with heat recovery configurations achieving total energy efficiencies exceeding 80 percent in combined heat and power mode. These systems serve critical functions where grid reliability proves inadequate or where thermal and electrical loads coexist in industrial, commercial, or institutional settings. Diesel generators and gas-fueled reciprocating engines retain dominant installed base positions across the technology segment, though fuel cell installations are gaining fastest in premium uptime applications where emissions constraints tighten. The industrial end user category commands the deepest margin pools due to continuous operating profiles and customized engineering requirements, while portable installations expand most rapidly in disaster response and remote construction markets.
The EPA regulates stationary reciprocating internal combustion engines under 40 CFR Part 60 Subpart JJJJ, compelling embedded generator operators toward lower-emitting models or exhaust aftertreatment retrofits that reshape equipment replacement cycles. ISO 8528 governs transient response and load acceptance standards for generator set performance, creating compliance barriers for entrants lacking certified test facilities. Stakeholders must monitor evolving carbon border adjustment mechanisms and state-level clean energy mandates that will redefine competitive economics between fossil-fueled and zero-carbon embedded generation alternatives.
Market Dynamics
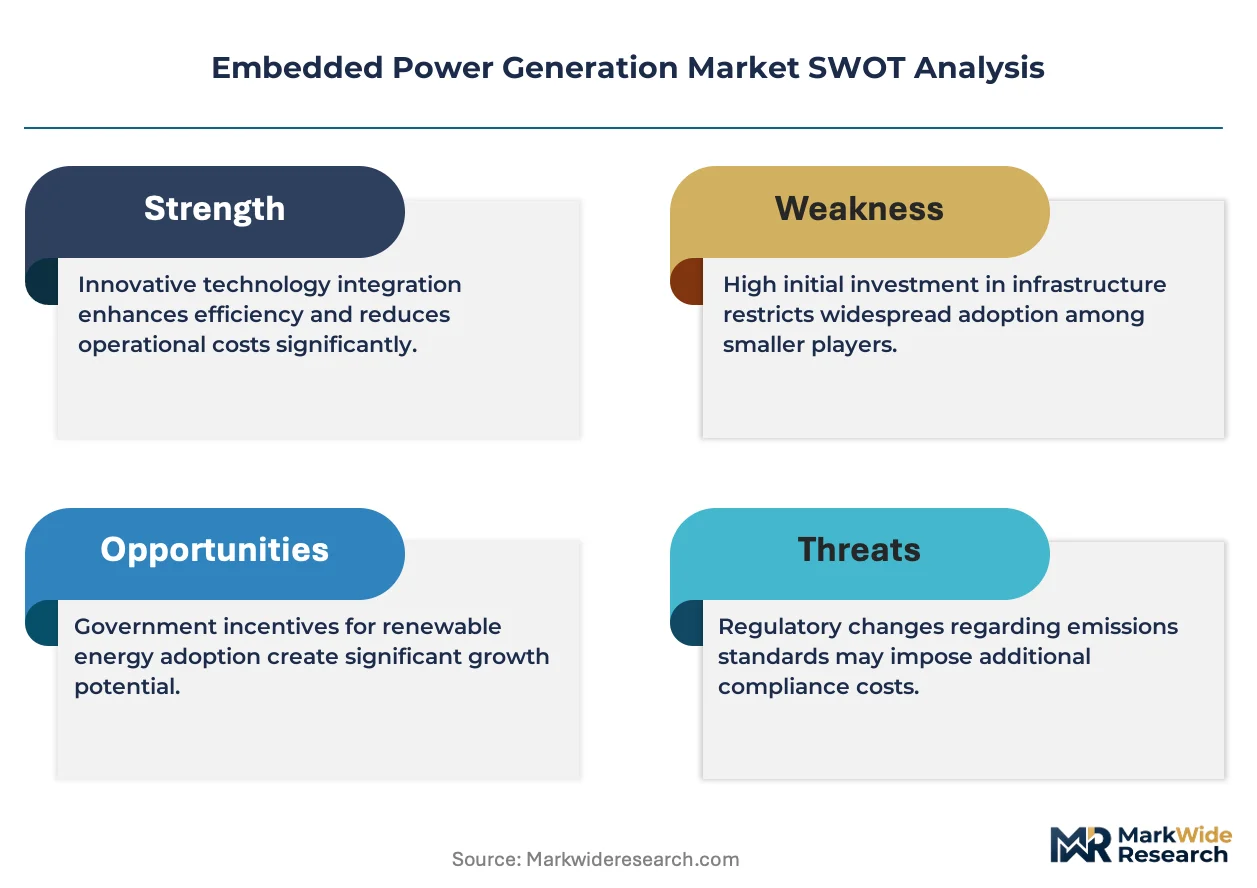
Grid interconnection queue delays exceeding five years in key US markets are forcing data center operators and industrial facilities toward captive generation architectures, compressing procurement cycles for reciprocating engines and solid oxide fuel cells while elevating hybrid system specifications.
Growth Catalysts
- EPA Stationary Engine Standards:Updated 40 CFR Part 60 Subpart JJJJ emission limits are accelerating equipment replacement cycles toward Tier 4 Final and aftertreatment-equipped models in backup power applications.
- Data Center Uptime Requirements:Hyperscale and colocation facilities are mandating N+1 or 2N redundancy architectures that embed multi-megawatt generation capacity on-site.
- Solid Oxide Fuel Cell Efficiency Gains:Electrical efficiencies approaching 60 percent are expanding fuel cell deployment into continuous baseload roles previously dominated by reciprocating engines.
Market Restraints
- Natural Gas Price Volatility:Input cost swings for gas-fueled reciprocating engines and turbines are compressing project IRRs and delaying utility-scale embedded generation commitments.
- Electrolyzer and Hydrogen Supply Concentration:Equipment and fuel sourcing for hydrogen-ready generator sets remains concentrated among European and East Asian suppliers, creating procurement bottlenecks.
- Interconnection Queue Friction:Utility approval timelines for grid-synchronized embedded systems extend 18-36 months in high-growth US markets, freezing project execution.
Strategic Opportunities
- India Industrial Cogeneration:Petroleum refinery and chemical cluster expansions along the Gujarat and Maharashtra coasts are creating demand for 50-200 MW combined heat and power installations.
- EU Green Deal Hydrogen Readiness:The European Commission's REPowerEU framework is incentivizing H2-capable reciprocating engine retrofits in district heating and industrial applications.
- Energy Storage Hybridization:Pairing lithium-ion battery systems with fast-ramp reciprocating engines creates frequency regulation revenue streams in wholesale power markets.
Industry Challenges
- Commissioning Engineer Scarcity:Specialized talent for large reciprocating engine and fuel cell startup procedures is concentrating among OEM service networks, extending project handover timelines.
- ISO 8528 Certification Burden:Transient response and load acceptance testing requirements create capital barriers for regional generator set assemblers lacking certified dynamometer facilities.
- Legacy Control System Integration:Embedded generation projects face protocol translation complexity when interfacing with existing SCADA architectures in mature industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Power Generation Market |
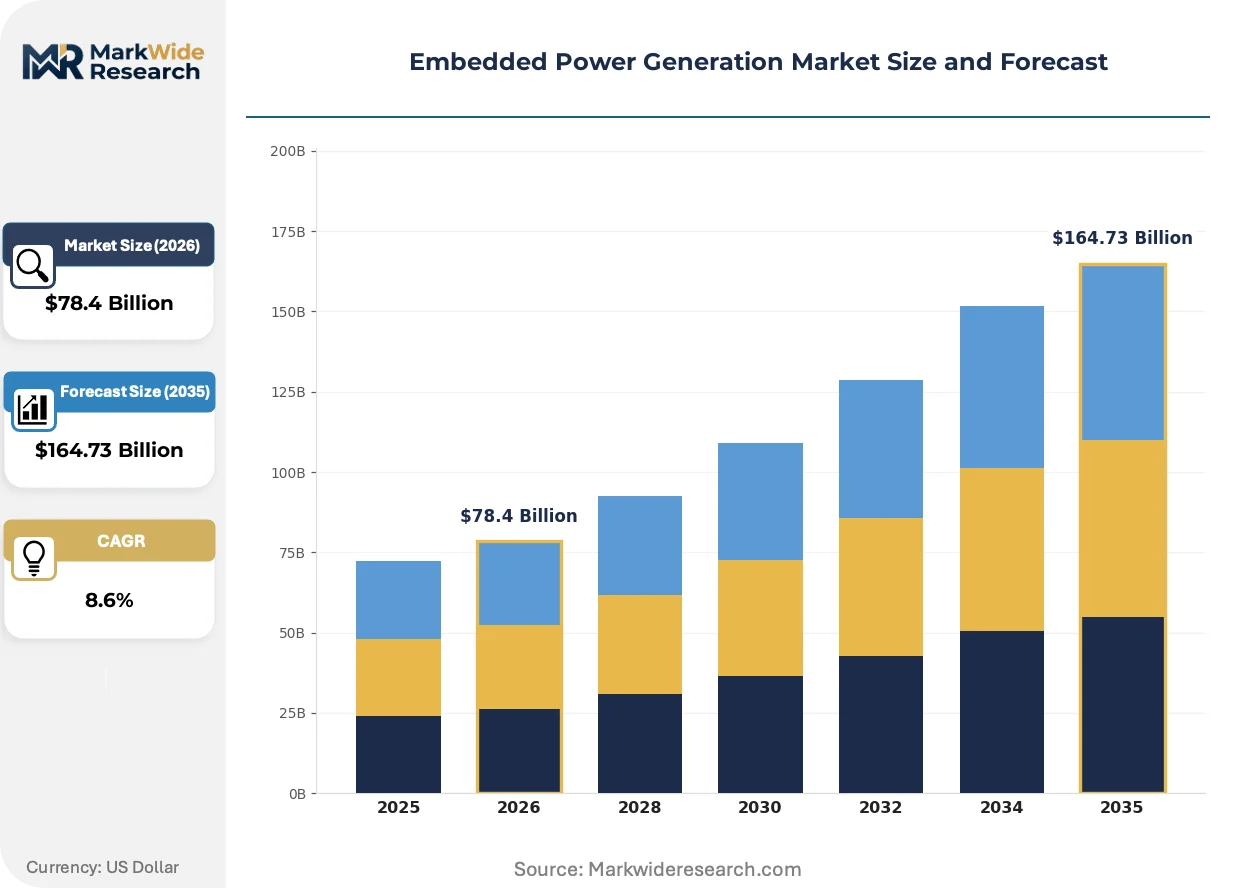
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Microturbines, Fuel Cells, Solar Panels, Diesel Generators End User: Residential, Commercial, Industrial, Military Installation: On-site, Off-grid, Grid-tied, Portable Power Rating: Up to 10 kW, 10-50 kW, 50-100 kW, Greater than 100 kW |
| Companies Covered | Schneider Electric, Caterpillar, General Electric, Siemens, ABB, Cummins, Mitsubishi Heavy Industries, Wärtsilä, Kohler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Power Generation Market Trends and Innovations
Technology trajectories in embedded power generation are converging on hybrid architectures, digitalized asset management, and fuel-flexible combustion platforms that redefine operational economics across industrial and critical infrastructure applications.
Reciprocating engine technology is migrating from fixed-speed diesel and natural gas platforms toward variable-speed, multi-fuel capable designs with integrated selective catalytic reduction. Data center operators in Northern Virginia and Phoenix are specifying these configurations for primary power roles. The shift is compressing demand for conventional fixed-speed generator sets while expanding the addressable market for engine OEMs into continuous-duty applications.
The European Union's F-Gas Regulation is phasing down hydrofluorocarbon availability for cooling systems in embedded generation packages, compelling manufacturers toward CO2 or ammonia-based heat rejection architectures. Industrial CHP installations in Germany and the Netherlands face accelerated retrofit timelines. Packaged generator set suppliers are responding with integrated adsorption chiller and dry cooler options that eliminate refrigerant dependency.
Service contracting patterns are fragmenting from bundled OEM maintenance agreements toward unbundled component-level service procurement. Large industrial end-users in Texas and Louisiana are separating engine overhaul, control system maintenance, and fuel system servicing across specialized providers. This unbundling is most pronounced in continuous-operation petrochemical facilities where in-house technical capabilities support selective outsourcing strategies.
Embedded Power Generation Market Segmentation
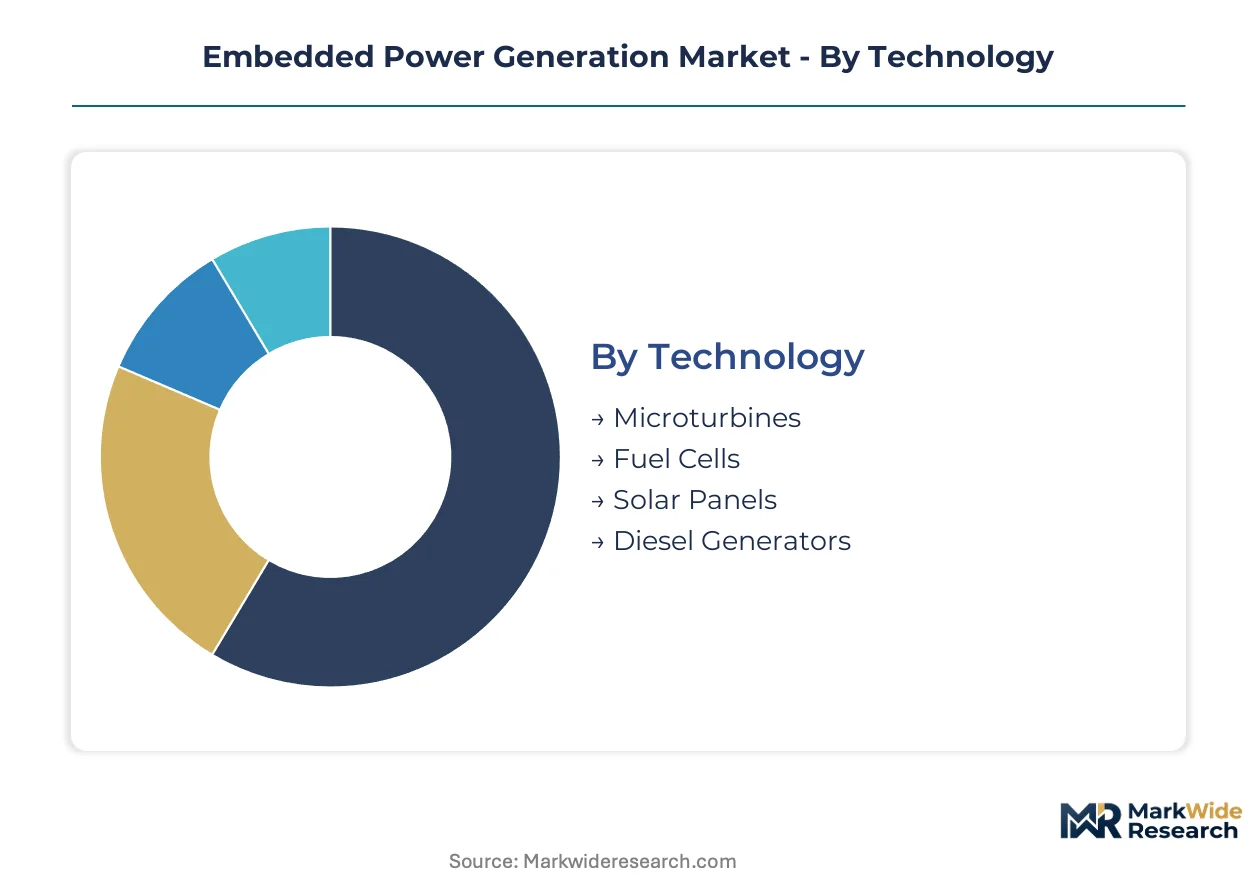
Embedded power generation procurement cycles vary dramatically by segment, with some technologies requiring decade-long replacement timelines while others turn over in under five years. Understanding these velocity differences shapes inventory planning, service contract structures, and R&D prioritization for equipment suppliers.
Technology:
Replacement cycles stretch from fifteen-year fuel cell installations to sub-decade diesel generator refreshes, compressing revenue recognition timelines for combustion-based suppliers.
- Diesel Generators:Compression-ignition reciprocating engines rated from 10 kW to multi-megawatt output dominate backup power specifications. Data center operators in Northern Virginia and Phoenix are accelerating replacement toward Tier 4 Final emission configurations.
- Fuel Cells:Electrochemical devices converting hydrogen or natural gas directly to electricity achieve electrical efficiencies approaching 60 percent. Solid oxide installations at hyperscale facilities in California and New York are displacing reciprocating engines in premium uptime roles.
- Microturbines:Gas turbine derivatives operating at rotational speeds exceeding 100,000 RPM serve distributed CHP applications below 500 kW.
- Solar Panels:Photovoltaic arrays integrated with battery storage provide renewable baseload in remote industrial camps and military forward operating bases.
Diesel generators anchor the volume base while fuel cells gain share at the steepest rate.
End User:
Margin structures diverge sharply between continuous-duty industrial operators and intermittent residential adopters, with the former commanding customized engineering premiums.
- Industrial:Petrochemical refineries, mining operations, and manufacturing facilities require 24/7 baseload power with heat recovery integration. Petroleum clusters along the Gujarat coast in India are specifying 50-200 MW combined heat and power installations.
- Commercial:Office complexes, retail centers, and hospitality facilities prioritize backup resilience over thermal efficiency. Colocation data centers in Frankfurt and Amsterdam are mandating N+1 redundancy architectures.
- Military:Forward operating bases and naval vessels demand fuel-flexible, rapidly deployable power systems.
- Residential:Single-family and multi-family dwellings employ sub-50 kW standby generators for outage protection.
Industrial end users concentrate the deepest margin pools while military procurement expands most quickly.
Installation:
Interconnection complexity and regulatory burden scale inversely with grid independence, reshaping project development economics.
- On-site:Permanently installed generation assets at industrial and commercial facilities with dedicated fuel delivery infrastructure. EPA 40 CFR Part 60 Subpart JJJJ compliance is accelerating equipment replacement toward aftertreatment-equipped models.
- Portable:Trailer-mounted or containerized systems deployed for disaster response, remote construction, and temporary events. Hurricane resilience mandates in Florida and Texas are expanding state-level procurement programs.
- Off-grid:Fully autonomous installations without utility interconnection serving remote mining camps and island communities.
- Grid-tied:Synchronized systems exporting surplus power and providing grid services through net metering or wholesale market participation.
On-site installations anchor the volume base while portable configurations climb the fastest.
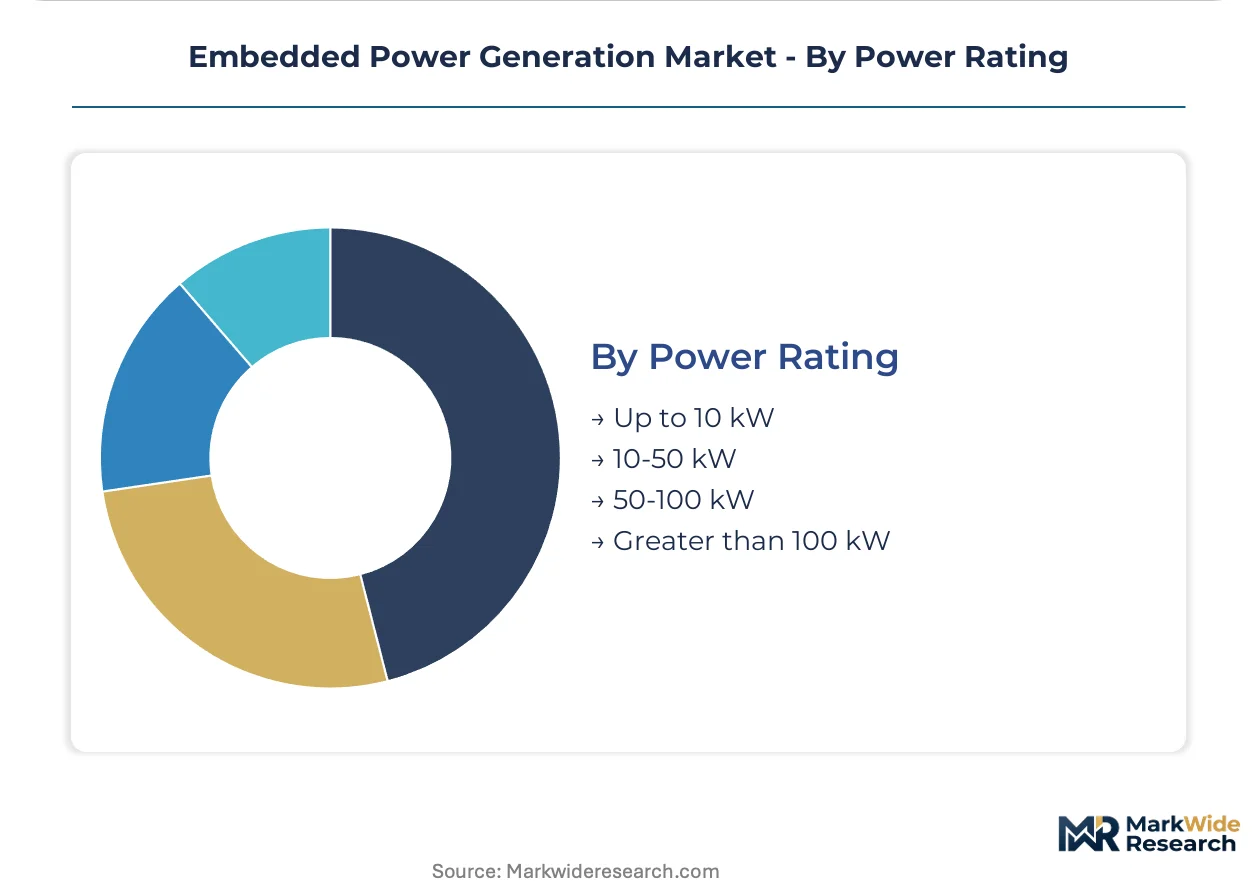
Power Rating:
Unit economics and competitive dynamics fragment across scale tiers, with mid-range segments facing the most intense price pressure.
- Greater than 100 kW:Multi-megawatt reciprocating engines and gas turbines serving industrial baseload and data center prime power. Hyperscale facilities in Ashburn and Loudoun County are embedding 10-50 MW generation campuses.
- 50-100 kW:Mid-scale systems bridging commercial backup and light industrial applications.
- 10-50 kW:Commercial standby and light industrial duty cycles with standardized enclosure packages.
- Up to 10 kW:Residential standby and small commercial units with air-cooled engine architectures.
Above-100 kW systems anchor the volume base while 50-100 kW units gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing concentrates in Germany, the United States, and Japan, where OEMs anchor reciprocating engine and fuel cell assembly. Demand fragmentation across data center, industrial, and military end users creates divergent procurement patterns by geography.
United States
Interconnection queue delays exceeding five years in Virginia and Texas force hyperscale data centers toward captive generation architectures. EPA 40 CFR Part 60 Subpart JJJJ emission standards accelerate Tier 4 Final equipment replacement cycles. Northern Virginia's Loudoun County embeds 10-50 MW generation campuses at colocation facilities.
Germany
Industrial CHP installations face accelerated retrofit timelines under the EU F-Gas Regulation phasing down hydrofluorocarbon cooling systems. The country's national energy regulator enforces grid stability standards that favor hybrid battery-engine systems. Chemical clusters along the Rhine corridor specify CO2-based heat rejection architectures.
India
Petroleum refinery expansions along the Gujarat and Maharashtra coasts drive 50-200 MW combined heat and power procurement. The Central Electricity Authority mandates grid synchronization protocols for embedded generation above 10 MW. Mumbai-Pune industrial corridor facilities deploy gas-fueled reciprocating engines for continuous process power.
Japan
Earthquake resilience mandates accelerate distributed generation deployment at semiconductor fabrication facilities. METI's hydrogen roadmap incentivizes fuel cell installations for premium uptime applications. Kyushu region industrial parks integrate solid oxide systems with existing thermal loads.
Saudi Arabia
Remote mining and petrochemical camps in the Eastern Province deploy off-grid embedded systems without utility interconnection. The national industrial development authority promotes captive power for strategic sector localization. NEOM construction phases specify containerized generator sets for temporary power.
Embedded Power Generation Market Competitive Landscape
Integrated industrial conglomerates and specialized power equipment manufacturers split the market into consolidated premium tiers and fragmented mid-scale supply. Tier 1 positions concentrate among firms with captive engine manufacturing and global service networks. Tier 2 competition intensifies around regional assembly and standardized enclosure packaging. Dominant competitive moves include hybrid system portfolio expansion and predictive maintenance platform development.
Within the integrated conglomerate tier, Schneider Electric, Siemens, and General Electric exemplify full-stack capabilities spanning switchgear, controls, and generation assets. These firms occupy positions where digital twin integration and energy management software create account stickiness. Caterpillar and Cummins anchor the reciprocating engine specialist archetype with dense dealer service networks. Wärtsilä represents the hybridization-focused tier, pairing engine technology with energy storage systems.
| Leading Market Players |
|---|
| Schneider Electric |
| Caterpillar |
| General Electric |
| Siemens |
| ABB |
| Cummins |
| Mitsubishi Heavy Industries |
| Wärtsilä |
| Kohler |
| Others |
Pricing and Supply Chain Analysis
German and Japanese engine block foundries concentrate critical casting capacity, anchoring margin capture at the component tier while downstream system integrators compete on project bundling and aftermarket service attach rates. This upstream concentration forces pricing discipline at the generator set assembly level, where OEMs differentiate through control system integration and remote monitoring platform subscriptions.
Pricing Analysis
Long-term service contracts and predictive maintenance subscriptions generate lifetime value multiples exceeding original equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates Tier 4 Final-certified systems with integrated SCR from basic backup configurations. Cost compression in mid-scale commercial segments is intensifying because standardized enclosure packages face competition from regional assemblers. Data center operators show least price sensitivity due to uptime penalty clauses, while residential standby buyers concentrate demand at economy tiers.
Supply Chain Analysis
Contract manufacturing for generator set enclosures and control panels concentrates among industrial fabrication specialists in China, Mexico, and Poland. Engine block castings draw from German, Japanese, and Indian metallurgical suppliers, while power electronics and switchgear rest on South Korean and Taiwanese semiconductor capacity. Single-source vulnerability runs through SCR catalyst substrate supply from European chemical processors. Distribution runs through OEM-authorized dealer networks for large reciprocating engines, with direct procurement emerging for containerized microturbine and fuel cell packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid-tied battery storage and utility-scale solar-plus-storage installations represent the substitution threat that incumbent embedded generation suppliers must navigate through hybrid architecture development.
For Market Incumbents: Entrench position through captive control system software development and predictive maintenance platform lock-in. Backward integration into power electronics assembly reduces exposure to semiconductor supply volatility. Solid oxide fuel cell efficiency gains threaten reciprocating engine incumbency in premium uptime applications; defend through hybrid battery-engine system offerings that capture frequency regulation revenue streams. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with 50-200 kW gas-fueled reciprocating engine specifications underserved by established OEM service networks. Portable disaster response installations in hurricane-prone US states offer second white-space opportunity through state procurement program participation. Go-to-market angle should emphasize containerized rapid-deployment configurations with integrated fuel storage. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional generator set assemblers lacking ISO 8528 certification infrastructure. Long-term viability hinges on regulatory compliance capability across evolving EPA emission tiers and EU F-Gas cooling system mandates. Watch solid oxide fuel cell cost curves as inflection signal for technology substitution velocity in data center prime power applications.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Portfolio Expansion | Pairing lithium-ion batteries with fast-ramp reciprocating engines captures frequency regulation revenue in wholesale markets. |
| Predictive Maintenance Platform Development | Remote monitoring subscriptions generate recurring revenue streams that offset equipment margin compression. |
| Fuel Cell Technology Licensing | Solid oxide efficiency gains above 60 percent enable displacement of diesel engines in premium uptime roles. |
| Backward Integration into Power Electronics | In-house production of switchgear and control systems reduces semiconductor supply chain vulnerability. |
| Regional Assembly Footprint Expansion | Localized generator set packaging in India and Southeast Asia shortens delivery timelines for petrochemical cluster demand. |
Research Methodology
A standing panel of data center facility directors, industrial plant engineers, EPC contractors, and OEM aftermarket service heads provided ongoing calibration across the study period. Primary interviews combined with secondary validation from EPA regulatory filings, EIA embedded generation statistics, FERC interconnection queue databases, and customs trade data for engine imports. Bottom-up equipment shipment analysis triangulated against top-down utility capacity planning disclosures.
Scenario-bracketing framed demand projections across the modeling period, with segmentation dimensions spanning fuel source, power rating tier, end-use application, installation type, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and capacity expansion announcements. Forecast inputs incorporated interconnection queue duration assumptions and emission standard compliance cost trajectories.
Macroeconomic conditions sit as an overlay; deviation in natural gas price volatility and industrial construction spending would shift the trajectory. Forecasts reflect assumptions regarding grid reliability deterioration rates and carbon border adjustment implementation timing. Quarterly review of hyperscaler data center capex disclosures and EPA enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
South Korea Battery Management Systems Market
Power Systems
Generator Circuit Breaker Market
Power Systems
Thyristor Market
Power Systems
Japan Surge Protector Market
Power Systems
Global Data Center Transformer Market
Power Systems
North America Variable Frequency Drive Market
Power Systems
Global DC Power Supply Module Market
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market
Power Systems
APAC Variable Frequency Drives Market
Power Systems
Flyback Transformer Market
Power Systems
AC Voltage Transducer Market
Power Systems
South America DC Distribution Network Market
Power Systems
Semiconductor Rectifier Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Global Frequency Converter Market
Power Systems
Organic Fixed Power Capacitors Sales Market