
 Inline Quality Control Sensors Market | 2026-2036
Inline Quality Control Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Inline Quality Control Sensors Market Foresight
Silicon photonics is expanding its footprint in inline sensor arrays, displacing legacy CMOS-based detection modules in high-speed manufacturing environments. Micro-Epsilon Messtechnik leverages proprietary laser triangulation patents to dominate dimensional gauging in European automotive plants. Sick AG anchors its position through backward integration into optical chip design, while Keyence competes aggressively in Asian electronics assembly with rapid-deployment vision systems.
Inline quality control sensors are non-contact measurement devices integrated directly into production lines to detect dimensional deviations, surface defects, or material inconsistencies at throughput speeds exceeding 1,000 units per minute. These systems employ structured light projection, confocal chromatic imaging, or time-of-flight laser ranging to generate sub-micron measurement resolution for real-time process adjustment. Vision sensors lead installed base across automotive and electronics sectors due to mature software ecosystems and declining camera module costs. Machine learning technology represents the fastest-expanding segment as neural network inference migrates to edge hardware, reducing latency for defect classification. Pharmaceutical production end users concentrate margin pools in validated systems requiring FDA 21 CFR Part 11 compliance documentation.
FDA regulations in the United States mandate process analytical technology for pharmaceutical batch release, directly stimulating sensor validation spending. The EU Machinery Directive and CE marking requirements enforce functional safety standards on automated inspection systems sold into European manufacturing lines. China's GB standards and SAMR certification protocols create market access conditions for foreign sensor suppliers in domestic automotive supply chains. Stakeholders must monitor convergence between cybersecurity frameworks and sensor data integrity requirements as connected factory architectures proliferate.
Market Dynamics
Edge-computing sensor architectures are compressing decision latency from cloud-dependent milliseconds to microseconds, forcing vendors to redesign optical hardware for localized neural network inference rather than centralized processing.
Growth Catalysts
- EU Machinery Directive zero-defect mandates:German automotive OEMs now require inline vision systems for every welding station, accelerating sensor deployment across European production lines.
- Silicon photonics wafer inspection:South Korean semiconductor foundries embed time-of-flight arrays to catch sub-micron defects before dicing, slashing scrap rates in memory fabrication.
- FDA 21 CFR Part 11 pharmaceutical validation:US drug manufacturers invest in documented sensor calibration chains to secure batch release approvals, creating premium demand for compliant systems.
Market Restraints
- Specialized optical component concentration:German and Japanese laser diode suppliers control critical illumination sources, exposing buyers to single-source vulnerability.
- Cleanroom integration capex:Semiconductor-grade sensor installation requires ISO Class 5 environment construction, doubling project timelines versus standard factory floors.
- Machine learning model obsolescence:Rapid algorithm iteration cycles force buyers into recurring revalidation costs for FDA-compliant pharmaceutical lines.
Strategic Opportunities
- India automotive supplier tier-2 penetration:Domestic component manufacturers under PLI scheme pressure lack inspection infrastructure, opening entry points for mid-range vision systems.
- Silicon photonics-CMOS hybrid convergence:Packaging both technologies on single substrates enables multi-modal defect detection previously requiring separate hardware stacks.
- China GB standard automotive certification:SAMR protocols for connected vehicle quality create certified-supplier status advantages for early compliant entrants.
Industry Challenges
- Multi-disciplinary engineering talent scarcity:Systems require simultaneous expertise in optics, embedded software, and process engineering, with few training pipelines producing qualified integrators.
- Legacy PLC communication protocol fragmentation:Proprietary industrial Ethernet variants force sensor vendors to maintain multiple firmware branches, diluting R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inline Quality Control Sensors Market |
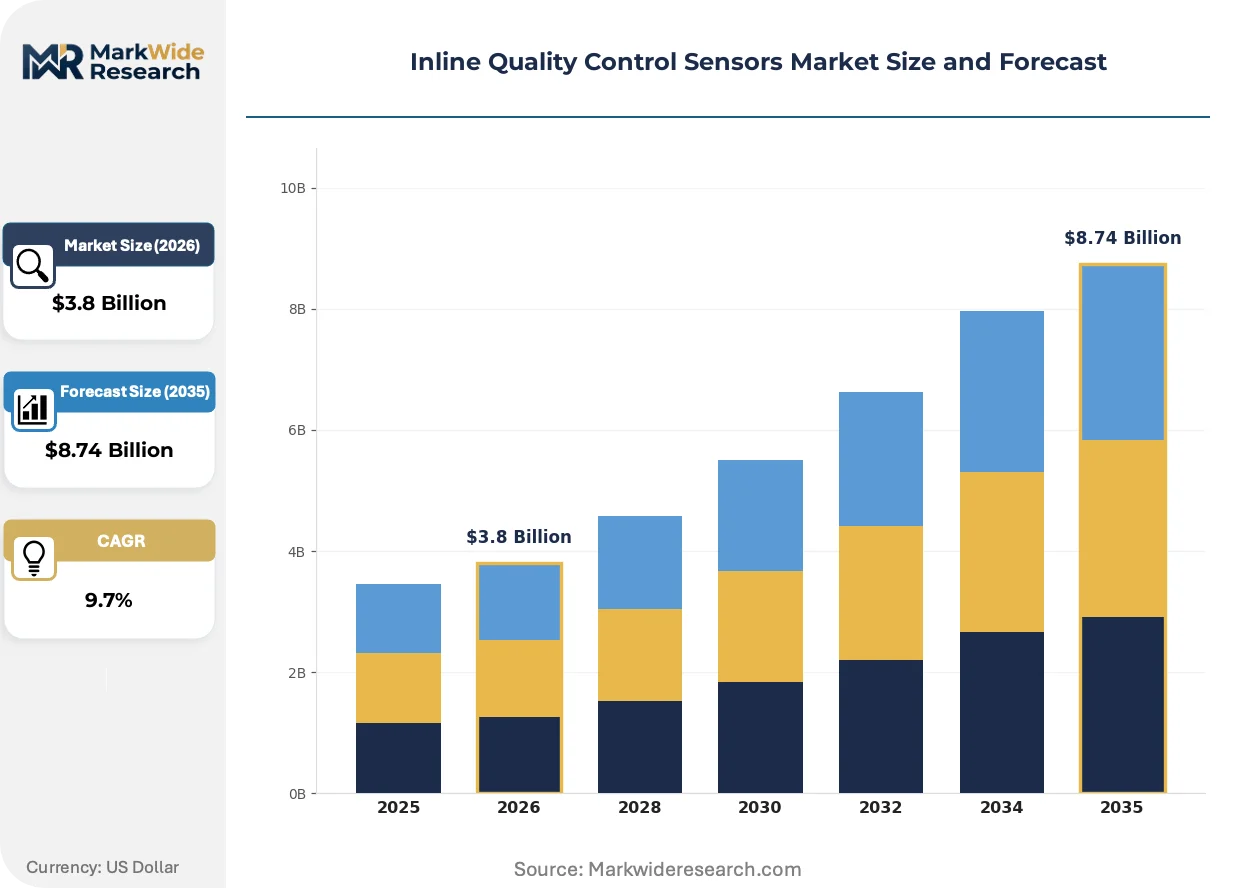
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Sensors, Vision Sensors, Pressure Sensors, RFID Sensors Technology: Machine Learning, Image Processing, IoT, Data Analytics End User: Automotive Manufacturing, Food Processing, Electronics Assembly, Pharmaceutical Production Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Micro-Epsilon Messtechnik, Baumer Group, LMI Technologies, Stemmer Imaging, Leuze Electronic, Sick AG, Keyence, Rockwell Automation, Banner Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inline Quality Control Sensors Market Shifts & Advancements
Neural network inference migration to sensor-edge hardware is collapsing the traditional separation between data acquisition and decision layers, compressing system architecture and rewriting vendor competitive boundaries.
Hyperspectral imaging is unifying material composition verification with surface defect detection in single-pass inspection. Food processors in the Netherlands deploy these systems to simultaneously check seal integrity and foreign-object contamination. The technology is unifying what previously required separate X-ray and vision stations, reducing line footprint and capital duplication.
Japan's METI has issued updated JIS B 7440 standards for machine vision performance verification, mandating traceable measurement uncertainty documentation for automotive suppliers. Tier-1 component manufacturers must now submit sensor calibration certificates with every shipment. Electronics assembly plants in Aichi Prefecture are restructuring supplier qualification processes to capture this documentation overhead.
Pharmaceutical buyers are unbundling sensor hardware from validation service contracts, treating compliance documentation as separately purchasable from equipment. This procurement pattern shift pressures traditional bundled pricing at German and Swiss vendors. Contract research organizations in Massachusetts and North Carolina now source inspection hardware through distributors while engaging specialized validation consultants directly.
Inline Quality Control Sensors Market Segmentation
Inline quality control sensors fragment across hardware generations, software sophistication levels, and integration architectures that determine where value pools concentrate. Understanding these divisions reveals which specifications command price premiums and which deployment models reduce total cost of ownership.
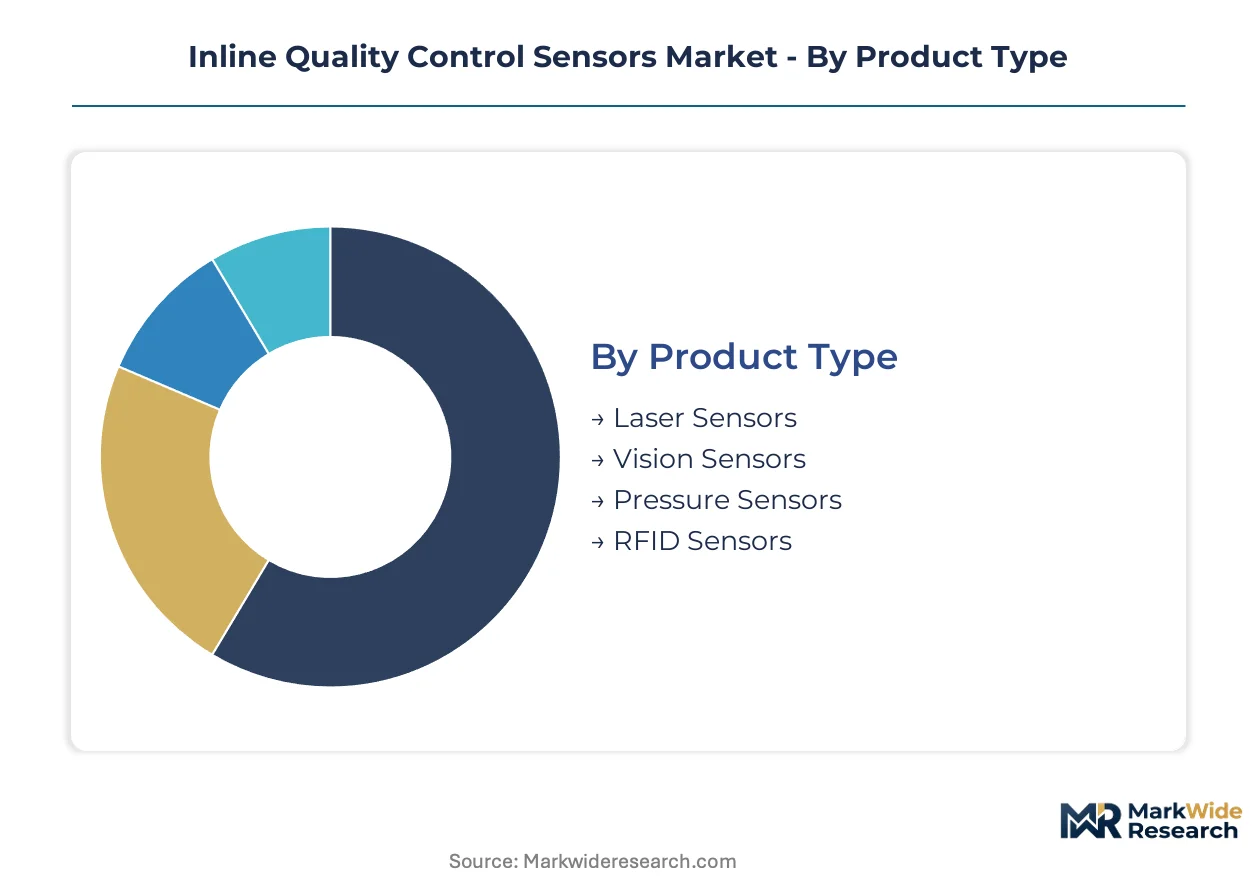
Product Type:
Standardized optical modules compete against application-specific sensor heads engineered for single measurement tasks.
- Vision Sensors:Camera-based systems with embedded LED illumination capture dimensional and surface data at line speeds exceeding 1,000 units per minute. Automotive welding stations in Germany embed these under EU Machinery Directive zero-defect mandates, with software ecosystems from Cognex and Keyence reducing deployment friction.
- Laser Sensors:Triangulation and time-of-flight architectures deliver sub-micron resolution for dimensional gauging. South Korean semiconductor foundries concentrate procurement here for wafer thickness mapping before dicing, where scrap cost justifies premium hardware spend.
- Pressure Sensors:Piezoelectric and capacitive variants monitor seal integrity and force consistency in packaging lines. Food processors in the Netherlands deploy these for vacuum seal verification alongside foreign-object detection.
- RFID Sensors:Read-write heads track component genealogy and process parameters through production sequences. Pharmaceutical manufacturers use these for FDA 21 CFR Part 11 batch documentation.
Leading the category by volume: Vision Sensors. Growing fastest: Laser Sensors.
Technology:
Processing location determines latency, data sovereignty, and model update cadence across this layer.
- Machine Learning:Neural network inference at the edge classifies defects without cloud round-trips. Japanese automotive plants under JIS B 7440 standards demand traceable uncertainty documentation, forcing vendors to embed model versioning directly into sensor firmware.
- Image Processing:Traditional algorithmic filters and geometric pattern matching execute on FPGA or ASIC hardware. Electronics assembly in Aichi Prefecture retains these for deterministic cycle times where inference variability is unacceptable.
- IoT:Sensor-to-platform connectivity protocols enable centralized fleet management and predictive maintenance scheduling. Cloud-based architectures dominate in multi-site pharmaceutical operations with centralized quality oversight.
- Data Analytics:Post-process statistical aggregation identifies process drift and correlates defect rates with upstream variables. Hybrid deployments separate real-time pass-fail decisions from batch-level trend analysis.
Widest installed base: Image Processing. Steepest expansion trajectory: Machine Learning.
End User:
Validation requirements and throughput specifications create divergent procurement criteria across manufacturing verticals.
- Automotive Manufacturing:Zero-defect protocols mandate 100% inline inspection at welding, painting, and assembly stations. German OEMs under EU Machinery Directive requirements specify vision systems with SIL-rated safety integration.
- Pharmaceutical Production:FDA process analytical technology mandates drive sensor validation spending. US drug manufacturers purchase calibration documentation as separately contracted services from specialized consultants.
- Electronics Assembly:Miniaturization and high-mix production favor rapid-deployment vision systems with software-defined inspection routines. South Korean memory fabrication concentrates demand for sub-micron defect detection.
- Food Processing:Hyperspectral systems unify seal integrity and contamination detection in single-pass configurations. Dutch processors lead adoption where line footprint reduction justifies capital premium.
Highest validation margins: Pharmaceutical Production. Fastest hardware refresh: Electronics Assembly.
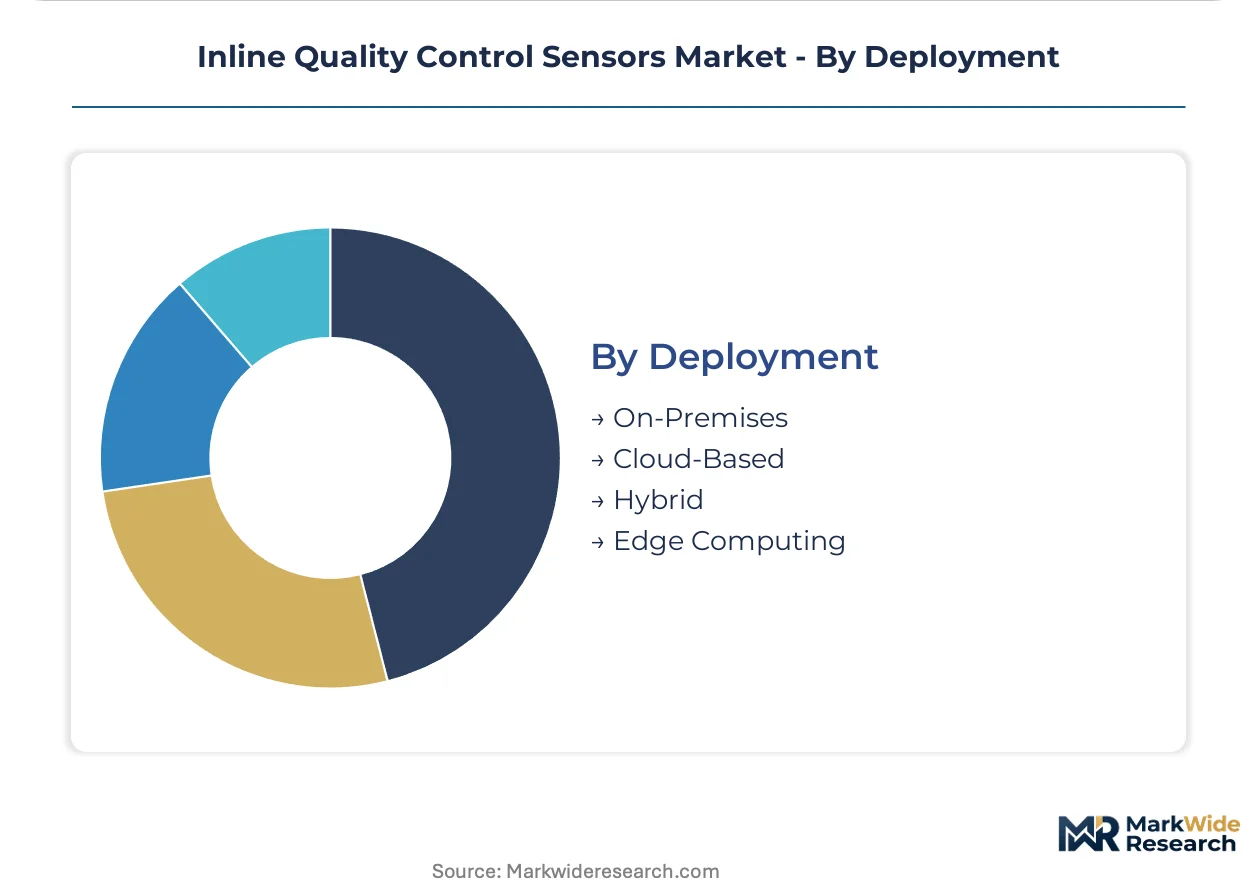
Deployment:
Architecture choice trades latency, scalability, and cybersecurity surface area against integration complexity.
- Edge Computing:Localized neural network inference collapses decision latency from milliseconds to microseconds. South Korean foundries embed these architectures for real-time wafer scrap prevention.
- On-Premises:Dedicated server infrastructure maintains data sovereignty for defense and aerospace suppliers. German automotive tier-1s favor this model for air-gapped production networks.
- Hybrid:Edge inference with cloud-based model training and fleet analytics balances responsiveness with centralized optimization. Multi-site pharmaceutical operations deploy this for corporate quality dashboards.
- Cloud-Based:Fully centralized processing suits low-volume, high-variability inspection tasks. Contract research organizations in Massachusetts use this for flexible capacity without capital commitment.
Dominant architecture by new installations: Edge Computing. Expanding most quickly: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in South Korea and industrial parks in Germany concentrate sensor demand through tax incentives tied to advanced manufacturing investment. These zones attract semiconductor foundries and automotive OEMs requiring zero-defect inspection infrastructure. Regulatory harmonization across export markets is forcing multinational manufacturers to standardize sensor validation protocols regionally.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg mandate vision systems at every welding station under EU Machinery Directive zero-defect protocols. The KBA enforces functional safety standards on automated inspection systems sold into domestic supply chains. Stuttgart's manufacturing cluster embeds laser triangulation sensors for dimensional gauging in electric vehicle battery assembly lines.
United States
FDA process analytical technology mandates drive sensor validation spending among pharmaceutical manufacturers in Massachusetts and North Carolina. The agency's 21 CFR Part 11 requirements force documented calibration chains for batch release approvals. Boston-area contract research organizations now unbundle hardware procurement from validation services, treating compliance documentation as separately contracted.
Japan
METI's updated JIS B 7440 standards mandate traceable measurement uncertainty documentation for automotive suppliers in Aichi Prefecture. Tier-1 component manufacturers must submit sensor calibration certificates with every shipment. Electronics assembly plants in Nagoya are restructuring supplier qualification processes to capture this documentation overhead.
South Korea
Semiconductor foundries in the Seoul Capital Area embed time-of-flight arrays for sub-micron defect detection before wafer dicing. The MFDS oversees equipment validation in pharmaceutical applications, though industrial sensor deployment falls under KOSHA safety protocols. Samsung and SK Hynix memory fabrication facilities concentrate procurement of edge-computing sensor architectures for real-time scrap prevention.
China
GB standards and SAMR certification protocols create market access conditions for foreign sensor suppliers in domestic automotive supply chains. The MIIT promotes connected factory architectures that integrate inline inspection with centralized quality dashboards. Yangtze River Delta manufacturing hubs demand multi-modal defect detection systems for electric vehicle component production.
Inline Quality Control Sensors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with European optics houses dominating dimensional gauging while Asian electronics vendors capture rapid-deployment vision contracts. The vendor base concentrates around three strategic archetypes: laser triangulation patent holders, backward-integrated optical chip designers, and software-centric rapid-deployment specialists. Competitive moves center on silicon photonics-CMOS hybrid packaging and edge inference hardware redesign.
Among German precision measurement specialists, Micro-Epsilon Messtechnik and Sick AG exemplify the patent-anchored archetype through proprietary optical architectures. Japanese conglomerate Keyence occupies a position representing the rapid-deployment software-centric model. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without overlapping segment focus.
| Leading Market Players |
|---|
| Micro-Epsilon Messtechnik |
| Baumer Group |
| LMI Technologies |
| Stemmer Imaging |
| Leuze Electronic |
| Sick AG |
| Keyence |
| Rockwell Automation |
| Banner Engineering |
| Others |
Supply & Pricing Matrix
Silicon wafer price indices cascade through optical component supply chains, compressing margins for CMOS-based sensor modules while concentrating pricing power with German and Japanese laser diode suppliers serving validated pharmaceutical systems.
Pricing Analysis
Short lead-time premiums of 15-25% apply to edge-computing sensor architectures for South Korean semiconductor foundries, while spot inventory of standard vision sensors trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from automotive vision modules and unbundled hardware for contract research organizations. Cost compression in mid-range vision sensors is intensifying because of CMOS commoditization and Chinese vendor entry. Tier-2 automotive suppliers in India exhibit highest price sensitivity; pharmaceutical manufacturers under FDA 21 CFR Part 11 mandates show least sensitivity due to compliance-driven procurement.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese suppliers of high-power laser diodes for triangulation sensors, exposing buyers to concentration risk in precision illumination components. Manufacturing draws from Germany, Japan, and South Korea for optical chip fabrication, with final assembly concentrated in China and Mexico for cost-sensitive segments. Raw material dependencies include silicon wafers, rare-earth-doped laser crystals, and precision optical glass. Tariff exposure on Chinese-assembled modules threatens cost structures for North American automotive tier-1s. Distribution runs through authorized system integrators for validated pharmaceutical applications and direct OEM sales for high-volume automotive contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around edge-computing architectures and silicon photonics capabilities, with machine learning model obsolescence pressures forcing smaller vision-system vendors toward acquisition or exit.
For Market Incumbents: To counter software-centric rapid-deployment specialists from Asia, deepen backward integration into optical chip design and establish captive supply of laser illumination sources. Anchor position through exclusive validation service contracts with pharmaceutical manufacturers, converting compliance documentation from cost center to recurring revenue stream. For New Entrants and Emerging Players: Begin with mid-range vision systems for India's tier-2 automotive suppliers under PLI scheme pressure, where inspection infrastructure gaps outpace incumbent coverage. Target electronics assembly subcontractors in Vietnam and Mexico seeking rapid-deployment alternatives to established German and Japanese brands. Lead with unbundled hardware pricing that separates sensor procurement from integration services. For Investors and Strategic Acquirers: Distressed-cycle entries favor patent-anchored laser triangulation specialists in Germany and backward-integrated optical component manufacturers in Japan, where capability scarcity supports premium valuations through consolidation windows. Watch for FDA validation backlog clearance as inflection signal for pharmaceutical sensor demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics-CMOS Hybrid Packaging | Enables multi-modal defect detection on single substrates, collapsing hardware stacks for South Korean foundries. |
| Edge Inference Hardware Redesign | Compresses decision latency to microseconds for real-time wafer scrap prevention in memory fabrication. |
| Validation Service Unbundling | Separates compliance documentation from equipment sales, opening distributor channels for pharmaceutical hardware. |
| India Tier-2 Market Entry | Captures PLI-driven infrastructure buildout among domestic automotive component manufacturers lacking inspection systems. |
| Laser Diode Backward Integration | Secures captive supply of critical illumination sources, defending against single-source vulnerability in German supply chains. |
Research Methodology
Trade publications, semiconductor equipment market databases, and regulatory filing repositories formed the secondary backbone, cross-referenced against primary interviews with sensor system integrators, automotive tier-1 procurement directors, pharmaceutical validation consultants, and optical component manufacturing engineers. Bottom-up and top-down triangulation reconciled shipment data from vision system vendors with end-user capital expenditure disclosures across German automotive OEMs and South Korean foundry operators.
Bottom-up modeling aggregated unit economics across vision, laser, pressure, and RFID sensor categories, while top-down analysis anchored total addressable market sizing to manufacturing automation investment flows. Segmentation dimensions included product type, processing technology, end-user vertical, and deployment architecture, with CAGRs derived from slope-intercept fitting of historical penetration curves against projected automation intensity. Industry-specific inputs incorporated EU Machinery Directive compliance timelines, FDA 21 CFR Part 11 validation cycle durations, and JIS B 7440 standard adoption rates across the analysis window.
Semiconductor capital expenditure volatility, automotive production schedule disruptions, and pharmaceutical regulatory inspection backlog fluctuations are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding edge-computing adoption curves and silicon photonics cost-reduction trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Force Sensor Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
Contact Steering Torque Sensor Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Global Wireless Brain Sensors Market
Sensors and Controls
Asia-Pacific Wireless Brain Sensors Market
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
Echo Sounder Market
Sensors and Controls
Distributed Temperature Sensing Market
Sensors and Controls
Smart Condition Monitoring Market
Sensors and Controls
Oxygen Gas Sensors Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Global Intelligent Flow Meter Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
Europe Nano Sensors Market