
 Air Pressure Sensor Market | 2026-2036
Air Pressure Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Air Pressure Sensor Market Outlook
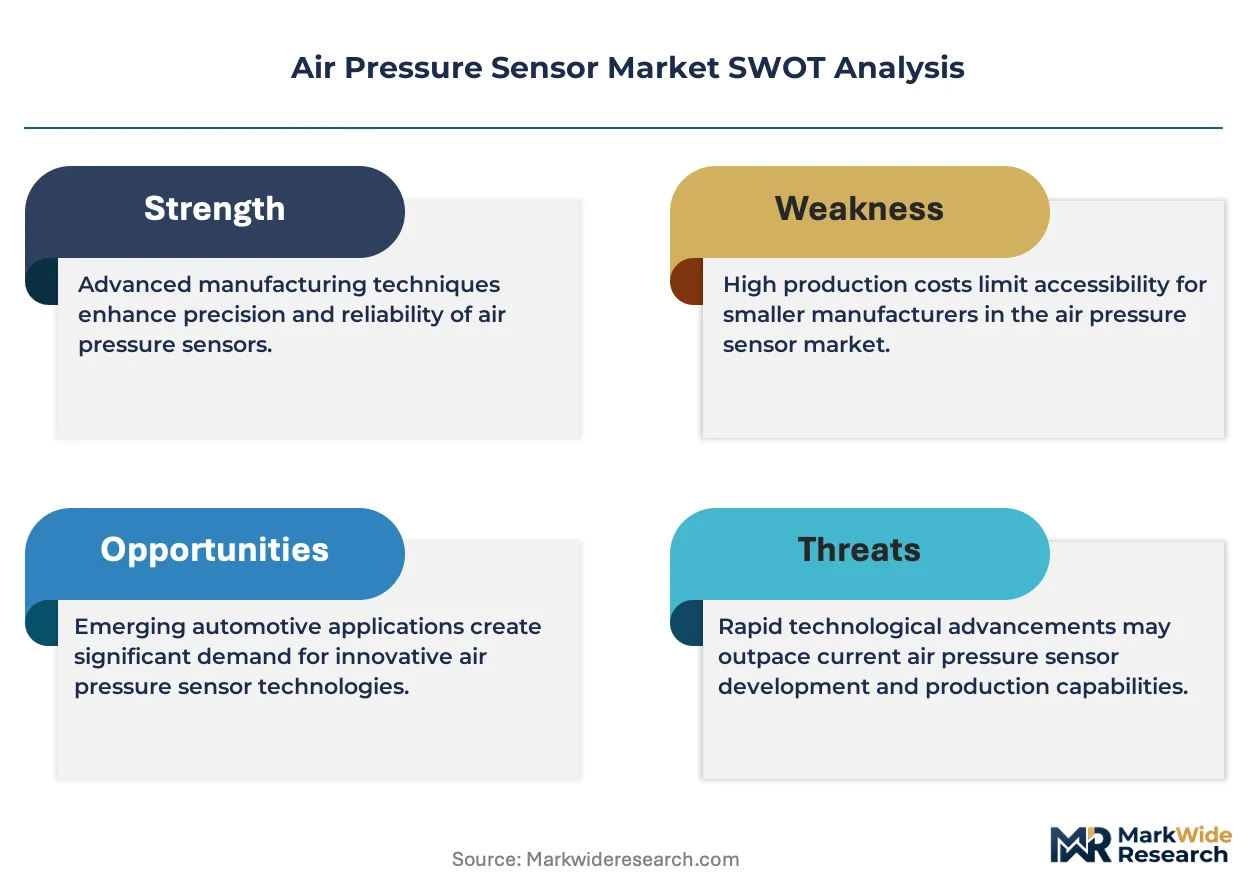
Automotive OEMs are collapsing their supplier base for electrified powertrain pressure monitoring, shifting volume toward tier-one sensor houses with captive MEMS fabrication. Honeywell International Inc. sustains dominance in aerospace-grade absolute pressure modules through in-house production of hermetic ceramic substrates. Infineon Technologies anchors automotive differential sensing with proprietary capacitive MEMS processes certified to AEC-Q100. Sensata Technologies specializes in panel-mounted industrial transmitters, leveraging backward integration into strain gauge wafer manufacturing to control lead times.
An air pressure sensor converts fluid force into an electrical signal through piezoresistive, capacitive, or optical transduction mechanisms, typically operating across ranges from millibars to hundreds of bars with accuracy thresholds of 0.1% full scale. These devices enable closed-loop control in pneumatic systems, altitude compensation, and leak detection across safety-critical applications. Ceramic technology leads in harsh-environment automotive underhood placements due to thermal shock resistance, while optical sensing represents the fastest-growing technology dimension as fiber-optic designs penetrate aerospace fly-by-wire architectures. Gauge pressure products dominate HVAC and manufacturing installations where atmospheric reference stability matters, whereas multi-pressure variants command premium positioning in integrated engine management units.
FAA certification requirements for pitot-static systems and EPA onboard diagnostics mandates for evaporative emission pressure monitoring shape product validation cycles and barrier-to-entry economics. EMA's Medical Device Regulation and REACH substance restrictions additionally constrain material selection for sensors deployed in healthcare and European industrial settings. Stakeholders must monitor convergence between functional safety standards and cybersecurity protocols as wirelessly connected installations proliferate in smart factory deployments.
Market Dynamics
Automotive electrification programs are collapsing legacy supplier hierarchies, forcing tier-one sensor houses to absorb calibration and MEMS fabrication capabilities that OEMs previously distributed across multi-vendor chains.
Growth Catalysts
- EPA onboard diagnostics mandates:Evaporative emission pressure monitoring requirements tighten sensor accuracy thresholds to 0.1% full scale, forcing replacement cycles in US vehicle parc.
- Battery thermal management:Lithium-ion cell stack architectures demand multi-point pressure transduction for thermal runaway prevention, concentrating procurement in electrified powertrain programs.
- China's dual carbon goals:GB standards for vehicle emissions accelerate domestic production of ceramic-substrate pressure modules calibrated to AEC-Q100.
Market Restraints
- MEMS foundry concentration:Taiwan and South Korea control 70% of automotive-grade MEMS wafer capacity, exposing supply chains to single-point geopolitical friction.
- Platinum-group metal volatility:Strain gauge electrodes depend on ruthenium and palladium thin-film deposition, subject to mining supply shocks.
- REACH substance restrictions:ECHA constraints on lead-based piezoelectric ceramics force reformulation of harsh-environment underhood sensors.
Strategic Opportunities
- India's PLI scheme for automotive components:Tier-two suppliers can capture localization incentives for pressure transducer assembly serving domestic OEMs.
- Fiber-optic fly-by-wire:Optical pressure sensing convergence with aerospace avionics creates premium positioning for hermetic modules in next-generation aircraft.
- Smart factory wireless retrofit:Battery-powered pressure transmitters with LoRaWAN backhaul open greenfield installation in legacy pneumatic infrastructure.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification for brake-system pressure sensors requires specialized validation talent concentrated in Germany and Japan.
- Multi-physics simulation capex:MEMS design houses must invest in coupled electro-mechanical-thermal FEA tools to compress AEC-Q100 qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Pressure Sensor Market |
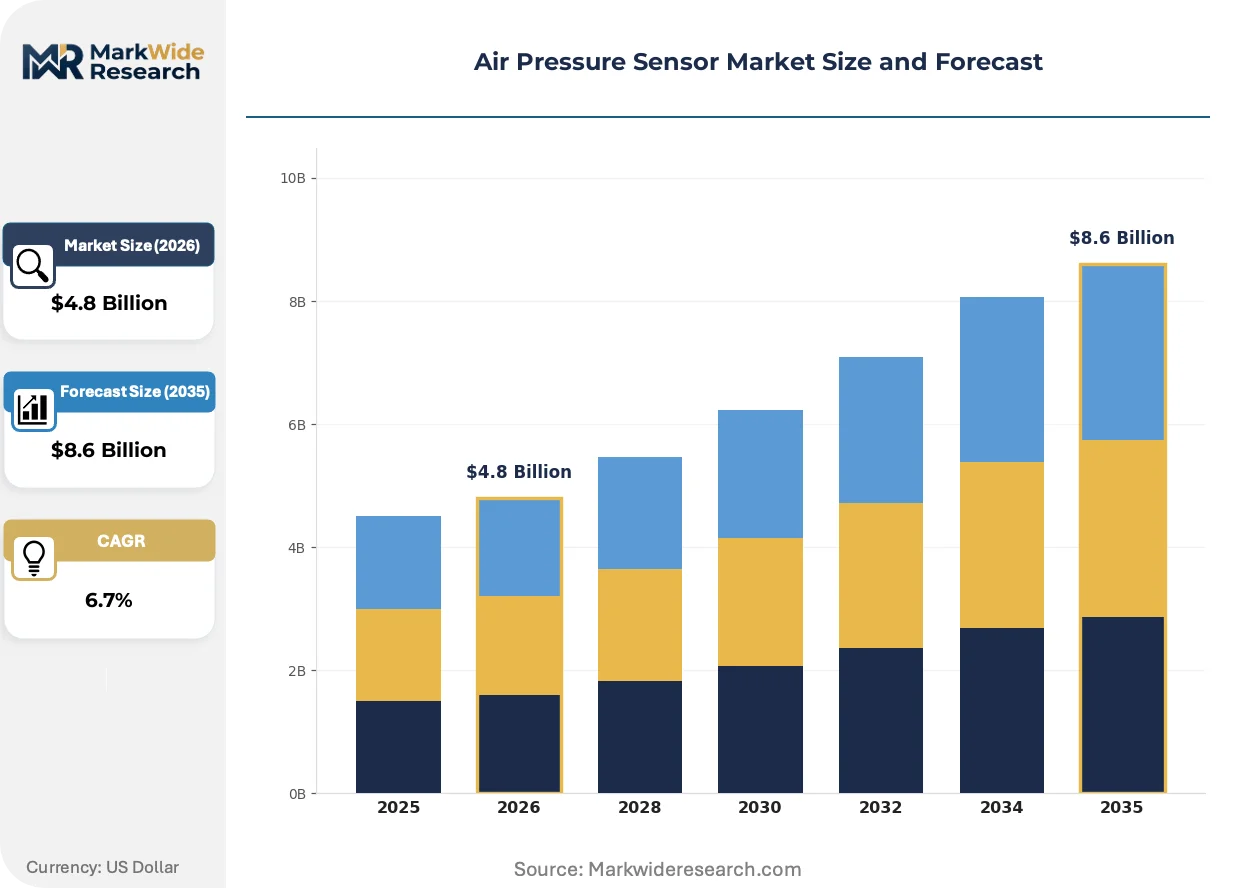
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute, Gauge, Differential, Multi-Pressure Technology: Ceramic, Strain Gauge, Capacitive, Optical End User: Aerospace, Automotive, Manufacturing, HVAC Installation: Embedded, Portable, Panel-Mounted, Wirelessly Connected |
| Companies Covered | Amphenol Corporation, ABB, Honeywell International Inc., NXP Semiconductors, Infineon Technologies, TE Connectivity, Sensata Technologies, STMicroelectronics, Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Pressure Sensor Market Strategic Shifts
Three simultaneous vectors are compressing product lifecycles: MEMS process node migration, regulatory calibration tightening, and procurement consolidation around vertically integrated sensor houses.
Optical pressure transduction is fragmenting the historical dominance of piezoresistive MEMS in safety-critical applications. Fiber-Bragg grating designs now penetrate aerospace pitot-static systems where electromagnetic immunity outweighs unit cost. Boeing and Airbus procurement specifications now bifurcate sensor categories by transduction physics rather than pressure range alone.
REACH substance restrictions are forcing material substitutions across European industrial sensor deployments. ECHA candidate list updates constrain lead zirconate titanate formulations, compelling manufacturers to qualify sodium potassium niobate alternatives. Medical device and food-processing installations face the tightest compliance windows.
Buyer concentration among automotive OEMs is compressing supplier negotiation leverage. Volkswagen Group, Toyota, and Hyundai-Kia now mandate single-source accountability for electrified powertrain pressure monitoring, collapsing tier-two distributor margins. Germany's Stuttgart-Munich supplier corridor exhibits the most aggressive vendor base rationalization.
Air Pressure Sensor Market Segmentation
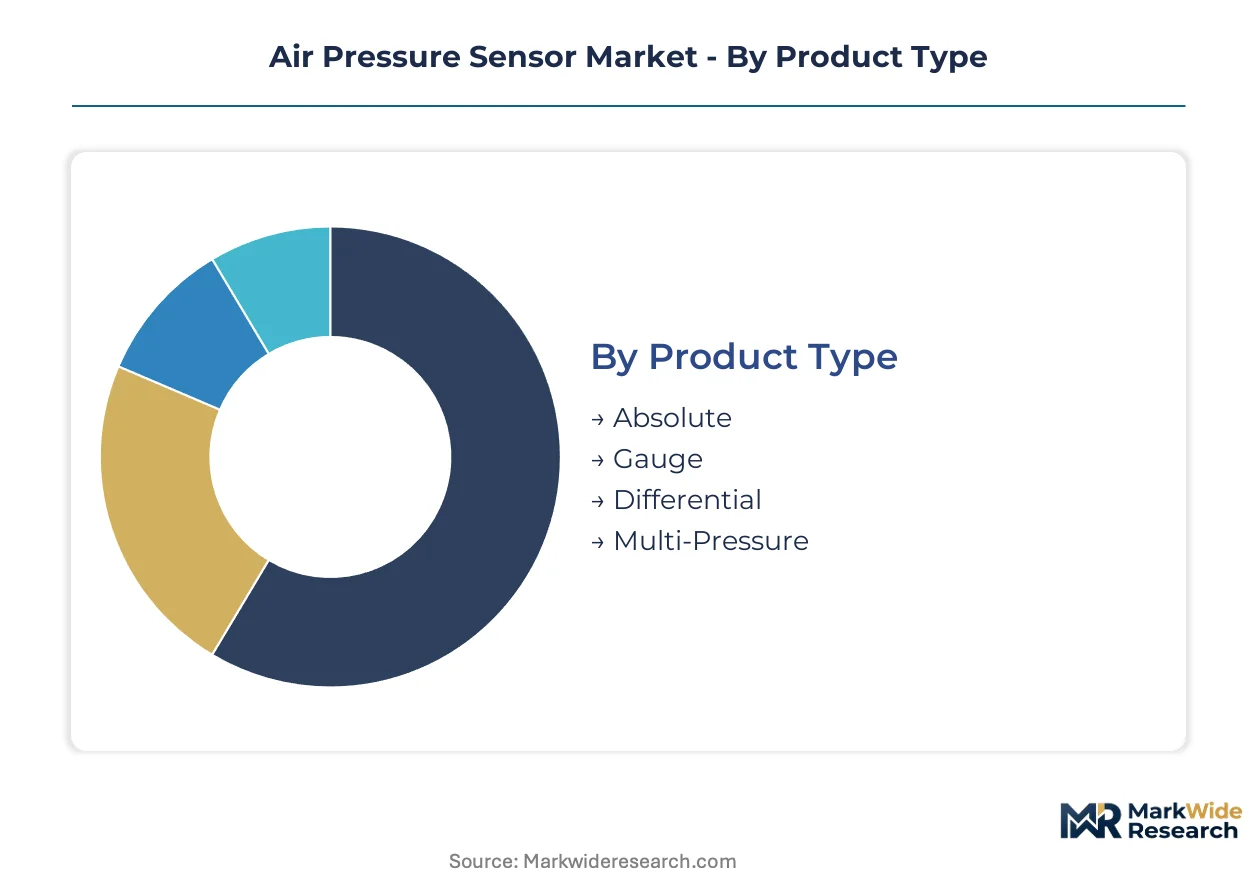
Air pressure sensor procurement channels bifurcate sharply by certification burden and volume scale. Aerospace and automotive OEMs demand captive supply relationships with AEC-Q100 or FAA-certified houses, while industrial buyers route through distribution for standard gauge products.
Product Type:
Channel mix varies dramatically: absolute pressure modules flow through aerospace prime contractor agreements, gauge products dominate HVAC wholesale distribution, and differential sensors concentrate in automotive tier-one direct procurement.
- Absolute:Hermetic ceramic substrates measure pressure against sealed vacuum reference. Boeing and Airbus pitot-static specifications drive demand toward fiber-optic variants immune to electromagnetic interference.
- Gauge:Atmospheric-referenced designs dominate HVAC and manufacturing installations where barometric stability matters. Procurement runs through industrial distributors serving facility maintenance channels.
- Differential:Dual-port architectures enable flow measurement and filter monitoring across pneumatic systems.
- Multi-Pressure:Integrated engine management units combine absolute, gauge, and differential sensing in single ceramic packages.
By volume, gauge pressure leads. By growth pace, multi-pressure variants are climbing the fastest as electrified powertrains consolidate sensing nodes.
Technology:
Cost tiers separate cleanly: optical modules command aerospace premiums, ceramic dominates automotive underhood placements, strain gauge and capacitive fill industrial mid-market gaps.
- Ceramic:Alumina and zirconia substrates withstand thermal shock in automotive underhood environments. China's GB standards for emissions monitoring accelerate domestic calibration capacity.
- Optical:Fiber-Bragg grating transduction eliminates electromagnetic susceptibility in fly-by-wire architectures. FAA certification timelines stretch 18-24 months for pitot-static replacements.
- Strain Gauge:Metal-foil and semiconductor designs serve general industrial pressure measurement.
- Capacitive:MEMS-fabricated differential cells anchor automotive manifold absolute pressure applications.
By installed base, strain gauge leads. By expansion trajectory, optical sensing is gaining share fastest as electromagnetic immunity requirements harden.
End User:
Customer type dictates specification rigor: automotive mandates AEC-Q100 and ISO 26262 ASIL-D, aerospace requires FAA TSO-C88a, manufacturing and HVAC accept industrial-grade accuracy.
- Automotive:Battery thermal management and evaporative emission monitoring concentrate procurement. EPA onboard diagnostics mandates force replacement cycles in US vehicle parc.
- Aerospace:Pitot-static, bleed air, and cabin pressure systems demand hermetic absolute modules. Boeing and Airbus now specify transduction physics separately from pressure range.
- Manufacturing:Pneumatic system monitoring and leak detection drive panel-mounted transmitter demand.
- HVAC:Refrigerant pressure and airflow measurement dominate commercial building automation.
By revenue concentration, automotive leads. By margin structure, aerospace is expanding most quickly.
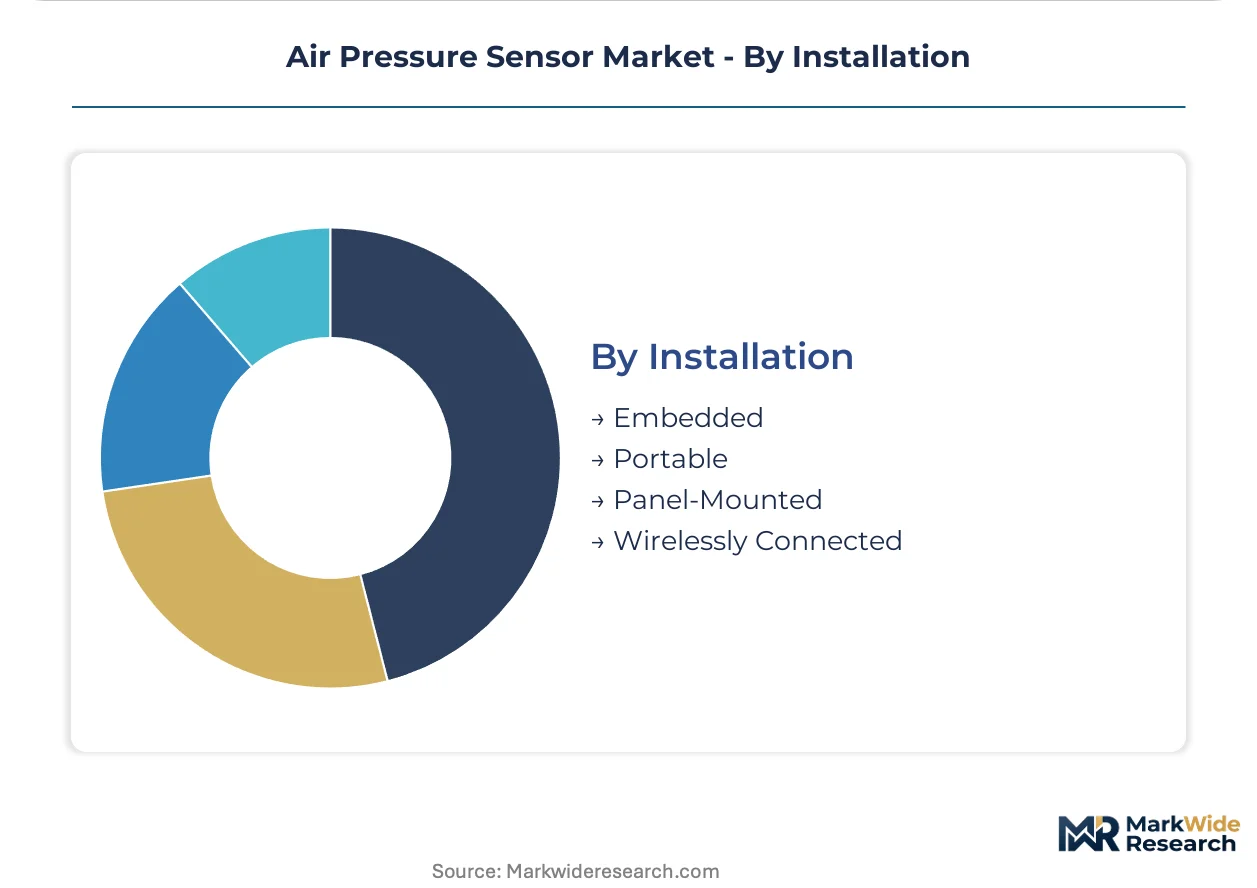
Installation:
Supply concentration tracks integration depth: embedded sensors flow through automotive tier-one houses, portable units fragment across industrial distributors, wireless retrofits open greenfield channels.
- Embedded:Engine control unit and battery management system integration demands solderable MEMS packages. Volkswagen Group and Toyota mandate single-source accountability for electrified powertrain monitoring.
- Wirelessly Connected:Battery-powered LoRaWAN transmitters enable legacy pneumatic infrastructure retrofit without cabling runs.
- Panel-Mounted:Industrial transmitters with local display and 4-20mA output serve process control applications.
- Portable:Handheld calibration and diagnostic tools serve field service technicians.
By shipment volume, embedded leads. By deployment velocity, wirelessly connected variants show steepest expansion trajectory as smart factory retrofits accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision pressure modules to automotive OEMs across China and North America, while Taiwan and South Korea control MEMS foundry capacity serving tier-one sensor houses worldwide.
United States
EPA onboard diagnostics mandates force replacement cycles in the vehicle parc for evaporative emission monitoring. FAA certification requirements govern pitot-static systems for Boeing and Gulfstream aircraft. Detroit's automotive supplier corridor concentrates procurement of brake-system pressure sensors requiring ISO 26262 ASIL-D validation.
Germany
Volkswagen Group and BMW mandate single-source accountability for electrified powertrain pressure monitoring. KBA enforces stringent calibration requirements under EU vehicle emissions frameworks. Stuttgart and Munich anchor the most aggressive vendor base rationalization in Europe's automotive supplier corridor.
China
Domestic OEMs accelerate procurement of ceramic-substrate modules for battery thermal management systems. GB standards for vehicle emissions tighten calibration requirements under the country's dual carbon goals. Yangtze River Delta manufacturing clusters scale AEC-Q100 certified production for local EV programs.
Japan
Automotive OEMs concentrate differential sensing procurement for manifold absolute pressure applications. METI oversees industrial standards for strain gauge and capacitive MEMS fabrication. Nagoya's Chubu region hosts tier-one sensor houses with captive MEMS design capabilities.
South Korea
Hyundai-Kia procurement programs consolidate pressure monitoring for electrified powertrains under single-source contracts. MFDS regulates medical device pressure sensors for healthcare applications. Seoul Capital Area foundries supply automotive-grade MEMS wafers to tier-one houses globally.
Air Pressure Sensor Market Competitive Environment
Listed leaders compete with private specialists across certification burden and MEMS fabrication depth. The vendor base exhibits moderate concentration, with tier-one sensor houses absorbing calibration capabilities previously distributed across multi-vendor chains. Three archetypes dominate: aerospace-grade specialists with hermetic ceramic expertise, automotive differential sensing houses with proprietary capacitive processes, and industrial panel-mounted transmitter manufacturers with strain gauge backward integration. Competitive moves center on captive MEMS foundry acquisition and AEC-Q100 qualification timeline compression.
Among diversified technology conglomerates, ABB and Emerson Electric Co. exemplify industrial automation positioning with process control transmitter portfolios. Honeywell International Inc. occupies the aerospace-grade absolute pressure tier, while Sensata Technologies sits within the automotive and industrial specialist segment. Infineon Technologies and NXP Semiconductors represent semiconductor-integrated houses with MEMS fabrication capabilities. STMicroelectronics and TE Connectivity anchor the scale-driven component supply tier serving multiple end-use verticals.
| Leading Market Players |
|---|
| Amphenol Corporation |
| ABB |
| Honeywell International Inc. |
| NXP Semiconductors |
| Infineon Technologies |
| TE Connectivity |
| Sensata Technologies |
| STMicroelectronics |
| Emerson Electric Co. |
| Others |
Value Chain & Pricing Dynamics
Wafer-scale MEMS fabrication economics in Taiwan and South Korea compress unit costs for automotive-grade pressure transducers while simultaneously elevating price floors for aerospace-certified optical modules. Scale concentration among foundry operators concentrates procurement leverage among tier-one sensor houses, forcing tier-two assemblers to absorb margin compression or exit volume segments.
Pricing Analysis
Current-generation ceramic-substrate automotive sensors trade at mid-tier price points against prior-generation strain gauge designs in industrial retrofit applications and next-generation fiber-optic modules commanding aerospace premiums. Pricing stratifies across AEC-Q100 certified automotive tiers, FAA TSO-C88a aerospace tiers, and uncertified industrial economy tiers, with certification grade and volume scale as the dominant differentiation drivers. Cost compression in gauge pressure industrial segments is intensifying because distributor consolidation eliminates tier-two margin buffers. HVAC and facility maintenance buyers exhibit highest price sensitivity, while electrified powertrain procurement teams at Volkswagen Group and Toyota accept premium positioning for single-source accountability.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for automotive-grade MEMS capacitive cells, while Germany and China concentrate ceramic substrate processing and final sensor assembly. Supply chains draw from ruthenium and palladium thin-film deposition for strain gauge electrodes, alumina and zirconia ceramic feedstocks, and hermetic packaging materials for aerospace modules. Single-source vulnerability runs through Taiwan foundry concentration, exposing tier-one sensor houses to geopolitical friction. Distribution runs through automotive tier-one direct procurement for embedded sensors, industrial distributors for panel-mounted transmitters, and aerospace prime contractor agreements for pitot-static systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification and fiber-optic fly-by-wire adoption are reshaping competitive positioning, creating urgency for capability repositioning across the value chain.
For Market Incumbents: Consolidate calibration and MEMS fabrication capabilities that OEMs previously distributed across multi-vendor chains. Acquire captive AEC-Q100 qualified foundry capacity in the Yangtze River Delta to defend against Taiwan supply concentration. Deepen backward integration into ceramic substrate manufacturing to compress lead times for battery thermal management programs.
For New Entrants and Emerging Players: Lead with wireless LoRaWAN pressure transmitters for smart factory retrofit applications where legacy pneumatic infrastructure lacks cabling. Target India's PLI scheme for automotive component localization, capturing assembly incentives for domestic OEM pressure transducer demand. Pursue hospital procurement channels for medical device pressure sensors where MFDS and EMA regulatory pathways create defensible positioning.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors tier-two sensor houses with strain gauge backward integration and emerging optical transduction capabilities. Long-term viability hinges on qualification timeline compression and certification breadth across automotive, aerospace, and medical verticals. Watch for FAA certification backlog resolution as the inflection signal for aerospace module supply expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Foundry Acquisition | Tier-one sensor houses absorb AEC-Q100 fabrication capacity from Taiwan and South Korea foundries. |
| Ceramic Substrate Backward Integration | Alumina and zirconia supply control secures thermal shock resistance for automotive underhood placements. |
| Fiber-Optic Certification Investment | FAA TSO-C88a qualification opens Boeing and Airbus pitot-static replacement cycles. |
| Wireless Retrofit Platform Launch | LoRaWAN battery-powered transmitters penetrate legacy pneumatic infrastructure without cabling runs. |
| India PLI Localization Assembly | Domestic pressure transducer assembly captures incentives serving Maruti Suzuki and Tata Motors procurement. |
Study Parameters
A standing panel of automotive tier-one supplier procurement managers, OEM platform engineers, aerospace avionics certification leads, and industrial facility maintenance directors provided ongoing calibration against secondary validation. Primary interviews combined with FAA TSO-C88a certification databases, EPA onboard diagnostics regulatory filings, AEC-Q100 qualification registries, and customs trade data for ceramic substrate and MEMS wafer flows. Bottom-up shipment modeling across product type, technology, end user, and installation segments triangulated against top-down OEM procurement budget disclosures.
Consistency checks validated volume and value outputs against IHS Markit vehicle production databases, semiconductor industry association MEMS unit forecasts, and aerospace OEM component procurement disclosures across the projection horizon. Segmentation dimensions modeled include pressure measurement type, transduction physics, end-use vertical, certification tier, and regional production cluster. CAGRs derived from fitted growth curves applied to segment-level baseline estimates, with battery thermal management node counts and evaporative emission monitoring replacement cycles as automotive-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification capex, stable Taiwan foundry operations, or unaltered REACH substance restrictions would require recalibration. Forecasts reflect documented assumptions regarding EPA mandate enforcement timelines, GB standard adoption curves, and FAA certification throughput capacity. Recalibration cycles align with material shifts in dual carbon policy implementation, MEMS process node migrations, and wireless connectivity protocol standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Automotive Cabin Air Quality Sensors Market
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Window Sensors Market
Sensors and Controls
China Pressure Sensors Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Global Hazardous Location Thermostats Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
France Digital Thermometer Market
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
US Temperature Sensors Market
Sensors and Controls
Occupancy Sensor Market
Sensors and Controls
Piezoelectric Actuators Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Exhaust Sensors for Automotive Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
Thermometer Market