
 Latin America Occupancy Sensors Market | 2026-2036
Latin America Occupancy Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Occupancy Sensors Market Foresight
Healthcare facility automation is rebalancing the Latin America Occupancy Sensors Market as hospitals prioritize energy-efficient patient monitoring environments. Schneider Electric SE leverages its building management integration to anchor projects across Brazilian healthcare infrastructure. Siemens AG competes through specialized infrared detection systems for clinical settings. Honeywell International Inc sustains channel control via distributor networks serving Mexican facility managers.
Latin America occupancy sensors are electro-optical or ultrasonic devices detecting human presence through motion, heat signature, or sound wave disruption, typically operating at detection ranges of 15-30 feet with 180-degree coverage arcs for automated lighting and climate control. Passive infrared variants dominate installation volumes due to lower unit costs and simplified wiring demands, while dual-technology sensors capture expanding share in security-sensitive commercial applications where false-trigger reduction justifies premium positioning. Wireless connection types are gaining fastest traction among residential end users retrofitting older structures without conduit access.
Brazil's INMETRO and Mexico's CONUEE set efficiency certification thresholds that filter non-compliant imports from Asian suppliers, tightening market access for uncertified hardware. Legrand SA and Signify Holding BV navigate these frameworks through localized testing partnerships that accelerate product registration timelines. Stakeholders must monitor how CONUEE updates its commercial building energy codes, as stricter mandates would force accelerated replacement cycles across Mexican office stock.
Market Dynamics
Wireless retrofit architectures are compressing installation timelines across Brazilian and Mexican commercial buildings, eroding the traditional hardwired sensor base as facility managers prioritize minimal-disruption upgrades over conduit-dependent deployments.
Growth Catalysts
- INMETRO certification mandates:Brazil's mandatory efficiency labeling for electrical equipment filters import competition and elevates certified product margins for compliant suppliers.
- Hospital HVAC automation:Healthcare facilities across São Paulo and Mexico City are deploying occupancy-triggered climate zones to reduce energy expenditure in patient care environments.
- Passive infrared cost curves:Manufacturing scale economies for PIR sensors are lowering per-unit costs below ultrasonic alternatives, accelerating volume uptake in price-sensitive residential retrofits.
Market Restraints
- Copper and semiconductor input volatility:Sensor PCB and wiring costs fluctuate with commodity markets, compressing assembler margins during price spike periods.
- Asian supplier concentration:Component sourcing clusters in Shenzhen and Guangzhou create single-geography exposure for Latin American integrators.
- Dual-technology price premiums:PIR-ultrasonic fusion sensors cost substantially more than single-mode units, limiting penetration outside security-critical applications.
Strategic Opportunities
- Colombian commercial construction:Bogotá and Medellín office development corridors remain undersupplied with building automation infrastructure relative to Brazilian saturation.
- CONUEE code tightening:Anticipated Mexican federal energy efficiency mandates would force accelerated sensor replacement across existing office stock.
- Bluetooth mesh convergence:Integration of occupancy detection with wireless lighting control networks is opening unified platform contracts for building technology providers.
Industry Challenges
- Certification timeline compression:INMETRO and CONUEE registration cycles delay product launches by 8-14 months, freezing supplier responsiveness to demand shifts.
- Legacy building integration friction:Pre-2010 electrical infrastructure across Latin American commercial stock lacks neutral wiring required for modern sensor installations, demanding costly remediation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Occupancy Sensors Market |
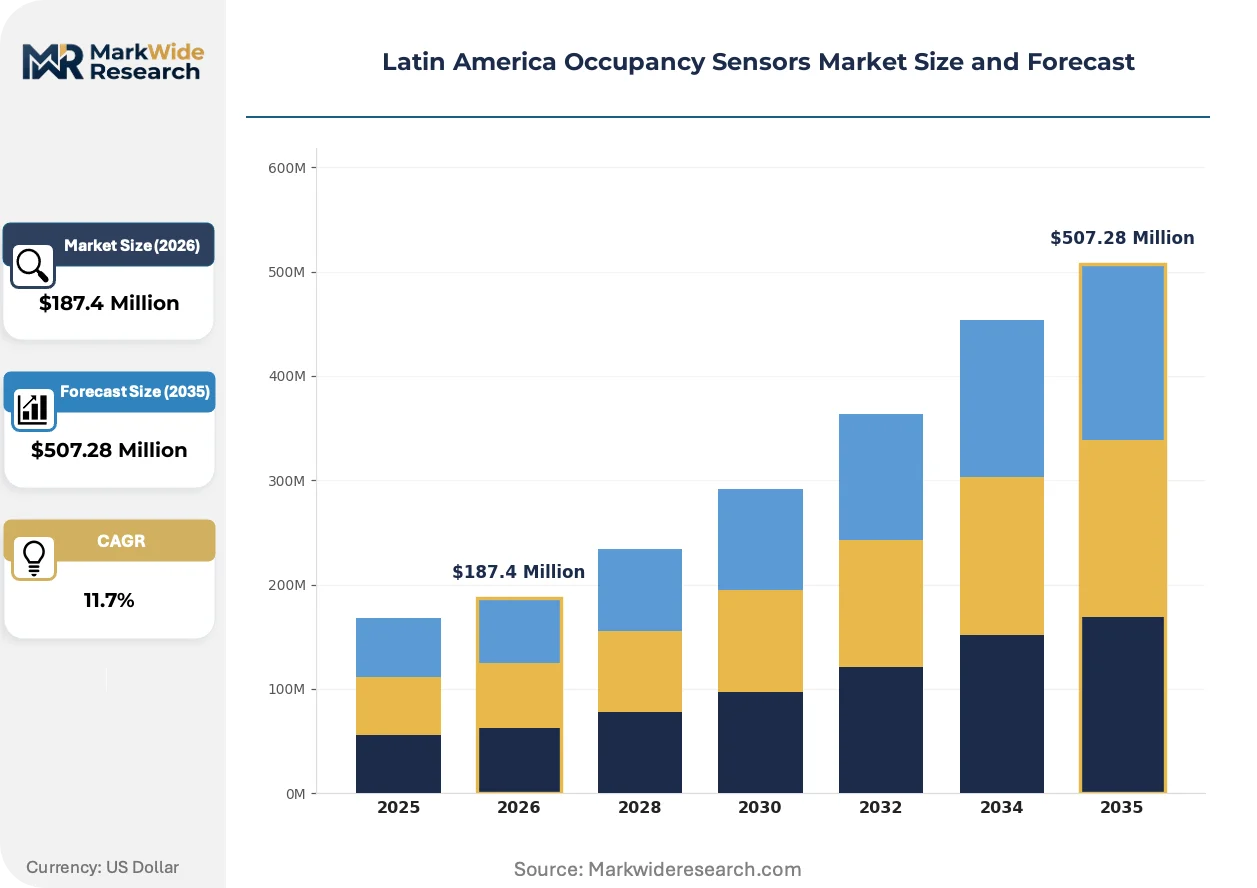
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Infrared, Ultrasonic, Dual Technology, Microwave Application: Commercial Buildings, Residential Spaces, Healthcare Facilities, Industrial Settings Connection Type: Wired, Wireless, Powerline Communication, Ethernet End User: Facility Managers, Homeowners, Building Contractors, System Integrators |
| Companies Covered | Schneider Electric SE, Honeywell International Inc, Signify Holding BV, Eaton Corp PLC, Johnson Controls Inc, Legrand SA, General Electric Co, Siemens AG, Texas Instruments Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Occupancy Sensors Market Shifts & Advancements
Sensor architectures are converging with broader building management platforms, collapsing standalone device categories into integrated environmental control systems that bundle detection, actuation, and analytics.
Dual-technology occupancy sensors is unifying infrared and ultrasonic detection modalities into single housings that reduce false-trigger rates below 2% in high-activity commercial corridors. Brazilian hospital facility managers are specifying these units for patient monitoring zones where reliability overrides cost sensitivity. The technology is unifying previously separate security and energy management procurement decisions into single vendor relationships.
CONUEE commercial building energy codes are tightening mandatory efficiency thresholds for new construction and major renovations across Mexican states. The regulation forces mechanical and electrical contractors to specify occupancy-based automation as default rather than optional upgrade. Mexican office developers in Monterrey and Guadalajara are responding by pre-wiring sensor infrastructure during shell construction to avoid retrofit penalties.
Facility management procurement patterns are compressing vendor selection cycles as Brazilian and Mexican property operators consolidate building technology spending under single master service agreements. Distributor networks serving independent electrical contractors are losing share to direct manufacturer relationships with large portfolio owners. São Paulo-based commercial real estate investment trusts are driving this consolidation most aggressively, bundling sensor deployment with multi-year energy performance contracts.
Latin America Occupancy Sensors Market Segmentation
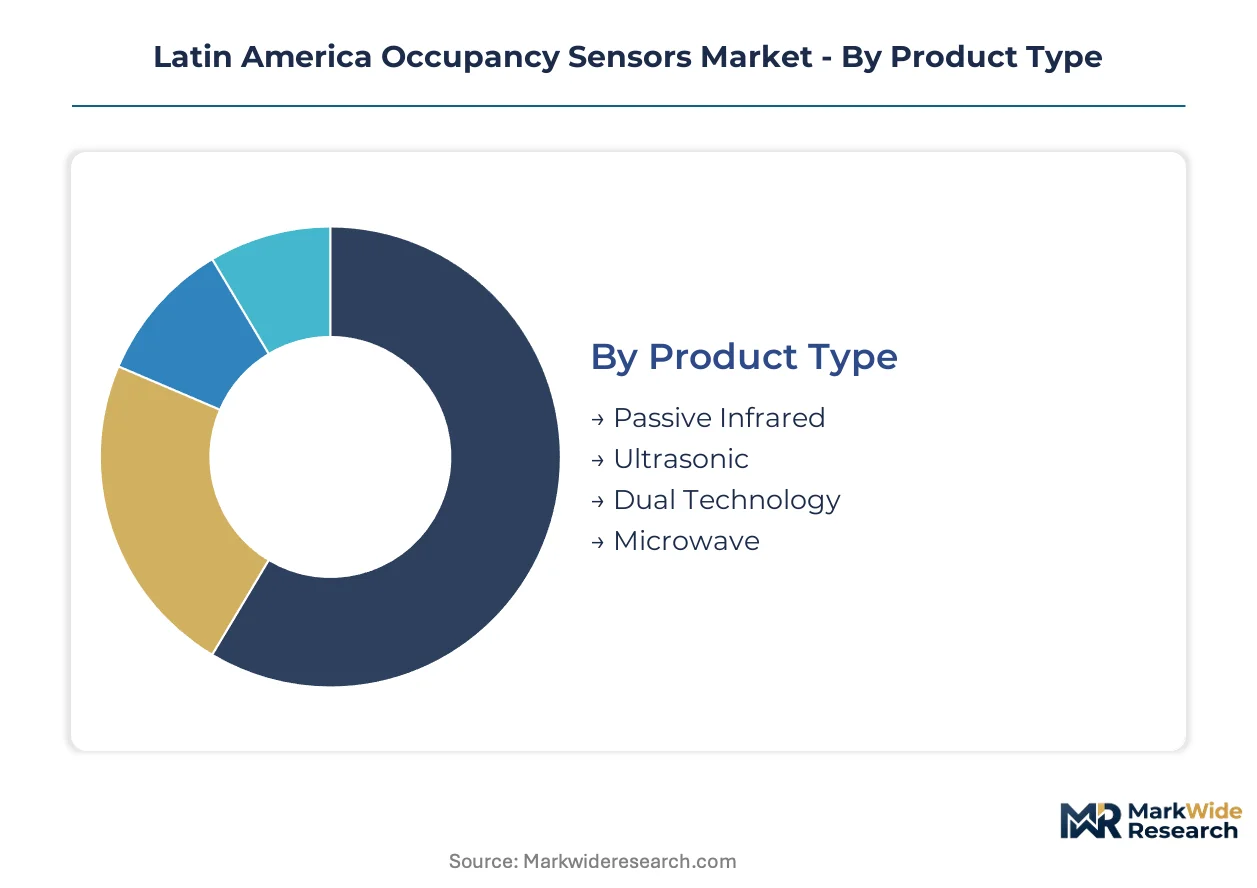
Occupancy sensor procurement across Latin America fragments across technology maturity, infrastructure legacy, and end-user sophistication. Suppliers must align product portfolios with distinct installation constraints and certification requirements that vary by building type and buyer category.
Product Type:
Standardization dominates at the low end with commoditized infrared units, while dual-technology and microwave variants demand application-specific calibration for Brazilian and Mexican commercial environments.
- Passive Infrared:These sensors detect body heat through pyroelectric elements, typically covering 180-degree arcs at ranges up to 30 feet. Brazilian residential retrofits and price-sensitive commercial corridors in Mexico City concentrate demand here, driven by INMETRO certification cost thresholds that favor simpler electronics.
- Dual Technology:PIR-ultrasonic fusion reduces false triggers below 2% through cross-correlation algorithms. São Paulo hospital facility managers specify these units for patient monitoring zones where reliability overrides unit cost sensitivity.
- Ultrasonic:High-frequency sound wave detection excels in irregular room geometries where line-of-sight infrared fails. Mexican industrial warehouses deploy these for rack-aisle coverage.
- Microwave:Doppler-based detection penetrates partitions and glass, serving Brazilian open-plan offices requiring zone granularity without surface mounting constraints.
Most installed capacity flows through Passive Infrared. Expansion is steepest in Dual Technology.
Application:
Volume concentrates in commercial new-build, while retrofit complexity and regulatory pressure reshape healthcare and industrial deployment timelines.
- Commercial Buildings:Office towers and retail complexes across Monterrey and Guadalajara specify occupancy-triggered HVAC and lighting as baseline infrastructure. CONUEE commercial energy codes are forcing mechanical contractors to treat automation as default rather than upgrade.
- Healthcare Facilities:Patient rooms, surgical suites, and corridor networks demand 24/7 reliability with minimal false triggers. Brazilian hospital construction in São Paulo and Rio de Janeiro anchors specialized procurement for clinical-grade detection.
- Residential Spaces:Wireless retrofit architectures bypass conduit limitations in pre-2010 Latin American housing stock. Homeowners prioritize battery-powered PIR units for garage and entryway automation.
- Industrial Settings:High-bay warehouses and manufacturing floors require extended-range detection with dust and vibration tolerance. Mexican automotive supplier plants near Toluca drive specification for ruggedized housings.
Commercial Buildings absorb the largest share of sensor volume. Healthcare Facilities are climbing the fastest as efficiency mandates tighten.
Connection Type:
Legacy wired infrastructure dominates institutional procurement, while wireless protocols capture residential and retrofit commercial where conduit access is prohibitively expensive.
- Wired:Hardwired 120V/240V installations deliver reliable power and signal integrity for new Brazilian commercial construction. Facility managers with multi-year energy performance contracts prefer these for maintenance predictability.
- Wireless:Battery-operated and energy-harvesting units eliminate electrical rough-in costs. Mexican residential retrofits and heritage building upgrades concentrate demand here.
- Powerline Communication:Data transmission over existing electrical wiring serves industrial settings with robust power infrastructure but limited network cabling.
- Ethernet:PoE-enabled sensors integrate directly with building management system backbones. Large São Paulo commercial real estate investment trusts specify these for centralized analytics platforms.
Wired connections still handle most sensor traffic. Wireless is gaining share fastest where retrofit economics dominate.
End User:
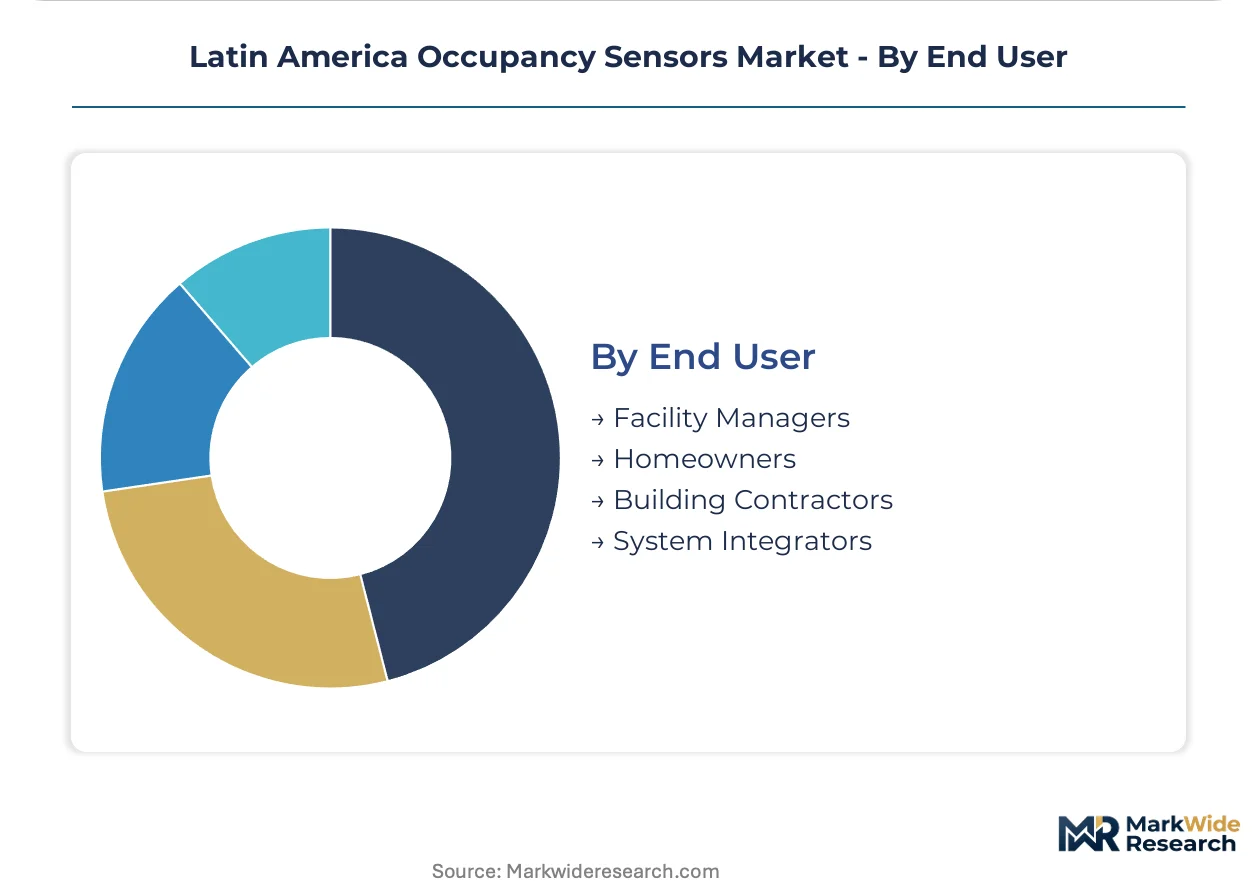
Procurement authority is consolidating under portfolio-scale facility managers, fragmenting the traditional contractor-driven specification channel.
- Facility Managers:Multi-building operators across Brazilian and Mexican commercial real estate investment trusts negotiate master service agreements bundling sensor deployment with energy performance guarantees.
- Building Contractors:Electrical and mechanical contractors specify sensors during shell construction to avoid CONUEE retrofit penalties. Pre-wiring during Mexican office development in Monterrey and Guadalajara is becoming standard practice.
- System Integrators:Technology providers unify detection, actuation, and analytics into single platforms. Bluetooth mesh convergence is opening unified lighting control contracts for these specialists.
- Homeowners:Individual residential buyers prioritize plug-and-play wireless units with smartphone configuration. Price sensitivity limits this segment to PIR basics.
Facility Managers control the largest procurement volume. System Integrators are expanding most quickly as platform consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's metropolitan construction corridor anchors Latin American occupancy sensor deployment, with Brazilian and Mexican facility managers driving automation procurement across healthcare and commercial verticals.
Brazil
Hospital HVAC automation and commercial new-build specifications concentrate demand in São Paulo and Rio de Janeiro. INMETRO certification mandates filter import competition and elevate margins for compliant electrical equipment suppliers. São Paulo-based commercial real estate investment trusts bundle sensor deployment with multi-year energy performance contracts.
Mexico
CONUEE commercial building energy codes force mechanical contractors to specify occupancy-triggered automation as baseline infrastructure. Monterrey and Guadalajara office developers pre-wire sensor infrastructure during shell construction to avoid retrofit penalties. Mexican industrial zones near Toluca drive specification for ruggedized detection systems in automotive supplier plants.
Colombia
Bogotá and Medellín office development corridors remain undersupplied with building automation infrastructure relative to Brazilian saturation. The country's national energy efficiency regulator maintains certification thresholds that shape import access. Colombian facility managers prioritize wireless retrofit architectures to bypass conduit limitations in existing commercial stock.
Chile
Mining sector facility automation and Santiago commercial construction anchor detection system procurement. The national electrical safety regulator sets equipment compliance standards that filter supplier participation. Santiago's corporate headquarters concentration drives specification for integrated building management platforms.
Argentina
Buenos Aires metropolitan healthcare renovation and commercial retrofit activity sustain sensor demand despite macroeconomic volatility. The country's federal energy efficiency agency maintains labeling requirements for electrical equipment. Argentine facility operators concentrate procurement in Buenos Aires province where construction activity exceeds interior provinces.
Latin America Occupancy Sensors Market Competitive Landscape
Strategic partnerships dominate the current landscape as building technology providers converge detection, actuation, and analytics into unified platforms. The vendor base spans three tiers: diversified electrical conglomerates with building management integration capabilities, specialized sensor manufacturers with calibration expertise, and regional distributors serving contractor channels. Consolidation pressure intensifies as facility management procurement shifts toward master service agreements. Technology licensing and portfolio diversification represent the dominant competitive moves.
Among European-based electrical conglomerates, Schneider Electric SE, Siemens AG, and Legrand SA exemplify the building management integration archetype. These companies occupy positions where detection hardware converges with broader environmental control platforms. Schneider Electric SE anchors this tier through Brazilian healthcare infrastructure relationships. Siemens AG exemplifies specialized detection capabilities for clinical settings. Legrand SA navigates certification frameworks through localized testing partnerships that accelerate product registration timelines.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Honeywell International Inc |
| Signify Holding BV |
| Eaton Corp PLC |
| Johnson Controls Inc |
| Legrand SA |
| General Electric Co |
| Siemens AG |
| Texas Instruments Inc |
| Others |
Supply & Pricing Matrix
CONUEE commercial building energy codes in Mexico and INMETRO efficiency mandates in Brazil gate qualified supply access and premium-tier pricing power for occupancy sensor suppliers, compressing margins for uncertified imports while elevating certified product premiums.
Pricing Analysis
Distributor margins for electrical equipment in São Paulo and Mexico City typically absorb 25-35 points before reaching facility managers, with direct-to-OEM relationships compressing this layer for large portfolio owners. Three-tier pricing structure across premium dual-technology, standard PIR, and economy infrared levels tracks certification grade and wireless connectivity bundling. Cost compression in standard PIR tiers is intensifying because manufacturing scale economies from Shenzhen suppliers are flooding Latin American channels. Residential retrofit buyers exhibit highest price sensitivity, while Brazilian hospital facility managers prioritize reliability over unit cost.
Supply Chain Analysis
INMETRO local-content testing partnerships and Mexico's CONUEE registration requirements are reshaping sourcing toward Brazilian and Mexican assembly operations with certified component flows. Pyroelectric sensor elements and microcontroller units draw from China, Taiwan, and South Korea, while copper wiring and plastic housings feed from regional Latin American suppliers. Single-source vulnerability concentrates in Shenzhen-based PCB fabrication clusters. Distribution runs through electrical wholesale networks serving independent contractors, with direct manufacturer relationships capturing share among large commercial real estate investment trusts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Latin American occupancy sensors rests on wireless retrofit volume scaling and dual-technology premium tier penetration, with component cost curves from Asian manufacturing feeding downstream pricing flexibility.
For Market Incumbents: Anticipate consolidation pressure from platform-integrating building technology providers by deepening direct relationships with São Paulo-based commercial real estate investment trusts and accelerating INMETRO certification refresh cycles. Channel control through master service agreements represents the critical defensive lever against distributor disintermediation. For New Entrants and Emerging Players: Enter via Colombian commercial construction corridors in Bogotá and Medellín, where building automation infrastructure remains undersupplied relative to Brazilian saturation. Wireless retrofit architectures for pre-2010 commercial stock offer the most penetrable application segment, with Bluetooth mesh lighting control integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for specialized sensor calibration firms because CONUEE and INMETRO registration timelines create captive revenue streams from compliance-dependent buyers. Target mid-cap integrators with established Brazilian healthcare infrastructure relationships. Monitor CONUEE code tightening announcements as the signal indicating accelerated replacement cycle inflection.| Strategic Initiative | Industry Significance |
|---|---|
| INMETRO Certification Investment | Accelerates product registration timelines and filters import competition from Asian suppliers. |
| Bluetooth Mesh Platform Integration | Captures unified lighting control contracts with São Paulo commercial real estate investment trusts. |
| Wireless Retrofit Architecture Launch | Addresses conduit limitations in pre-2010 Latin American commercial and residential building stock. |
| Colombian Distribution Partnership | Establishes presence in Bogotá and Medellín office corridors ahead of infrastructure saturation. |
| Dual-Technology Product Line Expansion | Serves Brazilian hospital patient monitoring zones where reliability overrides cost sensitivity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with facility managers at Brazilian commercial real estate investment trusts, electrical contractors in Monterrey and Guadalajara, and procurement leads at Mexican automotive supplier plants with secondary validation from INMETRO certification databases, CONUEE energy efficiency filings, and customs import records for sensor components. Bottom-up sensor deployment estimates triangulated against top-down building automation spending projections.
Segment-weighting approaches distributed volume and value across technology type, application vertical, connection architecture, and end-user procurement authority throughout the forecast period. CAGRs derived from installation run-rate modeling and regulatory mandate timing assumptions. Forecast inputs incorporated INMETRO certification pipeline data and CONUEE commercial building code revision schedules.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time construction permit data for Colombian and Chilean markets introduce uncertainty bands around near-term volume estimates. Forecasts reflect documented assumptions regarding wireless protocol adoption curves and certification timeline compression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market
Sensors and Controls
Europe Optical Sensors Market
Sensors and Controls
Global Proximity and Displacement Sensors Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market
Sensors and Controls
Industrial Wireless Sensor Market
Sensors and Controls
US Acoustic Sensors Market
Sensors and Controls
Asia-Pacific Wireless Brain Sensors Market
Sensors and Controls
Middle-East and Africa Nanosensors Market
Sensors and Controls
Asia-Pacific MEMS and Sensors Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market
Sensors and Controls
Silicon Photomultiplier (Sipm) Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Europe Nano Sensors Market
Sensors and Controls
Air Flow Monitoring System Market