
 GCC Air Purifiers Market | 2026-2036
GCC Air Purifiers Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Air Purifiers Market Foresight
Activated carbon composite media is pivoting toward synthetic fiber substrates, trimming unit weight and extending adsorption cycles in desert-climate deployments. Philips leverages integrated sensor-to-filter platforms to sustain premium positioning across Gulf retail channels. Honeywell International Inc. anchors its regional presence through localized distribution partnerships with Saudi HVAC contractors. Dyson Limited differentiates via bladeless airflow architectures that compete on aesthetics in high-end residential developments.
GCC air purifiers are electromechanical filtration devices engineered to remove particulate matter, volatile organic compounds, and biological contaminants from enclosed air volumes, typically achieving CADR ratings between 200 and 400 cubic meters per hour for residential units. HEPA Purifiers dominate value capture due to mandatory healthcare specifications, while Activated Carbon Purifiers lead volume in hospitality retrofit programs addressing tobacco and cooking odor remediation. Portable Units currently occupy the largest installation share, though Duct-Integrated Solutions are gaining traction in new commercial construction across Qatar and Kuwait.
The Emirates Authority for Standardization and Metrology and Saudi Standards, Metrology and Quality Organization enforce electrical safety and energy efficiency labeling that shapes product eligibility for government procurement tenders. The UAE's Ministry of Climate Change and Environment has tightened indoor environmental quality guidelines for public buildings, directly expanding specification requirements for multi-stage filtration systems. Stakeholders must monitor evolving Gulf Cooperation Council harmonization talks on appliance efficiency tiers, as unified standards would reshape cross-border supply strategies and certification costs.
Market Dynamics
Healthcare procurement mandates across Saudi Arabia and the UAE are compressing supplier qualification timelines, forcing filtration OEMs to pre-certify multi-stage systems before tender participation. This structural pressure is redrawing competitive entry barriers.
Growth Catalysts
- SFDA Medical Device Registration:Saudi Arabia's tightened classification of HEPA systems as Class I medical devices is channeling institutional buyers toward pre-approved vendor lists, accelerating specification-grade procurement.
- Smart Hospital Construction:Riyadh's healthcare infrastructure pipeline is embedding duct-integrated purification into mechanical specifications, creating captive demand for centralized filtration architectures.
- Activated Carbon Substrate Innovation:Synthetic fiber composites are extending adsorption cycles in high-humidity Gulf climates, reducing maintenance frequency for hospitality operators.
Market Restraints
- Filter Media Supply Concentration:High-efficiency glass microfiber supply concentrates among three Asian manufacturers, exposing GCC assemblers to input volatility and extended lead times.
- Desert Dust Loading Rates:Ambient particulate concentrations in Kuwait and Qatar accelerate pre-filter saturation, compressing replacement intervals and raising total cost of ownership for residential users.
- Energy Efficiency Labeling Friction:Divergent testing protocols between ESMA and SASO create dual certification burdens for suppliers targeting cross-border distribution.
Strategic Opportunities
- Bahrain Hospitality Retrofit:Luxury hotel renovation cycles are specifying odor-remediation systems for smoking lounges and food service zones, opening volume deployment of activated carbon-dominant units.
- Oman Residential Underpenetration:Household air purifier ownership rates trail UAE benchmarks by a significant margin, presenting first-mover positioning for retail-channel entrants.
- IoT-Enabled Predictive Maintenance:Sensor-integrated platforms are converging with filter lifecycle analytics, enabling subscription-based consumable replenishment models.
Industry Challenges
- Certification Timeline Compression:ESMA conformity assessment periods for electrical air treatment appliances currently exceed commercial construction bidding windows, disqualifying new entrants from fast-track projects.
- HVAC Integration Complexity:Duct-integrated solutions require coordination with MEP contractors during building core-and-shell phases, demanding specialized technical sales capabilities absent from portable-unit distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Air Purifiers Market |
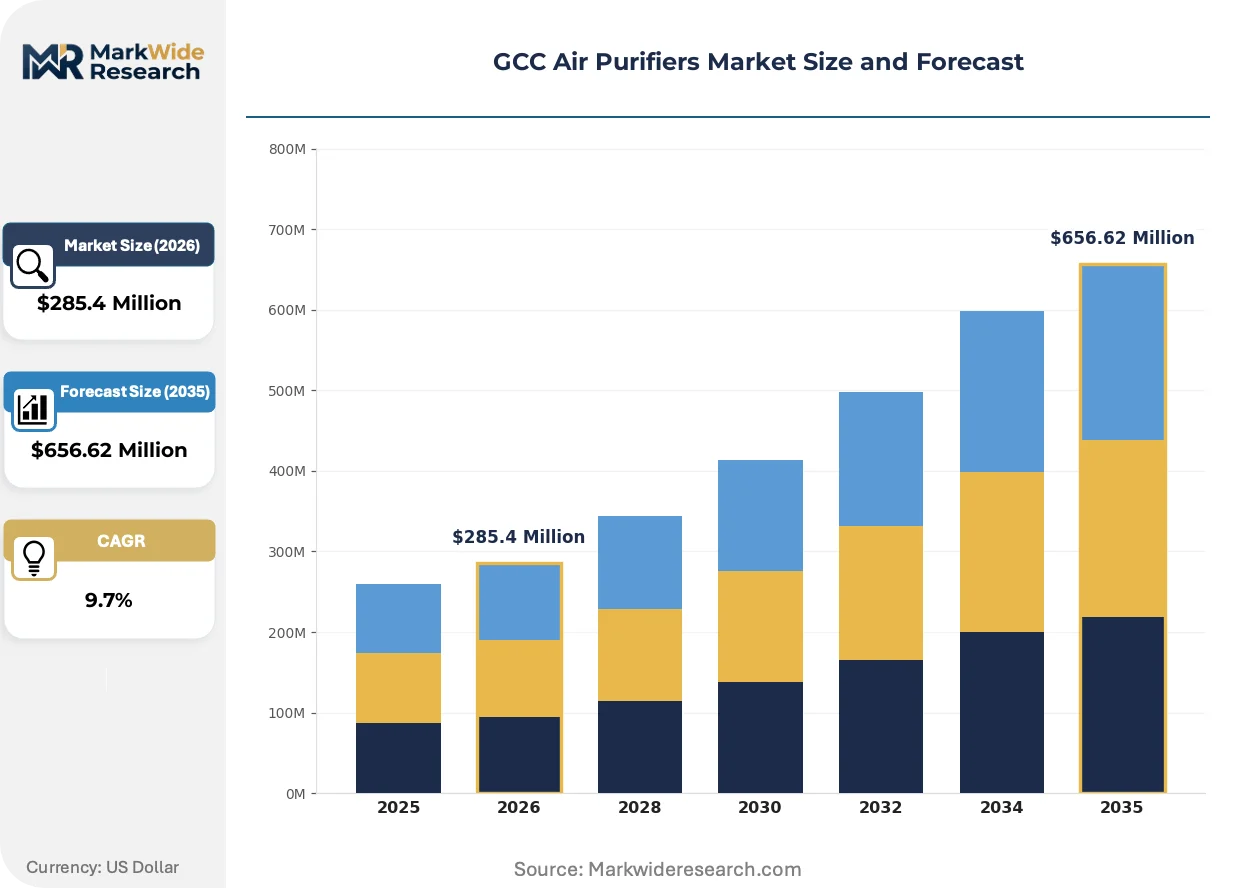
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $656.62 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Purifiers, Activated Carbon Purifiers, UV Air Purifiers, Ionic Air Purifiers, Electrostatic Precipitators Application: Residential Spaces, Commercial Offices, Educational Institutes, Healthcare Facilities, Hospitality Venues Installation: Portable Units, Wall-Mounted Systems, Ceiling-Mounted Devices, Duct-Integrated Solutions, Floor-Standing Models Customer Type: Homeowners, Small Businesses, Educational Administrators, Medical Centers, Hotel Operators |
| Companies Covered | Philips, Honeywell International Inc., Dyson Limited, Sharp Corporation, LG Electronics, Panasonic Corporation, Samsung Electronics Co. Ltd., Blueair AB, Coway Co., Ltd., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Air Purifiers Market Shifts & Advancements
Filtration architectures are converging around intelligence layers that anticipate contaminant loads rather than react to them. This shift is compressing the traditional specification process.
Electrochemical sensor arrays paired with machine-learning algorithms are absorbing real-time particulate and VOC data to modulate fan speeds and filter sequencing. Hospital engineering departments in Dubai are specifying these platforms for critical care zones, and the technology is absorbing specification share from timer-based legacy systems in premium residential towers.
ESMA's updated conformity requirements for electrical air treatment appliances are mandating standardized CADR disclosure and energy efficiency labeling. This regulatory tightening is disqualifying non-compliant imports from retail channels. Healthcare procurement teams are responding by embedding pre-qualification clauses that reference ESMA registration numbers in tender documentation.
Facility managers are unbundling after-sales service from equipment procurement, negotiating multi-year filter replenishment contracts separately from capital purchases. This behavioral shift is compressing distributor margins on hardware while expanding recurring revenue pools for consumable specialists. The pattern is most visible in Qatar's commercial tower segment, where property management firms centralize maintenance across portfolios.
GCC Air Purifiers Market Segmentation
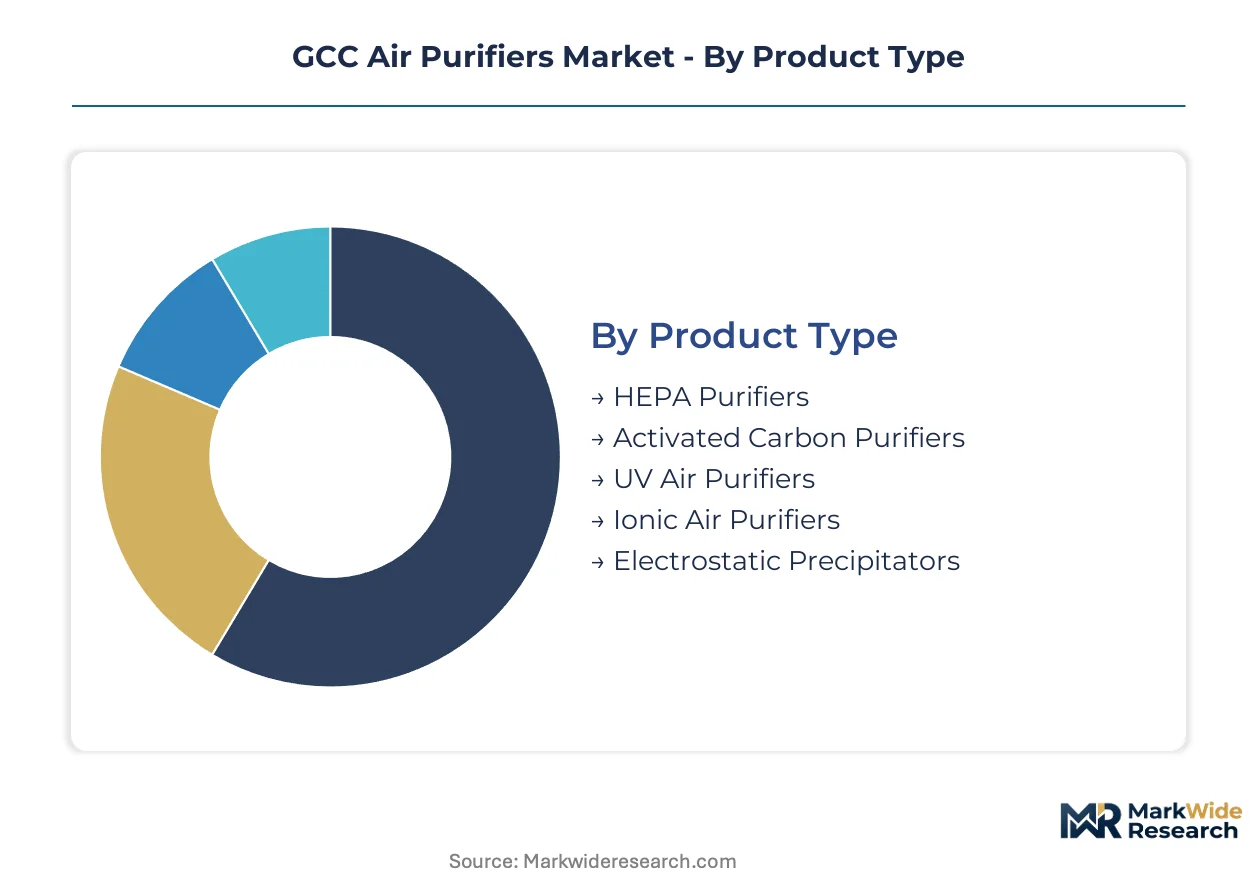
Segmentation in the GCC air purifiers market reveals how filtration architectures align with distinct climate pressures, regulatory mandates, and procurement workflows across the Gulf. Understanding these divides exposes where specification-grade premiums concentrate versus where volume commoditization threatens margins.
Product Type:
Technical sophistication spans from standardized mechanical filtration to advanced oxidation systems, with customization depth tracking end-use criticality and ESMA certification requirements.
- HEPA Purifiers:High-efficiency particulate air systems deploy glass microfiber media rated at 99.97% efficiency for 0.3-micron particles. Saudi healthcare procurement mandates from the Saudi Food and Drug Authority channel institutional demand toward pre-certified HEPA architectures in Riyadh's smart hospital pipeline.
- Activated Carbon Purifiers:Synthetic fiber substrates impregnated with activated carbon adsorb VOCs and gaseous contaminants through physisorption mechanisms. Dubai's hospitality sector specifies these units for smoking lounges and food service zones where odor remediation drives replacement cycles.
- UV Air Purifiers:Ultraviolet-C germicidal irradiation chambers disrupt microbial DNA in healthcare-critical applications.
- Ionic Air Purifiers:Corona discharge technologies precipitate particulates onto collector plates for residential maintenance-light preferences.
- Electrostatic Precipitators:Industrial-grade systems capture sub-micron particles through electrostatic attraction in heavy-duty commercial deployments.
Most installed capacity flows through HEPA Purifiers given mandatory healthcare specifications. Expansion is steepest in Activated Carbon Purifiers as hospitality retrofit programs accelerate across Bahrain and Qatar.
Application:
End-use differentiation tracks indoor air quality liability exposure, with regulatory enforcement intensity determining specification grade and service contract attachment rates.
- Healthcare Facilities:Critical care zones demand multi-stage filtration with HEPA final filters, real-time particle monitoring, and redundant fan arrays. Dubai's Ministry of Health and Prevention guidelines for infection control drive duct-integrated specifications in new hospital construction.
- Hospitality Venues:Luxury properties in Doha and Manama specify odor-remediation systems with high-capacity carbon banks for guest experience differentiation in smoking-permitted environments.
- Residential Spaces:Portable units dominate Riyadh and Dubai apartments where tenant turnover limits permanent installation investment.
- Commercial Offices:LEED-aligned buildings in Kuwait City integrate purification into centralized HVAC for workforce productivity claims.
- Educational Institutes:Abu Dhabi public school procurement favors wall-mounted units with lockable controls for vandalism resistance.
Procurement volume concentrates in Healthcare Facilities where tender mandates enforce premium tier specification. Climbing the fastest is Hospitality Venues as hotel renovation cycles synchronize with post-pandemic guest confidence rebuilding.
Installation:
Physical integration depth determines project phase entry points and technical sales capability requirements, with permanent installations demanding MEP contractor coordination.
- Portable Units:Self-contained floor or tabletop devices with plug-and-play deployment dominate retail channel volume. Kuwait's residential market favors these for seasonal dust storm response without structural modification.
- Duct-Integrated Solutions:Centralized filtration modules install within air handling units during core-and-shell construction, requiring mechanical specification before tenant fit-out. Qatar's commercial tower pipeline embeds these for property-wide air quality management.
- Wall-Mounted Systems:Fixed installations serve permanent spaces in educational and small commercial settings.
- Ceiling-Mounted Devices:Recessed units preserve floor space in premium residential developments.
- Floor-Standing Models:High-CADR tower configurations address open-plan offices without HVAC modification.
Current deployment favors Portable Units for flexibility and lower capital commitment. Gaining share fastest is Duct-Integrated Solutions as new construction across Doha and Riyadh embeds mechanical specifications early.
Customer Type:
Purchasing sophistication varies from individual retail selection to centralized procurement with multi-year service contracts and consumable bundling.
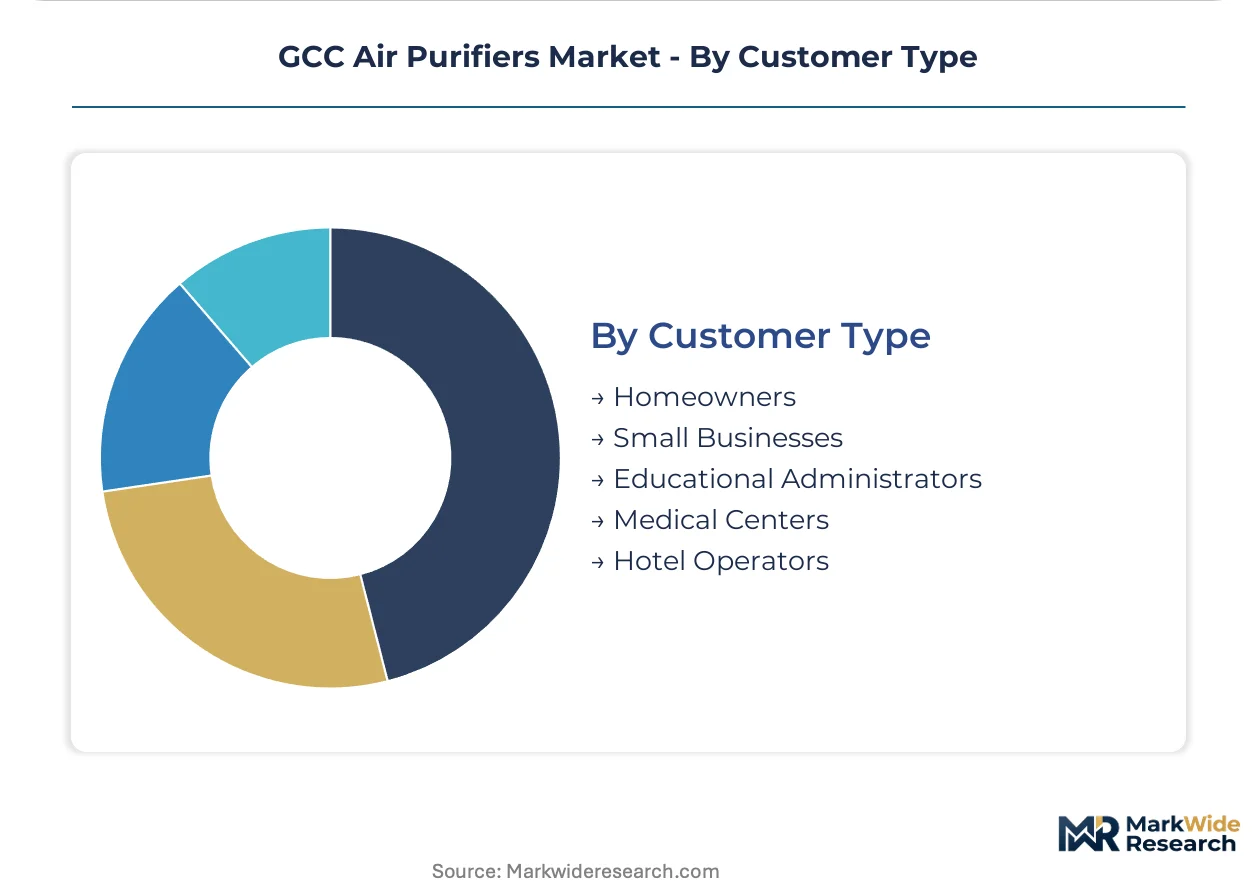
- Medical Centers:Hospital engineering departments issue specification-grade tenders with ESMA registration prerequisites and preventive maintenance clauses. Saudi Arabia's SFDA medical device classification compresses vendor qualification to pre-approved lists.
- Hotel Operators:Property management firms negotiate portfolio-wide filter replenishment contracts separate from capital equipment, shifting margin pools toward consumable specialists.
- Homeowners:Retail channel purchasers prioritize CADR-per-dirham metrics and aesthetic integration.
- Small Businesses:Cost-conscious operators favor portable units with minimal installation disruption.
- Educational Administrators:Government procurement frameworks emphasize durability and vandal resistance over performance optimization.
Contract value concentrates with Medical Centers where regulatory compliance enforces premium procurement. Expanding most quickly is Hotel Operators as facility management unbundling reshapes vendor relationships across the Gulf.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh's smart hospital construction pipeline anchors GCC demand for duct-integrated HEPA systems. Procurement concentrates in Saudi Arabia and the UAE where regulatory tightening compresses vendor qualification timelines.
Saudi Arabia
Riyadh's healthcare infrastructure expansion embeds centralized filtration into mechanical specifications for new hospital wings. The Saudi Food and Drug Authority classifies HEPA systems as Class I medical devices, channeling institutional buyers toward pre-approved vendor lists. Eastern Province industrial zones are specifying heavy-duty electrostatic precipitators for petrochemical facility air handling.
United Arab Emirates
Dubai's luxury hospitality renovation cycles are driving activated carbon unit deployment for smoking lounge odor remediation. The Emirates Authority for Standardization and Metrology mandates standardized CADR disclosure and energy efficiency labeling for electrical air treatment appliances. Abu Dhabi's public school procurement favors wall-mounted units with vandal-resistant controls for educational infrastructure.
Qatar
Doha's commercial tower pipeline embeds duct-integrated solutions during core-and-shell construction phases. The Ministry of Public Health guidelines for indoor environmental quality in healthcare facilities enforce multi-stage filtration specifications. Lusail City's smart district developments are specifying sensor-integrated platforms for property-wide air quality management.
Kuwait
Kuwait City's LEED-aligned commercial buildings integrate purification into centralized HVAC systems for workforce productivity claims. Desert dust loading rates accelerate pre-filter saturation, compressing replacement intervals for residential users. The Public Authority for Industry oversees conformity assessment for electrical appliance imports, shaping retail channel eligibility.
Bahrain
Manama's luxury hotel renovation programs specify high-capacity carbon banks for food service zone odor control. The Ministry of Industry, Commerce and Tourism procurement frameworks emphasize durability specifications for hospitality deployments. Seef District commercial developments are deploying floor-standing high-CADR configurations for open-plan office environments.
GCC Air Purifiers Market Competitive Landscape
Strategic partnerships dominate the current landscape as filtration OEMs seek localized distribution capabilities. The vendor base concentrates around multinational electronics conglomerates with established Gulf retail networks, tiered against specialized HVAC contractors with MEP integration expertise. Three archetypes occupy distinct positions: integrated sensor-to-filter platform providers, bladeless airflow architecture specialists, and synthetic fiber substrate innovators. Capacity expansion and certification pre-qualification constitute the dominant competitive moves as construction bidding windows compress.
Among diversified electronics conglomerates, Philips, Honeywell International Inc., and Dyson Limited exemplify contrasting positioning vectors. Philips occupies a position within the integrated platform tier, anchoring premium retail channel presence through sensor-to-filter architectures. Honeywell International Inc. sits within the industrial systems archetype, leveraging distribution partnerships with Saudi HVAC contractors for specification-grade penetration. Dyson Limited represents the design-forward segment, competing on aesthetics in high-end residential developments through distinctive airflow engineering.
| Leading Market Players |
|---|
| Philips |
| Honeywell International Inc. |
| Dyson Limited |
| Sharp Corporation |
| LG Electronics |
| Panasonic Corporation |
| Samsung Electronics Co. Ltd. |
| Blueair AB |
| Coway Co., Ltd. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap filtration specialists across South Korea and Japan anchor high-efficiency glass microfiber supply, translating concentrated ownership into disciplined capacity allocation and premium pricing power for GCC assemblers. Their selective customer prioritization shapes procurement timelines for Riyadh hospital contractors and Dubai hospitality developers alike.
Pricing Analysis
Input-cost pass-through from synthetic fiber substrate and activated carbon media suppliers shapes tiered pricing across certification grades. Three-tier pricing structure across premium, standard, and economy levels separates ESMA-registered medical-grade systems from retail-channel consumer units. Cost compression in the standard tier is intensifying because hospitality procurement teams unbundle hardware from filter replenishment contracts. Residential homeowners in Kuwait exhibit highest price sensitivity, while Saudi medical centers accept premium positioning for SFDA Class I device compliance.
Supply Chain Analysis
Single-source vulnerability sits with three Asian manufacturers controlling high-efficiency glass microfiber output, exposing GCC assemblers to allocation decisions made in Seoul and Osaka. Raw material flows draw from South Korean synthetic fiber producers, Japanese precision media formulators, and Chinese carbon activation facilities. Tariff exposure through Gulf Cooperation Council customs harmonization gaps threatens cross-border component movements. Distribution runs through Saudi HVAC contractor networks for specification-grade projects, while retail channels in Dubai and Riyadh rely on electronics conglomerate storefronts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC air purifiers function as a stable compounder, with healthcare procurement mandates from Saudi Arabia's SFDA and UAE's ESMA embedding recurring replacement demand into institutional budgets.
For Market Incumbents: Deepen sensor-to-filter platform integration to defend against emerging IoT-native entrants from Shenzhen. Anchor certification investment in SASO and ESMA pre-qualification lists before Riyadh smart hospital bidding windows compress further. Prioritize backward integration into synthetic fiber substrate production to offset Asian supplier concentration. For New Entrants and Emerging Players: Omani residential households represent the most penetrable buyer archetype, with ownership rates trailing UAE benchmarks by substantial margins. Bahrain luxury hotel renovation cycles offer hospitality retrofit entry without incumbent specification lock-in. Pursue direct distribution partnerships with Manama and Muscat retail chains rather than competing for Saudi institutional tenders. For Investors and Strategic Acquirers: HVAC contractors with MEP integration capabilities are the most active acquirer in this space, consolidating technical sales expertise for duct-integrated solutions. Target mid-cap filtration OEMs holding ESMA registration numbers and established Saudi distribution relationships. Watch for Gulf Cooperation Council harmonization talks on appliance efficiency tiers as the inflection signal for cross-border supply strategy consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ESMA Pre-Certification Investment | SASO registration compresses vendor qualification timelines for Saudi healthcare tenders. |
| Sensor-to-Filter Platform Integration | Philips and Honeywell anchor premium positioning through real-time contaminant modulation. |
| Synthetic Fiber Substrate Backward Integration | Reduces dependency on three Asian glass microfiber suppliers for GCC assemblers. |
| Hospitality Filter Replenishment Contracting | Qatar property management firms unbundle service from hardware procurement. |
| Oman Retail Channel Partnership | First-mover positioning captures underpenetrated residential demand outside UAE-Saudi core. |
Research Methodology
Multiple input streams — primary interviews with hospital procurement managers, HVAC contractor technical directors, and ESMA conformity assessment officers; secondary validation through Saudi SFDA medical device registrations, UAE ESMA certification databases, and customs import records — were reconciled using bottom-up installation tracking and top-down market sizing across the analysis window.
Data-stream reconciliation anchored volume projections to modeled segmentation across product type, application, installation depth, and customer purchasing sophistication. CAGRs were derived from trend extrapolation of healthcare infrastructure pipelines, hospitality renovation cycles, and regulatory enforcement intensity. Forecast inputs incorporated Saudi smart hospital construction schedules, Dubai luxury property development permits, and GCC cross-border trade flow patterns.
Underlying measurement precision varies by segment; duct-integrated solutions and medical center procurement carry tighter precision than portable residential retail estimates. Forecasts reflect assumptions around regulatory harmonization timelines and healthcare infrastructure spending continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
SCR Dosing Control Modules Market
Sensors and Controls
Confocal Displacement Sensor Market
Sensors and Controls
Advanced Carbon Dioxide (CO2) Sensors Market
Sensors and Controls
Piezoelectric Polymers Market
Sensors and Controls
Laser Scanner Market
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
MEMS Inertial Sensors Market
Sensors and Controls
Global Mid-And-High-Level Precision GPS Receiver Market
Sensors and Controls
MEMS Energy Harvesting Devices Market
Sensors and Controls
APAC Chemical Sensors Market
Sensors and Controls
Connected Sensors Market
Sensors and Controls
Factory Automation Sensor Market
Sensors and Controls
Sensor Signal Conditioner (SSC) Ics Market
Sensors and Controls
Digital Infrared Thermometer Market