
 Control Knobs for Panel Potentiometer Market | 2026-2036
Control Knobs for Panel Potentiometer Market Size, Share, and Industry Trends Forecast 2026-2036
Control Knobs for Panel Potentiometer Market Insights
REACH compliance is expanding material certification burdens for knob suppliers serving European industrial OEMs. Bourns, Inc. leverages captive polymer compounding to navigate these requirements internally. Alps Alpine Co., Ltd. anchors its position through precision CNC machining capacity in Japan. TT Electronics plc competes on medical-grade aluminum knob portfolios with full lot traceability.
Control knobs for panel potentiometers are mechanical interface components typically molded or machined to mate with rotary shaft potentiometers, featuring standardized bore diameters, knurl patterns, and torque specifications that enable precise manual adjustment of electrical resistance in circuits. These components serve as the human-machine interface in environments where finger-operated analog control outperforms digital alternatives. Metal and aluminum segments command premium positioning due to thermal stability and EMI shielding properties in automotive controls and industrial equipment. Plastic variants sustain volume leadership in consumer electronics where cost minimization dominates procurement criteria. Injection molding technology occupies the highest throughput tier, while CNC machining leads where lot sizes fall below ten thousand units.
The EPA regulates volatile organic compound emissions from injection molding operations affecting domestic knob production. ECHA enforces SVHC disclosure thresholds that reshape composite material formulations across European supply chains. Japan's METI promotes JIS standards for industrial control interfaces that influence export specifications from Asian manufacturers. Stakeholders must monitor evolving material restrictions and automation-ready design standards as analog interfaces persist in safety-critical systems.
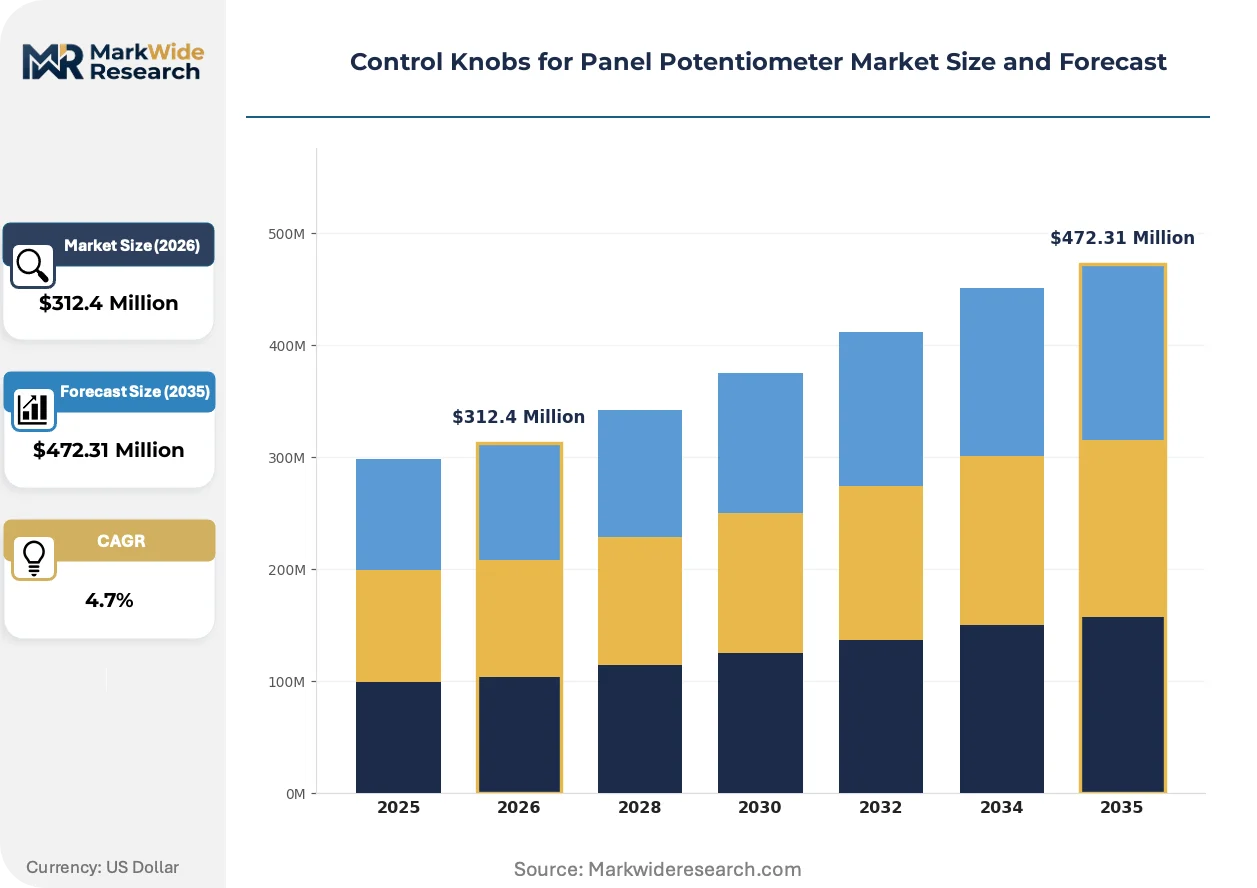
Market Dynamics
Factory automation in Germany and Japan is accelerating demand for metal control knobs with thermal stability and EMI shielding, while REACH compliance in Europe forces material disclosure restructuring across plastic and composite supply chains.
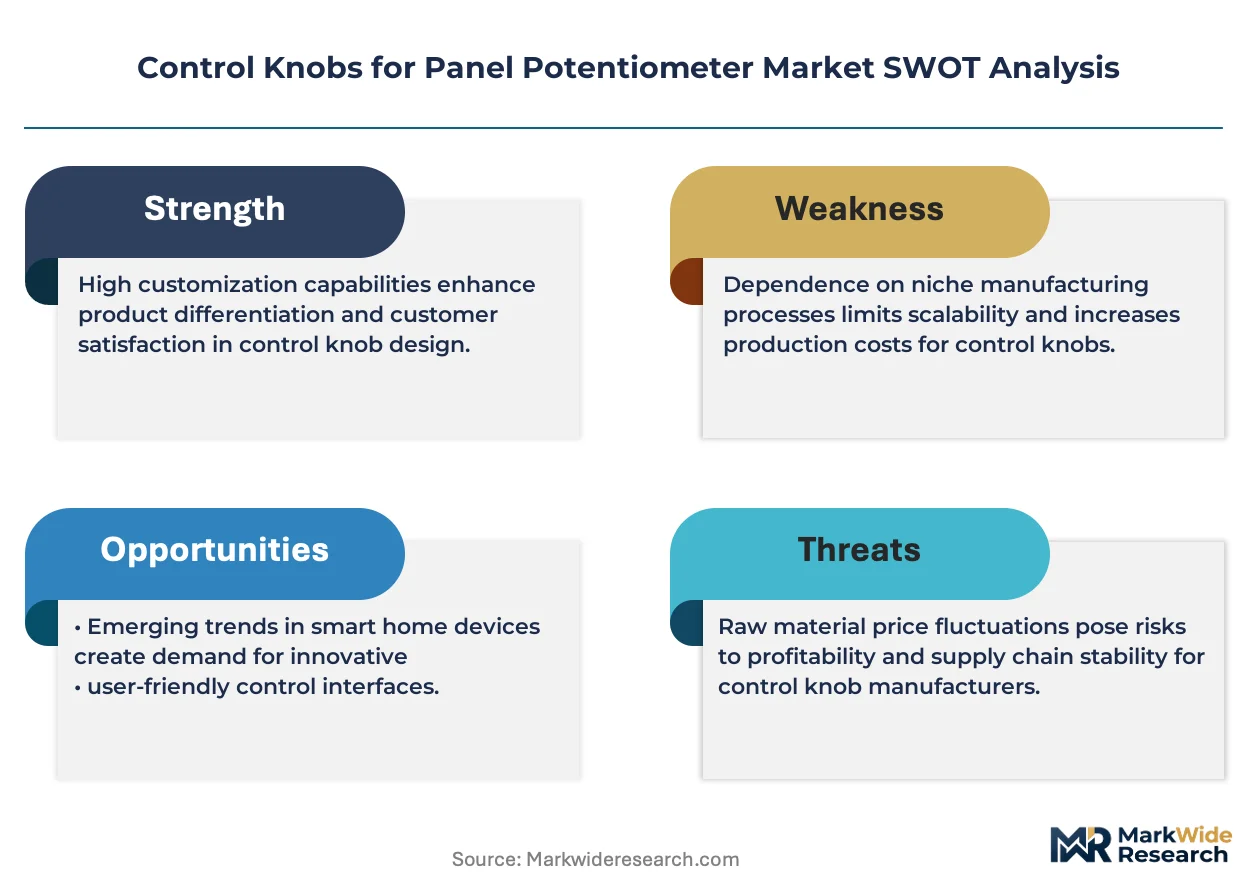
Growth Catalysts
- Automotive Human-Machine Interface Expansion:Analog controls persist in safety-critical vehicle systems where tactile feedback outperforms touchscreens. OEMs specify aluminum knobs for thermal cycling resistance in climate control modules.
- REACH SVHC Disclosure Mandates:ECHA enforcement tightens composite material traceability requirements. Suppliers with captive polymer compounding capabilities capture preference from European industrial OEMs seeking streamlined certification.
- Medical Device Contamination Resistance Standards:Sterilization-compatible aluminum knob designs gain traction in surgical equipment and diagnostic instruments where surface integrity under autoclave cycles matters.
Market Restraints
- Aluminum Price Volatility:LME aluminum fluctuations compress margin structures for precision-machined knob producers serving automotive tier-1 suppliers.
- Injection Molding Capital Intensity:Tooling costs for multi-cavity molds exceed recovery thresholds at lot sizes below ten thousand units, constraining flexibility for medical device contract manufacturers.
- Digital Potentiometer Substitution:Touch-based and software-configurable interfaces displace mechanical knobs in consumer electronics, eroding volume leadership in plastic variants.
Strategic Opportunities
- India Industrial Automation Buildout:PLI scheme incentives for manufacturing equipment create demand for JIS-standard control interfaces among Japanese machinery exporters establishing local assembly.
- EU Green Deal Material Circularity:Recycled aluminum content mandates in industrial equipment procurement specifications favor suppliers with closed-loop machining waste recovery systems.
- Telehealth Hardware Localization:Remote patient monitoring device manufacturers seek medical-grade knob suppliers with FDA-registered quality systems for distributed production models.
Industry Challenges
- Multi-Standard Certification Parallelism:Knob suppliers serving cross-border medical device OEMs must maintain simultaneous FDA 21 CFR Part 820, EU MDR technical documentation, and PMDA foreign manufacturer registration.
- Legacy Equipment Interface Compatibility:Industrial retrofit markets demand shaft bore dimensional tolerances matching decades-old potentiometer specifications, constraining design standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Control Knobs for Panel Potentiometer Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Metal, Rubber, Aluminum, Acrylic, Composite Technology: Injection Molding, Die Casting, CNC Machining, 3D Printing, Metal Stamping Application: Automotive Controls, Consumer Electronics, Industrial Equipment, Medical Devices, Audio Equipment End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers, Equipment Manufacturers |
| Companies Covered | Panasonic Corporation, TT Electronics plc, Alps Alpine Co., Ltd., NKK Switches, CTS Corporation, Bourns, Inc., Honeywell International, Nidec Copal Electronics, Vishay Intertechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Control Knobs for Panel Potentiometer Market Trends and Innovations
Material science advances and regulatory disclosure requirements are compressing supplier qualification timelines while fragmenting procurement specifications across end-use verticals.
Multi-material hybrid knob construction is rewriting thermal management and tactile precision trade-offs in automotive climate control applications. Tier-1 suppliers specify aluminum cores with overmolded polymer grip surfaces to meet both EMI shielding and haptic feedback requirements. This convergence is compressing the traditional metal-versus-plastic sourcing decision into integrated single-source relationships.
ECHA REACH SVHC candidate list expansion is forcing reformulation of glass-filled nylon compounds used in industrial control knobs. Compounders must disclose full substance composition down to 0.1% weight thresholds, extending material qualification cycles for European OEMs. Medical device manufacturers respond by accelerating aluminum knob specifications that bypass polymer disclosure complexity entirely.
Direct procurement from CNC machining job shops is displacing traditional distributor intermediaries in low-volume medical and aerospace segments. Buyers with internal metrology capabilities now source precision-machined aluminum knobs through online manufacturing platforms that expose shop-floor capacity and lot traceability data. This channel shift is most pronounced in North American and German markets where ISO 13485-certified machine shops cluster regionally.
Control Knobs for Panel Potentiometer Market Segmentation
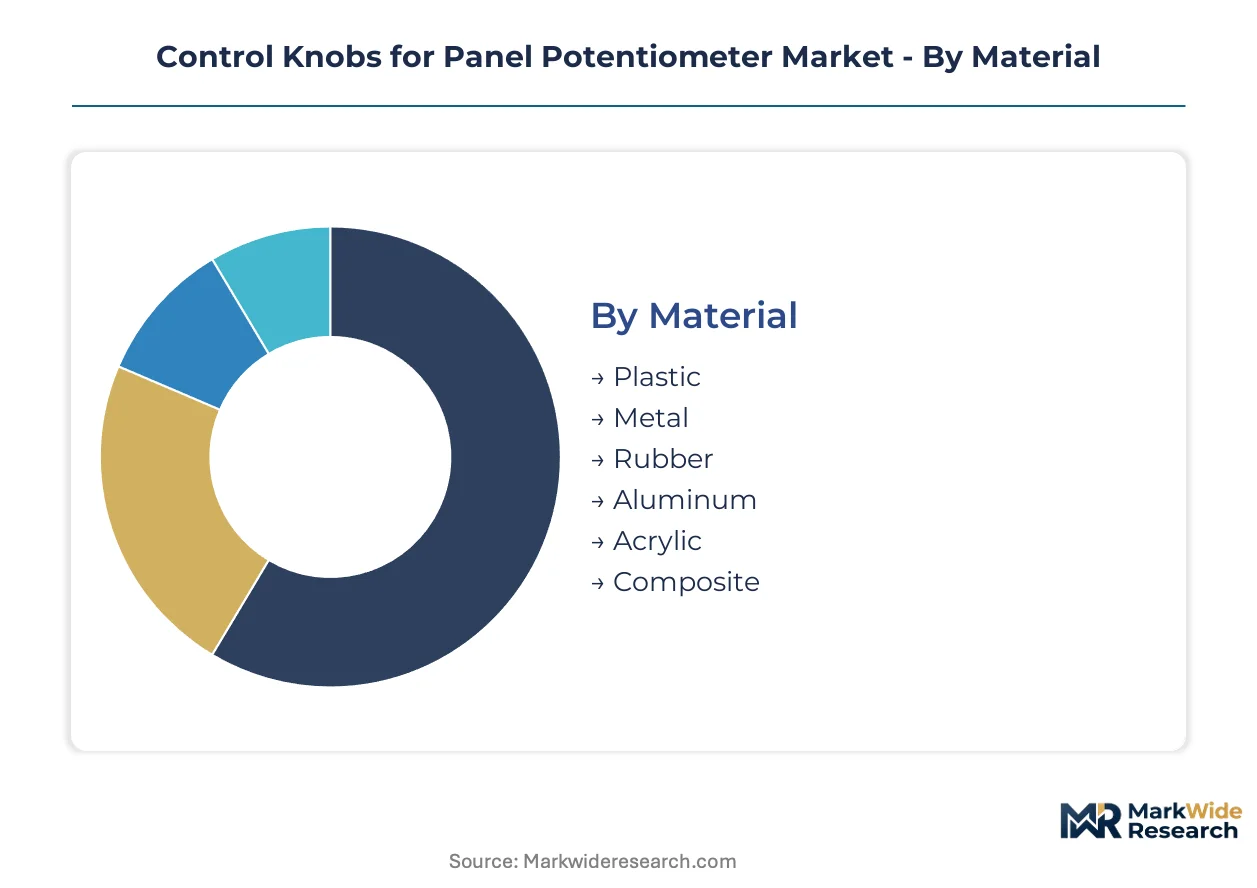
Control knob procurement splits across material performance tiers, manufacturing scale thresholds, and regulatory compliance burdens that reshape supplier-customer relationships. Each segmentation dimension carries distinct margin structures and qualification timelines that determine competitive positioning.
Material:
Customization intensity spans from commodity thermoplastics to aerospace-grade aluminum alloys with full lot traceability requirements.
- Plastic:Injection-molded ABS and polycarbonate formulations dominate consumer electronics volume. Cost minimization drives procurement in remote controls and small appliances where tactile precision requirements remain modest.
- Metal:Brass and steel knob variants serve industrial equipment where shaft retention torque and thermal cycling resistance matter. German factory automation OEMs specify zinc-plated finishes for corrosion protection in humid manufacturing environments.
- Rubber:Overmolded thermoplastic elastomer grips enhance haptic feedback in automotive climate controls. Soft-touch surfaces reduce operator fatigue during prolonged adjustment sequences.
- Aluminum:Precision-machined 6061-T6 and 7075 alloys deliver EMI shielding for medical devices and automotive electronics. Anodized finishes meet sterilization compatibility requirements in surgical equipment.
- Acrylic:Transparent and translucent variants enable backlighting integration in audio mixing consoles and broadcast equipment. Laser-etched legends support custom branding without secondary printing operations.
- Composite:Glass-filled nylon compounds balance structural rigidity with weight reduction in aerospace control panels. REACH SVHC disclosure mandates are forcing reformulation cycles among European compounders.
Most installed capacity flows through Plastic. Expansion is steepest in Aluminum.
Technology:
Capital intensity and lot size economics determine process selection across medical, automotive, and industrial volume tiers.
- Injection Molding:Multi-cavity tooling achieves unit economics below ten cents at million-piece annual volumes. Automotive tier-1 suppliers favor this process for climate control module knobs with standardized shaft interfaces.
- Die Casting:Zinc and aluminum alloy casting produces complex geometries with thin-wall sections for weight-sensitive aerospace applications. Porosity control remains critical for medical device acceptance criteria.
- CNC Machining:Five-axis milling centers deliver ±0.025mm tolerances for medical and laboratory equipment where lot traceability and surface finish specifications dominate. Low-volume flexibility supports prototyping through production transitions.
- 3D Printing:Selective laser sintering and fused deposition modeling enable rapid customization for replacement parts in legacy industrial systems. Material anisotropy limits structural load applications.
- Metal Stamping:Progressive die operations form thin-gauge aluminum and steel for cost-sensitive consumer electronics. Knurl patterns and indicator lines integrate in single press cycles.
Injection Molding commands the highest throughput volumes. CNC Machining is expanding most quickly in medical device supply chains.
Application:
End-use environments dictate material selection, certification requirements, and supplier qualification rigor.
- Automotive Controls:Climate modules and infotainment systems specify aluminum cores with polymer overmolds for EMI compliance and tactile feedback. Thermal cycling from -40°C to 85°C drives material selection.
- Consumer Electronics:Remote controls and personal audio equipment prioritize cost minimization over durability. Plastic variants sustain volume leadership despite touchscreen displacement trends.
- Industrial Equipment:Factory automation interfaces in Germany and Japan specify metal knobs with contamination resistance for food processing and cleanroom environments. JIS standard compliance enables cross-border machinery exports.
- Medical Devices:Surgical equipment and diagnostic instruments demand aluminum knob designs with autoclave sterilization compatibility. FDA 21 CFR Part 820 quality systems govern supplier selection.
- Audio Equipment:Professional mixing consoles and broadcast gear emphasize precision detent mechanisms and weighted feel. Custom machining supports low-volume, high-aspiration product positioning.
Industrial Equipment channels the largest procurement volumes. Medical Devices are gaining share fastest.
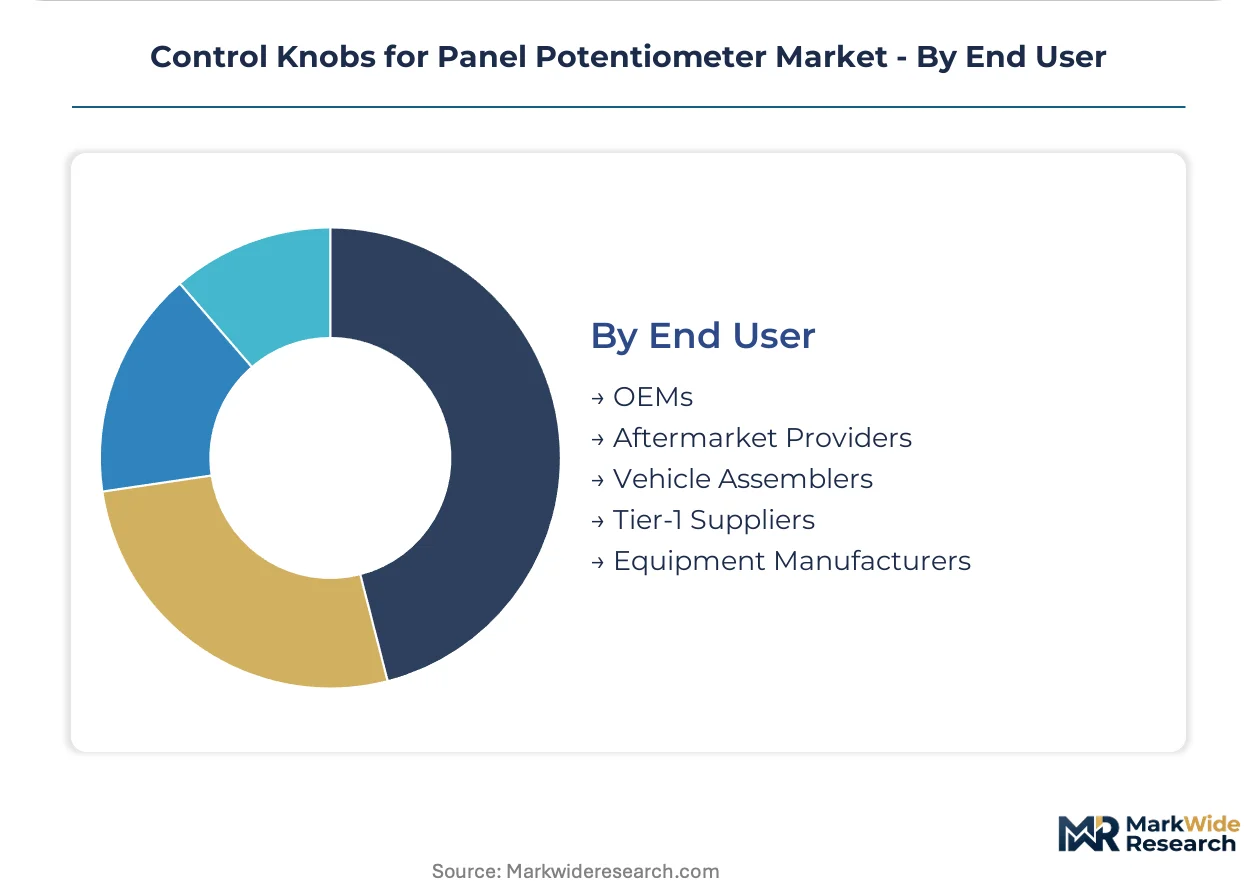
End User:
Supply chain position determines specification authority, volume predictability, and technical support requirements.
- OEMs:Original equipment manufacturers in automotive and medical verticals control material specifications and qualify secondary suppliers directly. Long-term agreements stabilize capacity planning.
- Aftermarket Providers:Replacement part distributors serve repair markets for legacy industrial and audio equipment. Shaft dimensional compatibility with decades-old potentiometer specifications constrains design freedom.
- Vehicle Assemblers:Final automotive manufacturers consolidate knob procurement through tier-1 module suppliers. Platform standardization across vehicle lines drives volume concentration.
- Tier-1 Suppliers:Climate control and infotainment module manufacturers intermediate between assemblers and component vendors. Design-in relationships span multi-year program lifecycles.
- Equipment Manufacturers:Industrial machinery builders in Germany and Japan specify JIS-standard interfaces for export compatibility. PLI scheme incentives in India are attracting Japanese machinery exporters to local assembly partnerships.
Tier-1 Suppliers manage the highest procurement volumes. Equipment Manufacturers are expanding most rapidly in emerging industrial automation markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision machining talent clusters in Stuttgart, Nagoya, and Shenzhen anchor the geographic distribution of control knob manufacturing expertise. Tool-and-die specialists and CNC operators concentrate in these industrial corridors, shaping regional competitive advantages. Regulatory divergence across major economies fragments material certification pathways.
Germany
Factory automation OEMs in Bavaria and Baden-Württemberg specify metal knobs with JIS-compatible shaft interfaces for machinery exports. ECHA REACH SVHC disclosure mandates force compounders to restructure glass-filled nylon formulations. The Stuttgart metropolitan area hosts precision machining job shops serving medical device tier-1 suppliers with ISO 13485-certified capacity.
Japan
METI promotes JIS standards for industrial control interfaces that influence specifications across Asian supply chains. Automotive climate module manufacturers in the Nagoya-Chubu corridor demand aluminum cores with polymer overmolds for EMI compliance. Osaka-based fabricators maintain captive polymer compounding to navigate material traceability requirements.
United States
EPA volatile organic compound regulations constrain injection molding operations affecting domestic plastic knob production. Medical device OEMs in the Minneapolis-St. Paul cluster source aluminum knobs with full lot traceability for surgical equipment. FDA 21 CFR Part 820 quality systems govern supplier qualification timelines.
China
MIIT industrial upgrading policies accelerate automation equipment deployment across the Yangtze River Delta. Precision machining capacity concentrates in Suzhou and Dongguan for export-oriented medical and automotive contracts. GB standards for electronic components increasingly align with JIS specifications for machinery exports.
India
PLI scheme incentives for manufacturing equipment attract Japanese machinery exporters to Gujarat and Maharashtra assembly partnerships. BIS certification requirements reshape material specifications for industrial control interfaces. The Pune-Ahmedabad corridor develops CNC machining clusters serving medical device contract manufacturers.
Control Knobs for Panel Potentiometer Market Competitive Landscape
The competitive structure tilts toward vertically integrated component specialists with captive material processing capabilities. Market concentration remains moderate, with tier-1 automotive and medical OEMs maintaining direct qualification relationships across multiple supplier categories. Three archetypes dominate: precision CNC machining houses with medical-grade certifications, polymer compounders with REACH-compliant formulation libraries, and diversified electronics component manufacturers with scale advantages in injection molding. Competitive moves center on backward integration into polymer compounding and geographic expansion through online manufacturing platforms that expose shop-floor capacity data.
Among diversified electronics component manufacturers, Panasonic Corporation and Alps Alpine Co., Ltd. occupy positions exemplifying scale-driven polymer and metal processing capabilities. TT Electronics plc represents the precision-machined aluminum specialist archetype serving medical device supply chains with lot traceability systems. Bourns, Inc. anchors the captive compounding tier, internalizing REACH compliance navigation through in-house polymer formulation control.
| Leading Market Players |
|---|
| Panasonic Corporation |
| TT Electronics plc |
| Alps Alpine Co., Ltd. |
| NKK Switches |
| CTS Corporation |
| Bourns, Inc. |
| Honeywell International |
| Nidec Copal Electronics |
| Vishay Intertechnology |
| Others |
Pricing and Supply Chain Analysis
REACH SVHC disclosure mandates from ECHA are forcing European industrial OEMs to requalify polymer knob suppliers, compressing procurement timelines and shifting volume toward aluminum alternatives that bypass material certification complexity entirely. This specification pivot rewards suppliers with captive compounding or precision machining capabilities while squeezing margin structures for distributors caught between reformulation costs and fixed contract pricing.
Pricing Analysis
Bundled material-certification services increasingly separate premium suppliers from commodity competitors in this market. Three-tier pricing structure across medical-grade, industrial-standard, and consumer-economy levels reflects certification burden differentiation, with FDA-registered aluminum knob producers commanding substantial premiums over injection-molded plastic alternatives. Pricing pressure stems from LME aluminum volatility that compresses margins for CNC machining houses serving automotive tier-1 suppliers. Medical device OEMs exhibit lowest price sensitivity due to sterilization compatibility requirements, while consumer electronics buyers prioritize unit cost minimization above all other attributes.
Supply Chain Analysis
Single-source vulnerability sits with precision aluminum machining capacity concentrated in Germany, Japan, and select Chinese industrial clusters. Raw material feeds draw from LME-traded aluminum ingots, glass-filled nylon compounds subject to REACH reformulation cycles, and zinc alloys for die-cast industrial variants. Supply chain risk centers on regulatory restriction cascades from ECHA SVHC list expansions that force emergency material substitutions. Distribution runs through tier-1 module suppliers in automotive and direct OEM qualification relationships in medical devices, with online manufacturing platforms displacing traditional distributors in low-volume aerospace and laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by persistent analog interface demand in safety-critical automotive and medical systems where tactile feedback outperforms digital alternatives. Factory automation deepening across German and Japanese industrial corridors sustains replacement cycle visibility.
For Market Incumbents: Hedge against digital potentiometer substitution by deepening polymer compounding capabilities that streamline REACH compliance navigation for European OEMs. Expand CNC machining capacity in Stuttgart and Nagoya clusters to capture medical device lot traceability requirements. Defensive positioning demands backward integration into aluminum scrap recovery systems ahead of EU Green Deal recycled content mandates.
For New Entrants and Emerging Players: Aftermarket providers serving legacy industrial equipment retrofit markets represent an underserved buyer archetype with dimensional compatibility constraints that deter incumbent redesign efforts. Telehealth hardware localization for remote patient monitoring devices offers penetrable white space requiring only FDA-registered quality systems rather than full medical device certifications. Go-to-market execution should leverage online manufacturing platforms that expose shop-floor capacity and bypass established distributor relationships.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision CNC machining houses holding ISO 13485 certifications and established lot traceability systems for medical device supply chains. Long-term viability across the analysis window favors suppliers with dual aluminum and polymer processing capabilities that navigate material restriction volatility. Watch for ECHA SVHC candidate list expansion velocity as the critical inflection signal determining aluminum versus polymer specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Polymer Compounding | ECHA REACH compliance internalization captures preference from European industrial OEMs seeking streamlined certification pathways. |
| Medical-Grade CNC Capacity Expansion | ISO 13485-certified machining clusters in Stuttgart and Minneapolis-St. Paul secure surgical equipment supplier qualifications. |
| Recycled Aluminum Closed-Loop Systems | EU Green Deal recycled content mandates favor machining waste recovery capabilities in industrial equipment procurement. |
| Online Manufacturing Platform Integration | Direct shop-floor capacity exposure displaces distributor intermediaries in low-volume medical and aerospace segments. |
| JIS Standard Compliance Investment | METI-promoted interface specifications enable cross-border machinery exports from Japanese automation OEMs. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with procurement directors at automotive tier-1 suppliers, quality systems managers at medical device OEMs, plant engineers at German factory automation manufacturers, and channel partners in industrial distribution informed demand-side dynamics. Secondary validation drew from ECHA SVHC candidate list publications, FDA 21 CFR Part 820 guidance documents, METI JIS standard specifications, and SEC filings from diversified electronics component manufacturers. This dual approach triangulates volume estimates against disclosed capacity and shipment data.
Input-output matrix framing connects aluminum and polymer raw material flows through injection molding, CNC machining, and die-casting processes to end-use applications across automotive, medical, industrial, and consumer electronics segments. Modeled dimensions span material grade, manufacturing technology, application environment, and supply chain position from OEM through tier-1 to aftermarket. CAGRs derive from segment-level demand elasticity analysis calibrated against historical replacement cycle patterns and regulatory-driven specification shift assumptions. Forecast inputs incorporate PLI scheme incentive trajectories in India and EU Green Deal procurement timeline expectations.
Underlying measurement precision varies by segment; medical device and automotive applications carry tighter precision than consumer electronics and aftermarket replacement channels due to disclosed supplier qualification data availability. Forecasts reflect assumptions about regulatory enforcement continuity, material substitution elasticities, and automation equipment deployment rates that external shocks could materially revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
US Acoustic Sensors Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
Eye Tracking Systems Market
Sensors and Controls
Italy Digital Thermometer Market
Sensors and Controls
Middle East Robotic Sensors Market
Sensors and Controls
Thermal Flow Meter Market
Sensors and Controls
Europe Smart Glove Market
Sensors and Controls
Echo Sounder Market
Sensors and Controls
Global Thermocouple Temperature Sensors Market
Sensors and Controls
Flow Sensor Market
Sensors and Controls
Europe Proximity Sensors Market
Sensors and Controls
Spain Digital Thermometer Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Water Quality Sensor Market