
 Wireless Ph Monitoring Systems Market | 2026-2036
Wireless Ph Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Ph Monitoring Systems Market Analytics
Multi-source component procurement is repositioning supply economics for wireless pH sensor manufacturers. Medtronic leverages captive electrode fabrication to sustain margin control across hospital-grade monitor lines. GE Healthcare anchors North American distribution through direct field-service networks, while Philips Healthcare competes on integrated telemetry platforms that bundle pH with multiparameter sensing.
Wireless pH monitoring systems comprise battery-powered electrochemical sensors, signal conditioning circuits, and radio-frequency transmitters that stream hydrogen-ion concentration data to centralized dashboards without hardwired connections. These devices employ glass or ion-selective field-effect transistor electrodes with typical measurement ranges from 0 to 14 pH and resolution to 0.01 units, serving continuous process control in bioreactors, wastewater streams, and patient gastric monitoring. Portable monitors dominate unit shipments in home healthcare and agricultural spot-testing where mobility outweighs continuous logging needs. Continuous monitoring devices command premium pricing in hospital critical-care settings and industrial bioprocessing, where real-time alkalinity drift triggers automated corrective dosing. Smart sensors represent the fastest-expanding product tier, embedding edge-computing capability that filters noise and transmits only exception-flagged readings to reduce cloud bandwidth load.
FDA 510(k) clearance requirements govern clinical-grade wireless pH monitors marketed for patient diagnostics, while EPA NPDES permits mandate continuous pH logging for municipal and industrial effluent discharge in the United States. ISO 13485 quality-management certification shapes supplier eligibility for OEM partnerships in medical device supply chains. Stakeholders must weigh regulatory pathway duration against sensor-platform versatility when allocating R&D budgets across clinical and environmental end uses.
Market Dynamics
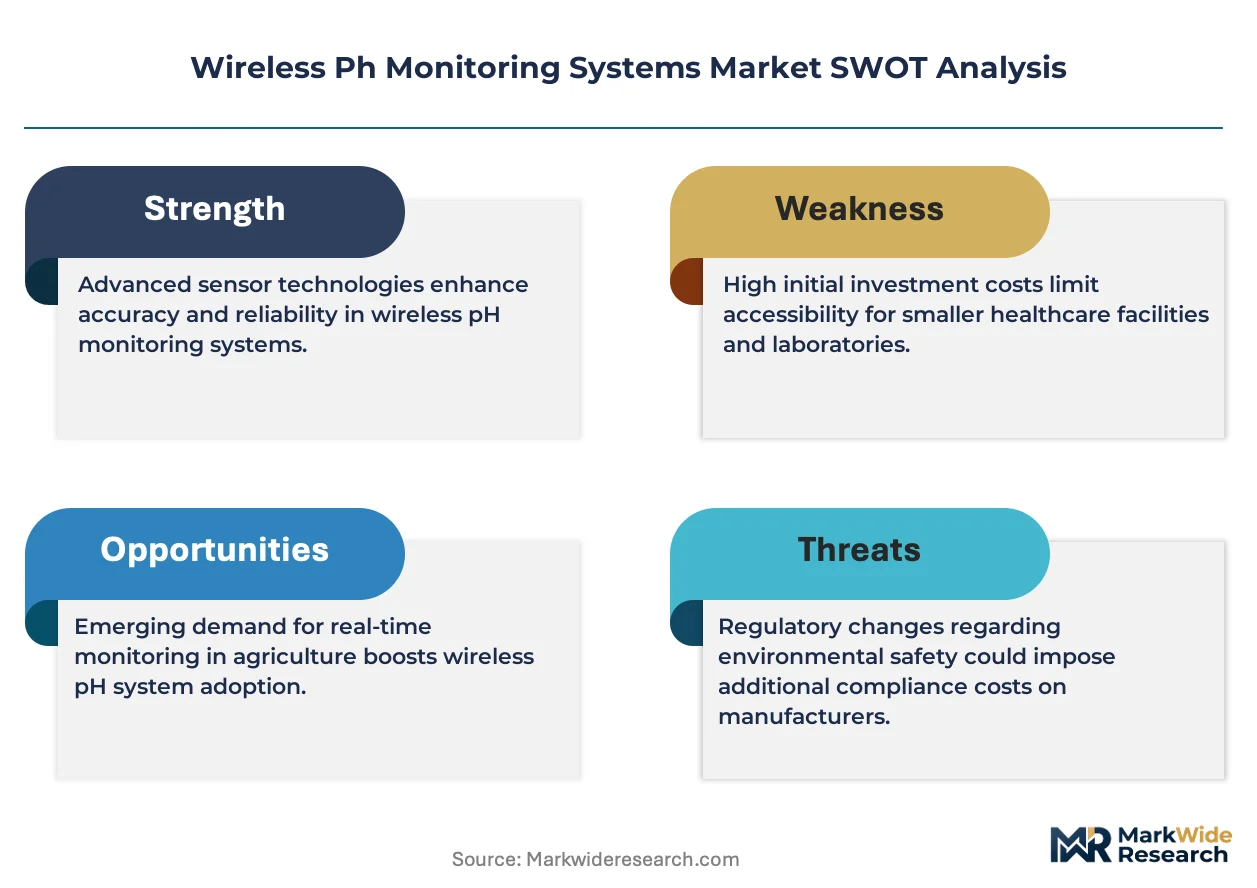
Bluetooth-enabled electrode miniaturization is compressing sensor footprints by half, forcing incumbent manufacturers to retool fabrication lines while opening entry points for modular hardware startups.
Growth Catalysts
- EPA NPDES discharge mandates:Tightened effluent logging requirements compel municipal water treatment utilities across the United States to replace analog pH recorders with wireless telemetry.
- Bioprocessing automation:Continuous bioreactor monitoring in pharmaceutical manufacturing demands real-time alkalinity feedback loops for automated buffer dosing.
- Edge-computing integration:Smart sensors with onboard noise filtering reduce cloud bandwidth consumption, lowering total cost of ownership for distributed monitoring networks.
Market Restraints
- Glass electrode fragility:Ion-selective glass membranes require frequent calibration and replacement in high-particulate wastewater streams, elevating lifetime operating costs.
- Radio-frequency interference:Dense industrial environments with metallic infrastructure degrade Bluetooth signal reliability, necessitating redundant mesh network investments.
- ISO 13485 certification barriers:Medical-grade OEM partnerships demand 12-18 month quality management audits, delaying revenue recognition for clinical sensor developers.
Strategic Opportunities
- Home healthcare penetration:Portable wireless pH monitors for gastric reflux tracking address underdiagnosed patient populations in outpatient settings.
- Agricultural spot-testing:Soil and irrigation water monitoring in precision farming operations creates demand for handheld, smartphone-connected probes.
- EU Green Deal alignment:Carbon-neutral manufacturing incentives accelerate retrofit demand for energy-efficient wireless monitoring in German chemical processing plants.
Industry Challenges
- Electrochemist talent scarcity:Specialized expertise in ion-selective field-effect transistor design concentrates in academic laboratories, constraining commercial R&D throughput.
- Legacy system integration:Industrial facilities with 4-20 mA analog control loops face protocol translation complexity when grafting wireless pH transmitters onto existing SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Ph Monitoring Systems Market |
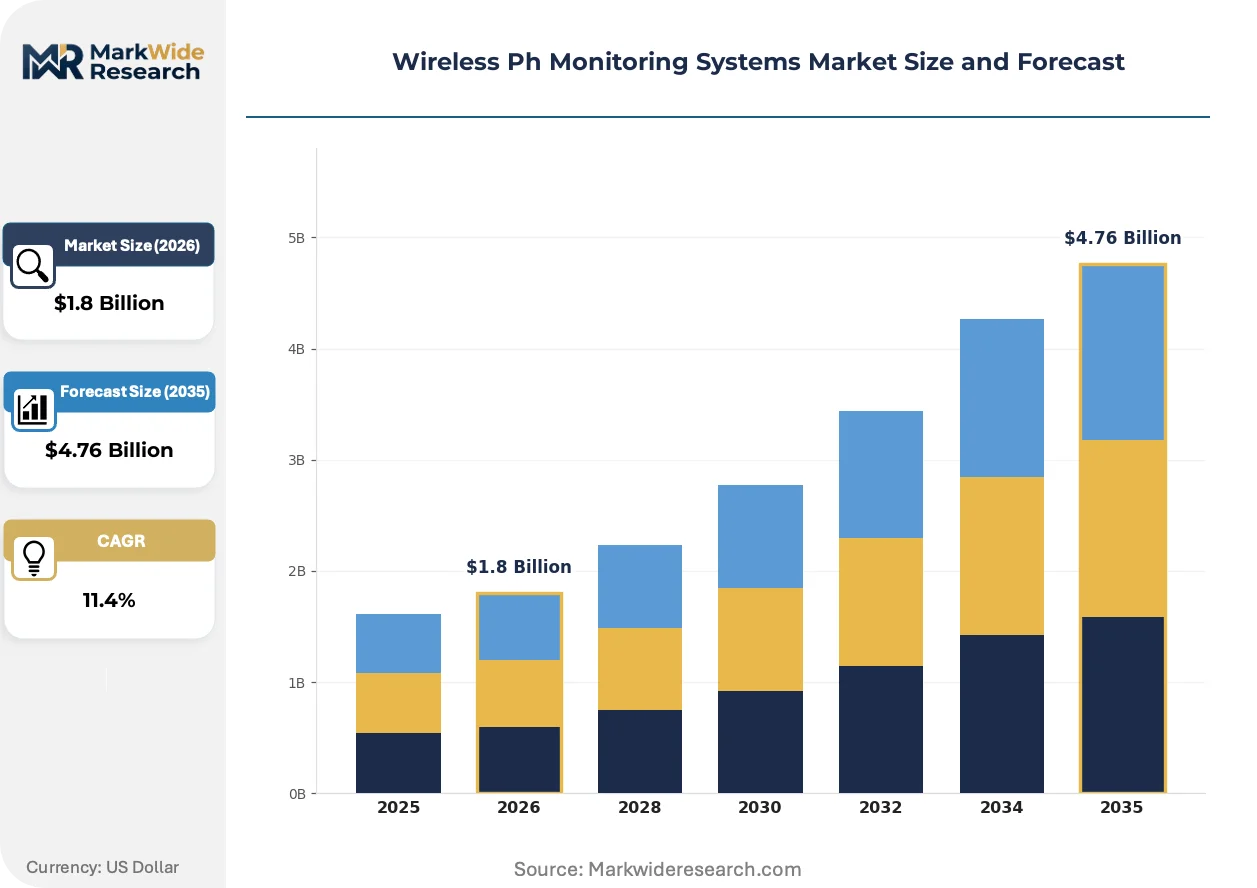
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Continuous Monitoring Devices, Data Loggers, Smart Sensors Technology: Digital, Analog, Wireless Transmission, Electrode-Based End User: Hospitals, Research Laboratories, Educational Institutions, Home Healthcare Application: Agricultural Testing, Environmental Monitoring, Clinical Diagnostics, Industrial Processing |
| Companies Covered | Medtronic, Wellmark, GE Healthcare, Philips Healthcare, Nihon Kohden, Abbott Laboratories, Mindray Medical, Drager Medical, Honeywell HomMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Ph Monitoring Systems Market Evolving Landscape
Wireless pH monitoring is pivoting from data transmission hardware toward intelligent edge devices that preprocess chemical signals before cloud upload, compressing response latency and infrastructure burden.
Solid-state ion-selective field-effect transistor electrodes are overtaking traditional glass bulb architectures in portable and implantable applications. These silicon-based sensors eliminate hydration maintenance requirements. Hospital critical-care departments and wearable device developers are adopting them for continuous gastric and interstitial fluid monitoring. The shift is overtaking established supply chains centered on blown-glass electrode manufacturing.
EPA NPDES permit renewals now mandate timestamped digital pH logs with tamper-evident audit trails. Municipal wastewater authorities must deploy wireless transmitters with encrypted data streams to satisfy compliance officers. Industrial discharge permit holders in the Great Lakes basin are retrofitting analog recorders fastest due to regional enforcement prioritization.
Sensor-as-a-service contracting is displacing capital purchase models among mid-sized water utilities. Third-party vendors retain hardware ownership while charging per-reading fees tied to regulatory filing volume. This reconfiguration concentrates procurement decision-making with finance departments rather than engineering teams, most visibly in California municipal districts facing ratepayer scrutiny over infrastructure spending.
Wireless Ph Monitoring Systems Market Segmentation
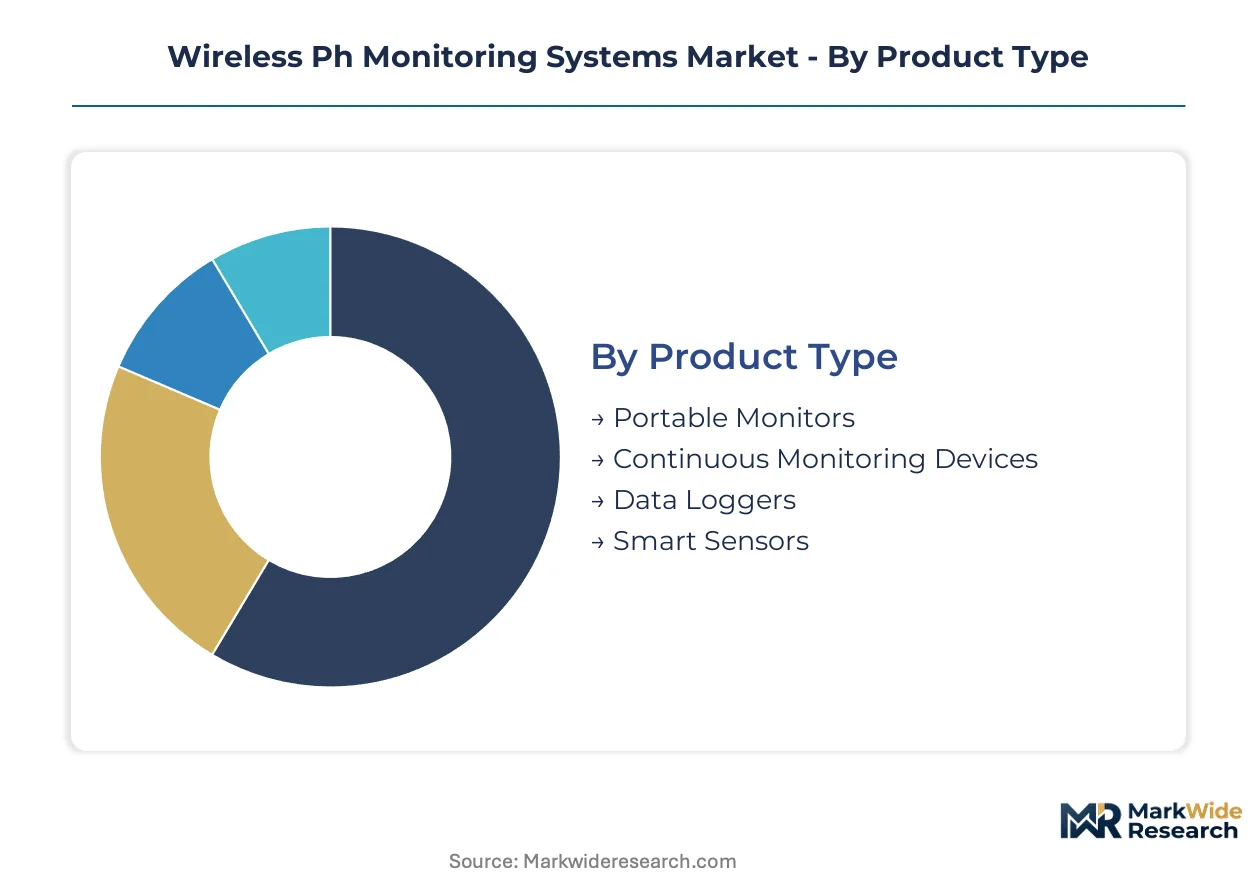
Product architecture and connectivity standards fragment the wireless pH monitoring landscape across clinical, environmental, and industrial domains. Each segment carries distinct certification burdens, electrode durability requirements, and data transmission protocols that shape procurement economics and vendor positioning.
Product Type:
Portable monitors dominate unit shipments while continuous monitoring devices extract premium pricing through real-time telemetry capabilities.
- Portable Monitors:Battery-powered handheld units with Bluetooth smartphone pairing serve agricultural spot-testing and home healthcare gastric reflux tracking. Demand concentrates in Germany where outpatient diagnostic reimbursement favors patient-owned devices over hospital-based testing.
- Continuous Monitoring Devices:Hardwired or wireless telemetry systems stream pH data to centralized dashboards for automated process control. Hospital critical-care departments in the United States drive adoption as FDA 510(k) clearance requirements elevate clinical-grade specifications.
- Data Loggers:Standalone recording devices with internal memory buffers capture time-stamped readings for regulatory filing.
- Smart Sensors:Edge-computing-enabled probes filter noise and transmit exception-flagged readings to reduce cloud bandwidth consumption.
Mature deployment sits with continuous monitoring devices. Newer deployment is concentrated in smart sensors.
Technology:
Digital signal processing commands price premiums over legacy analog architectures, while electrode miniaturization redefines form-factor constraints across all tiers.
- Digital:Microcontroller-based conditioning circuits with onboard calibration algorithms eliminate drift errors in bioreactor environments. Pharmaceutical manufacturers in Switzerland demand ISO 13485-certified digital platforms for GMP-compliant batch documentation.
- Analog:Voltage-output sensors with 4-20 mA current loops persist in legacy SCADA integrations where protocol translation costs delay wireless retrofit decisions.
- Wireless Transmission:Bluetooth Low Energy and proprietary RF protocols eliminate cabling infrastructure in distributed monitoring networks.
- Electrode-Based:Glass bulb or ion-selective field-effect transistor architectures remain the fundamental sensing layer across all product categories.
Established infrastructure favors analog systems. Steepest expansion trajectory belongs to wireless transmission.
End User:
Regulatory pathway complexity separates hospital procurement from research and consumer channels, with certification timelines dictating vendor specialization.
- Hospitals:Critical-care departments require FDA-cleared devices with encrypted telemetry and tamper-evident audit trails for patient gastric monitoring. North American health systems prioritize integrated platforms that bundle pH with multiparameter sensing.
- Research Laboratories:Academic and commercial R&D facilities demand high-resolution units with customizable sampling intervals for experimental reproducibility.
- Educational Institutions:University chemistry and environmental science programs procure entry-level units for undergraduate laboratory instruction.
- Home Healthcare:Direct-to-consumer portable monitors address underdiagnosed reflux populations with smartphone-connected symptom tracking applications.
Institutional purchasing maturity centers on hospitals. Emerging volume is concentrating in home healthcare.
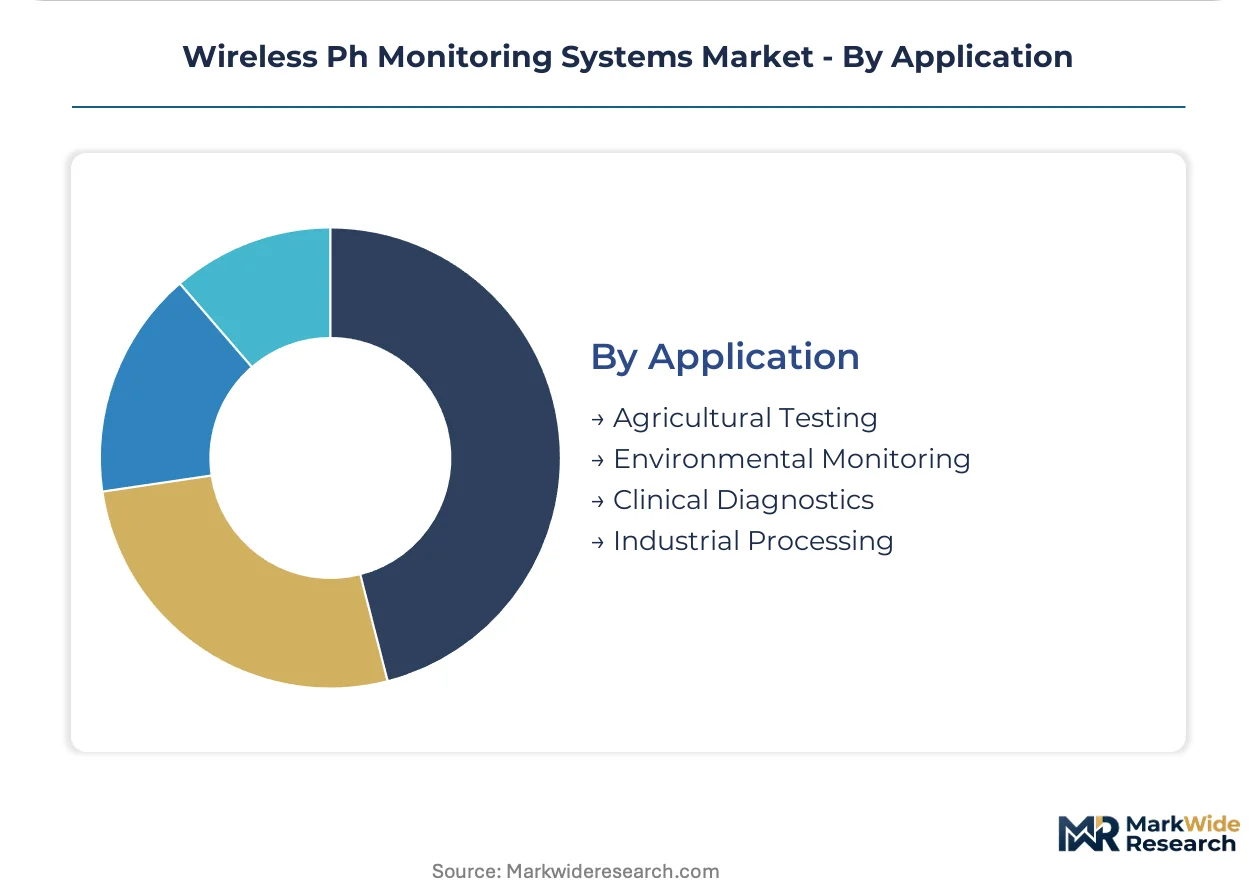
Application:
Environmental compliance mandates and bioprocessing automation create divergent performance specifications across end-use contexts.
- Agricultural Testing:Soil and irrigation water probes with ruggedized housings withstand field particulate exposure. Precision farming operations in California's Central Valley deploy smartphone-connected handheld units for real-time nutrient management decisions.
- Environmental Monitoring:EPA NPDES permit holders deploy encrypted wireless transmitters with timestamped digital logs to satisfy tamper-evident audit requirements. Municipal wastewater authorities in the Great Lakes basin retrofit analog recorders fastest due to regional enforcement prioritization.
- Clinical Diagnostics:Patient-worn or implantable sensors for gastric and interstitial fluid monitoring demand biocompatible materials and sterilization compatibility.
- Industrial Processing:Chemical and pharmaceutical manufacturers integrate continuous pH loops into automated buffer dosing systems for bioreactor alkalinity control.
Regulatory-driven replacement dominates environmental monitoring. Technology-driven upgrade cycles characterize industrial processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water treatment utilities in the United States drive the largest share of wireless pH monitoring demand as federal discharge mandates tighten. Germany and Switzerland anchor European adoption through industrial retrofit cycles. China and Japan represent the fastest-expanding Asian markets for clinical-grade sensors.
United States
Municipal wastewater authorities across the Great Lakes basin retrofit analog pH recorders fastest due to regional enforcement prioritization. EPA NPDES permit renewals now mandate timestamped digital logs with tamper-evident audit trails. Hospital critical-care departments in Boston and Minneapolis prioritize FDA-cleared devices with encrypted telemetry for patient gastric monitoring.
Germany
Industrial processors in the chemical corridor between Ludwigshafen and Leverkusen retrofit legacy analog systems with wireless telemetry. EU Green Deal carbon-neutral manufacturing incentives accelerate demand for energy-efficient monitoring infrastructure. The Rhine-Ruhr metropolitan region concentrates procurement decision-making for mid-sized water utilities adopting sensor-as-a-service contracting models.
Switzerland
Pharmaceutical manufacturers in Basel demand ISO 13485-certified digital platforms for GMP-compliant batch documentation. Swissmedic oversight shapes supplier eligibility for OEM partnerships in medical device supply chains. The country's precision instrument cluster around Zurich anchors development of solid-state ion-selective field-effect transistor electrodes for portable applications.
China
Bioprocessing automation in Shanghai and Suzhou drives demand for continuous bioreactor monitoring with real-time alkalinity feedback loops. The country's national pharmaceutical regulator tightens quality management requirements for clinical-grade sensor imports. Yangtze River Delta chemical parks deploy encrypted wireless transmitters to satisfy evolving environmental compliance frameworks.
Japan
Academic and commercial R&D facilities in Osaka and Nagoya demand high-resolution units with customizable sampling intervals for experimental reproducibility. METI industrial policy supports domestic development of edge-computing-enabled probes. The Kanto region's hospital networks evaluate integrated telemetry platforms that bundle pH with multiparameter sensing for critical-care departments.
Wireless Ph Monitoring Systems Market Competitive Landscape
Strategic partnerships dominate the current landscape as sensor manufacturers seek electrode fabrication capabilities and distribution reach. The vendor base clusters around three tiers: diversified medical device conglomerates with captive supply chains, specialized electrochemical sensor houses, and modular hardware startups leveraging Bluetooth-enabled miniaturization. Two archetypes define positioning: integrated platform providers bundling multiparameter sensing, and focused pH specialists emphasizing edge-computing integration. M&A activity and technology licensing agreements represent the primary competitive moves as firms address ISO 13485 certification barriers and electrochemist talent scarcity.
Within the diversified medical technology tier, Medtronic and GE Healthcare exemplify contrasting approaches to margin control and market access. Medtronic leverages captive electrode fabrication to sustain pricing power across hospital-grade monitor lines. GE Healthcare anchors North American distribution through direct field-service networks. Philips Healthcare occupies a position emphasizing integrated telemetry platforms that bundle pH sensing with broader physiological monitoring capabilities.
| Leading Market Players |
|---|
| Medtronic |
| Wellmark |
| GE Healthcare |
| Philips Healthcare |
| Nihon Kohden |
| Abbott Laboratories |
| Mindray Medical |
| Drager Medical |
| Honeywell HomMed |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between FDA-cleared clinical monitors and uncertified environmental sensors splits pricing power and supplier economics across divergent procurement channels. ISO 13485 compliance timelines concentrate premium-tier supply among captive electrode fabricators, while commodity-grade environmental transmitters draw from modular hardware assemblers competing on per-unit cost.
Pricing Analysis
Volume shipments concentrate in portable monitors for agricultural spot-testing, while continuous monitoring devices in hospital critical-care settings extract margin premiums through encrypted telemetry bundling. Price differentiation hinges on ISO 13485 certification grade and Bluetooth-enabled edge-computing capability, with clinical-grade specifications commanding substantial premiums over environmental counterparts. Pricing pressure stems from electrode miniaturization enabling modular hardware startups to undercut legacy glass-bulb manufacturers on unit cost. Municipal water utilities exhibit highest price sensitivity as ratepayer scrutiny drives sensor-as-a-service adoption, whereas pharmaceutical bioprocessors prioritize measurement reliability over procurement expenditure.
Supply Chain Analysis
Freight cost sensitivity elevates regional electrode fabrication, with glass membrane production clustering in Germany and silicon-based ion-selective field-effect transistor development centering on Switzerland and Japan. Supply chains draw from specialty chemical suppliers for reference electrolytes, lithium-ion cell manufacturers for battery modules, and RF component houses for Bluetooth Low Energy transmitters. Single-source vulnerability concentrates in ion-selective membrane chemistry, where academic laboratory expertise constrains commercial R&D throughput. Distribution runs through direct field-service networks for hospital-grade equipment and third-party sensor-as-a-service vendors for municipal water utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemist talent scarcity props pricing for specialized electrode design, constraining supply expansion faster than demand growth across clinical and industrial segments.
For Market Incumbents: Anticipate margin compression from Bluetooth-enabled miniaturization by accelerating captive fabrication of solid-state ion-selective field-effect transistor electrodes. Defensive consolidation should prioritize backward integration into reference electrolyte chemistry to offset glass membrane supply volatility. ISO 13485 certification investment remains essential for hospital procurement access as FDA 510(k) clearance requirements tighten. For New Entrants and Emerging Players: Capture white-space in agricultural spot-testing for precision farming operations, where smartphone-connected handheld probes face limited incumbent presence. Home healthcare gastric reflux monitoring offers penetrable volume as outpatient reimbursement shifts toward patient-owned devices. Go-to-market execution should leverage direct-to-consumer digital channels bypassing hospital GPO contracting complexity. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical device conglomerates seeking electrode fabrication capabilities and telemetry platform integration. Long-term viability favors targets with ISO 13485-certified manufacturing and established FDA regulatory pathways over pure-play environmental sensor houses. Watch for EPA NPDES enforcement acceleration in the Great Lakes basin as inflection indicator for municipal retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks hospital procurement channels and OEM partnership eligibility for clinical-grade sensor lines. |
| Sensor-as-a-Service Contracting Model | Shifts municipal utility procurement toward finance-department decision-making with recurring revenue streams. |
| Edge-Computing Probe Development | Reduces cloud bandwidth costs for distributed monitoring networks in industrial bioprocessing environments. |
| Backward Integration into Electrode Fabrication | Secures margin control against glass membrane supply volatility and electrochemist talent scarcity. |
| Bluetooth Low Energy Miniaturization | Compresses sensor footprints for portable applications in agricultural spot-testing and home healthcare. |
Research Methodology
Independent corroboration across primary interviews with biomedical engineers, hospital purchasing committees, municipal water utility operations managers, and electrochemical sensor R&D directors underwrites the qualitative findings. Secondary validation draws from EPA NPDES permit filings, FDA 510(k) clearance databases, ISO 13485 certification registries, and municipal procurement contract disclosures. Bottom-up demand modeling triangulates against top-down market sizing across product architecture, connectivity standard, and end-use application dimensions.
Comparable-period anchoring to historical wireless telemetry adoption curves in adjacent medical device categories shaped the projection horizon calibration. The analytical framework segments volume and value across portable monitors, continuous monitoring devices, data loggers, and smart sensors, with technology tiers spanning digital, analog, wireless transmission, and electrode-based architectures. CAGRs derive from regression analysis of replacement cycle timing, regulatory mandate enforcement schedules, and bioprocessing automation investment patterns. Forecast inputs incorporate Bluetooth-enabled miniaturization adoption curves and solid-state electrode technology substitution rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA enforcement prioritization shifts, ISO 13485 audit backlog duration, and electrochemist talent pipeline expansion. Forecasts reflect documented assumptions regarding regulatory pathway timelines and technology substitution elasticities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Position Sensor Market
Sensors and Controls
Distributed Fiber Optic Sensing Market
Sensors and Controls
Gimbal Market
Sensors and Controls
Echo Sounder Market
Sensors and Controls
Thermography Condition Monitoring Equipment Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
Global Radar Sensor Market
Sensors and Controls
Europe Machine Control System Market
Sensors and Controls
Condition Monitoring Equipment Market
Sensors and Controls
Inline Viscosity Sensor Market
Sensors and Controls
Radar Level Transmitter Market
Sensors and Controls
Smart Thermometer Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market
Sensors and Controls
North America Pressure Sensors Market