
 Europe Vibration Sensors Market | 2026-2036
Europe Vibration Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vibration Sensors Market Foresight
MEMS-based miniaturization is reshaping how vibration sensors integrate into compact rotating equipment and IoT-enabled asset platforms. SKF GmbH leverages its bearing-to-sensor vertical integration to dominate predictive maintenance deployments across Nordic wind farms. Emerson Electric Corporation anchors its European position through specialized hardware-software bundles for process industries. Texas Instruments Inc. competes by extending its piezoelectric signal conditioning portfolio into lower-power industrial edge nodes.
Vibration sensors are electromechanical transducers that convert mechanical oscillation into proportional electrical signals, typically operating across frequency ranges from 0.1 Hz to 20 kHz with sensitivities calibrated in mV/g or mm/s; they serve primarily to detect imbalance, misalignment, and bearing degradation in rotating machinery before catastrophic failure occurs. Accelerometers lead product type revenue due to their versatility across aerospace and automotive crash-test applications, while condition monitoring sensors represent the fastest-expanding category as cloud-native analytics platforms proliferate in European manufacturing. Among end users, energy sector procurement is accelerating fastest as offshore wind operators in the North Sea deploy fiber-optic sensing arrays for drivetrain health verification.
The EU Machinery Directive mandates functional safety validation for sensors deployed in critical rotating equipment, while REACH compliance constrains piezoelectric ceramic formulations containing restricted substances. CE marking requirements under the EU AI Act increasingly govern smart sensors with embedded anomaly detection algorithms. Stakeholders must monitor how ECHA substance restrictions and evolving EU Green Deal industrial benchmarks will reshape material sourcing and sensor recyclability obligations across European supply chains.
Market Dynamics
MEMS miniaturization is compressing sensor footprints below 5mm³ while EU Machinery Directive safety mandates force redesign cycles across rotating equipment OEMs. This dual pressure—technology capability pulling, regulatory compliance pushing—defines current competitive positioning.
Growth Catalysts
- EU Machinery Directive functional safety mandates:Critical rotating equipment must now deploy validated sensors with SIL-rated outputs, forcing replacement of legacy unmonitored assets across German process plants.
- Offshore wind drivetrain monitoring:North Sea operators deploy fiber-optic sensing arrays for gearbox health verification under harsh marine conditions.
- Piezoelectric ceramic advances:Lead-free formulations meeting REACH substance restrictions enable continued high-temperature sensing in aerospace turbine applications.
Market Restraints
- Palladium supply concentration:Russian and South African sources dominate electrode material for high-temperature piezoelectric elements, exposing European converters to input cost volatility.
- REACH substance restrictions:ECHA candidate list expansion constrains PZT ceramic compositions, forcing reformulation R&D before commercial deployment.
- Optical sensing substitution:Fiber Bragg grating arrays displace electromechanical sensors in high-EMI environments like electric vehicle powertrains.
Strategic Opportunities
- EU Green Deal industrial benchmarks:Carbon border adjustment mechanisms incentivize sensor-enabled efficiency optimization in energy-intensive Spanish and Italian steel operations.
- Edge-AI sensor fusion:Convergence of MEMS accelerometers with on-chip neural inference enables localized anomaly detection without cloud dependency.
- Polish manufacturing corridor:Underpenetrated automotive component sector offers white space for condition monitoring as FDI relocates from higher-cost EU member states.
Industry Challenges
- Functional safety certification timelines:TÜV SÜD and DEKRA validation cycles for SIL 2/3 sensors extend 14-18 months, delaying product launches.
- Embedded firmware integration:Legacy SCADA protocols in German chemical plants resist seamless integration with IIoT-native sensor outputs.
- Multiphysics simulation expertise:Shortage of engineers combining vibration analysis with thermal and electromagnetic modeling constrains OEM development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vibration Sensors Market |
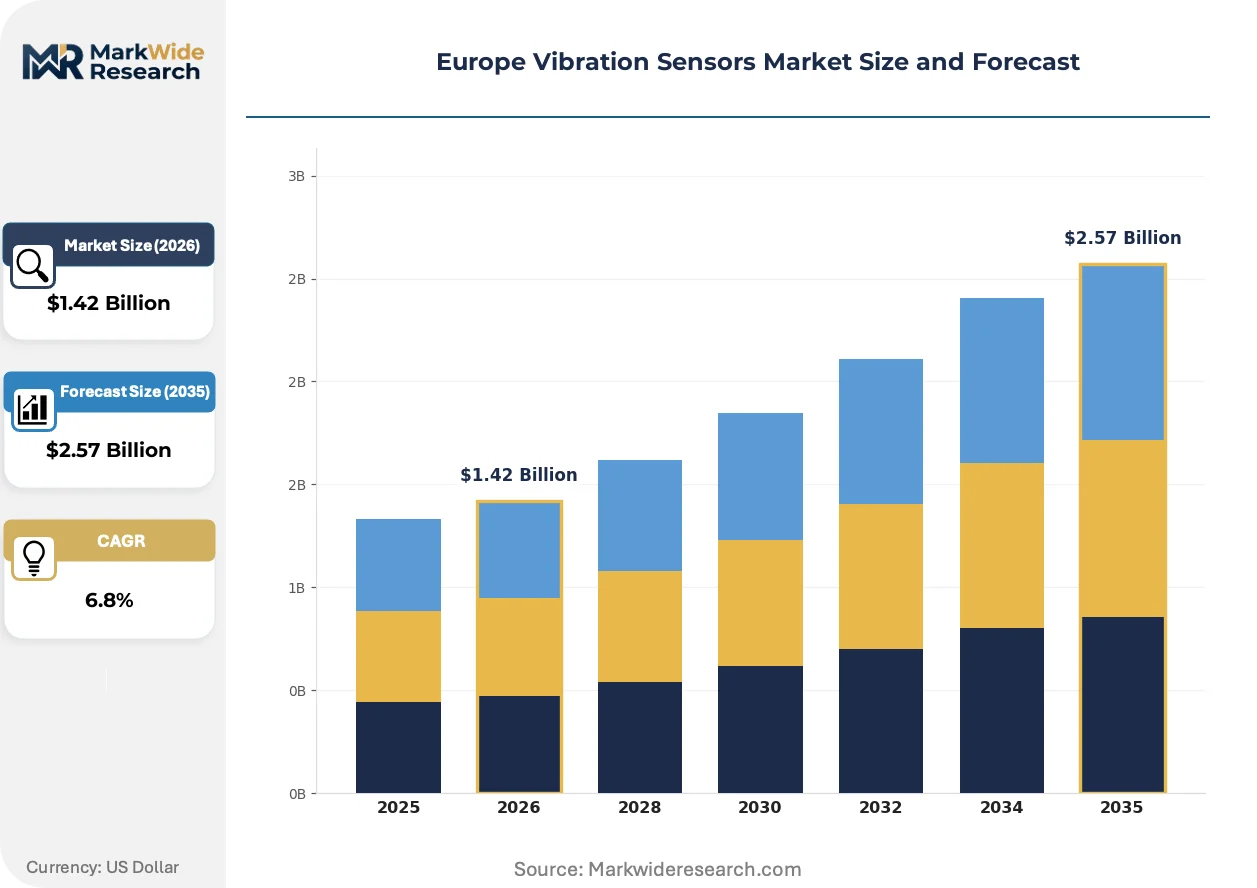
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Displacement Sensors, Velocity Sensors, Condition Monitoring Sensors End User: Manufacturing, Aerospace, Automotive, Energy Technology: Piezoresistive, Capacitive, Optical, Electromagnetic Application: Predictive Maintenance, Structural Health Monitoring, Process Automation, Vibration Analysis |
| Companies Covered | SKF GmbH, Emerson Electric Corporation, Honeywell International Inc., Texas Instruments Inc., National Instruments Corporation, TE Connectivity Ltd., Hansford Sensors Ltd., Analog Devices Inc., Bosch Sensortec GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vibration Sensors Market Shifts & Advancements
Signal processing architectures are migrating toward edge-native implementations, compressing latency for real-time machinery protection. This shift redefines hardware-software boundaries and opens new competitive terrain for specialized European vendors.
Capacitive MEMS accelerometers are migrating from consumer electronics into industrial rotating equipment, offering sub-milliwatt power budgets that enable battery-free energy harvesting. Danish wind turbine OEMs now specify these devices for nacelle monitoring. The technology is migrating from high-volume, low-precision applications into safety-critical industrial nodes, collapsing the traditional performance-cost tradeoff that favored piezoelectric alternatives.
REACH compliance deadlines are forcing reformulation of lead zirconate titanate ceramics before 2026 sunset clauses activate. Industrial sensor manufacturers must qualify alternative perovskite structures without sacrificing sensitivity-temperature stability. German automotive crash-test laboratories face the steepest retooling burden, as their calibrated reference sensors require recertification against new material baselines.
Buyer consolidation among Nordic wind farm operators is compressing vendor qualification cycles and demanding multi-year sensor-as-a-service contracts. Traditional component sales models face displacement by integrated hardware-software-subscription bundles. This pattern is most visible in Denmark and Norway, where Ørsted and Equinor procurement teams now mandate predictive analytics inclusion in sensor supply agreements.
Europe Vibration Sensors Market Segmentation
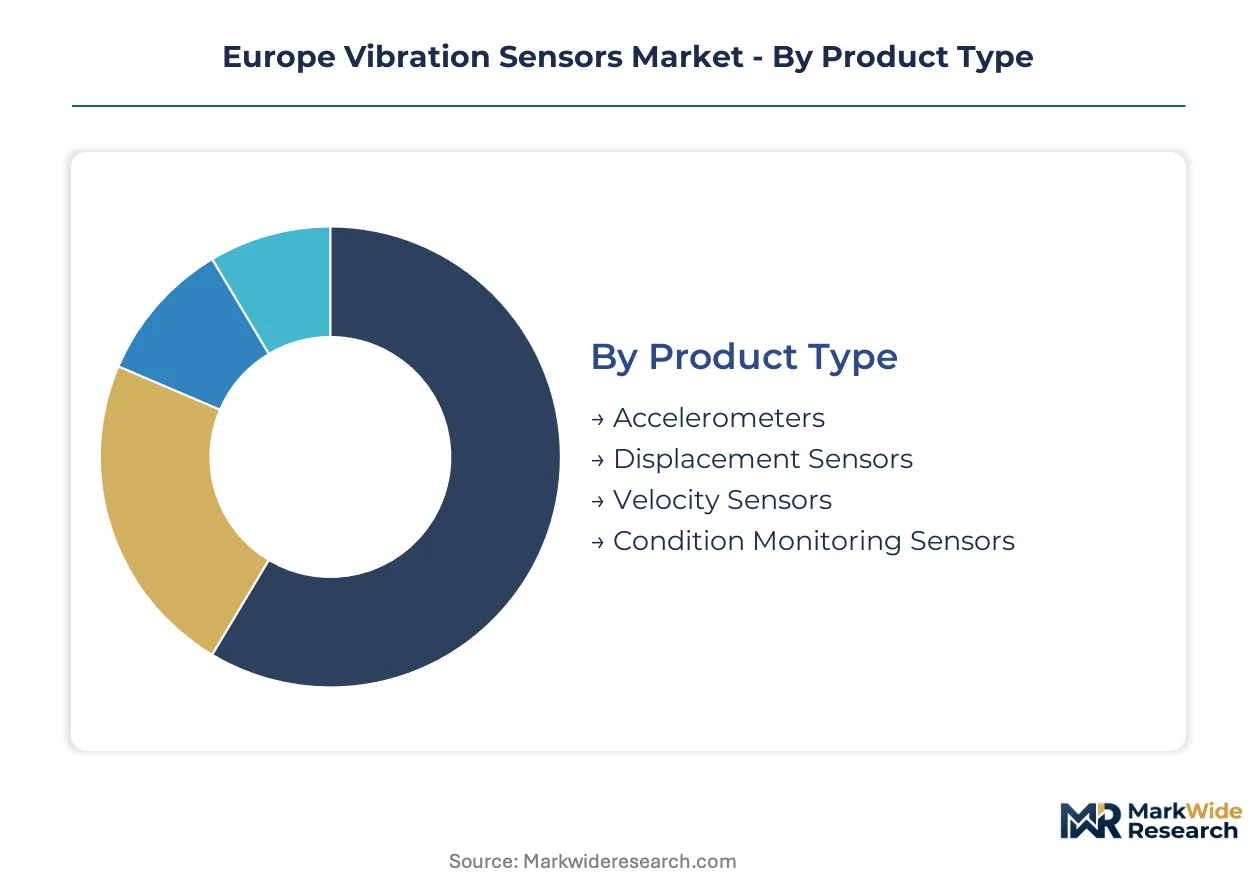
Vibration sensor procurement cycles vary dramatically across European industrial verticals. Aerospace qualification timelines stretch across years while automotive crash-test programs refresh sensors quarterly. Understanding these velocity differentials shapes inventory strategy and R&D prioritization for component suppliers.
Product Type:
Accelerometers turn over fastest in consumer-electronics test labs, while condition monitoring sensors embed for decade-long industrial lifecycles. Replacement velocity directly correlates with calibration drift tolerance and functional safety recertification burdens.
- Accelerometers:MEMS and piezoelectric variants convert mechanical acceleration into electrical signals across 0.1 Hz to 20 kHz bandwidths. German automotive OEMs in Bavaria deploy these for crash-test validation and active suspension feedback, with procurement cycles accelerating as electrification programs multiply validation protocols.
- Condition Monitoring Sensors:Integrated vibration-temperature units with edge-AI inference capability enable localized anomaly detection without cloud dependency. Nordic wind farm operators in the North Sea specify these for drivetrain health verification under harsh marine conditions, with sensor-as-a-service contracts displacing traditional component sales.
- Displacement Sensors:Eddy-current and laser triangulation devices measure shaft position and air gap variations in turbomachinery.
- Velocity Sensors:Electrodynamic and piezoelectric velocity transducers target low-frequency machinery monitoring in paper mills and steel rolling operations.
Accelerometers dominate installed base across European test and measurement infrastructure. Condition monitoring sensors are where expansion concentrates as predictive maintenance platforms proliferate.
End User:
Cost tier stratification separates specification-grade aerospace procurement from price-sensitive automotive volume contracts. Certification burden and liability exposure drive pricing spreads exceeding 10x between adjacent verticals.
- Energy:Offshore wind operators deploy fiber-optic sensing arrays for gearbox and generator health verification under salt spray and electromagnetic interference. North Sea installations in Danish and Norwegian waters anchor European demand as turbine scale increases mechanical stress monitoring requirements.
- Automotive:German OEMs integrate MEMS accelerometers into active safety systems and electric powertrain NVH optimization. Baden-Württemberg test facilities drive reference-grade sensor demand for homologation against EU type-approval standards.
- Manufacturing:Process industries in the Rhine-Ruhr corridor deploy vibration monitoring for pump and compressor protection under EU Machinery Directive mandates.
- Aerospace:Turbine engine manufacturers specify high-temperature piezoelectric elements for blade health and bearing monitoring in flight-critical applications.
Manufacturing holds the deepest installed base from legacy equipment retrofits. Energy is climbing the fastest as offshore wind capacity targets reshape capital deployment.
Technology:
Supply concentration in ceramic substrate processing favors established European converters over Asian module assemblers. REACH compliance timelines force reformulation decisions before material sunset clauses activate.
- Piezoresistive:Strain-gauge elements bonded to silicon or metal substrates measure static and dynamic stress in structural applications. German steel operations in the Saarland specify these for rolling mill load monitoring under EU Green Deal efficiency benchmarks.
- Capacitive:MEMS structures with sub-milliwatt power budgets enable battery-free energy harvesting in rotating equipment. Danish wind turbine OEMs now specify capacitive devices for nacelle monitoring, migrating the technology from consumer electronics into safety-critical industrial nodes.
- Optical:Fiber Bragg grating arrays eliminate electromagnetic interference susceptibility in electric vehicle powertrains and high-voltage switchgear.
- Electromagnetic:Eddy-current proximity probes target shaft orbit monitoring in large turbomachinery with non-contact measurement advantages.
Piezoresistive technology anchors historical volume across European heavy industry. Optical sensing is gaining share fastest as electrification multiplies electromagnetic interference environments.
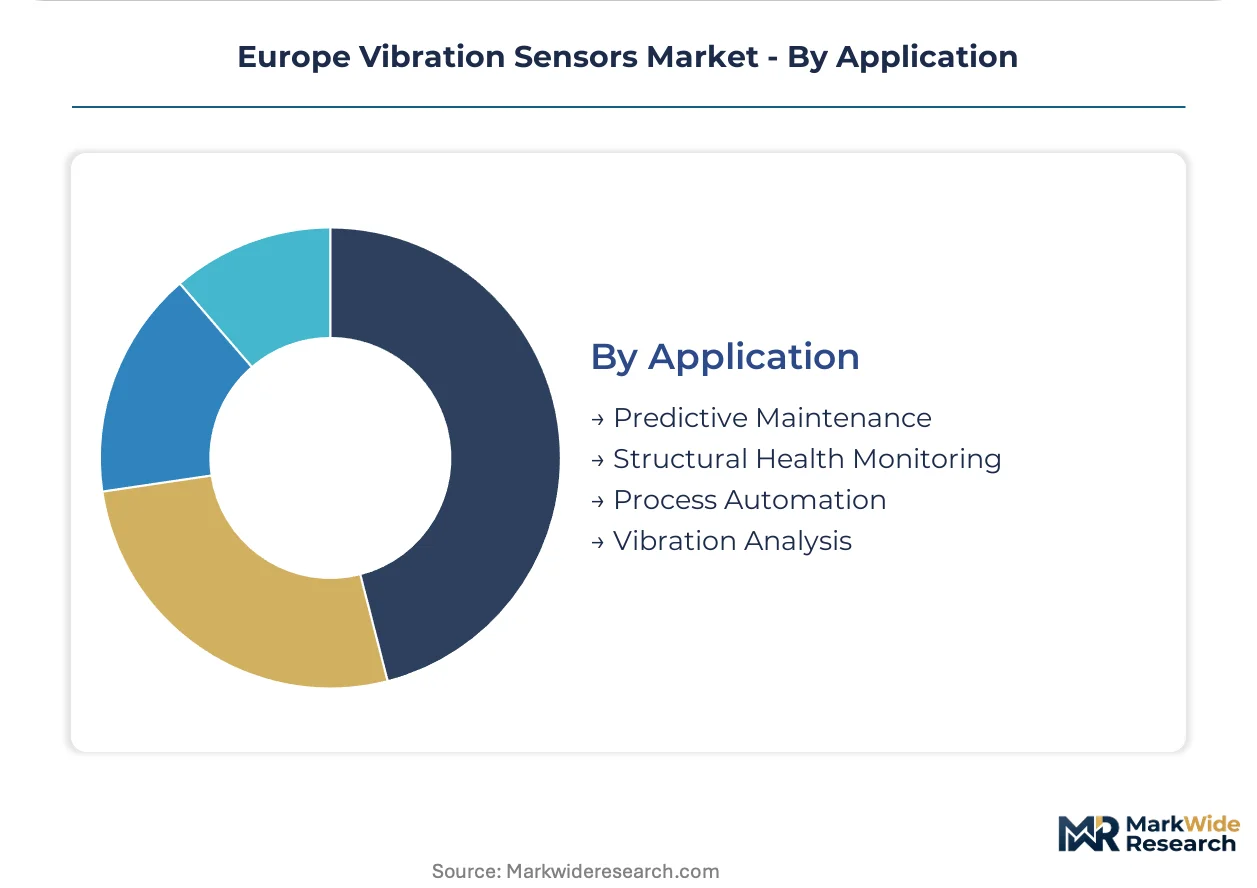
Application:
Customer type separation distinguishes asset-owner procurement from OEM embedded specifications. End-user buyers prioritize total cost of ownership while equipment builders optimize bill-of-materials cost.
- Predictive Maintenance:Cloud-native analytics platforms process vibration signatures to forecast bearing degradation and imbalance before catastrophic failure. Spanish and Italian steel operations adopt these systems under EU Green Deal carbon border adjustment incentives for energy-intensive process optimization.
- Vibration Analysis:Laboratory-grade measurement chains with calibrated reference sensors support R&D validation and forensic failure investigation. German automotive crash-test laboratories face steepest retooling burdens as REACH deadlines force piezoelectric ceramic reformulation and recertification.
- Structural Health Monitoring:Distributed sensing networks track fatigue accumulation in bridges, aircraft, and wind turbine blades.
- Process Automation:Real-time machinery protection systems trigger emergency shutdowns when vibration thresholds exceed safe operating limits.
Vibration analysis commands premium pricing through calibration traceability requirements. Predictive maintenance is where expansion concentrates as IIoT platforms democratize access to advanced analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sensor manufacturers export MEMS accelerometers and piezoelectric transducers to Nordic wind farm operators and automotive test facilities across the continent. This north-south trade corridor concentrates high-value component flows through Rotterdam and Hamburg logistics hubs.
Germany
Baden-Württemberg automotive OEMs and Bavarian industrial automation clusters drive demand for SIL-rated vibration sensors under EU Machinery Directive mandates. The KBA enforces type-approval standards for active safety systems. Stuttgart's testing laboratories recalibrate reference-grade piezoelectric sensors as REACH deadlines force ceramic reformulation.
Denmark
Ørsted and Vestas procurement teams specify fiber-optic sensing arrays for offshore turbine drivetrains in the North Sea. Danish environmental permits require continuous machinery health monitoring for installations exceeding 15 MW capacity. Copenhagen-based operators now mandate predictive analytics inclusion in sensor supply agreements.
Spain
Basque Country steel mills and Catalan chemical plants deploy vibration monitoring under EU Green Deal carbon border adjustment incentives. The national industrial regulator enforces energy efficiency benchmarks for process equipment. Bilbao's port infrastructure supports sensor imports for Atlantic offshore wind projects.
Poland
Automotive component manufacturers in the Silesian and Greater Poland voivodeships represent underpenetrated territory for condition monitoring systems. EU cohesion funds accelerate FDI relocation from higher-cost member states. Warsaw procurement offices increasingly specify IIoT-native sensors for new production lines.
Netherlands
Rotterdam's petrochemical complex and Eindhoven's high-tech systems sector create dual demand vectors for process automation sensors. The national environmental agency enforces F-Gas Regulation compliance for refrigeration machinery monitoring. Brainport Eindhoven coordinates MEMS fabrication clusters serving industrial sensor OEMs.
Europe Vibration Sensors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware-software bundles and component supply tiers. The vendor base organizes into three strata: integrated industrial conglomerates with captive distribution, mid-scale technology specialists with vertical application focus, and regional component fabricators serving retrofit markets. Dominant competitive moves include strategic partnerships between sensor OEMs and cloud analytics platforms, plus geographic expansion into underpenetrated Central European manufacturing corridors.
Among bearing-to-sensor integrated players, SKF GmbH exemplifies the hardware-software bundle archetype through predictive maintenance deployments. Emerson Electric Corporation and Texas Instruments Inc. occupy positions at opposite ends of the value chain, with the former anchoring process industry solutions and the latter extending signal conditioning portfolios into industrial edge nodes. Bosch Sensortec GmbH represents the MEMS miniaturization specialist tier migrating consumer electronics capabilities into safety-critical applications.
| Leading Market Players |
|---|
| SKF GmbH |
| Emerson Electric Corporation |
| Honeywell International Inc. |
| Texas Instruments Inc. |
| National Instruments Corporation |
| TE Connectivity Ltd. |
| Hansford Sensors Ltd. |
| Analog Devices Inc. |
| Bosch Sensortec GmbH |
| Others |
Supply & Pricing Matrix
Rotterdam-Hamburg freight corridors carry ceramic substrates and MEMS wafers from German foundries to Nordic wind farm assembly sites, with container rates feeding directly into landed cost calculations that separate premium-tier SIL-certified sensors from standard industrial grades.
Pricing Analysis
Cost-plus contracts with palladium indexation dominate long-term supply agreements for high-temperature piezoelectric elements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with TÜV SÜD SIL 2/3 validation adding substantial margin to aerospace and automotive safety applications. Price erosion runs through standard industrial accelerometers as Chinese MEMS assemblers compress entry-level quotes. Automotive OEMs in Baden-Württemberg exhibit lowest price sensitivity due to liability exposure, while Polish component manufacturers represent the most cost-conscious buyer segment.
Supply Chain Analysis
Tariff exposure between Russia and European Union member states dominates supply chain risk calculations for palladium electrode materials. Ceramic substrate processing concentrates in Germany, Japan, and the United States, with PZT wafer fabrication drawing from South African and Russian palladium sources. REACH substance restrictions on lead zirconate titanate formulations constitute the primary regulatory chokepoint forcing reformulation timelines. Distribution runs through authorized industrial distributors in Stuttgart, Copenhagen, and Eindhoven, with direct OEM relationships capturing high-volume automotive and wind energy contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
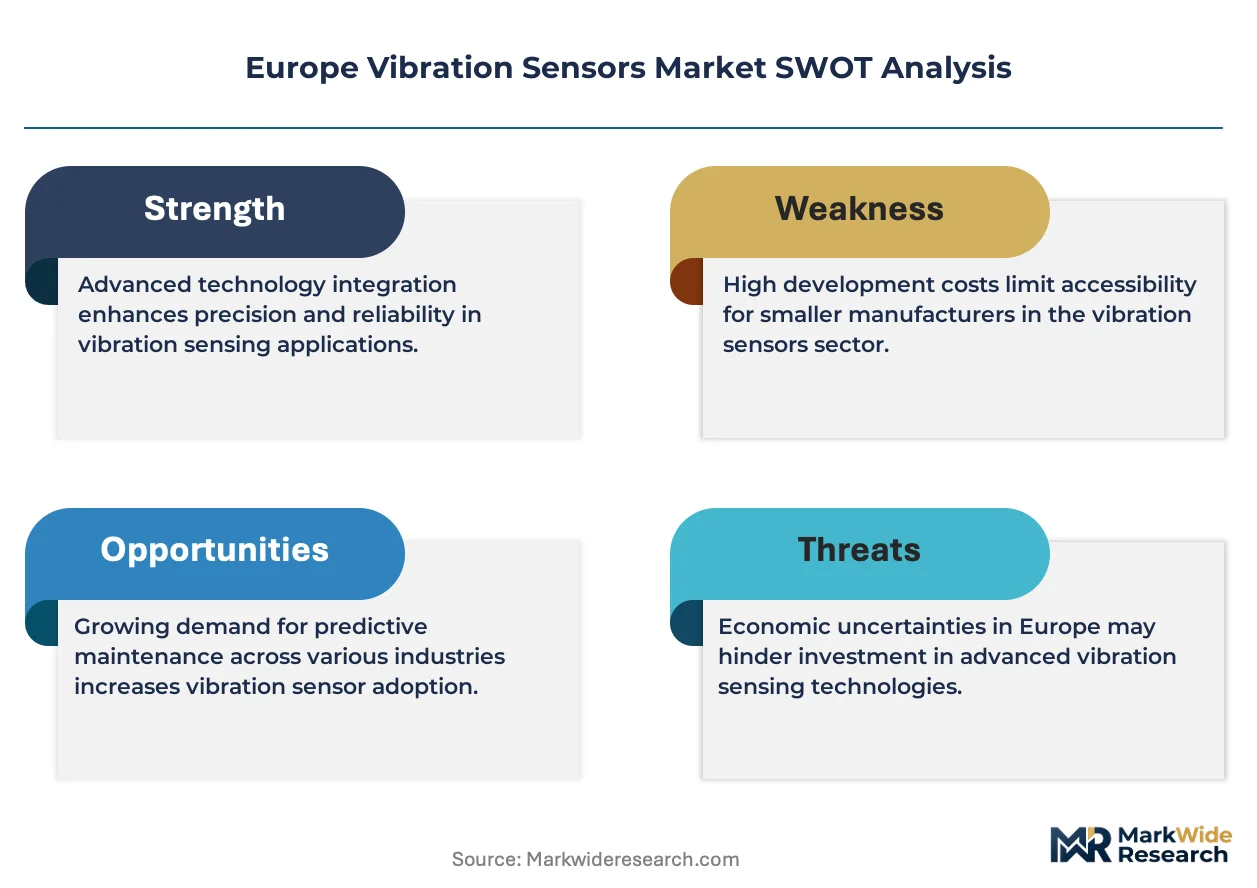
This market functions as a defensive-moat arena where EU Machinery Directive certification requirements create switching costs that protect incumbent positions against low-cost Asian competition.
For Market Incumbents: Entrench market position by acquiring Polish and Czech condition monitoring specialists before FDI relocation accelerates local competitor formation. Deepen captive supply of lead-free piezoelectric ceramics through backward integration into German materials research institutes, insulating against ECHA candidate list expansions that threaten legacy PZT formulations.
For New Entrants and Emerging Players: The Silesian automotive component corridor offers white-space opportunity as EU cohesion funds attract Tier 1 supplier relocation from Western Europe. Target Spanish steel mill retrofits under EU Green Deal carbon border adjustment incentives, where sensor-as-a-service contracts displace traditional component sales and lower upfront capital barriers to entry.
For Investors and Strategic Acquirers: Edge-AI sensor fusion specialists with on-chip neural inference capability represent the priority acquisition archetype for industrial automation conglomerates seeking predictive maintenance platform integration. Watch for inflection when Danish and Norwegian wind farm operators consolidate procurement into multi-year sensor-as-a-service mandates, signaling subscription model validation.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Ceramic Reformulation | ECHA substance restrictions force German automotive crash-test laboratories to recalibrate reference sensor baselines before sunset clauses activate. |
| Sensor-as-a-Service Contract Conversion | Ørsted and Equinor procurement teams now mandate predictive analytics inclusion, displacing traditional component sales models. |
| Edge-AI Inference Integration | MEMS accelerometers with on-chip neural processing enable localized anomaly detection without cloud dependency for North Sea wind farms. |
| Polish Manufacturing Corridor Expansion | EU cohesion funds accelerate FDI relocation into Silesian and Greater Poland voivodeships for underpenetrated automotive condition monitoring. |
| Fiber-Optic Sensing Array Deployment | Danish turbine OEMs specify optical sensing for nacelle monitoring to eliminate electromagnetic interference in high-voltage drivetrain environments. |
Research Methodology
Desk research of EU regulatory filings, ECHA substance restriction databases, and industrial trade flow statistics preceded structured interviews with maintenance directors at German process plants, procurement leads at Nordic wind farm operators, OEM sensor specification engineers, and aftermarket service heads at bearing manufacturers. Secondary validation drew from KBA type-approval documentation, TÜV SÜD certification registries, and customs records for ceramic substrate imports. Bottom-up sensor shipment estimates triangulated against top-down predictive maintenance platform adoption curves.
Assumptions held EU Machinery Directive enforcement timelines and REACH reformulation deadlines fixed across the projection horizon, while varying offshore wind capacity deployment scenarios and automotive electrification program acceleration. Segmentation modeling incorporated product type, end-use vertical, technology architecture, and application mode dimensions. CAGRs derived from installed base replacement velocities and greenfield predictive maintenance platform penetration rates, with palladium price volatility and fiber-optic substitution thresholds treated as sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese MEMS foundries or accelerated optical sensing substitution by Danish turbine OEMs would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Laser Displacement Sensor Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
Global Intelligent Flow Meter Market
Sensors and Controls
Distributed Fiber Optic Sensing Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Asia-Pacific Machine Control System Market
Sensors and Controls
Proximity Sensors Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
IoT Sensor Market
Sensors and Controls
Asia-Pacific Nano Radiation Sensors Market
Sensors and Controls
Fluid Sensors Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Corrosion Monitoring Market
Sensors and Controls
DCT Mechatronic Control Unit Market
Sensors and Controls
Canada Digital Thermometer Market