
 Japan Sensor Market | 2026-2036
Japan Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Sensor Market Insights
Japan's Carbon Neutral Green Growth Strategy is broadening the addressable market for industrial sensors by mandating real-time emissions monitoring across energy-intensive facilities. Omron Corporation leverages its factory automation heritage to dominate process control sensor installations. Denso Corporation anchors automotive sensor supply through deep ties with Toyota and other domestic OEMs. Sony Semiconductor Solutions Corporation specializes in image sensors for advanced driver-assistance systems and industrial vision applications.
A sensor is a transducer that detects physical, chemical, or biological stimuli and converts them into measurable electrical signals, typically operating across temperature ranges from minus forty to one hundred twenty-five degrees Celsius with response times in milliseconds. Its primary purpose is to enable closed-loop control, safety interlocks, and data acquisition in automated systems. Pressure sensors command the largest product type share due to pervasive deployment in automotive powertrain and HVAC systems, while optical sensors represent the fastest-expanding category fueled by lidar and machine vision growth. MEMS technology leads by volume because of silicon foundry scalability, though capacitive sensing captures premium margins in precision industrial metrology.
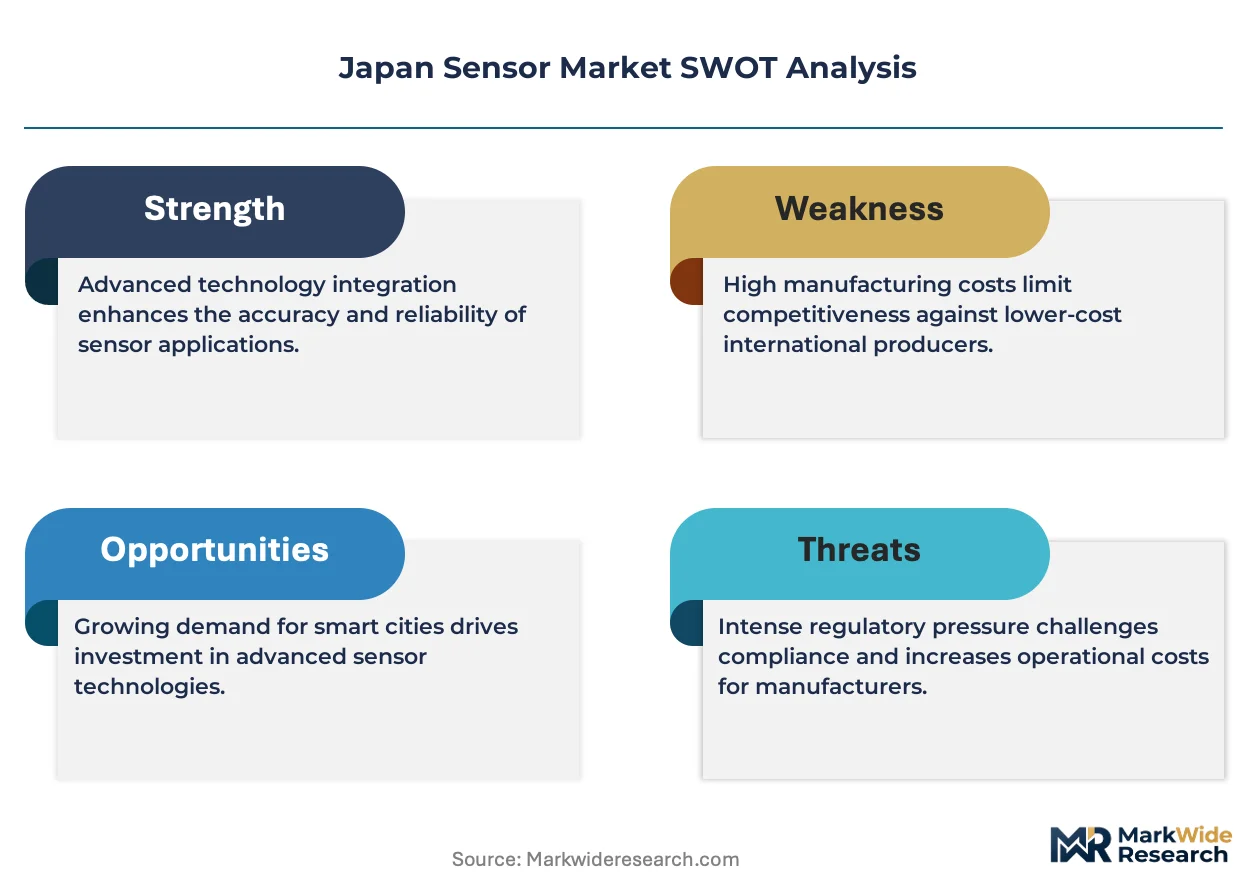
METI enforces JIS standards and energy efficiency regulations that compel manufacturers to integrate smarter sensing for predictive maintenance and load optimization. PMDA oversees sensor performance claims in medical devices, adding a compliance layer for healthcare end users. Stakeholders must weigh domestic R&D tax incentives against the capital intensity of migrating to next-generation solid-state and quantum sensing platforms.
Market Dynamics
METI's carbon neutrality mandates are forcing energy-intensive manufacturers to retrofit facilities with real-time emissions monitoring systems, compressing procurement cycles for industrial-grade sensing hardware across the Kanto corridor.
Growth Catalysts
- Automotive safety mandates:Domestic OEMs are expanding ADAS sensor suites to meet evolving collision avoidance standards, pulling demand through tier-one suppliers.
- Factory automation density:Robotics clusters in Gunma and Kanagawa prefectures are standardizing on MEMS-based motion sensing for precision assembly lines.
- JIS efficiency standards:METI's tightening industrial energy regulations compel process manufacturers to install predictive maintenance sensors or face operational penalties.
Market Restraints
- Silicon wafer cost volatility:Foundry input pricing swings compress margins for MEMS fabricators serving price-sensitive automotive contracts.
- Single-source optical component risk:Precision lens supply concentrates in a narrow band of Nagano prefecture suppliers, exposing buyers to earthquake disruption.
- Quantum sensing maturity gaps:Solid-state alternatives lack the temperature stability and field calibration protocols needed for industrial deployment.
Strategic Opportunities
- Kyushu semiconductor corridor:TSMC's Kumamoto fab expansion is seeding a secondary demand cluster for process control and environmental monitoring sensors.
- Medical device convergence:PMDA's streamlined approval pathways for digital therapeutics create entry points for biosensor integration into home healthcare platforms.
- Edge-AI sensor fusion:On-device inference chips combined with multi-modal sensing are opening premium pricing tiers in autonomous mobile robot navigation.
Industry Challenges
- Embedded systems firmware expertise:Shortages of engineers fluent in real-time operating systems delay product qualification timelines.
- Legacy SCADA integration:Brownfield manufacturing sites require costly protocol bridging to connect modern IoT sensors to decades-old control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Sensor Market |
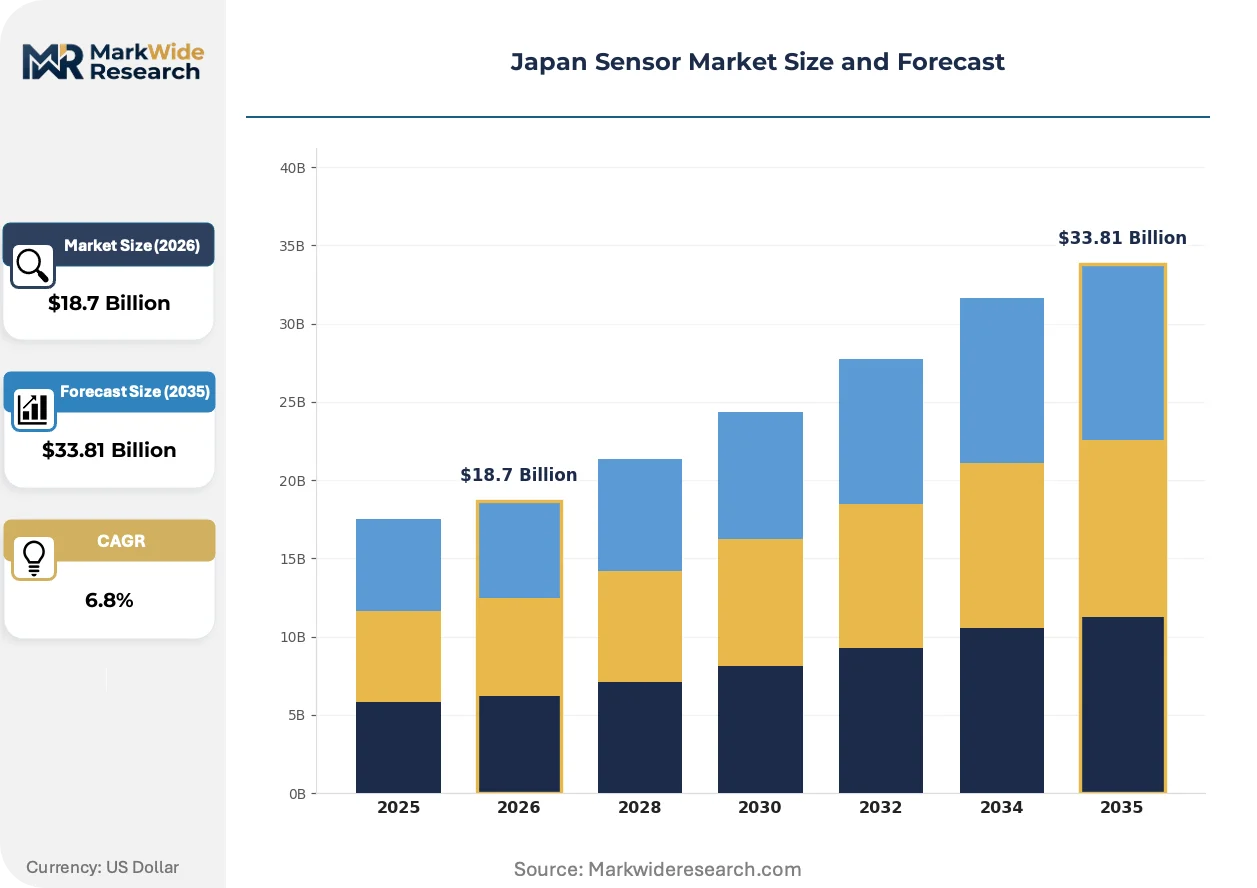
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Temperature Sensors, Proximity Sensors, Optical Sensors End User: Automotive, Consumer Electronics, Healthcare, Industrial Automation Technology: MEMS, Optical, Ultrasonic, Capacitive Application: Smart Home, Wearable Devices, Automotive Safety, Environmental Monitoring |
| Companies Covered | Honeywell International Inc., ABB Limited, Siemens AG, Texas Instruments Incorporated, NXP Semiconductors, Omron Corporation, Denso Corporation, Sony Semiconductor Solutions Corporation, Asahi Kasei Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Sensor Market Trends and Innovations
Solid-state lidar architectures and on-chip spectral analysis are compressing form factors while expanding addressable applications beyond traditional automotive and industrial strongholds.
Photonic integrated circuits are rewriting cost structures for coherent optical sensing. Tier-one automotive suppliers in Aichi prefecture are qualifying solid-state lidar modules for highway-speed autonomous functions. This convergence is collapsing the price premium between mechanical scanning and chip-scale alternatives.
METI's GX League framework imposes granular carbon accounting on steel, chemical, and cement producers. Facilities must install continuous emissions monitoring sensors or surrender preferential electricity tariffs. Heavy industry buyers in the Keihin industrial zone are consolidating procurement around vendors offering integrated sensing and compliance reporting platforms.
Sensor-as-a-service contracting is displacing capital purchase models among mid-sized precision manufacturers. Subscription pricing bundles hardware, calibration, and cloud analytics, reducing upfront barriers for Osaka-based SMEs. This shift is most pronounced in machine tool monitoring, where buyers prioritize operational expenditure predictability over asset ownership.
Japan Sensor Market Segmentation
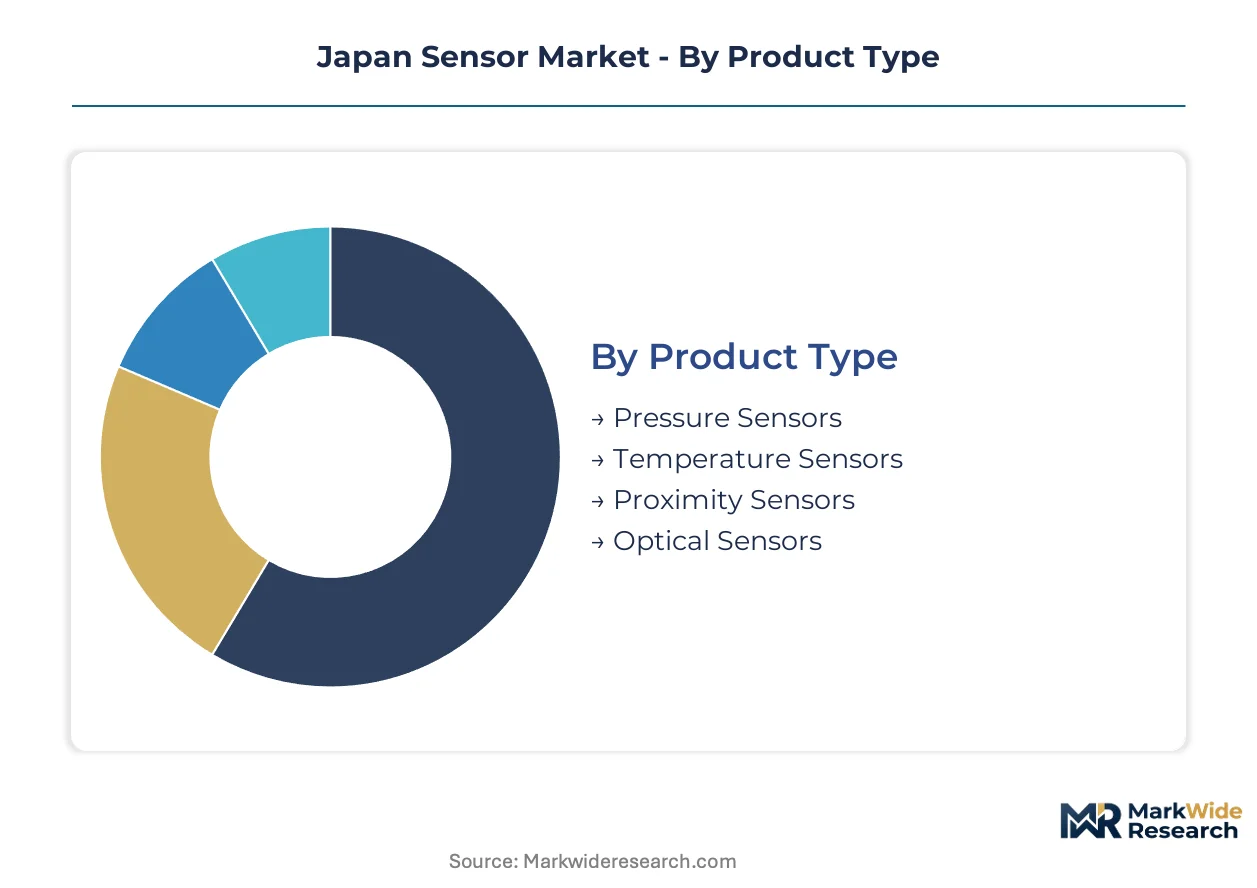
Japanese buyers prioritize reliability certification and supply chain proximity when selecting sensor configurations. Segmentation reveals how procurement patterns diverge across automotive OEMs, precision manufacturers, and healthcare device makers operating under distinct regulatory frameworks.
Product Type:
Cost tier determines specification rigor, with premium contracts demanding JIS-certified units and economy buyers accepting commercial-grade alternatives.
- Pressure Sensors:Piezoresistive and capacitive transducers measure fluid and gas pressure across ranges from vacuum to 700 bar. Automotive powertrain and HVAC systems in Aichi prefecture drive procurement volume, with METI efficiency mandates forcing upgrades to higher-precision units for leak detection.
- Optical Sensors:Photodiode and CMOS-based detectors capture visible, infrared, and ultraviolet spectra with nanosecond response times. Lidar module assembly in Gunma prefecture and machine vision deployment across Kanagawa robotics clusters are expanding demand most rapidly.
- Temperature Sensors:RTD and thermocouple elements monitor thermal conditions from cryogenic to 1000°C ranges. Steel and chemical processors in the Keihin industrial zone install these for METI-mandated emissions compliance.
- Proximity Sensors:Inductive and capacitive field detectors sense object presence without physical contact. Precision assembly lines in Osaka prefecture standardize on these for robotic positioning accuracy.
Pressure sensors lead on scale; optical sensors lead on momentum.
End User:
Application environment dictates packaging requirements, with automotive and healthcare buyers imposing the strictest qualification protocols.
- Automotive:Tier-one suppliers integrate sensors for powertrain control, cabin comfort, and ADAS functions. Toyota and Honda procurement specifications drive JIS Q 9100 certification adoption across the supplier base.
- Industrial Automation:Factory automation systems deploy multi-sensor arrays for predictive maintenance and process optimization. Gunma and Kanagawa prefecture robotics clusters generate concentrated demand for MEMS motion sensing.
- Healthcare:PMDA-regulated devices require biocompatible materials and sterilization tolerance. Home healthcare platforms in Tokyo and Osaka are integrating biosensors for remote patient monitoring.
- Consumer Electronics:Smartphone and wearable manufacturers prioritize miniaturization and power efficiency. Domestic brands source primarily through Taiwan and South Korea foundry partnerships.
Automotive commands procurement volume; healthcare shows steepest expansion trajectory.
Technology:
Manufacturing maturity separates deployable solutions from laboratory-stage alternatives, with foundry availability constraining volume scaling.
- MEMS:Silicon micromachined structures integrate mechanical and electrical functions on single chips. Volume production at domestic foundries supports automotive and consumer electronics scale requirements.
- Optical:Photonic integrated circuits and solid-state architectures enable coherent detection and spectral analysis. Solid-state lidar qualification by Aichi prefecture suppliers is collapsing price premiums versus mechanical scanning.
- Capacitive:Electrode-based field sensing achieves sub-micron resolution for precision metrology. Industrial measurement equipment in the Kanto corridor specifies these for dimensional inspection.
- Ultrasonic:Piezoelectric transducers emit and receive high-frequency acoustic waves for ranging and imaging. Parking assistance and industrial level sensing represent primary applications.
MEMS dominates production volume; optical technology gains share fastest.
Application:
Customer type shapes integration complexity, with enterprise buyers demanding turnkey systems and consumer markets accepting standalone components.
- Automotive Safety:Collision avoidance and occupant protection systems fuse radar, lidar, and camera inputs. Domestic OEM ADAS roadmaps mandate sensor suite expansion through tier-one supply chains.
- Environmental Monitoring:Continuous emissions detection and air quality measurement support regulatory compliance. METI GX League carbon accounting requirements compel steel and cement producers in the Keihin zone to install monitoring networks.
- Smart Home:Connected devices integrate motion, temperature, and air quality sensing for automation control. Tokyo and Osaka metropolitan area housing developers specify these for new construction.
- Wearable Devices:Miniaturized biosensors track physiological parameters for fitness and medical applications. PMDA streamlined pathways accelerate digital therapeutic integration.
Automotive safety leads on scale; environmental monitoring leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's sensor industry traces its lineage to post-war precision manufacturing clusters in Osaka and Nagoya, where optical and electromechanical expertise concentrated during the 1960s electronics boom. Domestic OEM supply chains and METI industrial policy cemented this foundation, creating enduring geographic specialization that persists across today's production networks.
Kanto
Tokyo and surrounding prefectures generate concentrated demand for MEMS and optical sensing components from precision electronics and robotics clusters. METI's carbon neutrality mandates compel steel and chemical processors in the Keihin industrial zone to install continuous emissions monitoring systems. Yokohama-based tier-one suppliers are expanding ADAS sensor qualification laboratories to serve Toyota and Honda procurement specifications.
Kansai
Osaka prefecture's precision assembly lines standardize on proximity sensors for robotic positioning accuracy in factory automation systems. JIS efficiency standards force process manufacturers to retrofit facilities with predictive maintenance sensors or surrender operational licenses. The Osaka-Kobe manufacturing corridor is consolidating procurement around vendors offering integrated sensing and compliance reporting platforms.
Chubu
Aichi prefecture anchors automotive sensor demand through deep ties between Denso Corporation and Toyota's supply chain. Tier-one suppliers in Nagoya are qualifying solid-state lidar modules for highway-speed autonomous functions. METI's tightening industrial energy regulations accelerate upgrades to higher-precision pressure sensors for powertrain leak detection across the region's automotive foundries.
Kyushu
TSMC's Kumamoto fab expansion is seeding a secondary demand cluster for process control and environmental monitoring sensors. Semiconductor fabrication requires sub-micron resolution metrology equipment that specifies capacitive sensing architectures. Fukuoka prefecture officials are coordinating infrastructure to support sensor vendor co-location near the new foundry complex.
Japan Sensor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and foundry integration depth. The vendor base stratifies between JIS Q 9100-certified automotive specialists and commercial-grade industrial suppliers serving price-sensitive contracts. Three archetypes dominate: integrated electronics conglomerates with captive foundry capacity, precision component specialists focused on single sensing modalities, and foreign multinationals leveraging global scale for standard product lines. Competitive intensity centers on backward integration into silicon wafer supply and strategic partnerships for solid-state lidar qualification.
Within the integrated conglomerate tier, Omron Corporation, Denso Corporation, and Sony Semiconductor Solutions Corporation exemplify divergent specialization vectors. Omron leverages factory automation heritage across process control installations. Denso anchors automotive sensor supply through domestic OEM relationships. Sony Semiconductor Solutions occupies a position in image sensors for advanced driver-assistance systems and industrial vision applications.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| ABB Limited |
| Siemens AG |
| Texas Instruments Incorporated |
| NXP Semiconductors |
| Omron Corporation |
| Denso Corporation |
| Sony Semiconductor Solutions Corporation |
| Asahi Kasei Corporation |
| Others |
Pricing and Supply Chain Analysis
Tier-one automotive suppliers in Aichi prefecture concentrate procurement volumes, locking in contract-based long-term offtake agreements that compress pricing flexibility for MEMS fabricators serving domestic OEM programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates JIS Q 9100-certified automotive units from commercial-grade industrial alternatives and unqualified economy imports. Price differentiation hinges on certification grade and volume scale, with Toyota and Honda procurement specifications commanding substantial premiums over Osaka-based SME orders. Cost compression in the economy tier is intensifying because silicon wafer input pricing swings squeeze foundry margins. Healthcare device makers show least price sensitivity due to PMDA compliance requirements, while precision manufacturers in Kansai exhibit highest sensitivity as they migrate toward sensor-as-a-service subscriptions.
Supply Chain Analysis
Refurbishment flows for industrial sensors concentrate in Nagano prefecture, where specialized optics suppliers recover precision lens components from decommissioned equipment for recalibration and resale. Geographic supply concentration centers on Japan, Taiwan, and South Korea for silicon foundry capacity and photonic integrated circuit fabrication. Raw material dependencies draw from high-purity silicon wafers, rare-earth dopants for optical fibers, and specialty ceramics for high-temperature transducers. Single-source vulnerability in Nagano's precision lens corridor exposes buyers to seismic disruption. Distribution runs through authorized distributor networks serving tier-one automotive suppliers and direct OEM relationships for large-scale industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's sensor market functions as a geographic-arbitrage play where METI's carbon neutrality mandates impose compliance costs that foreign competitors avoid, while domestic R&D tax incentives offset capital intensity for local players.
For Market Incumbents: Extend factory automation heritage into integrated sensing-and-compliance platforms that bundle hardware, calibration, and carbon accounting software for Keihin industrial zone steel and chemical processors. Deepen backward integration into silicon wafer supply to defend margins against foundry input volatility. Prioritize JIS Q 9100 certification maintenance as emerging Chinese MEMS vendors threaten automotive tier-two supplier positions.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in optical sensing creates entry space for solid-state lidar specialists targeting Gunma prefecture machine vision clusters and Aichi autonomous vehicle qualification programs. Focus white-space capture on Kyushu's TSMC-corridor process control sensor demand and Osaka-based SME sensor-as-a-service migration. Pursue partnership-based go-to-market models with existing factory automation distributors rather than direct OEM penetration.
For Investors and Strategic Acquirers: Industrial conglomerates with captive manufacturing bases are the most active acquirer in this space, seeking sensor capabilities to complete vertical automation stacks. Long-term viability favors targets with METI GX League compliance reporting integration and established tier-one automotive qualification. Monitor PMDA streamlined approval pathway utilization rates as inflection signal for biosensor platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Wafer Supply | Captive wafer sourcing insulates Denso and Omron against foundry pricing volatility from Taiwan suppliers. |
| Solid-State Lidar Qualification | Aichi prefecture tier-one suppliers collapsing price premiums versus mechanical scanning through photonic integrated circuit adoption. |
| Sensor-as-a-Service Platform Launch | Subscription bundling reduces upfront barriers for Osaka SME precision manufacturers prioritizing operational expenditure predictability. |
| GX League Compliance Reporting Integration | Combined hardware-software offerings capture METI-mandated carbon accounting procurement from Keihin steel and cement producers. |
| Kyushu Semiconductor Corridor Co-location | Process control sensor vendors positioning near TSMC Kumamoto fab to serve sub-micron metrology equipment demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tier-one automotive procurement officers, factory automation system integrators, METI policy officials, PMDA regulatory leads, and precision manufacturing operations directors with secondary validation against METI industrial statistics, JIS certification databases, semiconductor trade association reports, and customs import records. Bottom-up sensor shipment estimates triangulated against top-down manufacturing value-add calculations.
Segment-weighting approaches distributed total market value across product type, end user, technology, and application dimensions, with additional granularity for regional production cluster concentration. CAGRs derived from fitted growth curves incorporating technology substitution rates, regulatory compliance deadline impacts, and foundry capacity expansion timelines. Forecast inputs included ADAS penetration roadmaps from domestic OEMs and METI GX League membership expansion trajectories.
Caveats apply where TSMC Kumamoto production ramp delays, seismic disruption in Nagano optical component corridors, or quantum sensing technology breakthroughs could materially shift the outlook. Practitioners should monitor solid-state lidar qualification timelines and PMDA digital therapeutic approval volumes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Sensors Market
Sensors and Controls
Advanced Carbon Dioxide (CO2) Sensors Market
Sensors and Controls
France Digital Thermometer Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
Lighting Control Sensors Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
France Air Purifier Market
Sensors and Controls
Global Accelerometers Market
Sensors and Controls
Europe Advanced CO2 Sensor Market
Sensors and Controls
US Temperature Sensors Market
Sensors and Controls
Global Wireless Brain Sensors Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Digital Radiography Sensor Market
Sensors and Controls
Magnetoresistive Sensors Market