
 Toroid Inductor Market | 2026-2036
Toroid Inductor Market Size, Share, and Industry Trends Forecast 2026-2036
Toroid Inductor Market Insights
AEC-Q200 automotive qualification is redrawing competitive boundaries in toroid inductor supply. TDK leverages its materials science heritage to sustain ferrite core leadership across high-frequency power applications. Coilcraft specializes in compact RF toroids for telecommunications infrastructure, while Murata Manufacturing anchors Asian supply networks through vertically integrated ferrite production.
A toroid inductor is a passive electronic component constructed by winding conductive wire around a doughnut-shaped magnetic core, typically manufactured from ferrite, iron powder, or amorphous steel, with inductance values ranging from microhenries to millihenries depending on core permeability and turn count. Its toroidal geometry confines magnetic flux within the core, minimizing electromagnetic interference and enabling efficient energy storage in switch-mode power supplies, filtering circuits, and RF signal paths. Power inductors dominate unit volume due to proliferation of DC-DC converters in electric vehicles and renewable energy inverters, while RF inductors command premium positioning in 5G base station deployments where insertion loss specifications tighten. Shielded inductors represent the fastest-growing material category as designers combat crosstalk in densely packed automotive control modules.
EPA fuel economy standards and NHTSA safety electrification mandates in the United States compress design cycles for automotive-grade magnetics, while REACH substance restrictions in Europe constrain core plating chemistries and winding insulation formulations. China's GB standards for electromagnetic compatibility, enforced by SAMR conformity assessment procedures, create additional testing burdens for imported toroid assemblies. Stakeholders must monitor evolving efficiency tier thresholds in appliance and EV charger regulations to align R&D roadmaps with qualification windows that determine market access.
Market Dynamics
AEC-Q200 automotive qualification requirements are compressing supplier timelines and forcing magnetics manufacturers to revalidate ferrite formulations, winding techniques, and thermal cycling protocols for electric vehicle powertrains.
Growth Catalysts
- EU Ecodesign Efficiency Mandates:Tighter standby power limits for appliances and industrial equipment are expanding procurement of high-efficiency toroid inductors in motor drives and switch-mode supplies across German manufacturing clusters.
- Automotive Electrification:Onboard charger and DC-DC converter deployment in battery electric vehicles is accelerating demand for high-reliability magnetics capable of operating at elevated temperatures and switching frequencies.
- Amorphous Steel Core Materials:Metglas and similar alloys are penetrating renewable energy inverter applications where core loss reduction translates directly to system efficiency gains in utility-scale solar installations.
Market Restraints
- Raw Material Concentration:Rare earth element processing for high-permeability ferrites concentrates in Chinese refining facilities, exposing supply chains to export quota volatility and geopolitical friction.
- Copper Price Volatility:Winding wire represents 35-45% of bill-of-materials cost in power inductors, with LME copper futures creating margin pressure that contract manufacturers struggle to pass through under fixed-price automotive agreements.
- Planar Magnetic Substitution:PCB-integrated inductor architectures are capturing board space in compact consumer electronics, constraining toroid growth in sub-10A applications where height clearance permits alternative geometries.
Strategic Opportunities
- India PLI Scheme for Electronics:Production-linked incentives for semiconductor and component manufacturing are attracting toroid inductor assembly investments to Karnataka and Tamil Nadu industrial corridors.
- Vehicle-to-Grid Bidirectional Charging:Dual-active-bridge converter topologies in V2G infrastructure require specialized high-current toroids with saturation ratings above conventional automotive grades.
- 5G mmWave Infrastructure:Low-insertion-loss RF toroids for 28GHz and 39GHz base station deployments command premium positioning as network densification accelerates in South Korean and Japanese metropolitan markets.
Industry Challenges
- AEC-Q200 Certification Timelines:Automotive qualification cycles extending 18-24 months are misaligning product development with compressed EV platform launch schedules from Tier-1 suppliers.
- Magnetic Simulation Talent Scarcity:Finite element analysis expertise for core loss modeling and thermal management is concentrating among senior engineers at established ferrite houses, constraining new entrant capability building.
- REACH Substance Compliance:ECHA restrictions on nickel and cobalt compounds in core plating chemistries are forcing reformulation of established winding termination processes without degradation of solderability or corrosion resistance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toroid Inductor Market |
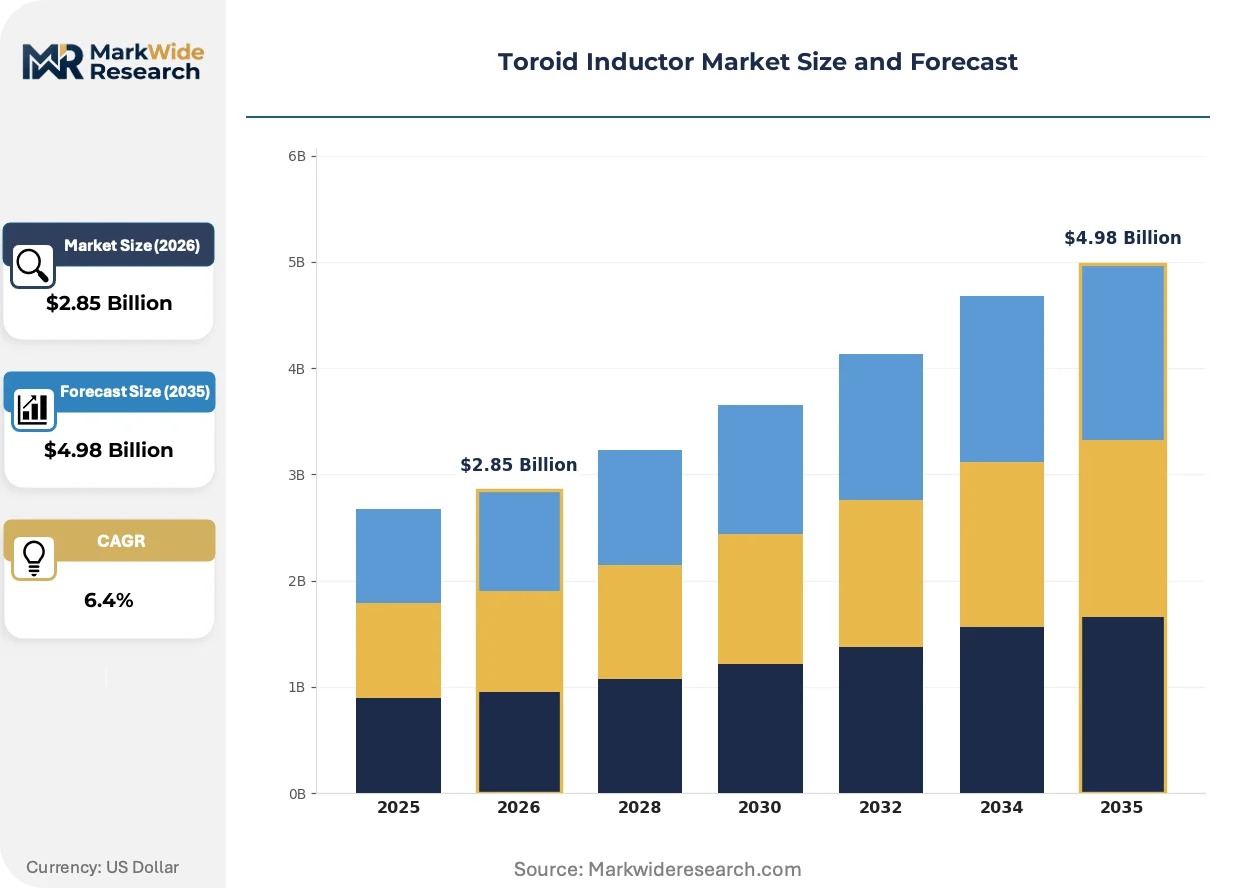
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Inductors, RF Inductors, Current Sense Inductors, Shielded Inductors End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Application: Power Management, Signal Processing, Filtering, Energy Storage Material: Ferrite, Iron Powder, Amorphous Steel, Carbonyl Iron |
| Companies Covered | Hammond Manufacturing, TDK, ABB Ltd., Coilcraft, Murata Manufacturing, Talema Group, Noratel, Standex-Meder Electronics, Triad Magnetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toroid Inductor Market Trends and Innovations
Materials science breakthroughs and regulatory efficiency mandates are converging to reshape toroid inductor specifications across power and RF applications, with performance thresholds tightening faster than legacy manufacturing processes can accommodate.
Amorphous and nanocrystalline metal ribbon cores are displacing conventional ferrite in high-frequency power applications where core loss density determines thermal design margins. Wind turbine inverter manufacturers and EV fast-charging infrastructure developers are specifying these alloys for 50kHz+ switching frequencies. The transition is compressing addressable market share for manganese-zinc ferrite suppliers in applications above 10kW power levels.
REACH substance restrictions enforced by ECHA are eliminating hexavalent chromium passivation and certain nickel-based plating chemistries from core surface treatments. Winding termination suppliers must qualify tin-zinc and organic coating alternatives that maintain solderability under automotive thermal cycling requirements. European appliance and industrial motor manufacturers are prioritizing inductor suppliers with verified green chemistry compliance in their approved vendor lists.
Contract manufacturers in Guangdong province are consolidating procurement authority for toroid inductors through direct relationships with ferrite powder producers, bypassing traditional distributor channels. Shenzhen-based power electronics assemblers now specify core permeability grades and winding configurations at the purchase order level rather than accepting standard catalog offerings. This behavioral shift is visible most acutely in server power supply and EV charging module production lines where volume concentration supports custom magnetic development programs.
Toroid Inductor Market Segmentation
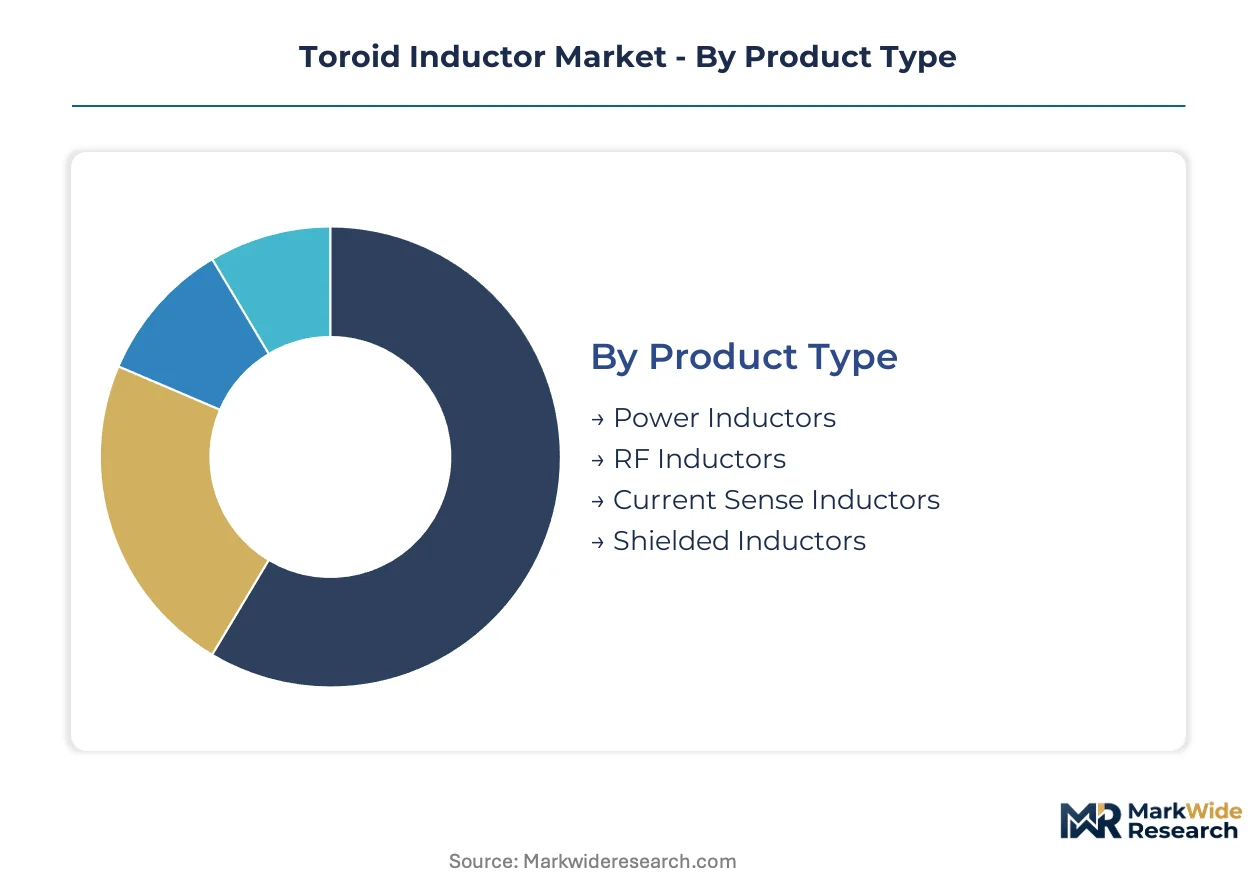
Toroid inductor specifications diverge sharply across power handling, frequency response, and thermal envelopes. Procurement patterns cluster around material science capabilities and end-use qualification requirements rather than commoditized price competition.
Product Type:
Margin pools concentrate in automotive-qualified and shielded variants where reliability premiums offset raw material volatility.
- Power Inductors:These components handle current loads from single-digit amperes to hundreds of amperes in DC-DC converter stages, with core saturation characteristics determining thermal design margins. Demand concentrates in Guangdong province contract manufacturing clusters serving EV onboard charger programs, where switching frequencies above 100kHz favor low-loss ferrite formulations. The dominant share belongs to Power Inductors, while Shielded Inductors is closing the gap fastest.
- RF Inductors:Optimized for impedance matching and signal isolation in high-frequency circuits, these toroids achieve quality factors exceeding 50 at gigahertz frequencies through precise winding geometry control. South Korean and Japanese 5G base station deployments are specifying low-insertion-loss variants for 28GHz and 39GHz millimeter-wave front ends, tightening tolerance requirements beyond conventional catalog offerings.
- Current Sense Inductors:Precision-wound toroids with controlled DCR values enable non-invasive current monitoring in motor drives and battery management systems.
- Shielded Inductors:Magnetic flux containment through pot-core or toroidal shielding geometries suppresses crosstalk in densely packed automotive control modules and server power supplies.
Power Inductors anchor procurement volumes, though RF variants command steepest expansion trajectory in telecommunications infrastructure.
End User:
Application complexity and qualification burden determine customer profitability tiers, with automotive and industrial segments extracting premiums for traceability and longevity guarantees.
- Automotive:AEC-Q200 qualification mandates 1000-hour thermal aging tests and mechanical shock validation for powertrain magnetics, compressing supplier pools to ferrite houses with dedicated automotive programs. German and Chinese EV platform launches are accelerating procurement of high-reliability toroids for bidirectional onboard chargers operating at 85°C ambient. Automotive captures the deepest margin pools, while Telecommunications is climbing the fastest.
- Telecommunications:Base station and optical networking equipment requires tight inductance tolerance across temperature extremes, with 5G densification driving demand for compact RF toroids in macro and small cell deployments.
- Consumer Electronics:Smartphone and laptop power supplies prioritize height reduction over absolute efficiency, exposing this segment to planar magnetic substitution in sub-10A applications.
- Industrial Equipment:Motor drives, welding equipment, and renewable energy inverters specify toroids with extended temperature ranges and vibration resistance for factory floor environments.
Automotive procurement dominates value concentration, though Telecommunications is gaining share fastest through 5G infrastructure buildouts.
Application:
Functional requirements split the market between energy-handling applications demanding core saturation resilience and signal-path applications emphasizing linearity and noise suppression.
- Power Management:DC-DC conversion stages in EVs, servers, and telecom equipment require toroids with soft saturation characteristics to maintain inductance under transient current spikes. China's GB standards for electromagnetic compatibility, enforced through SAMR conformity assessment, add testing layers for power management magnetics in imported assemblies.
- Energy Storage:Flyback and forward converter topologies in EV chargers and solar inverters depend on toroidal geometry for efficient magnetic energy containment.
- Signal Processing:RF front ends and analog filter networks utilize high-Q toroids for impedance transformation and harmonic suppression.
- Filtering:Common-mode and differential-mode EMI filters in appliance and industrial motor drives employ toroidal chokes for conducted noise attenuation.
Power Management commands the largest application share, while Energy Storage is expanding most quickly through renewable energy inverter deployment.
Material:
Core material selection trades off permeability, saturation flux density, and frequency-dependent losses against cost and supply security considerations.
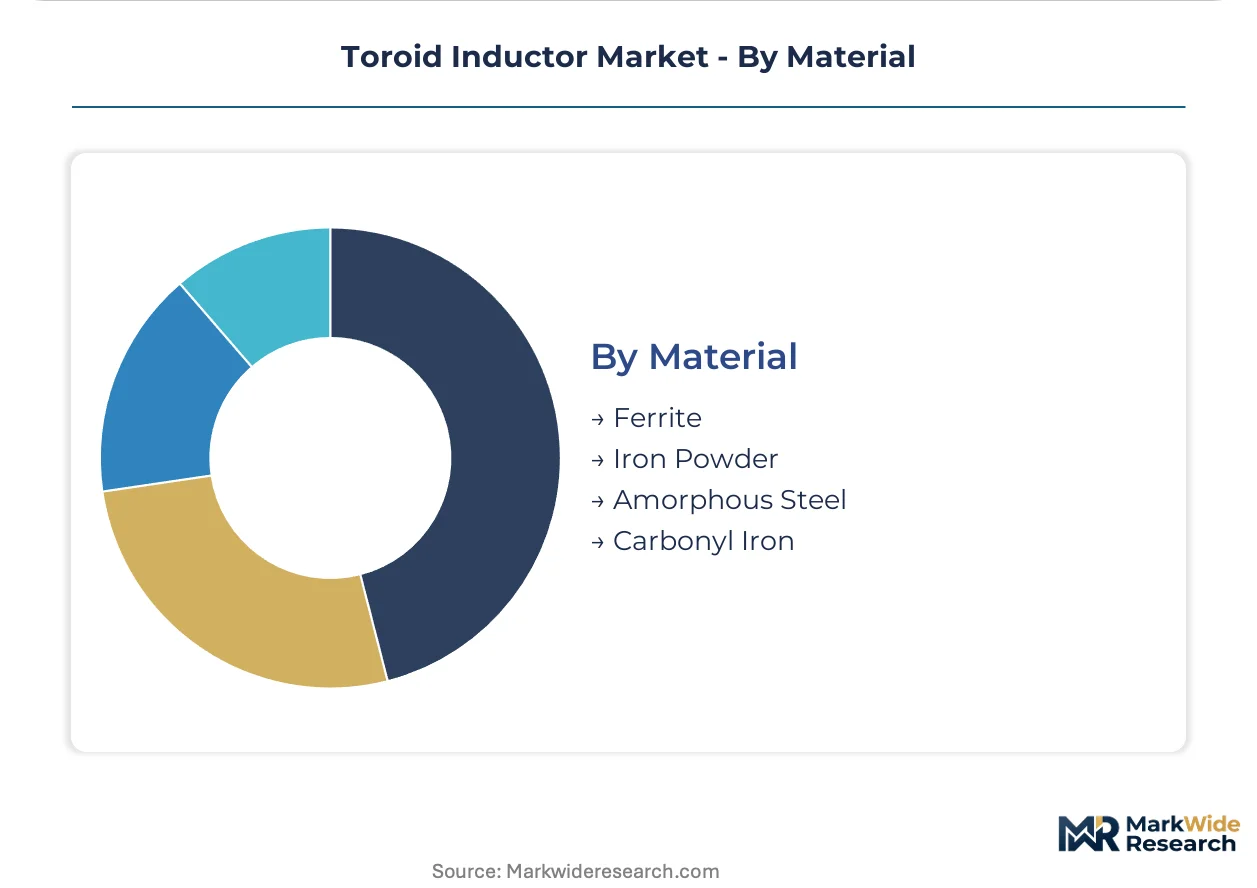
- Ferrite:Manganese-zinc and nickel-zinc formulations dominate frequencies from tens of kilohertz to several megahertz, with TDK and Murata Manufacturing anchoring supply through captive ferrite powder production. EU ecodesign efficiency mandates are tightening core loss specifications for appliance and industrial motor applications, favoring suppliers with advanced materials science capabilities.
- Amorphous Steel:Metglas and similar iron-based alloys achieve core losses below 10W/kg at 50kHz, displacing ferrite in utility-scale solar inverters and EV fast-charging infrastructure above 10kW power levels.
- Iron Powder:Distributed air-gap toroids suit high-DC-bias applications where gradual saturation behavior protects downstream semiconductors.
- Carbonyl Iron:High-frequency response through 100MHz makes this material suitable for RF and microwave inductors in radar and communications systems.
Ferrite retains dominant material share, though Amorphous Steel is gaining ground fastest in high-frequency power conversion above 50kHz.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes in India and China's dual carbon targets are redirecting toroid inductor assembly capacity toward Asia-Pacific manufacturing corridors, while EU ecodesign rules and NHTSA electrification mandates in the United States tighten qualification requirements for automotive-grade magnetics.
China
Guangdong province hosts the densest concentration of power electronics contract manufacturers, with Shenzhen-based assemblers specifying custom ferrite core permeability grades for EV onboard charger programs. SAMR enforces GB standards for electromagnetic compatibility through conformity assessment procedures that add testing layers for imported toroid assemblies. The Pearl River Delta corridor dominates procurement authority consolidation as manufacturers bypass traditional distributors to source directly from ferrite powder producers.
Germany
Automotive electrification programs from Bavarian OEMs are accelerating procurement of high-reliability magnetics for DC-DC converters and bidirectional onboard chargers operating at elevated temperatures. KBA type-approval processes align with EU ecodesign efficiency mandates that tighten standby power limits for industrial equipment motor drives. The Baden-Württemberg manufacturing cluster anchors demand for advanced ferrite formulations in switch-mode power supplies.
United States
EPA fuel economy standards and NHTSA safety electrification mandates compress design cycles for automotive-grade toroids in Michigan and Ohio-based Tier-1 supplier networks. FERC grid interconnection rules for utility-scale solar are specifying amorphous steel core inductors in renewable energy inverter applications above 50kHz. The Southeast industrial corridor attracts contract manufacturing investments serving domestic EV charger production lines.
India
The PLI scheme for electronics manufacturing is attracting toroid inductor assembly investments to Karnataka and Tamil Nadu industrial corridors near semiconductor fabrication hubs. BIS certification requirements for power electronics components create qualification pathways for domestic suppliers serving appliance and industrial motor drive markets. Tamil Nadu's Sriperumbudur electronics manufacturing cluster hosts emerging magnetics assembly operations.
Japan
METI energy efficiency standards for industrial equipment are driving specification of low-loss ferrite cores in factory automation motor drives and power supplies. Kansai and Chubu regional manufacturers supply high-frequency RF toroids for domestic 5G base station deployments where insertion loss specifications tighten at 28GHz and 39GHz. Nagoya-area automotive electronics suppliers qualify shielded inductor variants for densely packed control modules.
Toroid Inductor Market Competitive Landscape
Player mix skews toward vertically integrated materials specialists and precision-winding contract manufacturers. The vendor base separates into three functional tiers: captive ferrite powder producers controlling core material supply, dedicated magnetics houses optimizing winding geometries for specific frequency bands, and diversified electronics conglomerates leveraging component cross-selling. Consolidation pressure concentrates among mid-scale winding specialists facing raw material volatility. Strategic moves center on backward integration into ferrite powder production and qualification investments for AEC-Q200 automotive certification.
Among Japanese electronics conglomerates, TDK and Murata Manufacturing occupy positions anchored by captive ferrite production capabilities that insulate core material supply from rare earth processing concentration risks. Coilcraft represents the specialized precision-winding archetype, with its naming convention indicating craft-focused manufacturing heritage rather than materials integration. These three entities exemplify divergent competitive vectors: materials science depth versus winding geometry specialization versus Asian supply network density.
| Leading Market Players |
|---|
| Hammond Manufacturing |
| TDK |
| ABB Ltd. |
| Coilcraft |
| Murata Manufacturing |
| Talema Group |
| Noratel |
| Standex-Meder Electronics |
| Triad Magnetics |
| Others |
Pricing and Supply Chain Analysis
Amorphous steel core substitution for manganese-zinc ferrite in high-frequency power applications is simultaneously redrawing supply geography toward Japanese and German alloy producers while compressing pricing premiums that ferrite houses commanded in renewable energy inverter markets. This materials transition feeds directly into procurement restructuring as buyers requalify winding suppliers around core loss specifications rather than legacy ferrite permeability grades.
Pricing Analysis
AEC-Q200 certification level creates the primary spread between automotive-grade and industrial-grade toroid inductors, with qualified variants commanding substantial premiums over catalog offerings. Three-tier pricing structure across automotive-qualified, shielded industrial, and standard commercial levels reflects the cost of thermal cycling validation and traceability documentation. Pricing pressure stems from copper LME volatility that contract manufacturers cannot fully pass through under fixed-price automotive agreements. Consumer electronics buyers exhibit highest price sensitivity as planar magnetic alternatives capture sub-10A board space.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Shenzhen port congestion periodically disrupt ferrite powder delivery schedules to Guangdong winding facilities. Rare earth refining concentrates in Chinese facilities, while precision winding equipment sources from Germany and Japan. The supply chain draws from ferrite powder production, copper wire drawing, and core plating chemistries that face REACH restriction pressures. Single-source vulnerability exists in high-permeability ferrite formulations where qualified alternative suppliers require 18-month revalidation cycles. Distribution runs through direct manufacturer relationships with power electronics assemblers rather than traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Toroid inductor demand sits in early-cycle expansion as vehicle-to-grid bidirectional charging infrastructure creates first-mover opportunities in saturation-rated high-current designs that exceed conventional automotive grades.
For Market Incumbents: Fortify captive ferrite powder supply positions through backward integration or long-term offtake agreements with rare earth processors, as export quota volatility threatens core material security. Accelerate AEC-Q200 qualification investments to compress 18-24 month certification timelines that currently misalign with compressed EV platform launch schedules from Tier-1 suppliers. Prioritize amorphous steel core R&D partnerships to defend position against alloy suppliers displacing ferrite in 50kHz+ inverter applications above 10kW power levels. For New Entrants and Emerging Players: Anchor in India's Karnataka and Tamil Nadu industrial corridors where PLI scheme incentives attract assembly investments near semiconductor fabrication hubs with underdeveloped magnetics supplier ecosystems. Target vehicle-to-grid dual-active-bridge converter specifications where specialized high-current toroids with elevated saturation ratings face limited qualified competition. Pursue qualification partnerships with Tamil Nadu-based power electronics assemblers seeking domestic BIS-certified component sources for appliance and industrial motor drive markets. For Investors and Strategic Acquirers: Capital is best deployed toward precision-winding specialists with demonstrated finite element analysis capability for core loss modeling, as magnetic simulation talent scarcity constrains new entrant capability building across the industry. Long-term viability favors targets with verified green chemistry compliance for REACH substance restrictions on nickel and cobalt plating chemistries. Monitor ECHA regulatory expansion timelines as the inflection signal that would accelerate reformulation investments and consolidate supplier pools around compliant winding termination processes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Powder Production | Captive supply insulates against Chinese rare earth export quota volatility and secures core material qualification continuity. |
| AEC-Q200 Certification Investment | Automotive qualification compresses supplier pools and unlocks procurement from German and Chinese EV platform launches. |
| Amorphous Steel Core Partnership | Metglas alloy access displaces ferrite in 50kHz+ renewable energy inverter applications above 10kW power levels. |
| India PLI Scheme Manufacturing Footprint | Karnataka and Tamil Nadu assembly positions capture domestic BIS certification pathways for power electronics clusters. |
| Green Chemistry Compliance Program | REACH-aligned tin-zinc and organic coating alternatives maintain solderability under automotive thermal cycling requirements. |
Research Methodology
A spread of perspectives from ferrite materials scientists, automotive Tier-1 procurement managers, power electronics contract manufacturers, and winding equipment specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings from magnetics suppliers, SAMR conformity assessment documentation for GB standards compliance, and ECHA REACH restriction notices. Trade data from ferrite powder and copper wire imports, alongside IHS Markit vehicle production databases for EV platform tracking, anchored bottom-up and top-down triangulation across the analysis window.
Segmentation dimensions modeled span core material type, inductor product classification, end-use industry vertical, and application function across power management and signal processing domains. CAGRs were derived from installed base projections for DC-DC converters in battery electric vehicles, renewable energy inverter deployment pipelines, and 5G base station densification schedules. Forecast inputs incorporated switching frequency migration trends above 100kHz in onboard charger designs and thermal envelope specifications from AEC-Q200 qualification protocols.
Decision-makers should treat outputs as directional under assumptions of sustained automotive electrification investment and stable rare earth processing capacity; material deviation in either would warrant model refresh. Specific risk factors include REACH substance restriction acceleration, copper commodity price spikes, and planar magnetic substitution penetration in consumer electronics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
China Small Signal Transistor Market
RF Components
Radiofrequency Identification (RFID) Market
RF Components
US RFID Tags Market
RF Components
RF Tester Market
RF Components
Millimeter Wave Equipment Market
RF Components
RF Isolator Market
RF Components
UHF RFID Inlays Market
RF Components
GPS Low Noise Amplifier Market
RF Components
Radio Frequency Front End Module Market
RF Components
Global Gan RF Devices Market
RF Components
5G Driver Amplifier Market
RF Components
Global Ceramic Dielectric Filters Market
RF Components
RF Transceiver Chip Market
RF Components
RF Power Amplifiers Market
RF Components
Global RF Plasma Generator Market
RF Components
Americas Small Signal Transistor Market