
 RF Tester Market | 2026-2036
RF Tester Market Size, Share, and Industry Trends Forecast 2026-2036
RF Tester Market Outlook
The capability gap between benchtop instrument specialists and modular platform vendors is collapsing as software-defined architectures commoditize core measurement functions. Keysight Technologies leverages its proprietary ASIC fabrication to sustain margin advantages in millimeter-wave segments. Rohde & Schwarz anchors European defense and aerospace calibration contracts through Berlin-based accreditation. Anritsu Group competes aggressively in Asian telecommunications conformance testing with localized service centers.
An RF tester is an electronic instrument that measures radio frequency signal parameters including power, frequency, impedance, and modulation accuracy across ranges from kilohertz to sub-terahertz. These instruments validate component and system performance in wireless communications, radar, and broadcast equipment prior to regulatory certification and mass production. Spectrum analyzers command the largest installed base among product types, though software-defined platforms are displacing legacy analog architectures fastest in 5G new radio test cells. Network analyzers concentrate margin pools in automotive radar module validation, where phase coherence requirements exceed consumer electronics tolerances. Research institutions represent the most price-elastic end-user segment, while government agencies impose the longest qualification cycles.
The FCC mandates electromagnetic compatibility certification under Title 47 CFR Part 15 for all RF devices marketed in the United States, directly shaping test protocol requirements and instrument bandwidth specifications. ETSI harmonized standards under the EU Radio Equipment Directive enforce parallel measurement regimes for CE marking, compelling vendors to dual-certify firmware algorithms. China's MIIT issues network access licenses for cellular equipment through rigid type-approval testing that favors domestic language interfaces and local calibration traceability. Stakeholders must monitor whether Open RAN disaggregation fragments test requirements across sub-6 GHz and mmWave bands or consolidates them onto unified platform architectures.
Market Dynamics
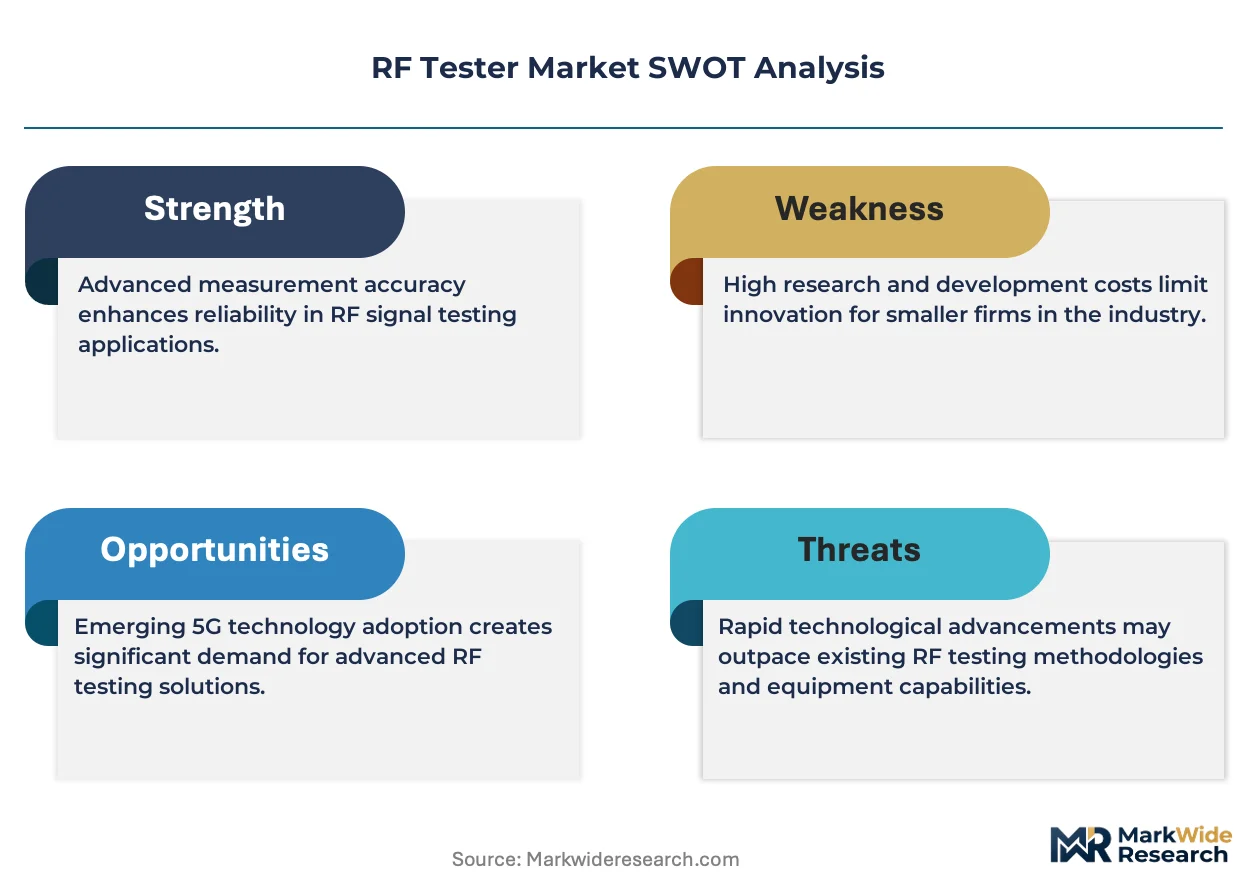
The RF tester market is restructuring around software-defined architectures that collapse the historical performance gap between benchtop and modular platforms. This shift compresses vendor margins while democratizing access to high-frequency measurement capabilities previously locked behind proprietary hardware stacks.
Growth Catalysts
- 5G Infrastructure Mandates:China's MIIT domestic deployment targets are driving localized test equipment procurement from state-backed telecommunications operators. Vector network analyzer demand concentrates in Shenzhen and Beijing manufacturing corridors.
- Spectrum Auction Rules:The FCC's millimeter-wave allocation framework in the United States forces manufacturers toward wider bandwidth validation protocols. Test houses must upgrade to sub-terahertz-capable systems for device certification.
- Automotive Radar Validation:Phase coherence requirements for advanced driver-assistance systems exceed consumer electronics tolerances. Tier-1 automotive suppliers are establishing captive RF test cells for module qualification.
Market Restraints
- ASIC Fabrication Concentration:Proprietary millimeter-wave chip production remains concentrated among three foundry clusters in Taiwan and South Korea. Supply disruption risk elevates instrument lead times.
- Calibration Traceability Costs:National metrology institute standards require periodic recertification of vector network analyzer reference planes. Aerospace and defense contracts impose 18-month qualification cycles that freeze vendor selection.
- Second-Hand Instrument Circulation:Depreciated spectrum analyzers from 4G test cells flood secondary markets. Price pressure from refurbished equipment delays new-platform adoption among research institutions.
Strategic Opportunities
- Open RAN Disaggregation:Interface standardization across sub-6 GHz and mmWave bands creates demand for unified multi-band test platforms. European telecommunications operators are piloting vendor-agnostic conformance suites.
- India Manufacturing Incentives:The country's PLI scheme for telecom equipment is attracting RF module production. Local test service bureaus require turnkey analyzer deployments with Hindi-language firmware interfaces.
- Over-the-Air Test Convergence:Combined conducted and radiated test methodologies are merging onto single chassis. 5G new radio massive MIMO validation is driving adoption of compact antenna test ranges.
Industry Challenges
- Millimeter-Wave Engineering Talent Scarcity:Design and calibration of 28 GHz and 39 GHz test fixtures requires specialized electromagnetic simulation expertise. Universities in Germany and Japan are the primary training pipelines.
- Firmware Algorithm Dual-Certification:ETSI harmonized standards under the EU Radio Equipment Directive and FCC Title 47 CFR Part 15 impose parallel validation regimes. Vendors must maintain separate code branches for CE marking and US market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Tester Market |
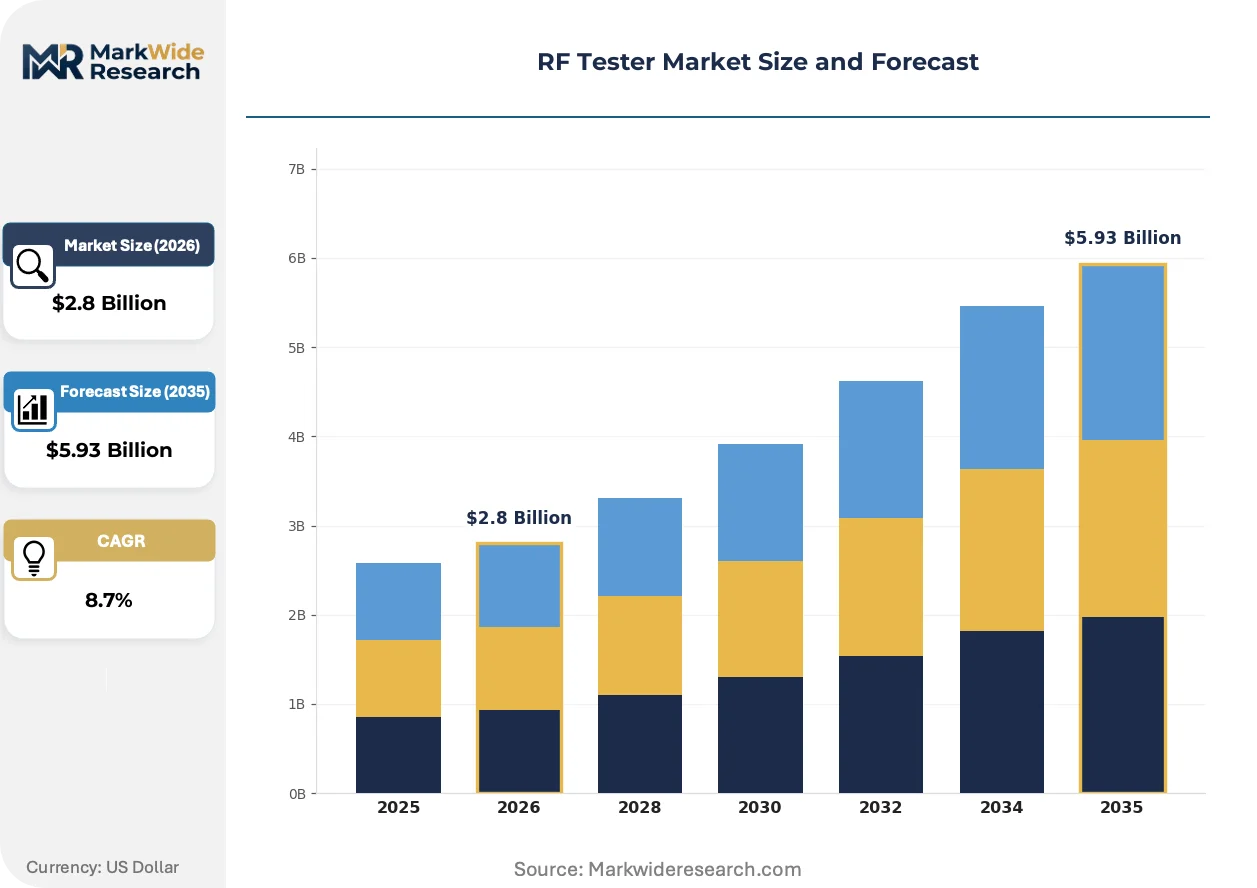
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Signal Generators, Spectrum Analyzers, Network Analyzers, Power Meters Application: Telecommunications, Aerospace, Automotive, Consumer Electronics End User: Manufacturers, Research Institutions, Service Providers, Government Agencies Technology: Analog, Digital, Software-Defined, Hybrid |
| Companies Covered | Keysight Technologies, Anritsu Group, Rohde & Schwarz, Tektronix, Teledyne Technologies, National Instruments, Yokogawa Electric Corporation, Viavi Solutions, EXFO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Tester Market Strategic Shifts
Software-defined measurement engines are collapsing the traditional hardware hierarchy in RF validation. This transformation is redistributing value toward algorithm developers while commoditizing analog front-end components.
Cloud-native test orchestration platforms are bifurcating the installed base between centralized high-throughput manufacturing lines and distributed R&D benches. Semiconductor fabs in South Korea are deploying these architectures for wafer-level RF probing. The shift enables real-time yield optimization while compressing capital expenditure per test site.
ETSI's harmonized standards under the EU Radio Equipment Directive are mandating modular firmware architectures that support over-the-air updates. Test equipment vendors must decouple measurement algorithms from hardware release cycles. Automotive radar module suppliers in Stuttgart and Munich are the earliest adopters, driven by type-approval timeline compression.
Telecommunications operators are consolidating RF test procurement through managed service contracts rather than capital purchases. European mobile network operators in Germany and France are leading this transition, transferring calibration liability to instrument vendors. The model shifts revenue recognition from hardware shipment to recurring calibration and firmware subscription streams.
RF Tester Market Segmentation
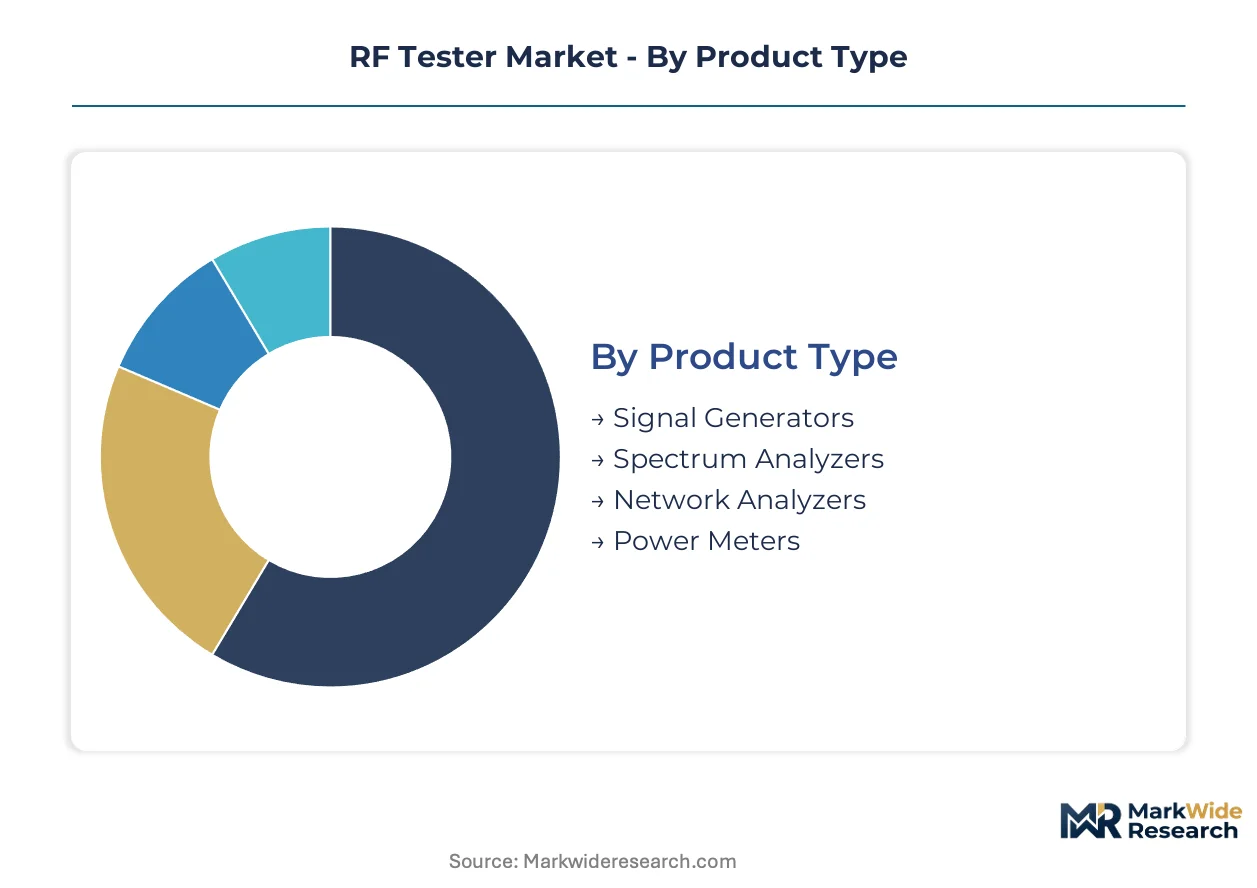
RF tester segmentation reflects divergent substitution pressures across hardware architectures and end-use requirements. Software-defined platforms are compressing margins for legacy analog instruments while creating new competitive battlegrounds in high-frequency validation.
Product Type:
Substitution pressure intensifies as software-defined measurement engines collapse performance gaps between benchtop and modular architectures, forcing incumbent vendors to defend position through proprietary ASIC differentiation.
- Spectrum Analyzers:These instruments measure signal power distribution across frequency bands with resolution bandwidths spanning hertz to gigahertz. Demand concentrates in Shenzhen manufacturing corridors where MIIT's 5G infrastructure mandates drive procurement for base station component validation. FCC spectrum auction rules in the United States are pushing test houses toward sub-terahertz-capable systems for device certification.
- Network Analyzers:Vector network analyzers characterize scattering parameters and impedance matching with phase coherence critical for millimeter-wave applications. Automotive radar module suppliers in Stuttgart and Munich establish captive test cells where phase accuracy requirements exceed consumer electronics tolerances by an order of magnitude.
- Signal Generators:These sources produce calibrated RF waveforms for stimulus-response testing across modulation formats.
- Power Meters:Average and peak power sensors provide absolute power reference measurements for transmitter calibration.
Spectrum analyzers anchor the volume base while network analyzers gain share at the steepest rate.
Application:
Cost tier stratification separates mission-critical aerospace qualification from high-volume consumer electronics screening, with automotive radar validation occupying an intermediate position demanding both precision and scale.
- Telecommunications:5G new radio test cells require combined conducted and radiated methodologies for massive MIMO validation. European operators in Germany and France are piloting vendor-agnostic conformance suites under Open RAN disaggregation.
- Automotive:Advanced driver-assistance systems mandate phase-coherent test fixtures at 28 GHz and 39 GHz for radar module qualification. Tier-1 suppliers face compressed type-approval timelines under ETSI harmonized standards.
- Aerospace:Defense and satellite applications impose 18-month qualification cycles that freeze vendor selection through Berlin-based accreditation requirements.
- Consumer Electronics:High-volume smartphone and IoT device manufacturing drives demand for compact, multi-port test systems with Hindi and Mandarin firmware interfaces.
Telecommunications applications anchor the volume base while automotive applications expand most quickly.
End User:
Customer type determines procurement modality, with manufacturers favoring capital purchase against service providers migrating toward managed test contracts with embedded calibration liability transfer.
- Manufacturers:Semiconductor fabs in South Korea deploy cloud-native test orchestration for wafer-level RF probing, enabling real-time yield optimization. These centralized high-throughput lines contrast with distributed R&D benches in research settings.
- Service Providers:Telecommunications operators consolidate procurement through recurring calibration and firmware subscription streams rather than hardware shipment. This model shifts revenue recognition timing and vendor risk allocation.
- Research Institutions:Universities in Germany and Japan constitute the primary training pipelines for millimeter-wave engineering talent, exhibiting the most price-elastic demand in the installed base.
- Government Agencies:National metrology institutes require periodic recertification of vector network analyzer reference planes, imposing the longest qualification cycles and most stringent traceability documentation.
Manufacturers anchor the volume base while service providers are climbing the fastest.
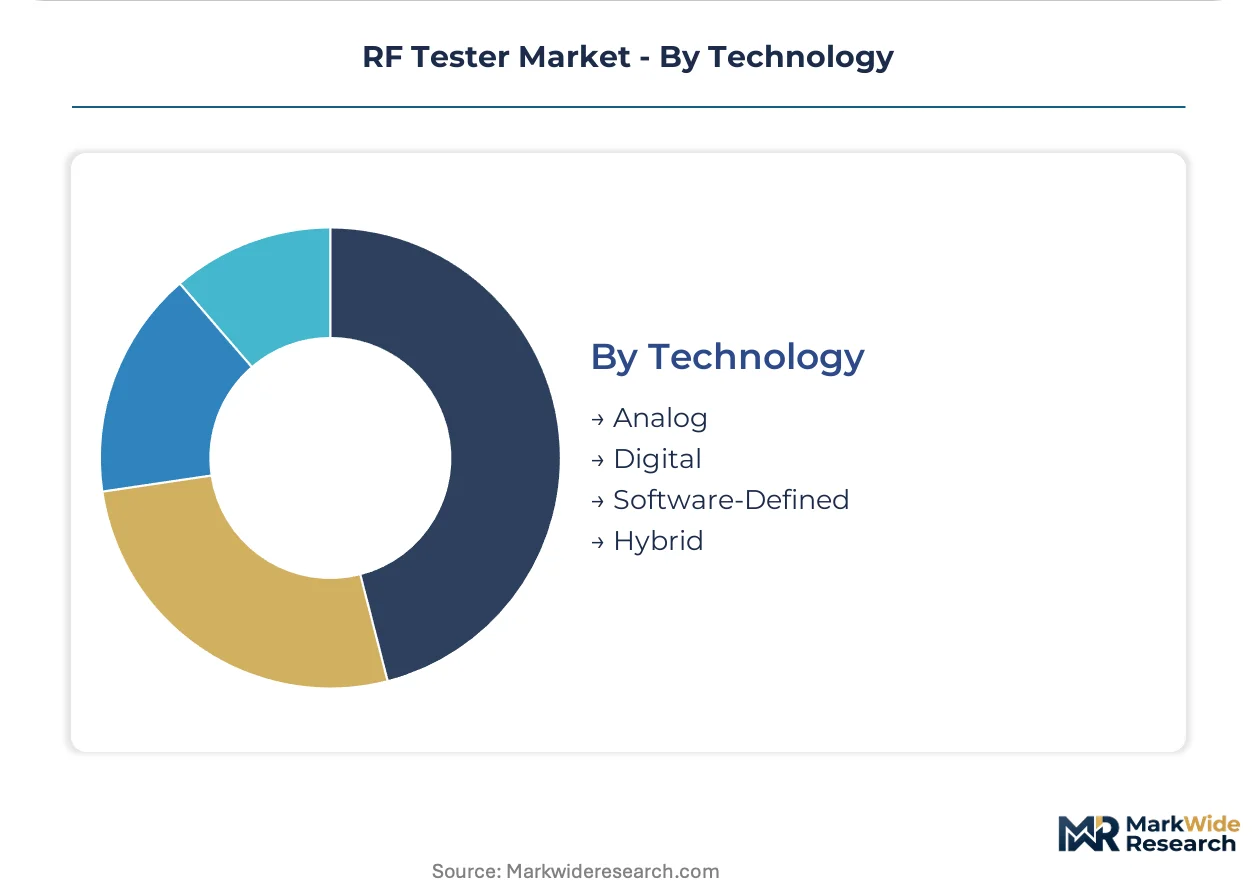
Technology:
Architecture maturity separates commoditized analog front-ends from algorithm-differentiated software-defined platforms, with hybrid configurations emerging as a transitional bridge for legacy test cell retrofit.
- Software-Defined:FPGA-based measurement engines decouple algorithms from hardware release cycles, enabling over-the-air firmware updates mandated by ETSI harmonized standards. These architectures redistribute value toward algorithm developers while commoditizing analog components.
- Analog:Legacy superheterodyne architectures retain installed base in 4G test cells, though depreciated instruments flood secondary markets and pressure new-platform adoption.
- Digital:Direct sampling architectures eliminate mixer stages for lower-frequency applications with reduced spurious response requirements.
- Hybrid:Mixed-signal approaches combine analog front-end sensitivity with digital back-end flexibility for mid-range test requirements.
Analog technology anchors the volume base while software-defined platforms are gaining share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's precision calibration corridors while Chinese manufacturing clusters compete on procurement scale. The United States commands premium margins through FCC-mandated certification complexity. Japan and South Korea anchor millimeter-wave engineering talent pipelines that constrain global supply.
United States
FCC spectrum auction rules under Title 47 CFR Part 15 mandate sub-terahertz validation protocols for device certification. Test houses in California and Massachusetts upgrade bandwidth capabilities to meet electromagnetic compatibility requirements. Defense contractors in the Washington-Baltimore corridor impose 18-month qualification cycles that freeze vendor selection.
China
MIIT domestic 5G infrastructure targets drive localized test equipment procurement from state-backed telecommunications operators. Shenzhen manufacturing corridors concentrate vector network analyzer demand for base station component validation. Beijing-Tianjin-Hebei clusters favor domestic language interfaces and local calibration traceability for network access licenses.
Germany
ETSI harmonized standards under the EU Radio Equipment Directive enforce parallel measurement regimes for CE marking. Berlin-based accreditation anchors European defense and aerospace calibration contracts. Stuttgart and Munich automotive radar suppliers establish captive test cells where phase coherence requirements exceed consumer electronics tolerances.
Japan
METI industrial policy supports millimeter-wave engineering talent development at universities in Tokyo and Osaka. Research institutions exhibit the most price-elastic demand in the installed base. Chubu-Nagoya manufacturing belts deploy software-defined architectures for automotive module qualification.
South Korea
Semiconductor fabs deploy cloud-native test orchestration for wafer-level RF probing. Seoul Capital Area concentration enables real-time yield optimization across centralized high-throughput lines. Busan-Ulsan corridors attract RF module production under expanded manufacturing incentives.
RF Tester Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the RF tester market. The vendor base stratifies into three tiers: precision instrument specialists defending proprietary ASIC fabrication, modular platform vendors commoditizing core measurement functions through software-defined architectures, and regional service integrators capturing calibration and maintenance contracts. Consolidation pressure intensifies as FPGA-based engines collapse historical performance gaps between benchtop and modular systems. Dominant competitive moves include strategic partnerships for millimeter-wave foundry access and geographic expansion into India PLI scheme corridors.
Among precision instrument specialists, Keysight Technologies and Rohde & Schwarz exemplify the proprietary hardware archetype. Keysight occupies a position sustained by captive ASIC fabrication for millimeter-wave segments. Rohde & Schwarz anchors European defense and aerospace accreditation through Berlin-based calibration infrastructure. Anritsu Group sits within the telecommunications conformance tier, competing through localized Asian service centers. These three represent divergent geographic and segment specializations rather than direct head-to-head competition.
| Leading Market Players |
|---|
| Keysight Technologies |
| Anritsu Group |
| Rohde & Schwarz |
| Tektronix |
| Teledyne Technologies |
| National Instruments |
| Yokogawa Electric Corporation |
| Viavi Solutions |
| EXFO |
| Others |
Value Chain & Pricing Dynamics
Long-term calibration service contracts lock in both millimeter-wave ASIC supply access and multi-year price visibility for RF test equipment vendors. These arrangements tether instrument manufacturers to Taiwan and South Korea foundry clusters while insulating aerospace and defense buyers from spot-market volatility.
Pricing Analysis
Configured-to-order pricing for vector network analyzers with phase coherence specifications commands a 40-60% premium over standard spectrum analyzer configurations. Subscription-based firmware and calibration bundles are displacing perpetual licenses among telecommunications operators in Germany and France. Price differentiation stems from certification tier (FCC Part 15 vs. ETSI CE marking dual-validation) and volume procurement scale. Cost compression in entry-level software-defined platforms is intensifying because depreciated 4G test equipment floods secondary markets. Research institutions exhibit the highest price sensitivity, while government agencies accept extended qualification cycles at premium pricing.
Supply Chain Analysis
Inventory lead times for proprietary millimeter-wave ASICs have extended to 26-32 weeks, constraining instrument delivery schedules. Component fabrication concentrates in Taiwan, South Korea, and Japan, with back-end assembly distributed across Malaysia and Mexico. Raw material dependencies span gallium arsenide substrates, high-frequency laminates, and precision coaxial connectors. Single-source vulnerability at the 28 GHz and 39 GHz foundry node elevates disruption risk. Distribution runs through authorized channel partners for defense and aerospace contracts, while direct sales dominate high-volume manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RF tester market is entering a cyclical recovery phase driven by 5G infrastructure replacement cycles and automotive radar module qualification waves. Capital expenditure normalization among telecommunications operators and semiconductor fabs will sustain instrument procurement momentum.
For Market Incumbents: Shield proprietary ASIC fabrication advantages through exclusive foundry partnerships in Taiwan and South Korea. Deepen backward integration into millimeter-wave chip design to defend margin pools against software-defined platform commoditization. Prioritize Berlin-based accreditation maintenance for European defense calibration contracts. Accelerate Hindi and Mandarin firmware localization to capture India PLI scheme and China MIIT procurement flows. For New Entrants and Emerging Players: Cloud-native test orchestration service layers represent the most penetrable white-space where incumbents under-serve distributed R&D benches. Target South Korean semiconductor fabs with wafer-level RF probing subscription models. Pursue European Open RAN pilot programs with vendor-agnostic conformance suites as the primary go-to-market angle. Establish calibration service bureaus in India PLI corridors before hardware vendors consolidate maintenance contracts. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined measurement engine specialists with FPGA algorithm portfolios. Long-term viability over a 5-10 year horizon favors vendors decoupling firmware from hardware release cycles. Monitor ETSI harmonized standard revision timelines as the critical inflection signal for consolidation pressure. Avoid legacy analog architecture pure-plays facing secondary market price erosion.| Strategic Initiative | Industry Significance |
|---|---|
| ASIC Foundry Partnership | Secures millimeter-wave chip supply from Taiwan and South Korea clusters. |
| Firmware Localization | Unlocks China MIIT and India PLI procurement with Mandarin and Hindi interfaces. |
| Calibration Service Expansion | Captures recurring revenue from European operators shifting from capital purchases. |
| Open RAN Conformance Suite | Positions for vendor-agnostic test demand from German and French operators. |
| Cloud-Native Test Orchestration | Enables real-time yield optimization for South Korean semiconductor fabs. |
Study Parameters
A standing panel of RF test equipment product managers, telecommunications procurement directors, semiconductor fab yield engineers, and aerospace calibration specialists provided ongoing calibration against market developments. Primary interviews with these stakeholders combined with secondary validation from FCC equipment authorization databases, ETSI harmonized standard publications, MIIT network access license records, and SEC filings from listed instrument vendors. Bottom-up instrument shipment tracking and top-down telecommunications capex analysis were triangulated for consistency.
Consistency checks validated volume and value outputs against semiconductor capital expenditure disclosures and 5G base station deployment announcements from major operators. The analytical framework modeled product type, application, end user, and technology segments across the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking infrastructure deployment schedules. Millimeter-wave frequency band allocation decisions and Open RAN standardization timelines served as key forecast inputs.
Underlying assumptions cover sustained 5G infrastructure investment, stable foundry capacity allocation, and regulatory harmonization between FCC and ETSI regimes, with deviation risk concentrated in ASIC supply disruption and spectrum auction delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Noise Suppression Components Market
RF Components
Global Small Cell Power Amplifier Market
RF Components
Americas Small Signal Transistor Market
RF Components
Gan RF Semiconductor Devices Market
RF Components
RF Power Detector Market
RF Components
RF Isolator Market
RF Components
Embedded Antenna Systems Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
GPS Low Noise Amplifier Market
RF Components
Space Traveling Wave Tube Amplifiers Market
RF Components
RF Microwave MLCC Market
RF Components
RF Semiconductor Market
RF Components
High-Power Microwave Source Market
RF Components
Stand-Alone Radio Receivers Market
RF Components
Global RF Plasma Generator Market
RF Components
Low Noise Amplifier Market