
 RF Antenna Market | 2026-2036
RF Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
RF Antenna Market Insights
Defense contractors are collapsing the historical gap with telecommunication providers as the dominant buyer archetype for high-performance RF antennas. Huawei Technologies Co., Ltd. leverages its integrated baseband-to-antenna portfolio to dominate 5G macro deployments across multiple continents. Amphenol RF anchors its position through precision connector and antenna module specialization for aerospace and test instrumentation segments. Ericsson AB competes by sustaining one of the industry's deepest R&D commitments to massive MIMO and active antenna system architectures.
An RF antenna converts electrical signals into electromagnetic waves and vice versa, typically operating across frequency bands from kilohertz to millimeter-wave ranges with impedance matching near 50 ohms for minimal reflection loss. Its primary commercial purpose is enabling reliable over-the-air communication for wireless networks, radar, and satellite links. Patch antennas occupy the volume tier in consumer electronics and IoT devices where planar form factors and low manufacturing cost override efficiency concerns. Phased array technology leads in military and satellite applications where electronic beam steering eliminates mechanical gimbal weight and latency penalties. MIMO configurations differentiate in cellular infrastructure by multiplying spectral efficiency through spatial multiplexing rather than additional spectrum allocation.
The FCC enforces Part 15 and Part 27 rules governing unlicensed and licensed RF emissions, directly shaping antenna efficiency requirements and spurious emission limits for market access in the United States. ETSI harmonizes European testing standards through EN 301 908 and EN 302 567, while China's MIIT administers GB standards for domestic telecommunications equipment certification. Stakeholders must monitor evolving spectrum reallocations and satellite-to-ground coordination rules as non-terrestrial networks expand.
Market Dynamics
Defense procurement of phased array systems for electronic warfare platforms is compressing development cycles and pulling engineering talent from commercial 5G infrastructure projects. This demand bifurcation between military and telecommunications buyers is restructuring supplier priorities across the RF antenna value chain.
Growth Catalysts
- China's national 5G infrastructure rollout:State-backed deployment of macro base stations sustains volume demand for massive MIMO antenna arrays. Domestic equipment certification accelerates procurement timelines.
- ETSI electromagnetic compatibility mandates:Tighter EN 301 908 certification requirements for 5G base station deployments force antenna efficiency upgrades across European networks.
- Electronic warfare platform modernization:Defense contractors accelerate phased array procurement for radar and signal intelligence applications, prioritizing electronic beam steering over mechanical alternatives.
Market Restraints
- Millimeter-wave substrate cost volatility:Specialized low-loss laminates and ceramic materials concentrate pricing power with Japanese and Taiwanese substrate suppliers.
- FCC Part 27 spurious emission limits:Licensed spectrum rules impose antenna efficiency floors that increase R&D overhead for base station manufacturers seeking US market access.
- Passive component substitution in consumer IoT:Patch antennas face displacement by chip-scale ceramic antennas in cost-sensitive wearable and sensor applications.
Strategic Opportunities
- India's satellite internet constellation programs:ISRO's commercial launch services and private sector ground station buildouts create demand for Ka-band and Ku-band terminal antennas.
- Non-terrestrial network integration:3GPP Release 17 specifications enable direct-to-satellite smartphone connectivity, converging cellular and satellite antenna architectures.
- US CHIPS Act semiconductor packaging incentives:Domestic advanced packaging subsidies support RF front-end module integration, reducing import dependency for antenna-filter-switch assemblies.
Industry Challenges
- Electromagnetic simulation talent scarcity:Finite element and method-of-moments modeling expertise concentrates with aerospace primes and specialized consulting firms, constraining mid-tier supplier design velocity.
- Active antenna system integration complexity:Combining power amplifiers, beamforming ASICs, and thermal management into sealed radome assemblies extends qualification timelines for new platform wins.
- Cross-border certification reciprocity gaps:Divergent FCC, ETSI, and MIIT test procedures force redundant validation cycles for multi-region product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Antenna Market |
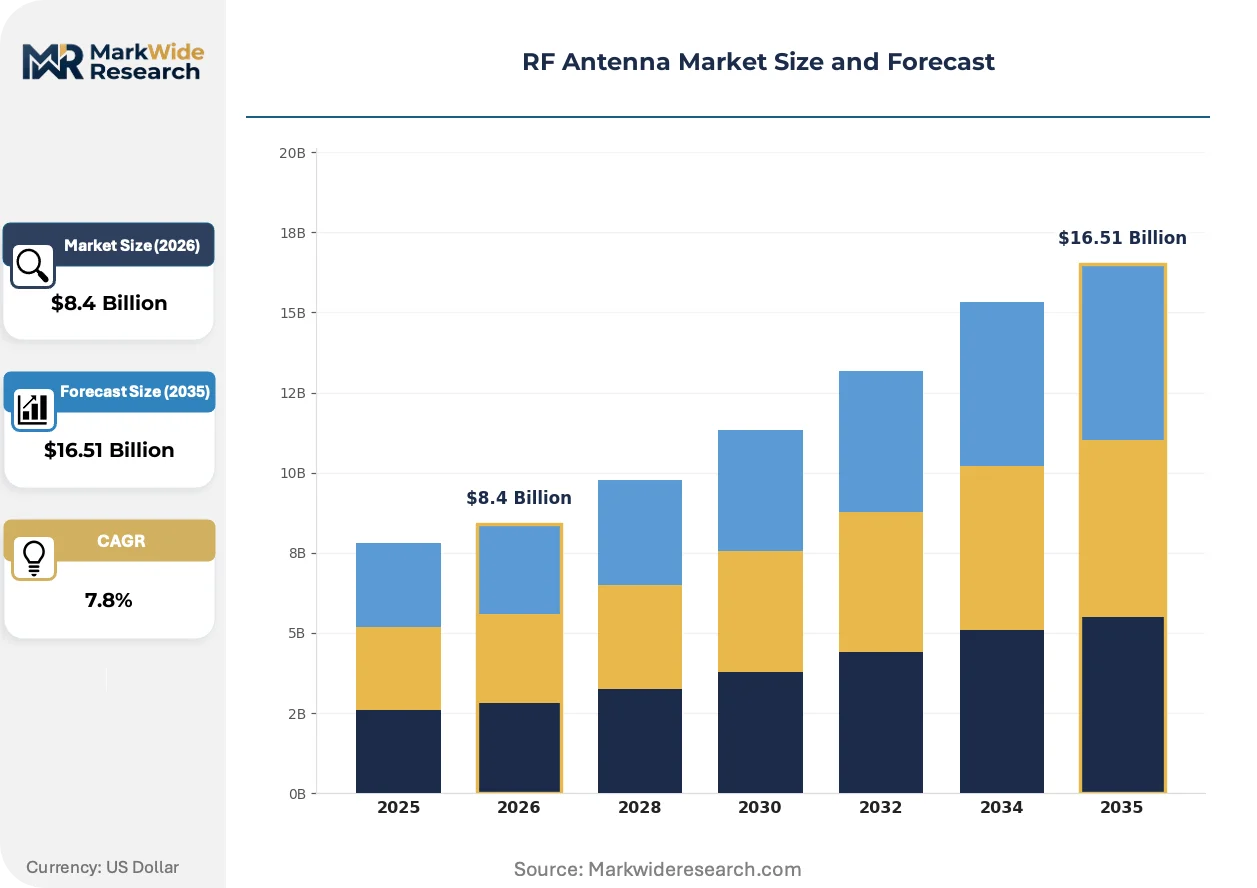
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patch Antennas, Helical Antennas, Dipole Antennas, Loop Antennas, Microstrip Antennas Technology: Beamforming, Phased Array, MIMO, Smart Antennas, Diversity Antennas Application: Wireless Communication, Satellite Communication, Radar Systems, Military Communication, Navigation End User: Telecommunication Providers, Defense Contractors, Space Agencies, Maritime Operators, Broadcasting Companies |
| Companies Covered | Huawei Technologies Co., Ltd., Comba Telecom Systems Holdings Ltd., Amphenol RF (Amphenol Corporation), HUBER+SUHNER, JMA Wireless, CommScope Holding Company Inc., Ericsson AB, Airgain, Inc., TE Connectivity plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Antenna Market Trends and Innovations
RF antenna architectures are converging around software-defined reconfigurability, blurring historical boundaries between passive radiators and active electronic systems. This shift demands new competencies in semiconductor integration and thermal engineering from traditional antenna suppliers.
Reconfigurable intelligent surfaces are fragmenting the established dichotomy between fixed-beam passive antennas and fully active phased arrays. These metamaterial structures enable dynamic beam shaping without distributed phase shifters or amplifiers. Telecom infrastructure vendors and smart building integrators are piloting RIS deployments for indoor coverage extension and outdoor backhaul relay. The technology is fragmenting procurement patterns by inserting programmable surfaces between base stations and end devices, potentially displacing conventional small cell densification strategies.
The FCC's Part 15 unlicensed spectrum expansion for 6 GHz Wi-Fi 6E and 7 is forcing antenna redesigns across enterprise networking equipment. Higher frequency operation demands tighter manufacturing tolerances for printed circuit board antennas and new radome materials with lower dielectric loss. Enterprise access point manufacturers are responding with dual-band-plus-6 GHz tri-band architectures that triple RF chain counts per device, compressing board space for antenna isolation and diversity spacing.
Defense procurement offices are compressing supplier qualification cycles through digital engineering mandates that prioritize model-based systems engineering over physical prototype iterations. This behavioral shift rewards antenna vendors with mature electromagnetic simulation workflows and automated test data pipelines. The transition is most visible in US Navy and Air Force electronic warfare programs, where prime contractors now require digital thread compatibility from subsystem suppliers before contract award.
RF Antenna Market Segmentation
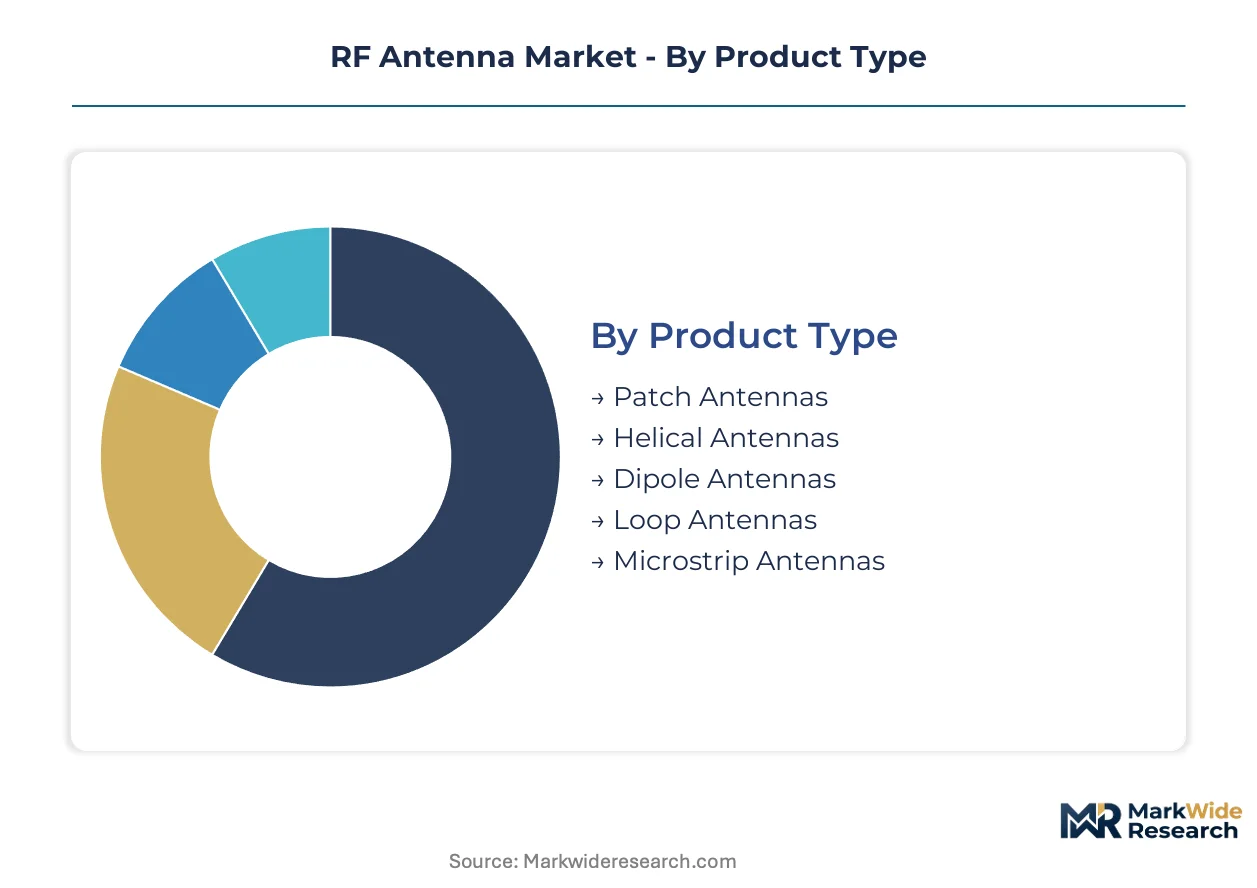
RF antenna procurement channels diverge sharply by performance tier and certification rigor. Defense contractors route high-value phased array systems through prime contractor integration, while telecommunication providers source massive MIMO arrays via direct equipment vendor relationships.
Product Type:
Patch antennas dominate consumer electronics distribution through contract manufacturers in Shenzhen and Taipei. Helical and dipole variants flow through specialized RF distributors serving aerospace and test instrumentation markets.
- Patch Antennas:Planar radiating elements etched on dielectric substrates enable low-profile integration in smartphones, wearables, and IoT sensors. China's BYD Electronic and Foxconn consume the highest volumes for 5G handset and connected vehicle programs. FCC Part 15 certification complexity limits new supplier entry despite commodity pricing.
- Helical Antennas:Wire-wound cylindrical structures deliver circular polarization for satellite links and GPS reception. ISRO's NavIC constellation deployments and SpaceX Starlink terminal production concentrate demand in Bangalore and Hawthorne manufacturing clusters. Dielectric loading variations separate commercial from radiation-hardened space grades.
- Dipole Antennas:Simple balanced radiators serve as reference standards and basic broadcast reception. AM/FM radio and legacy VHF applications sustain steady replacement demand.
- Loop Antennas:Magnetic field coupling enables near-field communication in RFID and NFC payment systems. Retail POS terminal upgrades drive incremental volume.
- Microstrip Antennas:Printed circuit board integration supports phased array subarrays in radar and 5G base stations. Defense primes source through captive fabrication or qualified substrate laminators.
By volume, Patch Antennas lead. By growth pace, Microstrip Antennas are climbing the fastest.
Technology:
Cost tiers separate passive beam-steering approaches from active electronically scanned arrays. Military qualification overhead pushes phased array pricing 8-12x above commercial MIMO equivalents.
- Beamforming:Analog or digital weighting of element signals shapes radiation patterns without mechanical movement. Enterprise Wi-Fi 6E access points and 5G small cells embed beamforming ASICs from Qualcomm and MediaTek reference designs.
- Phased Array:Distributed phase shifters enable microsecond beam steering for radar and electronic warfare. Raytheon and Northrop Grumman prime contracts absorb the majority of US DoD procurement through the Pentagon's Digital Engineering Initiative mandates.
- MIMO:Spatial multiplexing multiplies spectral efficiency through uncorrelated propagation paths. Massive MIMO 64T64R configurations anchor China Mobile and Verizon macro deployment specifications.
- Smart Antennas:Adaptive algorithms optimize patterns in response to interference or user mobility. Cognitive radio prototypes and private 5G networks pilot embedded intelligence.
- Diversity Antennas:Multiple uncorrelated elements mitigate multipath fading in mobile handsets. Dual-antenna configurations are now baseline in mid-tier smartphones.
Phased Array commands the highest unit margins. MIMO is expanding most quickly by installation count.
Application:
Application segmentation tracks frequency allocation and regulatory jurisdiction. Satellite and radar applications demand ITU coordination and national spectrum administration clearances that wireless communication bypasses.
- Wireless Communication:Cellular base stations, Wi-Fi infrastructure, and private network equipment constitute the revenue base. ETSI EN 301 908 certification gates European 5G massive MIMO deployment.
- Satellite Communication:Geostationary, medium earth orbit, and low earth orbit terminals require polarization agility and pointing precision. OneWeb and Amazon Kuiper constellation ground segment procurements are concentrating vendor qualification efforts.
- Radar Systems:Weather monitoring, air traffic control, and automotive ADAS operate across L-band through W-band. Automotive radar at 77 GHz is displacing 24 GHz under ETSI frequency harmonization.
- Military Communication:Secure tactical links and electronic warfare platforms specify radiation-hardened active arrays. US Navy's Next Generation Jammer program is compressing supplier lead times.
- Navigation:GPS, GLONASS, Galileo, and BeiDou reception requires right-hand circular polarization and axial ratio control. Precision agriculture and autonomous vehicle positioning are deepening performance requirements.
Wireless Communication leads by installed base. Satellite Communication is gaining share fastest.
End User:
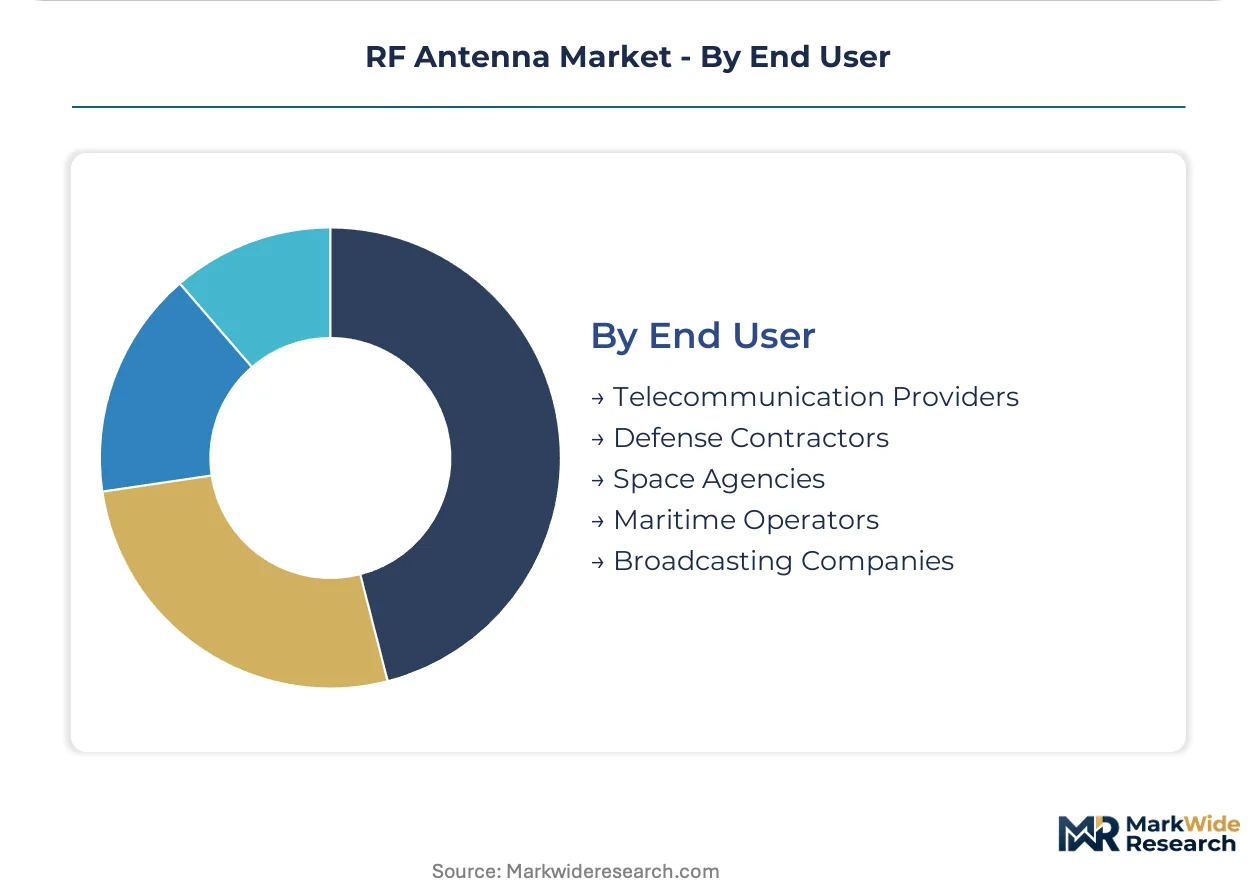
End user concentration determines contract structure and technical support intensity. Defense and space agencies impose multi-year qualification protocols that telecommunication providers abandoned for vendor-managed inventory models.
- Telecommunication Providers:Huawei, Ericsson, and Nokia direct antenna specification for macro and small cell deployment. China Tower Corporation's centralized procurement shapes global volume allocation.
- Defense Contractors:Lockheed Martin, BAE Systems, and Thales integrate subarray assemblies into platform-specific radomes. US DoD Trusted Foundry requirements constrain supplier pools.
- Space Agencies:NASA, ESA, and JAXA qualification protocols govern radiation tolerance and outgassing limits. Commercial space growth is relaxing heritage component mandates.
- Maritime Operators:Inmarsat and Iridium terminal refresh cycles drive stabilized antenna demand for commercial shipping fleets.
- Broadcasting Companies:ATSC 3.0 transition and DVB-T2 upgrades sustain transmitter antenna replacement demand.
Telecommunication Providers dominate by annual procurement value. Defense Contractors are expanding their share of high-performance RF content.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Substrate fabrication and antenna module assembly concentrate in East Asian manufacturing clusters, with precision component finishing distributed across German and US aerospace corridors. Regulatory divergence between FCC Part 27, ETSI EN 301 908, and China's GB standards fragments certification workflows for multi-region suppliers.
China
MIIT's 5G base station deployment mandates and satellite internet constellation programs drive massive MIMO antenna procurement at scale. GB standards certification accelerates domestic equipment timelines while restricting foreign supplier participation. Shenzhen and Dongguan manufacturing clusters absorb the highest volumes of patch antenna production for handset and IoT device integration.
United States
Defense primes compress phased array qualification cycles through Pentagon Digital Engineering Initiative mandates, pulling engineering talent from commercial 5G projects. FCC Part 15 and Part 27 rules enforce antenna efficiency floors and spurious emission limits that increase R&D overhead for base station manufacturers. Boston and Los Angeles aerospace corridors concentrate electronic warfare subsystem integration for Navy and Air Force programs.
Germany
Automotive radar at 77 GHz displaces 24 GHz under ETSI frequency harmonization, reshaping antenna specifications for ADAS platforms. REACH and RoHS compliance requirements constrain material selection for millimeter-wave substrates. Stuttgart and Munich industrial clusters anchor RF component supply into European automotive OEM supply chains.
Japan
METI funding for 6G pre-standardization research drives experimental antenna architectures in sub-terahertz bands. Specialized low-loss laminate suppliers concentrate pricing power for high-frequency substrates. Tokyo and Nagoya electronics corridors maintain captive fabrication for aerospace and instrumentation-grade antenna modules.
India
ISRO's commercial launch services and private sector ground station buildouts create demand for Ka-band and Ku-band terminal antennas. TRAI spectrum allocation frameworks for satellite broadband remain in regulatory development. Bangalore's aerospace and telecom hardware clusters are expanding RF subsystem assembly capacity for domestic and export markets.
RF Antenna Market Competitive Landscape
Concentration sits with integrated telecommunication equipment vendors and precision RF component specialists serving divergent buyer archetypes. The supplier base stratifies across three tiers: vertically integrated baseband-to-antenna platforms, specialized connector and module fabricators, and contract manufacturers serving consumer electronics volumes. M&A activity targets electromagnetic simulation software assets and substrate lamination capabilities. Geographic expansion focuses on India and Southeast Asia to bypass tariff exposure and capture satellite internet ground segment demand.
Among integrated equipment vendors, Huawei Technologies Co., Ltd. and Ericsson AB exemplify the baseband-to-antenna platform archetype with sustained R&D commitments to massive MIMO architectures. Amphenol RF anchors the precision component specialist tier through connector and antenna module specialization for aerospace and test instrumentation segments. These three companies occupy positions that reflect the market's structural bifurcation between telecommunications infrastructure scale and defense-aerospace performance premiums.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Comba Telecom Systems Holdings Ltd. |
| Amphenol RF (Amphenol Corporation) |
| HUBER+SUHNER |
| JMA Wireless |
| CommScope Holding Company Inc. |
| Ericsson AB |
| Airgain, Inc. |
| TE Connectivity plc |
| Others |
Pricing and Supply Chain Analysis
Ninety-day substrate lead times for specialized low-loss laminates concentrate pricing power with Japanese and Taiwanese suppliers, compressing margins for antenna module assemblers while amplifying cost pass-through leverage at the material tier. This inventory-to-pricing dynamic rewards buyers with strategic stockpile positions and punishes just-in-time procurement models during allocation periods.
Pricing Analysis
FCC Part 27 spurious emission limits dictate the pricing tier structure across licensed spectrum equipment, separating radiation-hardened military grades from commercial massive MIMO arrays. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with defense contractors absorbing 8-12x premiums for phased array qualification overhead. Cost compression in consumer patch antennas intensifies because chip-scale ceramic alternatives displace printed circuit board solutions in wearable applications. Telecommunication providers exhibit highest price sensitivity through centralized procurement mandates, while space agencies tolerate premium positioning for radiation-tolerant specifications.
Supply Chain Analysis
Strategic stockpile preferences dominate defense and aerospace procurement, contrasting with just-in-time inventory models in consumer electronics contract manufacturing. Substrate fabrication concentrates in Japan, Taiwan, and South Korea, while precision connector finishing localizes in German and US aerospace corridors. Raw material dependencies rest on ceramic dielectrics, copper-clad laminates, and rare-earth magnetic components for beamforming assemblies. Single-source vulnerability pervades specialized low-loss laminate supply, where two Japanese suppliers control high-frequency substrate pricing. Distribution runs through prime contractor integration for defense programs and direct equipment vendor relationships for telecommunications infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF antenna demand sits in early-cycle expansion as non-terrestrial network integration and 6G pre-standardization research open architectural white space before commoditization pressures mature.
For Market Incumbents: Fortify electromagnetic simulation talent pipelines through acquisition of specialized consulting firms and automated test data pipeline investments, defending against digital engineering mandates that now gate Pentagon contract eligibility. Deepen backward integration into substrate lamination capabilities to offset Japanese supplier pricing power, while capturing CHIPS Act packaging incentives for RF front-end module assembly. For New Entrants and Emerging Players: Electromagnetic simulation talent scarcity at mid-tier suppliers creates entry opportunity through outsourced design services and qualification acceleration partnerships. India's satellite internet ground segment buildouts represent the most penetrable geography, with ISRO commercial launch services lowering barrier to Ka-band terminal antenna qualification. Pursue channel partnerships with Bangalore aerospace clusters for domestic assembly foothold before export expansion. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across active antenna system architectures, favoring scaled platforms with semiconductor integration capabilities over pure-play radiator suppliers. Long-term viability through the next technology cycle favors targets with captive substrate qualification relationships and Pentagon digital engineering certification. Watch for 3GPP Release 18 timeline acceleration as inflection indicator for satellite-to-cellular convergence capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Substrate Lamination Acquisition | Captive supply of specialized low-loss laminates neutralizes Japanese supplier pricing leverage. |
| Digital Engineering Certification | Pentagon Digital Engineering Initiative compliance gates electronic warfare subsystem contract eligibility. |
| RF Front-End Module Integration | CHIPS Act advanced packaging subsidies reduce import dependency for antenna-filter-switch assemblies. |
| Reconfigurable Intelligent Surface Pilot | Programmable metamaterial deployments displace conventional small cell densification in indoor coverage extension. |
| India Ground Station Partnership | ISRO commercial launch services and private sector buildouts concentrate Ka-band terminal antenna demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with defense procurement officers, telecommunication equipment vendor antenna specification leads, substrate lamination plant managers, and electromagnetic simulation consulting directors. Secondary validation drew from FCC Part 15 and Part 27 docket filings, ETSI EN 301 908 certification registries, MIIT GB standard publication records, and Pentagon Digital Engineering Initiative contract award disclosures. Bottom-up antenna shipment aggregation and top-down infrastructure capex allocation were triangulated for volume reconciliation.
Across the projection horizon, analytical framework modeling tracked product type, technology tier, application frequency band, and end-user qualification rigor dimensions. CAGRs were derived from segment-level penetration curves and replacement cycle analysis, with defense procurement cycle compression and 5G base station deployment trajectories serving as primary forecast inputs.
Forecasts assume regulatory continuity in FCC Part 27, ETSI EN 301 908, and MIIT GB regimes; material policy shifts would require re-modeling. Spectrum reallocation decisions, satellite-to-ground coordination rule changes, and electromagnetic compatibility certification reciprocity agreements constitute specific revision triggers. Revision becomes warranted when defense procurement cycle compression accelerates beyond modeled parameters or substrate allocation periods extend past six-month thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Radio Frequency Front End Market
RF Components
Low Noise Amplifier Market
RF Components
Smart Antenna Market
RF Components
Z-Wave Products Market
RF Components
Frequency Synthesizer Market
RF Components
Gaas RF Switch Market
RF Components
China Small Signal Transistor Market
RF Components
Digital Phase Shifter Market
RF Components
RF Over Fiber (Rfof) Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
RF Filters Market
RF Components
RF Components Market
RF Components
Global Inductors Market
RF Components
RF Semiconductor Market
RF Components
Multilayer Coupled Inductor Market
RF Components
5G Driver Amplifier Market