
 Radiofrequency Identification (RFID) Market | 2026-2036
Radiofrequency Identification (RFID) Market Size, Share, and Industry Trends Forecast 2026-2036
Radiofrequency Identification (RFID) Market Analytics
Distribution channels for enterprise RFID hardware is narrowing as direct-to-manufacturer relationships replace multi-tier distributor networks in high-volume deployments. Zebra Technologies Corporation leverages its captive channel infrastructure to sustain pricing control across North American industrial accounts. Avery Dennison Corporation anchors global tag supply through backward integration into antenna inlay manufacturing. NXP Semiconductors dominates secure element silicon for payment and access credentials, competing primarily on cryptographic certification depth.
Radiofrequency Identification encompasses wireless data capture systems operating across low frequency to ultra high frequency spectra, typically employing passive backscatter or active transmitter architectures to exchange stored identifiers with interrogator devices. Passive RFID tags harvest energy from reader electromagnetic fields, enabling unit costs below ten cents for high-volume logistics applications. Ultra High Frequency technology leads volume shipments in supply chain management due to multi-meter read ranges and rapid bulk-scanning capabilities. Active RFID occupies premium positioning in asset tracking for cold-chain pharmaceuticals and high-value industrial equipment where real-time location telemetry commands superior margin pools.
FCC Part 15 rules govern unlicensed RFID spectrum allocation in the United States, while ETSI EN 302 208 standardizes European UHF carrier frequencies and power thresholds. ISO 18000-6C shapes global interoperability for passive UHF tags, directly conditioning reader-tag compatibility across multinational supply chains. Stakeholders must monitor evolving electromagnetic compatibility mandates from multiple national regulators and assess whether dual-frequency tag architectures warrant R&D commitment against fragmented spectrum policy trajectories.
Market Dynamics
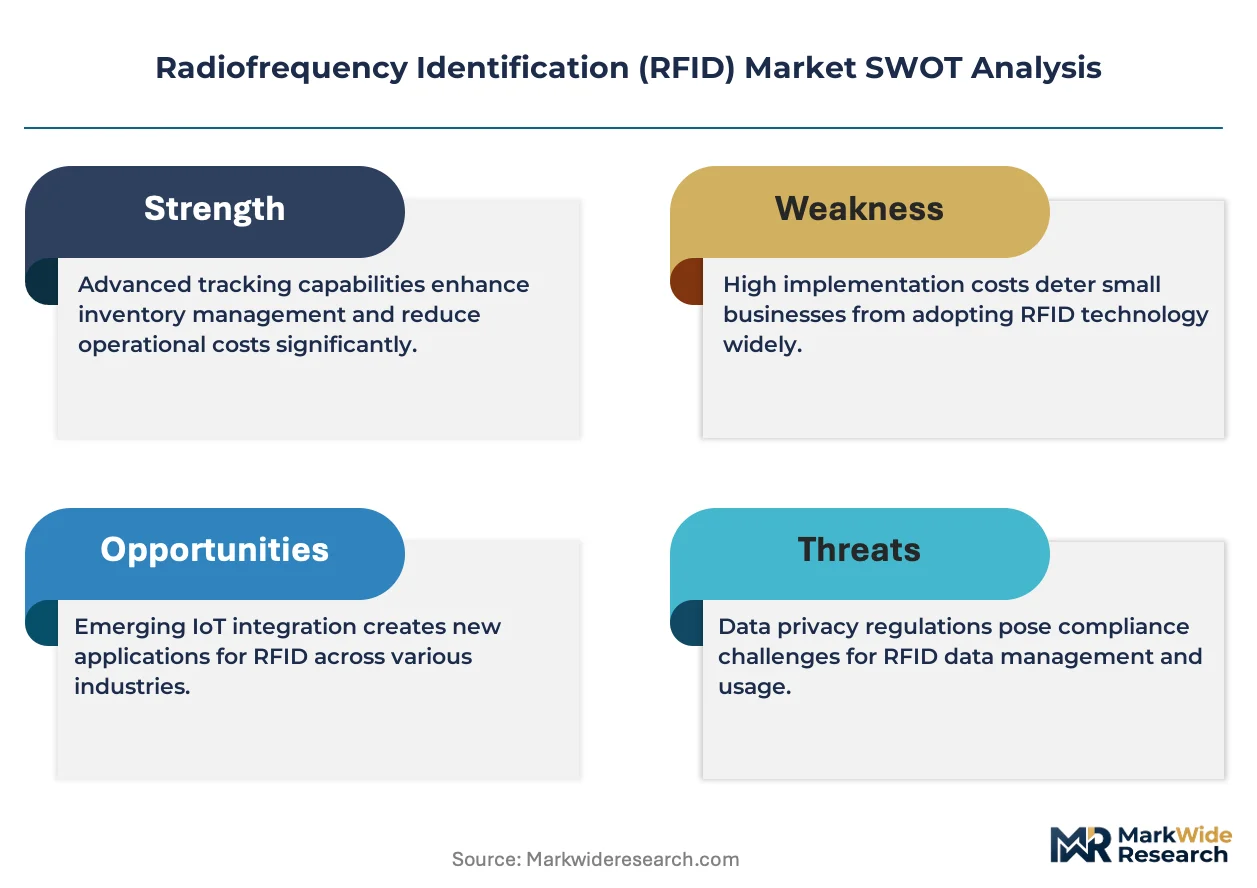
EU Green Deal e-waste directives are forcing RFID manufacturers to eliminate heavy-metal substrates and redesign antenna inlays for circular material flows, compressing legacy supply chains while opening certified-green premium tiers.
Growth Catalysts
- Patient wristband mandates:Healthcare providers in Germany are embedding UHF RFID into admission workflows for real-time location tracking, driven by hospital digitization frameworks.
- REACH substance restrictions:European chemical regulations are accelerating substitution of conductive inks toward silver-nanoparticle alternatives with lower environmental persistence.
- Smart factory architectures:Automotive OEM clusters in Stuttgart and Wolfsburg are deploying passive tag networks for work-in-progress traceability across multi-tier supplier ecosystems.
Market Restraints
- Silicon wafer cost volatility:Secure element chip fabrication depends on 300mm wafer supply concentrated in Taiwan and South Korea, exposing tag margins to foundry pricing swings.
- UHF spectrum fragmentation:FCC Part 15 and ETSI EN 302 208 maintain incompatible power thresholds, forcing dual-frequency R&D overhead without guaranteed regulatory convergence.
- Optical barcode persistence:Two-dimensional matrix codes retain cost advantages below five cents per unit for low-value consumer goods, capping RFID penetration in mass retail.
Strategic Opportunities
- Cold-chain pharmaceutical telemetry:Active RFID with temperature logging is penetrating vaccine distribution networks where real-time alerts command tenfold tag premiums over passive alternatives.
- India PLI scheme alignment:Domestic electronics manufacturing incentives are attracting antenna inlay production to Gujarat and Tamil Nadu, creating localized supply for Asian pharmaceutical exporters.
- Blockchain-anchored authentication:Convergence of NFC-enabled secure elements with distributed ledger verification is opening anti-counterfeit applications in luxury goods and spirits.
Industry Challenges
- RF engineering talent scarcity:Antenna design for metal-mount and liquid-proximity environments requires electromagnetic simulation expertise concentrated in Munich and Boston metro areas, constraining mid-tier tag vendor expansion.
- ISO 18000-6C certification timelines:Multi-protocol reader interoperability testing extends product launch cycles by eight to fourteen months for entrants targeting multinational logistics accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiofrequency Identification (RFID) Market |
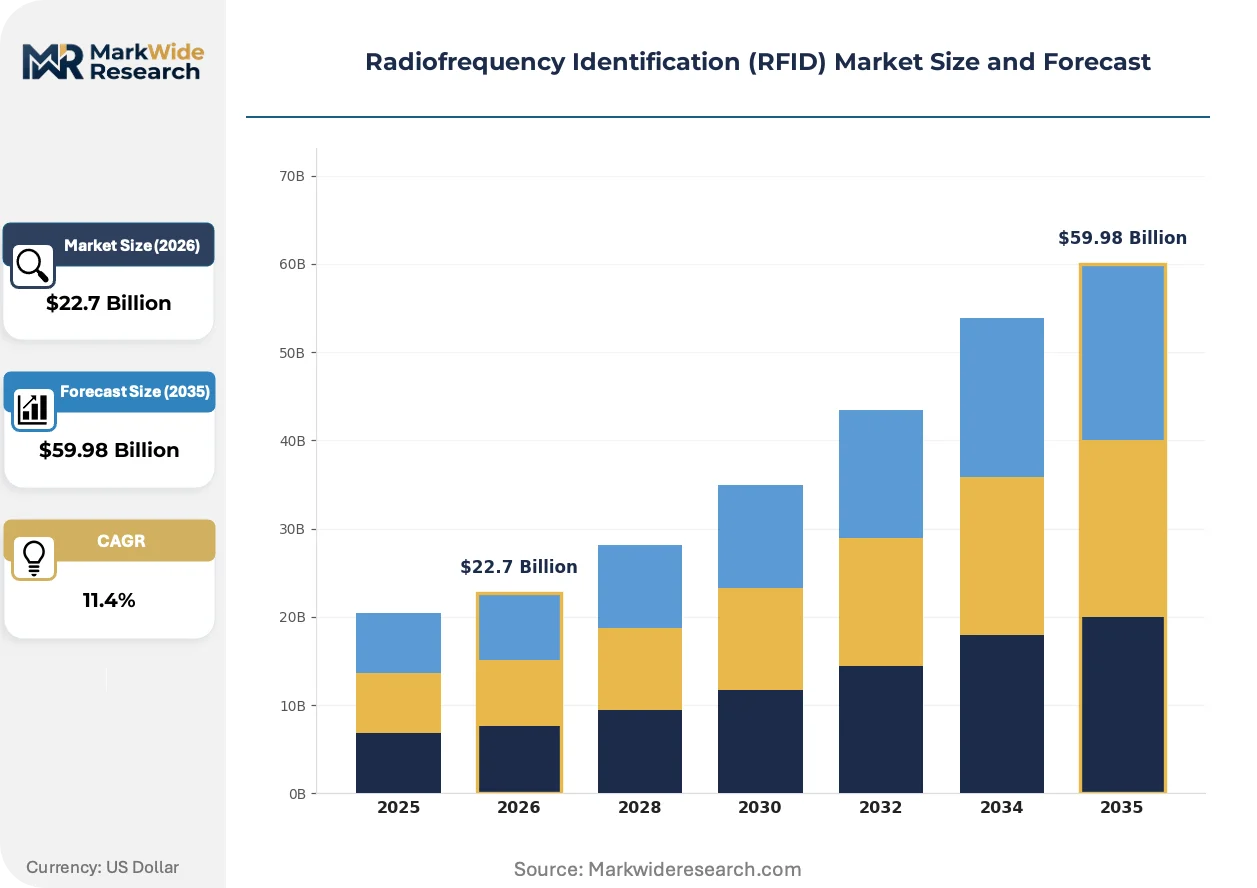
| Market Size in 2026 | $22.7 Billion |
| Market Size in 2035 | $59.98 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active RFID, Passive RFID, Semi-Passive RFID, RFID Tags Application: Asset Tracking, Inventory Management, Access Control, Supply Chain Management End User: Retail, Healthcare, Logistics, Manufacturing Technology: Near Field Communication, Ultra High Frequency, Low Frequency, High Frequency |
| Companies Covered | Zebra Technologies Corporation, Avery Dennison Corporation, NXP Semiconductors, Honeywell International, Impinj, Alien Technology, GAO Group, Checkpoint Systems, Fujitsu Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiofrequency Identification (RFID) Market Evolving Landscape
Chipless RFID encoding through printable conductive polymers is collapsing unit economics for single-use applications, while regulatory pressure on material provenance is elevating substrate traceability to a competitive differentiator.
Printed electronics using graphene-based conductive inks is digitizing inventory visibility for fast-moving consumer goods where traditional silicon tags remain cost-prohibitive. European packaging converters in the Netherlands and Denmark are piloting reel-to-reel antenna production at throughput rates matching conventional etched-aluminum methods. This technology is digitizing shelf-life monitoring by integrating humidity-sensitive resistive layers directly into label substrates.
The EU Green Deal's extended producer responsibility framework is mandating recyclability certifications for all electronics placed on European markets after 2027. RFID inlay manufacturers must now document substrate separation protocols and heavy-metal content below 0.1% threshold limits. German automotive suppliers are responding fastest, qualifying paper-based antenna carriers to preempt compliance risk in just-in-time component tracking.
Direct manufacturer relationships are displacing multi-tier distributor networks for enterprise hardware above ten thousand unit annual volumes. Industrial buyers in North American manufacturing verticals now expect field engineering support bundled with reader deployments, a service tier distributors cannot economically provision. This channel compression is most visible in automotive tier-one supplier campuses where Zebra Technologies maintains captive technical staff embedded at customer logistics centers.
Radiofrequency Identification (RFID) Market Segmentation
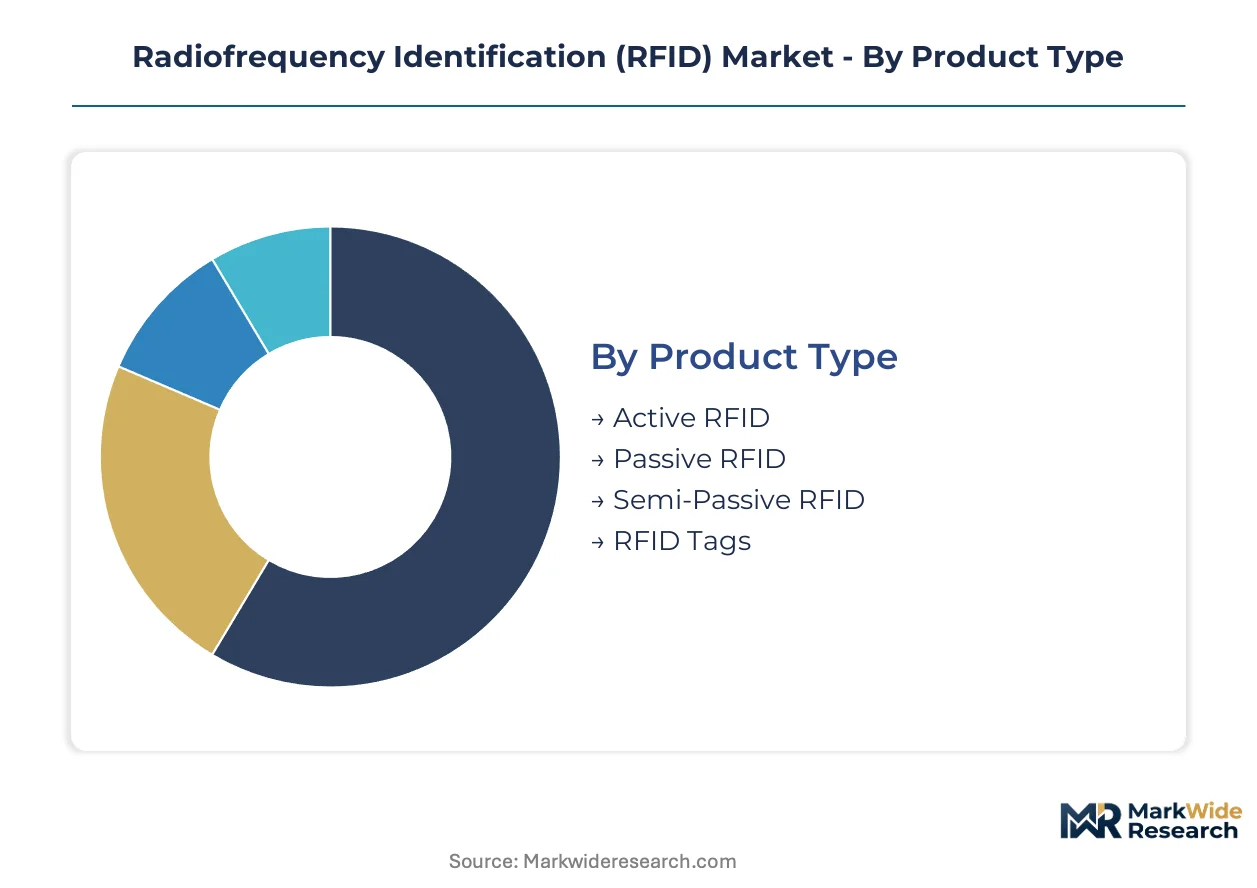
RFID market segmentation reveals divergent margin architectures across power-source categories, frequency spectra, and end-use verticals. Procurement patterns vary sharply between healthcare authentication mandates and automotive work-in-progress traceability requirements.
Product Type:
Power-source architectures define total cost of ownership and deployment scale across the use-case spectrum.
- Passive RFID:Tags harvest electromagnetic energy from reader fields, eliminating onboard batteries and enabling unit economics below ten cents for high-volume logistics. Demand concentrates most acutely in German automotive supplier networks where just-in-time component tracking mandates bulk-scale passive tag deployment.
- Active RFID:Self-powered transmitters deliver real-time location telemetry across multi-meter ranges, commanding premium positioning in cold-chain pharmaceutical distribution where temperature-logging alerts justify tenfold cost multiples over passive alternatives.
- Semi-Passive RFID:Battery-assisted backscatter extends read range without full transmitter complexity, serving intermediate applications in reusable container tracking for European retail pooling systems.
- RFID Tags:Standalone tag manufacturing as a discrete product category encompasses inlay fabrication, antenna printing, and final conversion into pressure-sensitive labels or durable enclosures for industrial asset marking.
The dominant share belongs to Passive RFID, while Active RFID is closing the gap fastest through cold-chain pharmaceutical telemetry adoption.
Application:
Functional deployment patterns track directly against operational complexity and integration depth.
- Supply Chain Management:Bulk-scanning UHF infrastructure dominates cross-dock operations and international freight corridors, with ETSI EN 302 208 and FCC Part 15 compliance requirements fragmenting hardware specifications across Atlantic trade lanes.
- Asset Tracking:Real-time location systems command premium hardware and software integration, penetrating hospital equipment fleets in Germany where digitization frameworks mandate wristband-to-asset visibility loops.
- Inventory Management:Cycle-counting automation through fixed reader gantries and handheld interrogators reduces labor intensity in retail backrooms and manufacturing warehouses.
- Access Control:Secure element integration into NFC-enabled credentials dominates corporate campus and healthcare facility entry systems, competing on cryptographic certification depth against biometric alternatives.
Supply Chain Management captures the broadest installed base, though Asset Tracking exhibits the steepest expansion trajectory through healthcare digitization mandates.
End User:
Customer-type concentration reflects sector-specific regulatory pressure and automation maturity.
- Healthcare:Patient wristband mandates and pharmaceutical authentication requirements drive UHF and NFC deployment across German hospital networks, with EU Green Deal e-waste directives forcing substrate redesign toward recyclable paper-based antenna carriers.
- Manufacturing:Stuttgart and Wolfsburg automotive clusters embed passive tag networks for work-in-progress traceability across multi-tier supplier ecosystems, demanding field engineering support bundled with reader hardware.
- Logistics:Third-party fulfillment operators deploy bulk-scanning infrastructure for parcel sortation and cross-border freight visibility, with India PLI scheme incentives attracting antenna inlay production to Gujarat for Asian pharmaceutical export corridors.
- Retail:Item-level tagging remains cost-constrained against optical barcode persistence below five cents per unit, though luxury goods authentication through blockchain-anchored NFC secure elements opens premium application tiers.
Manufacturing holds the dominant share, while Healthcare is gaining share fastest through regulatory digitization frameworks.
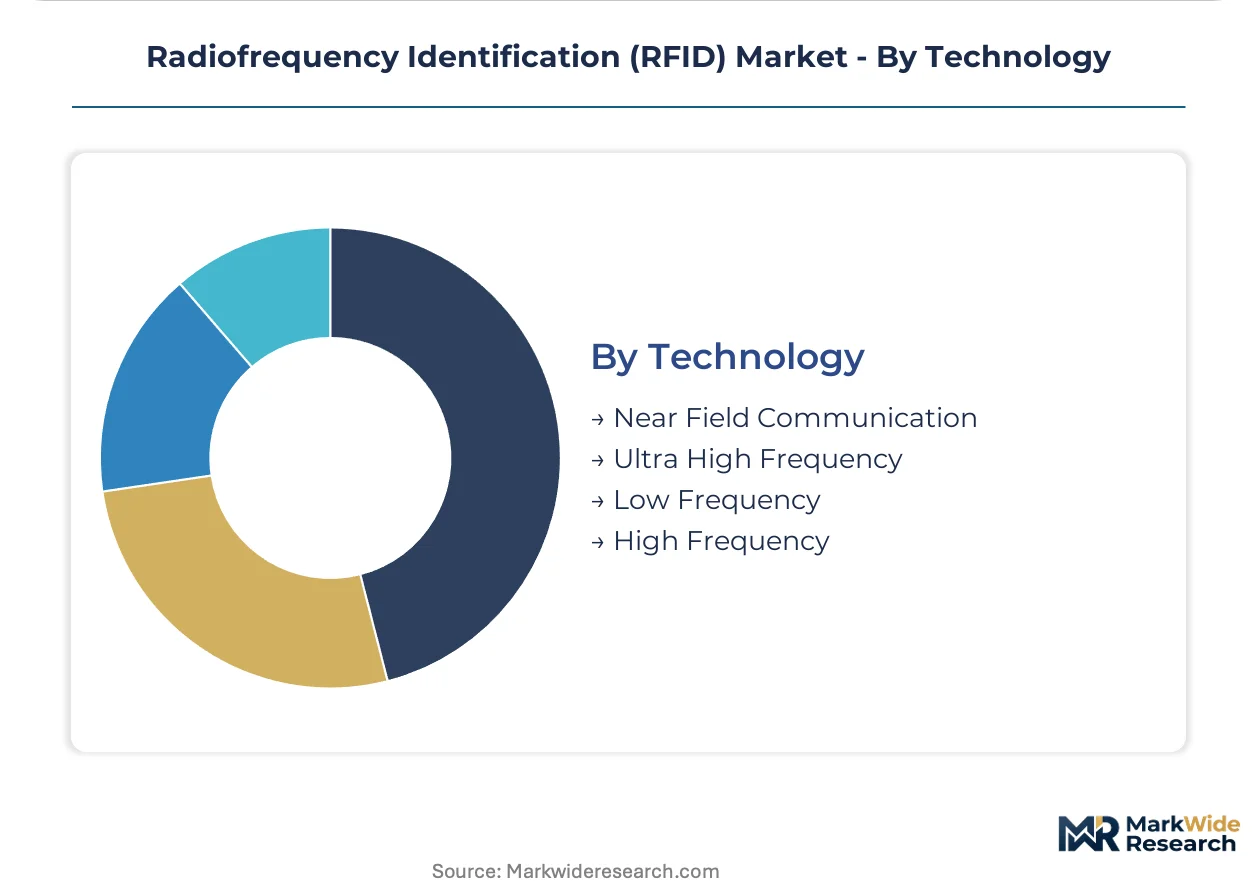
Technology:
Frequency-band selection conditions read range, interference tolerance, and global interoperability.
- Ultra High Frequency:Multi-meter read ranges and rapid bulk-scanning capabilities dominate supply chain volume shipments, though FCC Part 15 and ETSI EN 302 208 power threshold incompatibilities force dual-frequency R&D overhead.
- Near Field Communication:Short-range inductive coupling enables secure payment and access credential applications, with NXP Semiconductors dominating secure element silicon through cryptographic certification depth.
- High Frequency:ISO 15693 standardization supports library management and pharmaceutical bottle tracking where moderate range and liquid-proximity tolerance outweigh UHF penetration advantages.
- Low Frequency:Near-field magnetic coupling penetrates water and metal for animal identification and industrial container tracking, though limited data rates constrain application scope.
Ultra High Frequency commands the dominant share, while Near Field Communication is climbing the fastest through payment credential and anti-counterfeit convergence with distributed ledger verification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal extended producer responsibility frameworks are forcing substrate redesign across European manufacturing bases, while India's PLI scheme for electronics manufacturing is attracting antenna inlay production to Gujarat and Tamil Nadu for Asian pharmaceutical export corridors.
Germany
Automotive OEM clusters in Stuttgart and Wolfsburg embed passive UHF tag networks for work-in-progress traceability across multi-tier supplier ecosystems. REACH substance restrictions from ECHA accelerate substitution of conductive inks toward silver-nanoparticle alternatives with lower environmental persistence. Hospital digitization frameworks in Berlin and Munich mandate patient wristband tracking, driving NFC and UHF deployment into admission workflows.
United States
FCC Part 15 rules govern unlicensed spectrum allocation for RFID deployments across industrial manufacturing and retail logistics. FDA patient safety initiatives complement hospital digitization efforts in Boston and Houston metro areas, expanding wristband authentication mandates. Zebra Technologies maintains captive technical staff embedded at automotive tier-one supplier campuses in Michigan and Ohio, displacing traditional distributor networks.
China
MIIT standards development for ultra high frequency equipment shapes domestic interoperability requirements for supply chain infrastructure. Yangtze River Delta manufacturing clusters in Shanghai and Suzhou drive volume production of passive tags for export logistics. Dual carbon goals from MEE are pressuring substrate suppliers toward recyclable paper-based antenna carriers for circular material flows.
India
PLI scheme incentives for domestic electronics manufacturing attract antenna inlay production to Gujarat and Tamil Nadu, creating localized supply for pharmaceutical exporters. CDSCO pharmaceutical authentication requirements expand NFC-enabled secure element deployment across Mumbai and Hyderabad distribution networks. BIS certification mandates for imported RFID equipment protect nascent domestic converter capabilities.
Japan
METI industrial digitization roadmaps embed RFID into smart factory architectures across Nagoya automotive clusters and Osaka pharmaceutical manufacturing. JIS standardization for high frequency applications supports library management and pharmaceutical bottle tracking where liquid-proximity tolerance outweighs UHF penetration. PMDA cold-chain requirements for biologics distribution drive active RFID telemetry adoption in Kanto region vaccine networks.
Radiofrequency Identification (RFID) Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability clusters: silicon foundry-dependent secure element manufacturers, backward-integrated antenna inlay converters, and captive channel hardware integrators. Semiconductor specialists compete on cryptographic certification depth for payment credentials. Packaging converters battle on reel-to-reel throughput rates for passive tag economics. Systems integrators differentiate through field engineering bundling for enterprise deployments. Dominant competitive moves include strategic partnerships between tag converters and automotive OEMs, plus geographic expansion of antenna inlay production to India under PLI scheme alignment.
Among North American hardware integrators, Zebra Technologies Corporation exemplifies the captive channel archetype through embedded technical staffing at customer logistics centers. Avery Dennison Corporation anchors the backward-integrated converter tier, controlling antenna inlay manufacturing upstream of final label conversion. NXP Semiconductors occupies the secure element specialist position, competing on cryptographic certification depth for NFC payment and access credential applications. These three patterns—captive service bundling, upstream materials control, and silicon-level security differentiation—structure competitive positioning across procurement decisions.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Avery Dennison Corporation |
| NXP Semiconductors |
| Honeywell International |
| Impinj |
| Alien Technology |
| GAO Group |
| Checkpoint Systems |
| Fujitsu Group |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor shapes cost dynamics across the RFID value chain, with container rate volatility feeding into antenna inlay pricing and downstream tag economics. Supply concentration in Taiwanese foundry capacity and German automotive demand clusters creates asymmetric pricing power that rewards certified-green substrate suppliers with premium positioning against commodity converters.
Pricing Analysis
Certification level (ISO 18000-6C/REACH-compliant/EU Green Deal-certified) creates the primary spread across passive tag tiers, separating automotive-grade inlays from generic logistics labels. Three-tier pricing structure across premium certified, standard industrial, and economy unbranded levels reflects cryptographic depth and substrate traceability. Cost compression in economy passive tags is intensifying because printed graphene alternatives erode etched-aluminum cost floors. Healthcare authentication buyers show lowest price sensitivity due to patient safety liability, while mass retail procurement teams drive aggressive unit-cost negotiations below ten-cent thresholds.
Supply Chain Analysis
Export-control restrictions on semiconductor manufacturing equipment limit 300mm wafer capacity expansion beyond Taiwan and South Korea, constraining secure element chip supply for NFC credentials. Antenna inlay production draws from silver-nanoparticle conductive ink suppliers in Japan, PET substrate converters in China, and reel-to-reel equipment manufacturers in Germany. Single-source vulnerability concentrates in Taiwan foundry output for cryptographic silicon. Distribution runs through direct manufacturer relationships for enterprise volumes above ten thousand units, displacing multi-tier distributor networks in North American industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RFID market returns accrue to players controlling scarce electromagnetic simulation talent and backward-integrated antenna production, with capability gaps in metal-mount tag design constraining mid-tier vendor expansion.
For Market Incumbents: Insulate secure element margins by deepening cryptographic certification depth against emerging fabless competitors from India PLI scheme zones. Accelerate paper-based substrate qualification to preempt EU Green Deal extended producer responsibility mandates. Channel control through embedded field engineering at automotive OEM campuses protects pricing power against distributor disintermediation. For New Entrants and Emerging Players: Build out cold-chain pharmaceutical telemetry capabilities where active RFID temperature-logging commands tenfold premiums over passive alternatives. Target semi-passive reusable container tracking for European retail pooling systems as the most penetrable intermediate segment. Lead with blockchain-anchored NFC authentication for luxury goods verification, converging secure elements with distributed ledger verification protocols. For Investors and Strategic Acquirers: EU Green Deal 2027 recyclability deadlines reshape the acquisition landscape toward certified-green substrate converters with documented heavy-metal separation protocols. Five-to-ten year viability favors antenna inlay specialists with reel-to-reel throughput rates matching conventional methods. Watch for BIS certification mandates in India accelerating domestic converter consolidation as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Antenna Inlay Manufacturing | Avery Dennison controls upstream substrate supply against silver-nanoparticle ink volatility. |
| Embedded Field Engineering Deployment | Zebra Technologies maintains captive technical staff at automotive tier-one supplier campuses. |
| REACH-Compliant Conductive Ink Substitution | German automotive suppliers qualify silver-nanoparticle alternatives ahead of ECHA substance restrictions. |
| India PLI Scheme Manufacturing Alignment | Antenna inlay production shifts to Gujarat for Asian pharmaceutical export corridor supply. |
| Blockchain-Anchored NFC Authentication | Secure element convergence with distributed ledger verification opens luxury goods anti-counterfeit tiers. |
Research Methodology
Cross-validation between primary interviews with RFID systems integrators, antenna design engineers, and hospital procurement managers and secondary validation through FCC equipment authorization databases, ETSI harmonized standards filings, and EU Green Deal regulatory impact assessments anchors the qualitative findings. Bottom-up tag volume estimates from automotive supplier clusters in Stuttgart and Wolfsburg triangulate against top-down healthcare digitization spending frameworks from German hospital digitization mandates.
Calibration against historical ISO 18000-6C certification timelines and foundry capacity utilization rates from Taiwan and South Korea shapes the projection horizon. Segmentation dimensions span power-source architecture, frequency band, end-use vertical, and regional regulatory cluster. CAGRs derive from installed base growth rates cross-referenced with unit economics trajectories for printed graphene versus etched-aluminum antenna methods. Cold-chain pharmaceutical telemetry adoption curves and India PLI scheme manufacturing incentives feed scenario-weighted outputs.
Stress conditions across silicon wafer pricing volatility, EU e-waste directive enforcement intensity, and UHF spectrum fragmentation persistence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory convergence timelines and substrate substitution rates. Material shifts in FCC-ETSI power threshold harmonization or breakthrough chipless RFID encoding economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Flat Antenna Market
RF Components
RF Components Market
RF Components
CATV RF Amplifiers Market
RF Components
RFID Tags Market
RF Components
RF Front End Module Market
RF Components
Radio Frequency Front End Module Market
RF Components
Coaxial Splitters Market
RF Components
Smartphone RF Power Amplifier Market
RF Components
Digital Phase Shifter Market
RF Components
RF Spectrum Analyzer Market
RF Components
RFID Antenna Market
RF Components
RF Microwave MLCC Market
RF Components
Phase Shifters Market
RF Components
Multi-Mode Receiver Market
RF Components
Global Bulk Acoustic Wave (BAW) Filters Market
RF Components
EMI Microwave Absorber Market