
 Wi-Fi Module Market | 2026-2036
Wi-Fi Module Market Size, Share, and Industry Trends Forecast 2026-2036
Wi-Fi Module Market Intelligence
The divergence between high-performance, low-latency modules for industrial and automotive applications and cost-sensitive modules for basic consumer electronics is realigning the market's competitive structure. Murata Electronics specializes in highly integrated, miniaturized modules designed for space-constrained mobile and medical devices. Texas Instruments leverages its broad semiconductor portfolio to offer solutions across a wide spectrum of IoT end-points. Meanwhile, players like Longsys and MXCHIP compete on volume and cost-efficiency for the high-turnover consumer electronics segment.
A Wi-Fi module is a self-contained circuit board that integrates a radio frequency transceiver and a dedicated microcontroller to enable wireless connectivity. It operates on IEEE 802.11 standards, providing internet access to electronic devices that possess a host processor. Modules based on Wi-Fi 6 and Wi-Fi 6E technology command higher margins due to their performance in dense environments. Smart home applications constitute a high-volume segment, while connected vehicles represent a high-value, certification-intensive growth area.
Market access is governed by regional radio frequency regulations, including certifications from the FCC in the United States and compliance with CE marking in Europe. In China, the Ministry of Industry and Information Technology (MIIT) mandates specific approvals for radio transmission equipment, influencing module design and testing protocols. Stakeholders must navigate the evolving spectrum allocation policies and the security requirements embedded in new wireless standards.
Market Dynamics
The fundamental market dynamic is the bifurcation between high-performance modules for industrial automation and cost-optimized modules for consumer electronics. The adoption of Wi-Fi 6E technology is amplifying this split, creating distinct value chains for different end-markets.
Growth Catalysts
- Wi-Fi 6 and 6E Adoption:The technical superiority of Wi-Fi 6/6E, offering lower latency and higher capacity, is driving replacement cycles and new deployments in dense environments like smart factories and public venues.
- National IoT Policies:Government initiatives, such as China's push for smart city infrastructure, create large-scale, state-supported demand for connected devices, directly stimulating module consumption for public utilities and transport systems.
- Smart Home Proliferation:The expansion of the smart home ecosystem, encompassing everything from lighting to appliances, constitutes a massive, high-volume demand driver for cost-sensitive, low-power Wi-Fi modules.
Market Restraints
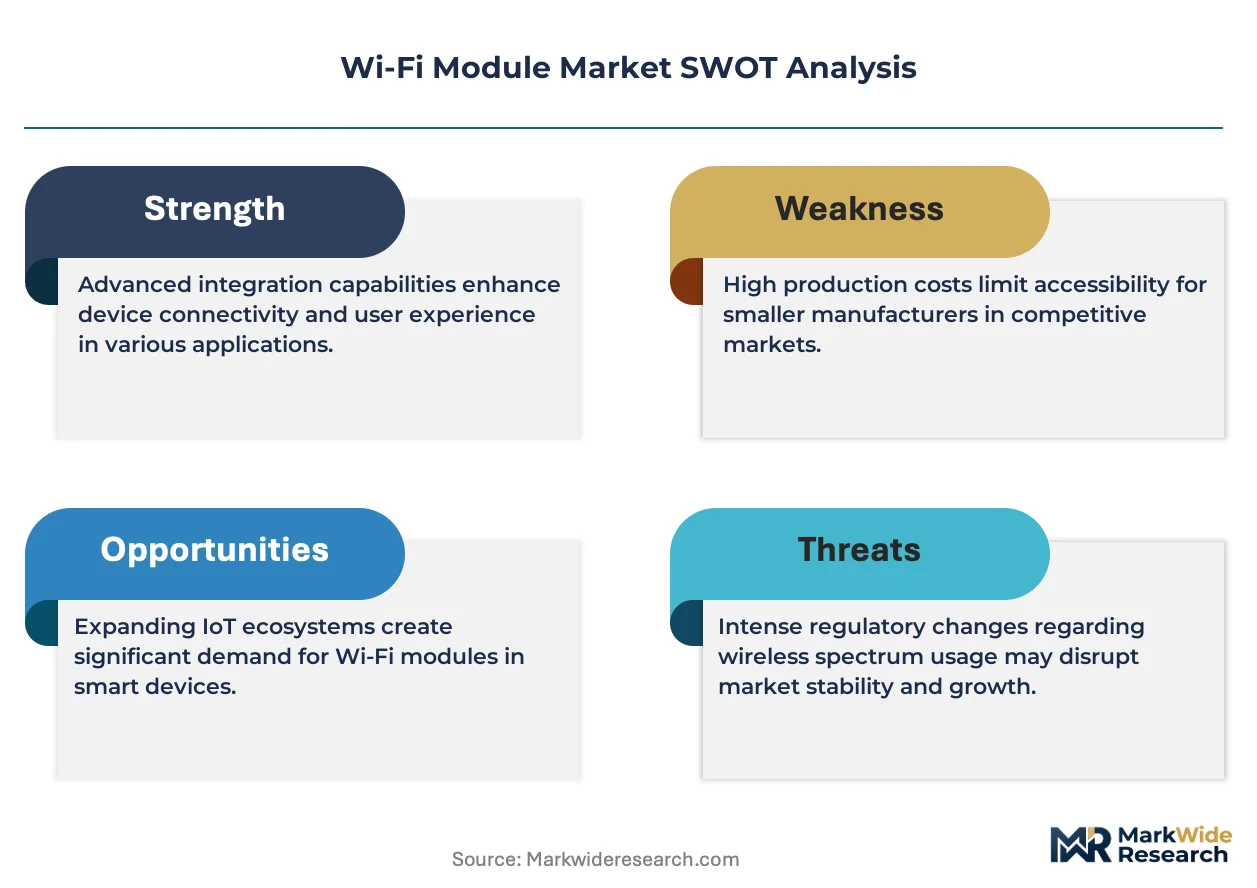
- Regulatory Fragmentation:Module manufacturers face significant overhead navigating disparate radio frequency regulations and certification bodies, such as the FCC in the US, CE marking in Europe, and MIIT in China.
- Semiconductor Volatility:The Wi-Fi module supply chain is directly exposed to fluctuations in the availability and pricing of core semiconductor components, including transceivers and microcontrollers, creating production risks.
- Spectrum Congestion:In many urban and industrial settings, the legacy 2.4 GHz and 5 GHz bands are highly congested, degrading performance and forcing upgrades to newer, more expensive Wi-Fi 6E modules to access the 6 GHz band.
Strategic Opportunities
- Connected Vehicles:Automotive applications represent a high-value growth vector, with modules being integrated for infotainment, telematics, and vehicle-to-everything (V2X) communication, despite stringent certification requirements.
- Technology Convergence:Combining Wi-Fi with other wireless standards like Bluetooth Low Energy (BLE) into a single, compact module addresses demand for multi-protocol connectivity in battery-powered IoT devices and wearables.
- Emerging Market Penetration:Developing economies in Southeast Asia and Latin America present significant growth potential as their industrial and consumer IoT adoption begins to accelerate, creating new markets for module vendors.
Industry Challenges
- Certification Timelines:The lengthy and expensive processes for obtaining certifications for specific high-stakes verticals, such as automotive-grade (AEC-Q100) or medical devices, create high barriers to entry and slow down product launches.
- Security Implementation:Implementing and maintaining robust, up-to-date security protocols like WPA3 across a vast and diverse fleet of IoT devices is a complex and continuous challenge for module and device makers.
- Interoperability with Legacy Systems:Ensuring new Wi-Fi modules can seamlessly integrate with and operate alongside older host processors and existing network infrastructure remains a persistent technical hurdle in industrial and enterprise settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wi-Fi Module Market |
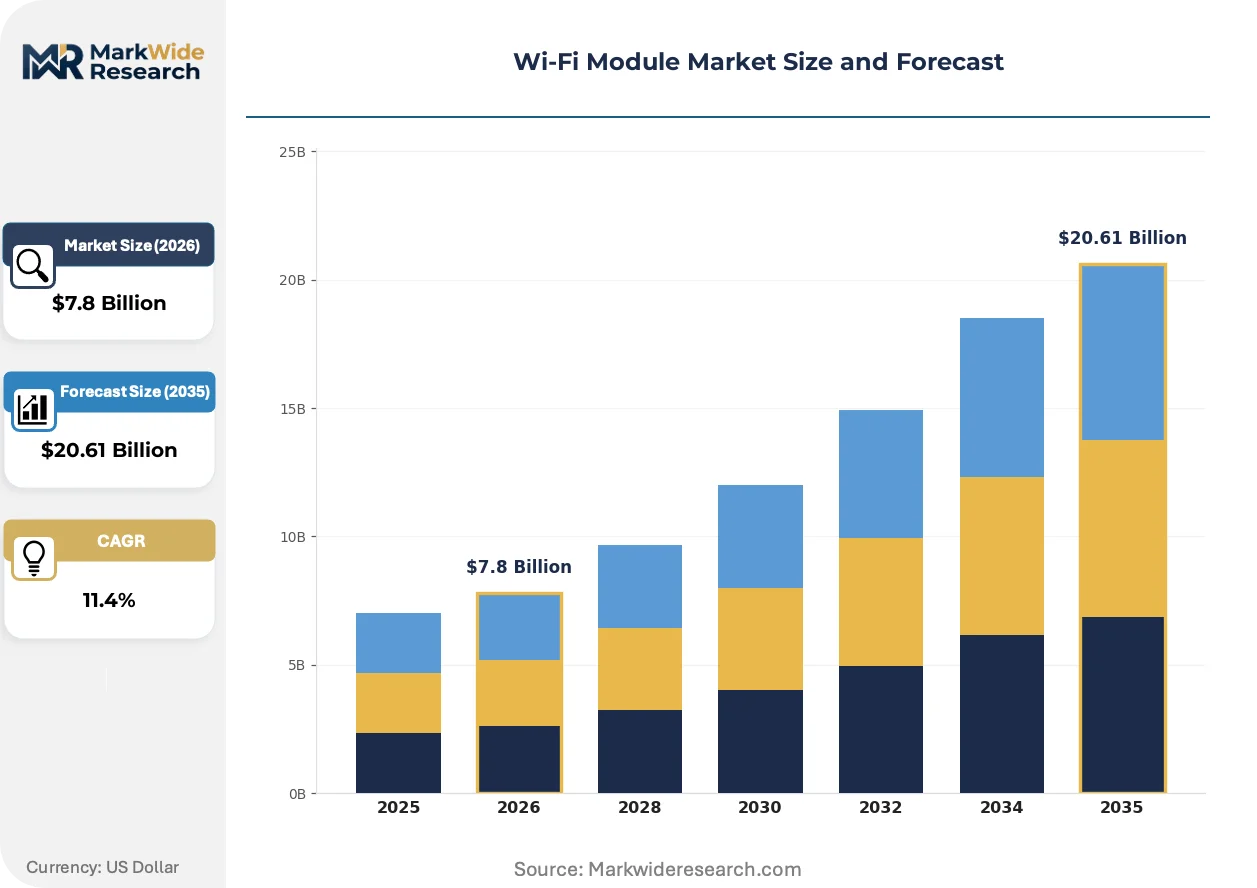
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Module, Standalone Module, PCB Module, USB Module, Mini PCIe Module Technology: Wi-Fi 4, Wi-Fi 5, Wi-Fi 6, Wi-Fi 6E, Wi-Fi 7 Application: Smart Home, Industrial Automation, Consumer Electronics, Building Management, Connected Vehicles End User: OEMs, System Integrators, Aftermarket Suppliers, Network Operators, IoT Solution Providers |
| Companies Covered | Texas Instruments, Microchip Technology, Murata Electronics, MXCHIP, Silex Technology, USI, Silicon Labs, Longsys, AzureWave, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wi-Fi Module Market Strategic Shifts & Innovations
Miniaturization and functional integration are defining current product development cycles. The market is moving toward highly integrated, pre-certified solutions that reduce design complexity and accelerate time-to-market for device manufacturers across all verticals.
Embedded System-on-Chip (SoC) Designs
System-on-Chip architectures integrate the radio transceiver, power management unit, and microcontroller onto a single piece of silicon. Device manufacturers in the wearables, smart home, and mobile accessory segments are rapidly adopting these compact designs. This high level of integration is automating the RF design portion of product development, allowing teams to focus on application-level software.
Spectrum Allocation for Wi-Fi 6E
Regulatory bodies worldwide are opening the 6 GHz band for unlicensed Wi-Fi use, following the lead of the FCC in the United States. This policy action directly enables the deployment of Wi-Fi 6E, which operates exclusively in this new spectrum. Module vendors targeting high-performance industrial, enterprise, and augmented reality applications are most affected, redesigning their premium-tier products to capitalize on the uncongested bandwidth.
Shift to Pre-Certified Modules
Device makers are increasingly procuring fully certified modules rather than designing radio frequency circuits from discrete components. This approach shifts the burden of complex and costly regulatory compliance testing, such as for FCC or CE standards, from the device maker to the module vendor. The pattern is most visible within the fast-moving consumer electronics and fragmented IoT startup sectors in North America and Europe.
Wi-Fi Module Market Segmentation
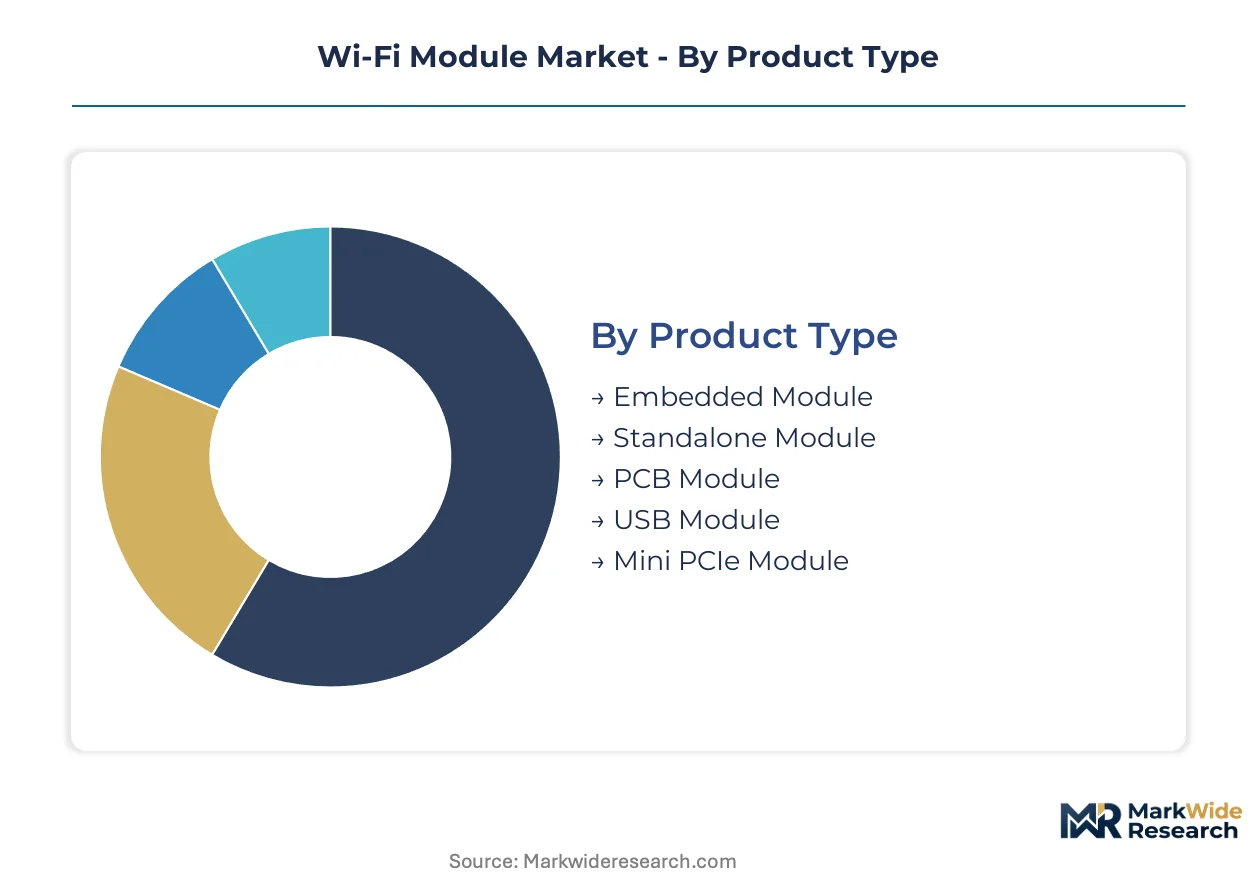
The Wi-Fi module market exhibits diverse requirements across various product configurations, underlying technologies, application domains, and end-user segments. Understanding these distinctions is critical for module manufacturers to align their product development and market strategies with specific demand profiles.
Product Type:
The spectrum from highly customized to standardized module solutions defines this category's competitive dynamics.
- Embedded Module:These modules are designed for direct integration onto a host device's printed circuit board, leveraging the host processor for core functions. Demand concentrates in compact IoT devices and smart home products, driven by miniaturization and low-cost manufacturing requirements.
- Standalone Module:A standalone module incorporates its own microcontroller and memory, offering a complete Wi-Fi solution with minimal reliance on a host processor. Industrial automation and complex embedded systems often utilize these modules for their self-contained operation and robust performance.
- PCB Module:PCB modules are surface-mount components, offering a balance between integration and flexibility for various electronic device designs.
- USB Module:These modules connect via a Universal Serial Bus interface, providing easy plug-and-play Wi-Fi connectivity for devices lacking integrated wireless capabilities.
- Mini PCIe Module:Mini PCIe modules are designed for integration into laptops, industrial PCs, and network appliances, offering a standardized form factor for expansion.
Leading the category by volume: Embedded Module. Growing fastest: USB Module.
Technology:
The maturity level of Wi-Fi standards significantly influences module adoption, performance, and cost structures within this segment.
- Wi-Fi 6E:Operating in the newly available 6 GHz band, Wi-Fi 6E modules offer unprecedented low latency and high capacity in uncongested spectrum. Industrial automation and augmented reality applications drive demand for these high-performance modules.
- Wi-Fi 6:Wi-Fi 6 modules enhance performance in dense environments through technologies like OFDMA and MU-MIMO, providing efficiency for multiple connected devices. Smart factories and public venues increasingly deploy these modules for their improved network capacity.
- Wi-Fi 4:Also known as 802.11n, Wi-Fi 4 modules provide foundational wireless connectivity for basic IoT devices due to their cost-effectiveness.
- Wi-Fi 5:Wi-Fi 5, or 802.11ac, offers higher throughput than Wi-Fi 4, making it suitable for consumer electronics and streaming applications.
- Wi-Fi 7:The latest generation, Wi-Fi 7 (802.11be), introduces extreme high throughput and ultra-low latency capabilities for future advanced applications.
Performance differentiation drives adoption across these technology tiers.
Application:
The margin profiles for Wi-Fi modules vary considerably across different application areas, reflecting diverse performance and certification demands.
- Industrial Automation:Wi-Fi modules in industrial automation facilitate real-time data processing, predictive maintenance, and control within smart factories and critical infrastructure. Stringent reliability and security requirements elevate module specifications for these environments.
- Connected Vehicles:Automotive applications integrate Wi-Fi modules for infotainment, telematics, and vehicle-to-everything (V2X) communication, necessitating rigorous certification and extended operational temperature ranges. Safety and regulatory compliance are paramount in this high-value segment.
- Smart Home:This high-volume segment encompasses devices like smart lighting, thermostats, and security cameras, requiring cost-effective and low-power Wi-Fi modules.
- Consumer Electronics:Wi-Fi modules enable connectivity in a broad range of consumer devices, including televisions, gaming consoles, and personal computers.
- Building Management:Building management systems utilize Wi-Fi modules for energy efficiency, access control, and environmental monitoring within commercial and residential buildings.
Each application segment demands specific performance and cost profiles from Wi-Fi modules.
End User:
The specific customer type dictates module procurement patterns and the level of technical support required from module vendors.
- OEMs:Original Equipment Manufacturers integrate Wi-Fi modules into their final products, ranging from consumer electronics to industrial equipment. Their focus is on seamless integration, cost-efficiency, and rapid time-to-market for their devices.
- IoT Solution Providers:These entities develop and deploy comprehensive Internet of Things systems, often bundling Wi-Fi modules with sensors, gateways, and cloud services. They seek pre-certified, easy-to-integrate modules that accelerate solution deployment for various enterprise and smart city projects.
- System Integrators:System integrators combine various hardware and software components to create customized solutions for clients across different industries.
- Aftermarket Suppliers:Aftermarket suppliers provide Wi-Fi connectivity solutions for existing devices, often through dongles or upgrade kits.
- Network Operators:Network operators deploy Wi-Fi modules in their infrastructure, such as access points and customer premises equipment, to deliver wireless services.
The diverse needs of these end-user categories dictate module selection and support requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's expansive electronics manufacturing ecosystem drives significant demand for Wi-Fi modules, underpinning global supply chains. This concentration of production and innovation influences market dynamics across key economies. Each nation presents unique regulatory landscapes and growth vectors.
China
China's national IoT policies stimulate demand for Wi-Fi modules in smart city infrastructure and public utility projects. The Ministry of Industry and Information Technology (MIIT) mandates specific approvals for all radio transmission equipment. Manufacturing hubs like the Yangtze River Delta integrate these modules into a vast array of industrial devices.
United States
The United States sees strong demand for Wi-Fi modules in connected vehicles and advanced industrial automation systems. Federal Communications Commission (FCC) certifications are critical for market access. Silicon Valley and Texas technology corridors foster innovation in high-performance Wi-Fi 6E modules for enterprise applications.
Germany
German industrial automation and automotive sectors require high-reliability Wi-Fi modules for smart factories and V2X communications. Compliance with CE marking is essential for all electronic products sold within the European Union. Bavaria's strong automotive manufacturing base integrates advanced Wi-Fi solutions for telematics and infotainment.
Japan
Japanese consumer electronics and precision industrial equipment drive demand for compact, high-performance Wi-Fi modules. The Ministry of Economy, Trade and Industry (METI) oversees regulations impacting module design and import. The Kanto region, including Tokyo, remains a hub for developing cutting-edge Wi-Fi 6E modules for next-generation devices.
South Korea
South Korea's robust smart home market and 5G infrastructure expansion generate substantial demand for Wi-Fi modules. The Korean Communications Commission (KCC) sets technical standards and certification requirements for wireless devices. The Seoul metropolitan area leads in integrating Wi-Fi modules into innovative consumer electronics and IoT solutions.
Wi-Fi Module Market Key Industry Players
Premium-margin players sit above commodity-margin players across performance and certification dimensions within the Wi-Fi module market. This market exhibits a tiered structure, with a clear bifurcation between high-performance, high-reliability modules and cost-optimized, volume-driven solutions. Two strategic archetypes emerge: specialized innovators focusing on highly integrated designs, and broad-portfolio providers leveraging extensive semiconductor expertise. Competitive moves center on strategic partnerships for technology co-development and portfolio diversification to address various end-market needs.
On the premium-tier vector, Texas Instruments leverages its broad semiconductor portfolio to offer solutions across a wide spectrum of IoT end-points, exemplifying a diversified approach. Murata Electronics represents specialized innovation, focusing on highly integrated, miniaturized modules for space-constrained mobile and medical devices. Meanwhile, Longsys occupies a position in the cost-sensitive, high-volume segment, competing on efficiency for the consumer electronics market.
| Leading Market Players |
|---|
| Texas Instruments |
| Microchip Technology |
| Murata Electronics |
| MXCHIP |
| Silex Technology |
| USI |
| Silicon Labs |
| Longsys |
| AzureWave |
| Others |
Cost & Logistics Intelligence
Stringent certification requirements for connected vehicles and medical devices elevate module specifications, forcing suppliers to invest heavily in compliance and driving premium pricing for specialized solutions. This dynamic bifurcates the market into high-margin and cost-sensitive segments.
Pricing Analysis
Performance-based pricing anchors high-end Wi-Fi modules, where throughput and low latency directly translate to operational efficiency in industrial automation. The dominant pricing structure is per-unit transactional, differentiated by certification level, such as AEC-Q100 for automotive, and miniaturization for medical devices. Cost compression in the high-volume consumer electronics segment intensifies due to intense competition and commoditization. Industrial and automotive OEMs exhibit lower price sensitivity compared to mass-market consumer electronics manufacturers.
Supply Chain Analysis
End-of-life management for high-value Wi-Fi modules, particularly in industrial and automotive applications, increasingly considers component recovery and refurbishment potential. The primary supply chain for core components such as transceivers and microcontrollers concentrates in Taiwan, South Korea, and China. Semiconductor volatility presents a significant structural risk, impacting module availability and pricing. Distribution runs through direct sales channels to large OEMs and a network of specialized electronics distributors for smaller IoT solution providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wi-Fi module market presents a significant cost-of-compliance story, where adherence to regulations like the FCC certification in the United States establishes a substantial barrier-to-entry moat for new participants. This regulatory landscape favors established players with robust testing and approval infrastructures.
For Market Incumbents: Deepen investment in next-generation Wi-Fi 7 module R&D to maintain a performance edge against emerging low-cost competitors. Expand certification portfolios to cover rigorous standards like AEC-Q100 for automotive applications, reinforcing market access and pricing power. Strengthen relationships with large OEMs through dedicated engineering support and pre-certified solutions, securing long-term supply agreements. This strategy counters margin pressure from commoditization in basic consumer segments. For New Entrants and Emerging Players: Capture market share by focusing on cost-effective, pre-certified Wi-Fi 4 and Wi-Fi 5 modules for the burgeoning smart home and basic IoT segments. Target developing economies in Southeast Asia and Latin America, offering significant growth potential with less stringent regulatory hurdles. A go-to-market strategy emphasizing ease of integration and robust developer support can accelerate adoption among fragmented IoT startups. For Investors and Strategic Acquirers: The window for entry favors strategic acquirers consolidating fragmented expertise in high-value Wi-Fi module segments. Long-term viability is strong for companies specializing in miniaturized, highly integrated solutions or those with extensive certification for automotive and medical devices. Target acquisition profiles include specialized innovators possessing strong intellectual property in Wi-Fi 6E/7. A key signal to watch is increasing M&A activity among automotive-grade module providers.| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Wi-Fi 7 Modules | Establishes technological leadership in the next generation of wireless connectivity. |
| Certification Investment: AEC-Q100 | Unlocks access to the high-value connected vehicle segment. |
| Strategic Partnership: Semiconductor Foundries | Secures critical component supply amidst global volatility. |
| Geographic Expansion: Southeast Asia | Taps into accelerating industrial and consumer IoT adoption. |
| Platform Integration: Multi-Protocol Modules | Addresses demand for converged connectivity in diverse IoT devices. |
Research Approach
Independent corroboration across MIIT reports, FCC filings, and Wi-Fi Alliance publications underwrites the qualitative findings and quantitative estimates. Primary interviews with device manufacturers, IoT solution providers, and module integrators provided critical insights into market dynamics. Secondary data sources included regulatory body guidelines and industry consortium reports. A rigorous process of bottom-up and top-down triangulation validated all market figures.
Historical reference periods anchored the forecast window, establishing baseline growth trajectories and market sizing. The analytical framework modeled market demand across product type, technology, application, end-user, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical trends and future technology roadmaps. Key forecast inputs included Wi-Fi technology adoption rates and IoT device proliferation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to spectrum allocation changes and semiconductor supply shocks. Forecasts reflect underlying assumptions regarding technological advancements and evolving security standards. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF-Microwave for 5G Market
RF Components
Digital Radio Frequency Market
RF Components
Monolithic Microwave Integrated Circuit (MMIC) Market
RF Components
Dielectric Resonator Market
RF Components
GPS Low Noise Amplifier Market
RF Components
Global RF Power Semiconductor Market
RF Components
Millimeter Wave Equipment Market
RF Components
Z-Wave Products Market
RF Components
Global Small Cell Power Amplifier Market
RF Components
Multiband Booster Market
RF Components
RF Interconnect Market
RF Components
RF Filters Market
RF Components
Frequency Synthesizer Market
RF Components
Global RF Plasma Generator Market
RF Components
RF and Microwave Diodes Market
RF Components
Acoustic Wave Filters Market