
 Global Actuator Sensor Interface Market | 2026-2036
Global Actuator Sensor Interface Market Size, Share, and Industry Trends Forecast 2026-2036
Global Actuator Sensor Interface Market Analysis
The migration from hardwired point-to-point I/O toward Ethernet-based deterministic networking is reshaping how actuator sensor interfaces integrate into modern control architectures. Siemens leverages its SIMATIC portfolio to dominate integrated automation platforms across process industries. Rockwell competes through its Logix ecosystem, anchoring North American manufacturing with tightly coupled controller-interface bundles. Pepperl+Fuchs specializes in hazardous-area certified interfaces, extending its position in oil, gas, and chemical installations where intrinsic safety requirements are non-negotiable.
An actuator sensor interface constitutes the electromechanical and electronic boundary layer that translates digital control commands into physical actuator motion while feeding sensor telemetry back to programmable logic controllers or distributed control systems, typically operating at voltage levels between 24V DC and 230V AC with response times measured in milliseconds. Electric actuators and digital technology together command the strongest margin pools as factories phase out pneumatic distribution infrastructure and demand precise position feedback for closed-loop servo control. Fieldbus technology retains substantial installed-base presence but faces displacement by EtherNet/IP and PROFINET variants that unify information technology and operational technology traffic on shared cabling.
The EU Green Deal and F-Gas Regulation push European manufacturers toward electrically actuated systems with lower leakage risk than pneumatic alternatives, while China's MIIT dual carbon goals mandate energy-efficiency ratings on new industrial equipment that favor intelligent sensor-actuator pairings with power diagnostics. The US EPA and OSHA jointly influence demand through emissions monitoring requirements and machine safety standards that specify redundant feedback channels. Stakeholders must monitor how IEC 62443 cybersecurity standards for operational technology networks reshape product certification requirements and procurement specifications across critical infrastructure sectors.
Market Dynamics
The migration from pneumatic to electric actuation is compressing installation footprints while forcing simultaneous upgrades to sensor-actuator interface architectures across automotive, food processing, and chemical plants.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in industrial cooling systems is accelerating replacement of pneumatic valve trains with electric actuators requiring precision position feedback interfaces.
- Automotive EV battery manufacturing:Gigafactory construction in Germany, China, and the United States is driving demand for cleanroom-compatible sensor-actuator modules with integrated power diagnostics.
- EtherNet/IP convergence:Single-cable architectures that unify sensor data and actuator control traffic are displacing legacy fieldbus installations in greenfield smart factory deployments.
Market Restraints
- Semiconductor input volatility:Dedicated industrial Ethernet PHY chips and isolated DC-DC converters for 24V field circuits face allocation constraints from automotive and consumer electronics demand.
- Intrinsic safety certification backlog:IEC 60079-11 entity parameter recertification for hazardous-area interfaces creates 14-18 month approval timelines that gate oil and gas project commissioning.
- Pneumatic infrastructure lock-in:Existing compressed air distribution systems in mature manufacturing regions represent sunk capital that delays electric actuator conversion economics.
Strategic Opportunities
- India PLI scheme for manufacturing:Production-linked incentives for industrial automation equipment are attracting module assembly investments that localize sensor-actuator interface supply for South Asian process industries.
- Cybersecurity certification services:IEC 62443-4-2 component-level compliance for operational technology networks opens recurring revenue streams around secure boot and encrypted firmware update capabilities.
- Digital twin integration:Real-time actuator health telemetry streamed directly into asset performance management platforms is creating attach-rate expansion for diagnostic-enabled interface modules.
Industry Challenges
- OT-IT skill convergence:Maintenance technicians must now troubleshoot Ethernet packet timing alongside electromechanical actuator failures, compressing training curves for brownfield workforce transitions.
- Legacy controller protocol fragmentation:Proprietary serial interfaces from 1990s distributed control systems resist seamless integration with modern PROFINET or EtherNet/IP actuator modules without gateway hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Actuator Sensor Interface Market |
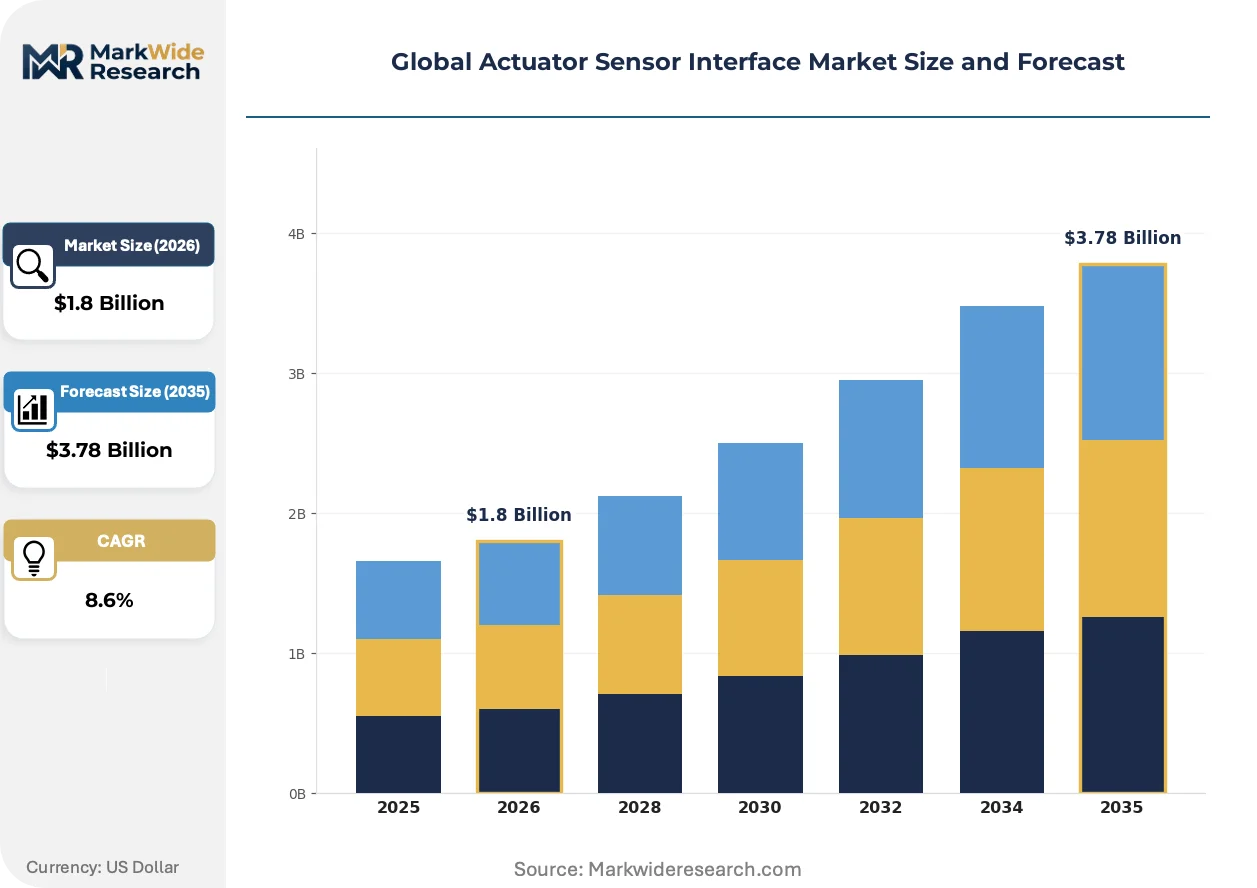
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic Actuators, Hydraulic Actuators, Electric Actuators, Mechanical Actuators Technology: Analog Technology, Digital Technology, Fieldbus Technology, Wireless Technology End User: Manufacturing, Automotive, Aerospace, Robotics Application: Industrial Automation, Process Control, HVAC Systems, Material Handling |
| Companies Covered | Siemens, Rockwell Automation, Honeywell, Schneider Electric, Emerson Electric, Pepperl+Fuchs, Bihl+Wiedemann, IFM Electronic, Phoenix Contact, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Actuator Sensor Interface Market Emerging Trajectories
Deterministic networking protocols are collapsing the historical separation between machine control traffic and enterprise data systems, forcing interface hardware to simultaneously handle microsecond-cycle motion commands and cloud-bound analytics streams.
Single-pair Ethernet physical layers are hybridizing power delivery and 10 Mbps data transmission over unshielded twisted pair cabling originally deployed for analog sensors. Automotive paint shops in Stuttgart and Wolfsburg are adopting these SPE interfaces to eliminate separate 24V power homeruns while maintaining SIL 3 safety integrity for robotic actuator zones. The technology is hybridizing installation cost structures by reducing copper mass per axis by approximately sixty percent compared to traditional four-wire fieldbus plus power configurations.
China's MIIT dual carbon mandates are tightening energy-efficiency labeling requirements for industrial motor systems above 0.75 kW, directly affecting variable-frequency drive and servo actuator procurement specifications in Jiangsu and Guangdong manufacturing clusters. Domestic equipment suppliers must now submit third-party test reports documenting standby power consumption and regenerative energy recovery capabilities. The regulation is compressing demand toward integrated motor-drive-actuator packages with embedded power measurement rather than separate controller and actuator sourcing.
Asset-as-a-service contracting is restructuring capital equipment procurement in North American food and beverage processing, with OEMs retaining ownership of automated packaging lines and charging per-unit output fees. This model transfers interface module reliability risk from plant operators to equipment builders, who now specify extended-temperature-rated components and predictive maintenance telemetry as standard rather than optional features. The shift is most visible in Wisconsin and Pennsylvania dairy processing cooperatives where seasonal volume volatility makes fixed automation capex difficult to justify.
Global Actuator Sensor Interface Market Segmentation
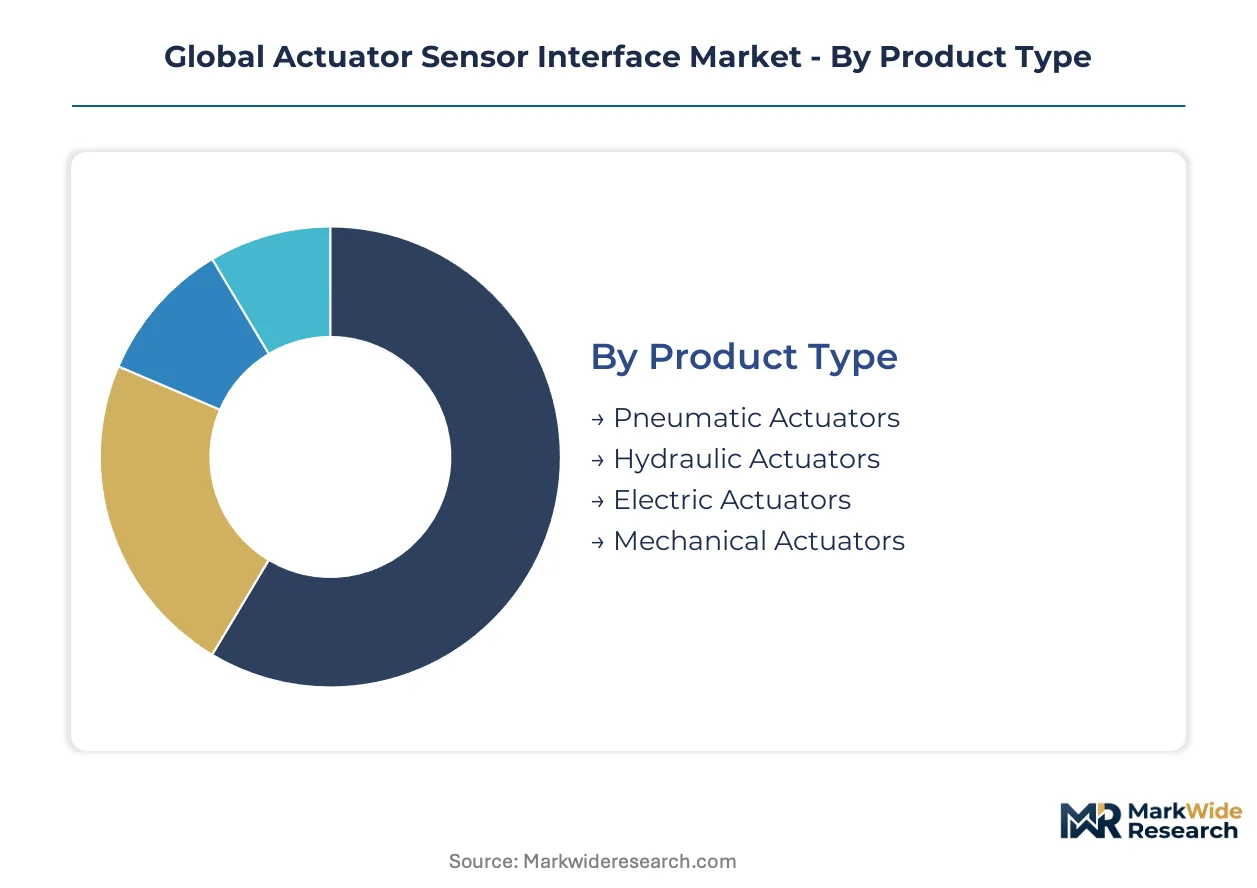
Segmentation in the actuator sensor interface market reveals how distinct technical requirements across actuation principles and communication protocols create divergent margin structures and aftermarket service opportunities. Understanding these boundaries helps suppliers calibrate R&D investment and field service deployment.
Product Type:
After-sales service intensity varies sharply across actuation technologies, with electric and pneumatic systems demanding fundamentally different maintenance cadences and spare parts strategies.
- Electric Actuators:Brushless DC and servo motor architectures with integrated position encoders require precision calibration services and bearing replacement programs. Demand concentrates in German automotive battery plants and Chinese electronics assembly where cleanroom compatibility and regenerative energy recovery are mandatory under MIIT efficiency labeling rules.
- Pneumatic Actuators:Cylinder-piston designs operating on compressed air deliver high force density but leak detection and seal refurbishment dominate lifecycle costs. Food processing clusters in Wisconsin and Pennsylvania retain substantial installed base despite EU F-Gas Regulation pressure to convert toward electric alternatives.
- Hydraulic Actuators:Fluid power systems with servo valves for heavy-load positioning.
- Mechanical Actuators:Screw-jack and cam mechanisms for simple linear motion without external power.
Electric actuators hold the largest share; momentum sits with servo-integrated variants climbing the fastest as factories phase out pneumatic distribution infrastructure.
Technology:
Cost tier differentiation separates legacy fieldbus installations from premium Ethernet-native architectures in greenfield smart factory deployments.
- Digital Technology:Microprocessor-based interfaces with diagnostic feedback and parameter configuration via software. German process industries and US automotive OEMs specify these modules for predictive maintenance integration with asset performance management platforms.
- Fieldbus Technology:PROFIBUS-DP and DeviceNet protocols retain substantial brownfield presence where controller replacement economics delay migration. Chemical plants in Louisiana and Texas face 14-18 month IEC 60079-11 recertification timelines that gate interface upgrades in hazardous areas.
- Analog Technology:4-20mA current loops and voltage signaling for basic position feedback.
- Wireless Technology:ISA100.11a and WirelessHART for mobile equipment and remote monitoring.
Fieldbus technology retains the largest installed base; digital architectures are expanding most quickly through EtherNet/IP and PROFINET convergence.
End User:
Application maturity shapes procurement sophistication, with robotics and aerospace demanding certified reliability while manufacturing segments prioritize cost-per-axis economics.
- Manufacturing:Discrete automation across metal fabrication, packaging, and assembly lines with high axis counts and standardized interface specifications. Chinese Jiangsu and Guangdong clusters drive volume under dual carbon mandates for equipment above 0.75 kW.
- Automotive:EV battery gigafactories in Stuttgart, Wolfsburg, and Nevada require cleanroom-compatible modules with integrated power diagnostics and SIL 3 safety integrity for robotic weld and paint zones.
- Aerospace:Flight control surface actuation and landing gear systems with DO-178C software certification requirements.
- Robotics:Collaborative and industrial robot joints demanding precise torque and position feedback.
Manufacturing commands the largest share; automotive applications are gaining share fastest as battery plant construction accelerates across Germany, China, and the United States.
Application:
Customer type segmentation separates project-based process control procurement from recurring HVAC and material handling replacement cycles.
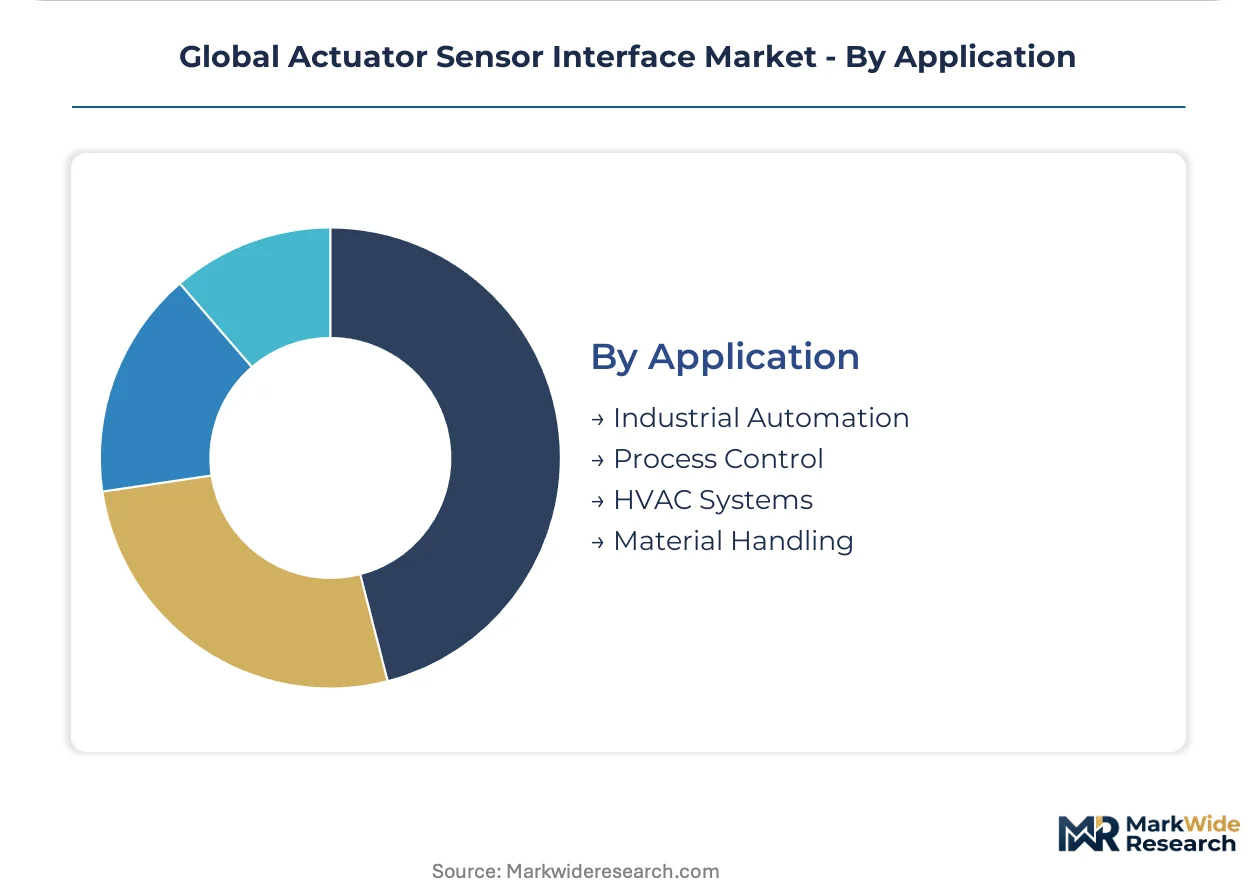
- Industrial Automation:Machine tool servo systems and robotic workcells with deterministic motion control. German automotive suppliers specify single-pair Ethernet interfaces to reduce copper mass by approximately sixty percent versus traditional four-wire configurations.
- Process Control:Oil, gas, and chemical valve automation with intrinsic safety requirements. North Sea and Gulf of Mexico installations drive demand for Pepperl+Fuchs hazardous-area certified interfaces where IEC 60079-11 entity parameters are non-negotiable.
- HVAC Systems:Damper and valve actuation for commercial building climate control with BACnet integration.
- Material Handling:Conveyor sorting and automated storage retrieval systems in distribution centers.
Industrial automation holds the largest share; process control is climbing the fastest as F-Gas Regulation accelerates electric actuator conversion in European industrial cooling systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation suppliers export integrated sensor-actuator modules to automotive battery plants in China and the United States, establishing the dominant trade-flow corridor for high-precision interface hardware.
United States
EV battery gigafactories in Nevada and Texas demand cleanroom-compatible actuator sensor interfaces with SIL 3 safety ratings for robotic weld zones. The EPA and OSHA jointly enforce emissions monitoring and machine safety standards that mandate redundant feedback channels. Wisconsin and Pennsylvania dairy processing cooperatives specify predictive maintenance telemetry as standard features under asset-as-a-service contracting models.
Germany
Automotive paint shops in Stuttgart and Wolfsburg adopt single-pair Ethernet interfaces to reduce copper mass by sixty percent versus traditional four-wire configurations. The EU F-Gas Regulation accelerates conversion from pneumatic valve trains to electric actuators requiring precision position feedback. Bavarian process industries specify integrated motor-drive-actuator packages with embedded power measurement to satisfy EU Green Deal decarbonization mandates.
China
Jiangsu and Guangdong manufacturing clusters drive volume demand for equipment above 0.75 kW under MIIT dual carbon labeling requirements. Domestic suppliers must submit third-party test reports documenting standby power consumption and regenerative energy recovery capabilities. Shanghai and Shenzhen battery plants import German-engineered interface modules for cleanroom robotic assembly lines.
India
The PLI scheme for industrial automation equipment attracts module assembly investments that localize sensor-actuator interface supply for South Asian process industries. Maharashtra and Gujarat chemical plants face 14-18 month IEC 60079-11 recertification timelines that gate hazardous-area interface upgrades. Bangalore and Chennai electronics assembly clusters specify digital interfaces with predictive maintenance integration.
Global Actuator Sensor Interface Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Siemens and Rockwell Automation anchor integrated automation platforms through controller-interface bundles that lock in replacement cycles. Three archetypes dominate: diversified industrial conglomerates with end-to-end portfolios, hazardous-area certification specialists, and component suppliers focused on discrete interface modules. Competitive moves concentrate on strategic partnerships for cybersecurity certification and geographic expansion through localized assembly investments.
Within the diversified industrial tier, Siemens and Rockwell Automation exemplify channel-controlling strategies. Pepperl+Fuchs occupies a position as the hazardous-area certification specialist, anchoring oil and gas applications where IEC 60079-11 entity parameters are mandatory. These three companies represent the dominant competitive archetypes: platform-integrated conglomerates, safety-certification specialists, and component-scale suppliers.
| Leading Market Players |
|---|
| Siemens |
| Rockwell Automation |
| Honeywell |
| Schneider Electric |
| Emerson Electric |
| Pepperl+Fuchs |
| Bihl+Wiedemann |
| IFM Electronic |
| Phoenix Contact |
| Others |
Supply Flow & Price Mechanics
Semiconductor input volatility for industrial Ethernet PHY chips and isolated DC-DC converters compresses both pricing tier spreads and supply chain configuration in the actuator sensor interface market. Buyers face allocation-driven cost premiums on digital-native modules while legacy fieldbus alternatives retain price stability through mature sourcing channels.
Pricing Analysis
Ethernet-native interface modules command 40-60% premiums over legacy fieldbus equivalents as factories prioritize deterministic networking convergence. Three-tier pricing structure across premium, standard, and economy levels separates SIL 3 safety-certified variants from basic position feedback modules and unbranded commodity interfaces. Cost compression in standard-tier products is intensifying because automotive and consumer electronics demand diverts semiconductor capacity from industrial allocations. Small-to-mid-sized process plants in India and Southeast Asia exhibit highest price sensitivity, while German automotive OEMs prioritize certification grade over unit cost.
Supply Chain Analysis
Contract manufacturing for interface modules concentrates in Germany, China, and Mexico where Siemens, Rockwell, and Pepperl+Fuchs maintain captive assembly or tightly controlled EMS partnerships. Supply draws from dedicated industrial Ethernet PHY silicon from Texas and Taiwan, isolated magnetic components from Japan, and precision position encoders from Switzerland. Single-source vulnerability around IEC 60079-11 certified hazardous-area components creates 14-18 month approval bottlenecks that gate oil and gas project commissioning. Distribution runs through direct OEM channel partnerships for large automotive and process industry accounts, with industrial distributors handling fragmented manufacturing segment demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EtherNet/IP and PROFINET ecosystem convergence is collapsing the traditional separation between controller hardware and interface modules, creating platform-lock economics that favor incumbents with integrated automation portfolios.
For Market Incumbents: Pre-empt emerging cybersecurity certification requirements by embedding IEC 62443-4-2 secure boot capabilities into next-generation interface modules before regulatory mandates harden procurement specifications. Consolidate position in automotive battery manufacturing by acquiring single-pair Ethernet interface specialists in Stuttgart and Wolfsburg clusters. Vertical integration into industrial Ethernet PHY sourcing reduces exposure to automotive demand diversion. For New Entrants and Emerging Players: Mid-market food processing cooperatives in Wisconsin and Pennsylvania represent the most penetrable entry point, where asset-as-a-service contracting transfers reliability risk to OEMs and creates demand for predictive maintenance-enabled interfaces at lower price points than German automotive specifications. Target India's PLI scheme beneficiaries with localized assembly partnerships for South Asian chemical and electronics manufacturing clusters. Lead with cybersecurity certification services as a recurring revenue wedge rather than hardware margin capture. For Investors and Strategic Acquirers: IEC 62443 cybersecurity standard adoption reshapes the acquisition landscape by elevating component-level secure boot and encrypted firmware update capabilities above pure hardware scale. Long-term viability centers on interface module suppliers with embedded software differentiation and recurring service attach rates rather than transactional hardware volume. Watch for MIIT dual carbon enforcement intensity in Jiangsu and Guangdong as the signal indicating whether Chinese domestic suppliers achieve technical parity with German-engineered modules.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | IEC 62443-4-2 compliance opens recurring revenue streams in critical infrastructure sectors. |
| Single-Pair Ethernet Interface Development | SPE adoption in Stuttgart automotive paint shops reduces copper mass by sixty percent per axis. |
| Localized Assembly Partnership | India PLI scheme localization captures South Asian process industry demand growth. |
| Predictive Maintenance Telemetry Integration | Asset-as-a-service contracting in Wisconsin dairy processing mandates diagnostic-enabled modules. |
| Hazardous-Area Certification Expansion | IEC 60079-11 entity parameter coverage secures North Sea and Gulf of Mexico oil and gas positions. |
Methodological Framework
A spread of perspectives from plant engineers at German automotive battery facilities, procurement leads at Chinese electronics assembly clusters, hazardous-area certification specialists at Pepperl+Fuchs, and aftermarket service directors at Rockwell Automation converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC filings from Siemens and Emerson, EU F-Gas Regulation implementation reports, and MIIT dual carbon labeling documentation. Bottom-up segmentation modeling triangulated against top-down industrial automation capex forecasts.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with electric actuator conversion rates in European process industries and EtherNet/IP port shipments serving as primary demand indicators. Segmentation dimensions included actuation principle, communication protocol generation, end-use industry maturity, and regional regulatory cluster. CAGRs derived from slope-consensus methodology across multiple scenario assumptions. Industry-specific inputs incorporated IEC 60079-11 recertification timeline data and automotive battery plant construction pipelines.
Practitioners should monitor semiconductor allocation shifts for industrial Ethernet PHY chips and IEC 62443 certification timeline acceleration for early signals requiring forecast revision. Quarterly review of MIIT enforcement intensity, EU F-Gas Regulation implementation pace, and automotive battery plant commissioning schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Gimbal Market
Sensors and Controls
Position Sensor Market
Sensors and Controls
RET Controller Market
Sensors and Controls
Global Digital Electronic Thermometers Market
Sensors and Controls
Inductive and LVDT Sensors Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
Capacitive Proximity Sensor Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
Asia-Pacific Thermocouple Temperature Sensors Market
Sensors and Controls
North America Wireless Sensors Market
Sensors and Controls
Piezoresistive Pressure Sensor Market
Sensors and Controls
Reservoir Monitoring System Market
Sensors and Controls
Distributed Fiber Optic Sensing Market