
 Radio Frequency Front End Market | 2026-2036
Radio Frequency Front End Market Size, Share, and Industry Trends Forecast 2026-2036
Radio Frequency Front End Market Analytics
RF engineering talent scarcity is collapsing across analog design and millimeter-wave testing, tightening product development cycles for module suppliers. Qualcomm Technologies leverages its modem-to-antenna integration to control premium smartphone sockets. Skyworks Solutions anchors its revenue base through backward integration into SAW and BAW filter fabrication. Murata Manufacturing dominates ceramic filter supply through proprietary material science and scale in Japan-based manufacturing.
Radio Frequency Front End refers to the circuitry between an antenna and the digital baseband processor, comprising power amplifiers, filters, switches, and low-noise amplifiers that condition signals across frequency ranges from sub-1 GHz to mmWave bands above 24 GHz. These components manage linearity, efficiency, and interference rejection in transmit and receive chains for cellular, Wi-Fi, and satellite links. Amplifiers and filters together capture the dominant share of value, with GaN technology penetrating radar and base station applications where power density and thermal performance outweigh cost, while CMOS and SOI processes maintain strong positions in handset switch and LDO integration where silicon economics prevail.
The FCC governs spectrum certification and emission limits in the United States, directly shaping filter bandwidth requirements and power amplifier efficiency targets for devices operating in newly auctioned bands. ETSI and national regulators across Europe enforce RED compliance and specific absorption rate limits, adding testing overhead for multi-band modules. China's MIIT mandates domestic encryption and frequency allocation protocols that influence transceiver architecture for vendors serving its telecom equipment market. Stakeholders must track spectrum auction calendars and material qualification timelines, as GaN-on-SiC substrate availability and ceramic powder supply constraints will determine which technology platforms can scale across defense and commercial deployments.
Market Dynamics
Smartphone OEMs are consolidating RF module procurement around integrated modem-to-antenna solutions, compressing vendor lists and forcing discrete component suppliers to defend socket access through filter fabrication scale and millimeter-wave test capacity.
Growth Catalysts
- 5G Mid-Band Deployment:Carrier aggregation requirements across C-band and 3.45 GHz are expanding module complexity and filter count per device.
- GaN-on-SiC Substrate Availability:Defense radar and base station applications are pulling high-power density amplifiers into volume production.
- South Korea Infrastructure Targets:Government spectrum allocation timelines and Samsung's device ecosystem are concentrating component demand in Seoul's procurement corridors.
Market Restraints
- Ceramic Powder Supply Constraints:Proprietary dielectric materials for BAW and ceramic filters face limited qualified suppliers in Japan-based manufacturing clusters.
- Millimeter-Wave Test Capacity:Anechoic chamber availability and calibration equipment lead times are extending qualification cycles for 28 GHz and 39 GHz modules.
- REACH Material Qualification:European chemical substance restrictions are forcing reformulation of packaging compounds and solder materials.
Strategic Opportunities
- India PLI Scheme:Domestic handset production incentives are creating captive demand for locally assembled RF subsystems.
- Satellite-to-Device Links:L-band and S-band front ends for direct-to-smartphone connectivity represent unpenetrated socket categories.
- AI-Driven Antenna Tuning:Machine learning algorithms for real-time impedance matching are converging with RF switch control logic.
Industry Challenges
- Analog Design Talent Scarcity:Experienced RFIC engineers for power amplifier linearity optimization are exiting the workforce faster than university programs replenish supply.
- Multi-Band Certification Overhead:FCC, ETSI, and MIIT emission testing for 15+ cellular bands per device is compressing product launch windows.
- Legacy 4G Inventory Absorption:Module suppliers must manage end-of-life transitions while supporting carrier maintenance commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radio Frequency Front End Market |
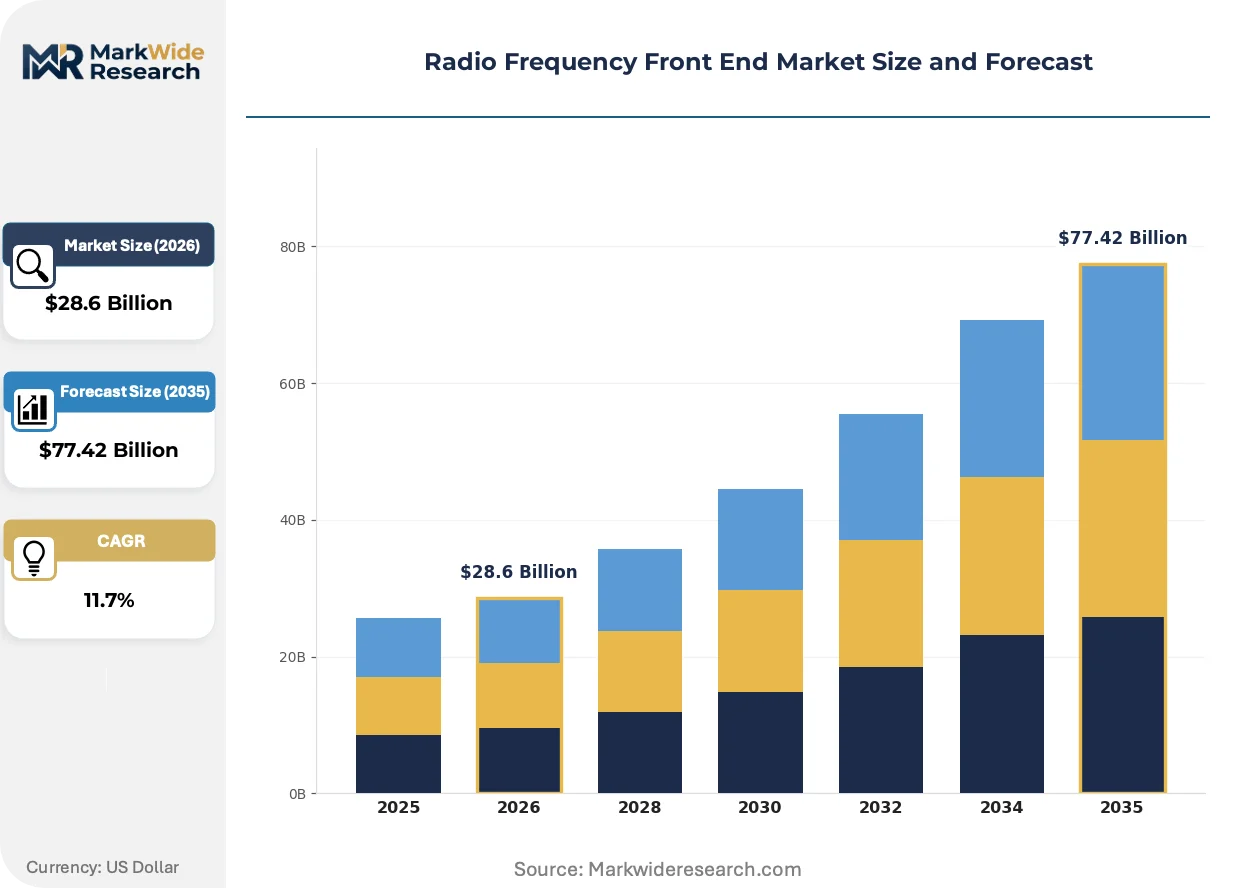
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $77.42 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amplifiers, Filters, Mixers, Transceivers Technology: GaN, LDMOS, GaAs, CMOS End User: Telecom, Aerospace, Automotive, Consumer Electronics Application: Communication Systems, Satellite, Radar, Test Equipment |
| Companies Covered | Qorvo, NXP Semiconductors, Qualcomm Technologies, Analog Devices, Infineon Technologies, Broadcom, Murata Manufacturing, TDK Corporation, Skyworks Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radio Frequency Front End Market Evolving Landscape
Integration architectures are collapsing discrete component counts while new spectrum allocations force filter bandwidth and power amplifier efficiency targets higher. Material platforms and test methodologies are shifting to match these structural demands.
BAW-SMR (Bulk Acoustic Wave Solidly Mounted Resonator) technology is supplanting traditional SAW filters in sub-6 GHz 5G paths where steep roll-off and temperature stability matter. Smartphone OEMs in the premium tier have accelerated adoption, with module suppliers now prioritizing BAW wafer capacity in their foundry commitments. This transition is compressing gross margins for SAW-dominant vendors while rewarding those with in-house BAW fabrication.
ETSI's Radio Equipment Directive (RED) cybersecurity mandates are imposing firmware documentation and vulnerability disclosure requirements on RF modules with software-defined tuning. European national regulators are enforcing these provisions through notified body assessments, adding six to twelve weeks to type approval timelines. Vendors serving EU-bound device shipments are reconfiguring quality systems to capture software bill-of-materials traceability.
Consolidated sourcing contracts are displacing multi-vendor RF module procurement as smartphone OEMs reduce supplier management overhead. Tier-one handset manufacturers now negotiate directly with integrated platform providers for complete transmit-receive chains, squeezing discrete filter and switch specialists into secondary socket opportunities. This concentration is most visible in South Korea, where Samsung's vertical integration preferences have reshaped component vendor rankings.
Radio Frequency Front End Market Segmentation
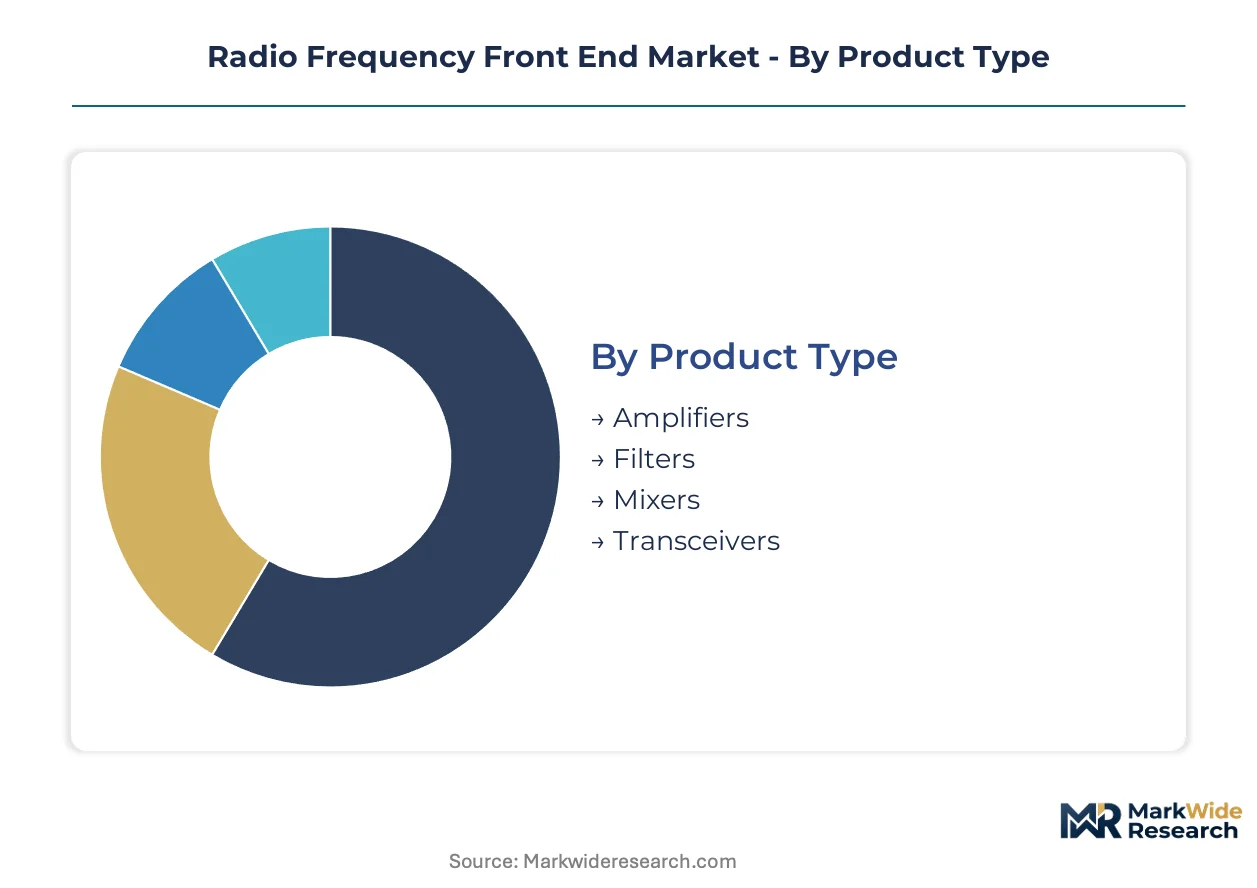
RF front end segmentation reveals distinct margin architectures across product categories, with integrated module suppliers capturing value through filter fabrication scale while discrete component vendors defend position via millimeter-wave test capacity. Technology choices and end-use applications create divergent profitability profiles that reshape competitive positioning.
Product Type:
Margin pools concentrate in filter and amplifier categories where material science differentiation and thermal performance specifications erect barriers to commoditization.
- Amplifiers:Power amplifiers and low-noise amplifiers condition signal strength across transmit and receive chains. GaN-on-SiC devices command premium positioning in base station and defense radar sockets where power density requirements dominate procurement criteria. South Korea's 5G infrastructure buildout is absorbing disproportionate volumes of high-linearity amplifiers for C-band macro deployments.
- Filters:SAW, BAW-SMR, and ceramic filters reject interference and shape channel bandwidth. BAW technology is displacing legacy SAW in sub-6 GHz 5G paths where temperature stability and steep roll-off characteristics determine socket access. Murata Manufacturing's proprietary dielectric materials anchor supply concentration in Japan-based fabrication clusters.
- Mixers:Frequency translation components enable signal conversion between intermediate and radio frequencies. CMOS process integration is collapsing discrete mixer counts into transceiver SoCs for handset applications.
- Transceivers:Integrated transmit-receive chains combine modulation, demodulation, and baseband interface functions. Modem-to-antenna platforms from Qualcomm Technologies are consolidating procurement around complete RF subsystems.
Filters hold installed capacity. Amplifiers are rotating up the share rankings.
Technology:
Process platform selection determines addressable market scope, with compound semiconductors defending premium infrastructure sockets while silicon economics capture handset volume.
- GaN:Gallium nitride on silicon carbide substrates delivers power density and thermal performance for radar and base station amplifiers. Defense procurement and 5G macro deployment are pulling GaN into volume production despite substrate cost premiums. FCC spectrum reallocation for C-band and 3.45 GHz is forcing power amplifier redesigns that favor GaN efficiency characteristics.
- LDMOS:Laterally diffused metal oxide semiconductor maintains cost-positioned share in cellular infrastructure below 4 GHz. Legacy base station installed base sustains demand despite GaN encroachment at higher frequencies.
- GaAs:Gallium arsenide pHEMT and HBT processes dominate handset power amplifiers where linearity and efficiency requirements intersect with moderate power levels. Skyworks Solutions anchors revenue through in-house GaAs fabrication.
- CMOS:Complementary metal oxide semiconductor enables switch, LNA, and control logic integration at silicon economics. SOI variants are displacing compound semiconductors in sub-6 GHz switch applications where insertion loss specifications have relaxed.
GaAs holds installed capacity. GaN is rotating up the share rankings.
End User:
Customer concentration patterns concentrate procurement leverage, with smartphone OEMs consolidating vendor lists around integrated platform providers.
- Telecom:Base station and network infrastructure procurement drives filter count and power amplifier efficiency requirements. Carrier aggregation across C-band and 3.45 GHz is expanding module complexity per macro site.
- Aerospace:Defense radar and electronic warfare applications demand GaN power density and temperature resilience. Export control classifications constrain supplier eligibility for classified programs.
- Automotive:V2X connectivity and satellite positioning are creating RF content expansion in telematics modules. REACH material qualification is forcing packaging compound reformulation for EU-bound vehicle shipments.
- Consumer Electronics:Smartphone OEMs in the 5G mid-band segment are expanding procurement of integrated RF modules. Samsung's device ecosystem in South Korea is concentrating component demand through vertical integration preferences.
Telecom holds installed capacity. Consumer Electronics is rotating up the share rankings.
Application:
Use-case diversification is creating unpenetrated socket categories while traditional communication systems absorb mature technology platforms.
- Communication Systems:Cellular base stations, handsets, and fixed wireless access terminals consume dominant filter and amplifier volumes. ETSI RED cybersecurity mandates are imposing firmware documentation requirements on software-defined tuning modules.
- Satellite:L-band and S-band front ends for direct-to-smartphone links represent emerging demand. Space-qualified component screening extends qualification cycles versus commercial equivalents.
- Radar:Defense and automotive applications pull GaN amplifiers into volume production where range resolution and clutter rejection specifications dominate. FCC emission limits shape filter bandwidth requirements for civilian radar.
- Test Equipment:Anechoic chamber availability and calibration equipment lead times are extending qualification cycles for 28 GHz and 39 GHz module validation. Millimeter-wave test capacity scarcity is tightening product development timelines.
Communication Systems holds installed capacity. Satellite is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. South Korea absorbs premium integrated modules for Samsung's device ecosystem. The United States prioritizes GaN amplifiers for defense radar and C-band infrastructure. China scales CMOS-based switch arrays for domestic handset production.
South Korea
Samsung Electronics and its supplier network drive concentrated demand for BAW-SMR filters and millimeter-wave modules. The Ministry of Science and ICT accelerates 28 GHz spectrum allocation for urban 5G densification. Seoul's Pangyo Techno Valley hosts RFIC design centers where Qualcomm and domestic vendors co-develop modem-to-antenna platforms.
United States
Defense procurement and FCC spectrum reallocation for C-band macro sites pull high-linearity GaN amplifiers into volume production. The FCC emission limits and NTIA spectrum coordination rules reshape filter bandwidth specifications for newly auctioned bands. Boston's Route 128 corridor anchors GaN-on-SiC substrate qualification labs serving radar and electronic warfare programs.
China
Domestic handset OEMs expand captive CMOS switch and LNA production for cost-optimized 5G mid-band devices. MIIT mandates domestic encryption protocols and frequency allocation standards that influence transceiver architecture for telecom equipment. Shenzhen's Pearl River Delta manufacturing clusters concentrate ceramic filter assembly for export-bound consumer electronics.
Japan
Murata Manufacturing and TDK Corporation leverage proprietary dielectric materials to dominate ceramic filter supply for premium smartphone sockets. METI's semiconductor strategy targets domestic BAW wafer capacity expansion amid substrate supply constraints. Kyoto-Osaka industrial corridors maintain specialized powder metallurgy facilities qualified for aerospace and automotive RF components.
Germany
Automotive OEMs integrate V2X and satellite positioning modules into telematics systems for EU-bound vehicle shipments. ECHA REACH restrictions force reformulation of packaging compounds and solder materials in RF subassemblies. Munich-Stuttgart engineering corridors host RF test houses specializing in ETSI RED cybersecurity certification for software-defined tuning modules.
Radio Frequency Front End Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in RF front end supply. Qualcomm Technologies and Broadcom anchor the premium tier through modem-to-antenna platform control, while Murata Manufacturing and TDK Corporation defend filter-centric positions through material science differentiation. The competitive arena splits between integration architects pursuing complete RF subsystem dominance and component specialists deepening captive fabrication of SAW, BAW, and ceramic resonators. Consolidation pressures intensify as smartphone OEMs reduce vendor counts, forcing discrete suppliers into secondary socket opportunities or acquisition targets.
Within the integrated platform tier, Qualcomm Technologies exemplifies the modem-to-antenna convergence strategy that premium smartphone OEMs now demand. Murata Manufacturing occupies a position anchored in proprietary ceramic dielectric materials and Japan-based fabrication scale. Skyworks Solutions represents the GaAs fabrication specialist archetype, defending handset power amplifier sockets through in-house wafer production. Qorvo and NXP Semiconductors sit within the diversified semiconductor conglomerate category, balancing RF front end exposure against broader analog and mixed-signal portfolios.
| Leading Market Players |
|---|
| Qorvo |
| NXP Semiconductors |
| Qualcomm Technologies |
| Analog Devices |
| Infineon Technologies |
| Broadcom |
| Murata Manufacturing |
| TDK Corporation |
| Skyworks Solutions |
| Others |
Value Network & Pricing Analysis
BAW-SMR filter substitution for legacy SAW technology is redrawing procurement geography toward Japan-based fabrication clusters while compressing gross margins for SAW-dominant vendors unable to secure dielectric material supply. This input transition simultaneously elevates pricing power for Murata Manufacturing and TDK Corporation while forcing smartphone OEMs into long-term offtake commitments for BAW wafer capacity.
Pricing Analysis
Long-term offtake contracts dominate premium BAW filter procurement, with Samsung and Apple locking multi-year supply agreements that insulate tier-one suppliers from spot market volatility. Price differentiation separates GaN-on-SiC amplifiers for defense radar from CMOS switch arrays for cost-optimized handsets, with certification grade for FCC C-band emission compliance commanding additional premiums. Cost compression in mid-tier handset modules is intensifying because Chinese OEMs are consolidating around integrated modem-to-antenna platforms. Discrete component suppliers face the steepest price sensitivity, while integrated platform providers maintain pricing leverage through captive filter fabrication.
Supply Chain Analysis
Strategic stockpiling of ceramic powder precursors distinguishes Japan-based filter suppliers from competitors exposed to Murata Manufacturing's proprietary dielectric material allocations. Supply concentration centers on Japan for BAW and ceramic filters, South Korea for GaAs handset amplifiers, and the United States for GaN-on-SiC defense components. Raw material dependencies include silicon carbide substrates for high-power amplifiers, proprietary dielectric ceramics for resonators, and high-purity gallium for pHEMT fabrication. Single-source vulnerability in qualified ceramic powder suppliers creates supply chain risk. Distribution runs through consolidated direct procurement contracts from smartphone OEMs to integrated platform providers, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon-on-insulator switch technology presents a substitution threat that GaAs power amplifier incumbents must navigate through performance differentiation and thermal efficiency gains. Defense radar and satellite-to-device applications offer structural demand buffers against handset commoditization.
For Market Incumbents: Secure captive BAW wafer capacity through foundry partnerships or in-house fabrication investments to defend socket access as Samsung and Apple consolidate vendor lists. Deepen GaN-on-SiC substrate qualification relationships with defense procurement programs to anchor revenue outside consumer electronics volatility. Prioritize millimeter-wave test chamber capacity expansion to compress qualification cycles for 28 GHz module launches.
For New Entrants and Emerging Players: FCC C-band certification fast-track programs offer entry pathways for filter specialists lacking legacy telecom relationships. Target India's PLI scheme for domestic handset assembly, where local content requirements create demand for RF subsystem providers without established Samsung supply chain presence. Pursue satellite-to-device L-band front end sockets as the most penetrable unclaimed category, leveraging partnerships with emerging direct-to-smartphone constellation operators.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed GaAs fabrication specialists seeking exit liquidity as CMOS displacement accelerates in sub-6 GHz switches. Five-to-ten year viability favors vendors with backward integration into SAW or BAW filter production rather than fabless amplifier designers exposed to foundry margin capture. Watch GaN-on-SiC substrate supply expansion timelines as the inflection indicator for defense and infrastructure amplifier margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| BAW Wafer Capacity Expansion | Murata Manufacturing's proprietary dielectric materials anchor supply concentration in Japan-based fabrication clusters. |
| GaN-on-SiC Substrate Qualification | Defense radar procurement pulls high-power density amplifiers into volume production despite substrate cost premiums. |
| Millimeter-Wave Test Chamber Investment | Anechoic chamber scarcity extends qualification cycles for 28 GHz and 39 GHz module validation. |
| India PLI Scheme Localization | Domestic handset production incentives create captive demand for locally assembled RF subsystems. |
| Satellite-to-Device Front End Development | L-band and S-band connectivity represents unpenetrated socket categories for direct-to-smartphone links. |
Research Methodology
A spread of perspectives from RFIC design engineers, smartphone procurement directors, foundry operations managers, and defense program officers converged on the working assumptions for technology transition timelines and socket consolidation patterns. Primary interview insights combined with secondary validation from FCC spectrum auction records, ETSI RED regulatory filings, SEC 10-K disclosures from listed component suppliers, and customs trade data for GaN substrate imports. Bottom-up module shipment estimates triangulated against top-down smartphone production forecasts.
Segmentation dimensions modeled include product type across amplifiers, filters, and integrated transceivers; technology platform spanning GaN, GaAs, CMOS, and SOI processes; end user categories from consumer electronics through aerospace; and application segments covering communication systems, radar, and satellite links. CAGRs derived from fitted growth curves calibrated to historical shipment data and announced capacity expansion timelines. Forecast inputs incorporated carrier aggregation requirements for C-band and 3.45 GHz deployment, plus MIIT domestic encryption mandates shaping China-bound transceiver architecture.
Underlying assumptions cover sustained 5G mid-band infrastructure investment, ceramic powder supply availability, and millimeter-wave spectrum allocation timelines, with deviation risk concentrated in GaN-on-SiC substrate qualification delays and REACH material reformulation compliance costs. Revision becomes warranted when FCC or ETSI regulatory thresholds for emission limits or cybersecurity mandates cross implementation thresholds that reshape module design requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Frequency Synthesizer Market
RF Components
Global Ceramic Dielectric Filters Market
RF Components
RF Power Amplifiers Market
RF Components
Embedded Antenna Systems Market
RF Components
Small Signal Mosfets Market
RF Components
RF Interconnect Market
RF Components
RF Power Detector Market
RF Components
Monolithic Microwave Integrated Circuit (MMIC) Market
RF Components
Digital Radio Frequency Memory Market
RF Components
RF Duplexer Market
RF Components
EMI Microwave Absorber Market
RF Components
Smartphone RF Power Amplifier Market
RF Components
High-Volume RF Front-End Module Test Systems Market
RF Components
RFID Antenna Market
RF Components
Harness-Level EMI and Shielding Component Systems Market
RF Components
RF Passive Component Market