
 Flat Antenna Market | 2026-2036
Flat Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Flat Antenna Market Analysis
Defense buyer consolidation around integrated satellite communications platforms is realigning procurement priorities for flat antenna suppliers. Kymeta Corporation leverages liquid crystal metasurface technology to dominate mobile maritime and land-mobile segments. ThinKom Solutions specializes in VICTS array architectures that sustain its position in airborne connectivity for government and commercial aviation. L3Harris Technologies anchors its presence through ruggedized military-grade flat panels designed for contested electromagnetic environments.
A flat antenna is a low-profile radiating element typically constructed from printed circuit board substrates, metamaterial layers, or liquid crystal matrices that transmits and receives electromagnetic signals without mechanical steering mechanisms, operating across frequencies from L-band to Ka-band with beam steering achieved through electronic phase control. The device serves critical functions in satellite-on-the-move, 5G millimeter-wave infrastructure, and concealed military communications where aerodynamic or aesthetic constraints prohibit traditional dish geometries. Military and satellite end user segments command premium pricing due to environmental qualification requirements and ITAR-controlled supply chains, while commercial aviation and IoT applications represent volume expansion opportunities as manufacturing scales reduce unit costs. Active and smart technology categories capture disproportionate value because software-defined beamforming enables multi-orbit, multi-frequency operation that passive architectures cannot replicate.
FCC spectrum allocations in the United States, ETSI standards in Europe, and ITU coordination frameworks collectively shape product certification timelines and cross-border deployment permissions for flat antenna manufacturers. Military procurement through the U.S. Department of Defense imposes additional MIL-STD environmental and EMI compliance that filters out commercial-only suppliers from defense revenue pools. Stakeholders must monitor Low Earth Orbit constellation deployment schedules and corresponding ground terminal certification requirements to align R&D investments with operational network availability.
Market Dynamics
Defense procurement consolidation around integrated satellite communications platforms is compressing supplier margins while elevating technical qualification barriers. Liquid crystal metasurface architectures are displacing traditional parabolic dishes across mobile terminal segments, forcing component suppliers to requalify for electronically steerable arrays.
Growth Catalysts
- LEO constellation deployment:Commercial space operators are accelerating ground terminal procurement to match orbital asset schedules. This creates pull-through demand for flat panel arrays capable of tracking multiple satellites simultaneously.
- FCC spectrum reallocation:Ka-band licensing reforms in the United States are streamlining certification timelines for mobile satellite terminals. Manufacturers can now bring electronically steerable products to market faster than under previous frameworks.
- NATO interoperability mandates:Allied defense ministries are standardizing on common waveform and antenna specifications for tactical communications. This harmonization reduces fragmentation and expands addressable market for qualified suppliers.
Market Restraints
- Compound semiconductor supply concentration:Gallium nitride substrate production clusters in East Asian foundries. Geographic concentration creates vulnerability for phased array manufacturers dependent on high-electron-mobility transistor components.
- ITAR compliance cost structure:U.S. State Department export controls impose documentation and facility security requirements that add fixed overhead. Commercial-only suppliers cannot amortize these costs across defense contracts.
- Thermal management limitations:Power density in compact flat panel arrays generates heat dissipation challenges that passive cooling cannot resolve. This constrains transmit power in airborne and maritime installations where space is constrained.
Strategic Opportunities
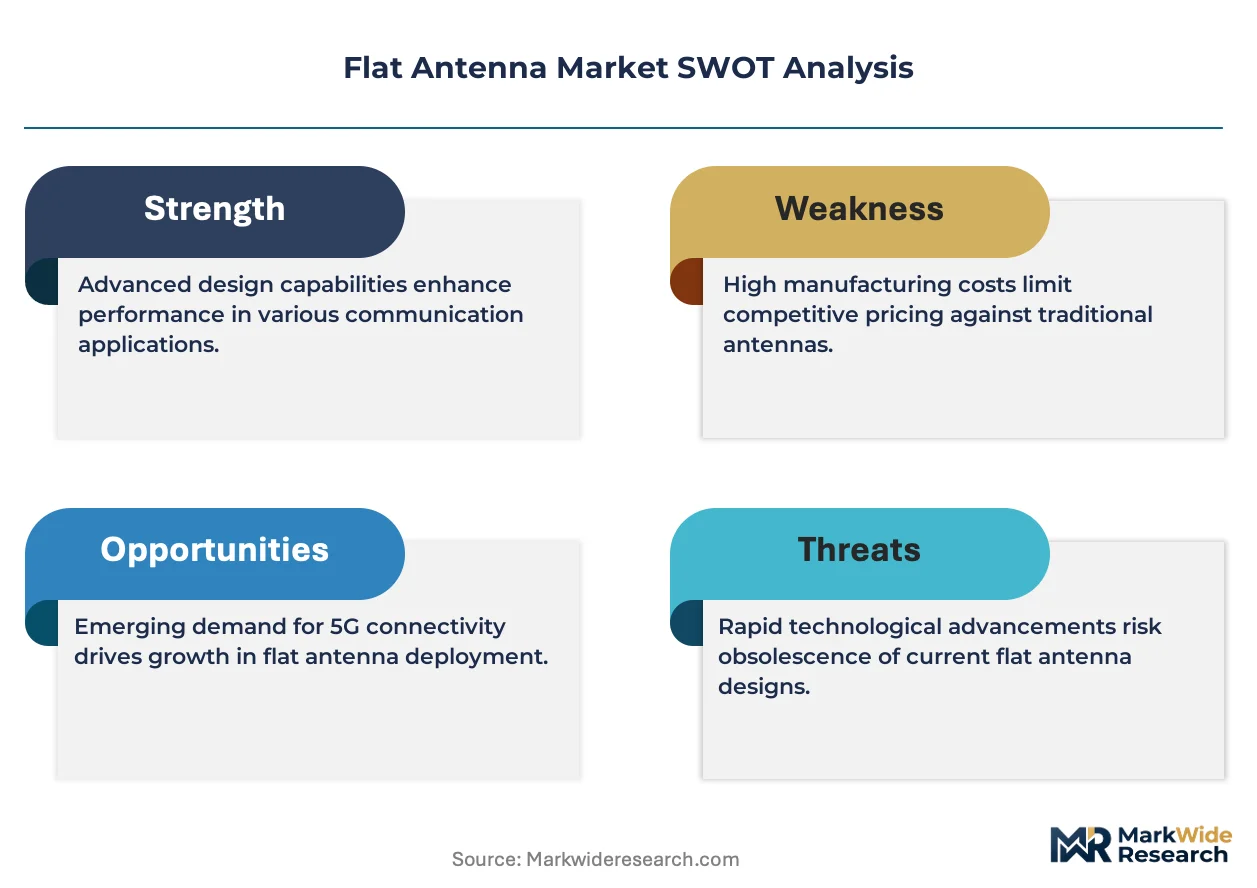
- 5G millimeter-wave infrastructure:Urban small cell deployments require low-profile base station antennas that blend with street furniture. Flat antenna architectures satisfy aesthetic constraints that prohibit traditional macro-cell geometries.
- Connected vehicle mandates:European Commission regulations requiring satellite-based emergency calling systems create embedded antenna demand. Automotive tier-one suppliers are sourcing flat panel solutions for roofline integration.
- Dual-use technology convergence:Commercial aviation connectivity terminals are adapting military-developed liquid crystal beamforming for passenger broadband. This technology transfer opens volume manufacturing pathways previously locked behind defense procurement.
Industry Challenges
- Phased array calibration expertise:The workforce skilled in electromagnetic simulation and near-field testing for electronically steerable antennas remains concentrated at defense contractors. Commercial entrants struggle to recruit and retain this specialized talent.
- Multi-orbit certification complexity:Terminal manufacturers must validate performance across geostationary, medium earth orbit, and low earth orbit constellations with distinct beam dynamics. Each orbital regime requires separate test campaigns that extend development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flat Antenna Market |
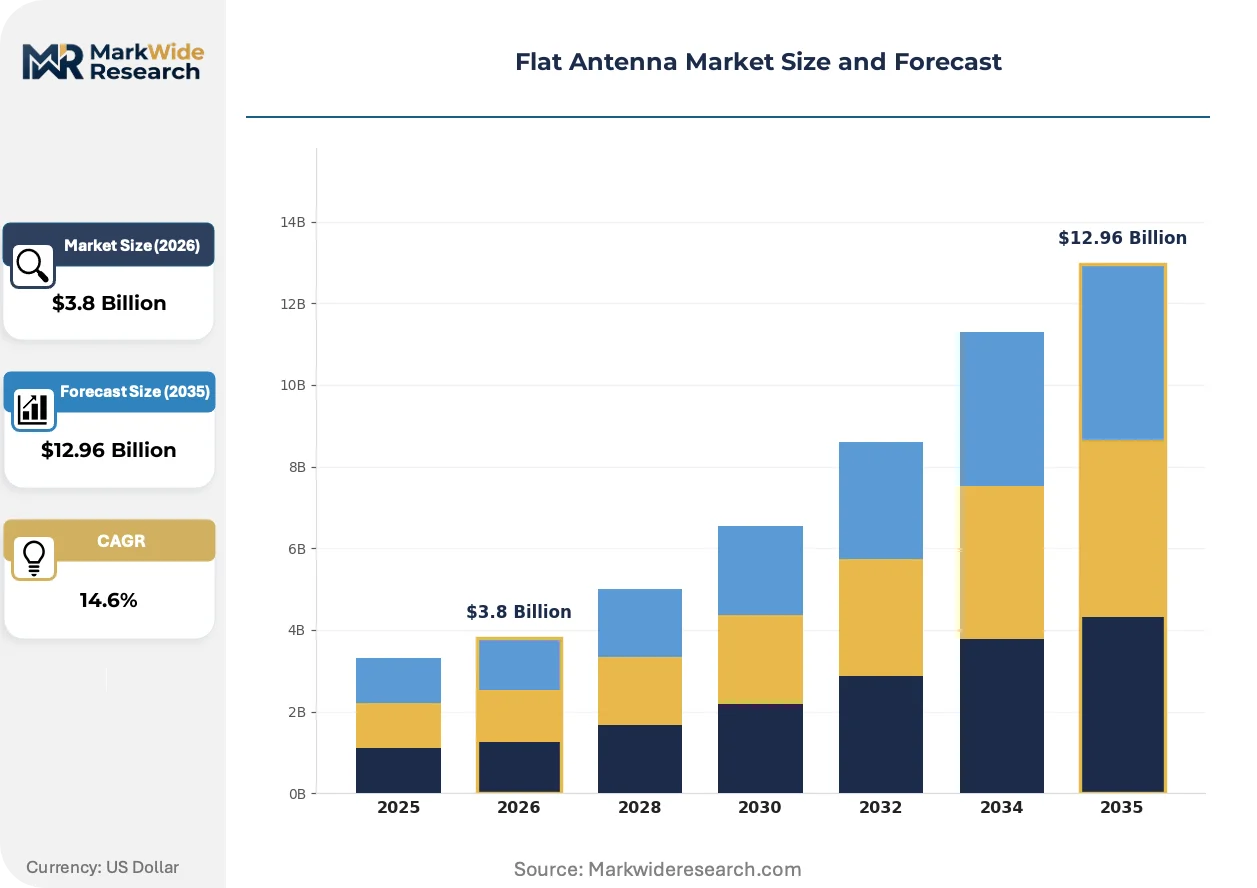
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer, Commercial, Military, Satellite Technology: Active, Passive, Smart, Integrated Form Factor: Flexible, Rigid, Patch, Array End User: Aerospace, Telecommunications, Automotive, IoT |
| Companies Covered | Cobham, Gilat Satellite Networks, Kymeta Corporation, Airbus, L3Harris Technologies, ThinKom Solutions, General Dynamics SATCOM Technologies, TTI Norte, Phasor Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flat Antenna Market Emerging Trajectories
Software-defined beamforming is collapsing hardware differentiation while elevating firmware and algorithmic capabilities as primary competitive battlegrounds. This shift rewards suppliers with vertical integration into semiconductor design and RF signal processing.
Metamaterial substrate technology is modularizing antenna manufacturing by enabling standardized tile architectures that scale across frequency bands and aperture sizes. Defense integrators are adopting these building-block designs to reduce non-recurring engineering for custom programs. The approach compresses development cycles from years to months while maintaining MIL-STD environmental qualification.
ETSI harmonized standards for satellite terminal electromagnetic compatibility are forcing design convergence across European markets. Manufacturers must now engineer for unified test protocols rather than national derogations. This regulatory consolidation favors larger suppliers with dedicated certification engineering teams and disadvantages mid-tier competitors operating on thinner R&D budgets.
Defense agencies are unbundling antenna procurement from integrated platform awards and contracting directly for flat panel subsystems. This disintermediation shifts margin from prime contractors to component specialists while exposing antenna suppliers to direct performance accountability. The United States Department of Defense is leading this structural change through its proliferated low earth orbit terminal acquisition strategy.
Flat Antenna Market Segmentation
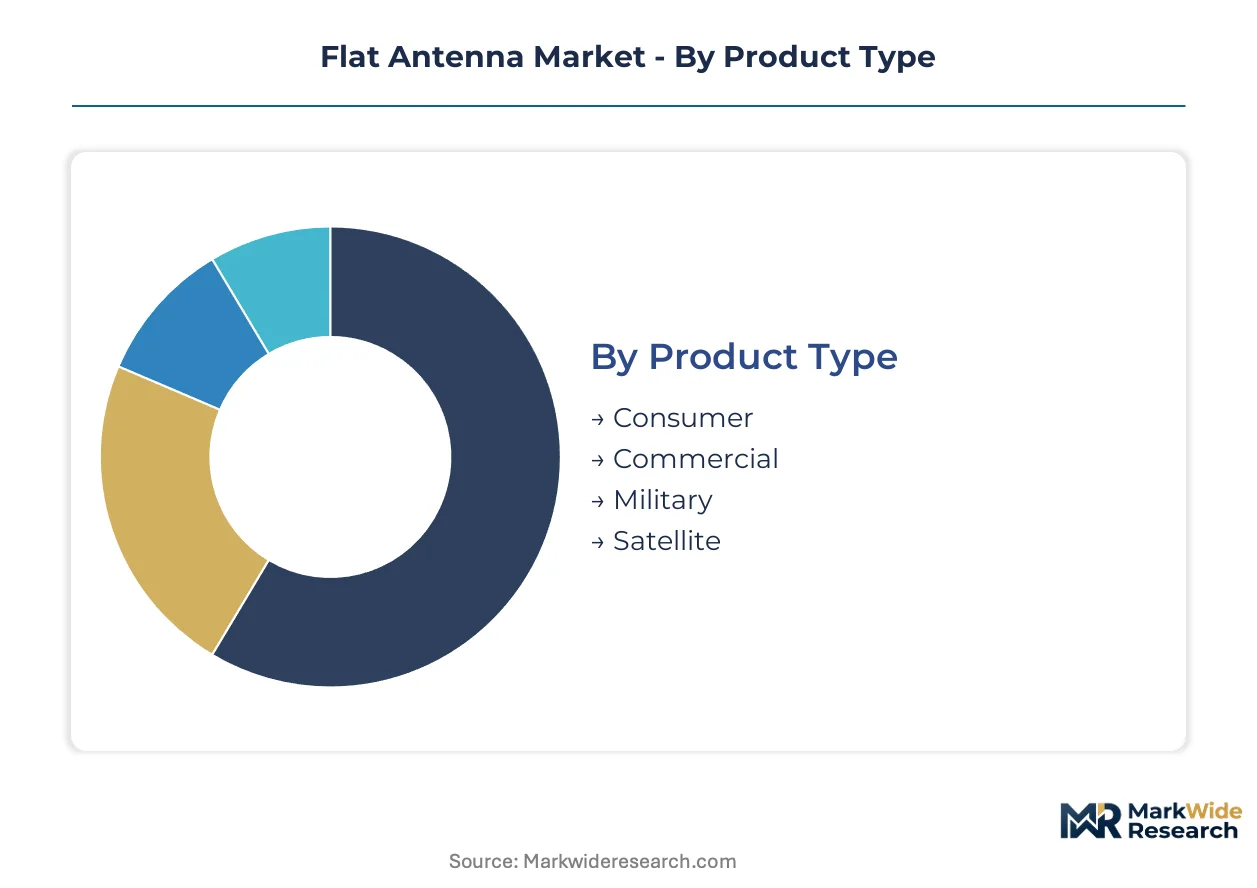
Flat antenna procurement splits sharply across certification regimes. ITAR-controlled military programs demand MIL-STD environmental qualification, while commercial aviation and automotive segments prioritize FCC Part 25 and ETSI EN 302 186 compliance timelines.
Product Type:
Defense procurement imposes ITAR facility security requirements on Military and Satellite segments, while Consumer and Commercial categories navigate FCC and CE marking pathways with lower documentation overhead.
- Military:Ruggedized flat panels built to MIL-STD-810G vibration and MIL-STD-461 EMI specifications. Pentagon procurement through the U.S. Department of Defense favors suppliers with cleared facilities, compressing the qualified vendor pool for tactical communications programs.
- Satellite:Electronically steerable arrays optimized for multi-orbit tracking across geostationary and low earth orbit constellations. Commercial space operators in the United States drive procurement volumes for ground terminals matching Starlink and OneWeb deployment schedules.
- Commercial:Enterprise-grade flat antennas for fixed and mobile satellite services. Maritime and land-mobile integrators source these units for fleet connectivity where parabolic dishes prove impractical.
- Consumer:Compact terminals for residential broadband and recreational vehicle installations. Price sensitivity here limits adoption of active beamforming, favoring simpler mechanically steered or fixed-beam architectures.
Military sits at the top of the volume ranking, with Satellite climbing the fastest.
Technology:
Cost tiers separate passive architectures from active and smart systems, with semiconductor content driving a 3-5x price multiple for electronically steerable variants.
- Active:Phased arrays with gallium nitride power amplifiers and silicon beamforming ICs enabling real-time electronic steering. Defense and commercial aviation platforms demand these systems for satellite-on-the-move connectivity where mechanical repositioning fails.
- Smart:Software-defined beamforming with liquid crystal metasurfaces or MEMS phase shifters. Kymeta Corporation and ThinKom Solutions dominate this segment for maritime and airborne terminals requiring low-profile apertures.
- Passive:Fixed-beam or mechanically steered flat panels without active RF components. Consumer and entry-level commercial applications absorb these units where cost constraints override steering agility requirements.
- Integrated:Antenna-radio combinations with embedded modems and power amplifiers. 5G millimeter-wave small cell deployments favor this form factor for simplified installation and reduced cable losses.
Active commands the revenue concentration, with Smart gaining share fastest on LEO constellation demand.
Form Factor:
Application constraints dictate geometry selection, with aerodynamic and aesthetic requirements pushing adoption toward conformal solutions.
- Array:Tile-based architectures scaling from 16 to 256+ elements for phased beamforming. Defense integrators adopt standardized array tiles to compress non-recurring engineering across custom programs.
- Flexible:Polyimide or liquid crystal polymer substrates enabling conformal mounting on curved surfaces. Automotive roofline integration and unmanned aerial vehicle airframes drive qualification investments for this segment.
- Patch:Single-element or small-array designs for narrowband IoT and asset tracking. Low cost and minimal thickness suit smart city sensor networks and logistics monitoring.
- Rigid:PCB-based flat panels with fixed geometry for ground terminals and infrastructure. Thermal management advantages support higher transmit power in compact footprints.
Array dominates defense and commercial aviation procurement, with Flexible expanding most quickly on automotive connectivity mandates.
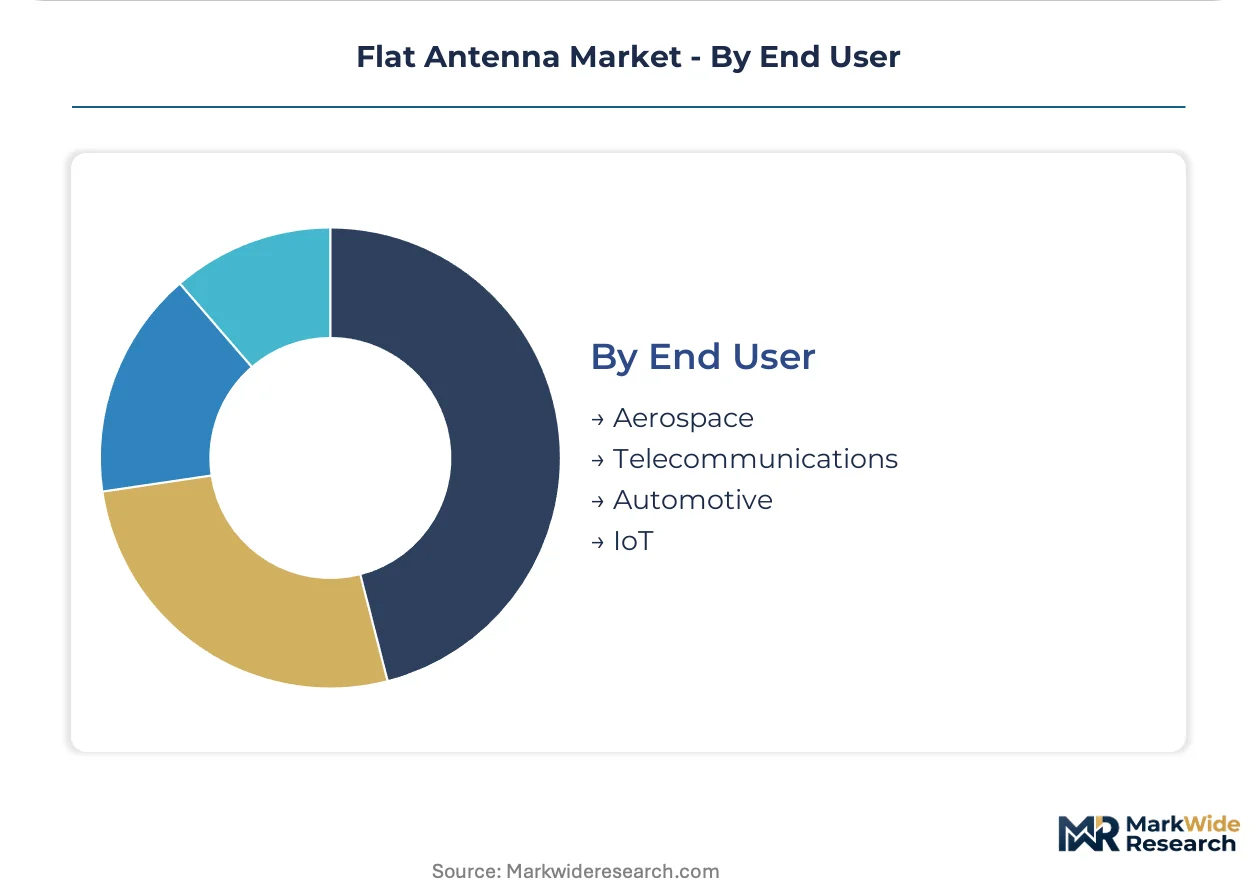
End User:
Customer type determines margin structure, with military and aerospace programs capturing premium pricing against volume-driven automotive and IoT segments.
- Aerospace:Commercial aviation and government aircraft requiring SATCOM terminals for passenger broadband and mission communications. FAA certification timelines for airborne hardware filter out suppliers lacking dedicated aerospace engineering teams.
- Telecommunications:5G base station and backhaul infrastructure. Urban small cell deployments in the United States and Germany favor low-profile flat antennas that blend with street furniture and building facades.
- Automotive:Connected vehicle emergency calling and infotainment systems. European Commission eCall regulations and similar mandates in Japan and South Korea embed flat antennas in roof modules and shark-fin assemblies.
- IoT:Low-power wide-area network endpoints and industrial sensor gateways. Narrowband IoT and LoRa deployments favor compact patch antennas for battery-constrained devices.
Telecommunications leads by unit volume, with Automotive on the steepest expansion trajectory driven by regulatory mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Germany demonstrate contrasting procurement models for flat antenna adoption, with Washington favoring defense-led integration and Berlin emphasizing commercial aviation certification harmonization. Japan and South Korea pursue autonomous satellite terminal capabilities through domestic manufacturing mandates. France anchors European defense procurement through multinational NATO programs.
United States
Pentagon satellite communications modernization and FCC Ka-band spectrum reforms accelerate flat panel array procurement for military and commercial terminals. The FCC streamlined mobile satellite terminal certification timelines under revised Part 25 frameworks. California hosts concentrated liquid crystal metasurface development clusters serving both defense integrators and commercial space operators.
Germany
Automotive emergency calling mandates and 5G millimeter-wave infrastructure deployment drive demand for conformal flat antennas in vehicles and urban small cells. ETSI harmonized electromagnetic compatibility standards enforce unified test protocols across EU member states. Bavaria's aerospace engineering corridor near Munich specializes in airborne terminal qualification for commercial aviation integrators.
Japan
METI satellite connectivity initiatives and maritime broadband expansion programs stimulate procurement of electronically steerable arrays for shipping and island communities. The national regulator promotes domestic manufacturing capabilities through technology development subsidies. Tokyo-Osaka industrial corridor concentrates RF component fabrication for phased array subsystems.
South Korea
Defense self-reliance programs and commercial LEO constellation ground terminal requirements create dual-use demand for compact flat panel architectures. The national spectrum authority coordinates Ka-band licensing reforms aligned with ITU frameworks. Seoul Capital Area hosts defense electronics integrators transitioning parabolic dish production to solid-state phased arrays.
France
NATO tactical communications standardization and national space sovereignty objectives prioritize interoperable flat antenna procurement for allied operations. The national defense procurement agency contracts directly for antenna subsystems under disintermediated acquisition strategies. Toulouse aerospace cluster specializes in satellite terminal integration for both military and commercial aviation platforms.
Flat Antenna Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across segmented certification regimes, creating tiered competitive dynamics. Defense contractors leverage cleared facility infrastructure and ITAR compliance capabilities to capture military procurement pools. Commercial specialists exploit faster certification cycles and volume manufacturing scale in aviation and automotive segments. Consolidation pressures intensify as prime contractors disintermediate antenna procurement and contract directly with subsystem suppliers. Technology licensing agreements proliferate as liquid crystal metasurface and phased array architectures require specialized electromagnetic simulation expertise.
Within the defense electronics tier, L3Harris Technologies and General Dynamics SATCOM Technologies exemplify conglomerate-scale suppliers with cleared manufacturing infrastructure. Kymeta Corporation occupies a specialist position representing liquid crystal metasurface technology commercialization. ThinKom Solutions anchors the commercial aviation segment through VICTS array architecture specialization. These three companies illustrate competitive positioning across divergent qualification pathways.
| Leading Market Players |
|---|
| Cobham |
| Gilat Satellite Networks |
| Kymeta Corporation |
| Airbus |
| L3Harris Technologies |
| ThinKom Solutions |
| General Dynamics SATCOM Technologies |
| TTI Norte |
| Phasor Solutions |
| Others |
Supply Flow & Price Mechanics
Defense procurement consolidation around integrated satellite communications platforms is compressing supplier margins while forcing component manufacturers to absorb ITAR compliance overhead. This buyer-driven pressure cascades through the supply chain as qualified vendors compete for limited program slots, eroding price floors for electronically steerable arrays.
Pricing Analysis
Capacity additions in East Asian foundries are reshaping price floors for gallium nitride power amplifiers and silicon beamforming ICs. Three-tier pricing structure across ITAR-qualified military, commercial aviation, and consumer residential tiers separates segments by certification burden and environmental qualification depth. Cost compression in the consumer tier is intensifying because Starlink terminal subsidies set reference points below active beamforming cost structures. Automotive emergency calling mandates represent the least price-sensitive demand pool due to regulatory compliance deadlines.
Supply Chain Analysis
ITAR facility security requirements and MIL-STD environmental qualification act as gating mechanisms that filter commercial-only suppliers from defense revenue pools. Manufacturing concentrates in the United States, Taiwan, and South Korea, with compound semiconductor fabrication anchored in East Asian foundries. The supply chain draws from gallium nitride substrates, liquid crystal polymer films, and high-frequency laminates as critical inputs. Single-source vulnerability in GaN-on-SiC wafer production creates structural exposure for phased array manufacturers. Distribution runs through defense prime contractors, commercial aviation integrators, and automotive tier-one suppliers in parallel channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in flat antennas rests on software-defined beamforming architectures that collapse hardware differentiation while capturing premium pricing for firmware-enabled multi-orbit capability. Liquid crystal metasurface manufacturing scale-down and automated calibration systems provide the cost-down pathway.
For Market Incumbents: Lock in cleared facility infrastructure and ITAR compliance capabilities as defensive moats against commercial entrants seeking defense revenue. Deepen backward integration into gallium nitride power amplifier design to reduce foundry dependency. Prioritize electromagnetic simulation talent retention against poaching from commercial space operators expanding phased array teams. For New Entrants and Emerging Players: Direct-to-defense-subsystem contracting channels opened by Pentagon disintermediation strategies offer bypass routes around prime contractor gatekeeping. Target commercial maritime and land-mobile segments where Kymeta's liquid crystal metasurface patents face expiration pressure and VICTS array alternatives remain underpenetrated. Lead with software-defined beamforming as a service model to reduce upfront hardware qualification burden. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier phased array calibration specialists possessing electromagnetic simulation expertise concentrated at legacy defense contractors. Long-term viability favors suppliers with dual-use technology portfolios spanning military and commercial aviation certification. Watch LEO constellation ground terminal procurement acceleration as the inflection signal for manufacturing scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Crystal Metasurface Manufacturing Scale-Up | Enables cost parity with parabolic dishes for maritime terminals under FCC Part 25 frameworks. |
| ITAR Facility Security Infrastructure Investment | Qualifies suppliers for Pentagon direct-subsystem contracting outside prime contractor channels. |
| Multi-Orbit Certification Engineering Expansion | Validates performance across Starlink, OneWeb, and geostationary constellations for unified terminals. |
| Automotive Roofline Integration Partnership | Captures European Commission eCall mandate volume through tier-one supplier channel control. |
| Software-Defined Beamforming Platform Launch | Collapses hardware differentiation while elevating firmware as primary competitive battleground. |
Methodological Framework
Multiple input streams — defense procurement database tracking, commercial space operator terminal deployment schedules, and semiconductor foundry capacity disclosures — were reconciled to construct demand and supply estimates. Primary interviews with satellite communications program managers, phased array RF engineers, defense procurement officers, and automotive tier-one antenna sourcing leads were validated against secondary sources including FCC Part 25 filings, ETSI EN 302 186 certification records, Pentagon budget justification documents, and MIL-STD environmental test reports. Bottom-up terminal shipment modeling and top-down addressable market sizing were cross-referenced for convergence.
Data-stream reconciliation across product type, technology architecture, form factor geometry, and end-use application dimensions produced volume and value estimates across the projection horizon. CAGRs were derived from segment-specific growth trajectories weighted by revenue concentration in military and satellite end-use categories. Forecast inputs incorporated LEO constellation deployment schedules, Ka-band licensing reform timelines, and NATO interoperability mandate implementation phases as demand drivers.
The model assumes a particular technology adoption path; alternative pathways for liquid crystal metasurface versus silicon-based phased arrays would alter the outlook for manufacturing scale economics and supplier market share distribution. Forecasts reflect assumptions regarding defense procurement continuity, compound semiconductor supply availability, and regulatory certification harmonization across FCC and ETSI jurisdictions. A model refresh is warranted upon material change in Pentagon proliferated LEO terminal acquisition strategy or gallium nitride substrate supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Asia-Pacific Small Signal Transistor Market
RF Components
Global Ceramic Dielectric Filters Market
RF Components
LTCC Power Dividers Market
RF Components
RFID Tags Market
RF Components
Global RF Plasma Generator Market
RF Components
Multilayer Coupled Inductor Market
RF Components
EMI Microwave Absorber Market
RF Components
RF Filters Market
RF Components
Frequency Synthesizer Market
RF Components
High-Volume RF Front-End Module Test Systems Market
RF Components
Europe Small Signal Transistor Market
RF Components
Phase Shifters Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
High-Frequency RF Evaluation Board Market
RF Components
RFID Antenna Market
RF Components
RF Mixers Market