
 Metamaterial Medium Market | 2026-2036
Metamaterial Medium Market Size, Share, and Industry Trends Forecast 2026-2036
Metamaterial Medium Market Analysis
Aftermarket service revenue for calibration and field reconfiguration of intelligent surfaces is rewriting margin expectations across the value chain. Pivotal Commware leverages its software-defined metamaterial architecture to sustain recurring licensing income from telecom operators. Echodyne anchors the radar subsegment with proprietary electronically scanned arrays that compete directly with conventional phased-array systems for drone detection and automotive safety.
A metamaterial medium comprises artificially engineered structures with subwavelength periodic or quasi-periodic geometries that yield negative permeability, negative permittivity, or tailored anisotropic responses unavailable in naturally occurring compounds. These structures are manufactured through nanofabrication, 3D printing, or precision lithography to manipulate electromagnetic, acoustic, or optical wavefronts for cloaking, super-resolution imaging, or beam steering. Electromagnetic metamaterials command the dominant share due to mature foundry processes for microwave and millimeter-wave devices, while optical metamaterials represent the fastest-expanding category as plasmonic and dielectric resonator designs mature for LiDAR and computational imaging. Acoustic metamaterials occupy a narrower but defensible niche in noise cancellation and seismic isolation, with energy harvesting applications still pre-commercial.
The Federal Communications Commission in the United States and the European Telecommunications Standards Institute shape spectrum-access rules that directly determine which metamaterial-enabled beamforming architectures qualify for commercial deployment. Japan's Ministry of Internal Affairs and Communications and South Korea's Radio Research Agency enforce national 5G/6G roadmaps that privilege domestic metamaterial suppliers through performance-based procurement criteria. Stakeholders must monitor evolving electromagnetic compatibility certification timelines across these jurisdictions, as regulatory lag between laboratory demonstration and type approval now constitutes the primary bottleneck for revenue conversion.
Market Dynamics
Defense procurement acceleration across NATO economies is compressing development cycles for electromagnetic metamaterials, forcing commercial foundries to absorb military-grade tolerances while telecom operators demand simultaneous cost reductions for 5G infrastructure deployment.
Growth Catalysts
- Electromagnetic spectrum reallocation:The Federal Communications Commission's 3.5 GHz and 6 GHz priority access licenses are mandating beam-steering architectures that only metamaterial-enabled surfaces can deliver at mass-market price points.
- Automotive radar mandates:Euro NCAP's 2024 safety protocols require enhanced pedestrian detection ranges that conventional phased arrays cannot achieve without metamaterial lens integration.
- Nanofabrication scaling:Deep-ultraviolet lithography lines in Germany and Japan now process metamaterial unit cells at wafer-scale throughput, collapsing prototype-to-production timelines.
Market Restraints
- Raw material concentration:High-purity gallium arsenide and indium phosphide substrates concentrate among three Japanese suppliers, exposing margins to export control volatility.
- Electromagnetic compatibility certification lag:The European Telecommunications Standards Institute's testing protocols for reconfigurable intelligent surfaces lack harmonized methodologies, delaying type approval by 14-18 months.
- Optical metamaterial yield limits:Plasmonic resonator fabrication at visible wavelengths achieves sub-40% functional yield, constraining LiDAR cost curves.
Strategic Opportunities
- Thermal metamaterial white space:Radiative cooling applications for data centers in Singapore and the United Arab Emirates remain unserved by incumbent suppliers.
- Software-defined surface convergence:Integration of machine learning inference at the edge with metamaterial tuning algorithms opens subscription revenue models for infrastructure operators.
- Acoustic metamaterial retrofit:Seismic isolation systems for existing commercial buildings in Japan represent a replacement market untouched by new-construction specialists.
Industry Challenges
- Multiphysics simulation talent scarcity:Engineers capable of coupling electromagnetic, thermal, and mechanical finite-element analysis command premium compensation that mid-scale foundries cannot sustain.
- Legacy radar integration friction:Defense contractors face software stack incompatibilities when inserting metamaterial apertures into 1980s-era airborne platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metamaterial Medium Market |
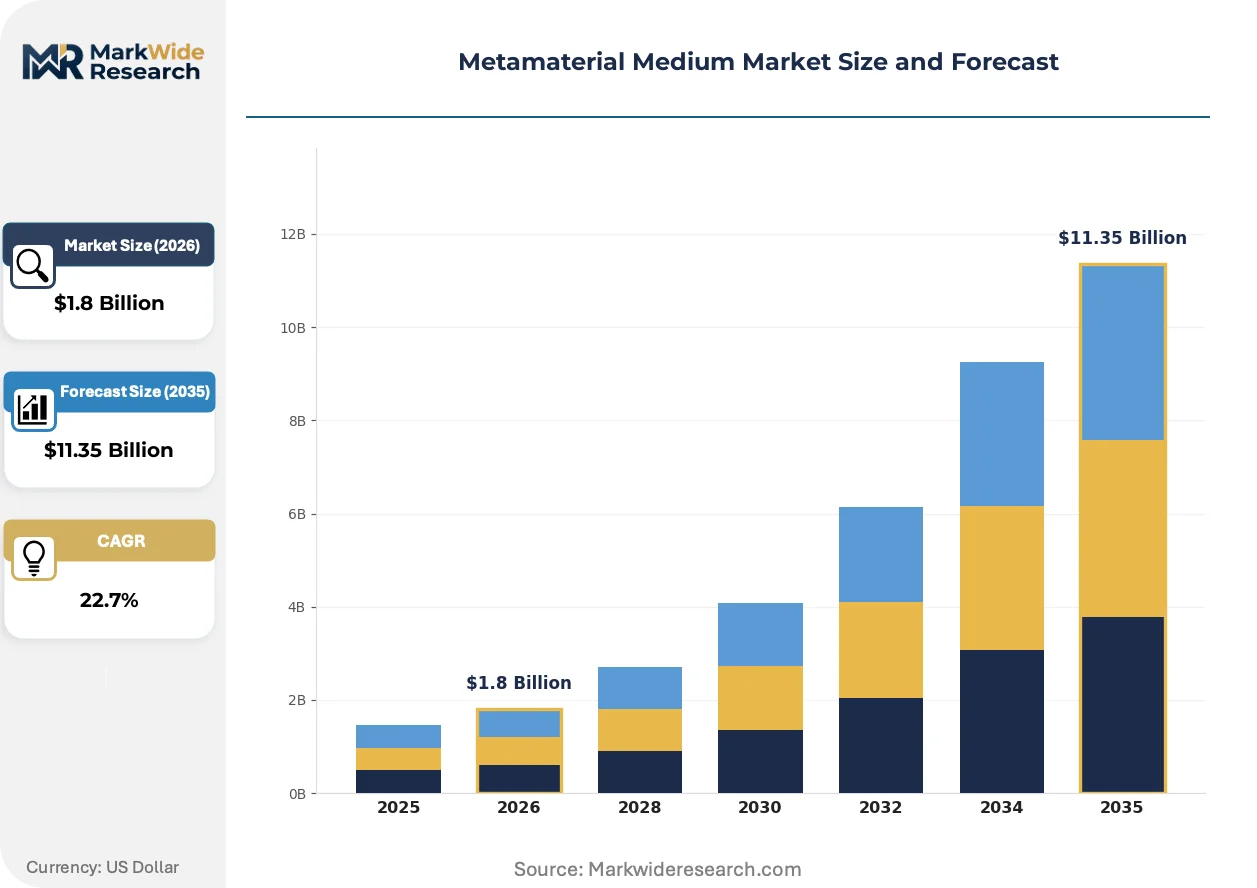
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic Metamaterials, Acoustic Metamaterials, Optical Metamaterials, Mechanical Metamaterials Application: Sensing, Imaging, Communication, Energy Harvesting End User: Aerospace, Automotive, Healthcare, Telecommunications Technology: 3D Printing, Nanofabrication, Layered Manufacturing, Simulation |
| Companies Covered | Pivotal Commware Inc., NKT Photonics A/S, Kymeta Corporation, Multiwave Technologies AG, Fractal Antenna Systems Inc., Echodyne Corporation, TeraView Limited, Lumotive Inc., Meta Materials Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metamaterial Medium Market Emerging Trajectories
Digital twin architectures are virtualizing metamaterial design workflows, collapsing the iteration cycle between electromagnetic simulation and physical validation while regulatory pressure on spectrum efficiency intensifies specification demands.
Reconfigurable intelligent surfaces based on PIN-diode switching matrices are virtualizing passive beamforming, replacing mechanically steered antennas in fixed wireless access deployments. Telecom operators in South Korea and Germany are deploying these at 28 GHz and 39 GHz bands for last-mile fiber extension. The technology is virtualizing capital allocation by converting hardware expenses into software-configurable operational expenditures.
The European Union's F-Gas Regulation is phasing down hydrofluorocarbon-based cooling in data centers, redirecting capital toward radiative metamaterial coatings that reject infrared heat without refrigeration. Hyperscale operators in Ireland and the Netherlands are piloting these surfaces on hyperscale roof structures. This regulatory compression is forcing metamaterial suppliers to accelerate weatherization testing that previously sat outside commercial roadmaps.
Service unbundling is separating metamaterial hardware from calibration and optimization contracts, with infrastructure buyers demanding à-la-carte field reconfiguration rather than bundled maintenance. This pattern concentrates in Japanese and German telecommunications markets where unionized technician workforces resist manufacturer-controlled service models. The shift compresses upfront contract values while extending revenue duration through recurring performance tuning engagements.
Metamaterial Medium Market Segmentation
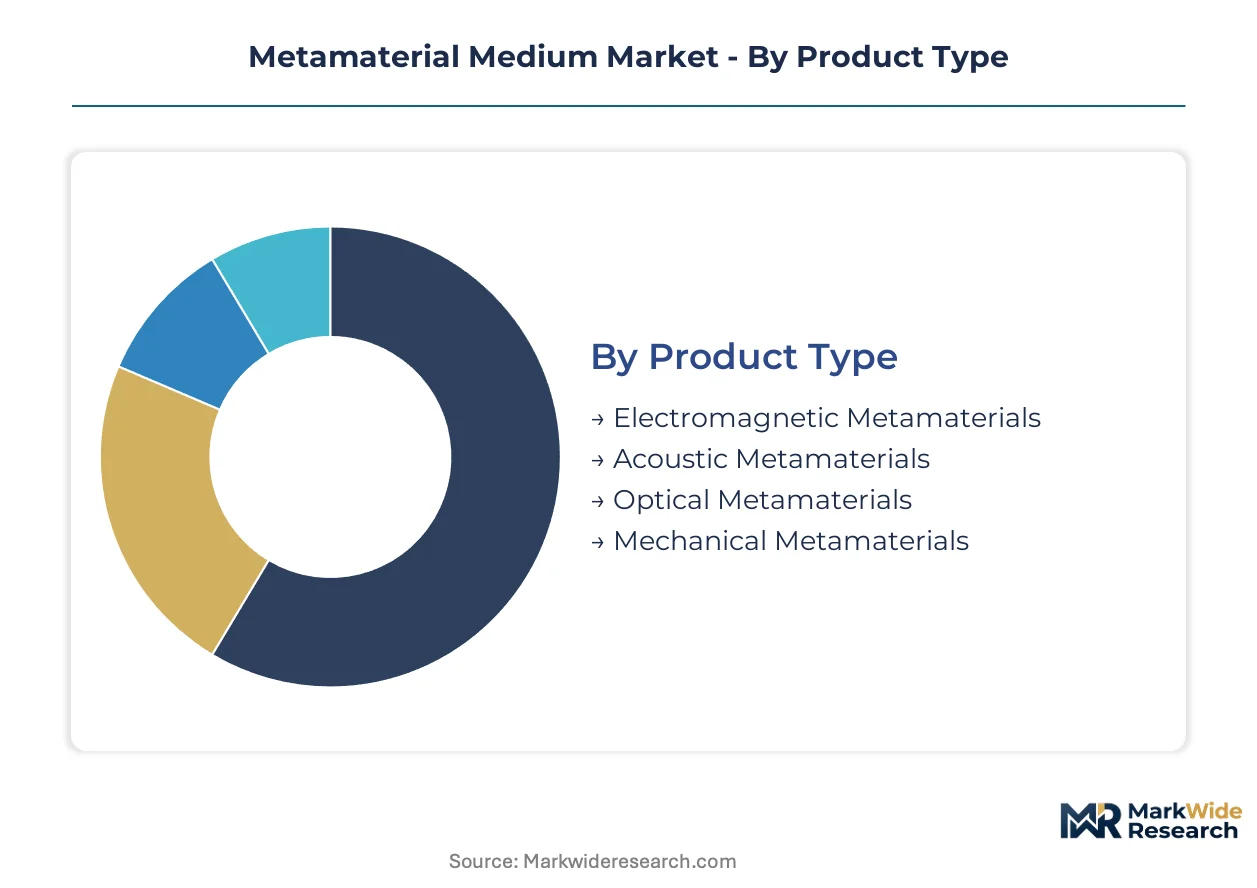
Segmentation in the metamaterial medium market exposes how fabrication physics, end-use performance thresholds, and procurement authority concentrate value differently across the value chain. Technology maturity and regulatory certification timelines fragment competitive positioning in ways that pure material properties cannot predict.
Product Type:
Cost tier stratification across product categories reflects foundry maturity and yield economics rather than intrinsic material complexity.
- Electromagnetic Metamaterials:Microwave and millimeter-wave structures with negative permeability or permittivity fabricated through printed circuit board and semiconductor lithography processes. Defense procurement in the United States and telecommunications infrastructure in Germany absorb volume at price points conventional phased arrays cannot match.
- Optical Metamaterials:Plasmonic and dielectric resonator designs manipulating visible and infrared wavefronts for LiDAR and computational imaging. Automotive safety mandates from Euro NCAP and sensor integration in South Korean manufacturing drive specification intensity despite sub-40% fabrication yields.
- Acoustic Metamaterials:Subwavelength lattice structures for noise cancellation and seismic isolation. Seismic retrofit demand in Japan and industrial noise control in Germany sustain niche positioning.
- Mechanical Metamaterials:Architected cellular solids with negative Poisson's ratio or programmable stiffness. Aerospace weight reduction programs and medical implant customization represent emerging demand pockets.
Electromagnetic metamaterials command the established base. The steepest expansion runs through optical metamaterials.
Application:
Application segmentation tracks how wavefront manipulation translates into monetizable functionality across end-use sectors.
- Sensing:Radar cross-section reduction, chemical detection, and biometric monitoring through resonant frequency shifts. Drone detection systems in the United States and automotive radar in Germany concentrate procurement volume.
- Communication:Beam steering, spectrum filtering, and signal isolation for 5G/6G infrastructure. Reconfigurable intelligent surfaces in South Korea and fixed wireless access in Japan absorb production capacity.
- Imaging:Super-resolution microscopy, computational photography, and medical diagnostics through engineered point-spread functions. LiDAR integration in German automotive manufacturing and ophthalmic devices in Japan drive specification development.
- Energy Harvesting:Thermophotovoltaic emitters and vibration-to-electricity converters. Data center radiative cooling pilots in Ireland and the Netherlands test commercial viability.
Communication applications anchor current revenue. Imaging applications are climbing the fastest as automotive and medical certification pathways mature.
End User:
End user segmentation reveals how procurement authority and technical specification power reshape margin capture across verticals.
- Aerospace:Stealth applications, satellite communications, and unmanned platform radar. Classified programs in the United States and NATO defense procurement compress development cycles while demanding military-grade tolerances.
- Automotive:Advanced driver-assistance systems, LiDAR enclosures, and pedestrian detection radar. Euro NCAP safety protocols and German OEM integration timelines determine qualification requirements.
- Healthcare:Magnetic resonance imaging coils, implantable sensors, and surgical navigation systems. Japan's PMDA and the United States FDA electromagnetic compatibility standards gate market entry.
- Telecommunications:Base station beamforming, reconfigurable intelligent surfaces, and spectrum filtering. South Korea's Radio Research Agency and Germany's Federal Network Agency shape deployment rules.
Telecommunications holds the volume base. Aerospace delivers the steepest margin expansion through dual-use technology transfer.
Technology:
Technology segmentation tracks fabrication methodology and its constraints on scalability, precision, and economic viability.
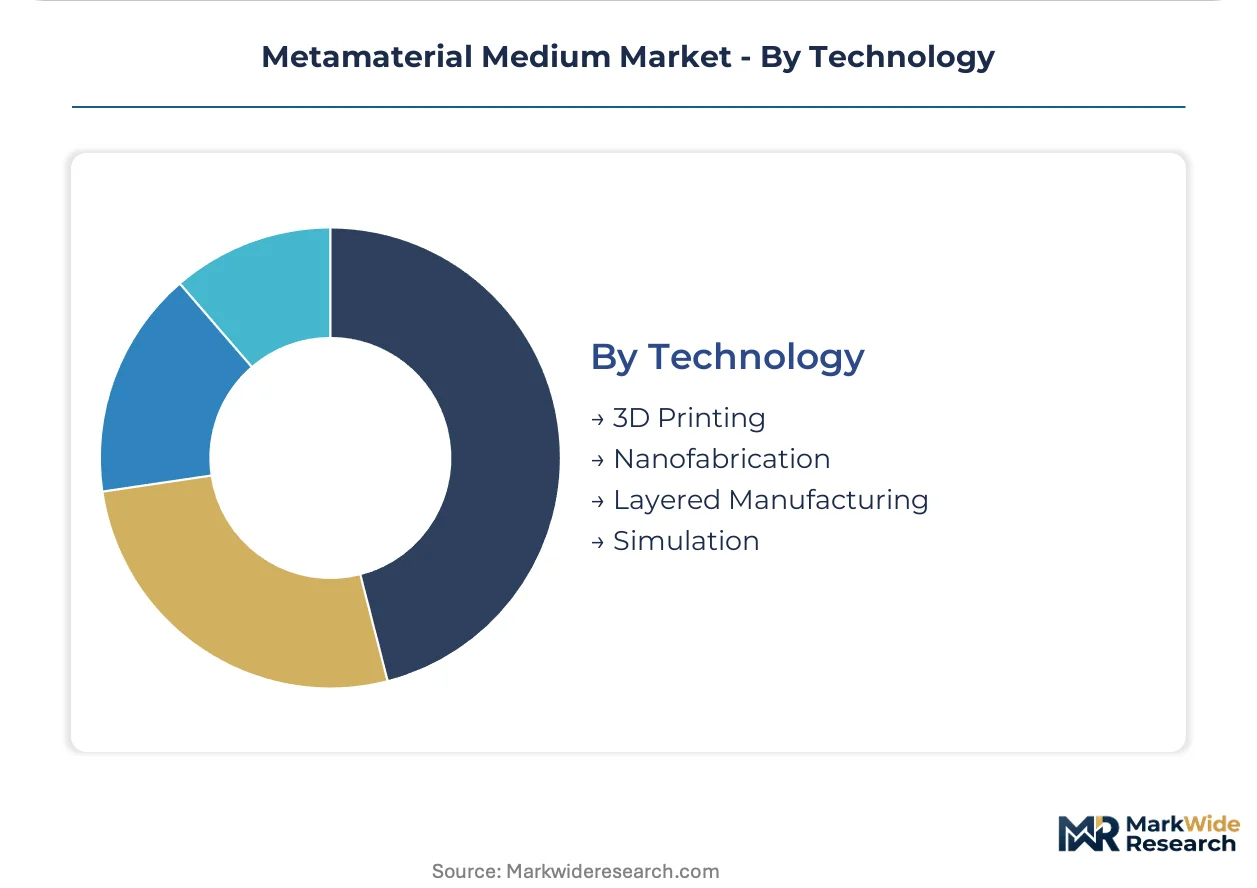
- Nanofabrication:Electron-beam lithography and focused ion beam milling for sub-100nm feature resolution. German deep-ultraviolet lithography lines and Japanese precision equipment suppliers control throughput bottlenecks.
- 3D Printing:Two-photon polymerization and direct laser writing for complex topologies. Prototyping services in the United States and Germany bridge design-to-production gaps.
- Layered Manufacturing:Stacked printed circuit board and thin-film deposition processes for microwave devices. Telecom infrastructure scaling in South Korea and Japan favors this cost structure.
- Simulation:Multiphysics finite-element modeling coupling electromagnetic, thermal, and mechanical domains. Talent scarcity in coupled-field analysis commands premium compensation across all geographies.
Layered manufacturing dominates unit economics. Nanofabrication is gaining share fastest as optical and terahertz applications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom operators in South Korea and Germany absorb volume at premium price points, while defense procurement in the United States tolerates cost escalation for classified electromagnetic applications. Price elasticity varies sharply across end-use verticals.
United States
Defense procurement programs through the Pentagon's Rapid Innovation Fund compress development cycles for electromagnetic metamaterials. The FCC's 3.5 GHz and 6 GHz priority access licenses mandate beam-steering architectures. Boston-area foundries and Seattle-area software-defined surface developers anchor dual-use technology transfer.
Germany
Telecommunications infrastructure upgrades for 5G and 6G spectrum allocation absorb reconfigurable intelligent surfaces at mass-market price points. The Federal Network Agency enforces electromagnetic compatibility certification timelines. Munich and Stuttgart industrial clusters concentrate precision lithography capacity for automotive radar integration.
South Korea
Radio Research Agency roadmaps privilege domestic metamaterial suppliers through performance-based procurement criteria for fixed wireless access deployments. Seoul Capital Area operators deploy PIN-diode switching matrices at 28 GHz and 39 GHz bands. Busan-Ulsan manufacturing corridors process layered manufacturing for microwave devices.
Japan
Ministry of Internal Affairs and Communications 5G/6G policies favor reconfigurable intelligent surface technologies for last-mile fiber extension. PMDA electromagnetic compatibility standards gate healthcare imaging applications. Kanto and Kansai industrial zones concentrate nanofabrication equipment suppliers.
Netherlands
Hyperscale data center operators pilot radiative metamaterial coatings under EU F-Gas Regulation phase-down mandates. Eindhoven deep-ultraviolet lithography lines process metamaterial unit cells at wafer-scale throughput. Randstad logistics corridors distribute thermal metamaterial components for data center cooling retrofits.
Metamaterial Medium Market Vendor Landscape
Defense-anchored specialists and telecom-scaled fabricators split the market along tolerance-for-complexity lines. Consolidation concentrates among electromagnetic metamaterial suppliers with mature foundry partnerships, while optical metamaterial segments fragment across university spinouts. Three archetypes dominate: software-defined surface architects, precision lithography foundries, and dual-use defense contractors. Capacity expansion and strategic technology licensing constitute the primary competitive moves.
Within the software-defined surface tier, Pivotal Commware Inc. and Kymeta Corporation exemplify architecture-first positioning. Echodyne Corporation anchors the radar subsegment among electronically scanned array specialists. These three occupy positions that bridge defense procurement cycles with commercial telecommunications scaling.
| Leading Market Players |
|---|
| Pivotal Commware Inc. |
| NKT Photonics A/S |
| Kymeta Corporation |
| Multiwave Technologies AG |
| Fractal Antenna Systems Inc. |
| Echodyne Corporation |
| TeraView Limited |
| Lumotive Inc. |
| Meta Materials Inc. |
| Others |
Supply Flow & Price Mechanics
Export control volatility on high-purity gallium arsenide and indium phosphide substrates determines both tiered pricing spreads across electromagnetic metamaterial grades and the geographic concentration of foundry partnerships. Buyers face widening cost differentials between Japan-sourced wafers and alternative supply routes as procurement teams absorb military-grade tolerance requirements alongside telecom cost compression mandates.
Pricing Analysis
Aftermarket calibration and field reconfiguration services now drive lifetime value beyond hardware margins. Three-tier pricing structure across defense-qualified, automotive-certified, and commercial-telecom tiers reflects electromagnetic compatibility certification grade and volume scale. Pricing pressure stems from South Korean operators demanding software-configurable operational expenditure models that collapse upfront capital commitments. Automotive OEMs in Germany exhibit lowest price sensitivity due to Euro NCAP safety mandate compliance deadlines, while fixed wireless access providers in Japan negotiate aggressively on unit economics.
Supply Chain Analysis
Upstream feedstock for metamaterial substrates concentrates among Japanese suppliers of compound semiconductor wafers. German deep-ultraviolet lithography lines and South Korean layered manufacturing corridors process unit cells at divergent throughput economics. Raw material dependencies span high-purity gallium arsenide, indium phosphide, and precision photoresist chemistries. Single-source vulnerability on Japanese substrate suppliers exposes margins to export restriction triggers. Distribution runs through defense contractor qualification programs and telecom operator procurement consortiums with divergent certification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from intelligent surface calibration and edge-tuning algorithms is expanding faster than hardware shipment value, repositioning margin capture toward recurring performance contracts.
For Market Incumbents: Pre-empt foundry capacity constraints by securing captive supply agreements with German lithography operators before defense procurement cycles absorb available throughput. Deepen backward integration into precision photoresist formulation to offset Japanese substrate concentration risk. Lock in electromagnetic compatibility certification pipelines with ETSI and FCC to delay challenger market entry by 14-18 months. For New Entrants and Emerging Players: Pursue thermal metamaterial white space in data center radiative cooling applications across Ireland and the Netherlands, where EU F-Gas Regulation phase-down redirects capital toward unproven supplier bases. Target seismic retrofit demand in Japan's commercial building stock through acoustic metamaterial isolation systems untouched by new-construction specialists. Lead with software-defined surface pilots that convert hardware capital into subscription operational expenditure models. For Investors and Strategic Acquirers: FCC 6 GHz priority access license implementation reshapes the acquisition landscape toward beam-steering architecture specialists with proven telecom operator deployments. Long-term viability centers on dual-use technology transfer capability bridging Pentagon Rapid Innovation Fund cycles and commercial infrastructure scaling. Watch ETSI harmonized testing protocol publication as the signal indicating type approval timeline compression and revenue conversion acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Surface Platform Launch | Pivotal Commware's licensing model converts hardware into recurring telecom operator revenue streams. |
| Precision Lithography Capacity Expansion | German foundry investments collapse prototype-to-production timelines for automotive radar integration. |
| Defense-Telecom Dual-Use Certification | Echodyne's electronically scanned arrays bridge Pentagon procurement and commercial drone detection markets. |
| Radiative Cooling Coating Pilot | Netherlands hyperscale operators test thermal metamaterial viability under EU F-Gas regulatory compression. |
| Acoustic Retrofit Channel Partnership | Japanese seismic isolation demand opens replacement market penetration for lattice structure specialists. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FCC spectrum allocation dockets, ETSI technical specifications, and defense procurement contract disclosures. Interviews with reconfigurable intelligent surface deployment engineers, precision lithography foundry managers, telecom infrastructure procurement leads, and electromagnetic compatibility certification specialists informed demand-side validation. Secondary sources include SEC filings from metamaterial developers, Radio Research Agency procurement criteria, and deep-ultraviolet lithography equipment supplier technical documentation. Bottom-up unit economics modeling triangulates against top-down defense and telecommunications capex projections.
Forecast inputs span electromagnetic versus optical versus acoustic product type trajectories, communication versus imaging versus sensing application intensity, and nanofabrication versus layered manufacturing technology adoption curves across the projection horizon. CAGRs derive from segment-level volume build-ups calibrated to national 5G/6G roadmap commitments and Euro NCAP safety protocol phase-ins. Industry-specific inputs include electromagnetic compatibility certification lag distributions and plasmonic resonator yield improvement curves.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or defense budget authorization trajectories would shift the trajectory. Forecasts reflect documented assumptions on spectrum allocation timing and foundry yield maturation. Cross-checking against national telecommunications regulator deployment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
Next Generation Processors Market
Emerging and Next Generation Technologies
Global Nano Batteries Market
Emerging and Next Generation Technologies
Asia Pacific Quantum Computing Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
3D Xpoint Technology Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
Nanoelectronics Market
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Global WI SUN Technology Market
Emerging and Next Generation Technologies
Programmable Semiconductor Technologies Market
Emerging and Next Generation Technologies
Global Smart Window Market
Emerging and Next Generation Technologies
Global Broad Ion Beam Technology Market
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market
Emerging and Next Generation Technologies
Next-Generation Transistors Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market