
 Global Inductors Market | 2026-2036
Global Inductors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inductors Market Foresight
East Asian ferrite production capacity is consolidating as regional suppliers rationalize legacy powder facilities against rising specification thresholds for automotive-grade components. TDK Corporation leverages integrated ferrite material science to sustain premium positioning in power inductor tiers. Murata Manufacturing Co., Ltd. anchors RF inductor supply for 5G base station rollouts across multiple continents. Coilcraft Inc. specializes in ultra-miniature chip inductor geometries that differentiate its catalog in aerospace and medical signal chains.
An inductor is a passive electronic component comprising a conductive coil wound around a magnetic core—typically ferrite, iron powder, or air—that stores energy in a magnetic field when current passes through it, measured in henries with tolerances often specified at ±20% or tighter for precision applications. Its primary commercial purpose centers on filtering, energy storage, and impedance matching in power conversion and radio frequency circuits. Ferrite core inductors dominate volume production due to cost efficiency at frequencies below several megahertz, while surface mount technology formats command the fastest expansion as OEMs eliminate through-hole assembly steps from computing device and consumer electronics lines. Power inductors carry disproportionate margin pools because thermal performance and saturation current ratings determine qualification for electric vehicle inverter modules and server voltage regulator applications.
The EU's RoHS and REACH frameworks restrict hazardous substance content in inductor plating and core binders, compelling reformulation of iron powder core mixtures and solder termination chemistries. China's GB standards and MIIT directives mandate electromagnetic compatibility certification for telecommunications equipment, directly conditioning inductor Q-factor and shielding specifications for domestic 5G infrastructure deployments. Japan's METI energy efficiency regulations for computing devices tighten loss budgets, favoring vendors with advanced ferrite composition laboratories. Stakeholders must monitor divergence between regional electromagnetic compatibility test regimes when qualifying single-SKU designs for multi-jurisdiction shipment.
Market Dynamics
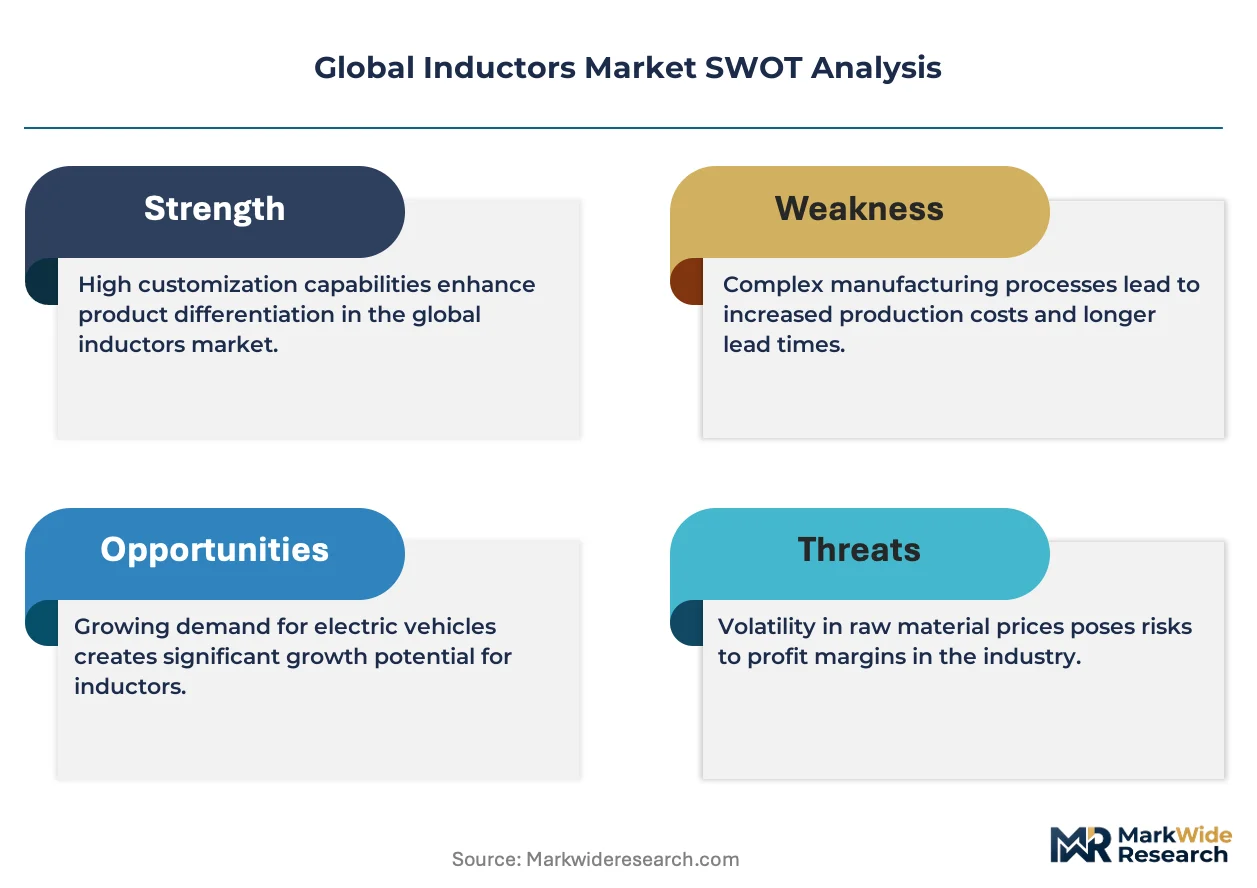
Automotive electrification programs are compressing qualification timelines for high-current power inductors while simultaneously tightening thermal performance thresholds that legacy ferrite formulations cannot satisfy.
Growth Catalysts
- Automotive electrification mandates:Germany's KBA certification requirements and Japan's METI energy efficiency standards are accelerating procurement of high-current inductors for onboard chargers in electric vehicle platforms.
- 5G infrastructure deployment:MIIT electromagnetic compatibility directives in China are conditioning Q-factor specifications for base station RF inductors across domestic telecommunications networks.
- Ferrite material science advances:Low-loss core compositions developed through integrated R&D pipelines are extending saturation current ratings for server voltage regulator modules in hyperscale data centers.
Market Restraints
- Rare earth supply concentration:Processing of specialized ferrite precursors remains concentrated in East Asian refining corridors, exposing procurement schedules to geopolitical friction.
- EU F-Gas Regulation compliance:Core binder reformulation requirements are extending qualification cycles for iron powder inductors destined for European automotive module suppliers.
- Technical performance ceilings:Air-core alternatives face inherent inductance density limitations that prevent displacement of ferrite in sub-megahertz power conversion applications.
Strategic Opportunities
- India telecommunications infrastructure:TRAI spectrum allocation frameworks and BIS certification pathways are opening procurement channels for RF inductor vendors in domestic 5G rollout programs.
- Renewable energy storage integration:Grid-scale battery inverter architectures are creating specification pull for high-ripple-current inductors in power conditioning stages.
- Medical device miniaturization:Ultra-miniature chip inductor geometries are penetrating implantable signal chain applications where footprint constraints previously blocked adoption.
Industry Challenges
- Electromagnetic compatibility test divergence:OEMs must maintain parallel qualification streams for FCC, CE marking, and GB standard regimes, fragmenting single-SKU economics.
- Precision winding automation:Tolerance tightening to ±10% for aerospace-grade components is straining capital equipment upgrade cycles at mid-tier contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inductors Market |
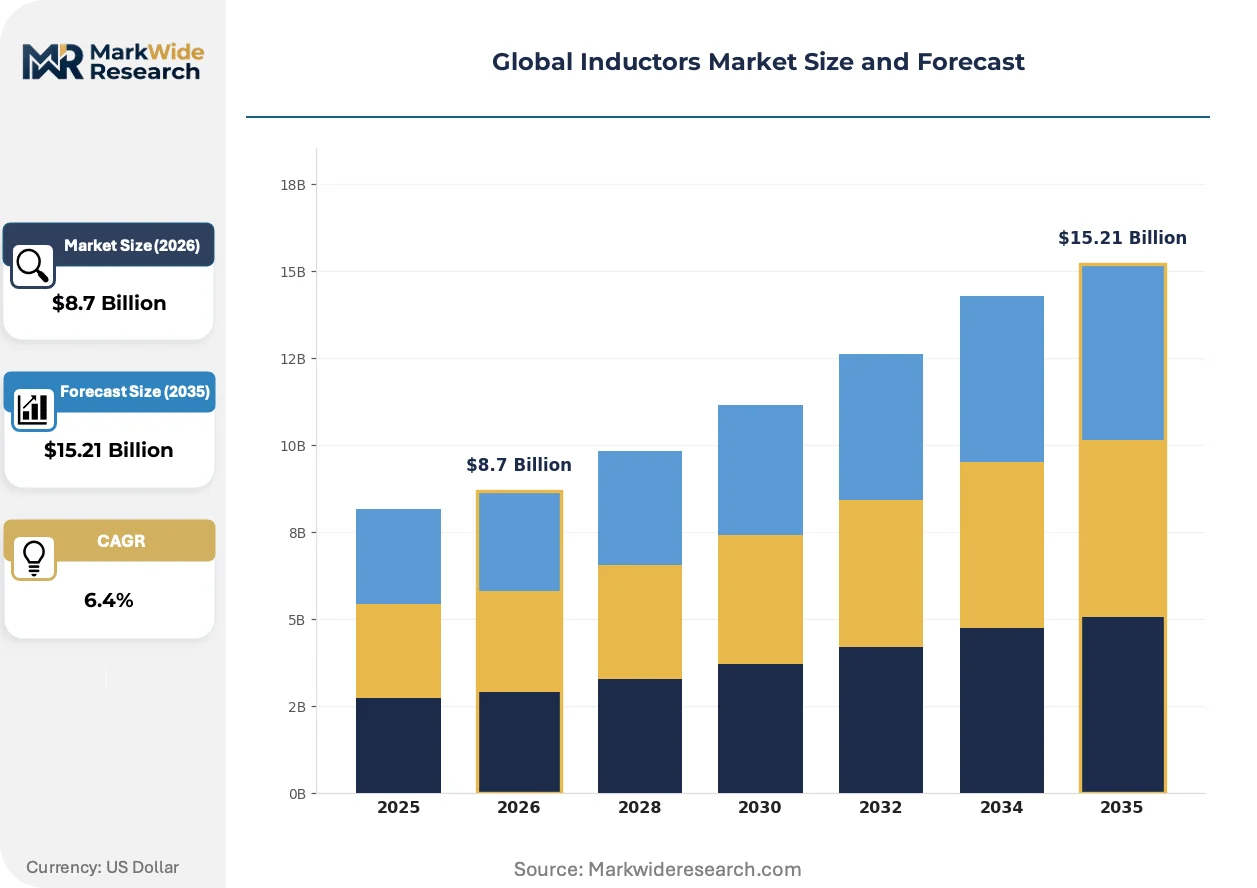
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Inductors, Variable Inductors, Air Core Inductors, Ferrite Core Inductors, Iron Powder Core Inductors Technology: Surface Mount Technology, Through-Hole Technology, High Frequency, Power Inductors, RF Inductors Application: Consumer Electronics, Aerospace, Telecommunications, Defense Equipment, Computing Devices End User: OEMs, Aftermarket Suppliers, Electronic Manufacturing Services, System Integrators |
| Companies Covered | Taiyo Yuden Co., Ltd., Panasonic Corporation, Murata Manufacturing Co., Ltd., Delta Electronics, Coilcraft Inc., TDK Corporation, Sumida Corporation, Chilisin Electronics, Vishay Intertechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inductors Market Shifts & Advancements
Material science convergence with thermal modeling software is compressing the traditional ferrite development cycle while enabling performance optimization for application-specific power inductor tiers.
Integrated composite magnetic cores combining distributed air gaps with optimized ferrite grain structures are rewriting thermal dissipation benchmarks for electric vehicle DC-DC converters. Tier 1 automotive module suppliers in Germany and South Korea are adopting these geometries for 800-volt platform designs. The technology is compressing the performance gap between discrete inductors and planar magnetics in high-density power stages.
REACH substance restrictions on hexavalent chromium plating are forcing termination chemistry reformulations across inductor portfolios bound for European markets. ECHA authorization requirements are extending supplier audit timelines for iron powder core mixtures. Surface mount device manufacturers are responding with tin-bismalt solder alternatives that satisfy RoHS compliance without sacrificing reflow compatibility.
Consolidated procurement frameworks at hyperscale cloud operators are compressing vendor qualification lists to three approved sources per inductor category. Distribution channels are consolidating around authorized distributors with in-house electromagnetic simulation support. This concentration is most visible in North American server motherboard supply chains, where direct OEM engagement is displacing traditional component distributor relationships for power inductor selection.
Global Inductors Market Segmentation
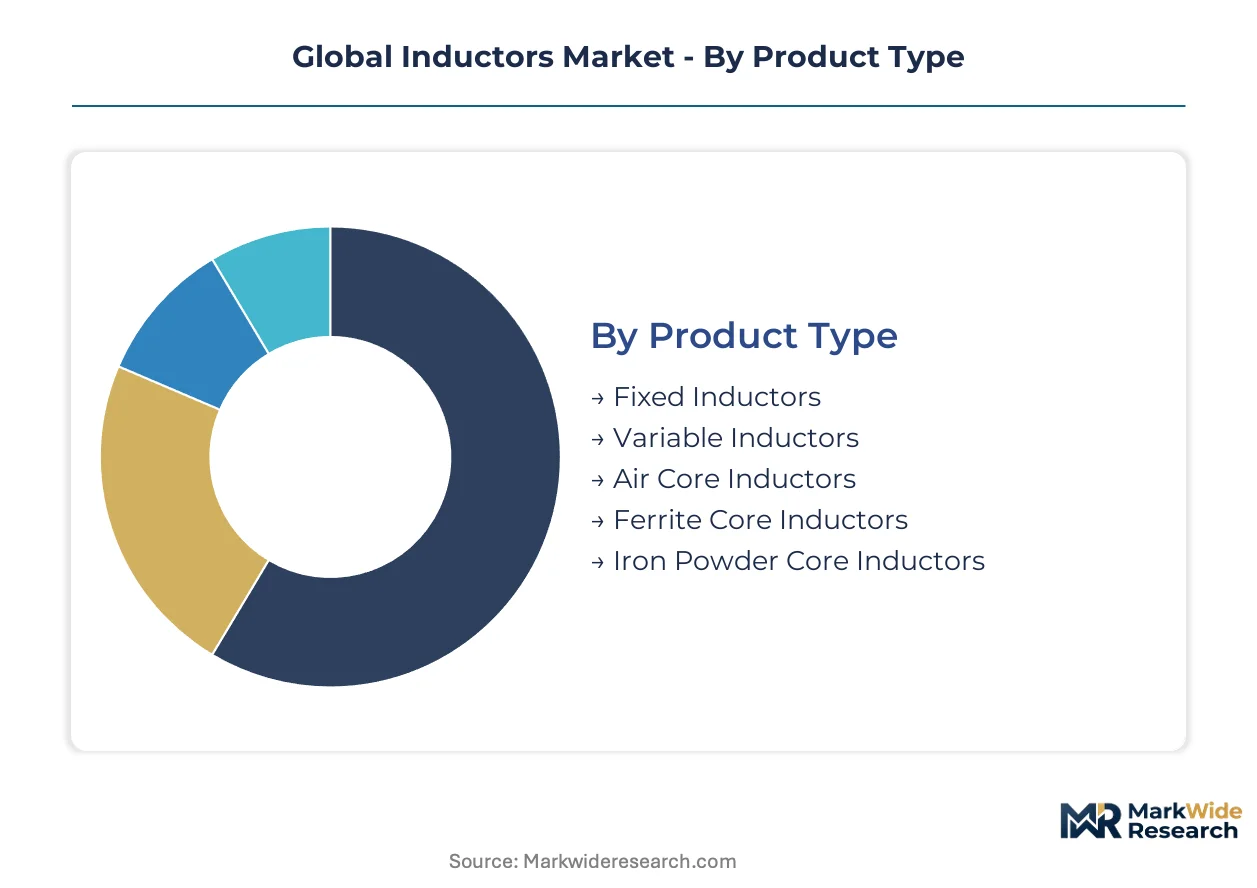
Inductor segmentation reveals divergent margin structures across integration depths. Standalone power inductors for automotive inverters command premium qualification cycles, while embedded RF inductors in 5G base stations scale through semiconductor packaging partnerships.
Product Type:
Integration depth varies sharply: ferrite cores dominate discrete board-level mounting, while iron powder formulations embed directly into power module substrates.
- Ferrite Core Inductors:Manganese-zinc and nickel-zinc compositions deliver permeability stability across temperature ranges critical for server voltage regulators. Procurement concentrates in Shenzhen and Tokyo-Yokohama manufacturing corridors, where automotive electrification programs in Germany and South Korea are tightening saturation current specifications.
- Power Inductors:High-current geometries with distributed air-gap cores store energy in DC-DC converters for electric vehicle platforms. Demand clusters around Tier 1 automotive module suppliers qualifying components for 800-volt architectures in Stuttgart and Seoul.
- Fixed Inductors:Standardized inductance values serve mass-production consumer electronics with minimal tuning requirements.
- Variable Inductors:Tunable core geometries enable impedance matching in RF test equipment and broadcast transmission systems.
- Air Core Inductors:Absence of magnetic material eliminates core losses at frequencies above 100 MHz for radar and satellite communication front-ends.
- Iron Powder Core Inductors:Distributed gap structures handle high DC bias currents in renewable energy inverters, though EU F-Gas Regulation compliance is extending European qualification timelines.
Ferrite core inductors lead volumes today; power inductors are gaining share fastest.
Technology:
Cost tier stratification separates premium high-frequency designs from commodity surface-mount formats.
- Surface Mount Technology:Tape-and-reel packaging eliminates through-hole insertion costs for smartphone and laptop motherboard assembly. Volume procurement at computing OEMs in Taiwan and South Korea favors compact geometries below 2mm height.
- RF Inductors:High-Q factor specifications with tight tolerance windings enable 5G base station filter banks. China's MIIT electromagnetic compatibility directives are conditioning Q-factor minimums for domestic telecommunications infrastructure.
- Through-Hole Technology:Mechanical robustness suits industrial power supplies and automotive engine compartment modules with vibration exposure.
- High Frequency:Ceramic core and multilayer constructions address gigahertz-range applications in radar and satellite systems.
- Power Inductors:Shielded drum and toroidal geometries manage thermal dissipation in multi-kilowatt conversion stages.
Surface mount technology leads volumes today; RF inductors are climbing the fastest.
Application:
Customer type divergence separates high-reliability aerospace procurement from price-sensitive consumer electronics tenders.
- Telecommunications:Base station power amplifiers and filter networks demand precision-wound RF inductors with tight tolerance. India's TRAI spectrum frameworks and BIS certification pathways are opening procurement channels for domestic 5G equipment vendors.
- Computing Devices:Voltage regulator modules for server processors require low-loss ferrite cores with high saturation current ratings. Hyperscale cloud operators in the United States are consolidating approved vendor lists to three sources per inductor category.
- Consumer Electronics:Miniaturized multilayer chip inductors populate smartphone and wearable circuit boards at billion-unit annual scales.
- Aerospace:MIL-PRF-qualified components with extended temperature ranges serve avionics and satellite payload electronics.
- Defense Equipment:Ruggedized shielded inductors meet shock and vibration specifications for military communication systems.
Consumer electronics leads volumes today; telecommunications is expanding most quickly.
End User:
Supply concentration differs between captive OEM manufacturing and outsourced electronics assembly.
- OEMs:Direct component specification by automotive and computing original equipment manufacturers locks in multi-year supply agreements. Japan's METI energy efficiency regulations for computing devices are tightening loss budgets that favor vendors with advanced ferrite laboratories.
- Electronic Manufacturing Services:Foxconn, Jabil, and Flex procurement desks aggregate demand across multiple OEM customers, consolidating volume leverage.
- Aftermarket Suppliers:Replacement inductors for repair and maintenance channels serve industrial equipment with decade-long service lives.
- System Integrators:Custom power subsystem designers specify inductors for medical imaging and renewable energy conversion equipment.
OEMs lead volumes today; electronic manufacturing services are capturing share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting inductor procurement flows as manufacturers seek jurisdictions with streamlined electromagnetic compatibility certification pathways and lower compliance friction for ferrite core formulations.
China
MIIT electromagnetic compatibility directives are conditioning Q-factor specifications for 5G base station RF inductors while dual carbon goals reshape material compliance requirements for ferrite core compositions. Domestic telecommunications infrastructure deployments concentrate procurement in Shenzhen manufacturing clusters where automotive-grade component specifications are tightening simultaneously.
Germany
KBA certification requirements are accelerating procurement of high-current inductors for onboard chargers in electric vehicle platforms. EU F-Gas Regulation compliance mandates are extending qualification cycles for iron powder core mixtures destined for European automotive module suppliers. Stuttgart anchors Tier 1 automotive module supplier concentration for 800-volt platform designs.
Japan
METI energy efficiency regulations for computing devices are tightening loss budgets that favor vendors with advanced ferrite composition laboratories. Automotive electrification programs are compressing qualification timelines for high-current power inductors. Tokyo-Yokohama manufacturing corridors host integrated ferrite material science operations serving premium power inductor tiers.
South Korea
Automotive electrification programs are driving procurement of high-current power inductors for DC-DC converters in electric vehicle platforms. Domestic electromagnetic compatibility standards align with export market requirements for multi-jurisdiction shipment qualification. Seoul manufacturing clusters concentrate demand for integrated composite magnetic cores in 800-volt platform designs.
United States
FCC electromagnetic compatibility test regimes are fragmenting single-SKU economics for OEMs maintaining parallel qualification streams with CE marking and GB standard frameworks. Hyperscale cloud operators are consolidating approved vendor lists to three sources per inductor category. Server motherboard supply chains in North American data center corridors are displacing traditional component distributor relationships for power inductor selection.
Global Inductors Market Competitive Landscape
Japanese producers anchor the premium-tier ferrite material science segment; Taiwanese and Chinese fabricators hold volume positions in surface-mount power inductor categories. The vendor base stratifies across integrated material science laboratories, precision winding automation specialists, and scale-driven contract manufacturers. Three archetypes dominate: ferrite composition innovators, RF inductor precision specialists, and automotive qualification aggregators. Capacity expansion in East Asian powder facilities and strategic partnerships for electromagnetic simulation support represent the dominant competitive moves.
Within the integrated material science tier, TDK Corporation and Murata Manufacturing Co., Ltd. exemplify archetypes combining ferrite core development with premium power inductor positioning. Coilcraft Inc. occupies a specialist position in ultra-miniature chip inductor geometries that differentiate catalog offerings for aerospace and medical signal chain applications. These three entities represent distinct competitive vectors—material science integration, RF precision, and miniaturization specialization—without overlapping positioning.
| Leading Market Players |
|---|
| Taiyo Yuden Co., Ltd. |
| Panasonic Corporation |
| Murata Manufacturing Co., Ltd. |
| Delta Electronics |
| Coilcraft Inc. |
| TDK Corporation |
| Sumida Corporation |
| Chilisin Electronics |
| Vishay Intertechnology |
| Others |
Supply & Pricing Matrix
Hyperscale cloud operators consolidating approved vendor lists to three sources per inductor category are imposing contract-based long-term offtake pricing that compresses spot-market volatility for power inductor tiers.
Pricing Analysis
Distributor margins in authorized channels handling automotive-grade components absorb qualification audit costs that direct-to-OEM agreements bypass entirely. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer electronics levels separates saturation current ratings and thermal performance certification tiers. Cost compression in consumer-grade ferrite cores intensifies because Taiwanese fabricators are expanding manganese-zinc powder capacity. EMS procurement desks at Foxconn and Jabil exhibit highest price sensitivity, while Tier 1 automotive module suppliers in Stuttgart and Seoul prioritize thermal performance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for server voltage regulator modules, displacing traditional component distributor relationships in North American data center corridors. Manufacturing gravity draws from Japan, South Korea, and China, with Tokyo-Yokohama and Shenzhen clusters hosting integrated ferrite material science operations. Raw material flows rest on manganese-zinc ferrite precursors, nickel-zinc compositions for RF applications, and specialized iron powder mixtures. Single-source vulnerability concentrates in East Asian rare earth processing corridors for specialized ferrite precursors. Distribution runs through authorized distributors with in-house electromagnetic simulation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Automotive electrification programs in Germany, Japan, and South Korea are shifting procurement toward premium power inductor specifications with tightened thermal performance thresholds.
For Market Incumbents: Cement ferrite composition laboratory capabilities against emerging entrants lacking integrated material science pipelines. Deepen backward integration into manganese-zinc powder production to defend margin position against rare earth supply concentration risks. Prioritize certification investment for EU F-Gas Regulation compliance to maintain European automotive module supplier access. For New Entrants and Emerging Players: Launch via India's TRAI spectrum allocation frameworks and BIS certification pathways for domestic 5G RF inductor procurement. Target medical device miniaturization applications where ultra-miniature chip inductor geometries face limited incumbent specialization. Pursue electromagnetic simulation support partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Tier 1 automotive module suppliers are the most active acquirer in this space, seeking captive inductor supply for 800-volt platform designs. The five-to-ten-year viability window favors precision winding automation specialists with aerospace-grade tolerance capabilities. Monitor divergence between FCC, CE marking, and GB standard electromagnetic compatibility test regimes as the critical inflection signal for single-SKU economics fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Ferrite Material Science Investment | TDK Corporation leverages captive laboratories to sustain premium positioning in automotive-grade power inductor tiers. |
| Precision Winding Automation Upgrade | Mid-tier contract manufacturers strain capital equipment cycles to meet ±10% tolerance requirements for aerospace components. |
| Electromagnetic Simulation Support Partnership | Authorized distributors consolidate channel control by embedding design-in capabilities for hyperscale cloud operator procurement. |
| Composite Magnetic Core Development | Tier 1 automotive suppliers in Germany adopt distributed air-gap geometries for 800-volt DC-DC converter thermal benchmarks. |
| Termination Chemistry Reformulation | Surface mount device manufacturers deploy tin-bismuth solder alternatives to satisfy REACH restrictions on hexavalent chromium plating. |
Research Methodology
Multiple input streams — primary interviews with inductor procurement managers at Tier 1 automotive suppliers, ferrite material science directors, and EMS category buyers — were reconciled against secondary validation from MIIT electromagnetic compatibility filings, KBA certification registries, and SEC disclosures from listed component manufacturers. Bottom-up demand modeling across product type, technology, and application segments was triangulated with top-down macroeconomic indicators.
Data-stream reconciliation anchored volume and value outputs across the analysis window, with segmentation dimensions spanning core material composition, mounting technology format, end-use application, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating automotive electrification program timelines, 5G infrastructure deployment schedules, and hyperscale data center capex cycles. Industry-specific forecast inputs included saturation current rating trajectories for electric vehicle platforms and Q-factor specification evolution for telecommunications infrastructure.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth supply disruption scenarios or accelerated electromagnetic compatibility test regime divergence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Global RF Plasma Generator Market
RF Components
Americas Small Signal Transistor Market
RF Components
Microwave Devices Market
RF Components
Latin America RFID Tags Market
RF Components
Digital Radio Frequency Market
RF Components
Radio Frequency Counter Market
RF Components
Flat Panel Antenna Market
RF Components
Japan Small Signal Transistor Market
RF Components
Harness-Level EMI and Shielding Component Systems Market
RF Components
RF Passive Component Market
RF Components
Radio Frequency Duplexer Market
RF Components
Digital Phase Shifter Market
RF Components
5G Millimeter Wave RF Transceiver Market
RF Components
RFID Tags Market
RF Components
Small Signal Mosfets Market
RF Components
433MHz Active RFID Reader Market