
 RF Duplexer Market | 2026-2036
RF Duplexer Market Size, Share, and Industry Trends Forecast 2026-2036
RF Duplexer Market Outlook
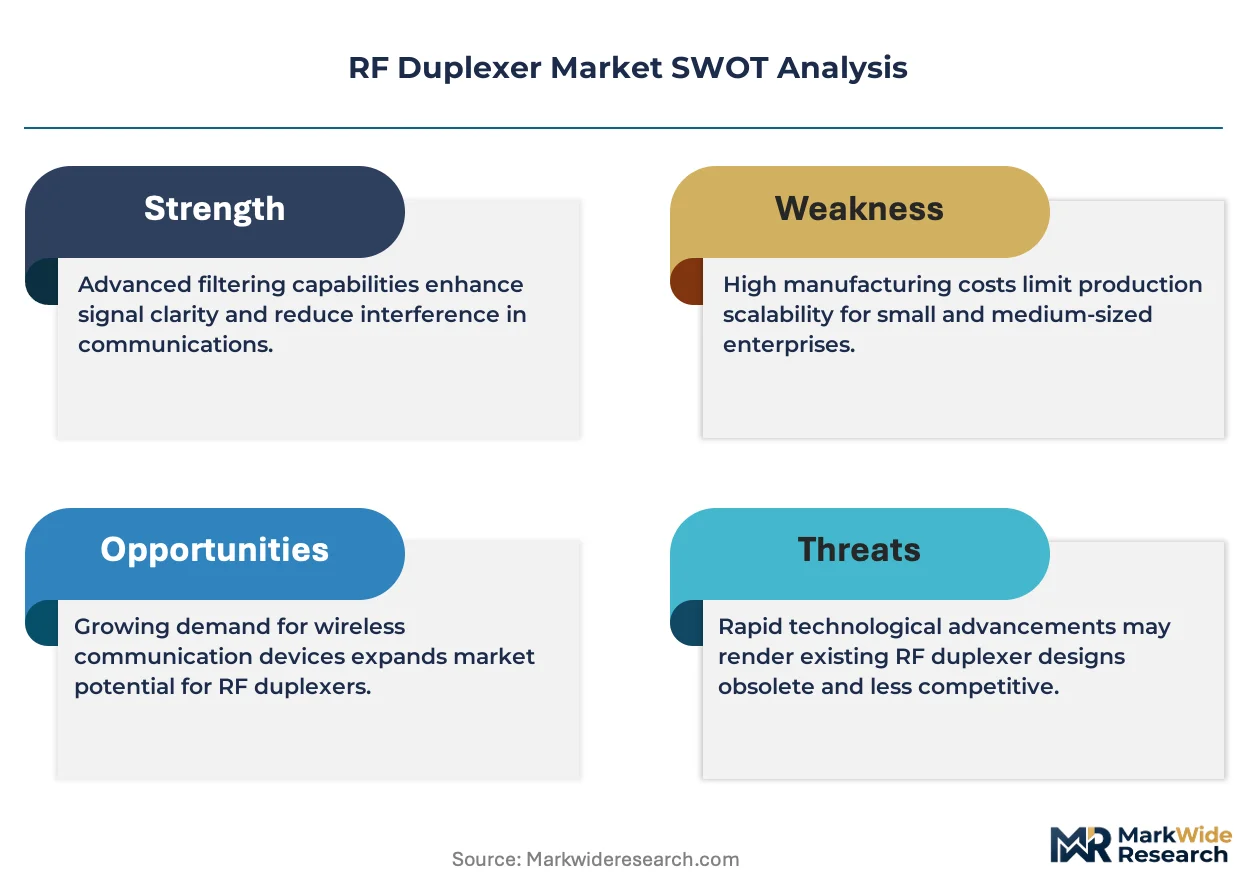
OEM direct sourcing is tilting away from traditional distributor networks as smartphone and base-station manufacturers consolidate RF front-end procurement. Broadcom leverages its captive gallium arsenide foundry capacity to dominate high-band architectures for flagship handsets. Murata Manufacturing sustains unmatched ceramic formulation expertise that anchors its position in low-band smartphone duplexers. Qorvo competes through integrated filter-LNA modules that reduce board space for 5G massive MIMO deployments.
An RF duplexer is a three-port passive device that uses surface acoustic wave or bulk acoustic wave resonators to isolate transmit and receive signals sharing a single antenna, typically achieving isolation exceeding 50 dB across adjacent frequency bands. Band Pass variants lead volume shipments due to their ubiquity in cellular handsets, while Waveguide architectures command premium positioning in base-station applications where power handling exceeds 100 watts. Ceramic technology occupies the largest share of consumer electronics installations, though Hybrid designs are gaining traction in aerospace end-use where temperature extremes demand combined material approaches.
The FCC enforces stringent out-of-band emission rules under Part 27 that compel duplexer manufacturers to tighten rejection specifications for C-band 5G equipment. ETSI harmonizes these limits across European Union member states through EN 301 908 standards, while China's MIIT mandates domestic certification through SRRC approval for all imported RF components. Stakeholders must monitor evolving spectrum reallocations and corresponding filter re-tuning requirements as regulators auction additional mid-band frequencies.
Market Dynamics
Smartphone OEMs are consolidating RF front-end procurement into direct supplier relationships, bypassing traditional distributor networks and compressing margins for component intermediaries across the supply chain.
Growth Catalysts
- 5G sub-6 GHz deployment:Smartphone manufacturers are expanding procurement of ceramic-based duplexers to support multi-band architectures in flagship and mid-tier handsets.
- FCC Part 27 enforcement:Tightened out-of-band emission rules for C-band equipment are compelling infrastructure OEMs to upgrade to higher-rejection filter specifications.
- Surface acoustic wave foundry concentration:China, South Korea, and Taiwan host the majority of SAW filter production capacity, creating geographic scale advantages for regional component suppliers.
Market Restraints
- Gallium arsenide wafer supply concentration:Captive foundry control by integrated RF module vendors limits merchant market access for independent duplexer specialists.
- Bulk acoustic wave temperature sensitivity:BAW resonators exhibit frequency drift beyond operational limits in aerospace and defense applications above 85°C ambient.
- ETSI EN 301 908 harmonization delays:Divergent national implementation timelines across EU member states fragment certification requirements for base-station equipment.
Strategic Opportunities
- India PLI scheme for telecom equipment:Production-linked incentives are attracting contract manufacturers to establish local RF component assembly for domestic 5G infrastructure.
- Filter-LNA integration:Convergence of duplexer and low-noise amplifier functions into single modules addresses board-space constraints in 5G massive MIMO antenna arrays.
- Hybrid ceramic-polymer formulations:Temperature-extreme applications in satellite communications are creating demand for material combinations beyond pure ceramic or pure polymer substrates.
Industry Challenges
- Acoustic resonator design talent scarcity:The specialized physics expertise required for SAW and BAW device modeling is concentrated among a limited pool of experienced engineers.
- SRRC certification timelines:China's State Radio Regulation Committee approval process for imported RF components extends product launch schedules by six to nine months.
- Legacy 4G filter inventory integration:Base-station OEMs face technical complexity in maintaining backward compatibility with existing RAN infrastructure during 5G upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Duplexer Market |
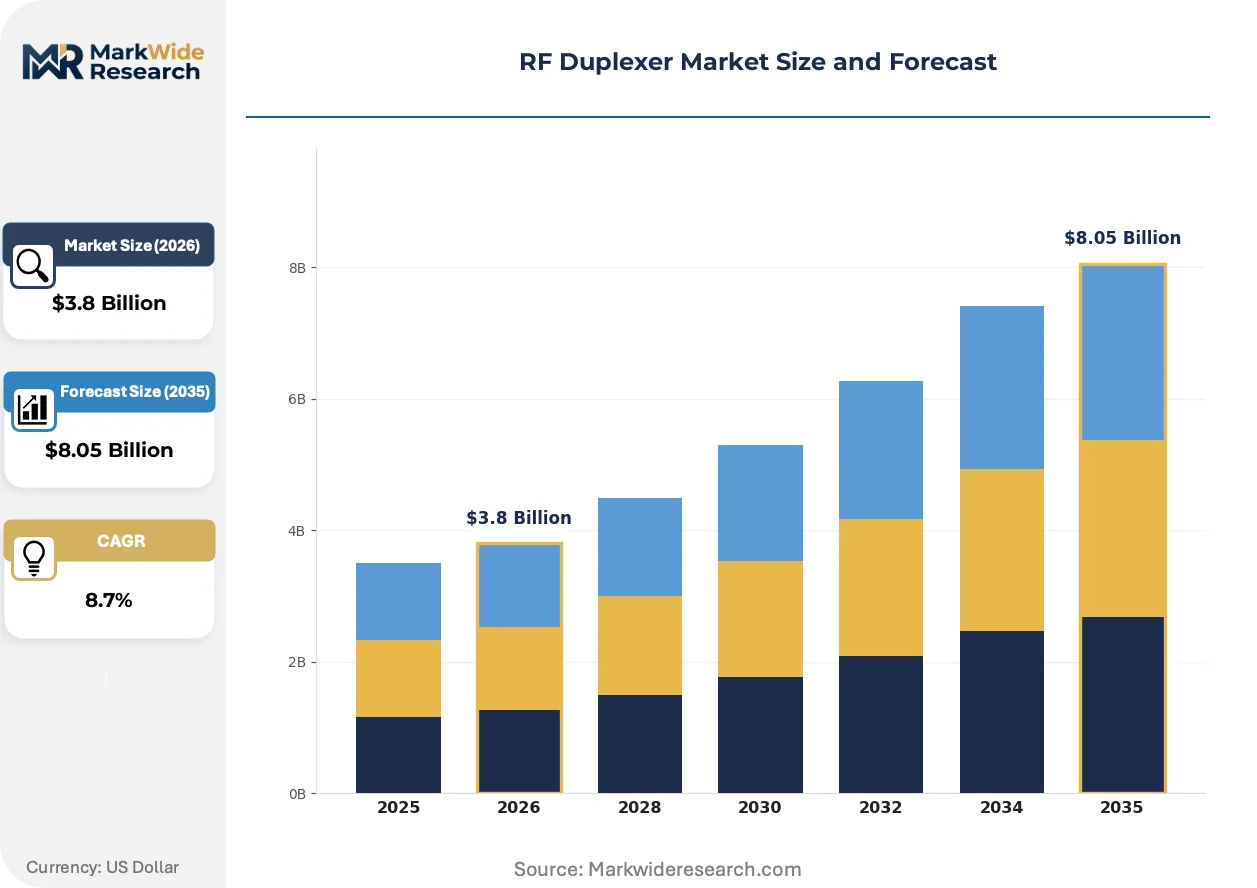
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Band Pass, Band Stop, Low Band, High Band Technology: Ceramic, Microstrip, Waveguide, Hybrid End User: Telecommunication, Aerospace, Automotive, Consumer Electronics Installation: Indoor, Outdoor, Rack-Mounted, Embedded |
| Companies Covered | Broadcom, Murata Manufacturing, Qorvo, Skyworks Solutions, TDK Corporation, Taiyo Yuden, CTS Corporation, API Technologies, Johanson Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Duplexer Market Strategic Shifts
Material science advances and regulatory pressure on spectral efficiency are converging to reshape duplexer architecture choices, with performance specifications tightening faster than historical replacement cycles.
BAW resonator technology is migrating from high-band smartphone applications into base-station infrastructure. Tower equipment manufacturers are adopting thin-film bulk acoustic wave filters for 3.5 GHz and 4.9 GHz bands to achieve sharper roll-off characteristics than ceramic alternatives permit. This migration from SAW-dominated base-station designs is compressing the performance gap between consumer and infrastructure-grade components.
REACH substance restrictions on lead and cadmium in electronic ceramics are forcing reformulation of piezoelectric materials used in SAW substrates. European manufacturers must certify alternative dopant compositions that maintain electromechanical coupling coefficients without restricted elements. High-volume smartphone duplexer suppliers with European export exposure are accelerating qualification of compliant ceramic formulations ahead of enforcement deadlines.
Direct sourcing contracts are displacing authorized distributor relationships for RF front-end procurement. Tier-one smartphone OEMs are consolidating vendor lists and negotiating multi-year supply agreements that bypass traditional component distributors. This channel restructuring is most visible in South Korean and Chinese handset supply chains, where captive RF module subsidiaries and direct foundry relationships dominate procurement decisions.
RF Duplexer Market Segmentation
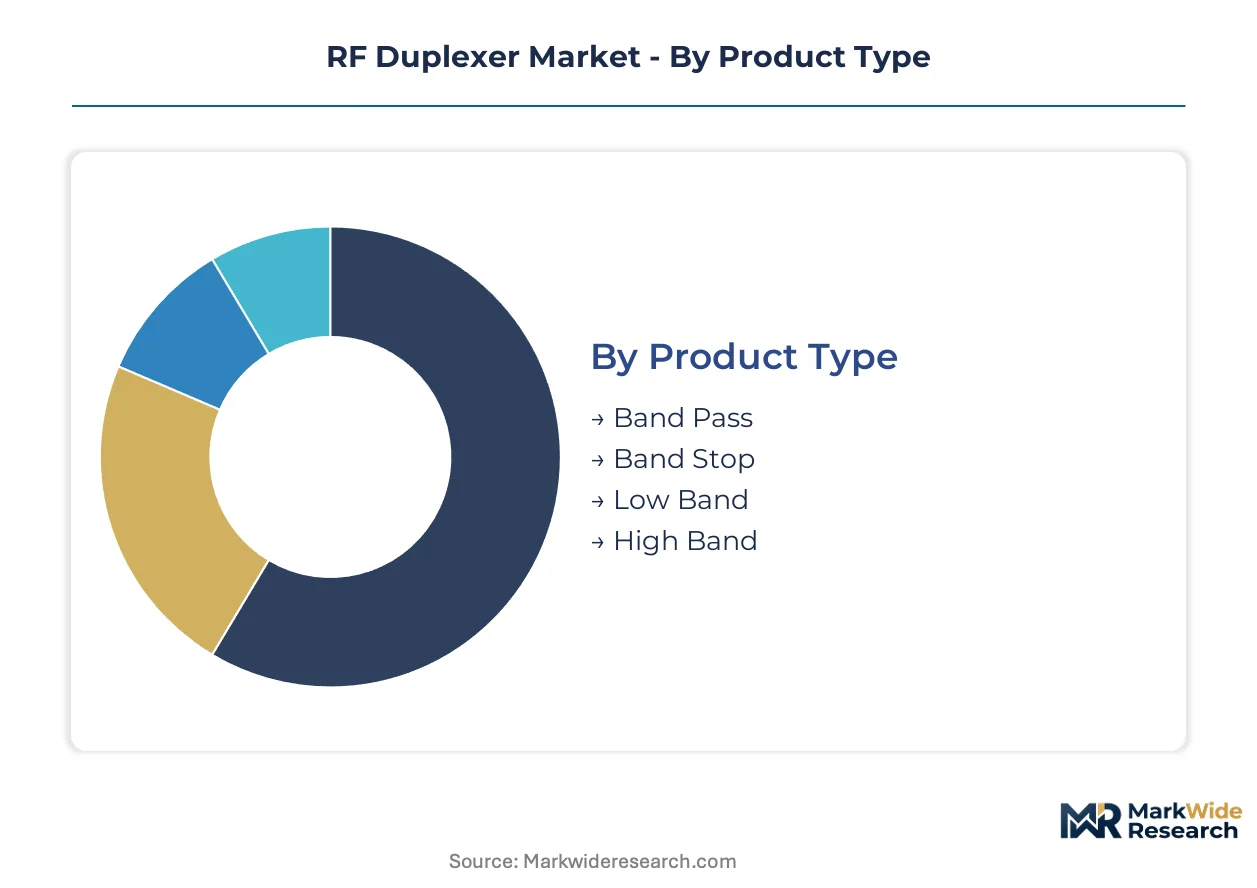
RF duplexer procurement patterns diverge sharply across installation environments and performance tiers, with after-sales service intensity varying from minimal for embedded consumer modules to extensive for outdoor base-station hardware. Component suppliers must calibrate technical support infrastructure to match segment-specific lifecycle expectations.
Product Type:
Service intensity escalates with spectral complexity, as multi-band architectures demand ongoing tuning support through deployment cycles.
- Band Pass:Ubiquitous in cellular handsets, these filters isolate adjacent frequency bands using SAW or BAW resonator arrays with isolation exceeding 50 dB. Smartphone OEMs in China and South Korea dominate procurement volumes, driven by 5G sub-6 GHz multi-band architectures requiring precise passband characterization.
- High Band:Operating above 3.5 GHz, these duplexers employ thin-film BAW technology to achieve sharper roll-off than ceramic alternatives permit. Base-station OEMs upgrading C-band infrastructure per FCC Part 27 mandates are the primary demand concentration, with rejection specifications tightening faster than historical replacement cycles.
- Band Stop:Attenuates specific interference frequencies while passing broader spectrum, deployed in coexistence scenarios between cellular and satellite systems.
- Low Band:Sub-1 GHz architectures rely on ceramic formulations for cost efficiency in emerging market handsets.
Band Pass holds the largest share; momentum sits with High Band as infrastructure OEMs migrate to 3.5 GHz and 4.9 GHz deployments.
Technology:
Material selection directly determines temperature resilience and manufacturing scalability across deployment scenarios.
- Ceramic:Dominates consumer electronics installations through piezoelectric formulations optimized for low-band smartphone duplexers. Murata Manufacturing's unmatched ceramic formulation expertise anchors this segment, though REACH substance restrictions on lead and cadmium are forcing accelerated reformulation timelines for European export compliance.
- Hybrid:Combines ceramic substrates with polymer encapsulation to address temperature extremes in satellite communications and aerospace applications. Satellite OEMs are expanding procurement as orbital deployments demand combined material approaches beyond pure ceramic or pure polymer substrates.
- Microstrip:Planar transmission line structures fabricated on PCB substrates for cost-sensitive IoT and automotive modules.
- Waveguide:Hollow metallic channels handling power levels exceeding 100 watts in macro base-station installations.
Ceramic commands volume leadership; Hybrid is climbing the fastest as temperature-extreme applications multiply.
End User:
Application-specific certification requirements fragment procurement patterns across verticals.
- Telecommunication:Encompasses smartphone and infrastructure OEMs consolidating RF front-end procurement into direct supplier relationships. FCC Part 27 and ETSI EN 301 908 emission standards are compelling design changes across C-band equipment, with filter re-tuning requirements tracking spectrum auction outcomes.
- Consumer Electronics:Wearables and tablets drive miniaturization demands, with board-space constraints pushing integration of duplexer and LNA functions into single modules.
- Aerospace:Temperature sensitivity of BAW resonators above 85°C limits adoption, creating demand for alternative architectures in defense and satellite systems.
- Automotive:V2X communication modules require automotive-grade qualification timelines that extend product development cycles.
Telecommunication absorbs the dominant volume; Consumer Electronics is gaining share fastest through wearable expansion.
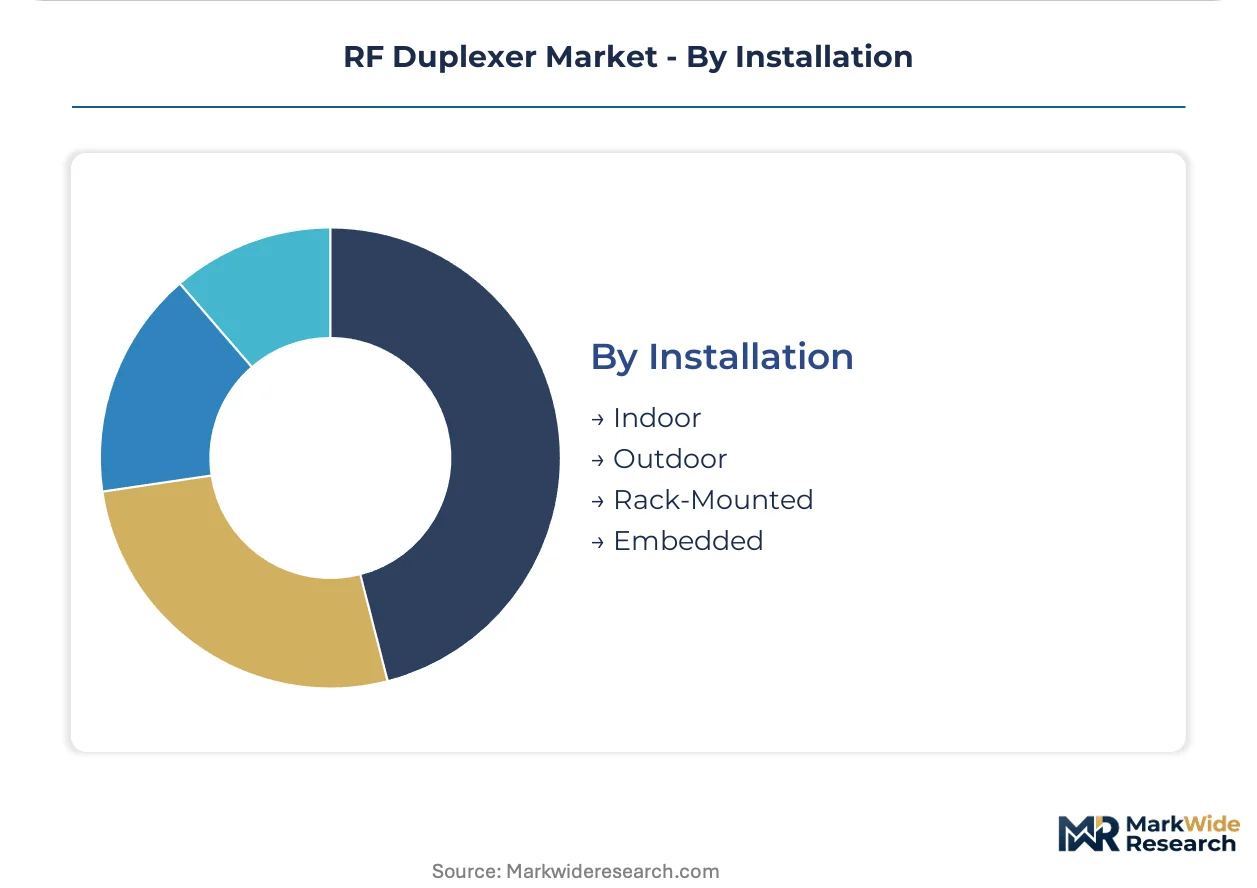
Installation:
Physical mounting configuration determines environmental sealing requirements and field service accessibility.
- Embedded:Integrated directly onto smartphone and IoT device mainboards with minimal external access, demanding highest reliability margins due to irreparability.
- Outdoor:Macro base-station installations exposed to precipitation and thermal cycling, requiring IP-rated enclosures and periodic field calibration.
- Indoor:Small cell and distributed antenna system deployments in climate-controlled environments.
- Rack-Mounted:Centralized baseband processing equipment in controlled data center environments.
Embedded represents the highest unit volume; Outdoor shows steepest expansion trajectory as 5G densification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government production-linked incentives and spectrum auction programs are reshaping procurement geography across major RF component markets. National regulators are tightening emission standards while channeling investment toward domestic manufacturing capacity.
United States
Base-station OEMs are upgrading C-band infrastructure to meet FCC Part 27 out-of-band emission mandates. The FCC's spectrum auction program continues reallocating mid-band frequencies for 5G deployment. Tower hardware manufacturers cluster in Texas and California, where defense and commercial RF engineering talent pools overlap.
China
Domestic smartphone brands are consolidating RF front-end procurement through direct foundry relationships. MIIT mandates SRRC certification for all imported RF components, extending approval timelines. Shenzhen and Dongguan host concentrated surface acoustic wave filter assembly operations serving both local OEMs and export markets.
South Korea
Flagship handset manufacturers are driving ceramic-based duplexer volumes for sub-6 GHz architectures. The national spectrum regulator coordinates with ETSI-aligned standards for equipment export compliance. Seoul Capital Area foundries maintain captive gallium arsenide wafer capacity for integrated RF module production.
Germany
REACH substance restrictions on lead and cadmium are forcing accelerated reformulation of piezoelectric ceramic substrates. ETSI EN 301 908 harmonization efforts create compliance complexity across EU member state timelines. Bavaria's automotive RF engineering centers are expanding V2X communication module qualification programs.
Japan
Ceramic formulation expertise anchors domestic suppliers in low-band smartphone duplexer segments. METI coordinates national standards with international spectrum allocation frameworks. Kyushu-based material science clusters are qualifying alternative dopant compositions ahead of European enforcement deadlines.
RF Duplexer Market Competitive Environment
On the supply side, the industry is consolidating around integrated RF module vendors with captive foundry capacity and specialized ceramic material houses. Merchant duplexer specialists face narrowing access to gallium arsenide wafer supply as vertically integrated competitors internalize critical inputs. Three archetypes dominate: integrated module vendors controlling upstream resonator production, ceramic material specialists with proprietary formulation IP, and contract manufacturers scaling assembly for regional infrastructure programs. Competitive moves center on foundry capacity expansion and direct sourcing contract capture with tier-one smartphone OEMs.
Among the integrated module vendors, Broadcom, Murata Manufacturing, and Qorvo exemplify contrasting strategic positions. Broadcom represents the captive-foundry archetype with internal gallium arsenide capacity. Murata Manufacturing occupies the materials-specialist position anchored in ceramic formulation expertise. Qorvo sits within the integration-focused tier pursuing filter-LNA module convergence. These three collectively illustrate how supply-side control over resonator technology and manufacturing scale determines competitive positioning.
| Leading Market Players |
|---|
| Broadcom |
| Murata Manufacturing |
| Qorvo |
| Skyworks Solutions |
| TDK Corporation |
| Taiyo Yuden |
| CTS Corporation |
| API Technologies |
| Johanson Technology |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on gallium arsenide wafer supply from captive foundries determines both the compression of mid-tier pricing spreads and the consolidation of procurement relationships toward direct OEM-factory contracts. This chokepoint simultaneously elevates premium-tier margins for integrated vendors while eroding distributor economics across standard-grade ceramic duplexer segments.
Pricing Analysis
Certification level (FCC Part 27 and ETSI EN 301 908 compliance tiers) creates the primary spread between base-station and handset-grade duplexers. The dominant pricing structure runs contract-based long-term offtake agreements with volume-scaled unit economics. Price differentiation rests on rejection specification thresholds and SRRC certification status for China market access. Cost compression in mid-tier ceramic duplexers is intensifying because smartphone OEMs are consolidating vendor lists and negotiating direct foundry relationships. Handset manufacturers show highest price sensitivity due to margin pressure in saturated sub-6 GHz segments, while aerospace and defense buyers prioritize temperature resilience over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for RF component procurement. Manufacturing gravity centers on China, South Korea, and Taiwan for surface acoustic wave filter foundry capacity, with Japan anchoring ceramic substrate formulation expertise. Raw material dependencies draw from piezoelectric ceramic powders, gallium arsenide wafers, and thin-film deposition equipment. Single-source vulnerability concentrates in captive gallium arsenide foundry control by integrated module vendors. Distribution runs through direct sourcing contracts that displace traditional authorized distributor networks, particularly visible in South Korean and Chinese handset supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF front-end procurement is consolidating into platform-centric direct relationships that mirror the interoperability demands of multi-band 5G architectures, creating winner-take-most dynamics for vendors controlling resonator technology and certification pathways.
For Market Incumbents: Build formulation IP moats around REACH-compliant ceramic dopant compositions ahead of European enforcement deadlines. Consolidate backward integration into thin-film BAW resonator production to capture infrastructure upgrade cycles. Defend against merchant foundry access restrictions by locking multi-year direct supply agreements with tier-one smartphone OEMs. Prioritize capacity addition in South Korea and Taiwan to maintain geographic proximity to concentrated SAW foundry clusters. For New Entrants and Emerging Players: India's underpenetrated contract manufacturing base offers the most accessible entry point through PLI scheme-aligned telecom equipment assembly. Target hybrid ceramic-polymer formulations for satellite communications applications where temperature extremes demand combined material approaches. Pursue filter-LNA module integration as the go-to-market angle to address board-space constraints in 5G massive MIMO deployments. Establish technical partnerships with regional infrastructure OEMs to bypass captive foundry bottlenecks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated module vendors with captive resonator production and certification infrastructure. Long-term viability over the next decade hinges on spectrum reallocation exposure and regulatory compliance scalability rather than pure manufacturing scale. Acquisition targets should display ceramic formulation expertise or thin-film BAW process IP. The signal to watch is MIIT spectrum auction announcements that trigger filter re-tuning requirements and vendor qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Formulation Reformulation | REACH compliance ahead of European enforcement deadlines secures export access for smartphone duplexers. |
| Filter-LNA Module Integration | Convergence addresses board-space constraints in 5G massive MIMO antenna arrays for base-station OEMs. |
| Direct Sourcing Contract Capture | Bypassing distributor networks compresses margins for intermediaries while locking volume commitments. |
| Hybrid Material Qualification | Ceramic-polymer combinations meet temperature extremes in satellite and aerospace deployments. |
| Regional Foundry Expansion | Proximity to China, South Korea, and Taiwan SAW clusters reduces logistics costs and SRRC timeline exposure. |
Study Parameters
Cross-validation between primary interviews with RF component procurement executives and secondary regulatory filings anchors the qualitative findings. Stakeholder consultations included smartphone OEM supply chain directors, base-station equipment procurement leads, ceramic materials R&D heads, and FCC and ETSI regulatory affairs specialists. Secondary sources comprised FCC Part 27 enforcement notices, ETSI EN 301 908 harmonization documents, MIIT SRRC certification databases, and REACH substance restriction timelines. Bottom-up unit demand modeling triangulated against top-down spectrum auction capacity projections.
Calibration against historical replacement cycles for SAW and BAW filter deployments shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type (band pass, high band, band stop, low band), technology (ceramic, hybrid, microstrip, waveguide), end user (telecommunication, consumer electronics, aerospace, automotive), and installation configuration (embedded, outdoor, indoor, rack-mounted). CAGRs were derived from elasticity-adjusted demand curves tied to 5G sub-6 GHz deployment trajectories and C-band infrastructure upgrade mandates. Industry-specific inputs included spectrum reallocation schedules and ceramic material qualification timelines.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by merchant duplexer specialists or accelerated REACH enforcement would shift outcomes. Material shifts in FCC mid-band auction timelines or MIIT SRRC approval process streamlining would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Flat Antenna Market
RF Components
Asia-Pacific Small Signal Transistor Market
RF Components
Gaas RF Switch Market
RF Components
Silicon Tuners Market
RF Components
Tunable Inductors Market
RF Components
Acoustic Wave Filters Market
RF Components
433MHz Active RFID Reader Market
RF Components
RF Mixers Market
RF Components
Gan RF Semiconductor Devices Market
RF Components
Multiband Booster Market
RF Components
Digital Phase Shifter Market
RF Components
Wi-Fi Module Market
RF Components
RF Power Detector Market
RF Components
Global RF Power Semiconductor Market
RF Components
Europe Small Signal Transistor Market
RF Components
5G Gain Block Amplifier Market