
 RF Isolator Market | 2026-2036
RF Isolator Market Size, Share, and Industry Trends Forecast 2026-2036
RF Isolator Market Analysis
GaN-on-SiC power amplifier integration is reconfiguring RF front-end architectures and elevating thermal isolation requirements for isolator suppliers. Murata Manufacturing leverages its ceramic component expertise to anchor supply contracts with base station OEMs across East Asia. Qorvo sustains technology leadership in broadband isolators optimized for defense radar frequencies. Mini-Circuits competes aggressively on lead times and catalog breadth for test equipment integrators.
An RF isolator is a non-reciprocal passive device employing ferrite material biased by a permanent magnetic field to permit microwave signal transmission in one direction while absorbing reflected power, typically specified by isolation exceeding 20 dB, insertion loss below 0.5 dB, and operating bandwidth spanning 100 MHz to 40 GHz depending on geometry. Its primary purpose is protecting power amplifiers and signal sources from destructive load mismatch reflections in transmit chains. Ferrite isolators dominate military and radar applications where temperature stability and high power handling command premium positioning, while ceramic-based variants serve cost-sensitive consumer electronics and automotive telematics modules where miniaturization and surface-mount compatibility drive volume. Waveguide isolators retain structural importance in satellite ground stations and broadcasting transmitters despite slower growth, as rectangular waveguide formats above 6 GHz remain irreplaceable for kilowatt-class power levels.
The FCC regulates electromagnetic emissions and spectrum certification for RF components deployed in US telecommunications infrastructure, while the EU AI Act and CE marking frameworks impose conformity assessment obligations on isolators integrated into autonomous automotive radar systems sold in Europe. China's MIIT enforces GB standards for domestic 5G equipment, creating divergent testing regimes that fragment certification pathways for multinational suppliers. Stakeholders must monitor evolving spectrum auction schedules and defense procurement priorities across these jurisdictions to align R&D roadmaps with compliant product configurations.
Market Dynamics
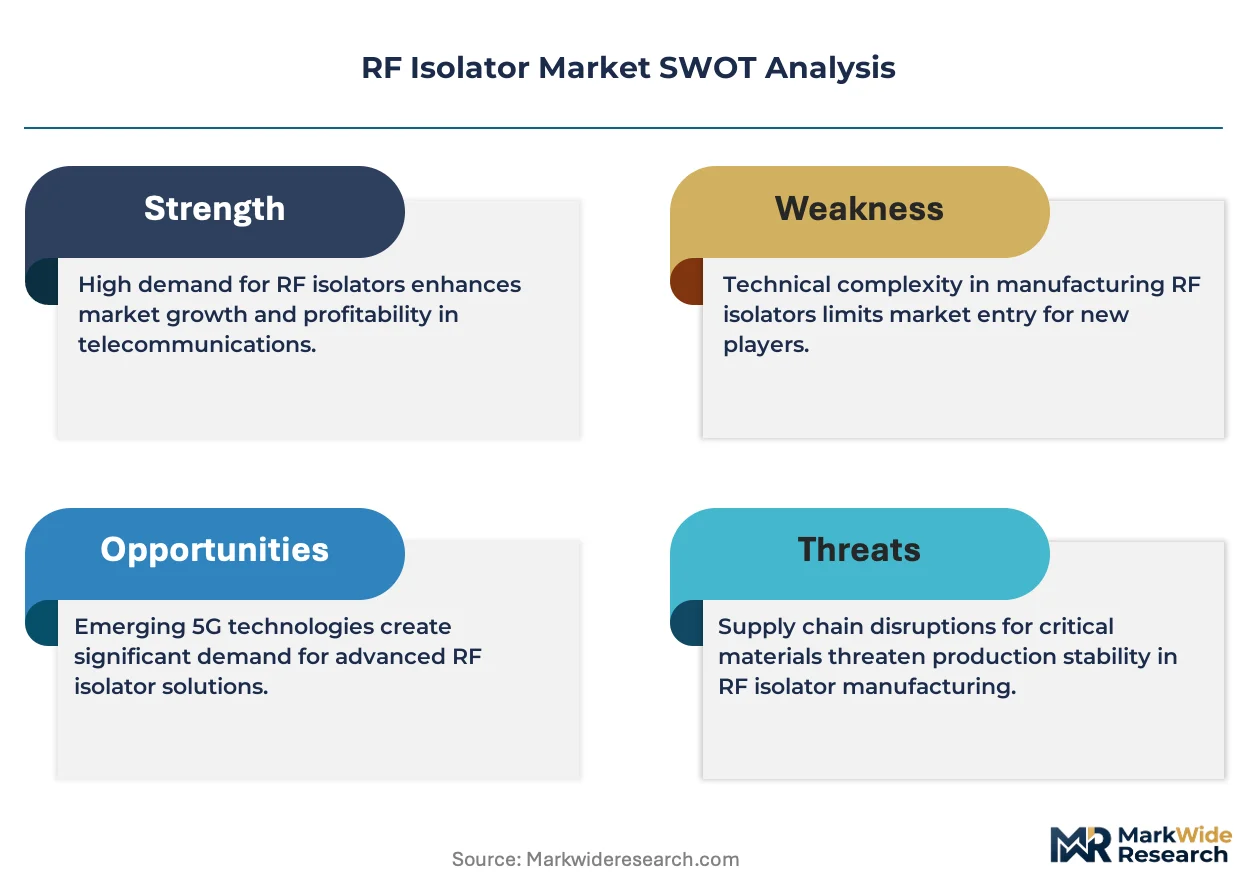
GaN-on-SiC power amplifier integration is forcing RF isolator suppliers to redesign thermal management architectures, as higher power densities demand ferrite materials with improved temperature coefficients and ceramic substrates with enhanced thermal conductivity.
Growth Catalysts
- 5G Infrastructure Mandates:China's MIIT GB standards for domestic base station deployment are consuming waveguide and ferrite isolator volumes at scale, with state-backed carriers accelerating procurement timelines for sub-6 GHz and mmWave bands.
- Satellite Constellation Expansion:Low Earth orbit broadband programs are driving demand for high-power waveguide isolators in ground terminal transmit chains, where kilowatt-class handling and space-qualified reliability specifications dominate vendor selection.
- Defense Radar Modernization:Phased array upgrades across NATO member states are elevating procurement for broadband isolators optimized for X-band through Ka-band frequencies, with thermal stability requirements exceeding commercial telecommunications grades.
Market Restraints
- Yttrium Iron Garnet Supply Concentration:Ferrite substrate production concentrates among Japanese and Chinese specialty ceramic manufacturers, creating input cost volatility when rare earth export quotas tighten.
- Technical Frequency Ceiling:Conventional ferrite isolators face insertion loss degradation above 40 GHz, limiting addressable share in emerging W-band automotive radar and 6G research applications.
- Regulatory Fragmentation:Divergent FCC, EU CE marking, and MIIT GB certification pathways force redundant testing cycles, extending product qualification timelines for multinational suppliers.
Strategic Opportunities
- India Telecom Infrastructure:TRAI spectrum auction schedules and domestic PLI scheme incentives for 5G equipment manufacturing are opening procurement channels for cost-optimized surface-mount isolator variants.
- Automotive Radar Integration:EU AI Act conformity requirements for autonomous vehicle sensor suites are creating certified-supplier preferences for isolators meeting functional safety and electromagnetic compatibility standards.
- Silicon Photonics Convergence:Hybrid optical-RF front-end architectures in data center interconnects are enabling isolator-on-chip designs that merge ferrite thin-film deposition with photonic waveguide fabrication.
Industry Challenges
- Electromagnetic Simulation Talent Scarcity:Finite element modeling expertise for non-reciprocal device optimization remains concentrated among legacy defense contractors, constraining product development velocity at commercial entrants.
- Legacy System Integration Friction:Replacement cycles for existing waveguide isolator installations in broadcasting transmitters face extended qualification periods due to mechanical interface standardization gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Isolator Market |
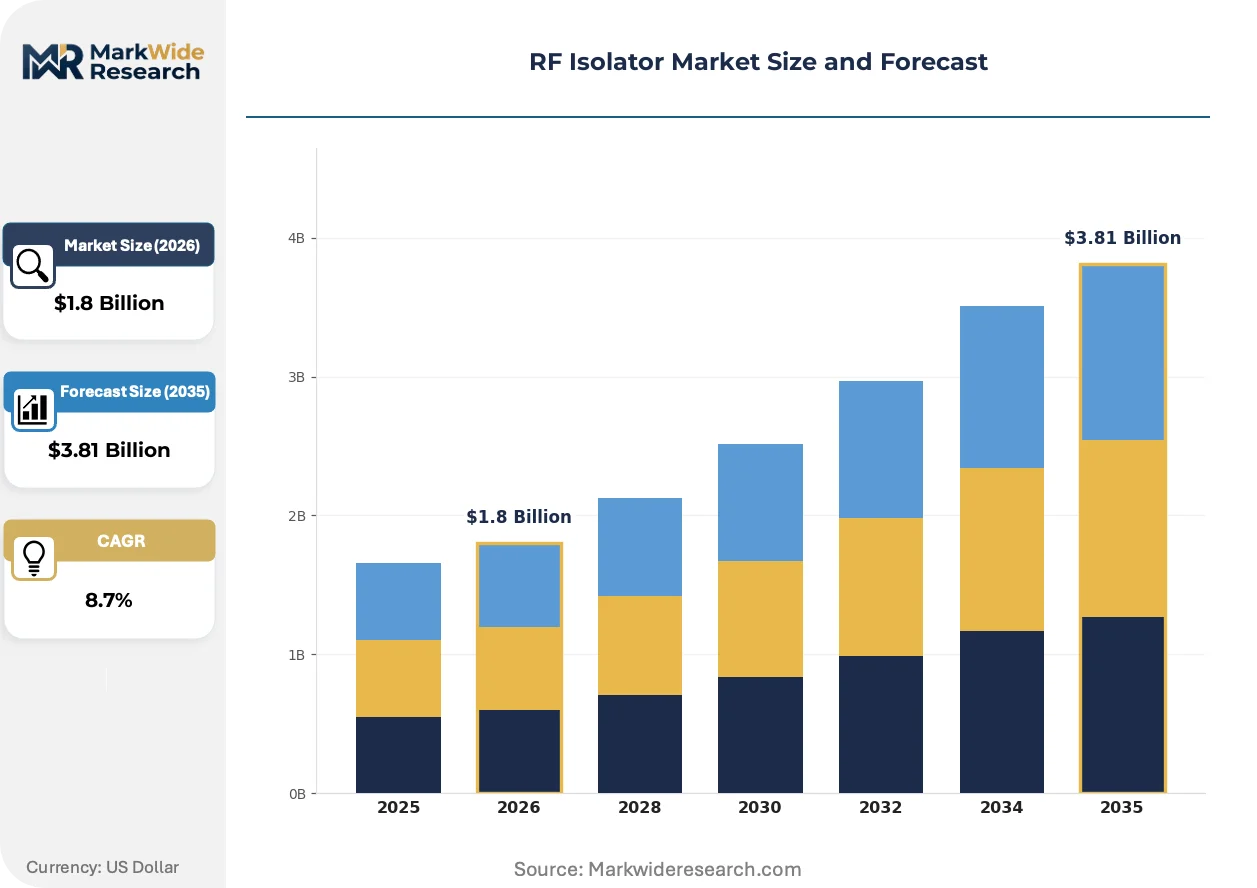
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Ceramic, Ferrite, Waveguide, Coupler Technology: Passive, Active, Hybrid, Digital Application: Telecommunications, Test Equipment, Radar Systems, Broadcasting End User: Aerospace, Automotive, Consumer Electronics, Military |
| Companies Covered | Murata Manufacturing, Skyworks Solutions, Qorvo, Broadcom, Analog Devices, NXP Semiconductors, TDK Corporation, Mini-Circuits, DiTom Microwave, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Isolator Market Emerging Trajectories
RF isolator technology is bifurcating between high-performance ferrite architectures for defense and satellite applications and miniaturized ceramic variants for volume consumer electronics, with manufacturing processes adapting to divergent thermal and cost specifications.
Thin-film ferrite deposition on semiconductor substrates is migrating from laboratory demonstration to pilot production at specialized foundries serving aerospace integrators. Defense prime contractors are qualifying these devices for space-constrained phased array modules. This technology is migrating from waveguide-based formats toward surface-mount-compatible footprints that compress assembly height below 2 millimeters.
The EU AI Act and associated CE marking frameworks for autonomous systems are mandating traceable electromagnetic compatibility documentation across automotive radar supply chains. Component suppliers must now maintain batch-level test records for isolators integrated into safety-critical sensor modules. European Tier 1 automotive electronics manufacturers are responding by consolidating vendor pools to pre-certified specialty ceramic houses.
Base station OEM procurement patterns are compressing supplier qualification cycles from 18 months to 9 months as 5G rollout timelines accelerate. Long-term framework agreements with volume commitments are displacing spot-market purchasing for ferrite isolators. This behavioral shift is most visible in China, where state-owned carriers bundle multi-year supply contracts with technology transfer requirements.
RF Isolator Market Segmentation
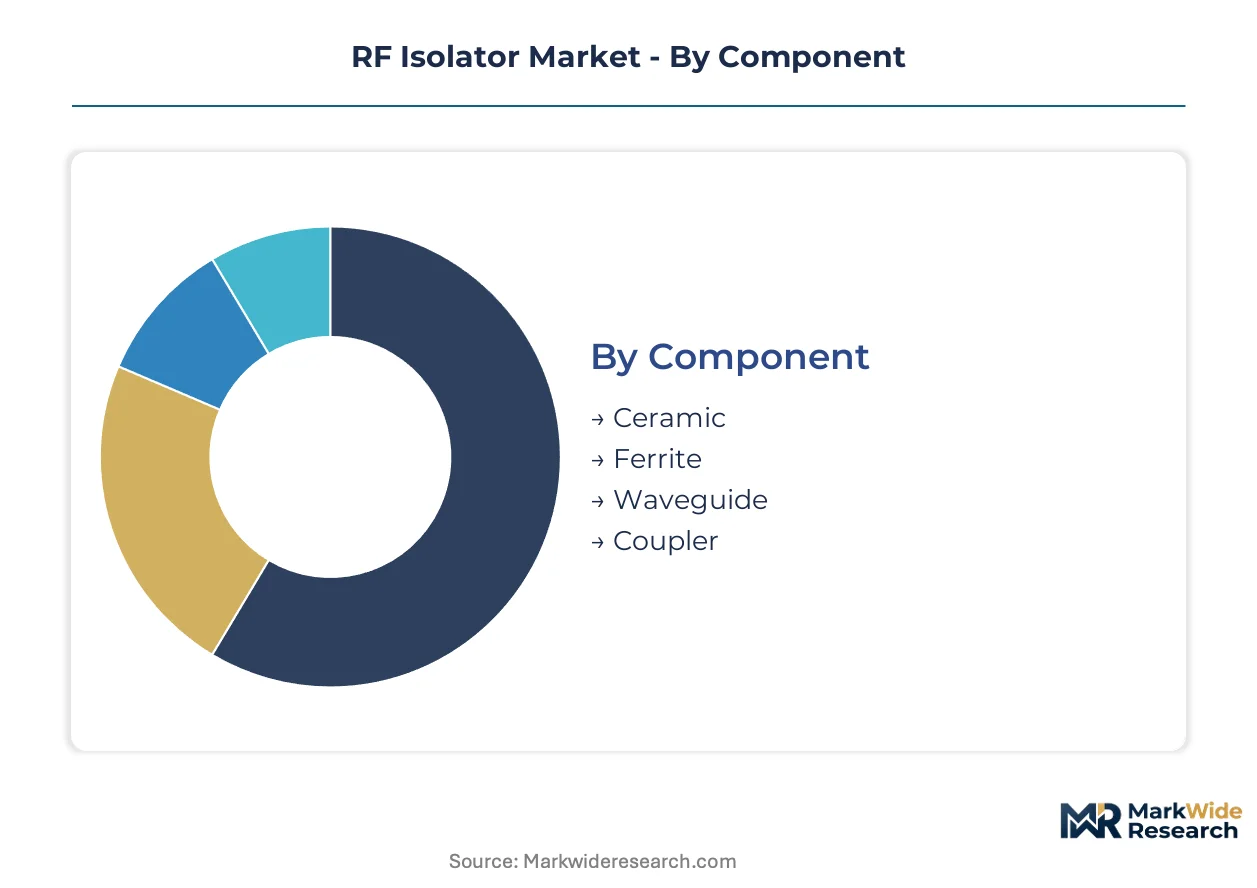
RF isolator procurement cycles vary dramatically by underlying physics and integration complexity. Ceramic variants refresh annually alongside smartphone launches, while waveguide installations persist for decades in ground station infrastructure. Understanding these velocity differentials clarifies inventory positioning and R&D allocation across supplier portfolios.
Component:
Ferrite substrates command the longest design-in cycles due to magnetic biasing calibration requirements, whereas ceramic components turn over fastest as consumer electronics OEMs compress supplier qualification timelines.
- Ferrite:Yttrium iron garnet compositions deliver non-reciprocal behavior through gyromagnetic resonance, with permanent magnet biasing enabling isolation exceeding 20 dB across military radar and satellite ground terminals. China's state-backed constellation programs are absorbing high-temperature-stable ferrite volumes for kilowatt-class transmit chains, though Japanese and Chinese specialty ceramic manufacturers concentrate substrate supply.
- Ceramic:Low-temperature co-fired ceramic substrates support surface-mount assembly below 2 millimeters height, targeting automotive radar modules and 5G small cell deployments where miniaturization overrides absolute isolation performance. South Korean and Taiwanese EMS providers are consolidating procurement around pre-qualified ceramic houses to compress 9-month qualification windows.
- Waveguide:Rectangular waveguide formats above 6 GHz remain irreplaceable for broadcasting transmitters and satellite uplink stations.
- Coupler:Directional coupling functions integrate with isolation in hybrid front-end modules for test equipment.
Waveguide dominates installed base. Ceramic is where expansion concentrates.
Technology:
Passive architectures anchor cost-sensitive volume tiers, while hybrid configurations capture margin in defense applications where digital control overlays analog isolation.
- Passive:Ferrite-based non-reciprocal devices without active electronics deliver lowest insertion loss below 0.5 dB, serving telecommunications infrastructure where simplicity ensures reliability. FCC spectrum reallocation mandates are forcing passive redesigns for higher frequency bands, compressing development timelines for established suppliers.
- Hybrid:Integration of ferrite cores with GaN-on-SiC power amplifier thermal management architectures addresses phased array radar modules where temperature coefficients must track active device drift. NATO member state defense procurement is elevating hybrid isolator specifications for X-band through Ka-band upgrades.
- Active:Transistor-based cancellation circuits compete at lower frequencies with reduced size.
- Digital:Software-defined isolation remains experimental for 6G research applications.
Passive architectures anchor revenue volume. Hybrid configurations are climbing the fastest.
Application:
Telecommunications procurement runs on carrier capex cycles, while test equipment demand tracks semiconductor capital intensity with sharper quarter-to-quarter volatility.
- Telecommunications:5G base station deployment across sub-6 GHz and mmWave bands consumes isolators protecting power amplifiers from antenna mismatch reflections. China's MIIT GB standards and state-owned carrier procurement are driving waveguide and ferrite volumes at scale, with multi-year framework agreements displacing spot-market purchasing.
- Radar Systems:Phased array modernization across NATO defense programs requires broadband isolators with thermal stability exceeding commercial grades. EU AI Act conformity documentation is mandating traceable electromagnetic compatibility records for automotive radar integrators.
- Test Equipment:Mini-Circuits competes on catalog breadth for vector network analyzer and spectrum analyzer manufacturers.
- Broadcasting:Legacy transmitter installations face extended replacement cycles due to mechanical interface standardization gaps.
Telecommunications anchors current procurement volume. Radar systems are gaining share fastest.
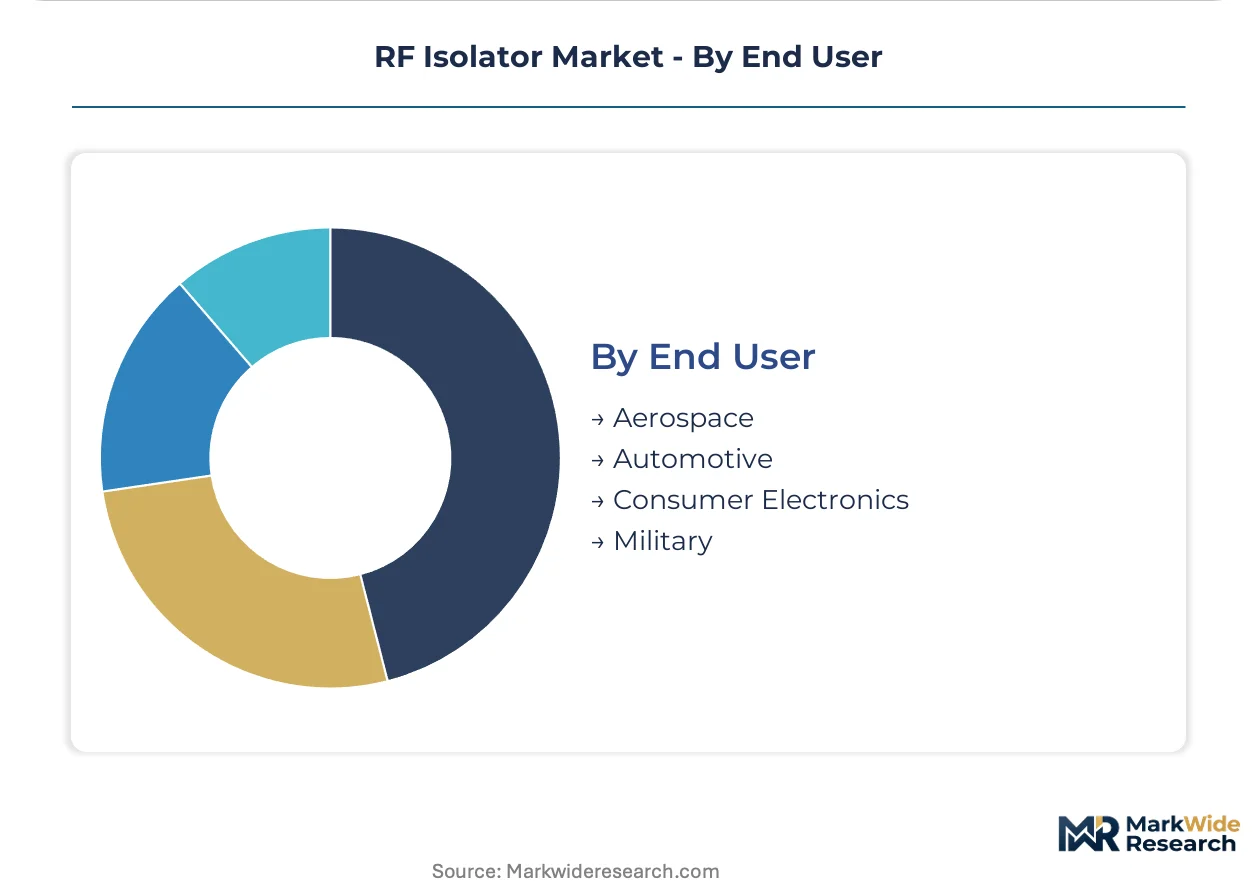
End User:
Military qualification cycles extend across years of environmental testing, while consumer electronics turns compress toward annual smartphone release cadences.
- Military:Defense prime contractors specify isolators for electronic warfare and radar platforms with operating temperature ranges spanning -55°C to +125°C. NATO phased array upgrades are elevating procurement for space-qualified reliability specifications where ferrite temperature stability commands premium positioning.
- Consumer Electronics:Smartphone RF front-end modules integrate miniature isolators alongside power amplifiers and switches, with South Korean and Chinese OEMs driving surface-mount ceramic volumes. EU CE marking and FCC certification fragmentation forces redundant testing cycles for multinational component suppliers.
- Aerospace:Satellite constellation ground terminals require high-power waveguide isolators with space-qualified heritage.
- Automotive:EU AI Act mandates are consolidating Tier 1 vendor pools to pre-certified specialty ceramic houses for autonomous sensor suites.
Military programs dominate value concentration. Consumer electronics is where volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in RF isolators track the geographic distribution of telecommunications infrastructure deployment and defense procurement budgets. Countries with active 5G spectrum auctions and satellite constellation programs dominate import demand for ferrite and waveguide variants.
United States
FCC spectrum reallocation mandates are compelling manufacturers to redesign isolators for higher frequency bands across sub-6 GHz and mmWave allocations. The FCC's electromagnetic emissions certification framework creates compliance obligations for components deployed in telecommunications infrastructure. Defense procurement concentrated in Massachusetts and California corridors sustains demand for broadband isolators optimized for radar frequencies.
China
Domestic 5G rollout and satellite constellation programs are consuming ferrite-based and waveguide isolator volumes at scale. MIIT enforces GB standards for base station equipment, creating divergent testing regimes that fragment certification pathways for multinational suppliers. State-backed carriers in Beijing and Shanghai are bundling multi-year supply contracts with technology transfer requirements.
Germany
Automotive radar integration for autonomous vehicle sensor suites is elevating procurement for ceramic isolators meeting functional safety standards. EU AI Act conformity assessment obligations mandate traceable electromagnetic compatibility documentation across automotive supply chains. Tier 1 electronics manufacturers in Bavaria and Baden-Württemberg are consolidating vendor pools to pre-certified specialty ceramic houses.
Japan
Yttrium iron garnet substrate production concentrates among specialty ceramic manufacturers serving military and satellite applications. METI industrial policy supports domestic ferrite material capabilities for defense radar and space-qualified reliability specifications. Industrial clusters in Nagoya and Osaka anchor precision ferrite component fabrication for regional telecommunications OEMs.
India
TRAI spectrum auction schedules and domestic PLI scheme incentives for 5G equipment manufacturing are opening procurement channels for cost-optimized surface-mount isolator variants. CEA grid connectivity standards indirectly shape telecommunications infrastructure deployment timelines. Electronics manufacturing services providers in Karnataka and Tamil Nadu are consolidating procurement around pre-qualified component houses.
RF Isolator Market Vendor Landscape
On the supply side, the industry is bifurcated between consolidated ferrite specialists and fragmented ceramic component assemblers. Japanese and Chinese manufacturers concentrate YIG substrate production, while South Korean and Taiwanese EMS providers dominate surface-mount integration. Two strategic archetypes prevail: vertically integrated material-to-module suppliers and catalog distributors competing on lead times. Competitive moves center on long-term framework agreements with volume commitments and accelerated supplier qualification cycles.
Within the premium-tier vector, Murata Manufacturing leverages ceramic component expertise to anchor supply relationships with base station OEMs. Qorvo occupies a position exemplifying broadband isolator specialization for defense radar frequencies. Mini-Circuits represents the catalog-breadth archetype competing aggressively on lead times for test equipment integrators.
| Leading Market Players |
|---|
| Murata Manufacturing |
| Skyworks Solutions |
| Qorvo |
| Broadcom |
| Analog Devices |
| NXP Semiconductors |
| TDK Corporation |
| Mini-Circuits |
| DiTom Microwave |
| Others |
Supply Flow & Price Mechanics
The Shanghai-to-Long Beach maritime corridor's container cost volatility feeds directly into RF isolator landed pricing, amplifying margin compression for ceramic substrate suppliers while Japanese ferrite houses leverage geographic proximity to Asian OEMs to sustain premium positioning against standard-tier competitors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on MIL-STD certification grade and volume scale commitments, with defense integrators absorbing 40-60% premiums for temperature-stable ferrite variants. Cost compression in the economy tier is intensifying because Chinese ceramic houses are flooding surface-mount segments with unqualified substitutes. Test equipment integrators exhibit highest price sensitivity, while satellite ground terminal contractors prioritize reliability over unit economics.
Supply Chain Analysis
Export-control restrictions on GaN-on-SiC technology under US Commerce Department regulations are fragmenting procurement pathways for hybrid isolator architectures. Yttrium iron garnet substrate production concentrates in Japan and China, with rare earth processing drawing from Chinese separation facilities. Single-source vulnerability pervades specialty ferrite magnet supply, particularly for permanent biasing components. Distribution runs through authorized distributor networks serving defense primes alongside direct OEM contracts for high-volume telecommunications procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF isolator procurement is evolving into a service-attach opportunity as calibration and field-replacement programs generate recurring revenue streams expanding faster than hardware shipments, particularly for waveguide installations with decade-long operational lifecycles.
For Market Incumbents: Insulate core ferrite competencies through backward integration into YIG substrate production, eliminating exposure to Chinese rare earth export quota volatility. Lock in multi-year framework agreements with Chinese state-owned carriers before qualification cycles compress further. Prioritize thermal management co-design partnerships with GaN-on-SiC amplifier suppliers to embed isolators into non-discrete procurement specifications. For New Entrants and Emerging Players: Build out India-facing manufacturing capacity to capture TRAI auction-driven procurement under PLI scheme incentives, positioning surface-mount ceramic variants for cost-optimized 5G small cell deployments. Target automotive radar integration as the most penetrable segment, exploiting EU AI Act certification gaps among incumbent European suppliers. Pursue qualification partnerships with South Korean EMS providers to bypass direct OEM sales cycle friction. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized ferrite material divisions lacking standalone defense sector focus. Five-to-ten year viability favors suppliers with captive rare earth sourcing and space-qualified heritage. Watch for MIIT GB standard harmonization announcements as the inflection signal triggering consolidation among multinational suppliers burdened by redundant certification costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into YIG Substrate Production | Captive supply of yttrium iron garnet eliminates Chinese rare earth quota exposure for Japanese and US defense suppliers. |
| Multi-Year Framework Agreement Expansion | Long-term volume commitments with China Mobile and China Telecom displace spot-market purchasing volatility. |
| GaN-on-SiC Thermal Co-Design Partnership | Joint development with Qorvo and Wolfspeed embeds isolators into non-discrete amplifier procurement specifications. |
| EU AI Act Certification Pre-Qualification | Batch-level electromagnetic compatibility documentation meets Tier 1 automotive radar supplier consolidation criteria. |
| India PLI Scheme Manufacturing Localization | Karnataka and Tamil Nadu production footprints capture TRAI auction-driven procurement with 15-20% cost advantage. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with RF component procurement managers, defense radar platform engineers, and telecommunications infrastructure planners; and secondary validation through FCC equipment authorization databases, MIIT GB standard filings, EU CE marking registries, and customs trade flow records. Bottom-up segment sizing triangulated against top-down OEM capex allocation patterns across the analysis window.
Forecast inputs span component type, technology architecture, application end-use, and geographic deployment cluster, with CAGRs derived from regression analysis against telecommunications infrastructure investment cycles and defense procurement budget trajectories. Phased array radar modernization timelines and satellite constellation launch schedules provided industry-specific demand elasticity parameters.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Japanese ceramic houses or sudden relaxation of GaN-on-SiC export controls would shift outcomes. Material shifts in Chinese rare earth export quota enforcement or FCC spectrum reallocation timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF Switches Market
RF Components
RF Microwave MLCC Market
RF Components
RF Passive Component Market
RF Components
Japan Small Signal Transistor Market
RF Components
China Small Signal Transistor Market
RF Components
High Reliability Oscillators Market
RF Components
Radio Frequency (RF) Signal Generators Market
RF Components
Radio Frequency Front End Module Market
RF Components
RF Tester Market
RF Components
Stand-Alone Radio Receivers Market
RF Components
Noise Suppression Components Market
RF Components
RF Power Amplifiers Market
RF Components
Gan RF Semiconductor Devices Market
RF Components
RFID Antenna Market
RF Components
RF Gan Market
RF Components
Dielectric Resonator Market