
 RF Acoustic Wave Filters Market | 2026-2036
RF Acoustic Wave Filters Market Size, Share, and Industry Trends Forecast 2026-2036
RF Acoustic Wave Filters Market Analytics
Filter module customization revenue is fragmenting across foundry partners and IDM houses as smartphone OEMs disaggregate RF front-end procurement. Murata Manufacturing Co., Ltd. sustains dominance in SAW filter supply through captive piezoelectric substrate production. Qorvo, Inc. competes aggressively in BAW technology for carrier aggregation architectures. Broadcom Inc. leverages its FBAR patent estate to control premium filter slots in flagship handsets.
RF acoustic wave filters are electromechanical devices that convert electrical signals into acoustic waves within piezoelectric substrates such as lithium niobate (LiNbO3) or aluminum nitride, then reconverting to electrical form after frequency-selective propagation; they operate at frequencies from hundreds of megahertz to over six gigahertz with insertion loss below three decibels in optimized designs. Their primary purpose is to isolate desired frequency bands while rejecting adjacent-channel interference in wireless transceivers. Bulk acoustic wave technology now captures the highest-margin slots in 5G infrastructure due to superior quality factors and thermal stability. Surface acoustic wave variants retain volume leadership in sub-3 GHz consumer electronics where cost sensitivity dominates engineering trade-offs. MEMS-based approaches are gaining design wins in sensing applications that require co-integration with CMOS logic.
The FCC in the United States and ETSI in Europe both enforce spurious emission limits that tighten filter rejection requirements at band edges, directly shaping R&D priorities for sharper roll-off characteristics. China's MIIT mandates domestic testing certification for all cellular modules, creating a parallel compliance pathway that filters must satisfy before base station or handset integration. South Korea's MSIT spectrum auctions for 28 GHz and sub-6 GHz bands have accelerated local demand for temperature-compensated BAW devices. Stakeholders must track how national spectrum allocation timelines and associated certification deadlines cascade into foundry loading decisions and inventory positioning across the RF supply chain.
Market Dynamics
Smartphone OEM disaggregation of RF front-end procurement is compressing filter design cycles while fragmenting revenue across foundry partners and integrated device manufacturers, forcing component suppliers to reconfigure pricing and certification strategies simultaneously.
Growth Catalysts
- 5G sub-6 GHz and mmWave deployment:Smartphone OEMs now specify acoustic wave filters as standard front-end architecture for these bands, creating sustained pull from handset production lines.
- FCC spectrum reallocation rules:The United States framework compresses design cycles for filter manufacturers, accelerating qualification timelines for new band definitions.
- Domestic base station buildout in China:MIIT-mandated infrastructure deployment absorbs the largest volume of BAW and SAW components globally, concentrating demand in a single manufacturing ecosystem.
Market Restraints
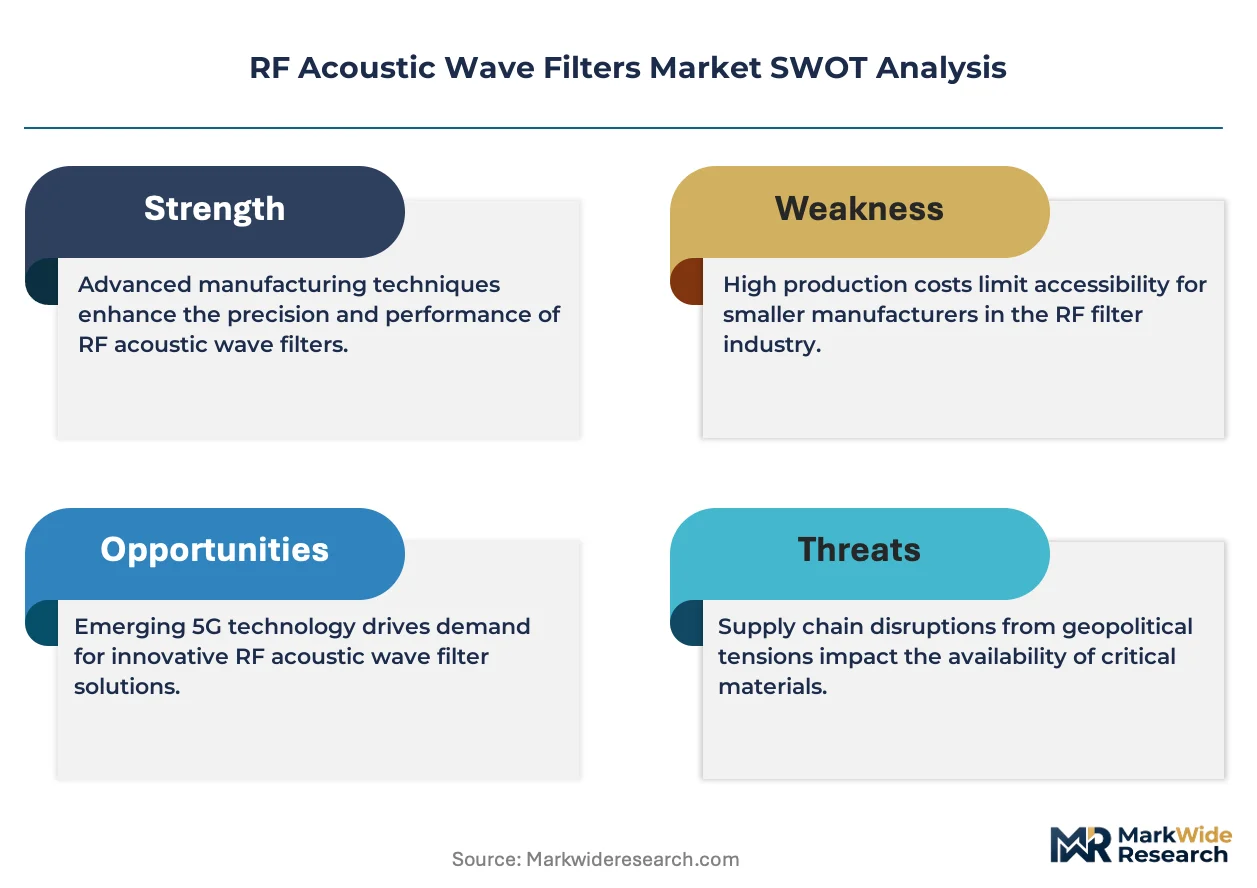
- Piezoelectric substrate supply concentration:Captive lithium niobate and aluminum nitride production concentrates among Japanese and Chinese material suppliers, creating input bottleneck risk.
- Thermal stability requirements in carrier aggregation:BAW technology faces fundamental material constraints when operating above six gigahertz with simultaneous multi-band transmission.
- MIIT domestic testing certification:China's parallel compliance pathway adds six to nine months to module qualification, creating regulatory friction for non-Chinese filter houses.
Strategic Opportunities
- Temperature-compensated BAW for South Korean 28 GHz:MSIT spectrum auctions for millimeter-wave bands accelerate local demand for thermally stable filter architectures.
- MEMS-CMOS co-integration for sensing:Converging microelectromechanical systems with logic processes opens design wins in automotive and industrial IoT transceivers.
- Foundry loading optimization through ETSI spurious emission alignment:European tightening of rejection requirements at band edges creates premium slots for sharper roll-off filter designs.
Industry Challenges
- Piezoelectric thin-film deposition expertise:The specialized skill set for aluminum nitride sputtering and lithium niobate wafer processing concentrates among aging engineering cohorts in Japan and Germany.
- Multi-jurisdiction certification parallelism:Simultaneous FCC, ETSI, and MIIT testing requirements force duplicate capital expenditure on characterization equipment and laboratory accreditation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Acoustic Wave Filters Market |
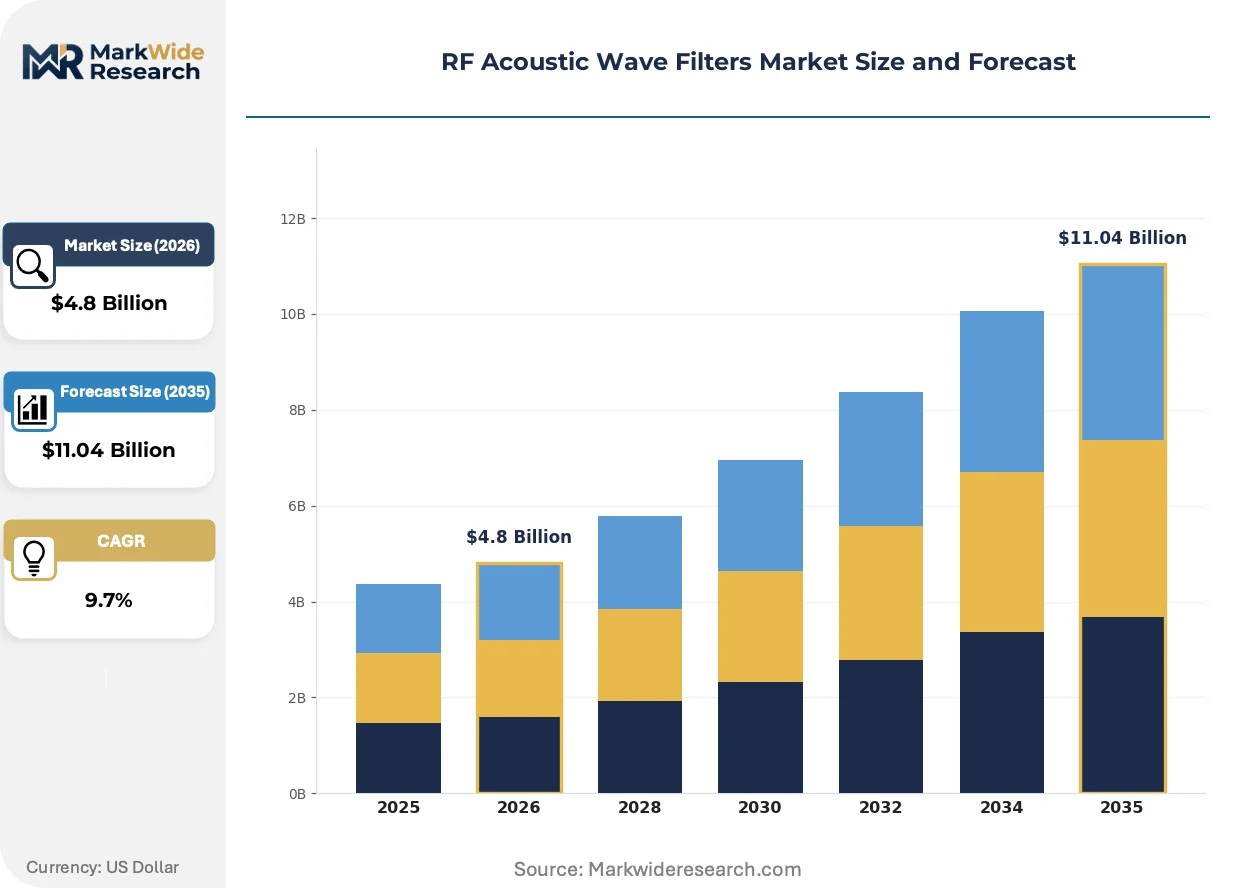
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Surface Acoustic Wave, Bulk Acoustic Wave, Resonators, Transducers End User: Telecommunications, Consumer Electronics, Automotive, Aerospace Application: Signal Processing, Frequency Control, Wireless Communication, Sensing Technology: LiNbO3, Quartz, Ceramic, MEMS |
| Companies Covered | Broadcom Inc., Murata Manufacturing Co., Ltd., Qorvo, Inc., Skyworks Solutions, Inc., TDK Corporation, Taiyo Yuden Co., Ltd., Kyocera AVX Components Corporation, Tai-Saw Technology Co., Ltd., Akoustis Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Acoustic Wave Filters Market Evolving Landscape
Filter architecture is converging with system-level integration demands as 5G complexity forces acoustic wave technology into tighter co-design with power amplifiers and antenna tuners, reshaping how OEMs evaluate supplier capabilities.
Film bulk acoustic resonator technology is virtualizing traditional discrete filter banks through monolithic integration of multiple frequency responses on single die. Flagship handset programs now specify FBAR-based multiplexers to reduce component count and board area. This consolidation is virtualizing the competitive landscape by rewarding patent-rich suppliers with premium socket access while marginalizing second-tier houses lacking FBAR fabrication depth.
ETSI's progressive tightening of spurious emission limits across European cellular bands is mandating steeper filter roll-off characteristics at adjacent channel edges. Filter manufacturers are redirecting R&D toward resonator coupling optimization and substrate material purity to meet these specifications. High-performance BAW designs for carrier aggregation architectures face the most acute certification pressure, with European OEMs now requiring pre-compliance documentation at the quotation stage.
Module procurement is fragmenting as smartphone OEMs disaggregate RF front-end sourcing across multiple qualified suppliers rather than single-sourcing integrated solutions. This pattern concentrates most visibly in Chinese handset production, where domestic foundries and IDM houses compete for individual filter slots within discretized bill-of-materials. The shift compresses supplier margins while elevating technical service and rapid customization as primary differentiation vectors over pure performance metrics.
RF Acoustic Wave Filters Market Segmentation
RF acoustic wave filter suppliers configure product roadmaps around four intersecting dimensions: component physics, end-user performance requirements, application-specific frequency demands, and substrate material constraints. Each dimension carries distinct margin profiles and certification burdens that reshape competitive positioning.
Component:
Cost tier stratification separates high-performance BAW architectures from volume-optimized SAW alternatives, with resonators and transducers occupying intermediate value positions based on integration depth.
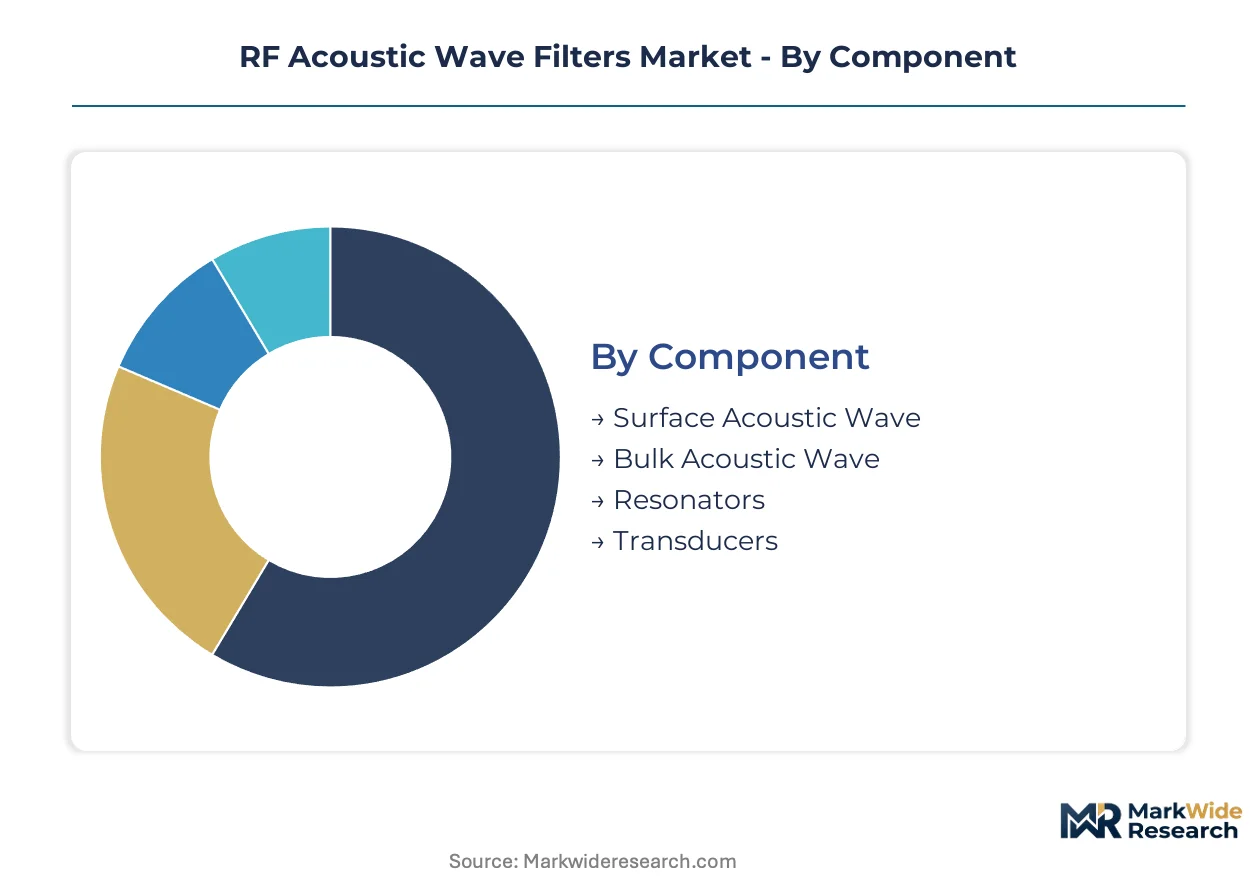
- Surface Acoustic Wave:Lithium niobate or quartz substrates propagate acoustic waves along the crystal surface, enabling multi-band filtering at sub-3 GHz frequencies. Chinese handset production lines absorb the largest SAW volumes where cost sensitivity dominates engineering trade-offs.
- Bulk Acoustic Wave:Aluminum nitride thin-film resonators trap acoustic energy vertically between electrode stacks, delivering quality factors above 2000 for carrier aggregation architectures. South Korean OEMs specify temperature-compensated BAW variants for 28 GHz millimeter-wave deployment.
- Resonators:Piezoelectric elements establish frequency reference points within oscillator circuits. Automotive telematics modules require AEC-Q200 qualified resonator components.
- Transducers:Bidirectional electromechanical converters interface between electrical and acoustic domains. Industrial sensing applications drive niche demand for high-linearity transducer designs.
Surface Acoustic Wave commands the established base. The steepest expansion runs through Bulk Acoustic Wave.
End User:
Application maturity varies sharply across verticals, with telecommunications infrastructure demanding decade-long reliability guarantees while consumer electronics cycles compress below eighteen months.
- Telecommunications:Base station and small cell deployment requires filters with thermal stability across -40°C to +85°C operating ranges. China's MIIT-mandated infrastructure buildout concentrates the largest BAW procurement volumes globally.
- Consumer Electronics:Smartphones, tablets, and wearables specify acoustic wave filters for 5G sub-6 GHz and mmWave front-end modules. FCC spectrum reallocation rules in the United States compress design cycles for handset-integrated components.
- Automotive:V2X communication and GNSS positioning systems require AEC-Q100 qualified filters with vibration resistance. German automotive suppliers specify BAW-based multiplexers for connected vehicle architectures.
- Aerospace:Satellite communication and radar systems demand radiation-hardened filters with hermetic packaging. Military qualification pathways extend development timelines significantly.
Telecommunications absorbs the highest absolute volumes. Consumer Electronics is climbing the fastest as 5G handset penetration accelerates replacement cycles.
Application:
Functional use cases determine filter specification priorities, with wireless communication dominating unit economics while sensing applications reward co-integration capabilities.
- Signal Processing:Intermediate frequency filtering and image rejection in receiver chains require sharp roll-off characteristics. European OEMs now demand pre-compliance documentation at the quotation stage under ETSI spurious emission limits.
- Frequency Control:Oscillator stabilization and clock generation depend on resonator-based reference circuits. Quartz substrate variants retain dominance in precision timing applications.
- Wireless Communication:Transmitter and receiver front-ends isolate desired bands while rejecting adjacent-channel interference. Carrier aggregation architectures multiply filter count per handset, expanding the addressable component market.
- Sensing:MEMS-acoustic hybrid devices detect pressure, temperature, and chemical composition through resonant frequency shifts. Automotive and industrial IoT transceivers drive design wins for CMOS-co-integrated sensing filters.
Wireless Communication holds the revenue concentration. Sensing is gaining share fastest through MEMS convergence.
Technology:
Substrate material selection locks in performance ceilings and supply chain dependencies, with lithium niobate and aluminum nitride production concentrating among Japanese and Chinese suppliers.
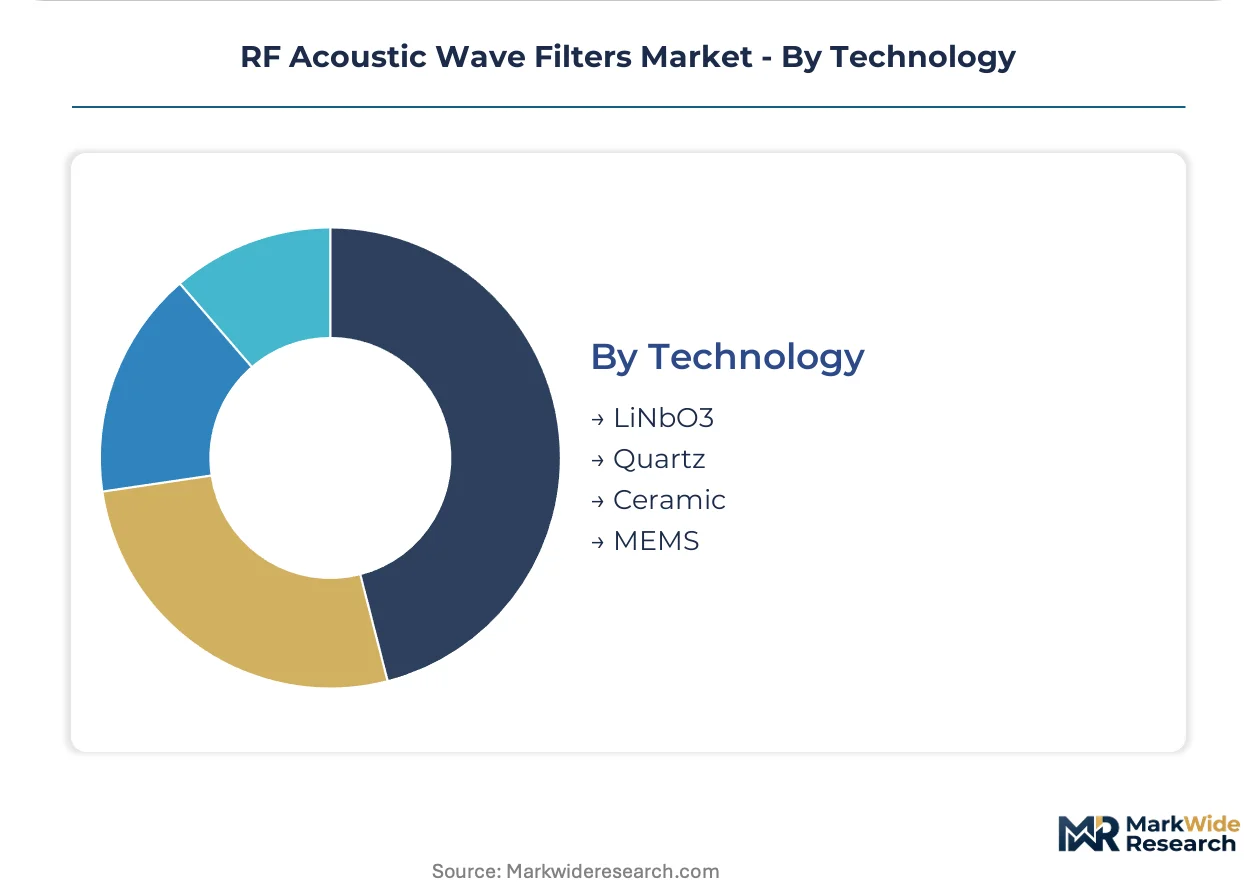
- LiNbO3:Lithium niobate substrates deliver high electromechanical coupling coefficients for wideband SAW filters. Japanese material houses control captive wafer production, creating input bottleneck risk for non-integrated filter manufacturers.
- Quartz:Crystalline silicon dioxide provides exceptional temperature stability for precision oscillators. German engineering cohorts retain specialized expertise in quartz wafer processing.
- Ceramic:Lead zirconate titanate and related compositions enable high-power handling in base station applications. Domestic Chinese ceramic suppliers serve local infrastructure deployment.
- MEMS:Microelectromechanical systems fabricate resonant structures through silicon foundry processes, enabling CMOS logic co-integration. South Korean foundries are developing MEMS-acoustic hybrid platforms for sensing applications.
LiNbO3 anchors the volume base. MEMS shows the steepest expansion trajectory through semiconductor process convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: China absorbs BAW and SAW components through domestic infrastructure buildout, while South Korea and the United States prioritize premium temperature-compensated architectures for millimeter-wave deployment.
China
MIIT-mandated base station deployment and handset manufacturing concentrate the world's largest BAW and SAW procurement volumes. The ministry's domestic testing certification creates a parallel six-to-nine-month compliance pathway that filters must satisfy before integration. Shenzhen and Dongguan manufacturing clusters absorb the majority of component output for both telecommunications infrastructure and consumer electronics export programs.
South Korea
MSIT spectrum auctions for 28 GHz millimeter-wave bands accelerate local demand for thermally stable BAW devices in flagship smartphone programs. The regulator's aggressive timeline for sub-6 GHz commercialization compresses filter qualification cycles for domestic OEMs. Seoul and Suwon technology corridors host concentrated RF front-end design activity tied to carrier aggregation architectures.
United States
FCC spectrum reallocation rules compress design cycles for filter manufacturers serving 5G sub-6 GHz and mmWave handset specifications. The commission's spurious emission limits tighten rejection requirements at band edges, directly shaping R&D priorities. Texas and California engineering centers drive architectural innovation for carrier aggregation and multiplexed filter banks.
Japan
METI-supported development of piezoelectric substrate technologies sustains captive lithium niobate and aluminum nitride production among domestic material houses. The ministry's industrial technology grants reinforce specialized thin-film deposition expertise concentrated in aging engineering cohorts. Kyoto and Osaka manufacturing regions retain critical wafer processing capabilities for high-coupling-coefficient SAW substrates.
Germany
ETSI-enforced spurious emission limits across European cellular bands mandate steeper filter roll-off characteristics, creating premium slots for sharper designs. The framework's progressive tightening redirects manufacturer R&D toward resonator coupling optimization. Munich and Stuttgart automotive supplier clusters specify AEC-Q100 qualified BAW multiplexers for connected vehicle architectures.
RF Acoustic Wave Filters Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where patent-rich integrated device manufacturers control premium sockets while foundry partners capture volume customization revenue. The vendor base organizes around three strategic archetypes: captive substrate producers, FBAR patent holders, and fabless design houses. Consolidation pressure runs through M&A activity targeting aluminum nitride deposition expertise and strategic partnerships disaggregating RF front-end procurement across multiple qualified suppliers.
Among Japanese integrated device manufacturers, Murata Manufacturing Co., Ltd. and Taiyo Yuden Co., Ltd. exemplify the captive-production archetype through in-house piezoelectric substrate control. Broadcom Inc. anchors the premium-tier vector as a representative of FBAR patent estate leverage. These three occupy positions that reward fabrication depth with socket access while marginalizing competitors lacking resonator integration capabilities.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Murata Manufacturing Co., Ltd. |
| Qorvo, Inc. |
| Skyworks Solutions, Inc. |
| TDK Corporation |
| Taiyo Yuden Co., Ltd. |
| Kyocera AVX Components Corporation |
| Tai-Saw Technology Co., Ltd. |
| Akoustis Technologies, Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese lithium niobate wafer fabrication is compressing foundry margins while concentrating pricing power among Japanese captive substrate producers. This utilization asymmetry forces filter manufacturers to absorb input cost volatility or surrender socket access to vertically integrated competitors.
Pricing Analysis
Long-term offtake contracts dominate procurement between smartphone OEMs and tier-one filter suppliers, locking in volume commitments against price stability guarantees. Three-tier pricing structure across premium, standard, and economy levels separates FBAR-based multiplexers from generic SAW components and unqualified second-source alternatives. Pricing pressure stems from OEM disaggregation of RF front-end sourcing, which fragments volume across multiple qualified suppliers. Chinese domestic foundries exhibit the highest price sensitivity, while South Korean flagship programs tolerate premium positioning for temperature-compensated BAW architectures.
Supply Chain Analysis
Upstream feedstock concentration in Japanese lithium niobate and Chinese aluminum nitride production anchors the filter supply chain. Japanese material houses and Chinese state-backed substrate foundries draw from captive piezoelectric crystal growth operations. Single-source vulnerability concentrates in high-purity aluminum nitride sputtering targets, where two Japanese suppliers control global output. Distribution runs through Shenzhen and Dongguan manufacturing clusters for handset integration, with separate channels serving telecommunications infrastructure deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics logic is displacing component-level competition as 5G complexity forces acoustic wave filters into mandatory co-design with power amplifiers and antenna tuners. The MIIT certification ecosystem in China and the FBAR patent estate controlled by US suppliers are creating interoperability barriers that reshape competitive boundaries.
For Market Incumbents: Pre-empt MEMS-CMOS convergence by acquiring thin-film piezoelectric deposition expertise before South Korean foundries scale hybrid platforms. Defend socket access through backward integration into lithium niobate wafer production, neutralizing the substrate bottleneck threat from Japanese material houses. Accelerate MIIT pre-certification investments to compress the six-to-nine-month compliance window that disadvantages non-Chinese competitors.
For New Entrants and Emerging Players: Establish a beachhead in automotive V2X sensing applications where AEC-Q200 qualification requirements filter out commodity SAW suppliers. Target industrial IoT transceivers for MEMS-acoustic hybrid designs, exploiting the co-integration capability gap among legacy filter houses. Pursue foundry partnerships with Chinese domestic IDMs as the fastest path to handset socket access without FBAR patent exposure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across BAW fabrication as multi-band carrier aggregation architectures demand thicker aluminum nitride stacks and precision electrode patterning. The five-to-ten-year viability window favors acquisition targets with captive substrate production or established MIIT certification pathways. Watch South Korean MSIT spectrum auction timelines as the inflection signal for temperature-compensated BAW demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Patent Estate Licensing | FBAR intellectual property access unlocks premium handset socket participation against vertically integrated competitors. |
| Substrate Backward Integration | Captive lithium niobate production neutralizes Japanese material house pricing power and supply interruption risk. |
| MIIT Certification Pre-Investment | Early compliance with China's domestic testing pathway compresses module qualification timelines for infrastructure deployment. |
| MEMS-CMOS Foundry Partnership | South Korean hybrid platform access enables sensing application expansion beyond traditional wireless communication markets. |
| Carrier Aggregation Architecture Co-Design | Deep OEM engagement on multiplexed filter banks secures multi-year platform commitments against second-source competition. |
Research Methodology
Operator-level perspectives from RF front-end procurement managers, foundry operations directors, and telecommunications infrastructure planners anchored the qualitative base. Primary interviews with smartphone OEM supply chain executives, piezoelectric substrate process engineers, and MIIT certification laboratory directors were cross-validated against FCC filing databases, ETSI harmonized standard publications, and SEC 10-K disclosures from listed filter manufacturers. Bottom-up unit demand modeling and top-down value chain triangulation converged on segment-level estimates.
Scenario-bracketing around aggressive versus conservative 5G handset replacement cycles shaped the projection framework across the analysis window. Segmentation dimensions included filter physics type, substrate material technology, end-use vertical, and regional regulatory cluster. CAGRs were derived from installed base evolution and content-per-device expansion in carrier aggregation architectures. Forecast inputs incorporated MIIT base station deployment schedules and MSIT spectrum auction timelines.
Stress conditions across aluminum nitride supply disruption, FCC spectrum reallocation delays, and Chinese domestic certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about substrate yield improvements and OEM disaggregation momentum. Cross-checking against IHS Markit RF component bill-of-materials data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Power Amplifier Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
Smartphone RF Power Amplifier Market
RF Components
Millimeter Wave Equipment Market
RF Components
Global RF Power Semiconductor Market
RF Components
Stand-Alone Radio Receivers Market
RF Components
High Reliability Oscillators Market
RF Components
Japan Small Signal Transistor Market
RF Components
Radio Frequency Filters Market
RF Components
RF Power Detector Market
RF Components
RF and Microwave Diodes Market
RF Components
RF Switches Market
RF Components
RF Duplexer Market
RF Components
RF Power Amplifiers Market
RF Components
Wireless Module Market
RF Components
High-Frequency RF Evaluation Board Market