
 Smart Airport Market | 2026-2036
Smart Airport Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Airport Market Intelligence
The EU Green Deal is realigning capital allocation toward net-zero terminal infrastructure across European hubs. Honeywell International Inc. leverages its building automation portfolio to capture retrofit cycles in aging facilities. Siemens AG anchors European market presence through integrated energy management and digital twin deployments for major hub operators. Thales Group competes on biometric identity platforms that streamline passenger flow while meeting EASA security benchmarks.
Smart airports integrate IoT sensors, AI-driven analytics, and cloud-native platforms to optimize terminal operations, aircraft turnaround, and passenger experience through real-time data orchestration. Automation within the technology segment leads capital deployment as operators target labor cost reduction and 24/7 operational continuity. Passenger processing applications command the dominant share of solution spending, though baggage handling systems represent the fastest-growing application category as RFID and computer vision reduce mishandled luggage rates.
FAA NextGen standards, EASA aerodrome certification requirements, and EU AI Act risk classifications for biometric surveillance collectively shape procurement specifications and vendor qualification criteria. The EU F-Gas Regulation further constrains HVAC system choices in terminal expansions, directing demand toward low-global-warming-potential alternatives. Stakeholders must weigh interoperability obligations against single-vendor platform lock-in as regulatory fragmentation deepens between North American and European compliance frameworks.
Market Dynamics
Post-pandemic operational mandates from aviation authorities are forcing terminal operators to rebuild passenger processing around contactless biometric infrastructure rather than traditional document-based checkpoints.
Growth Catalysts
- FAA NextGen mandates:The Federal Aviation Administration's modernization timeline compels US hub operators to replace legacy surveillance radar with satellite-based precision approach systems.
- Biometric identity verification:Facial recognition boarding gates at Dubai International Airport and Singapore Changi demonstrate throughput gains that justify capital redeployment from manual check-in desks.
- EU Green Deal retrofit cycles:Terminal energy performance certificates now condition access to concessional financing for expansion projects at Amsterdam Schiphol and Frankfurt.
Market Restraints
- Semiconductor supply concentration:Edge AI processors for passenger analytics depend on TSMC's advanced node capacity in Taiwan, creating single-source vulnerability for biometric platform vendors.
- F-Gas Regulation compliance costs:The EU's phasedown of hydrofluorocarbon refrigerants forces simultaneous HVAC replacement and building management system upgrades in 1990s-era terminals.
- Cyber-physical integration complexity:Converging IT and OT networks expose baggage handling and fueling systems to ransomware vectors that insurers now exclude from standard coverage.
Strategic Opportunities
- India's UDAN regional connectivity scheme:Greenfield airport development in Tier-2 cities bypasses legacy infrastructure constraints and permits native digital twin architecture.
- Predictive maintenance convergence:Vibration sensors on jet bridges combined with natural language processing of maintenance logs compress mean time to repair for critical passenger boarding equipment.
- EU AI Act biometric exemptions:Real-time passenger flow optimization systems that anonymize data streams qualify for reduced compliance burdens versus identity verification applications.
Industry Challenges
- OT cybersecurity skill scarcity:Terminal operators compete with energy and manufacturing sectors for industrial control system specialists capable of segmenting legacy SCADA from IP networks.
- Interoperability certification delays:EASA's aerodrome design standards and FAA's airport design engineering requirements diverge on biometric data retention periods, forcing dual-track product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Airport Market |
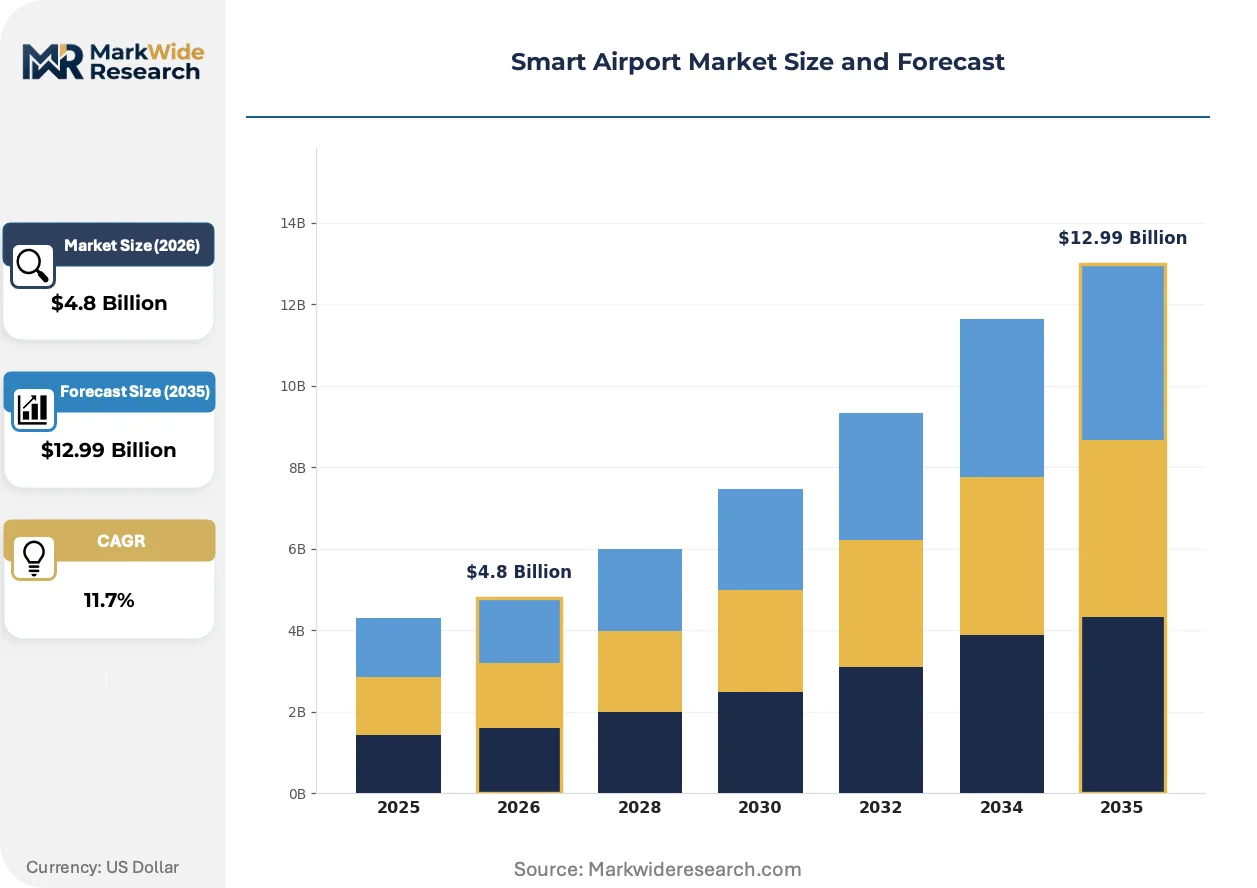
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, AI, Cloud Computing, Automation Application: Passenger Processing, Baggage Handling, Security, Flight Operations End User: Aviation Authorities, Airlines, Ground Handlers, Security Agencies Solution: Self-Check-in Kiosks, Digital Signage, Smart Luggage, Analytics Platforms |
| Companies Covered | Honeywell International Inc., Siemens AG, IBM Corporation, Cisco Systems Inc., SITA, Thales Group, Amadeus IT Group SA, Huawei Technologies Co. Ltd., Indra Sistemas S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Airport Market Strategic Shifts & Innovations
Cloud-native operational platforms are supplanting on-premise terminal management systems as operators prioritize elastic compute for irregular operations and demand spikes.
Computer vision baggage tracking is overtaking laser barcode scanning as the primary mishandled luggage reduction technology. Major hub operators in Germany and the United States are deploying camera arrays with neural network classifiers to identify bag orientation and damage in real time. This shift is compressing capital allocation toward GPU-accelerated edge servers and away from fixed infrastructure readers.
The EU AI Act's risk classification framework for biometric surveillance is redrawing procurement specifications for passenger processing vendors. Systems deployed at Schengen area hubs must now demonstrate proportionality assessments and human oversight protocols to qualify for operational authorization. North American operators are observing these compliance precedents to anticipate potential FAA harmonization.
Airline procurement departments are unbundling smart airport solution contracts into separate hardware, software, and managed service components. This disaggregation allows low-cost carriers to access predictive analytics through subscription models rather than capital expenditure. The pattern is most pronounced among European point-to-point operators seeking to match network carrier service levels without equivalent infrastructure balance sheets.
Smart Airport Market Segmentation
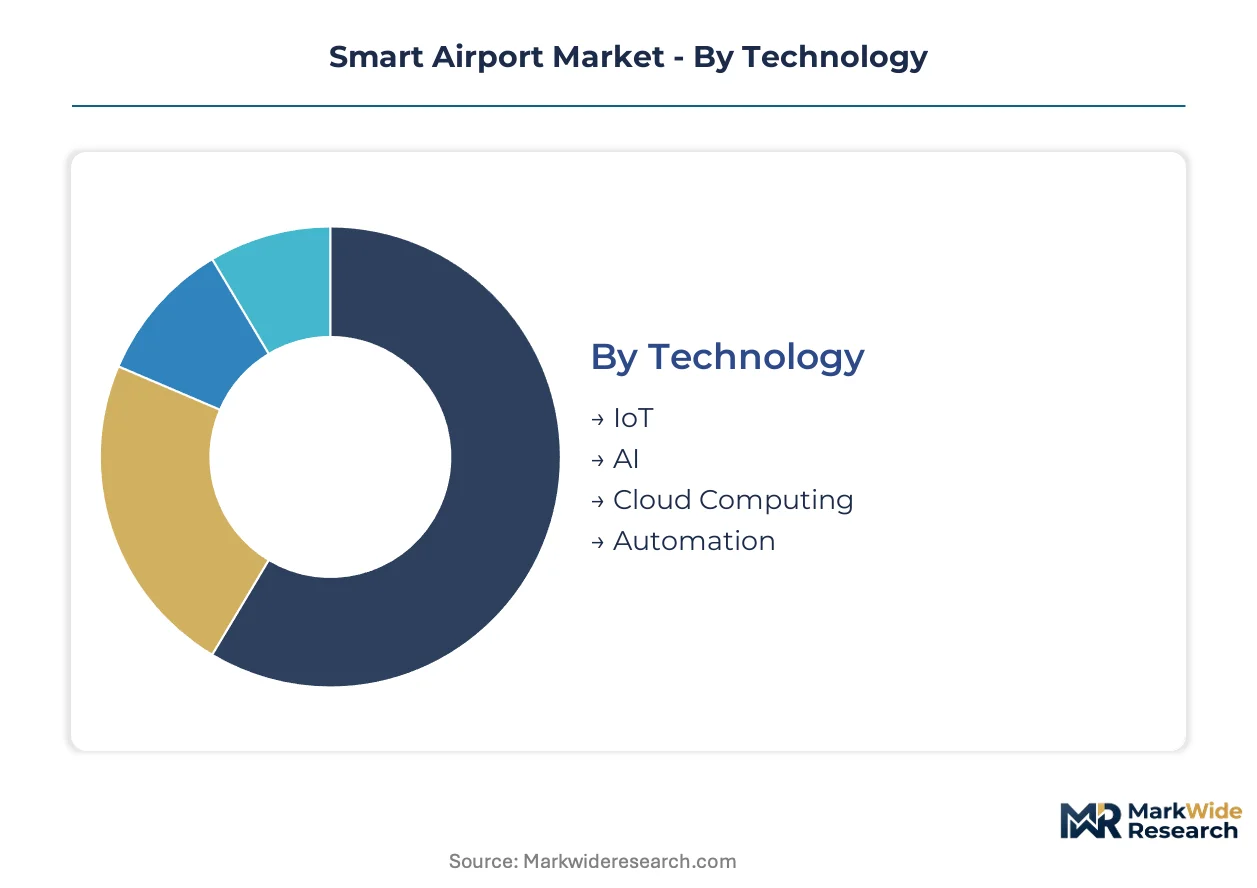
Smart airport procurement decisions split across technology maturity, operational function, and stakeholder risk appetite. Vendors must architect offerings that map precisely to these axes or face displacement by modular competitors.
Technology:
Processing architecture determines integration complexity and cybersecurity exposure for terminal operators.
- IoT:Sensor networks for environmental monitoring, asset tracking, and passenger flow measurement operate across unlicensed spectrum bands. Deployment concentrates in baggage handling tunnels and apron fueling zones where FAA NextGen mandates require real-time equipment status reporting.
- AI:Neural network classifiers power facial recognition gates, predictive maintenance algorithms, and anomaly detection for security screening. Demand clusters at Dubai International and Singapore Changi where throughput metrics justify GPU-accelerated edge infrastructure expenditure.
- Cloud Computing:Elastic compute resources support irregular operations and demand spikes without on-premise overprovisioning. European operators favor sovereign cloud deployments to satisfy GDPR data residency requirements.
- Automation:Robotic process automation and autonomous ground vehicles reduce labor dependency for 24/7 operations. Implementation spreads across cargo terminals and remote stand busing where union constraints are weakest.
AI leads on scale; automation leads on momentum.
Application:
Functional priority reflects where operational failures generate maximum passenger impact and regulatory exposure.
- Passenger Processing:Biometric identity verification, self-service check-in, and automated boarding gates streamline terminal flow. This category commands dominant solution spending as airlines eliminate manual check-in desks.
- Baggage Handling:RFID tracking, computer vision sorting, and automated retrieval systems reduce mishandled luggage rates. This segment gains share fastest as neural network classifiers displace laser barcode scanning.
- Security:CT-based cabin baggage screening and automated threat recognition platforms address evolving EASA and TSA checkpoint standards. Procurement accelerates where legacy equipment reaches end-of-service life.
- Flight Operations:Surface movement guidance, collaborative decision-making platforms, and digital NOTAM processing optimize aircraft turnaround. Adoption concentrates at slot-constrained hubs where minutes determine schedule integrity.
Passenger processing leads on scale; baggage handling leads on momentum.
End User:
Procurement authority and budget ownership vary sharply across stakeholder categories with divergent compliance obligations.
- Aviation Authorities:National regulators and airport operators specify system standards and certification requirements. Investment flows through FAA NextGen and EASA aerodrome modernization programs.
- Airlines:Network and low-cost carriers deploy passenger-facing systems to differentiate service levels and reduce ground handling costs. Subscription-based analytics access enables capability parity without capital balance sheet strain.
- Ground Handlers:Third-party service providers invest in turnaround optimization and cargo automation to defend contract renewals. Margin pressure drives selective technology deployment at highest-volume stations.
- Security Agencies:Government screening authorities mandate equipment specifications and data retention protocols. EU AI Act risk classifications reshape biometric surveillance procurement at Schengen area hubs.
Aviation authorities lead on scale; airlines lead on momentum.
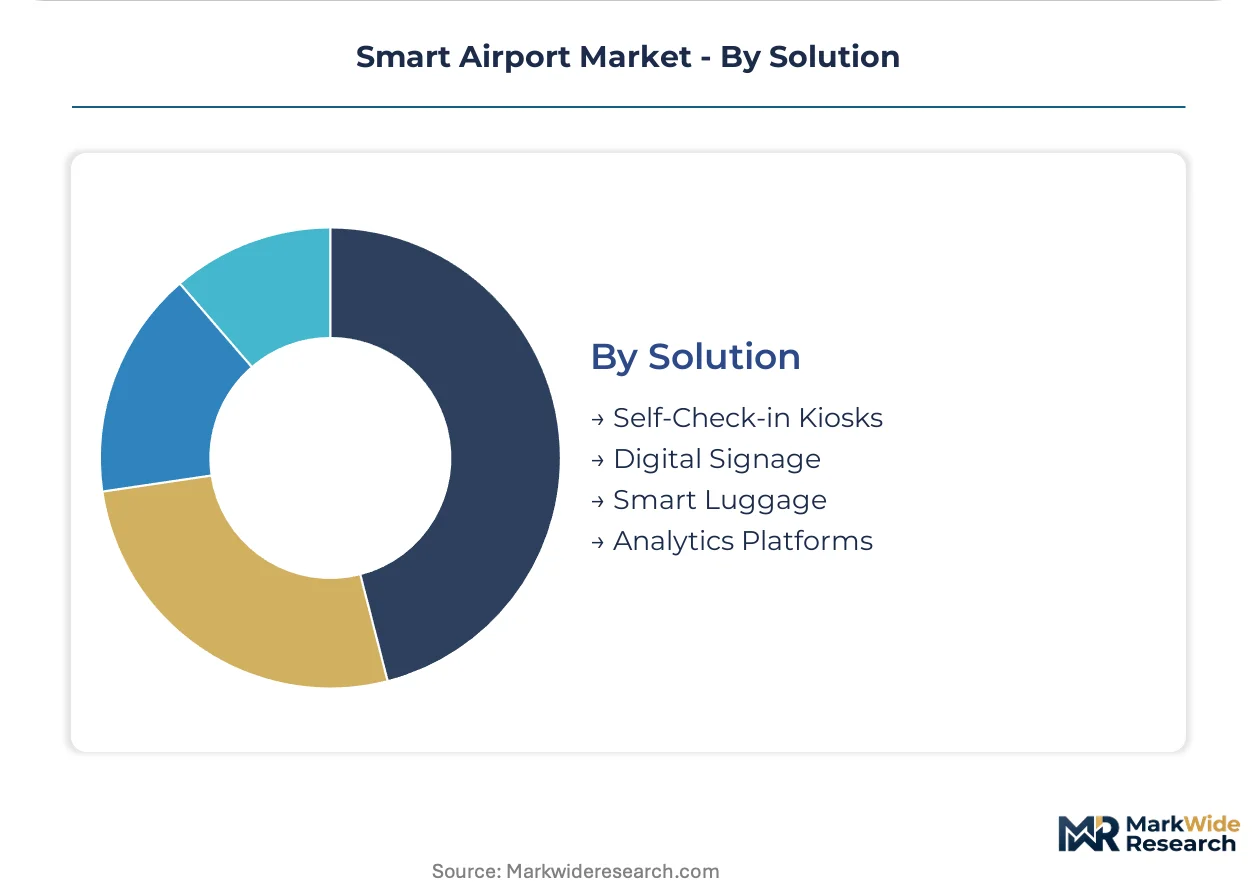
Solution:
Hardware-software-service bundling decisions reflect capital availability and internal IT capability across operator tiers.
- Self-Check-in Kiosks:Touchscreen terminals with biometric enrollment, boarding pass printing, and bag tag issuance functions. Deployment peaks where legacy counter infrastructure reaches replacement cycle.
- Digital Signage:Wayfinding displays, gate information systems, and advertising networks with centralized content management. Demand concentrates in retail-heavy terminals seeking concession revenue optimization.
- Smart Luggage:GPS-enabled bags with integrated tracking, digital locks, and weight sensors for self-service compliance. Growth tracks premium passenger segment expansion and airline ancillary revenue strategies.
- Analytics Platforms:Cloud-native operational dashboards integrating passenger flow, asset utilization, and energy consumption data. Adoption accelerates where operators unbundle contracts to access predictive capabilities through subscription models.
Self-check-in kiosks lead on scale; analytics platforms lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aviation infrastructure modernization traces its institutional roots to post-war US federal investment in instrument landing systems, establishing regulatory templates later adopted across NATO-aligned jurisdictions. Contemporary smart airport deployment patterns reflect this historical lineage while diverging across national procurement frameworks.
United States
FAA NextGen satellite-based precision approach mandates drive sustained infrastructure replacement cycles at Atlanta Hartsfield-Jackson and Chicago O'Hare. The Infrastructure Investment and Jobs Act channels funding toward terminal automation and surface movement guidance upgrades. Dallas-Fort Worth anchors southwestern hub modernization with integrated biometric boarding corridors and predictive baggage handling deployments.
Germany
Frankfurt and Munich operators face EU F-Gas Regulation deadlines forcing simultaneous HVAC replacement and building management system overhauls in 1990s-era terminals. The national climate protection program conditions airport expansion permits on energy performance certificate benchmarks. Bavaria's industrial automation cluster supplies digital twin architecture for Munich's second terminal retrofit.
United Arab Emirates
Dubai International's facial recognition boarding gates demonstrate throughput gains that justify capital redeployment from manual processing infrastructure. The General Civil Aviation Authority mandates biometric identity verification standards for all major hub expansions. Abu Dhabi integrates sovereign cloud platforms with passenger analytics to satisfy data residency requirements under federal cybersecurity frameworks.
Singapore
Changi Airport Group's Terminal 5 development bypasses legacy constraints through native digital twin architecture and autonomous ground vehicle corridors. The Civil Aviation Authority of Singapore's Smart Airport Masterplan specifies AI-driven baggage sorting and computer vision threat detection procurement timelines. The city-state's electronics manufacturing ecosystem supplies edge computing hardware for regional hub automation rollouts.
India
The UDAN regional connectivity scheme funds greenfield airport development in Tier-2 cities permitting uncabled sensor network deployment. The Airports Authority of India mandates biometric boarding infrastructure at all Category X and Y facilities by 2027. Karnataka's technology corridor supplies IoT platform integration for Bangalore Kempegowda's terminal expansion and predictive maintenance systems.
Smart Airport Market Key Industry Players
Capital-heavy building automation conglomerates compete with asset-light software specialists for terminal operator procurement contracts. The vendor base clusters around three strategic archetypes: diversified industrial technology holding companies with HVAC and security portfolios; telecommunications infrastructure providers leveraging 5G private network deployments; and pure-play aviation IT specialists with passenger processing heritage. Consolidation pressure intensifies as operators unbundle contracts into hardware, software, and managed service components. Geographic expansion through local system integrator partnerships represents the dominant competitive maneuver alongside portfolio diversification into predictive maintenance analytics.
Within the diversified industrial tier, Honeywell International Inc. and Siemens AG occupy positions anchored by building automation and energy management heritage. Thales Group exemplifies the defense-aerospace crossover archetype with biometric identity platform specialization. Among telecommunications-anchored competitors, Huawei Technologies Co. Ltd. and Cisco Systems Inc. represent infrastructure providers positioning around private 5G and edge computing deployment. IBM Corporation and Amadeus IT Group SA sit within the enterprise software and travel technology tier respectively, competing on cloud-native operational platform integration.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| IBM Corporation |
| Cisco Systems Inc. |
| SITA |
| Thales Group |
| Amadeus IT Group SA |
| Huawei Technologies Co. Ltd. |
| Indra Sistemas S.A. |
| Others |
Cost & Logistics Intelligence
Horizontal integration across building automation and security portfolios anchors pricing power for diversified industrial vendors serving terminal operators. Honeywell and Siemens leverage captive HVAC and energy management capabilities to bundle hardware-software-service contracts that resist unbundling pressure from low-cost competitors.
Pricing Analysis
Project-based contracting with subscription analytics overlays dominates procurement for major hub operators. Price differentiation rests on EASA certification tier and after-sales service bundling rather than base hardware specifications. Cost compression in biometric platform tiers is intensifying because airlines are disaggregating contracts into separable components. Low-cost carriers exhibit highest price sensitivity, while network carriers prioritize throughput metrics over unit economics.
Supply Chain Analysis
Freight costs for GPU-accelerated edge servers and precision sensor arrays have risen sharply on Asia-Europe routes, compressing margins for system integrators. Manufacturing concentrates in Taiwan, South Korea, and Germany for advanced semiconductors, industrial automation components, and precision HVAC equipment respectively. Raw material dependencies span rare earth elements for magnetic sensors, high-purity silicon for edge AI processors, and specialized refrigerants constrained by EU F-Gas Regulation phasedown. Single-source vulnerability around TSMC's advanced node capacity creates supply chain risk. Distribution runs through certified system integrator networks with EASA aerodrome design credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terminal operators can exploit regulatory arbitrage between FAA NextGen compliance timelines and EU AI Act biometric surveillance requirements, capturing cost differentials in procurement timing and data governance architecture.
For Market Incumbents: Cement platform stickiness through deep integration of digital twin architecture with existing building management systems at Frankfurt and Munich. Defend against asset-light software specialists by accelerating predictive maintenance analytics deployment. Invest in EASA aerodrome certification pre-qualification to extend contract renewal cycles.
For New Entrants and Emerging Players: Launch via sovereign cloud partnerships targeting European operators with GDPR data residency requirements. India's UDAN regional connectivity scheme offers the most penetrable geography for greenfield digital-native deployments. Target Tier-2 city airports with modular biometric boarding corridors sold through subscription rather than capital expenditure.
For Investors and Strategic Acquirers: Roll-up economics work for aviation IT specialists with passenger processing heritage because contract unbundling is fragmenting procurement authority across airline, airport operator, and ground handler stakeholders. The long-term viability window favors vendors with integrated energy management and biometric identity platforms. Watch for FAA-EASA regulatory harmonization signals as inflection indicator for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Platform Integration | Consolidates passenger processing contracts at Dubai International and Singapore Changi under unified EASA-compliant architecture. |
| Energy Management Retrofit | Captures EU Green Deal financing cycles at Amsterdam Schiphol through integrated HVAC and building automation upgrades. |
| Predictive Maintenance Analytics | Compresses mean time to repair for jet bridges at slot-constrained hubs using vibration sensors and NLP log processing. |
| Sovereign Cloud Deployment | Satisfies GDPR data residency requirements for European operators while enabling elastic compute for irregular operations. |
| Computer Vision Baggage Tracking | Displaces laser barcode scanning at German and US hubs through GPU-accelerated edge server deployment. |
Research Approach
Direct dialogue with airport operations directors, airline procurement executives, EASA certification specialists, and ground handling contract managers informed primary intelligence synthesis. Secondary validation drew from FAA NextGen implementation reports, EASA aerodrome design standards, EU AI Act regulatory filings, and Infrastructure Investment and Jobs Act funding disclosures. Bottom-up and top-down triangulation cross-checked vendor shipment data against operator capital expenditure patterns.
Bottom-up modeling aggregated individual technology segment deployments across IoT sensor networks, AI-enabled biometric platforms, cloud-native operational dashboards, and automation systems. Segmentation dimensions included processing architecture, functional application, procurement authority, and solution bundling approach. CAGRs were derived from fitted growth curves calibrated to regulatory mandate timelines and retrofit cycle patterns. Forecast inputs incorporated semiconductor supply constraints and EU F-Gas Regulation compliance deadlines.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor supply, abrupt FAA-EASA regulatory divergence, and pandemic-scale demand shocks. Forecasts reflect assumptions about regulatory implementation schedules and technology adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Air Traffic Smart Tower Solutions Market
Airport Technologies
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market
Airport Technologies
Airport Smart Lighting Market
Airport Technologies
Advanced Airport Technologies Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Smart Airport 2.0 Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Europe Smart Airport Market
Airport Technologies
Airport Airside Service Market
Airport Technologies
Helideck Monitoring System Market
Airport Technologies
Airport Runway Foreign Object Debris (FOD) Detection Systems Market
Airport Technologies
Commercial Airport Baggage Handling Systems Market
Airport Technologies
Airport RFID System Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Global Remote Towers Market
Airport Technologies
Airport Information Systems Market