
 Global Remote Towers Market | 2026-2036
Global Remote Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Remote Towers Market Foresight
Air traffic controller training pipelines and certified operator pools is reorganizing how quickly remote tower networks can deploy across continents. Thales Group leverages its digital aviation portfolio to sustain long-term contracts with European ANSPs. Saab AB anchors Nordic remote tower leadership through operational systems at multiple Swedish airports. L3Harris Technologies competes on sensor fusion depth for military airfield conversions in North America.
Remote towers consolidate airport traffic control functions into centralized facilities using high-resolution video feeds, radar data integration, and pan-tilt-zoom camera arrays replacing traditional out-the-window visibility. These systems process surveillance feeds with sub-second latency to maintain separation standards for commercial and military aircraft movements. Networked deployment configurations now attract the strongest procurement momentum as ANSPs seek to serve multiple aerodromes from single centers. Communication Platforms within the solution stack command sustained investment because voice-over-IP and integrated datalink systems constitute the operational backbone connecting controllers to pilots. Commercial Airports dominate application demand, though Regional Aerodromes present faster growth trajectories where staffing economics prove most compelling.
FAA certification standards for remote tower operations in the United States, EASA's regulatory framework across European member states, and ICAO's global guidance documents collectively shape product development timelines and market access conditions for system vendors. National aviation authorities in Germany, Norway, and Sweden have issued operational approvals that de-risk procurement decisions for peer regulators elsewhere. Stakeholders must track which jurisdictions transition from pilot programs to permanent operational mandates, as these regulatory inflection points determine contract timing and technology refresh cycles.
Market Dynamics
Networked deployment configurations are consolidating air traffic control functions across multiple aerodromes, compressing capital requirements while stretching regulatory certification timelines across jurisdictions.
Growth Catalysts
- EASA Remote Tower Certification:The European framework de-risks procurement decisions for national aviation authorities in Germany, Norway, and Sweden, accelerating peer regulator approvals elsewhere.
- Regional Aerodrome Economics:Staffing cost pressures at smaller facilities create compelling business cases for centralized operations serving multiple low-volume airports from single centers.
- Pan-Tilt-Zoom Camera Arrays:High-resolution video feeds with sub-second latency now match or exceed traditional out-the-window visibility standards for commercial aircraft separation.
Market Restraints
- Controller Training Pipeline Constraints:Certified operator pools limit how quickly remote tower networks can deploy, with requalification timelines extending operational readiness.
- FAA Certification Uncertainty:Absence of permanent operational mandates in the United States delays procurement decisions despite successful pilot programs.
- Legacy System Integration Complexity:Existing radar and voice communication infrastructure at established airports requires costly retrofitting to interface with remote tower platforms.
Strategic Opportunities
- Military Airfield Conversions:Sensor fusion depth for defense applications in North America opens adjacent demand beyond commercial aviation.
- ICAO Global Guidance Harmonization:Standardized international protocols reduce vendor customization burdens and accelerate multi-country contract execution.
- Voice-over-IP Backbone Modernization:Integrated datalink systems within communication platforms create recurring upgrade revenue streams as legacy copper networks depreciate.
Industry Challenges
- Cybersecurity Certification Burden:Air traffic control systems face escalating hardening requirements against intrusion, extending validation timelines before operational approval.
- Human Factors Engineering:Controller cognitive load management in screen-based environments demands specialized ergonomic design and ongoing validation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Remote Towers Market |
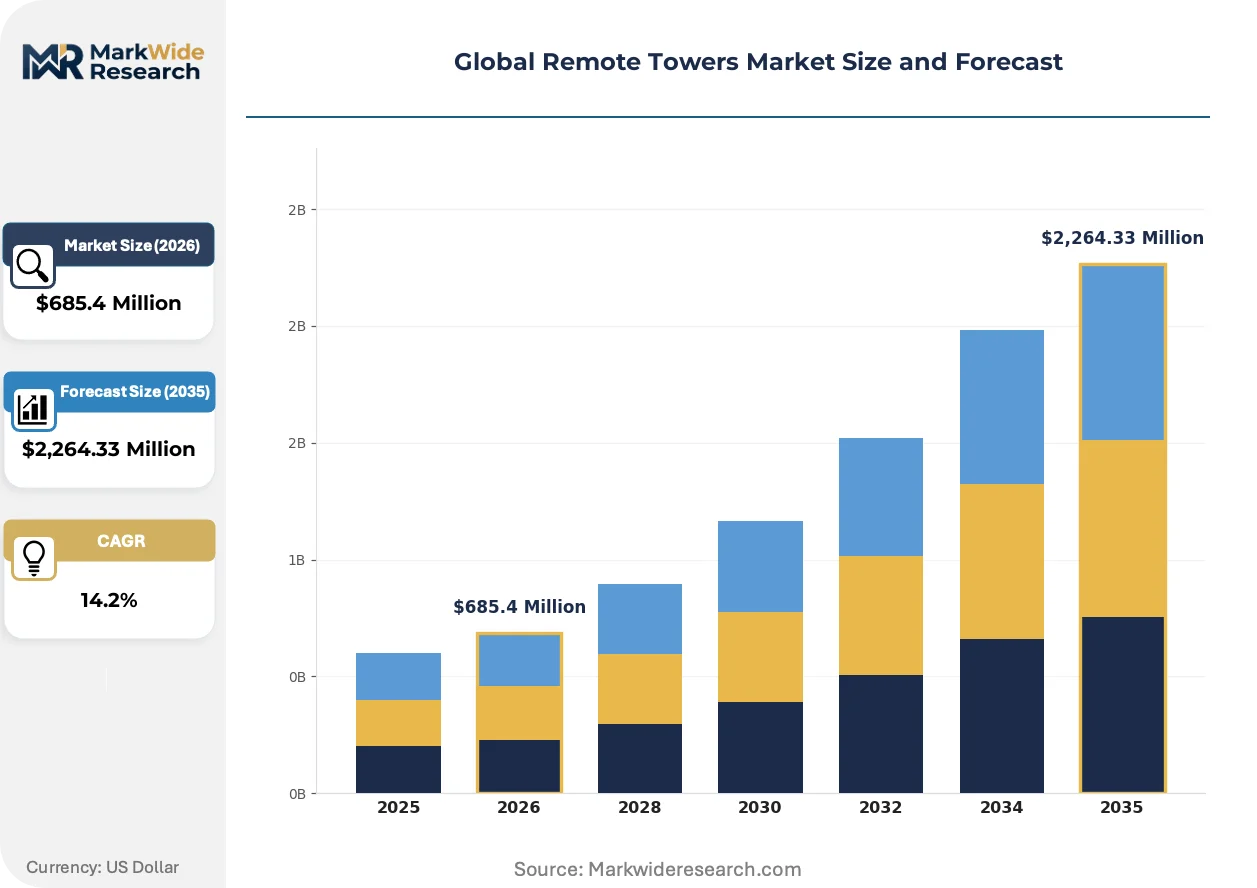
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,264.33 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Standalone, Networked, Hybrid, Virtual Tower, Satellite Operations Solution: Surveillance Systems, Communication Platforms, Data Analytics, Weather Monitoring, Security Control Application: Commercial Airports, Military Airfields, Cargo Terminals, Regional Aerodromes, Heliports End User: Air Navigation Service Providers, Airport Authorities, Defense Agencies, Cargo Handlers, Flight Operators |
| Companies Covered | Thales Group, Saab AB, Frequentist AG, Indra Sistemas, L3Harris Technologies, Searidge Technologies, Raytheon Technologies, Kongsberg Gruppen, Avinor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Remote Towers Market Shifts & Advancements
Digital aviation infrastructure is fragmenting traditional tower economics while regulatory frameworks crystallize around centralized operational models.
Artificial intelligence-assisted surveillance is fragmenting how controllers monitor aircraft movements. Machine vision algorithms now flag potential conflicts across multiple video feeds simultaneously. ANSPs in Germany and Sweden are deploying these systems at live remote tower installations, compressing reaction times for separation assurance.
EU Green Deal aviation decarbonization targets are accelerating ground infrastructure consolidation. Remote towers eliminate on-site energy consumption and construction materials at individual airports. EASA member states are incorporating carbon footprint reduction into remote tower procurement scoring, favoring networked deployment bids.
Controller workstation design is pivoting toward multi-airport supervision interfaces. Legacy single-aerodrome display configurations are yielding to modular screen arrays managing simultaneous operations. Norway's Avinor has operationalized triple-airport control from single centers, establishing reference architecture for peer ANSPs.
Global Remote Towers Market Segmentation
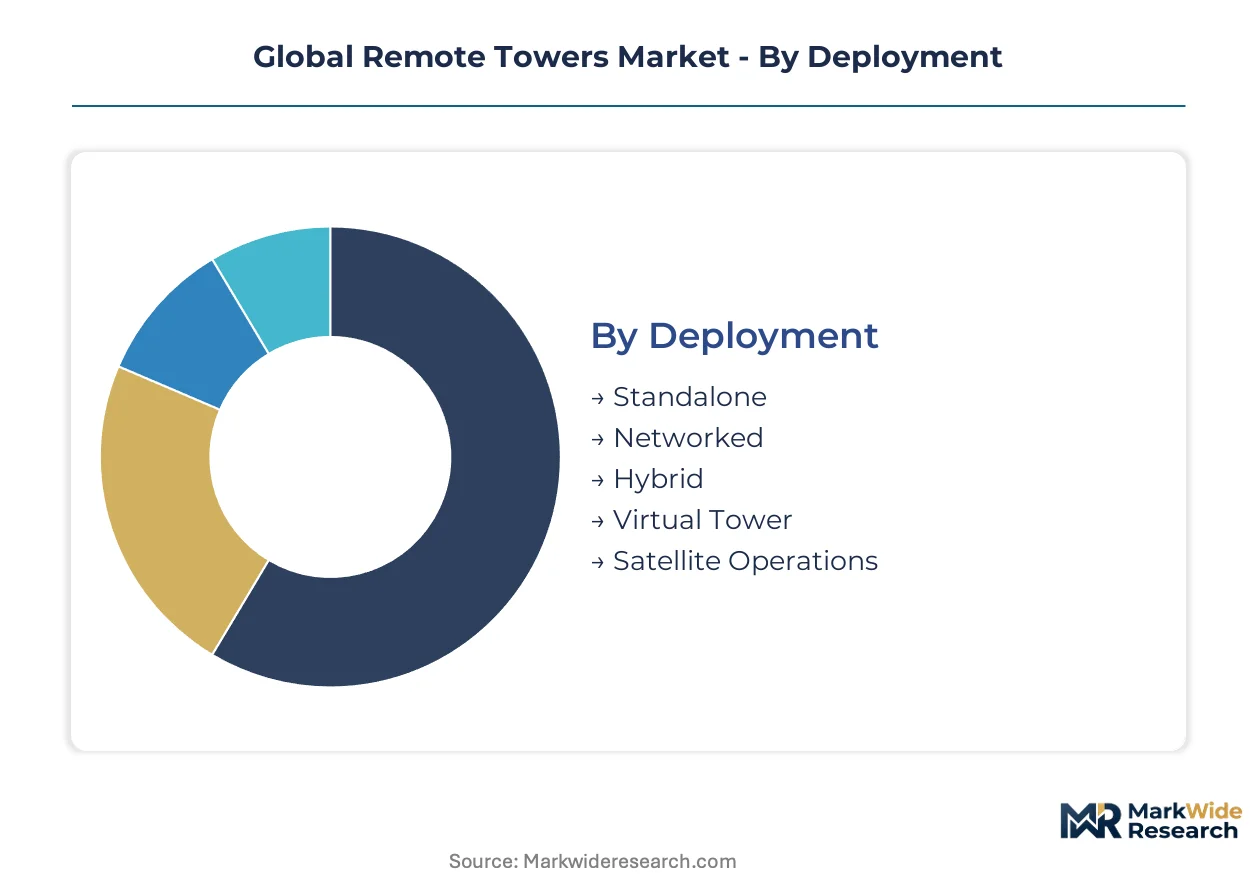
Remote tower procurement patterns diverge sharply by deployment architecture and operational scale, with margin pools concentrating where regulatory certification intersects multi-airport consolidation economics. Solution stack investments prioritize surveillance and communication layers that determine controller situational awareness quality.
Deployment:
Margin pools concentrate in configurations that amortize infrastructure costs across multiple aerodromes while meeting jurisdiction-specific certification timelines.
- Networked:Centralized facilities simultaneously manage traffic at 3-5 aerodromes using shared sensor arrays and controller pools. EASA-certified installations in Germany and Sweden demonstrate operational viability, compressing per-airport capital requirements while extending regulatory approval complexity across member states.
- Standalone:Single-aerodrome remote towers replace physical towers at individual airports without multi-site integration. Norway's Avinor deploys these at isolated regional facilities where staffing shortages outweigh networked economics.
- Hybrid:Transitional architectures combining on-site backup with remote primary control. Military airfields in North America favor this configuration for operational resilience requirements.
- Virtual Tower:Software-defined control environments using cloud-based processing without dedicated physical infrastructure. Emerging deployments target contingency operations and disaster recovery scenarios.
- Satellite Operations:Space-based relay systems extending remote tower coverage to ultra-remote aerodromes lacking terrestrial connectivity. Arctic region applications drive early adoption.
The dominant share belongs to Networked configurations, while Virtual Tower approaches are closing the gap fastest as cloud infrastructure matures.
Solution:
Technology stack investments track controller workflow priorities, with surveillance and communication layers commanding sustained upgrade cycles.
- Communication Platforms:Voice-over-IP and integrated datalink systems form the operational backbone connecting controllers to pilots. DFS Deutsche Flugsicherung in Germany prioritizes these platforms for multi-frequency coordination across networked installations.
- Surveillance Systems:High-resolution video feeds, radar integration, and pan-tilt-zoom camera arrays replacing traditional out-the-window visibility. Sub-second latency requirements drive sensor fusion investments at live European installations.
- Data Analytics:Machine vision algorithms flagging potential conflicts across multiple video feeds. ANSPs deploy these for separation assurance compression at high-density operations.
- Weather Monitoring:Automated meteorological sensors feeding real-time conditions into controller displays. Critical for low-visibility operations at Nordic facilities.
- Security Control:Cyber intrusion detection and access management systems hardening air traffic infrastructure against escalating threat profiles.
Communication Platforms capture the largest solution spend, though Data Analytics is expanding most quickly as AI-assisted surveillance gains operational validation.
Application:
End-use economics determine procurement urgency, with staffing pressures creating asymmetric adoption timelines across facility types.
- Commercial Airports:High-volume facilities with established regulatory frameworks and capital access. EASA certification pathways in Germany anchor initial deployment at major hubs before peer regulator adoption.
- Regional Aerodromes:Smaller facilities where controller staffing economics prove most compelling. Norway and Sweden lead operational approvals, establishing reference architectures for low-volume multi-site consolidation.
- Military Airfields:Defense applications prioritizing sensor fusion depth and operational security. North American procurement concentrates here pending FAA permanent mandate clarity.
- Cargo Terminals:Dedicated freight operations with distinct traffic patterns and separation requirements. Integration complexity with existing logistics systems constrains deployment speed.
- Heliports:Vertical flight operations demanding specialized low-altitude surveillance and rapid approach sequencing. Urban air mobility expansion creates adjacent demand pools.
Commercial Airports retain the dominant procurement volume, while Regional Aerodromes are gaining share fastest as staffing shortages intensify.
End User:
Purchasing authority fragmentation shapes contract structures, with service providers and infrastructure owners holding divergent investment timelines.
- Air Navigation Service Providers:DFS Deutsche Flugsicherung and Sweden's LFV drive networked deployment adoption under EASA frameworks. Long-term operational contracts favor capital-intensive system investments.
- Airport Authorities:Infrastructure owners prioritizing lifecycle cost reduction and facility consolidation. Procurement decisions hinge on regulatory approval certainty for permanent operational mandates.
- Defense Agencies:Military customers emphasizing cybersecurity hardening and contingency resilience. North American demand concentrates here with distinct certification pathways.
- Cargo Handlers:Logistics operators seeking integration with automated ground handling systems. Niche procurement limited by fragmented purchasing authority.
- Flight Operators:Airlines and charter services as indirect beneficiaries influencing ANSP investment priorities through operational feedback.
Air Navigation Service Providers control the dominant contract flow, while Airport Authorities are accelerating procurement fastest as permanent regulatory mandates crystallize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EASA's remote tower certification framework anchors European demand, with national aviation authorities in Germany, Norway, and Sweden issuing operational approvals that de-risk procurement decisions for peer regulators elsewhere.
Germany
DFS Deutsche Flugsicherung operates multiple live remote tower installations serving commercial airports and regional aerodromes. The national aviation authority has streamlined EASA compliance pathways, accelerating deployment timelines. Frankfurt and Munich anchor procurement concentration, with networked configurations serving smaller facilities in Lower Saxony and Bavaria.
Norway
Avinor has operationalized triple-airport control from single centers, establishing reference architecture for low-volume multi-site consolidation. The country's remote tower program addresses acute controller staffing shortages at isolated regional facilities. Bodø and Tromsø drive Arctic region applications, with satellite operations extending coverage to ultra-remote aerodromes lacking terrestrial connectivity.
United States
FAA pilot programs have demonstrated technical viability, though absence of permanent operational mandates delays procurement decisions at commercial airports. Military airfield conversions concentrate demand pending regulatory clarity. Sensor fusion investments prioritize defense applications, with installations concentrated at training facilities in the Southwest and Southeast corridors.
Sweden
LFV anchors Nordic remote tower leadership through operational systems at multiple Swedish airports. The transport agency has approved networked deployments serving 3-5 aerodromes from centralized facilities. Stockholm-Arlanda and Gothenburg anchor high-volume applications, while Linköping and Umeå demonstrate regional aerodrome economics.
United Kingdom
NATS Holdings evaluates remote tower feasibility for regional aerodrome consolidation under CAA oversight. London City Airport has hosted technology demonstrations, though permanent mandates await regulatory certainty. Highlands and Islands airports present compelling staffing economics for standalone and networked configurations.
Global Remote Towers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with aerospace conglomerates and defense contractors controlling certification-heavy segments while niche technology vendors capture modular solution components. The competitive landscape fragments across three strategic archetypes: full-stack system integrators bundling surveillance, communication, and analytics layers; sensor technology specialists supplying pan-tilt-zoom camera arrays and radar fusion modules; and ANSP-affiliated operators leveraging regulatory relationships for captive demand. Dominant competitive moves include strategic partnerships between technology vendors and national air navigation service providers, plus portfolio diversification into adjacent military airfield conversion opportunities.
Within the full-stack integrator tier, Thales Group and Saab AB exemplify archetypes combining digital aviation portfolios with long-term European ANSP contracts. L3Harris Technologies occupies a position emphasizing sensor fusion depth for defense applications in North America. These three anchors demonstrate how vendor selection tracks customer procurement authority—ANSPs favoring established European relationships, defense agencies prioritizing security-cleared supply chains, and airport authorities seeking turnkey deployment accountability.
| Leading Market Players |
|---|
| Thales Group |
| Saab AB |
| Frequentist AG |
| Indra Sistemas |
| L3Harris Technologies |
| Searidge Technologies |
| Raytheon Technologies |
| Kongsberg Gruppen |
| Avinor |
| Others |
Supply & Pricing Matrix
Cloud-based processing infrastructure is displacing on-premise hardware deployments across remote tower architectures, simultaneously compressing capital expenditure requirements for ANSPs and redistributing supply chain value toward software-centric vendors in Germany and Sweden. This substitution dynamic concentrates pricing power with full-stack integrators while fragmenting component supplier margins.
Pricing Analysis
European installations command 15-25% premiums over North American pilot programs due to EASA certification maturity and permanent operational mandates. Three-tier pricing structure across premium, standard, and economy levels tracks deployment complexity: networked multi-airport configurations anchor premium tiers, standalone regional towers occupy standard positioning, and virtual contingency systems represent economy access. Cost compression in standard-tier hardware is intensifying because sensor commoditization and Asian camera module sourcing. Regional aerodromes exhibit highest price sensitivity due to constrained capital budgets, while defense agencies demonstrate lowest sensitivity given security-cleared supply chain requirements.
Supply Chain Analysis
Germany and Sweden anchor pan-tilt-zoom camera array production and controller workstation assembly, while Taiwan and South Korea supply high-resolution sensor modules and FPGA processing chips. System integration draws from radar fusion modules, fiber-optic transmission hardware, and cybersecurity-hardened computing enclosures. Single-source vulnerability concentrates in military-grade encryption chipsets subject to export control restrictions. Distribution runs through ANSP procurement frameworks and defense agency contracting vehicles, with long-term operational service agreements capturing recurring revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EASA's permanent operational mandate framework has transformed remote towers from pilot-phase curiosity to infrastructure-grade procurement priority, compressing vendor qualification timelines while elevating certification-heavy incumbents.
For Market Incumbents: Consolidate controller workstation design expertise and multi-airport supervision software layers to defend against modular sensor vendors encroaching on system integration. Deepen backward integration into pan-tilt-zoom camera manufacturing to capture margin pools migrating from hardware to software. Prioritize cybersecurity certification investments as national aviation authorities escalate hardening requirements. For New Entrants and Emerging Players: Anchor in virtual tower and satellite operations segments where cloud infrastructure maturity is displacing capital-intensive physical deployments. Target contingency operations and disaster recovery applications at cargo terminals and heliports, where regulatory approval pathways remain less congested. Pursue OEM partnerships with established ANSPs to bypass lengthy direct certification cycles. For Investors and Strategic Acquirers: The market sits at a regulatory-validation phase that favors full-stack system integrators with live operational references. Long-term viability hinges on multi-country contract execution capability across EASA and eventual FAA frameworks. Acquisition target archetypes include AI-assisted surveillance specialists and voice-over-IP platform vendors with ANSP relationships. Monitor FAA permanent mandate announcements as the critical inflection signal for North American demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Multi-Country Certification | DFS Deutsche Flugsicherung leverages streamlined pathways to accelerate peer regulator approvals across member states. |
| AI-Assisted Surveillance Integration | Machine vision deployment at Swedish installations compresses controller reaction times for separation assurance. |
| Networked Deployment Scale-Up | Avinor's triple-airport control centers demonstrate operational viability for low-volume multi-site consolidation economics. |
| Military Airfield Conversion | Sensor fusion depth investments open adjacent demand pools beyond commercial aviation pending FAA clarity. |
| Voice-over-IP Backbone Modernization | Integrated datalink systems create recurring upgrade revenue as legacy copper networks depreciate across European ANSPs. |
Research Methodology
Desk research of ICAO guidance documents, EASA certification filings, and national aviation authority operational approvals preceded structured interviews with air traffic control system procurement managers, ANSP engineering directors, defense agency program officers, and remote tower technology vendors. Secondary validation drew from FAA pilot program reports, EU Green Deal aviation infrastructure assessments, and customs data on sensor module trade flows. Bottom-up installation tracking across Germany, Norway, Sweden, and the United States triangulated against top-down ANSP capital expenditure disclosures.
Variance decomposition across deployment architecture, solution stack layering, and application segments shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include networked versus standalone configurations, surveillance and communication platform investments, and commercial airport versus regional aerodrome demand profiles. CAGRs derived from installation pipeline analysis and regulatory approval velocity assumptions, with controller training pipeline constraints and cybersecurity certification timelines as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of EASA framework continuity and FAA mandate crystallization; material deviation would warrant model refresh. Specific risk factors include permanent mandate delays in North America, controller union opposition to centralized operations, and escalating cyber intrusion threats against air traffic infrastructure. Recalibration cycles align with material shifts in regulatory approval velocity and multi-country contract execution patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Commercial Airport Baggage Handling Systems Market
Airport Technologies
Airport Airside Service Market
Airport Technologies
Asia-Pacific Airport Ground Handling Systems Market
Airport Technologies
Asia-Pacific Smart Airport Market
Airport Technologies
Asia-Pacific Airport Baggage Handling Systems Market
Airport Technologies
Helideck Monitoring System Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Airport Smart Lighting Market
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Smart Airport 3.0 Market