
 Saudi Arabia Satellite-Based Earth Observation Market | 2026-2036
Saudi Arabia Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Satellite-Based Earth Observation Market Insights
Public-private partnership financing for satellite constellation build-outs is reshaping competitive access in Saudi Arabia's earth observation sector. The Saudi Space Agency leverages state-backed capital to anchor national imaging infrastructure. Airbus competes through its dual-use radar and optical platforms calibrated for desert terrain analysis. Planet Labs PBC positions its daily-coverage smallsat fleet to serve agricultural and urban planning clients across the Kingdom.
Satellite-based earth observation deploys sensors aboard orbital platforms to capture multispectral, hyperspectral, or synthetic aperture radar data with spatial resolutions ranging from sub-meter to tens of meters, then processes this into georeferenced imagery for surface monitoring and change detection. Optical satellites dominate current procurement for infrastructure and environmental tracking, while radar satellites extend coverage through sandstorm-penetrating all-weather imaging that oil field operators require. Government agencies represent the deepest end-user pool, as ministry budgets fund sovereign imaging capacity under Vision 2030 diversification mandates.
The Saudi Space Agency's licensing regime and the Communications, Space and Technology Commission's spectrum coordination rules shape market entry for foreign operators and domestic service providers. SFDA guidelines for environmental health monitoring and the National Center for Vegetation Cover's land-use mandates direct procurement specifications for agricultural and desertification applications. Stakeholders must track how domestic manufacturing requirements and data sovereignty provisions evolve as the Kingdom builds indigenous satellite assembly capabilities.
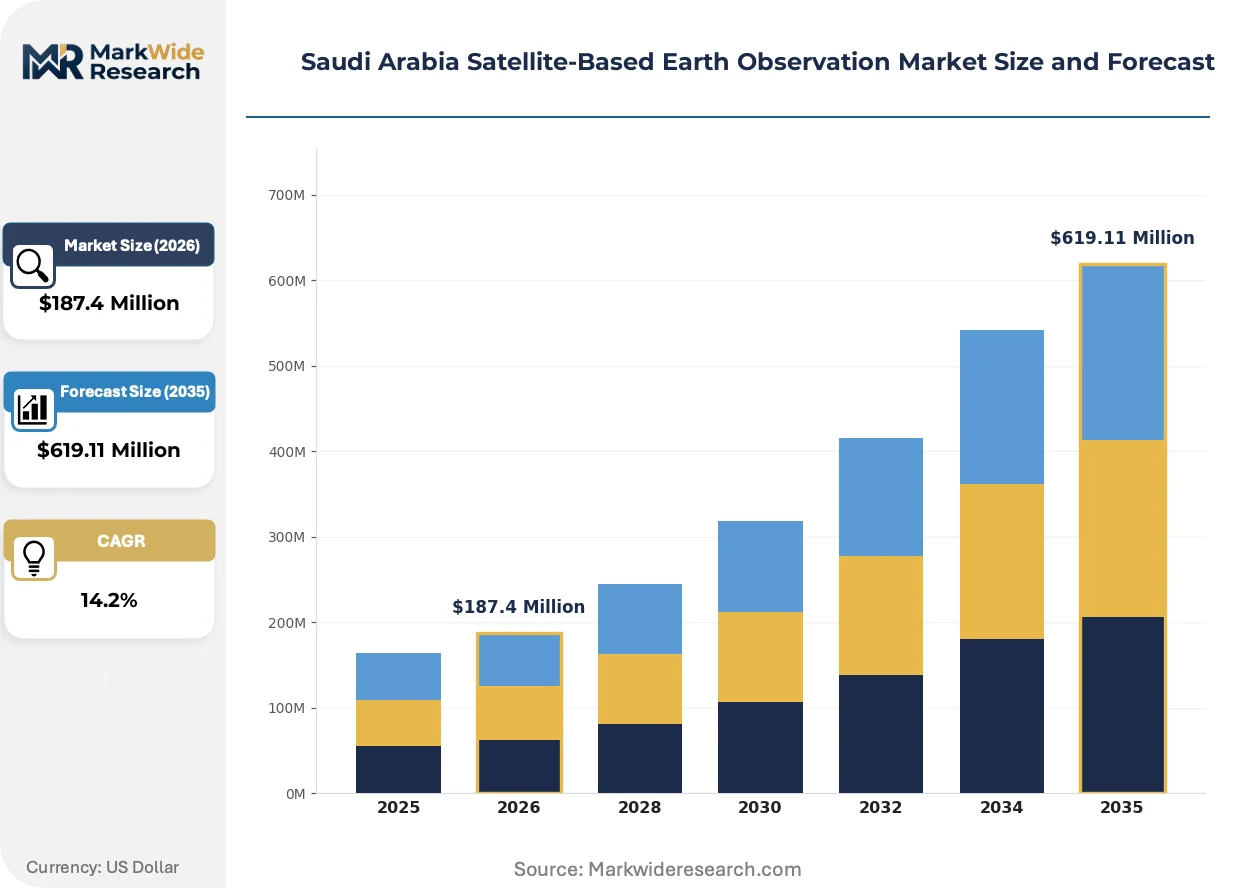
Market Dynamics
Public-private partnership financing for satellite constellation build-outs is concentrating competitive access around state-backed capital pools, with the Saudi Space Agency anchoring national imaging infrastructure through sovereign procurement mandates that privilege domestic operator participation.
Growth Catalysts
- Vision 2030 megaproject coordination:Ministry budgets for NEOM, The Line, and Red Sea Project generate concentrated demand for high-resolution terrain mapping and construction progress monitoring.
- SFDA environmental health frameworks:Mandatory satellite-based vegetation cover assessment for agricultural licensing expands recurring data subscriptions among farming cooperatives.
- Synthetic aperture radar penetration:All-weather imaging capabilities overcome sandstorm-induced optical blackout periods that disrupt pipeline monitoring operations.
Market Restraints
- Launch cost volatility:Dependence on foreign launch providers exposes domestic operators to payload pricing fluctuations and scheduling delays.
- Data sovereignty requirements:The Saudi Space Agency's commercial remote sensing licensing regime imposes ground station localization mandates that fragment operational architectures.
- Optical sensor substitution:Manned aerial surveys retain cost advantages for sub-meter resolution tasks across small geographic footprints.
Strategic Opportunities
- Eastern Province industrial corridor:Unpenetrated manufacturing zones around Jubail offer first-mover positioning for emissions monitoring and supply chain tracking services.
- Communications, Space and Technology Commission spectrum reforms:Proposed Ka-band allocation expansions would enable higher-bandwidth downlink capacity for real-time analytics.
- AI-hyper spectral fusion:Converging onboard processing with spectral imaging compresses analytics turnaround from hours to minutes for desertification alerts.
Industry Challenges
- Geospatial data science talent scarcity:Domestic universities produce insufficient remote sensing analysts to staff processing centers in Riyadh and Jeddah.
- Legacy GIS integration friction:Ministry IT systems built on decade-old architectures resist API-based satellite data feeds without middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Satellite-Based Earth Observation Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Satellites, Radar Satellites, Hyperspectral Satellites, Multispectral Satellites Application: Agriculture Monitoring, Urban Planning, Disaster Management, Climate Change Studies End User: Government Agencies, Research Institutions, Private Enterprises, Environmental Organizations Technology: Remote Sensing, GIS, Data Analytics, Cloud Computing |
| Companies Covered | Arabsat, Airbus, Leonardo S.p.A., SARsat Arabia, Thales, Raytheon Technologies Corporation, Maxar Technologies, Planet Labs PBC, Saudi Space Agency, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Satellite-Based Earth Observation Market Trends and Innovations
Three forces are compressing traditional satellite service delivery models in the Kingdom: sovereign data localization mandates, AI-driven onboard analytics, and ministry procurement centralization.
Small satellite constellations with daily revisit frequencies are collapsing the price-performance threshold that previously restricted operational monitoring to government budgets. Agricultural cooperatives in the Qassim region now subscribe to commercial tasking services previously affordable only to Aramco-scale operators. The cost compression is enabling parcel-level crop health surveillance across hundreds of thousands of hectares.
The Saudi Space Agency's commercial remote sensing licensing framework is mandating domestic ground segment infrastructure for all foreign-collected imagery sold within the Kingdom. This regulatory requirement is fragmenting operational architectures for Airbus, Planet Labs, and other international operators, forcing joint venture structures with Saudi entities. The policy is accelerating local assembly capabilities at King Abdulaziz City for Science and Technology facilities.
Ministry procurement consolidation under Vision 2030 coordination offices is displacing fragmented agency-level satellite data purchasing. The National Information Center now brokers imagery requirements across defense, agriculture, and municipal end-users, compressing vendor negotiation leverage. This centralization is most visible in Riyadh, where the Riyadh Region Municipality channels urban planning imagery through sovereign capacity rather than direct commercial contracts.
Saudi Arabia Satellite-Based Earth Observation Market Segmentation
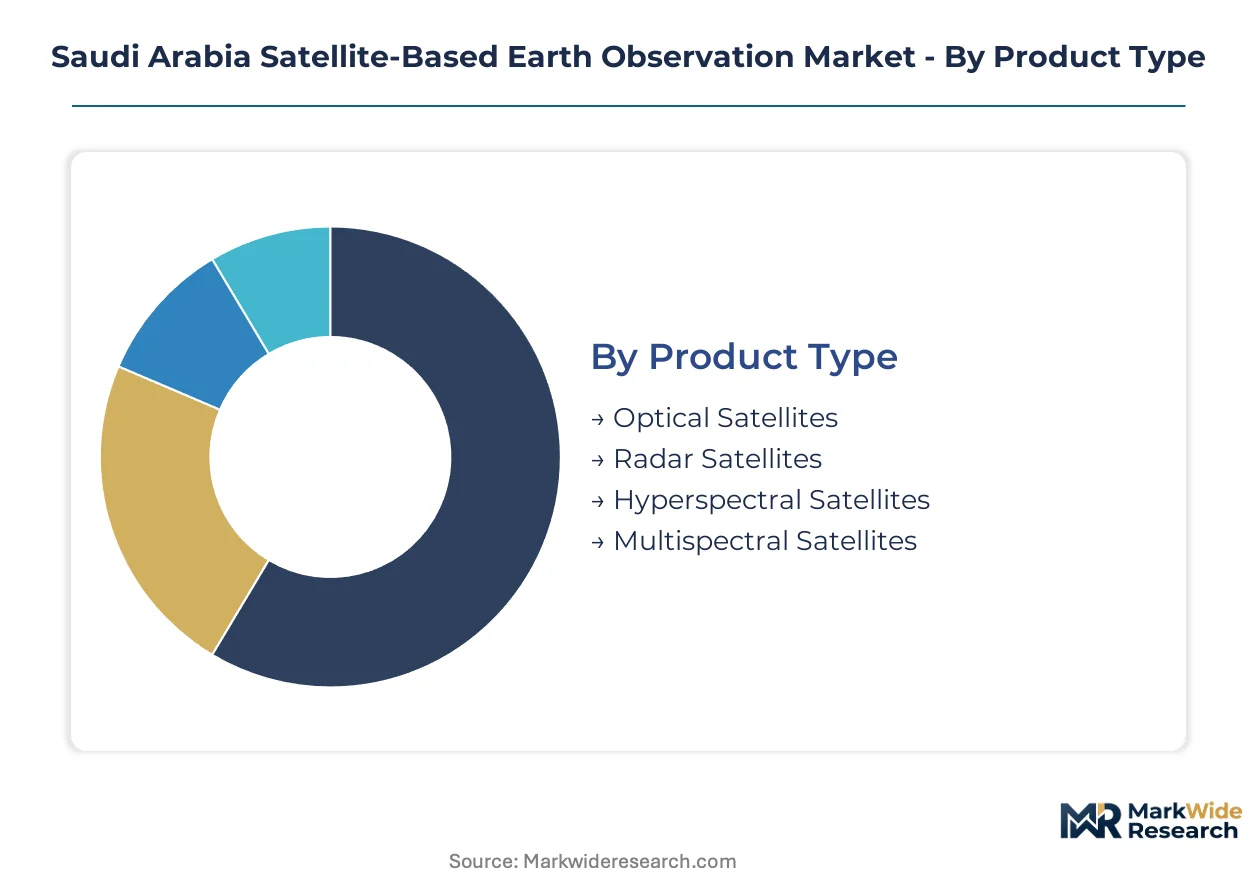
Segmentation in Saudi Arabia's satellite-based earth observation market reveals how procurement priorities diverge across imaging modalities, use cases, and institutional buyers. The Saudi Space Agency's licensing framework and Vision 2030 megaproject demands are reshaping which technologies capture ministry budgets and which end-user categories drive recurring data subscriptions.
Product Type:
Cost tier determines access patterns across imaging platforms, with capital-intensive radar systems commanding sovereign budgets while optical constellations penetrate commercial agriculture.
- Optical Satellites:These platforms capture visible and near-infrared reflectance across panchromatic and multispectral bands, delivering spatial resolutions down to sub-meter for infrastructure mapping. Riyadh's government cluster procures high-resolution optical tasking for NEOM construction monitoring and Red Sea Project environmental baselines, though sandstorm seasonality creates 15-20% annual downtime that operators must price around.
- Radar Satellites:Synthetic aperture radar systems transmit microwave pulses that penetrate cloud cover and dust storms, enabling all-weather surface deformation tracking. Saudi Aramco's geospatial division relies on radar constellations for pipeline integrity monitoring across the Eastern Province's dust-prone terrain, where optical blackout periods would halt critical leak detection operations.
- Hyperspectral Satellites:These sensors capture contiguous narrow bands across hundreds of spectral channels, enabling mineral identification and vegetation stress detection at 10-30 meter resolution.
- Multispectral Satellites:Discrete band imaging systems balance spectral discrimination with revisit frequency for agricultural yield forecasting across the Qassim and Asir regions.
Optical Satellites hold installed capacity. Radar Satellites is rotating up the share rankings.
Application:
Application focus separates sovereign mandate spending from commercial subscription growth, with megaproject coordination consuming the largest tasking volumes.
- Agriculture Monitoring:Satellite-derived normalized difference vegetation index mapping enables irrigation scheduling and pest early warning across Saudi Arabia's wheat and date palm cultivation zones. The National Center for Vegetation Cover mandates annual cover assessments for agricultural licensing, creating recurring procurement from farming cooperatives in Qassim and Al-Jouf that previously relied on ground surveys.
- Urban Planning:High-resolution stereo imagery supports 3D city modeling and informal settlement detection for municipal zoning enforcement. Riyadh Region Municipality channels urban planning imagery through the National Information Center's consolidated procurement, displacing direct commercial contracts that fragmented vendor relationships.
- Disaster Management:Rapid tasking protocols activate for flood and dust storm damage assessment, with the General Directorate of Civil Defense coordinating post-event imagery requirements.
- Climate Change Studies:Long-term desertification tracking and coastal erosion monitoring serve academic and environmental ministry research priorities.
Agriculture Monitoring anchors recurring revenue. Urban Planning is climbing the fastest.
End User:
Customer type concentration reveals where procurement centralization is compressing vendor margins versus where fragmented buying sustains pricing power.
- Government Agencies:Ministry budgets for defense, interior, and municipal affairs fund sovereign imaging capacity under Vision 2030 diversification mandates. The Saudi Space Agency's procurement brokering through the National Information Center has consolidated previously fragmented agency-level purchasing, reducing vendor negotiation leverage across Riyadh's government cluster.
- Private Enterprises:Mining, construction, and logistics operators subscribe to commercial tasking services for site selection and supply chain visibility. Jubail's industrial corridor presents unpenetrated demand for emissions monitoring and asset tracking that first-mover providers are targeting with specialized analytics packages.
- Research Institutions:King Abdulaziz City for Science and Technology and university remote sensing labs access subsidized imagery for algorithm development and climate modeling.
- Environmental Organizations:Non-governmental conservation groups leverage satellite data for protected area monitoring and species habitat mapping in the Red Sea coastal zone.
Government Agencies dominate committed spend. Private Enterprises is gaining share fastest.
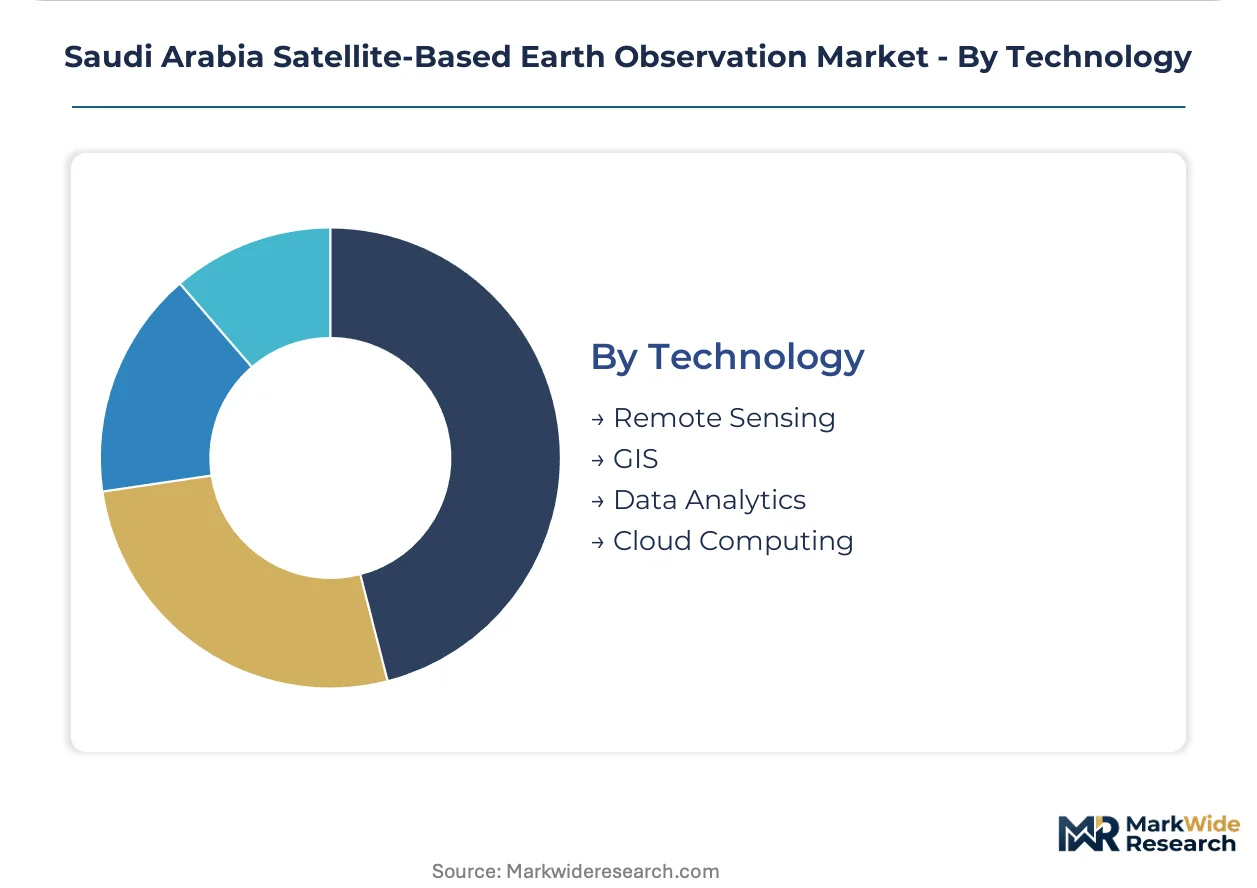
Technology:
Technology stack maturity separates legacy GIS integration challenges from emerging AI-driven analytics opportunities that compress turnaround times.
- Remote Sensing:The foundational discipline of sensor calibration, atmospheric correction, and geometric rectification that transforms raw satellite data into analysis-ready imagery. King Abdulaziz City for Science and Technology facilities are building domestic remote sensing processing capacity to satisfy data sovereignty requirements in the Saudi Space Agency's licensing regime.
- GIS:Geospatial information systems for layered vector-raster analysis and cartographic output remain entrenched in ministry IT architectures. Legacy systems resist API-based satellite data feeds without middleware development, creating integration friction that vendors must address through professional services revenue.
- Data Analytics:Machine learning classification and change detection algorithms automate feature extraction from imagery stacks.
- Cloud Computing:Scalable storage and compute infrastructure enables petabyte-scale archive access and distributed processing workflows.
Remote Sensing holds foundational position. Data Analytics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government procurement clusters and energy sector operators concentrate satellite imagery demand across Saudi Arabia's major economic zones. Ministry budgets and state-owned enterprise requirements shape regional service penetration patterns.
Riyadh
The capital's government and defense cluster coordinates sovereign imaging capacity through the National Information Center's consolidated procurement. The Saudi Space Agency's regulatory framework mandates domestic ground station infrastructure for foreign-collected imagery. King Abdulaziz City for Science and Technology facilities are building indigenous satellite assembly capabilities to satisfy localization requirements.
Eastern Province
Saudi Aramco's geospatial division drives demand for all-weather radar monitoring across pipeline networks and offshore assets. The Communications, Space and Technology Commission's spectrum coordination rules shape operator entry for industrial corridor services. Jubail's manufacturing zones present unpenetrated demand for emissions monitoring and supply chain tracking applications.
Western Region
The Red Sea Project and coastal tourism developments generate high-resolution terrain mapping requirements for environmental baseline establishment. SFDA guidelines for vegetation cover assessment direct agricultural licensing procurement in the Asir highlands. Jeddah's logistics hub channels commercial tasking services for port and shipping lane visibility.
NEOM Northwest
The Line and related megaprojects consume concentrated volumes of construction progress monitoring and 3D city modeling imagery. Vision 2030 coordination offices centralize previously fragmented agency-level satellite data purchasing. The zone's regulatory sandbox status attracts foreign operators seeking joint venture structures with Saudi entities.
Qassim
Agricultural cooperatives subscribe to commercial vegetation index mapping for irrigation scheduling across wheat and date palm cultivation zones. The National Center for Vegetation Cover's land-use mandates create recurring data subscriptions from farming operations. Small satellite cost compression enables parcel-level crop health surveillance across extensive hectarage previously served only by ground surveys.
Saudi Arabia Satellite-Based Earth Observation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Saudi Arabia's satellite earth observation sector. State-backed capital pools concentrate competitive access around sovereign procurement mandates that privilege domestic operator participation. Three archetypes dominate: sovereign agencies anchoring national infrastructure, dual-use defense contractors supplying radar and optical platforms, and commercial smallsat operators penetrating agricultural subscriptions. Consolidation through public-private partnerships and regulatory-mandated joint ventures represents the dominant competitive dynamic.
Within the sovereign infrastructure tier, the Saudi Space Agency anchors national imaging capacity through procurement brokering and licensing regime enforcement. Among international platform providers, Airbus and Thales represent dual-use specialists supplying radar and optical systems calibrated for desert terrain analysis. Planet Labs PBC exemplifies the commercial smallsat archetype with daily-coverage constellations serving agricultural and urban planning clients across price-compressed subscription models.
| Leading Market Players |
|---|
| Arabsat |
| Airbus |
| Leonardo S.p.A. |
| SARsat Arabia |
| Thales |
| Raytheon Technologies Corporation |
| Maxar Technologies |
| Planet Labs PBC |
| Saudi Space Agency |
| Others |
Pricing and Supply Chain Analysis
The King Abdulaziz Port corridor freight dynamics concentrate supply-side leverage among foreign launch providers while fragmenting downstream pricing power across domestic ground station operators and international imagery vendors. Cost-plus contracting with fuel-indexed adjustments governs payload delivery agreements, compressing margins for constellation operators while the Communications, Space and Technology Commission's spectrum fees add fixed-cost layers that price-sensitive agricultural cooperatives resist.
Pricing Analysis
Cost-plus contracts with fuel-indexed escalation clauses dominate launch procurement agreements between domestic operators and foreign providers. Three-tier pricing structure across premium radar tasking, standard optical subscriptions, and economy vegetation-index services separates Aramco-scale integrity monitoring from Qassim cooperative crop surveillance. Cost compression in smallsat optical tiers is intensifying because Planet Labs-style daily revisit constellations collapse per-hectare analytics costs. Agricultural cooperatives exhibit highest price sensitivity, while defense ministry budgets show lowest elasticity for all-weather radar capacity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from European launch brokers ease working capital strain for Saudi constellation operators awaiting licensing clearance. Manufacturing concentrates in France, Germany, and the United States for radar payload components; optical sensor fabrication centers on Japan and South Korea. Domestic assembly draws from gallium arsenide semiconductors, carbon-fiber bus structures, and precision reaction wheels. Single-source vulnerability runs through foreign launch pad access, as the Kingdom lacks indigenous orbital insertion capability. Distribution runs through joint-venture ground stations mandated by the Saudi Space Agency's data sovereignty framework.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
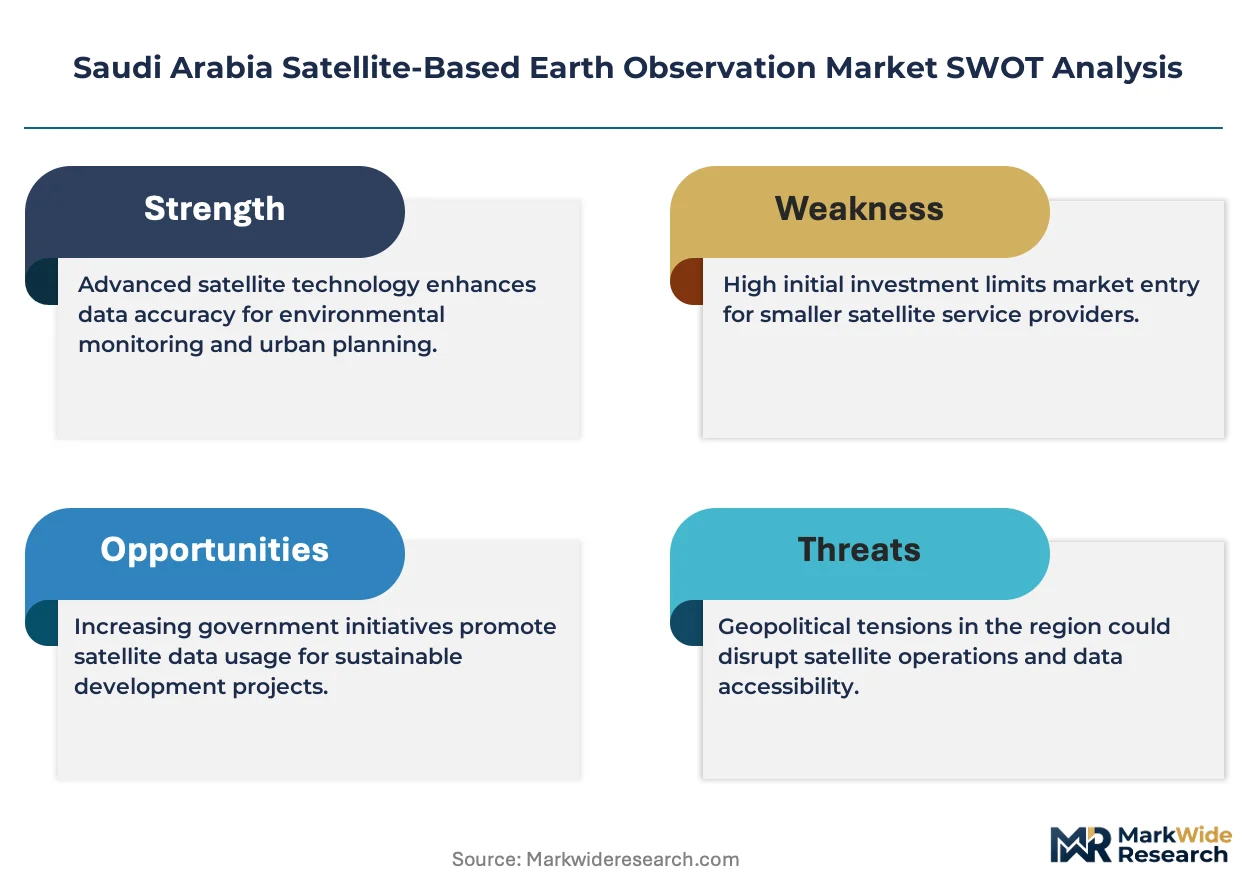
The Saudi Arabia satellite-based earth observation market reads as a service-attach opportunity where analytics subscriptions and tasking-on-demand layers expand faster than hardware procurement. Recurring revenue from agricultural vegetation-index monitoring now outpaces one-time satellite sales to government clusters.
For Market Incumbents: Build regulatory moats through pre-positioned domestic ground station infrastructure that satisfies Saudi Space Agency localization mandates before competitors secure joint-venture partnerships. Airbus and Thales should deepen backward integration into desert-calibrated sensor processing to defend against smallsat substitution in agricultural tiers. The threat of AI-driven onboard analytics compressing turnaround times demands captive algorithm development at King Abdulaziz City for Science and Technology facilities. For New Entrants and Emerging Players: Jubail's industrial corridor emissions monitoring presents unpenetrated white-space where first-mover analytics packages can anchor before Aramco consolidates vendor relationships. Qassim farming cooperatives offer accessible entry through vegetation-index subscriptions priced below sovereign procurement thresholds. Target the National Center for Vegetation Cover's mandatory licensing assessments as the go-to-market anchor, bundling compliance reporting with irrigation optimization tools. For Investors and Strategic Acquirers: Carve-out targets emerge from European defense primes spinning off commercial remote sensing divisions amid budget pressure on dual-use programs. Long-term viability hinges on positioning upstream of the Saudi Space Agency's domestic manufacturing mandates as indigenous assembly capacity scales. Watch for Communications, Space and Technology Commission spectrum allocation rulings as the inflection signal—Ka-band expansion would enable real-time analytics architectures that reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Ground Station Joint Venture | Satisfies Saudi Space Agency data sovereignty mandates while anchoring foreign operator market access. |
| AI-Onboard Processing Development | Compresses desertification alert turnaround from hours to minutes at King Abdulaziz City facilities. |
| Agricultural Analytics Subscription Launch | Captures Qassim cooperative demand previously served only by ground surveys. |
| Radar Constellation Capacity Expansion | Addresses Aramco pipeline integrity requirements through sandstorm-penetrating all-weather imaging. |
| Spectrum Coordination Partnership | Secures Ka-band allocation advantages through Communications, Space and Technology Commission engagement. |
Research Methodology
Operator-level perspectives from satellite constellation engineers, ground station operations managers, Saudi Space Agency licensing officers, and agricultural cooperative procurement leads anchored the qualitative base. Secondary validation drew from Communications, Space and Technology Commission spectrum filings, SFDA environmental health guidelines, National Center for Vegetation Cover procurement records, and satellite operator SEC disclosures. Bottom-up imagery demand modeling across ministry budgets and top-down market sizing from launch manifest analysis were triangulated to converge estimates.
Scenario-bracketing framed volume and value outputs across the projection horizon, with conservative cases assuming delayed domestic manufacturing scale-up and accelerated cases incorporating early Ka-band spectrum release. Segmentation dimensions modeled include imaging modality, application use case, end-user institutional type, and technology stack maturity. CAGRs derived from fitted growth curves applied to ministry budget trajectories under Vision 2030, with specific inputs from NEOM construction timelines and Aramco pipeline monitoring contract renewals.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed capital pools or accelerated indigenous assembly timelines would shift outcomes. Macroeconomic oil price volatility affecting ministry budgets, regulatory tightening on foreign imagery access, or breakthroughs in low-cost synthetic aperture radar miniaturization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Germany Satellite Connectivity Market
Satellite
US Remote Sensing Technology Market
Satellite
Satellite Services Market
Satellite
Satellite Communication Equipment Market
Satellite
India Satellite Communication Market
Satellite
ASEAN Satellite-Based Earth Observation Market
Satellite
Global Commercial Satellite Broadband Market
Satellite
Global Satellite Modem Market
Satellite
Earth Observation Satellite Market
Satellite
Global Remote Sensing Services Market
Satellite
United States Satellite Communications Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
Satellite Photography Service Market
Satellite
Broadband Satellite System Market
Satellite
Satellite Payload Market
Satellite
4K Satellite Broadcasting Market