
 Airport Smart Lighting Market | 2026-2036
Airport Smart Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Smart Lighting Market Intelligence
The bundling of smart controls with LED fixtures as a complete system is decoupling purchasing decisions from simple component-level costs. This shift favors integrated solution providers who can offer end-to-end performance guarantees for airport authorities. Siemens AG leverages its broad automation portfolio to offer comprehensive terminal and airside solutions. Honeywell International competes by integrating lighting controls into its wider building management and security systems.
Airport smart lighting refers to a network of interconnected luminaires and control systems designed for aviation environments. These systems often utilize DALI or wireless protocols for individual fixture control, enabling dynamic adjustment based on real-time data. The application segment for runways and taxiways requires high-reliability fixtures compliant with aviation standards, commanding premium pricing. Within technology, IoT-enabled systems represent the fastest-growing segment, allowing for predictive maintenance and energy optimization.
Regulations from bodies like the US Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA) mandate specific photometric performance and reliability for airside lighting. Concurrently, initiatives such as the EU Green Deal and China's dual carbon goals pressure airport operators to adopt energy-efficient LED technologies. The critical decision for airport authorities now centers on balancing upfront investment in intelligent systems against long-term operational savings and compliance.
Market Dynamics
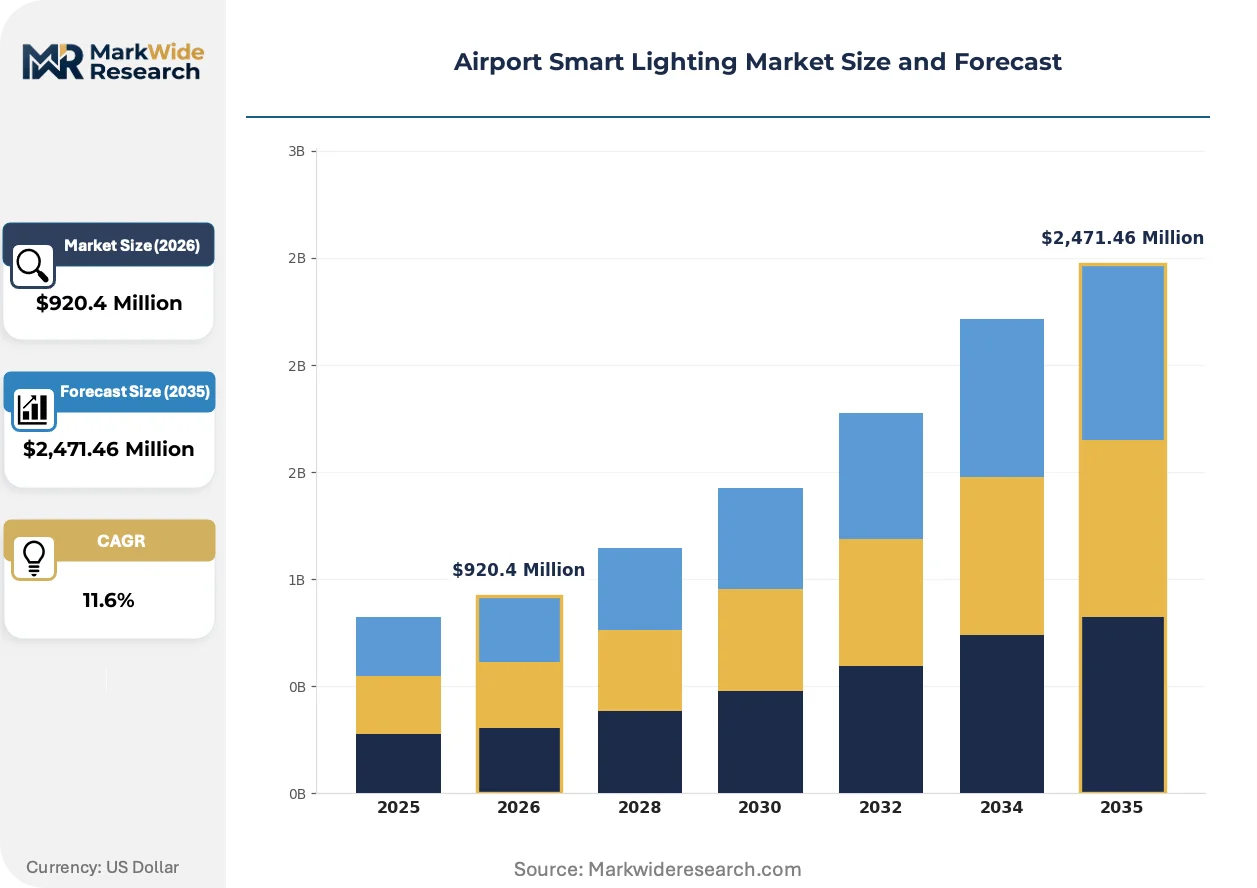
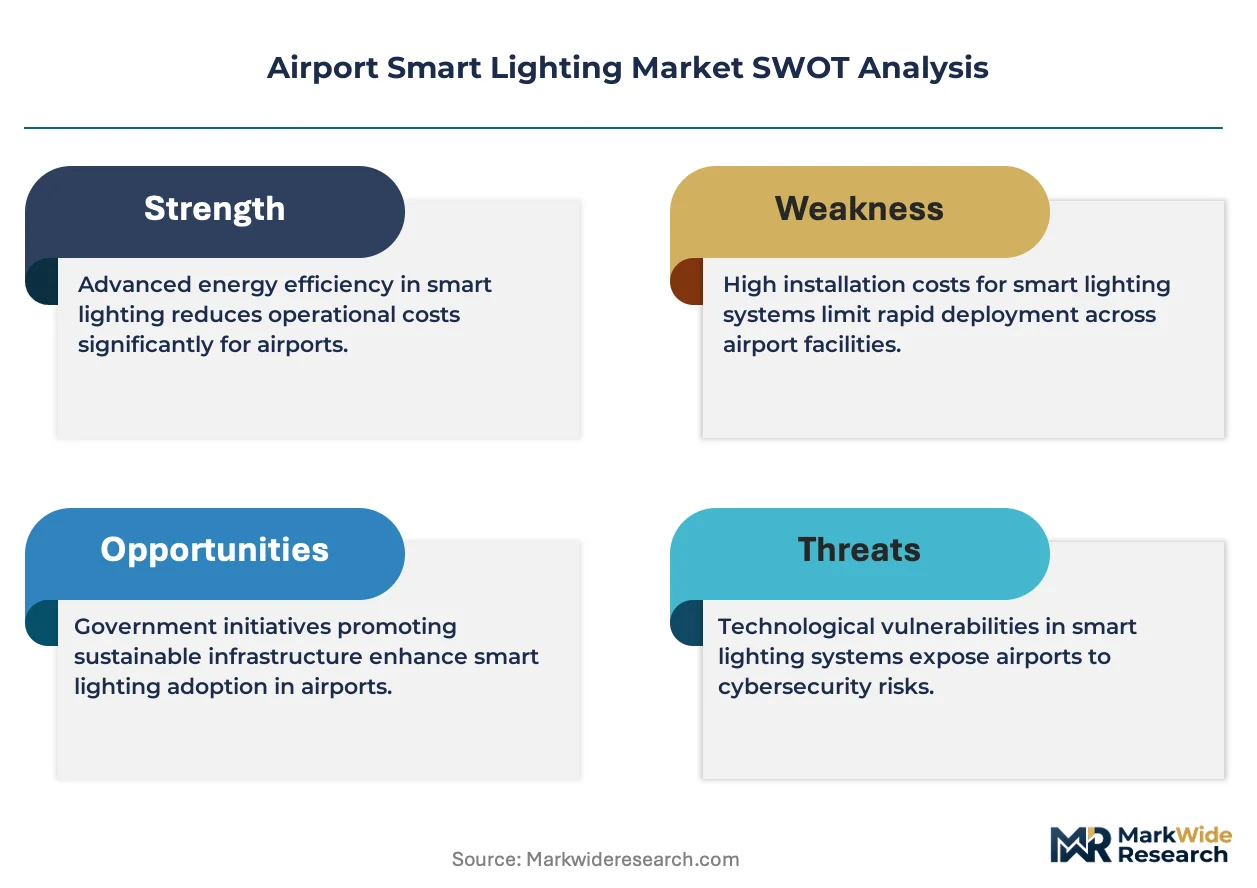
The central dynamic in the airport smart lighting market is the strategic tension between the high initial capital investment required for IoT-enabled systems and the compelling long-term operational savings and regulatory compliance benefits driven by global sustainability mandates.
Growth Catalysts
- Sustainability Mandates:Policy frameworks like the EU Green Deal and China's dual carbon goals compel airport operators to invest in energy-efficient technologies, making smart LED lighting a primary tool for achieving emission reduction targets in large-scale infrastructure.
- Passenger Experience Focus:Airports are increasingly competing on passenger experience, driving adoption of tunable and adaptive lighting within terminals to improve ambiance, reduce jet lag perception, and guide passenger flow, particularly in retail and lounge areas.
- Infrastructure Modernization:Massive greenfield airport projects and expansions, especially in the Middle East and Southeast Asia, provide opportunities to install integrated smart lighting systems from the ground up, bypassing the challenges of retrofitting older facilities.
Market Restraints
- High Upfront Investment:The significant cost of intelligent luminaires, network gateways, sensors, and control software presents a major hurdle for budget-constrained small and medium-sized airports, slowing market penetration beyond major international hubs.
- Lack of Protocol Standardization:The prevalence of proprietary or competing communication protocols like DALI and various wireless standards creates interoperability challenges, increasing integration complexity and the risk of vendor lock-in for airport authorities.
- Stringent Aviation Certification:Airside lighting for runways and taxiways must adhere to strict performance and reliability standards from bodies like the FAA and EASA, which limits the number of qualified suppliers and slows the introduction of new technology.
Strategic Opportunities
- Cybersecurity as a Service:The expansion of networked lighting systems creates a demand for specialized cybersecurity services to protect against potential vulnerabilities, offering a new, recurring revenue stream for solution providers.
- Modular Retrofit Solutions:Developing smart control modules that can be retrofitted onto existing, non-smart LED fixtures allows vendors to access the large installed base of airports that have already upgraded to LED but lack intelligent controls.
- Data Analytics for Operations:Occupancy and movement data gathered from lighting sensors can be anonymized and analyzed to optimize terminal layout, staff allocation, and retail concession performance, creating a valuable data-as-a-service offering.
Industry Challenges
- Legacy System Integration:Connecting modern smart lighting networks with older, disparate airport operational systems, such as building management systems (BMS) and flight information displays, requires significant custom engineering and poses major technical hurdles.
- Skilled Labor Scarcity:Implementing and maintaining complex IoT-based lighting systems demands a workforce with hybrid expertise in lighting engineering, IT networking, and data management, a skill set that is currently in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Smart Lighting Market |
| Market Size in 2026 | $920.4 Million |
| Market Size in 2035 | $2,471.46 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Smart Controls, Sensors, Fixtures Technology: IoT, Wireless, Optical, Energy Harvesting Application: Runways, Taxiways, Terminals, Parking Areas End User: Airport Authorities, Airlines, Contractors, Facility Managers |
| Companies Covered | Siemens AG, ADB Safegate Group, Honeywell International, Astronics Corporation, Zumtobel Group AG, Signify N.V., General Electric Company, Avlite Systems Pty Ltd, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Smart Lighting Market Strategic Shifts & Innovations
The market is evolving from viewing lighting as a passive, fixed utility to an active, data-generating infrastructure asset. This transformation is driven by the convergence of solid-state lighting with IoT connectivity, creating intelligent networks that enhance operational efficiency and airport security.
Wireless mesh networking protocols are a key enabling technology, allowing luminaires to communicate directly with each other without requiring a central controller or extensive data cabling. Airport operators in both terminal and landside applications are adopting this technology to gain deployment flexibility and reduce installation costs. The use of wireless mesh networks is consolidating system control from siloed, hardwired panels to a more resilient and scalable distributed intelligence architecture.
Regulatory pressure from initiatives such as the US Inflation Reduction Act (IRA) provides tax incentives for energy efficiency upgrades in public infrastructure, including airports. This policy directly encourages the replacement of legacy lighting with smart LED systems to lower operational expenditures and meet sustainability goals. The terminal and parking garage segments are most affected, responding by accelerating planned retrofits to capitalize on the available financial benefits.
A notable behavioral shift involves airport authorities moving toward service-based procurement models for lighting infrastructure. Instead of a one-time capital purchase, some airports are adopting long-term agreements where providers are responsible for installation, ongoing maintenance, and guaranteed performance levels for a recurring fee. This trend is most prominent in large North American and European hub airports seeking to convert capital expenditures into predictable operational costs.
Airport Smart Lighting Market Segmentation
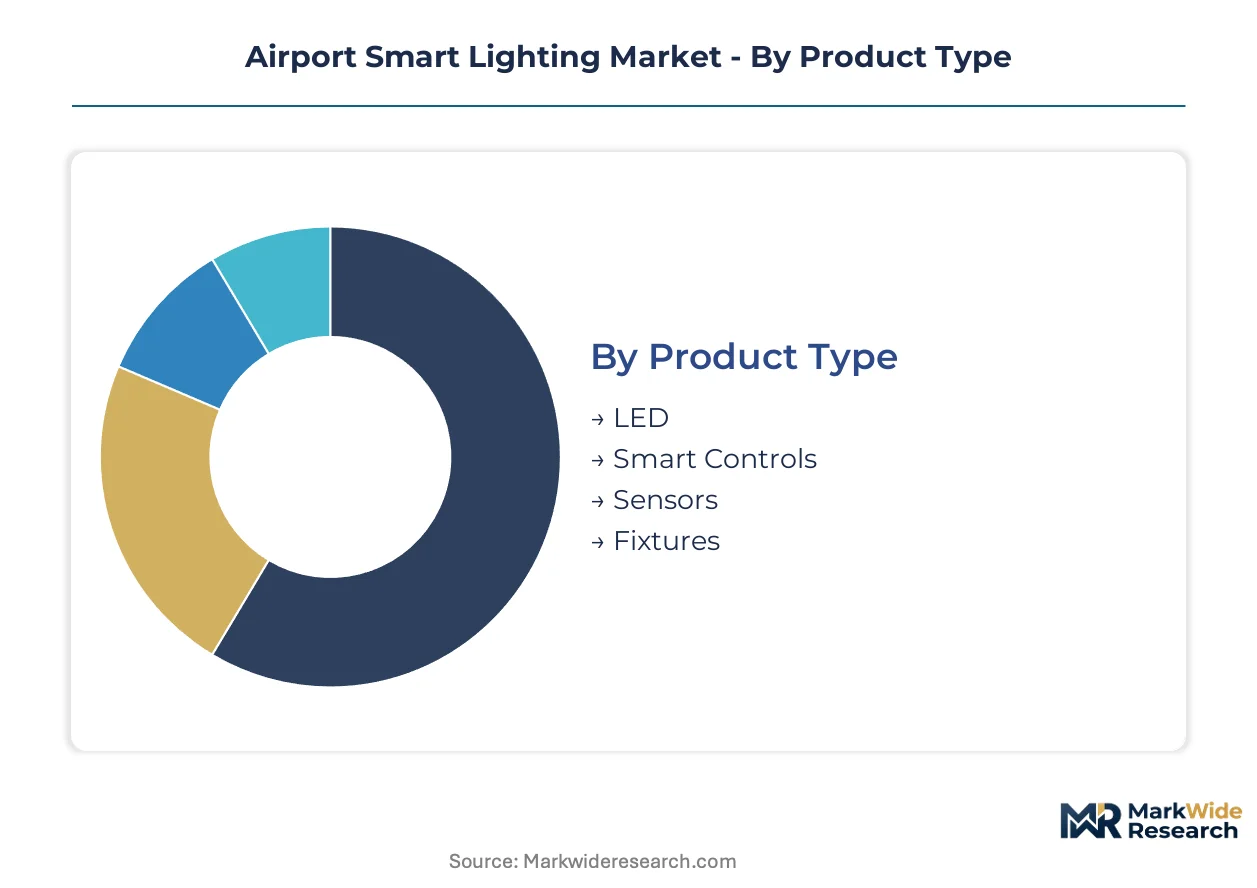
The airport smart lighting market segments by distinct product types, enabling technologies, operational applications, and key end-users. This segmentation allows for a granular understanding of demand drivers and competitive dynamics across the aviation infrastructure landscape.
Product Type:
The market for airport smart lighting components is differentiated by their core functional specifications and integration capabilities.
- LED:These solid-state lighting devices form the foundational light source for all smart lighting systems, offering superior energy efficiency and longevity. Demand concentrates in terminal and airside retrofits across European airports, driven by EU Green Deal mandates.
- Smart Controls:This segment includes hardware and software for managing lighting networks, enabling dynamic adjustments and data collection. North American airports prioritize smart controls for energy management and operational efficiency, integrating them into existing building management systems.
- Sensors:These devices detect occupancy, ambient light, and movement, providing real-time data for automated lighting adjustments and system optimization.
- Fixtures:This category encompasses the physical housing and optical elements that integrate light sources and often include embedded smart components.
LED components lead on installed scale; Smart Controls lead on momentum.
Technology:
The technological underpinnings of airport smart lighting systems are defined by their application in creating interconnected and data-rich environments.
- IoT:IoT-enabled systems integrate sensors, connectivity, and data analytics to optimize lighting performance, energy consumption, and predictive maintenance. Saudi Arabian and UAE airports are adopting IoT extensively in new greenfield projects to build future-ready infrastructure.
- Wireless:Wireless protocols facilitate communication between luminaires and control systems, reducing installation complexity and offering deployment flexibility. This technology is gaining traction in parking areas and landside applications, where extensive cabling is cost-prohibitive.
- Optical:Optical technologies relate to light distribution and quality, ensuring compliance with aviation standards for visibility and safety.
- Energy Harvesting:This technology captures ambient energy, such as solar or kinetic, to power low-energy smart lighting components in remote or off-grid locations.
IoT technology exhibits the steepest expansion trajectory, while wireless solutions rapidly expand deployment flexibility.
Application:
Airport smart lighting applications are segmented by the specific operational needs and regulatory requirements of different airport areas.
- Terminals:Terminal applications focus on enhancing passenger experience, guiding flow, and optimizing energy use in concourses, retail, and lounge areas. Operators prioritize tunable lighting and integration with passenger information systems in major European hubs.
- Runways:This segment demands high-reliability, precision lighting systems compliant with FAA and EASA standards for aircraft guidance and safety. Investment in runway lighting is critical for operational resilience at busy international airports.
- Taxiways:Taxiway lighting provides visual guidance for aircraft movement between runways, gates, and maintenance areas, requiring robust and compliant fixtures.
- Parking Areas:Smart lighting in parking garages and lots improves security, reduces energy consumption, and assists vehicle navigation through occupancy sensors.
Terminal applications drive significant value due to passenger-centric demands, while runway installations command premium pricing for critical safety functions.
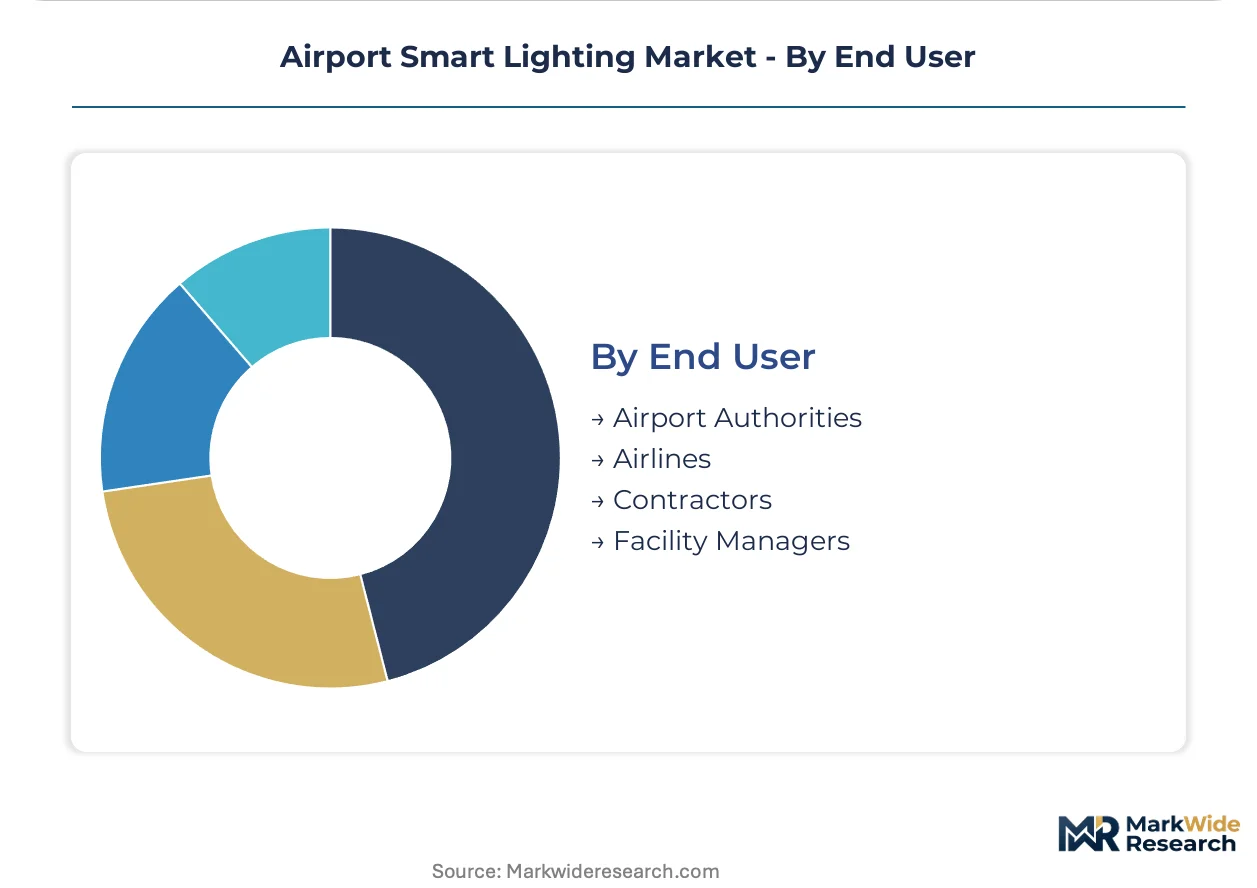
End User:
The end-user landscape for airport smart lighting is shaped by the primary stakeholders driving procurement and implementation decisions.
- Airport Authorities:These entities are the primary decision-makers and purchasers, responsible for overall airport infrastructure development, operations, and compliance. They prioritize long-term operational savings and regulatory adherence in their investment strategies.
- Contractors:Installation and integration contractors implement smart lighting systems, often working closely with authorities to ensure project delivery and technical specifications are met. Their role is crucial in translating design into operational systems.
- Airlines:Airlines influence lighting decisions related to gate areas and passenger boarding, focusing on branding consistency and operational efficiency for their specific ground services.
- Facility Managers:These professionals manage the day-to-day operation and maintenance of airport facilities, including lighting systems, seeking solutions that offer ease of control and predictive maintenance.
Airport Authorities represent the largest procurement volume, with contractors executing the majority of system deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The airport smart lighting market initially scaled in regions with significant aviation infrastructure development, particularly across North America and Europe. Early advancements in intelligent control systems and LED technology first found widespread adoption in these mature aviation markets. Demand drivers now extend globally, influenced by sustainability goals and passenger experience priorities.
United States
Demand for smart lighting systems in US airports stems from operational efficiency needs and enhanced security. The US Federal Aviation Administration (FAA) mandates stringent performance standards for airside lighting. Major aviation hubs like Atlanta Hartsfield-Jackson implement advanced smart lighting to manage passenger flow and reduce energy consumption.
Germany
German airports prioritize smart lighting solutions to meet ambitious EU Green Deal targets for energy efficiency. Public funding supports modernization of airport infrastructure with intelligent LED systems. Frankfurt Airport integrates smart controls to optimize terminal ambiance and airside safety.
Saudi Arabia
Saudi Arabia's extensive greenfield airport projects drive significant demand for integrated smart lighting. The Kingdom's Vision 2030 supports sustainable and technologically advanced aviation facilities. New developments like King Salman International Airport incorporate IoT-enabled lighting from the ground up.
United Arab Emirates
The United Arab Emirates focuses on smart lighting to enhance passenger experience and manage energy consumption. Regulations from the General Civil Aviation Authority (GCAA) encourage advanced safety technologies. Dubai International Airport utilizes adaptive lighting systems to improve navigation and reduce operational costs.
China
Chinese airports adopt smart lighting to align with the nation's dual carbon goals and support massive aviation infrastructure expansion. Government policies promote energy-efficient technologies and digital transformation. Beijing Daxing International Airport exemplifies large-scale integration of smart lighting for terminal and airside applications.
Airport Smart Lighting Market Key Industry Players
The competitive structure tilts toward integrated solution providers offering end-to-end smart lighting systems and services. The market features a blend of established industrial conglomerates and specialized lighting technology firms. Key archetypes include diversified industrial automation giants, dedicated aviation lighting specialists, and innovative IoT platform providers. Strategic partnerships for system integration and portfolio diversification across smart building technologies represent dominant competitive moves. Geographic expansion also remains a critical strategy for market share growth.
Within the diversified industrial automation giant archetype, Siemens AG leverages its broad portfolio to offer comprehensive terminal and airside solutions. Honeywell International, a US-based technology and manufacturing conglomerate, occupies a similar position by integrating lighting controls into its wider building management and security systems. Signify N.V., a Netherlands-based lighting specialist, anchors the dedicated aviation lighting segment, focusing on advanced LED fixtures and intelligent control platforms. These companies exemplify the trend towards offering bundled solutions rather than discrete components.
| Leading Market Players |
|---|
| Siemens AG |
| ADB Safegate Group |
| Honeywell International |
| Astronics Corporation |
| Zumtobel Group AG |
| Signify N.V. |
| General Electric Company |
| Avlite Systems Pty Ltd |
| Eaton Corporation |
| Others |
Cost & Logistics Intelligence
Skilled labor concentration in specialized aviation lighting engineering, particularly in European and North American manufacturing hubs, contributes to higher labor-cost differentials which translate into pricing-tier spreads for airside solutions.
Pricing Analysis
Project-based pricing dominates the airport smart lighting market, reflecting the custom engineering and integration required for each installation. Price differentiation stems from the specific aviation certification level of fixtures and the extent of post-installation service level agreements. Pricing pressure stems from the commoditization of standard LED components in terminal applications, particularly for large volume orders. Smaller regional airports exhibit higher price sensitivity compared to major international hubs, which prioritize long-term operational reliability and compliance.
Supply Chain Analysis
Logistics and freight costs significantly influence the final pricing of specialized airside lighting components due to their weight and often oversized dimensions for international shipping. Geographic supply concentration for smart lighting components rests primarily in China for standard LEDs and sensors, with specialized airside fixtures and advanced control systems often sourced from Germany and the Netherlands. The supply chain depends on critical raw materials such as rare earth elements for high-performance LEDs and specialized semiconductors for control units. Regulatory restrictions on certain electronic components present a structural risk. Distribution runs through a network of specialized system integrators and electrical contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a margin-expansion story, driven by the shift towards service-based procurement models that offer predictable recurring revenue streams for providers.
For Market Incumbents:Anticipate continued demand for integrated solutions by investing in R&D for advanced IoT connectivity and data analytics platforms. Bundle comprehensive cybersecurity services with networked lighting systems to counter potential vulnerabilities and offer a complete security posture. Focus on securing long-term service contracts that guarantee performance and maintenance, mitigating the threat of lower-cost, less integrated solutions. Leverage existing relationships with airport authorities to reinforce market position and influence future procurement standards.
For New Entrants and Emerging Players:Electrical contractors and system integrators represent crucial channel partners for market entry, particularly for modular retrofit solutions. Target the large installed base of airports that have already upgraded to basic LED but lack intelligent controls. Focus on developing cost-effective, wireless control modules compatible with existing non-smart LED fixtures. A go-to-market angle emphasizing rapid deployment and demonstrable energy savings for small and medium-sized airports provides significant white space.
For Investors and Strategic Acquirers:Valuations sit cheapest among specialized lighting technology firms with strong intellectual property in wireless protocols or sensor integration, but limited global distribution. The long-term viability of the airport smart lighting market remains strong, driven by global sustainability mandates and continuous airport infrastructure modernization. Target IoT platform providers with proven capabilities in data analytics and predictive maintenance for operational efficiency. The signal to watch is the increasing adoption rate of service-based procurement models by major European and North American hub airports.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Modular Retrofit Solutions | Allows access to the substantial base of airports that have already installed basic LED systems. |
| Integrate Cybersecurity Services | Addresses growing concerns over networked system vulnerabilities, enhancing trust for airport operators. |
| Expand Service-Based Procurement Models | Converts upfront capital expenditures into predictable operational costs for airport authorities. |
| Invest in IoT Data Analytics Platforms | Unlocks new revenue streams through data-as-a-service offerings for airport optimization. |
| Pursue Strategic Partnerships for System Integration | Enhances interoperability with existing airport operational systems, reducing implementation complexity. |
Research Approach
Multiple input streams — primary interviews with industry experts, extensive secondary research, and quantitative modeling — were reconciled to construct a comprehensive market overview. This approach involved deep dives into technological advancements and regulatory landscapes across various geographies. Insights were derived from a synthesis of qualitative and quantitative data points.
The analytical framework systematically integrated data streams to project market growth across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional adoption rates. Compound annual growth rates were derived from historical data trends and projected future demand, considering factors like airport infrastructure investment and energy efficiency mandates. The framework accounted for the interplay between technological innovation and policy drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts, technological disruptions, and economic downturns. Forecasts reflect assumptions documented through expert consensus and historical market behavior. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Airport Baggage Conveyor System Market
Airport Technologies
Global Remote Towers Market
Airport Technologies
Advanced Airport Technologies Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
North America Smart Airport Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
Commercial Airport Baggage Handling Systems Market
Airport Technologies
Asia-Pacific Airport Ground Handling Systems Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
Smart Airport Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Airport RFID System Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Airport Airside Service Market
Airport Technologies
Europe Airport Ground Handling Systems Market