
 Commercial Airport Radar Systems Market | 2026-2036
Commercial Airport Radar Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Airport Radar Systems Market Outlook
Shortages of certified radar systems engineers and air traffic control integration specialists is redrawing how manufacturers allocate technical talent across product lines. Thales Group leverages its deep bench of avionics engineers to sustain long-term service contracts with European hub airports. Raytheon Technologies Corporation anchors its position through captive semiconductor fabrication for phased array transmit-receive modules. Saab AB competes in the Nordic and Baltic markets by specializing in mobile deployable radars for contingency airfield operations.
Commercial airport radar systems detect, track, and identify aircraft and surface vehicles using radio frequency pulses in the L-band through X-band spectrum, with typical detection ranges from 60 nautical miles for terminal area coverage to 250 nautical miles for en-route surveillance. These systems enable safe separation minima, runway incursion prevention, and weather hazard alerting for civil aviation authorities and airport operators. Secondary radar dominates installed base value due to Mode S transponder mandates, while surface movement radar captures expanding margin pools as A-SMGCS upgrades proliferate at Category III airports. Phased array technology leads R&D allocation because electronic beam steering eliminates mechanical azimuth drive maintenance and enables multi-target tracking refresh rates below one second.
FAA NextGen requirements and EUROCONTROL SESAR standards dictate minimum surveillance performance specifications that filter out non-compliant suppliers from North American and European procurement cycles. The International Civil Aviation Organization's Annex 10 and national regulators including EASA and the UK's Civil Aviation Authority enforce interoperability protocols that shape product development roadmaps. Stakeholders must monitor how dual-use technology export controls affect component sourcing for phased array subsystems sourced from defense-centric supply chains.
Market Dynamics
The commercial airport radar systems market pivots on the forced obsolescence of mechanically scanned antennas as electronic beam steering achieves cost parity and reliability superiority. FAA NextGen mandates and EUROCONTROL SESAR deployment timelines compress replacement cycles for legacy primary and secondary surveillance radars across major hub airports.
Growth Catalysts
- Mode S Transponder Mandates:ICAO Annex 10 requirements for enhanced surveillance data exchange are forcing upgrades at airports across India, Brazil, and Indonesia. Terminal area radars must integrate Mode S interrogators to support reduced separation minima.
- Surface Movement Radar Expansion:A-SMGCS upgrades at Category III airports drive demand for millimeter-wave surface surveillance. European hub operators in Germany, France, and the Netherlands prioritize incursion prevention systems.
- Phased Array Semiconductor Cost Curves:Gallium nitride transmit-receive module yields from defense-industrial suppliers are crossing commercial viability thresholds. Solid-state architectures now undercut magnetron lifecycle costs.
Market Restraints
- Dual-Use Export Control Friction:Phased array subsystems face ITAR and EAR restrictions when sourced from defense-centric supply chains in the United States and European Union. Component qualification timelines extend procurement cycles.
- Certified Engineering Talent Scarcity:Air traffic control integration specialists and radar systems engineers concentrate at legacy manufacturers and national aviation authorities. Airport operators compete for scarce commissioning expertise.
- Mechanical Radar Spare Part Obsolescence:Azimuth drive systems and klystron transmitters from 1980s-1990s installations face discontinued supplier support. Sustaining engineering costs escalate for aging en-route surveillance infrastructure.
Strategic Opportunities
- Tier-2 and Tier-3 Airport Modernization:India's Regional Connectivity Scheme and Indonesia's airport expansion programs create greenfield demand for integrated surveillance systems. First-mover suppliers capture long-term service contracts.
- Mobile Deployable Radar Niches:Contingency airfield operations and humanitarian relief logistics require rapidly emplaced surveillance. Nordic and Baltic defense-civil coordination programs fund dual-use platform development.
- Weather-Radar Convergence:Terminal Doppler weather radar and primary surveillance functions merge through shared phased array apertures. Multi-function architectures reduce total site infrastructure costs.
Industry Challenges
- Legacy System Integration Complexity:New phased array installations must interoperate with existing Mode A/C transponder populations and analog voice switching systems. Retrofit engineering consumes 40% of project man-hours.
- Air Traffic Control Certification Timelines:National regulators including EASA, the UK's Civil Aviation Authority, and the FAA impose multi-year operational approval processes. Software-defined radar updates trigger re-certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Airport Radar Systems Market |
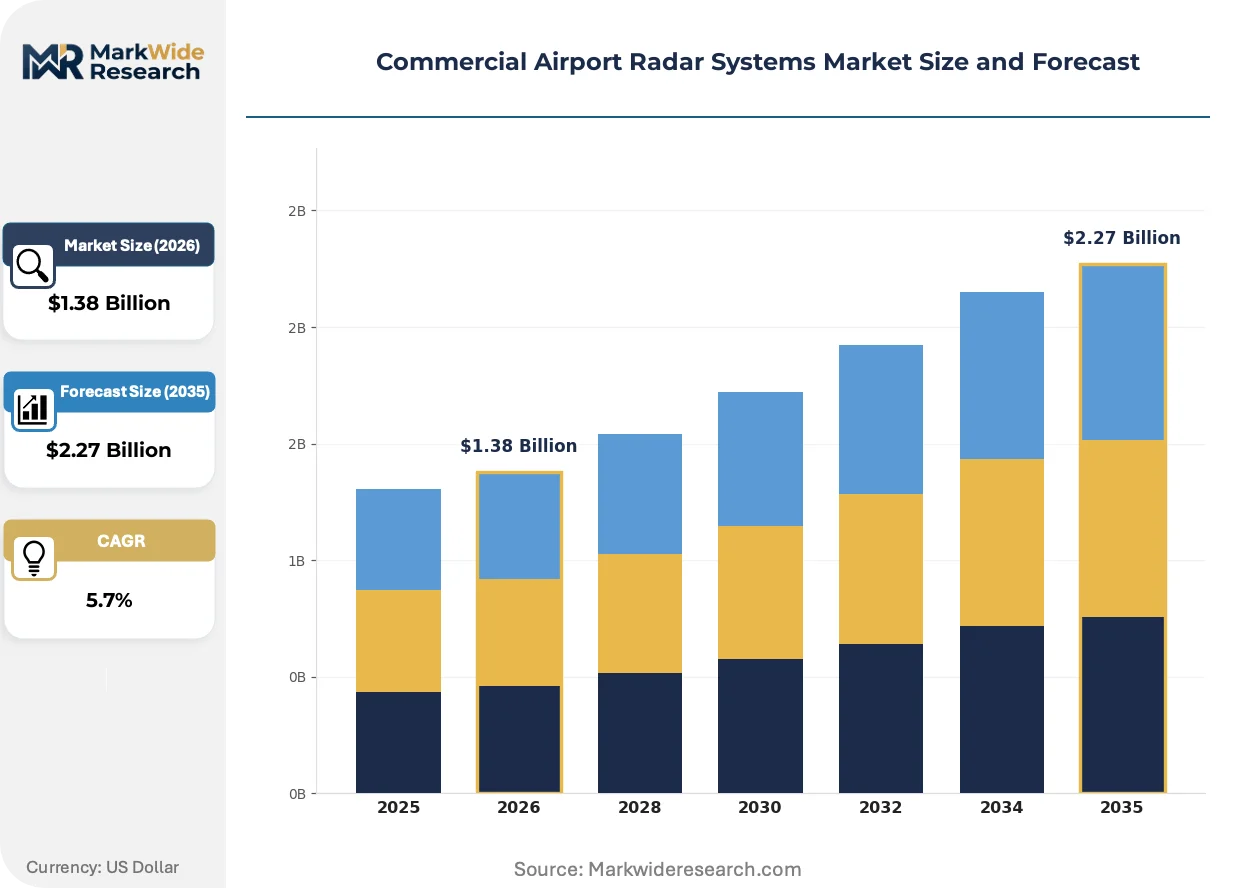
| Market Size in 2026 | $1.38 Billion |
| Market Size in 2035 | $2.27 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Radar, Secondary Radar, Surface Movement Radar, Weather Radar Technology: Pulse Doppler, MTI, Phased Array, Frequency Modulation End User: Airports, Air Traffic Control, Airlines, Defense Installation Type: Ground-Based, Airborne, Mobile, Fixed |
| Companies Covered | Thales Group, Honeywell International Inc., Raytheon Technologies Corporation, Indra Sistemas S.A., Saab AB, Northrop Grumman Corporation, Leonardo S.p.A., Hensoldt AG, BAE Systems Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Airport Radar Systems Market Strategic Shifts
Active electronically scanned array technology is compressing the installed base of mechanically steered radars while regulatory mandates synchronize upgrade cycles across major aviation markets. Three converging developments reshape competitive positioning and procurement patterns.
Phased array architectures with solid-state transmit-receive modules are displacing magnetron-powered parabolic dish systems in terminal area applications. Major European hub operators in Germany and France now specify electronic beam steering for all new secondary radar procurements. The technology eliminates mechanical azimuth drive maintenance and enables sub-second multi-target tracking refresh rates.
FAA NextGen requirements and EUROCONTROL SESAR standards enforce minimum surveillance performance specifications that filter non-compliant suppliers from North American and European procurement cycles. These mandates accelerate replacement of 1990s-era primary surveillance radars at en-route centers. Product development roadmaps at surviving vendors prioritize dual-use semiconductor sourcing strategies.
Airport operators increasingly unbundle hardware procurement from long-term service contracts, compressing vendor switching cycles. Nordic and Baltic markets lead this transition, with Swedish and Finnish airport authorities separating radar purchase from maintenance agreements. The shift rewards suppliers with captive semiconductor fabrication and penalizes pure-systems integrators.
Commercial Airport Radar Systems Market Segmentation
Radar system procurement patterns diverge sharply across product architectures and deployment contexts. Margin capture depends on matching semiconductor cost curves to regulatory mandate timelines in each segment.
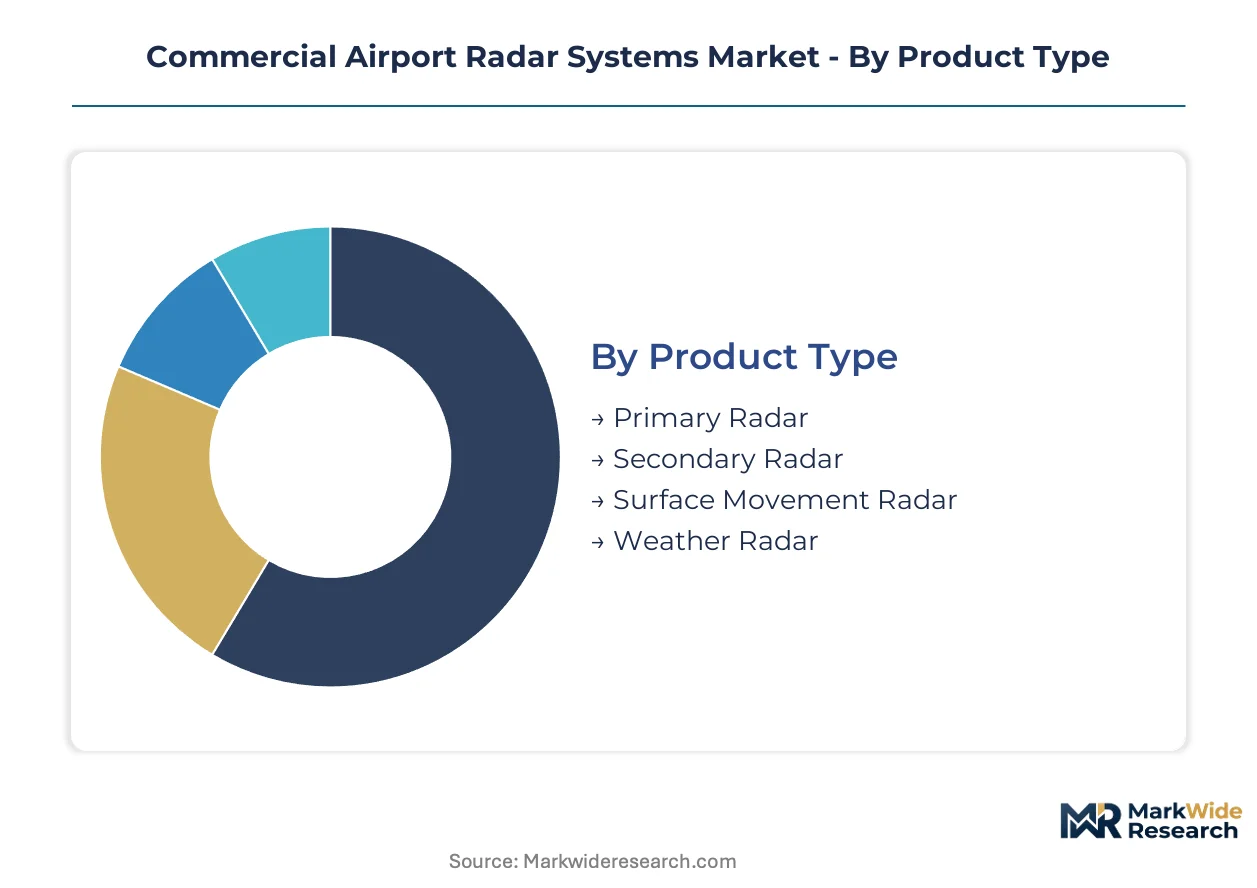
Product Type:
Secondary radar commands the deepest margin pools due to Mode S transponder mandates and recurring interrogator maintenance revenue.
- Primary Radar:Mechanically scanned parabolic dish systems detect aircraft position without transponder cooperation. India's Airports Authority of India deploys these at tier-2 airports under regional connectivity schemes where secondary radar infrastructure remains uneconomical.
- Secondary Radar:Mode S interrogators extract aircraft identity, altitude, and velocity from transponder replies. FAA NextGen mandates and EUROCONTROL SESAR specifications force replacement cycles at German, French, and Dutch hub airports, locking in long-term service contracts.
- Surface Movement Radar:Millimeter-wave systems track aircraft and vehicles on taxiways and runways. A-SMGCS upgrades at Category III airports drive procurement.
- Weather Radar:Terminal Doppler systems detect wind shear and precipitation hazards. Convergence with primary surveillance functions through shared phased array apertures is reducing standalone deployments.
Secondary radar holds installed capacity. Surface movement radar is rotating up the share rankings.
Technology:
Pulse Doppler architectures still dominate unit volumes in emerging markets, though semiconductor cost curves are compressing phased array adoption timelines.
- Pulse Doppler:Conventional magnetron-powered systems transmit coherent pulse trains to measure target velocity via Doppler shift. Brazil and Indonesia rely on these for cost-constrained terminal area coverage.
- MTI:Moving target indication processors cancel stationary clutter to highlight aircraft returns. Legacy en-route centers in the United States maintain these for compatibility with existing display systems.
- Phased Array:Active electronically scanned arrays steer beams electronically without mechanical azimuth drives. Solid-state gallium nitride transmit-receive modules now undercut magnetron lifecycle costs at European hub airports.
- Frequency Modulation:Continuous-wave FM techniques enable low-probability-of-intercept surveillance. Nordic defense-civil coordination programs fund dual-use platform development for contingency airfield operations.
Phased array climbs the fastest as electronic beam steering achieves reliability superiority. Pulse Doppler retains share in cost-sensitive procurement cycles.
End User:
Airport operators concentrate procurement authority, though air traffic control integration requirements shape specification details.
- Airports:Hub and regional airport authorities own radar infrastructure and contract integration services. Tier-2 and tier-3 modernization in India and Indonesia creates greenfield demand.
- Air Traffic Control:National ANSPs specify surveillance performance standards and certify operational approval. FAA, EUROCONTROL, and India's DGCA impose multi-year certification timelines.
- Airlines:Carriers rarely procure ground radar directly but influence surface movement requirements through A-CDM participation.
- Defense:Military contingency airfield programs fund mobile deployable radar development. Dual-use export controls from ITAR and EAR constrain component sourcing.
Airports anchor procurement volume. Air traffic control specifications are tightening fastest.
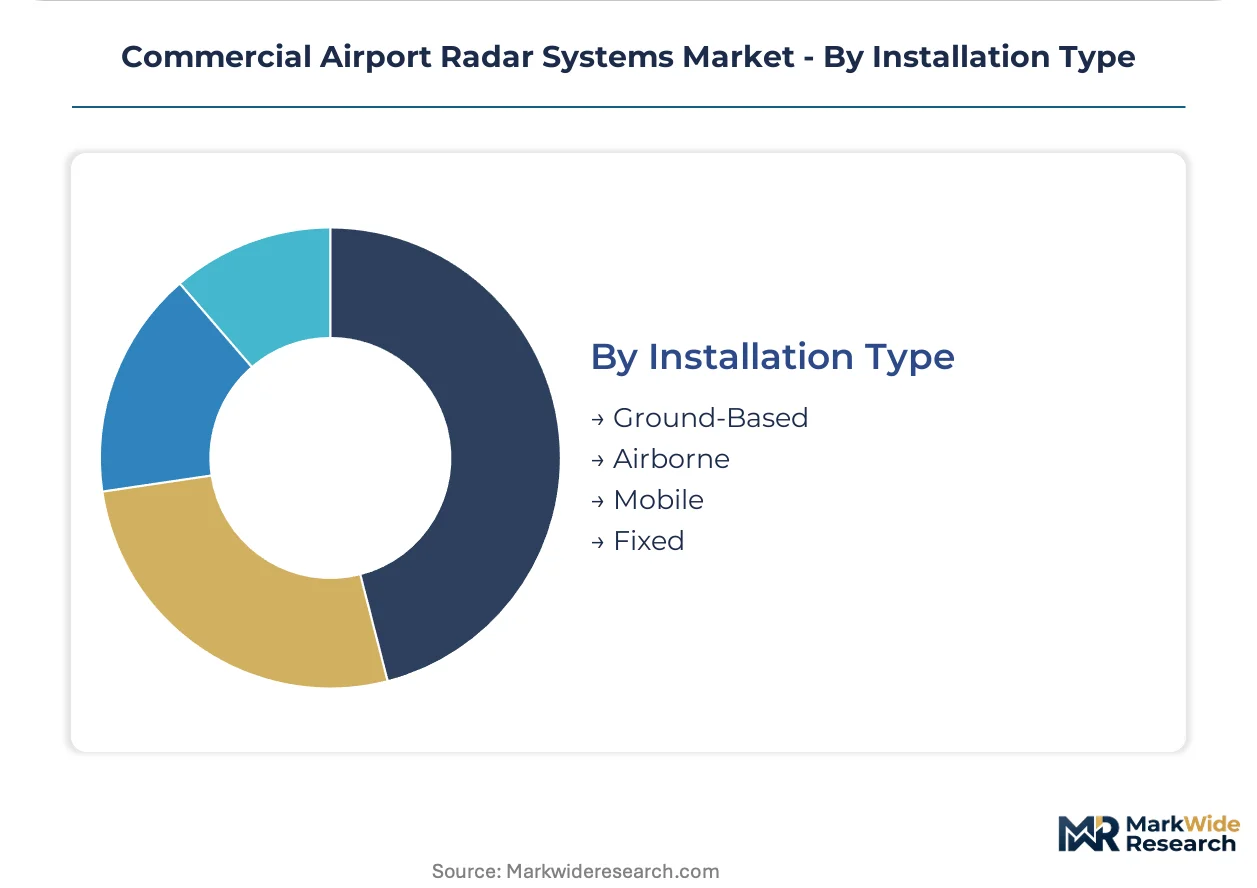
Installation Type:
Ground-based fixed installations absorb capital budgets, though mobile platforms capture contingency logistics niches.
- Ground-Based:Fixed-site radar towers dominate terminal area and en-route surveillance. Site preparation and civil works consume 30% of project costs at greenfield airports.
- Airborne:Radar-equipped surveillance aircraft provide gap-filling coverage. These supplement fixed infrastructure during outages or special events.
- Mobile:Rapidly emplaced trailer-mounted systems serve humanitarian relief and military contingency operations. Saab AB specializes in this niche for Nordic and Baltic markets.
- Fixed:Permanent installations with dedicated power and communications infrastructure support 24/7 operations. Retrofit engineering for legacy integration consumes 40% of project man-hours.
Ground-based fixed systems hold installed base value. Mobile platforms are gaining share in contingency logistics procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. European hub operators prioritize phased array replacements for en-route surveillance, while Indian regional connectivity schemes emphasize cost-optimized primary radar at tier-2 airports. North American procurement concentrates on NextGen-compliant secondary radar with Mode S interrogators.
United States
FAA NextGen mandates compress replacement cycles for 1990s-era primary surveillance radars at en-route centers. The Federal Aviation Administration imposes minimum surveillance performance specifications that filter non-compliant suppliers from procurement cycles. Dallas-Fort Worth and Atlanta hubs drive demand for integrated surface movement radar under A-SMGCS upgrade programs.
Germany
EUROCONTROL SESAR deployment timelines accelerate secondary radar replacements at Frankfurt and Munich hub airports. The country's national aviation regulator enforces interoperability protocols that shape product development roadmaps. Bavaria's defense-industrial corridor supplies gallium nitride transmit-receive modules for phased array subsystems.
India
The Airports Authority of India expands radar coverage at tier-2 and tier-3 airports under regional connectivity schemes. The Directorate General of Civil Aviation mandates Mode S transponder integration for reduced separation minima. Maharashtra and Karnataka clusters concentrate greenfield airport development with integrated surveillance procurement.
France
Charles de Gaulle and Orly hub operators specify electronic beam steering for all new secondary radar procurements. EASA enforces multi-year operational approval processes that extend certification timelines. The Île-de-France region anchors demand for millimeter-wave surface surveillance systems under A-SMGCS upgrades.
Sweden
Nordic defense-civil coordination programs fund dual-use mobile deployable radar development for contingency airfield operations. The Swedish Transport Agency separates radar purchase from maintenance agreements, compressing vendor switching cycles. Stockholm-Arlanda exemplifies the unbundling trend reshaping procurement patterns.
Commercial Airport Radar Systems Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive semiconductor fabrication distinguishing the upper tier from pure-systems integrators. Market structure rewards suppliers with in-house gallium nitride transmit-receive module production and long-term service contract capabilities. Two strategic archetypes dominate: vertically integrated defense-electronics conglomerates with dual-use supply chains, and regional specialists in mobile deployable platforms. Competitive moves concentrate on backward integration into semiconductor sourcing and geographic expansion through local partnership structures.
Among European-integrated conglomerates, Thales Group and Leonardo S.p.A. exemplify the upper-tier archetype with deep benches of avionics engineers and sustained relationships with hub airport authorities. Raytheon Technologies Corporation anchors the North American position through captive semiconductor fabrication for phased array subsystems. Saab AB occupies a specialist niche, representing the mobile deployable radar segment for Nordic and Baltic contingency operations.
| Leading Market Players |
|---|
| Thales Group |
| Honeywell International Inc. |
| Raytheon Technologies Corporation |
| Indra Sistemas S.A. |
| Saab AB |
| Northrop Grumman Corporation |
| Leonardo S.p.A. |
| Hensoldt AG |
| BAE Systems Plc |
| Others |
Value Chain & Pricing Dynamics
Long-term service contracts with integrated maintenance clauses lock in both gallium nitride transmit-receive module supply and decade-long price visibility for European hub airport operators. These agreements shield tier-1 manufacturers from spot-market semiconductor volatility while binding buyers to single-source dependencies.
Pricing Analysis
Project-based procurement with unbundled hardware and service components now dominates Nordic and Baltic markets, compressing vendor switching cycles. Three-tier pricing structure across premium phased array, standard pulse Doppler, and economy primary radar levels separates certification-grade systems from regional connectivity deployments. Cost compression in pulse Doppler tiers is intensifying because Indian and Indonesian airport authorities prioritize capital efficiency over electronic beam steering. Tier-2 and tier-3 airport operators exhibit highest price sensitivity, while Category III hub airports in Germany and France accept premium positioning for A-SMGCS integration.
Supply Chain Analysis
Defense-industrial semiconductor fabrication in the United States, Germany, and Japan anchors gallium nitride transmit-receive module availability for active electronically scanned arrays. Raw material dependencies span high-purity gallium substrates, ceramic packaging substrates, and specialized thermal interface materials. Single-source vulnerability concentrates in ITAR-controlled foundries serving dual-use radar applications. Distribution runs through national aviation authority procurement frameworks with multi-year qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified radar systems engineers and air traffic control integration specialists are concentrated at legacy manufacturers and national regulators, creating acquisition bottlenecks that reshape competitive dynamics. This scarcity forces airport operators to compete for commissioning expertise across product lines.
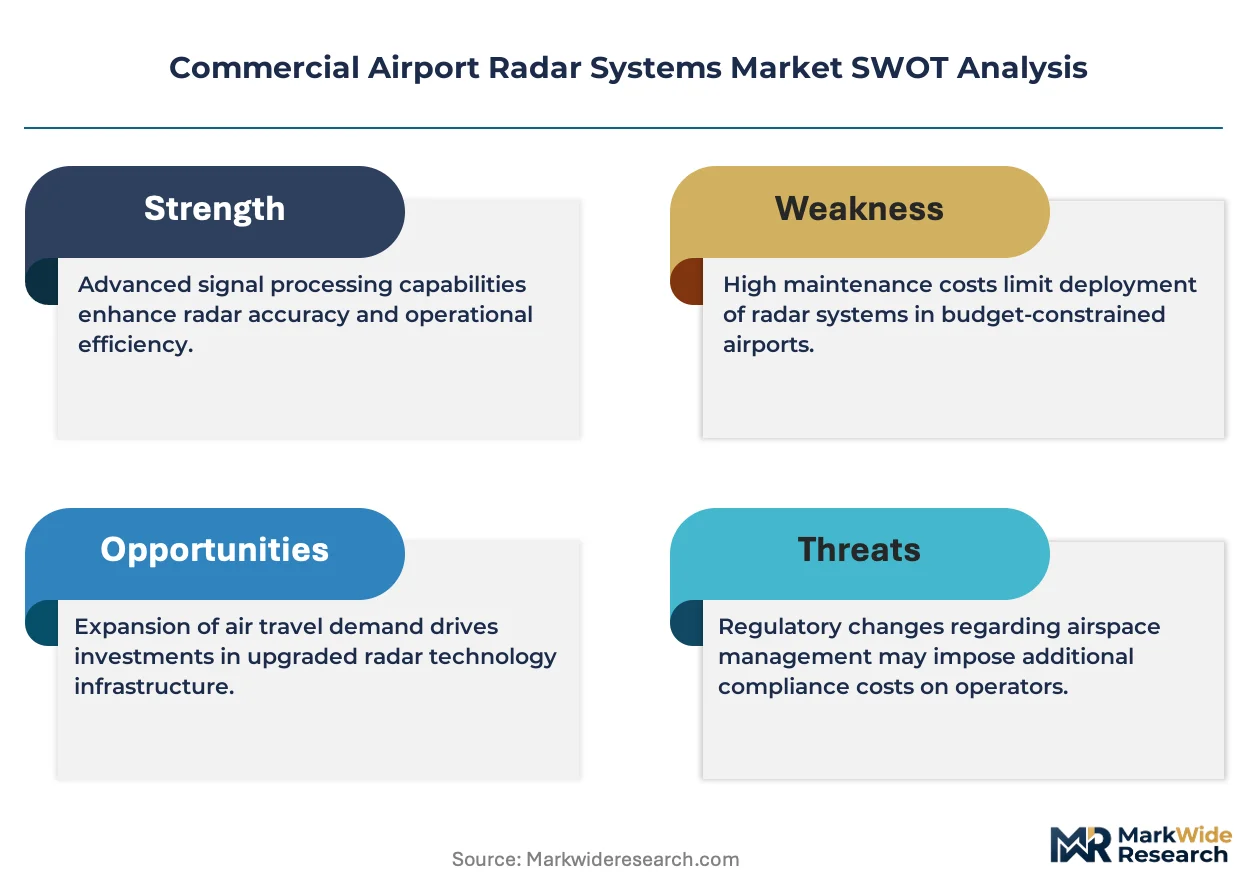
For Market Incumbents: Secure captive semiconductor fabrication capacity for phased array subsystems before ITAR and EAR restrictions tighten further. Deepen backward integration into gallium nitride foundry relationships to defend against emerging entrants with defense-civil dual-use platforms. Lock in long-term service contracts at Indian tier-2 airports under regional connectivity schemes. For New Entrants and Emerging Players: Anchor in mobile deployable radar niches for Nordic and Baltic contingency airfield operations, where defense-civil coordination programs fund dual-use platform development. Target India's tier-3 greenfield airports with cost-optimized primary radar bundles. Lead with rapid deployment capabilities and simplified certification pathways. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with integrated service contracts and captive semiconductor fabrication, positioning them for sustained cash flow quality. Prioritize acquisition targets with in-house gallium nitride transmit-receive module production and established relationships with European hub airports. Monitor FAA NextGen and EUROCONTROL SESAR mandate acceleration as inflection indicators for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Fabrication | In-house gallium nitride foundry capacity insulates against ITAR and EAR export control friction. |
| Long-term Service Contract Unbundling | Separating hardware procurement from maintenance agreements compresses vendor switching cycles at Nordic airports. |
| Mobile Deployable Platform Development | Rapidly emplaced trailer-mounted systems capture contingency logistics demand from defense-civil programs. |
| Tier-2 and Tier-3 Airport Modernization | India's Regional Connectivity Scheme creates greenfield demand for cost-optimized surveillance procurement. |
| Weather-Radar Convergence R&D | Shared phased array apertures for terminal Doppler and primary surveillance reduce total site infrastructure costs. |
Study Parameters
Desk research of FAA NextGen implementation timelines, EUROCONTROL SESAR deployment documentation, and ICAO Annex 10 surveillance specifications preceded structured interviews with radar systems engineers, air traffic control integration specialists, airport procurement directors, and national aviation authority certification leads. Secondary validation drew from customs trade data for radar component imports, SEC 10-K filings of defense-electronics conglomerates, and national regulator procurement disclosures. Bottom-up unit deployment estimates across product architectures triangulated with top-down market sizing from replacement cycle analysis.
Variance decomposition across technology adoption curves, regulatory mandate phasing, and semiconductor cost trajectories shaped the analytical framework. Segmentation dimensions modeled include radar product type, technology architecture, end-user category, and installation format across the projection horizon. CAGRs derived from fitted adoption curves for phased array displacement of mechanically scanned systems, with inputs from gallium nitride yield improvement trajectories and Mode S transponder mandate enforcement schedules.
Material uncertainties — dual-use export control expansion, certified engineering talent attrition, and legacy spare part obsolescence acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline adherence and semiconductor supply continuity. Practitioners should keep alternative scenarios live as FAA and EUROCONTROL mandate enforcement intensity evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Smart Airport 4.0 Market
Airport Technologies
Airport Runway Foreign Object Debris (FOD) Detection Systems Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Airport Information Systems Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Smart Airport Market
Airport Technologies
Asia-Pacific Airport Baggage Handling Systems Market
Airport Technologies
Europe Smart Airport Market
Airport Technologies
Smart Airport 2.0 Market
Airport Technologies
Global Remote Towers Market