
 Advanced Airport Technologies Market | 2026-2036
Advanced Airport Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Airport Technologies Market Analysis
Aftermarket service revenue is reshaping profitability across the Advanced Airport Technologies landscape as hardware margins compress and long-term support contracts expand. Thales Group leverages its command of air traffic management software to sustain recurring revenue streams across European hub upgrades. Siemens AG anchors its position through building automation and energy management systems that integrate with passenger processing infrastructure. Smiths Detection Group Ltd specializes in threat detection hardware and competes on certification breadth across multiple aviation security standards.
Advanced airport technologies encompass integrated digital and physical systems designed to automate, secure, and optimize airport operations, typically incorporating biometric authentication algorithms, IoT sensor networks, and real-time data analytics platforms operating at sub-second latency thresholds for passenger throughput management. Their primary commercial purpose is to reduce operational expenditure per passenger while elevating security efficacy and minimizing aircraft turnaround intervals. Biometric Screening within the Technology dimension is capturing disproportionate capital allocation as airports replace legacy document checks with facial recognition corridors. Passenger Processing applications dominate current deployment value, though Security Management systems are registering the fastest upgrade cycles as regulatory mandates for computed tomography baggage scanning proliferate.
The Federal Aviation Administration and the European Union Aviation Safety Agency enforce divergent certification pathways for automated boarding and navigation systems, compelling suppliers to maintain dual compliance architectures. The EU AI Act imposes risk-classification obligations on biometric screening algorithms deployed at Schengen Area entry points, directly conditioning product development roadmaps for vendors serving European airports. Stakeholders must monitor how emerging cybersecurity disclosure requirements from national aviation regulators will reshape procurement criteria and vendor qualification timelines.
Market Dynamics
Post-pandemic passenger volume recovery is compressing airport infrastructure upgrade timelines, forcing simultaneous deployment of biometric corridors, computed tomography baggage systems, and building automation platforms across terminals originally designed for lower throughput thresholds.
Growth Catalysts
- EU AI Act compliance mandates:Schengen Area airports must deploy risk-classified biometric algorithms, creating immediate procurement pull for vendors with pre-certified transparency documentation.
- Computed tomography baggage screening:ICAO standards are mandating next-generation threat detection, accelerating replacement cycles for legacy X-ray systems at security checkpoints.
- UAE-Singapore hub expansion:Mega-terminal construction in Dubai and Changi is absorbing fully integrated smart platform architectures, concentrating capital deployment in these jurisdictions.
Market Restraints
- Semiconductor supply concentration:Edge AI processors for facial recognition gates depend on fabrication capacity concentrated in Taiwan and South Korea, exposing deployment schedules to foundry allocation volatility.
- FAA-EASA certification divergence:Automated boarding systems require dual compliance architectures, extending vendor qualification timelines and inflating engineering overhead.
- Legacy infrastructure lock-in:Brownfield terminals in Germany and the United Kingdom face physical space constraints that prevent seamless biometric corridor retrofits without structural modification.
Strategic Opportunities
- India airport privatization wave:The Airports Authority of India is tendering greenfield terminals in Lucknow and Ahmedabad with embedded smart infrastructure specifications.
- AI-IoT convergence:Real-time passenger flow analytics platforms are merging with building management systems, enabling predictive energy optimization across terminal zones.
- Saudi Vision 2030 aviation cluster:King Salman International Airport construction is specifying fully automated passenger processing as a procurement baseline for all terminal systems.
Industry Challenges
- Cybersecurity certification complexity:National aviation regulators in France and Germany are imposing disclosure requirements for automated border control systems that lack harmonized standards, fragmenting vendor qualification protocols.
- Interoperability with legacy passenger service systems:Biometric boarding gates must interface with decades-old departure control databases, requiring costly middleware development for each airport operator.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Airport Technologies Market |
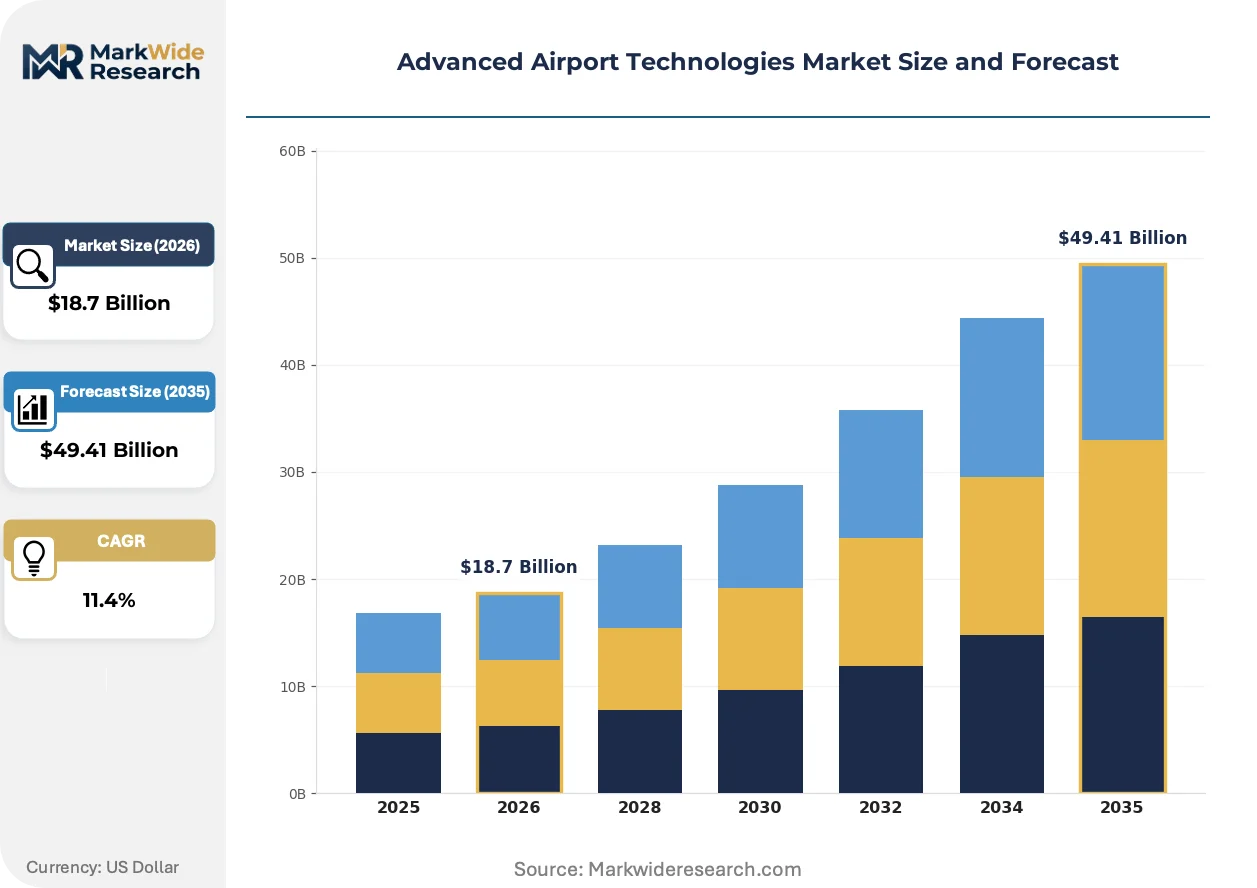
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Check-in, Automated Boarding, Baggage Tracking, Biometric Screening Application: Passenger Processing, Security Management, Baggage Handling, Navigation Systems End User: Airports, Airlines, Ground Handlers, Security Agencies Service Type: Operational Services, Maintenance Services, Consulting, Integration Services |
| Companies Covered | Honeywell International Inc., Thales Group, Raytheon Technologies, SITA, Siemens AG, Amadeus IT Group, Johnson Controls International PLC, L3Harris Technologies Inc., Smiths Detection Group Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Airport Technologies Market Emerging Trajectories
Algorithmic transparency requirements and edge computing architectures are restructuring how airport technology vendors design, certify, and deploy passenger processing systems across regulatory jurisdictions.
Contactless biometric corridors are migrating from pilot installations to standard terminal configurations. Major hub operators in Singapore and the United Arab Emirates are mandating facial recognition as the primary passenger identification modality. This technology is migrating from security checkpoints toward complete curb-to-gate passenger flow automation, compressing vendor roadmaps for integrated platform development.
The EU AI Act imposes conformity assessment obligations on biometric screening algorithms deployed at Schengen entry points. Vendors must document risk classification and algorithmic audit trails before system activation. European hub airports are responding by consolidating procurement around suppliers with pre-established EU regulatory dossiers, narrowing the qualified vendor pool.
Long-term service contracts are displacing transactional hardware sales as the dominant commercial model. Airport operators in Germany and France are unbundling maintenance from initial capital expenditure, favoring vendors with established local technical service presence. This shift is most visible in building automation and energy management segments, where fifteen-year performance guarantees are becoming standard procurement terms.
Advanced Airport Technologies Market Segmentation
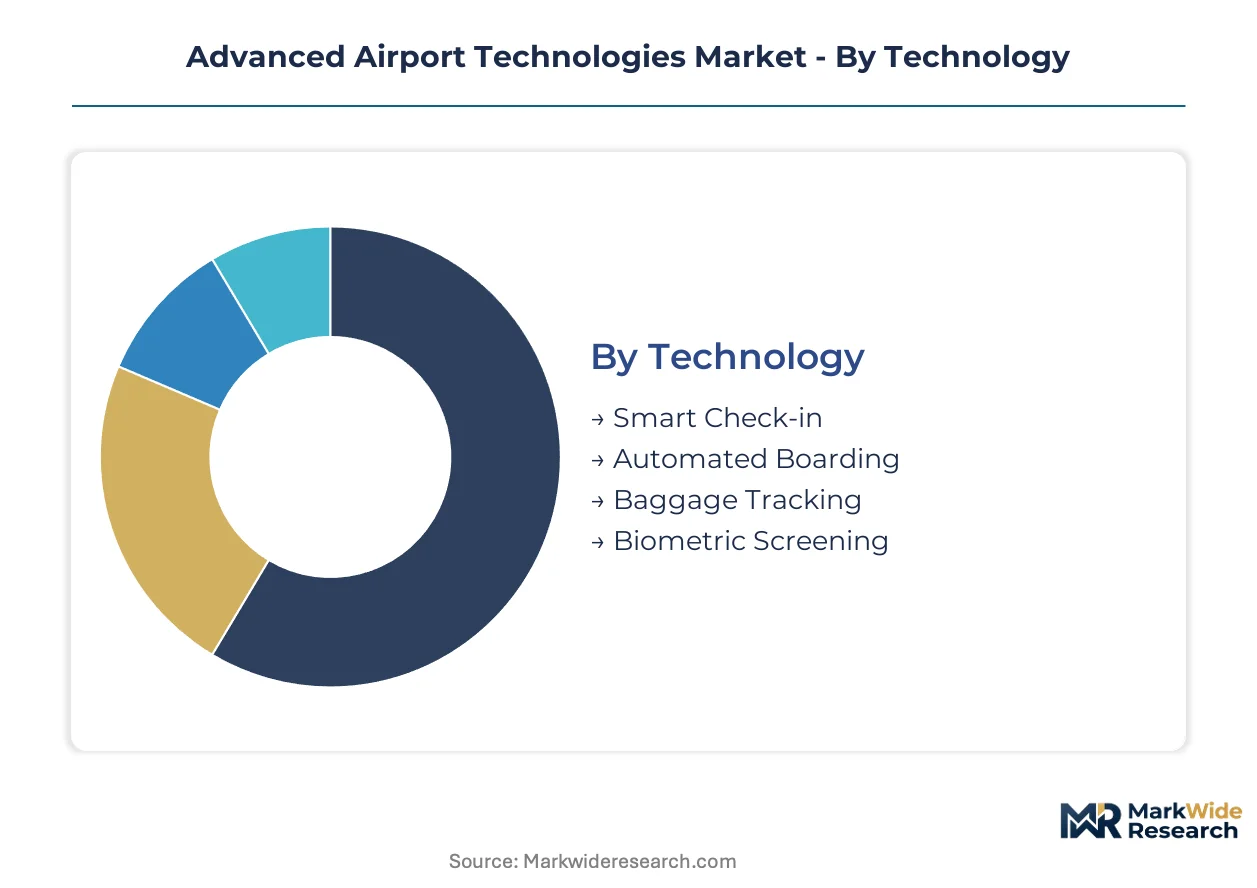
Segmentation in advanced airport technologies reveals how procurement decisions split between capital-intensive hardware deployments and recurring service obligations. Vendors must align their offerings across four distinct dimensions to capture value from divergent buyer priorities and regulatory contexts.
Technology:
After-sales service intensity varies sharply across technology segments, with biometric systems requiring continuous algorithm recertification and legacy hardware demanding obsolete parts sourcing.
- Biometric Screening:Facial recognition corridors and multimodal identity verification systems process passengers at sub-second latency thresholds. Demand concentrates in Singapore and Dubai mega-hubs where fully automated passenger flow is mandated; EU AI Act compliance documentation has become a non-negotiable procurement filter.
- Automated Boarding:Gate-based e-gates and self-boarding bridges eliminate manual document checks through integrated biometric validation. German and French hub operators are retrofitting existing gates under compressed timelines; FAA-EASA certification divergence extends vendor qualification cycles.
- Smart Check-in:Kiosk-based and mobile-enabled passenger processing systems with remote bag drop integration.
- Baggage Tracking:RFID and Bluetooth Low Energy tag systems for real-time luggage location monitoring across terminal zones.
Biometric Screening holds the largest share; momentum sits with Automated Boarding.
Application:
Cost tier stratification separates applications where hardware dominates procurement budgets from those where software and integration services absorb capital.
- Passenger Processing:End-to-end automation of check-in, security, and boarding workflows through unified biometric identity management. UAE and Singapore greenfield terminals specify fully integrated platforms; post-pandemic volume recovery is compressing brownfield upgrade timelines.
- Security Management:Computed tomography baggage scanners, automated threat detection algorithms, and access control systems. ICAO mandate acceleration is driving fastest replacement cycles; legacy X-ray system obsolescence creates immediate procurement windows.
- Baggage Handling:Automated sortation systems and robotic loading equipment for aircraft turnaround optimization.
- Navigation Systems:Surface movement guidance and airfield lighting control for ground traffic management.
Passenger Processing commands the largest deployment value; Security Management is climbing the fastest.
End User:
Customer type determines contract structure, with airports favoring long-term performance guarantees and airlines prioritizing interoperability with existing fleet systems.
- Airports:Terminal operators procuring integrated smart infrastructure across passenger touchpoints. Indian privatization wave in Lucknow and Ahmedabad specifies embedded automation; Saudi Vision 2030 aviation cluster mandates fully automated processing baselines.
- Airlines:Carriers deploying proprietary biometric boarding and loyalty integration systems at hub locations.
- Ground Handlers:Third-party service providers acquiring baggage and aircraft turnaround automation equipment.
- Security Agencies:Government border control authorities mandating algorithmic transparency for automated entry systems.
Airports represent the dominant buyer category; Security Agencies are expanding procurement fastest.
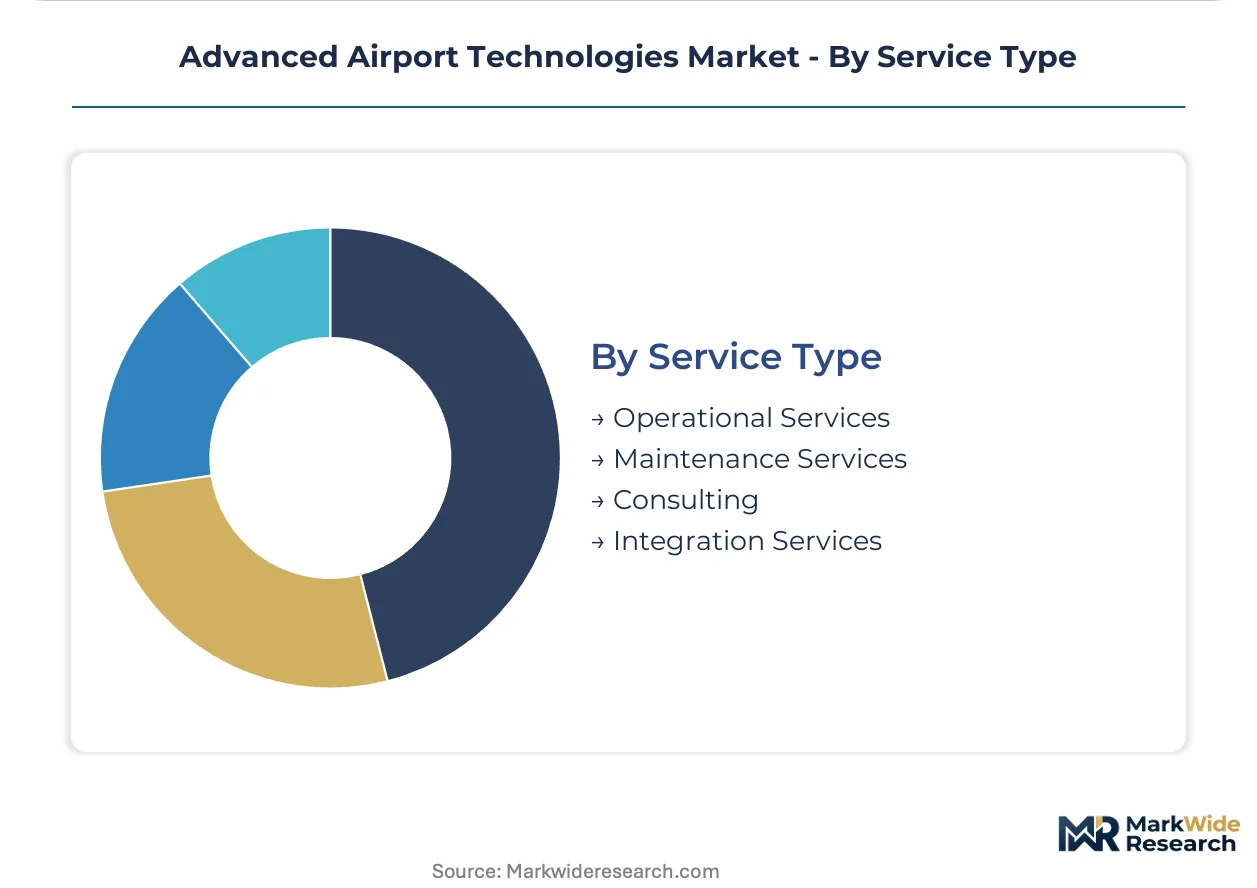
Service Type:
Margin structure diverges between transactional integration projects and recurring maintenance streams that extend across fifteen-year performance guarantee periods.
- Maintenance Services:Predictive upkeep, spare parts logistics, and firmware update management for deployed hardware fleets. German and French operators unbundle maintenance from capital expenditure; local technical service presence has become a decisive vendor selection criterion.
- Integration Services:Middleware development connecting biometric gates to legacy departure control databases and building management systems.
- Operational Services:Staffed system monitoring and passenger assistance during peak throughput periods.
- Consulting:Regulatory compliance advisory and technology roadmap planning for multi-phase terminal upgrades.
Maintenance Services generates the most predictable revenue; Integration Services faces steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between Gulf mega-hubs deploying fully integrated smart terminals and European brownfield sites constrained by legacy infrastructure retrofit costs.
United Arab Emirates
Dubai International and Al Maktoum International are absorbing fully automated passenger processing platforms under mega-hub expansion mandates. The General Civil Aviation Authority enforces stringent biometric system certification for border control applications. Abu Dhabi’s Zayed International Airport is consolidating procurement around vendors with pre-established Middle East technical service networks.
Singapore
Changi Airport Group mandates facial recognition as the primary identification modality across all terminal touchpoints. The Civil Aviation Authority of Singapore imposes sub-second latency requirements for biometric corridor throughput. The Changi East development is specifying integrated smart infrastructure as a baseline procurement condition for all terminal systems.
Germany
Frankfurt and Munich airports face compressed upgrade timelines for EU AI Act compliance on biometric algorithm risk classification. The Federal Office for Information Security imposes disclosure requirements for automated border control cybersecurity protocols. Berlin Brandenburg Airport exemplifies brownfield constraints where legacy departure control systems resist seamless biometric gate integration without costly middleware development.
India
The Airports Authority of India is tendering greenfield terminals in Lucknow and Ahmedabad with embedded automation specifications. The Bureau of Indian Standards is developing conformity assessment frameworks for biometric screening equipment procurement. Delhi International Airport is retrofitting existing terminals with computed tomography baggage scanners ahead of ICAO mandate deadlines.
Saudi Arabia
King Salman International Airport construction under Vision 2030 mandates fully automated passenger processing as a procurement baseline. The Saudi Food and Drug Authority regulates biometric data handling protocols for aviation security applications. The Riyadh aviation cluster is concentrating capital deployment from international vendors seeking long-term performance-guaranteed service contracts.
Advanced Airport Technologies Market Vendor Landscape
Capability concentration sits with specialized security technology developers; scale advantage sits with diversified industrial conglomerates with established aviation verticals. The vendor base stratifies across three tiers: integrated platform architects commanding mega-hub contracts, component specialists certified across multiple aviation security standards, and regional system integrators serving brownfield retrofit demand. Dominant competitive moves include strategic partnerships between biometric algorithm developers and hardware fabricators, plus geographic expansion through local technical service presence establishment.
Among diversified technology conglomerates, Honeywell International Inc., Siemens AG, and Thales Group exemplify contrasting strategic positions. Honeywell represents the building automation-to-aviation convergence archetype, anchoring energy management integration with passenger processing infrastructure. Siemens occupies a position emphasizing industrial automation heritage applied to terminal-wide system orchestration. Thales exemplifies the defense-to-civil technology transfer model, sitting within the tier where air traffic management software expertise sustains recurring revenue streams across European hub modernization cycles.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Thales Group |
| Raytheon Technologies |
| SITA |
| Siemens AG |
| Amadeus IT Group |
| Johnson Controls International PLC |
| L3Harris Technologies Inc. |
| Smiths Detection Group Ltd |
| Others |
Supply Flow & Price Mechanics
Taiwanese foundry capacity for edge AI processors directly conditions pricing power for biometric corridor vendors serving European and Gulf hub airports. Semiconductor allocation volatility feeds into extended delivery timelines and compressed margins for system integrators managing brownfield terminal retrofits.
Pricing Analysis
Long-term performance-guaranteed service contracts dominate procurement structures, displacing transactional hardware sales across German and French hub operators. Three-tier pricing structure across premium, standard, and economy levels differentiates vendors by EU AI Act pre-certification status and local technical service density. Cost compression in standard-tier biometric gates intensifies as middleware development for legacy departure control integration becomes a mandatory cost inclusion. Brownfield airport operators in Germany exhibit highest price sensitivity due to structural retrofit constraints, while greenfield mega-hubs in the UAE prioritize throughput performance over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for automated boarding system vendors with dual FAA-EASA compliance obligations. Edge AI processor fabrication concentrates in Taiwan and South Korea, while precision sensor arrays source predominantly from German and Japanese component specialists. Critical dependencies span gallium nitride semiconductors, high-resolution infrared imaging modules, and certified aviation-grade aluminum enclosures. Single-source vulnerability in advanced CMOS image sensors threatens deployment schedules for facial recognition corridor rollouts. Distribution runs through authorized system integrators with established civil aviation certification track records, bypassing direct OEM-to-airport sales for complex multi-vendor platform deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory compliance architectures creates specialized vendor niches as EU AI Act, FAA, and EASA divergence multiplies certification pathways. Post-pandemic passenger volume recovery compresses upgrade timelines, opening procurement windows for agile specialists.
For Market Incumbents: Insulate recurring revenue streams by embedding fifteen-year maintenance guarantees into German and French hub operator contracts before competitive unbundling accelerates. Deepen backward integration into edge AI processor supply through strategic partnerships with Taiwanese foundry networks, reducing exposure to allocation volatility that threatens margin stability. Prioritize pre-certification investment for EU AI Act algorithmic transparency documentation to narrow the qualified vendor pool and defend position against emerging biometric specialists. For New Entrants and Emerging Players: Indian greenfield terminals in Lucknow and Ahmedabad represent the most penetrable entry point, where embedded automation specifications lack incumbent lock-in and the Bureau of Indian Standards conformity framework remains under development. Saudi Vision 2030 aviation cluster procurement for King Salman International Airport offers second-mover advantage through fully automated passenger processing mandates that favor integrated platform bids over component specialists. Target initial market penetration through regional system integrator partnerships that bridge certification gaps and accelerate local technical service establishment. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because maintenance services generate predictable cash flows as hardware margins compress across European brownfield retrofit cycles. Acquisition target archetype: mid-cap biometric algorithm developers with pre-established EU regulatory dossiers and established Middle East technical service networks. Monitor ICAO mandate acceleration for computed tomography baggage screening as the signal to watch for replacement cycle inflection and security management segment capital deployment shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | Algorithmic transparency documentation becomes non-negotiable procurement filter at Schengen entry points. |
| Local Technical Service Network Expansion | Fifteen-year performance guarantees in Germany and France require established maintenance presence as selection criterion. |
| Middleware Development Partnerships | Biometric corridor retrofits demand legacy departure control integration capabilities for brownfield terminal operators. |
| Edge AI Processor Supply Securement | Taiwanese foundry allocation volatility threatens deployment schedules for facial recognition gate manufacturers. |
| Greenfield Terminal Platform Consolidation | UAE and Singapore mega-hub mandates favor fully integrated smart infrastructure over component specialists. |
Methodological Framework
Desk research of ICAO standards documentation, EU AI Act regulatory filings, and national aviation authority procurement disclosures preceded structured interviews with airport technology procurement directors, biometric system engineering leads, and civil aviation regulatory affairs specialists. Secondary validation drew from Federal Aviation Administration certification databases, European Union Aviation Safety Agency compliance bulletins, and customs trade data for edge AI processor imports. Bottom-up segment sizing across technology, application, end user, and service type dimensions was cross-checked against top-down market aggregation from disclosed vendor contract values.
Assumptions held fixed include EU AI Act enforcement timelines, ICAO computed tomography mandate adherence schedules, and semiconductor fabrication capacity allocation patterns across the analysis window. Variable assumptions encompass passenger volume recovery trajectories at major hub airports and brownfield retrofit penetration rates in Germany and the United Kingdom. The analytical framework modeled biometric screening, automated boarding, passenger processing, and security management segments with technology maturity curves and regulatory compliance tier differentiation. CAGRs were derived from segment-level deployment value trajectories calibrated against disclosed mega-hub capital expenditure programs.
Practitioners should monitor EU AI Act delegated act refinements, ICAO cybersecurity disclosure harmonization progress, and Taiwanese foundry capacity expansion announcements for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Global Airport Baggage Handling System Market
Airport Technologies
Airport Baggage Conveyor System Market
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Asia-Pacific Airport Baggage Handling Systems Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
Airport Interactive Kiosk Market
Airport Technologies
Smart Airport Market
Airport Technologies
Airport Airside Service Market
Airport Technologies
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market
Airport Technologies
Asia-Pacific Airport Ground Handling Systems Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Airport Information Systems Market