
 Smart Baggage Handling System Market | 2026-2036
Smart Baggage Handling System Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Baggage Handling System Market Outlook
ISO 9001 certification for quality management systems in airport infrastructure procurement is bifurcating the competitive landscape into qualified system integrators and peripheral component vendors. Vanderlande leverages its vertical integration across conveyor manufacturing and control software to dominate European hub installations. Siemens sustains technology leadership through its digital twin platforms that simulate baggage flow before physical deployment. Daifuku anchors Asian market presence with robotics-intensive sorting systems designed for high-throughput terminals.
A smart baggage handling system integrates automated conveyors, RFID tagging infrastructure, AI-driven sortation algorithms, and real-time tracking software to route luggage from check-in to aircraft loading with minimal human intervention. Systems typically process bags at speeds exceeding 600 meters per minute while maintaining tracking accuracy through distributed IoT sensor networks. Automated Systems and Robotics currently lead capital deployment as airports prioritize throughput capacity over incremental software upgrades. RFID Solutions represent the fastest-expanding segment as IATA Resolution 753 mandates end-to-end baggage tracking compliance across member carriers.
The FAA mandates specific fire-safety and electrical standards for baggage handling equipment installed in US airport terminals, while the EU AI Act imposes algorithmic transparency requirements on automated sortation decisions in European hubs. EASA coordinates with national regulators to certify robotics safety protocols for mixed human-machine baggage zones. Stakeholders must monitor how evolving cybersecurity frameworks for critical airport infrastructure reshape system architecture requirements and vendor qualification criteria.
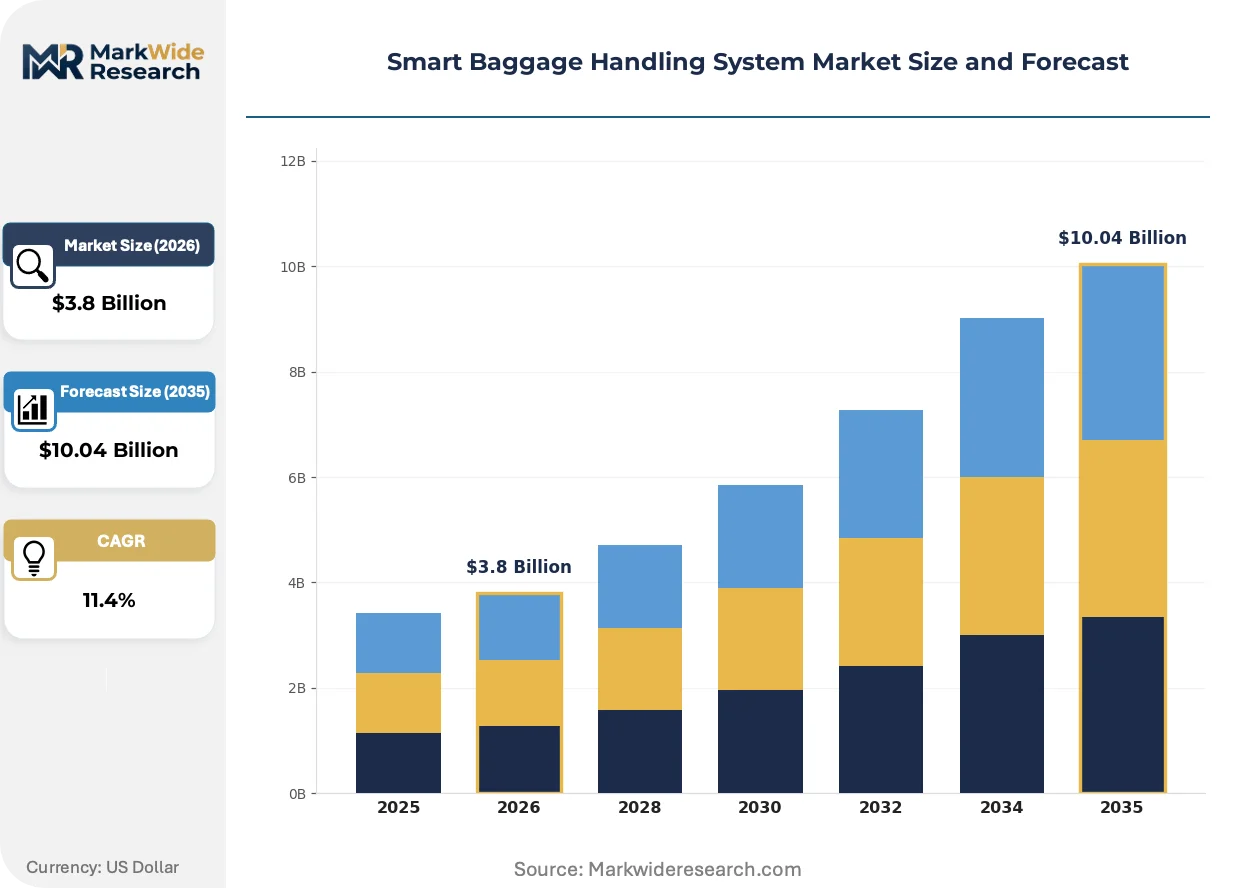
Market Dynamics
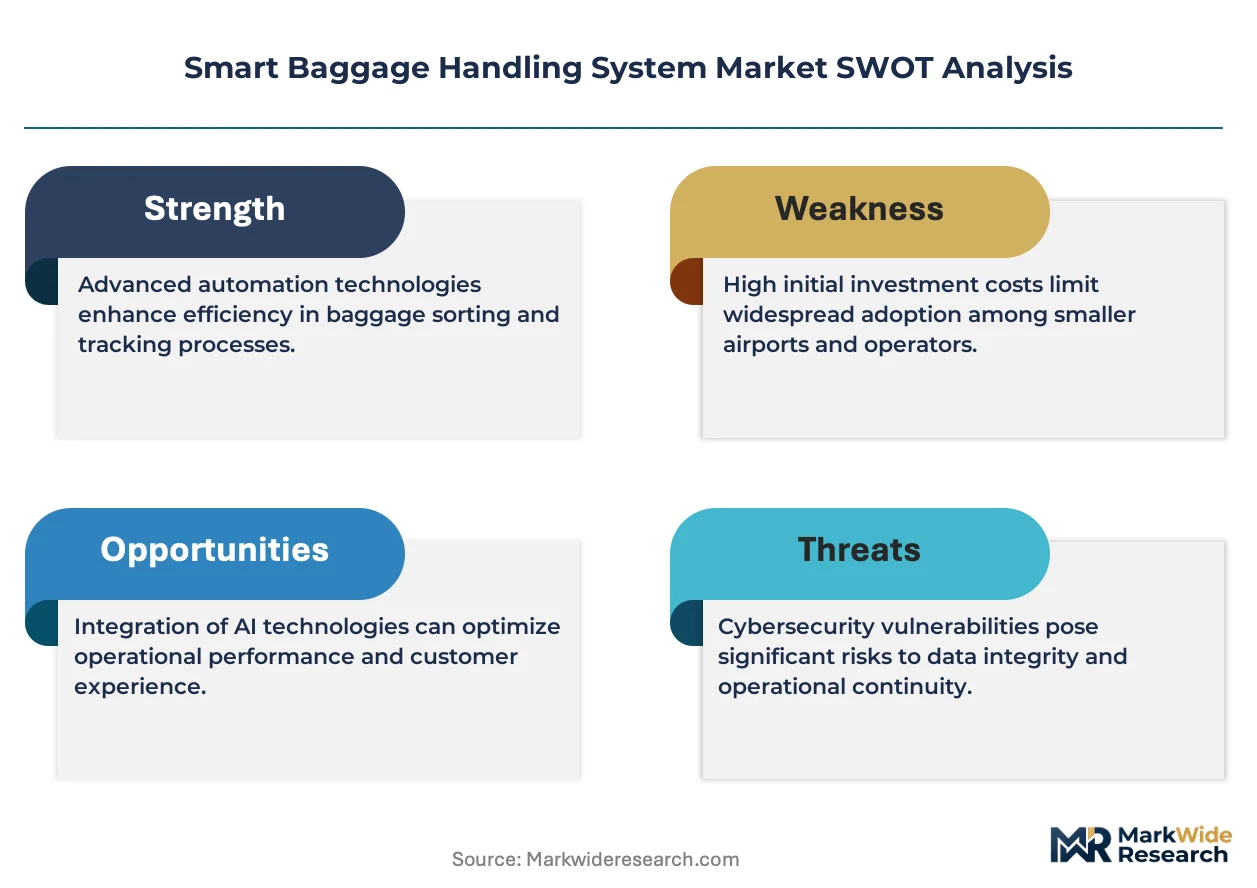
Airlines and airport authorities are accelerating replacement cycles for legacy baggage infrastructure as IATA Resolution 753 mandates end-to-end tracking compliance, forcing capital allocation toward RFID-integrated conveyor networks and AI-driven sortation systems.
Growth Catalysts
- EU F-Gas Regulation:European airports must phase out high-global-warming-potential refrigerants in climate-controlled baggage zones, redirecting procurement toward energy-efficient conveyor motors and heat-recovery systems.
- China mega-hub construction:Beijing Daxing, Shanghai Pudong expansion, and Guangzhou Baiyun capacity upgrades are deploying fully integrated smart baggage networks with robotics-intensive sortation from ground-up terminal designs.
- RFID infrastructure mandates:IATA Resolution 753 requires member carriers to track bags at four key journey points, pulling demand for tag readers, antenna arrays, and middleware integration across check-in, loading, transfer, and arrival zones.
Market Restraints
- Copper and rare-earth magnet costs:Conveyor motor windings and permanent-magnet synchronous drives face input price volatility from concentrated Chinese processing capacity, squeezing system integrator margins on fixed-price contracts.
- Legacy system interoperability:Brownfield airport terminals operate heterogeneous equipment vintages spanning three decades, creating technical debt that complicates IoT sensor retrofits and centralized control software deployment.
- EU AI Act algorithmic transparency:Automated sortation decisions in European hubs must now provide explainable routing logic, adding compliance overhead to machine-learning model development and validation timelines.
Strategic Opportunities
- Predictive maintenance convergence:Digital twin platforms combining physics-based simulation with real-time vibration sensing are compressing unplanned downtime for critical sortation equipment in high-throughput terminals.
- India airport privatization wave:Adani Group's acquisition of Mumbai, Ahmedabad, and Lucknow operations is creating greenfield deployment opportunities for fully automated baggage systems without legacy infrastructure constraints.
- Biometric-integrated bag drop:Facial recognition-linked self-service kiosks eliminating boarding pass and tag printing are opening white space for RFID tag encoding stations with embedded identity verification workflows.
Industry Challenges
- Control systems engineering talent:Scarcity of PLC programmers and SCADA specialists with aviation-sector cybersecurity clearances is extending commissioning timelines for complex multi-vendor installations.
- EASA robotics safety certification:Mixed human-machine baggage zones require extensive risk assessment documentation and third-party validation, creating bottlenecks for autonomous mobile robot deployment in European hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Baggage Handling System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, RFID Solutions, Conveyor Belts, Tracking Software Technology: IoT, AI, Machine Learning, Robotics End User: Airports, Airlines, Logistics Companies, Travel Agencies Service Type: Maintenance, Installation, Consulting, Upgrades |
| Companies Covered | Vanderlande, Siemens, Daifuku, Beumer Group, Alstef Group, SITA, Honeywell, Thales Group, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Baggage Handling System Market Strategic Shifts
Baggage handling architecture is fragmenting into modular, software-defined subsystems that decouple hardware procurement from control logic deployment, enabling phased modernization without terminal shutdowns.
Computer vision-based bag identification is decomposing traditional laser scanner dominance in sortation induction points. Major European hub operators are retrofitting camera arrays at 15-20% annual replacement rates for legacy barcode tunnels. This technology is compressing hardware refresh cycles while expanding data capture granularity for damage liability documentation.
The EU AI Act's algorithmic transparency requirements are forcing European airports to maintain auditable decision logs for every automated sortation routing choice. System integrators must now embed explainability modules into AI sortation engines, increasing software development overhead but creating differentiation for vendors with pre-certified compliance architectures. Hub operators in Germany, France, and the Netherlands are prioritizing vendors with established regulatory documentation packages.
Airport authorities are unbundling long-term service contracts from initial system procurement, shifting toward performance-based maintenance agreements with uptime guarantees and penalty clauses. Middle Eastern mega-hubs led by Dubai and Doha are piloting this model, where integrators retain operational responsibility for baggage system availability while airports pay per successfully handled bag rather than capital equipment lease.
Smart Baggage Handling System Market Segmentation
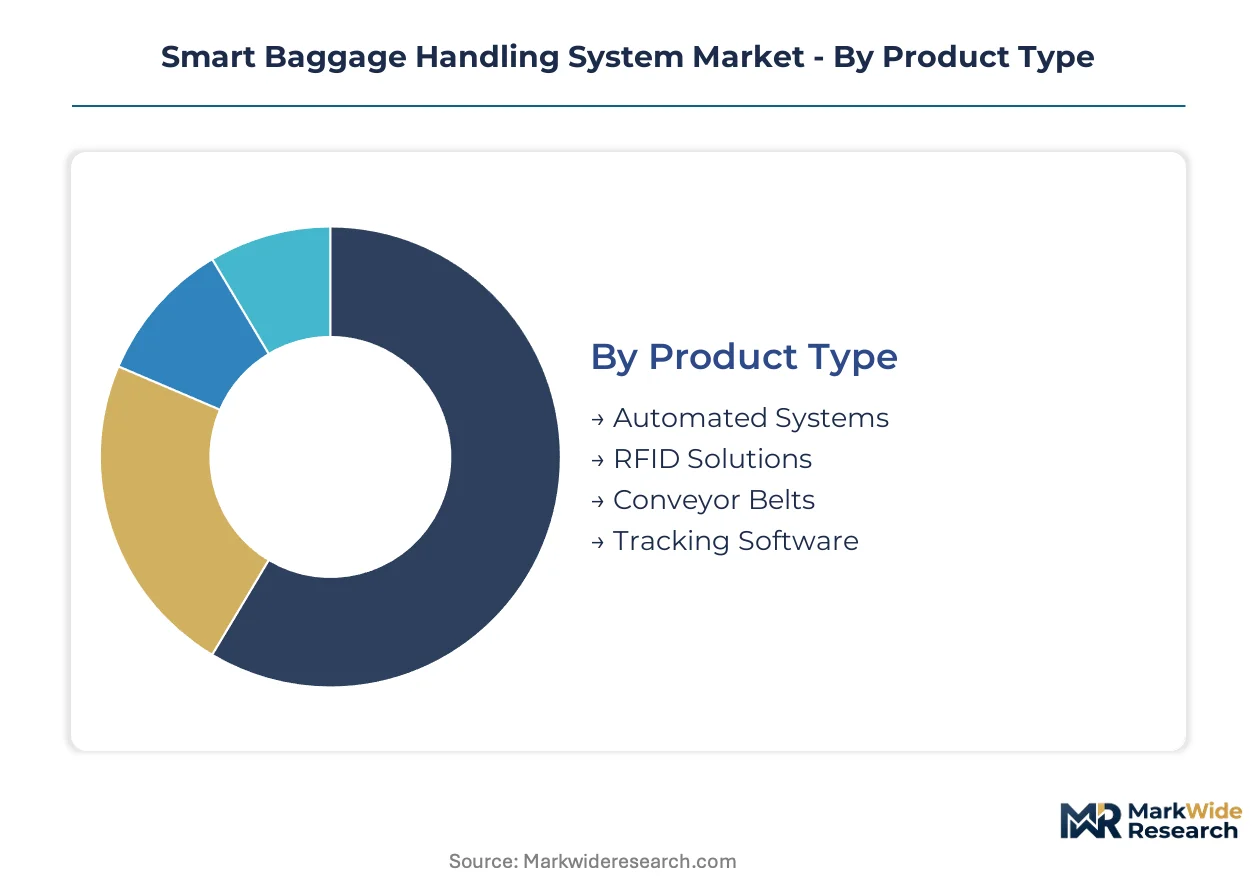
Smart baggage handling systems fragment into distinct procurement channels where hardware specifications, software integration depth, and service bundling determine vendor selection criteria. Understanding segment boundaries reveals how capital deployment flows between greenfield mega-hub construction and brownfield modernization cycles.
Product Type:
Channel mix varies sharply across product categories, with automated systems flowing through system integrator relationships while RFID solutions increasingly route through specialized component distributors serving retrofit markets.
- Automated Systems:Robotics-intensive sortation modules and high-speed conveyor arrays process bags at velocities exceeding 600 meters per minute. Demand concentrates in China's mega-hub construction—Beijing Daxing, Shanghai Pudong expansion, and Guangzhou Baiyun—where ground-up terminal designs specify fully integrated networks without legacy constraints. The EU F-Gas Regulation redirects European procurement toward energy-efficient motor configurations with heat-recovery integration.
- RFID Solutions:Tag readers, antenna arrays, and middleware platforms enable IATA Resolution 753 compliance across four mandated journey points. Airlines in Germany, France, and the Netherlands prioritize vendors with pre-certified EU AI Act documentation packages for algorithmic transparency in automated routing decisions.
- Conveyor Belts:Modular belt assemblies with distributed IoT sensor networks form the physical backbone of baggage transport infrastructure.
- Tracking Software:Real-time visibility platforms integrating SCADA control with passenger-facing mobile applications.
Automated Systems dominates installed base. RFID Solutions is where expansion concentrates.
Technology:
Cost tier stratification separates mature IoT deployments from emerging AI and robotics investments requiring specialized engineering talent and extended commissioning timelines.
- IoT:Distributed sensor networks and edge computing nodes provide real-time baggage position telemetry across terminal zones. Demand concentrates in brownfield retrofits where airports seek incremental visibility without conveyor replacement.
- AI:Machine-learning sortation engines optimize routing decisions based on flight schedules, bag dimensions, and transfer connection windows. European hubs under EU AI Act mandates require explainable decision logs, adding compliance overhead to model development.
- Machine Learning:Predictive algorithms forecasting equipment failure from vibration and thermal signatures.
- Robotics:Autonomous mobile robots and articulated arms handling irregular baggage in mixed human-machine zones.
IoT captures the broadest deployment footprint. AI commands the steepest expansion trajectory.
End User:
Customer type determines contract structure, with airports favoring capital purchase models while airlines increasingly shift toward performance-based availability agreements.
- Airports:Terminal authorities procure integrated systems combining hardware, software, and long-term maintenance under unified procurement frameworks. India's privatization wave—Adani Group's Mumbai, Ahmedabad, and Lucknow operations—creates greenfield deployment opportunities without legacy infrastructure constraints.
- Airlines:Carriers mandate IATA Resolution 753 compliance across member networks, driving RFID infrastructure investment at check-in, loading, transfer, and arrival zones. Middle Eastern mega-hubs pilot per-bag pricing models where integrators retain operational responsibility.
- Logistics Companies:Third-party ground handlers operating across multiple carrier contracts.
- Travel Agencies:Intermediaries bundling baggage tracking services with booking platforms.
Airports anchor capital expenditure volume. Airlines is where procurement innovation concentrates.
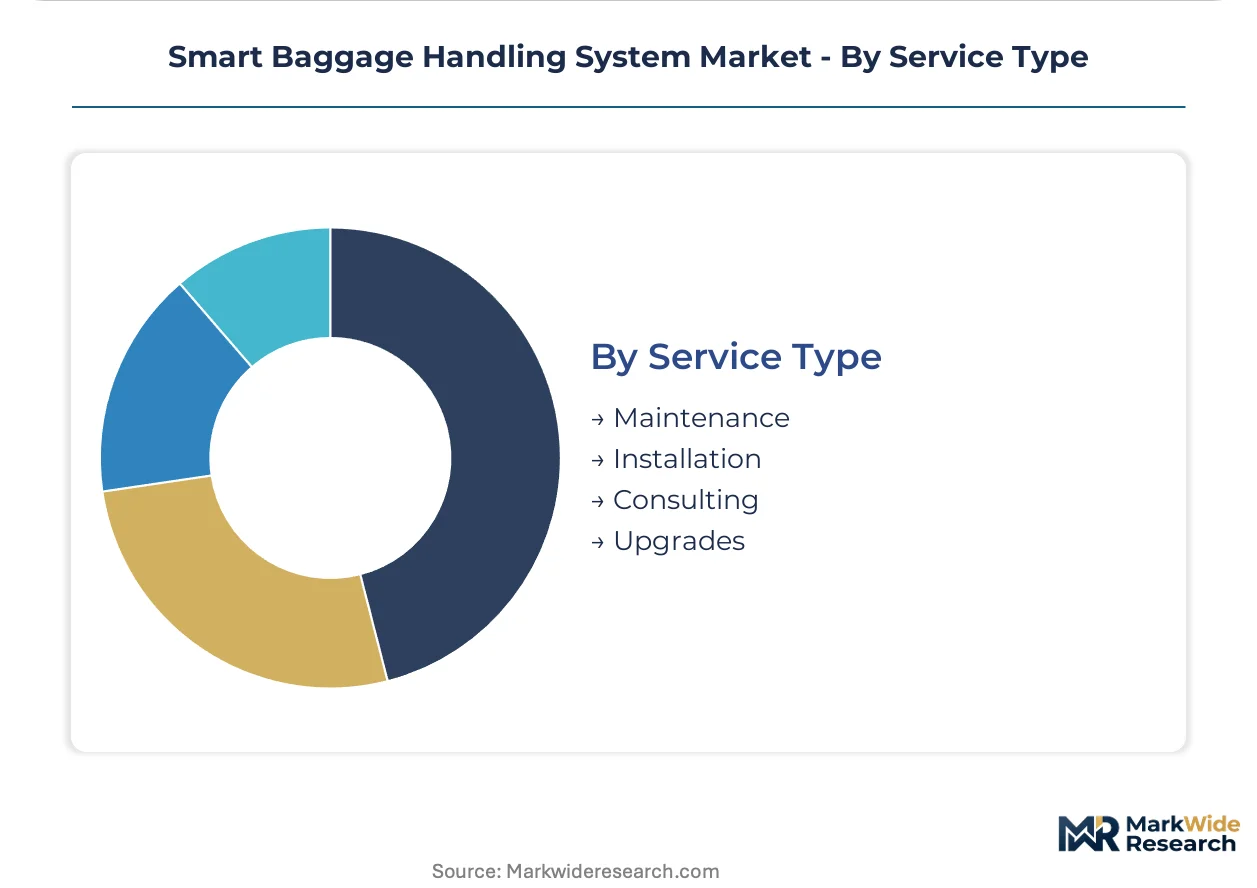
Service Type:
Margin structure diverges across service categories, with installation commanding front-loaded project economics while maintenance generates recurring revenue streams tied to uptime guarantees.
- Maintenance:Predictive maintenance platforms combining digital twin simulation with real-time vibration sensing compress unplanned downtime for critical sortation equipment. Dubai and Doha lead performance-based contracting with penalty clauses for availability shortfalls.
- Installation:Multi-vendor system integration requires PLC programmers and SCADA specialists with aviation-sector cybersecurity clearances, creating talent scarcity bottlenecks that extend commissioning timelines.
- Consulting:Regulatory compliance advisory for EU AI Act algorithmic transparency and EASA robotics safety certification.
- Upgrades:Modular retrofits enabling phased modernization without terminal shutdowns.
Maintenance commands the longest contract durations. Installation represents the highest project value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beijing Daxing International Airport's integrated terminal design underwrites China's dominance in smart baggage infrastructure deployment. The facility's fully automated networks process millions of bags annually without legacy system constraints.
China
Shanghai Pudong's expansion and Guangzhou Baiyun's capacity upgrades are deploying robotics-intensive sortation from ground-up terminal designs. The country's dual carbon goals from MEE redirect procurement toward energy-efficient motor configurations. Beijing Daxing anchors the Yangtze River Delta cluster where fully integrated smart baggage networks operate at scale.
Germany
Frankfurt and Munich hubs prioritize vendors with pre-certified EU AI Act documentation packages for algorithmic transparency. The F-Gas Regulation mandates phase-out of high-global-warming-potential refrigerants in climate-controlled baggage zones. Siemens anchors the Baden-Württemberg industrial corridor with digital twin platforms simulating baggage flow before physical deployment.
United States
Atlanta Hartsfield-Jackson and Dallas-Fort Worth are retrofitting heterogeneous equipment vintages with IoT sensor networks for incremental visibility. FAA mandates specific fire-safety and electrical standards for baggage handling equipment in US terminals. The Southeast cluster concentrates brownfield modernization demand without greenfield construction timelines.
India
Adani Group's acquisition of Mumbai, Ahmedabad, and Lucknow operations creates greenfield deployment opportunities without legacy infrastructure constraints. The PLI scheme for manufacturing incentivizes domestic component sourcing for conveyor assemblies. Maharashtra's Mumbai Chhatrapati Shivaji Maharaj International anchors western India's privatization wave.
United Arab Emirates
Dubai and Doha pilot performance-based maintenance agreements where integrators retain operational responsibility for baggage system availability. MOHAP coordinates with EASA-equivalent protocols for robotics safety in mixed human-machine zones. The Dubai-Al Maktoum cluster leads per-bag pricing models across Middle Eastern mega-hubs.
Smart Baggage Handling System Market Competitive Environment
Listed leaders compete with private specialists across technology licensing and service bundling dimensions. The vendor base concentrates around system integrators with captive software development and component distributors serving retrofit markets. Three archetypes dominate: full-stack integrators controlling conveyor manufacturing and control logic, software specialists licensing digital twin platforms, and regional fabricators with robotics-intensive sortation expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves as airports unbundle long-term service contracts from initial procurement.
Among European-based full-stack integrators, Vanderlande and Siemens exemplify the vertically integrated archetype spanning hardware production and control software. Daifuku occupies a position within the Asia-Pacific robotics-intensive tier, representing specialists in high-throughput autonomous sortation systems. These three anchors illustrate how geographic origin and company structure map to strategic positioning across greenfield mega-hub construction and brownfield modernization cycles.
| Leading Market Players |
|---|
| Vanderlande |
| Siemens |
| Daifuku |
| Beumer Group |
| Alstef Group |
| SITA |
| Honeywell |
| Thales Group |
| IBM |
| Others |
Value Chain & Pricing Dynamics
Twenty-four-month lead times for permanent-magnet synchronous motors concentrate pricing power with Chinese rare-earth processors, forcing system integrators to absorb cost volatility or pass through to airport procurement budgets. This inventory compression across conveyor motor windings tightens margins on fixed-price contracts while rewarding vendors with backward integration into component manufacturing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 9001-certified system integrators from peripheral component vendors and regional fabricators. Price differentiation hinges on certification grade and after-sales service bundling, with European hub operators paying premiums for EU AI Act pre-certified documentation packages. Cost compression in standard-tier conveyor assemblies is intensifying because copper and rare-earth magnet input volatility squeezes integrator margins. Budget-constrained brownfield retrofit operators in the United States exhibit highest price sensitivity, while Middle Eastern mega-hubs prioritizing uptime guarantees show lowest.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and container availability constraints on Asia-Europe trade lanes complicate just-in-time delivery for robotics-intensive sortation modules. Manufacturing concentrates in China, Germany, and the Netherlands, with component sourcing drawing from concentrated Chinese rare-earth processing for permanent-magnet drives and Japanese precision bearings for high-speed conveyor arrays. Single-source vulnerability in neodymium magnet supply creates structural risk for European integrators facing F-Gas Regulation compliance deadlines. Distribution runs through system integrator direct sales for greenfield mega-hubs and specialized component distributors serving RFID retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as IATA Resolution 753 mandates pull RFID infrastructure investment across member carrier networks, creating a compliance-driven adoption wave with decade-long replacement visibility.
For Market Incumbents: Consolidate control software capabilities through captive development of explainable AI modules for EU AI Act compliance, defending against emerging software specialists licensing digital twin platforms. Deepen backward integration into energy-efficient motor manufacturing to offset rare-earth cost volatility and protect margin structure on European hub contracts.
For New Entrants and Emerging Players: EASA robotics safety certification fast-track offers entry pathway into mixed human-machine baggage zones where incumbents face documentation bottlenecks. Target India's privatized airport operations—Adani Group's Mumbai, Ahmedabad, and Lucknow greenfield deployments lack legacy constraints and procurement relationships. Lead with performance-based maintenance contracts rather than capital equipment sales to bypass entrenched integrator relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because aviation-sector mandates create non-discretionary replacement cycles with contracted visibility. Acquisition focus centers on mid-tier software specialists with pre-certified EU AI Act documentation packages and established airport authority relationships. Monitor IATA Resolution 753 compliance deadline extensions as signal for RFID infrastructure investment acceleration or deferral.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Siemens simulates baggage flow before physical deployment, compressing commissioning risk for brownfield retrofits. |
| EU AI Act Pre-Certification Investment | Vanderlande embeds explainability modules, creating differentiation in German and Dutch hub procurement. |
| Performance-Based Maintenance Contracting | Dubai and Doha pilots shift integrator economics toward uptime guarantees and per-bag pricing. |
| Robotics Safety Certification Fast-Track | EASA coordination protocols create bottlenecks that pre-certified vendors exploit for competitive positioning. |
| Backward Integration into Motor Manufacturing | Daifuku reduces rare-earth exposure through captive supply of permanent-magnet synchronous drives. |
Study Parameters
Desk research of customs trade data, SEC filings from listed automation vendors, and IATA regulatory documentation preceded structured interviews with airport procurement directors, system integrator project managers, airline baggage operations executives, and EASA certification specialists. Primary fieldwork combined telephone interviews and on-site terminal observations across Beijing Daxing, Frankfurt, and Dubai hubs with secondary validation against equipment shipment records and contract award databases. Bottom-up installation tracking triangulated against top-down airport capital expenditure forecasts.
Variance decomposition across product type, technology tier, end-user category, and service model dimensions structured the analytical framework over the projection horizon. CAGRs derived from logistic curve penetration modeling for RFID compliance mandates and linear replacement cycle projections for conveyor infrastructure. Forecast inputs incorporated IATA Resolution 753 adoption timelines, EU F-Gas Regulation phase-out schedules, and China mega-hub construction cadence from MEE dual carbon goal announcements.
Underlying assumptions cover sustained aviation passenger recovery, stable rare-earth supply from Chinese processing capacity, and incremental EU AI Act enforcement without retroactive compliance requirements, with deviation risk concentrated in copper price volatility and EASA robotics certification timeline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Asia-Pacific Airport Baggage Handling Systems Market
Airport Technologies
Middle-East and Africa Airport Ground Handling Systems Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Airport Runway Foreign Object Debris (FOD) Detection Systems Market
Airport Technologies
Smart Airport 4.0 Market
Airport Technologies
Airport RFID System Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Airport Information Systems Market
Airport Technologies
Smart Airport 2.0 Market
Airport Technologies
Air Traffic Smart Tower Solutions Market
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Airport Baggage Tracking Systems Market