
 Air Traffic Smart Tower Solutions Market | 2026-2036
Air Traffic Smart Tower Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Air Traffic Smart Tower Solutions Market Analytics
Air traffic controller workforce shortages across aging tower facilities is reorganizing capital allocation toward remote and digital tower platforms. Thales Group leverages its sensor fusion portfolio to anchor European remote tower deployments. L3Harris Technologies, Inc. competes in North American military applications with integrated command-and-control interfaces. Saab AB specializes in camera-based remote tower systems that occupy the Nordic upgrade cycle.
Air Traffic Smart Tower Solutions encompass hardware-software architectures that replace or augment visual observation from physical control towers with distributed camera networks, radar feeds, and data analytics platforms operating at sub-second latency thresholds for real-time aircraft separation management. Their primary purpose centers on sustaining safe airspace throughput while enabling centralized control of multiple low-density airports from single facilities. Digital Towers capture the dominant share of current procurement budgets as aviation authorities prioritize full-outside-view replication over incremental automation add-ons. Remote Towers represent the fastest-expanding segment category, driven by cost consolidation across regional airport networks and military forward operating bases. Integrated Solutions concentrate margin pools through multi-site software licensing and long-term sustainment contracts.
FAA NextGen standards and EU SESAR Joint Undertaking frameworks shape product certification timelines, while ICAO Doc 4444 provisions govern minimum surveillance performance requirements for remote tower operations. EASA certification specifications for remote aerodrome air traffic services create market access barriers that favor established suppliers with prior operational approvals. Stakeholders must weigh regulatory harmonization gaps between FAA and EASA remote tower standards when designing platform architectures for cross-border airport operator bids.
Market Dynamics
Controller workforce attrition at aging physical tower facilities is forcing aviation authorities to consolidate operations onto centralized remote platforms, compressing procurement cycles for digital infrastructure.
Growth Catalysts
- FAA NextGen mandates:Modernization timelines require digital tower certification for enhanced surveillance integration, accelerating airport operator upgrade schedules across US facilities.
- Camera sensor arrays:Distributed visual systems now achieve sub-second latency thresholds, enabling real-time aircraft separation management from remote facilities.
- Military forward operating bases:Defense aviation authorities in Germany and Nordic states are procuring deployable remote tower units for expeditionary airfield operations.
Market Restraints
- EASA certification specifications:Remote aerodrome air traffic service approvals require extensive operational history, creating market access barriers for new platform vendors.
- High-resolution optical sensor costs:Camera network hardware represents concentrated capital outlay for regional airport operators with limited infrastructure budgets.
- Legacy radar system lock-in:Existing ground surveillance infrastructure at major hubs resists full replacement by optical-digital architectures.
Strategic Opportunities
- Multi-site software licensing:Integrated solutions enable single controllers to manage multiple low-density airports from centralized facilities, capturing margin through recurring sustainment contracts.
- EU SESAR Joint Undertaking deployment:Research framework funding accelerates cross-border harmonization of remote tower standards, opening procurement pathways for certified suppliers.
- India regional airport networks:Underpenetrated secondary aviation infrastructure presents white space for remote tower consolidation models adapted to tropical climate conditions.
Industry Challenges
- Controller retraining requirements:Transition from physical tower visualization to screen-based operations demands extensive human factors certification and simulator-based competency validation.
- ICAO Doc 4444 compliance:Minimum surveillance performance specifications for remote operations require continuous validation against evolving international safety benchmarks.
- System integration complexity:Digital tower platforms must interface with existing flight data processing, meteorological, and emergency response systems at each airport site.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Traffic Smart Tower Solutions Market |
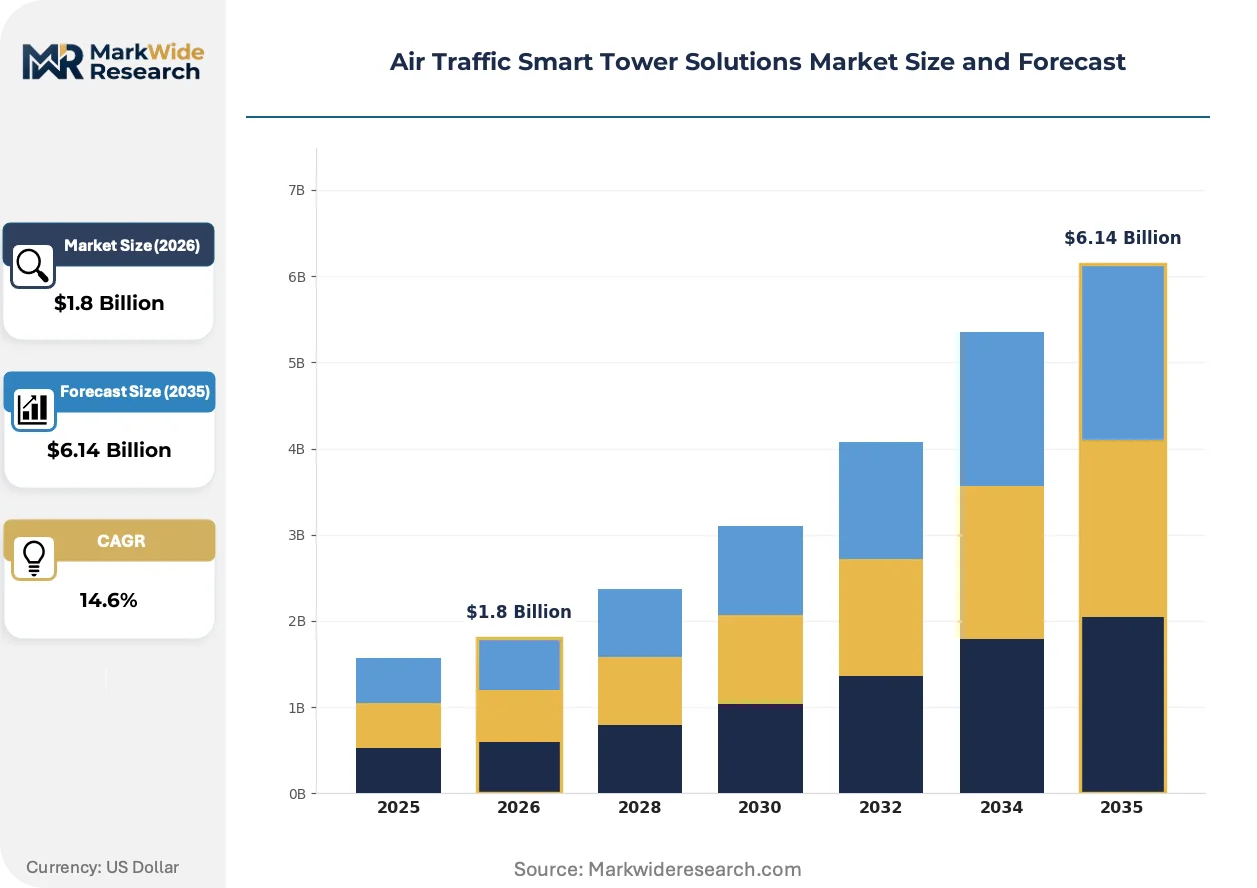
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Digital Towers, Remote Towers, Integrated Solutions Technology: Radar Systems, Communication Networks, Surveillance Systems, Data Analytics End User: Airports, Air Traffic Control, Aviation Authorities, Military Deployment Model: On-Premises, Cloud-Based, Hybrid, Modular |
| Companies Covered | Frequentis AG, Thales Group, Indra Sistemas, Lockheed Martin Corporation, L3Harris Technologies, Inc., BAE Systems plc, Honeywell International Inc., RTX Corporation, Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Traffic Smart Tower Solutions Market Evolving Landscape
Aviation authorities are redefining air traffic control architecture through sensor fusion and centralized operations, shifting capital from concrete infrastructure to software-defined surveillance networks.
High-fidelity camera-based remote tower systems are bifurcating the market between full digital replication and hybrid augmentation models. Nordic and German airport operators are deploying these systems at regional hubs with seasonal traffic volatility. The technology is compressing capital requirements for new tower construction while expanding the addressable market to previously uneconomical airfields.
EU SESAR Joint Undertaking frameworks are mandating interoperability standards for multi-modal surveillance integration across member states. This regulatory pressure forces platform architects to design for cross-border certification portability from inception. Remote tower suppliers with prior EASA operational approvals capture disproportionate share of framework-funded deployment tenders.
Service-based contracting is displacing traditional hardware-procurement models among cost-constrained regional airport consortia. Long-term performance agreements with guaranteed availability metrics replace capital-intensive ownership structures. Germany's DFS Deutsche Flugsicherung and affiliated airport groups are piloting these arrangements for clustered remote tower operations.
Air Traffic Smart Tower Solutions Market Segmentation
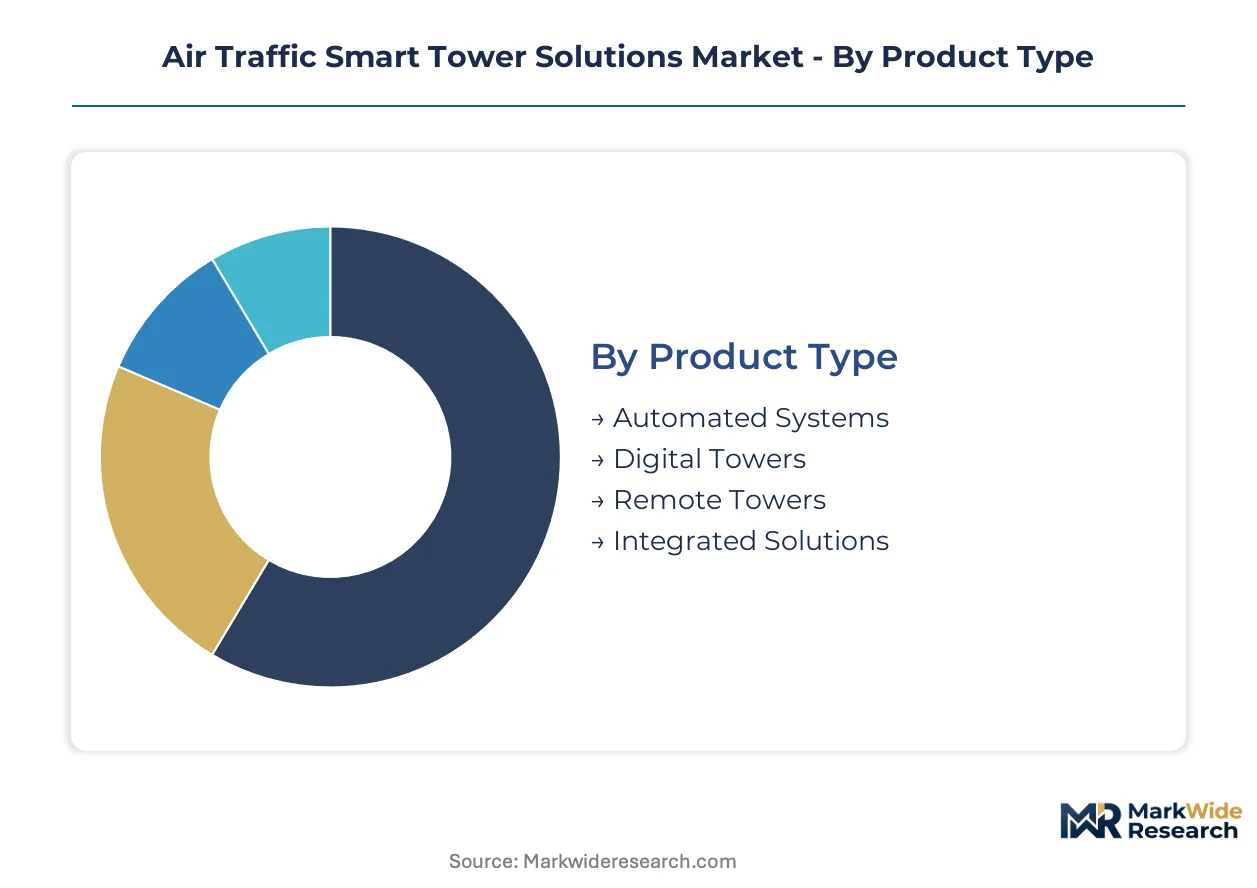
Segmentation in air traffic smart tower solutions reveals how procurement priorities diverge between regulatory mandates, operational scale, and infrastructure maturity. Each dimension exposes distinct margin pools and certification barriers that reshape competitive positioning across aviation authorities.
Product Type:
EASA and FAA certification timelines create divergent commercial windows for each product architecture, with full digital replication commanding longer approval cycles but higher contract values.
- Digital Towers:Complete outside-view replication systems using distributed camera networks and sensor fusion at sub-second latency thresholds. German aviation authorities prioritize these for major hub modernization under SESAR deployment frameworks, compressing procurement cycles for suppliers with prior EASA operational approvals.
- Remote Towers:Centralized control platforms enabling single facilities to manage multiple low-density airports. Nordic states and Germany's regional airport networks drive demand here, with military forward operating bases in Germany adding expeditionary procurement volumes.
- Automated Systems:Partial automation add-ons for legacy tower infrastructure, typically deployed where full digital replacement faces budget constraints.
- Integrated Solutions:Multi-site software licensing with long-term sustainment contracts, capturing recurring revenue through centralized facility management.
Established volume favors Digital Towers; emerging adoption favors Remote Towers.
Technology:
Hardware-software integration intensity varies sharply across technology layers, with surveillance and analytics commanding premium pricing against commoditized communication infrastructure.
- Surveillance Systems:Camera sensor arrays and multi-modal tracking platforms achieving ICAO Doc 4444 minimum performance specifications. German and Nordic remote tower deployments concentrate demand here, with sub-second latency requirements filtering vendor pools.
- Data Analytics:Real-time aircraft separation algorithms and predictive traffic management platforms. EU SESAR Joint Undertaking funding accelerates procurement for cross-border interoperability, opening framework-funded tenders to certified suppliers.
- Radar Systems:Legacy ground surveillance infrastructure resisting full replacement at major hubs, creating hybrid deployment patterns.
- Communication Networks:Voice and data transmission backbone for remote tower operations, increasingly standardized across vendor platforms.
Surveillance Systems capture dominant procurement budgets; Data Analytics exhibits the steepest expansion trajectory.
End User:
End-user procurement authority determines contract structure, with military buyers favoring rapid deployability and civilian authorities prioritizing multi-decade operational history.
- Aviation Authorities:National regulators including Germany's DFS Deutsche Flugsicherung and FAA-mandated US facilities drive standard-setting procurement. EASA certification specifications favor established suppliers, consolidating vendor relationships around prior approval holders.
- Military:Defense aviation authorities in Germany and Nordic states procure deployable remote tower units for expeditionary airfield operations, prioritizing rapid deployment over long certification timelines.
- Airports:Regional and secondary airport operators, often budget-constrained, favor service-based contracting over capital-intensive ownership.
- Air Traffic Control:Controller workforce organizations influence human factors requirements and retraining investment scope.
Aviation Authorities anchor procurement volume; Military applications gain share fastest.
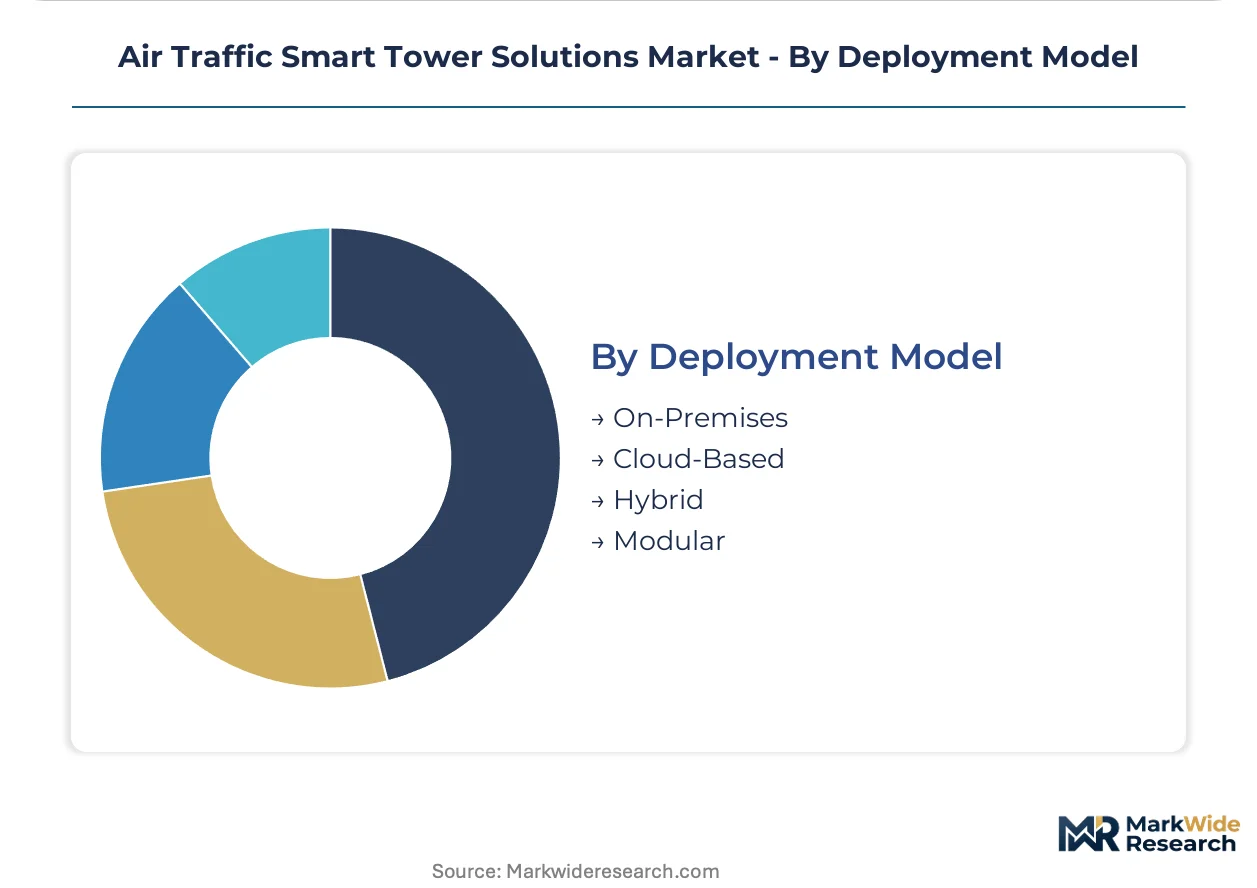
Deployment Model:
Capital availability and risk tolerance divide deployment preferences, with cost-constrained operators shifting toward performance-guaranteed service structures.
- Cloud-Based:Centralized software delivery with subscription economics, expanding among regional airport consortia seeking to avoid infrastructure ownership. Germany's DFS-affiliated airport groups pilot these arrangements for clustered remote tower operations.
- Hybrid:Split processing between local edge computing and centralized cloud resources, balancing latency requirements against cost consolidation.
- On-Premises:Full local infrastructure deployment, remaining preferred for major hubs with legacy system integration complexity.
- Modular:Containerized or transportable units for rapid field deployment, aligning with military expeditionary requirements and seasonal airport operations.
On-Premises retains installed base dominance; Cloud-Based models are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany treats remote towers as permanent infrastructure replacement, while the United States frames them as incremental NextGen add-ons and Nordic states deploy them for seasonal flexibility. This consumption-mix differential shapes procurement timelines, certification priorities, and vendor relationship structures across aviation authorities.
United States
FAA NextGen modernization mandates compress digital tower certification schedules for enhanced surveillance integration. The agency's operational approval frameworks prioritize interoperability with legacy radar infrastructure over full optical replacement. Dallas-Fort Worth and Atlanta hub operators pilot hybrid augmentation models while regional airports in the Mountain West test centralized remote facilities.
Germany
DFS Deutsche Flugsicherung operates multiple live remote tower installations as permanent replacements for aging concrete towers at regional airports. EASA certification specifications for remote aerodrome air traffic services favor suppliers with prior operational history, consolidating procurement around established vendors. The Leipzig-Halle aviation cluster anchors sensor fusion development for SESAR Joint Undertaking framework compliance.
Sweden
Saab AB camera-based systems serve Nordic airport operators managing seasonal traffic volatility at low-density airfields. The country's military aviation authority procures deployable remote tower units for expeditionary airfield operations in Arctic conditions. Stockholm-Arlanda coordinates multi-site software licensing pilots for clustered regional airport management.
United Kingdom
NATS Holdings evaluates remote tower consolidation for secondary airports facing controller workforce attrition. The Civil Aviation Authority's regulatory sandbox approach accelerates operational approval for digital tower trials at former military airfields. The Cranfield aviation technology cluster supports human factors research for controller transition from physical to screen-based operations.
India
Regional airport networks under the Airports Authority of India present white space for remote tower models adapted to tropical climate conditions and monsoon visibility challenges. The Directorate General of Civil Aviation develops certification pathways for camera-based surveillance at underpenetrated secondary aviation infrastructure. Bangalore and Hyderabad technology corridors host emerging domestic platform developers targeting cost-constrained airport consortia.
Air Traffic Smart Tower Solutions Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Air Traffic Smart Tower Solutions market. Tier-one suppliers combine sensor fusion portfolios with multi-decade operational approvals from EASA and FAA regulators, capturing disproportionate share of framework-funded deployment tenders. Specialist vendors concentrate on camera hardware, deployable military units, or regional software licensing. Competitive moves center on strategic partnerships for cross-border certification portability and service-based contracting models that displace traditional hardware procurement.
Within the integrated systems tier, Thales Group and Frequentis AG exemplify archetypes of sensor fusion and operational certification depth. Saab AB occupies a position among camera-specialist vendors with Nordic military and civilian deployment history. L3Harris Technologies, Inc. represents the defense-integrated command-and-control segment competing for North American military applications. These three anchors illustrate how geographic regulatory alignment and prior approval history determine competitive positioning more than pure technology differentiation.
| Leading Market Players |
|---|
| Frequentis AG |
| Thales Group |
| Indra Sistemas |
| Lockheed Martin Corporation |
| L3Harris Technologies, Inc. |
| BAE Systems plc |
| Honeywell International Inc. |
| RTX Corporation |
| Saab AB |
| Others |
Value Network & Pricing Analysis
Long-term performance agreements with guaranteed availability metrics lock in supply access and price visibility for regional airport operators migrating from capital-intensive ownership structures. Germany's DFS-affiliated airport groups pilot these arrangements for clustered remote tower operations, compressing procurement cycles while embedding multi-year sustainment contracts.
Pricing Analysis
Project-based contracting with recurring software licensing layers dominates procurement, separating premium-tier EASA-certified platforms from standard-tier regional deployments. Price differentiation hinges on certification grade and after-sales service bundling, with aviation authorities least sensitive and budget-constrained secondary airports most responsive to cost. Pricing pressure stems from service-based contracting displacing hardware ownership, forcing margin compression in pure equipment sales.
Supply Chain Analysis
Germany and Sweden anchor high-fidelity camera sensor production and sensor fusion development for European remote tower deployments. Component sourcing draws from specialized optical manufacturers in Japan and Taiwan, with software development concentrated in domestic technology corridors. Single-source vulnerability in high-resolution sensor arrays creates procurement risk. Distribution runs through aviation authority tender frameworks and defense procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from multi-site software licensing and long-term sustainment contracts expands faster than hardware sales, repositioning platform economics toward recurring revenue models.
For Market Incumbents: Consolidate certification depth across EASA and FAA jurisdictions to defend against emerging sensor fusion specialists. Vertical integration into camera sensor arrays reduces exposure to optical component supply constraints. Prioritize human factors research partnerships to accelerate controller retraining program deployment. For New Entrants and Emerging Players: Differentiate on tropical climate adaptation for India's underpenetrated regional airport networks. Target military expeditionary procurement in Nordic states where rapid deployability outweighs lengthy certification timelines. Pursue cloud-based subscription models for cost-constrained airport consortia seeking infrastructure avoidance. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined surveillance platforms with established operational approvals and recurring revenue visibility. Vendors with prior EASA certification history and multi-site deployment track records offer strongest long-term viability. Watch for EU SESAR framework funding disbursement velocity as inflection indicator for procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Site Software Licensing | Enables DFS Deutsche Flugsicherung to centralize control of clustered regional airports under single contracts. |
| EASA Certification Investment | Creates market access barriers favoring suppliers with prior operational approvals at German installations. |
| Sensor Fusion Partnership | Positions Thales Group to capture SESAR Joint Undertaking framework-funded deployment tenders. |
| Expeditionary Military Unit Development | Aligns Saab AB with Nordic defense procurement for Arctic-deployable remote tower systems. |
| Cloud-Based Service Transition | Allows regional airport consortia to shift capital expenditure to operational expenditure structures. |
Research Methodology
Operator-level perspectives from air traffic controllers, aviation authority procurement officers, military program managers, and airport operations directors anchored the qualitative base. Primary interviews combined with secondary validation from FAA NextGen documentation, EU SESAR Joint Undertaking deployment records, EASA certification specifications, and ICAO surveillance performance guidelines. Bottom-up installation tracking across German and Nordic remote tower sites triangulated against top-down aviation authority budget disclosures.
Sensitivity analysis tested forecast outputs against regulatory approval timeline variations and military procurement acceleration scenarios across the projection horizon. Segmentation dimensions modeled include product architecture, surveillance technology layer, end-user procurement authority, and deployment model complexity. CAGRs derived from fitted growth curves applied to certified installation bases and framework-funded tender pipelines, incorporating controller workforce attrition rates and sensor cost decline trajectories.
Forecasts assume regulatory continuity in EASA and FAA certification regimes; material policy shifts would require re-modeling. Specific risks include harmonization gaps between FAA and EASA remote tower standards and tropical climate adaptation requirements for Indian deployments. Recalibration cycles align with material shifts in SESAR funding disbursements and NextGen modernization milestone achievements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Commercial Airport Baggage Handling Systems Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Asia-Pacific Airport Baggage Handling Systems Market
Airport Technologies
Advanced Airport Technologies Market
Airport Technologies
Airport Smart Lighting Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
North America Smart Airport Market
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Helideck Monitoring System Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Global Airport Baggage Handling System Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Airport Interactive Kiosk Market