
 Airport Information Systems Market | 2026-2036
Airport Information Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Information Systems Market Intelligence
Aviation software engineering talent scarcity is unwinding deployment timelines for next-generation airport platforms. SITA leverages its global communications backbone to sustain dominance in passenger messaging networks across hub airports. Amadeus IT Group anchors its position through deep integration with airline reservation systems and departure control platforms. Thales Group competes on security-screening technology leadership, particularly in automated threat detection lanes.
Airport information systems encompass hardware and software infrastructure that aggregates, processes, and distributes real-time operational data across terminal environments, typically integrating flight schedules, passenger flows, baggage status, and resource allocation through centralized data architectures. These systems primarily enable coordinated decision-making among airlines, ground handlers, and airport authorities while supporting regulatory compliance and service-level agreements. Passenger processing systems occupy the largest installed base among system types, reflecting decades of check-in and boarding automation investment, while artificial intelligence applications within baggage handling and security screening represent the fastest-expanding margin pools as airports pursue autonomous operations. Cloud computing deployments are displacing on-premise legacy stacks, with biometric identification technology emerging as the critical integration layer across check-in, boarding, and immigration touchpoints.
FAA NextGen mandates and EU F-Gas Regulation compliance requirements are reshaping system procurement specifications for U.S. and European airport operators, respectively, while ICAO standards govern cross-border data interoperability for international passenger processing. China's GB standards and NMPA-equivalent aviation safety protocols impose additional localization requirements for foreign system vendors seeking access to domestic airport modernization programs. Stakeholders must weigh sovereign data residency rules against cloud platform economics when architecting multi-airport deployments.
Market Dynamics
Cloud-native architectures are compressing deployment cycles for passenger processing platforms while biometric integration mandates from aviation regulators force simultaneous legacy system coexistence. This structural tension between modernization velocity and operational continuity defines competitive positioning for system vendors.
Growth Catalysts
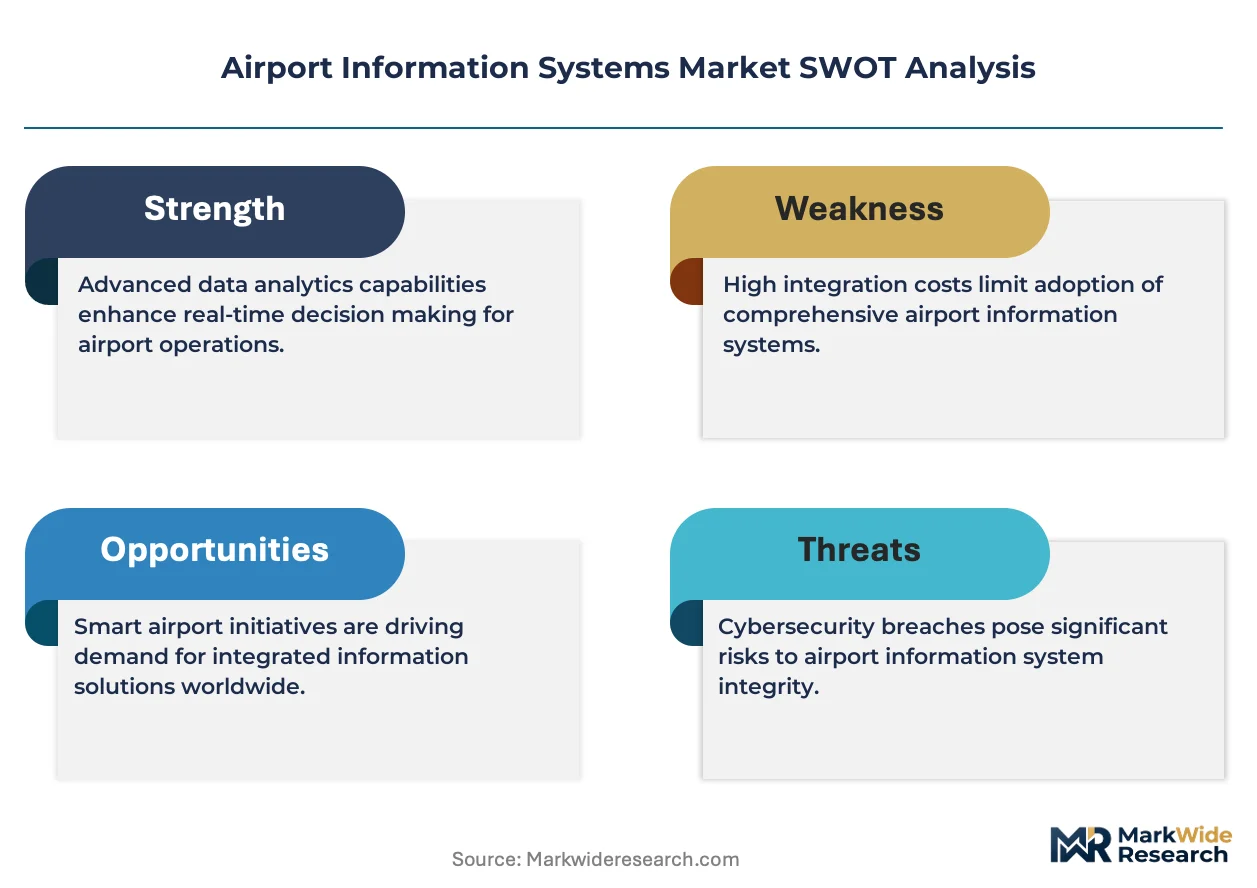
- Biometric boarding mandates:ICAO standards for digital travel credentials are accelerating procurement of integrated identity verification platforms at hub airports in the United States, Germany, and China.
- FAA NextGen compliance deadlines:Surface surveillance and data-sharing requirements are forcing system upgrades across U.S. airport operators, with EU F-Gas Regulation adding parallel pressure on European refrigeration-dependent baggage systems.
- AI-driven predictive maintenance:Machine learning models for baggage handling equipment are reducing unplanned downtime, with Dubai International Airport trials validating autonomous operations at scale.
Market Restraints
- Aviation software engineering scarcity:Specialized talent pools for safety-critical systems development concentrate in Germany and the United States, extending vendor delivery timelines by 40-60%.
- Legacy infrastructure lock-in:Decades-old passenger processing hardware at major hubs creates integration friction that inflates total cost of ownership for cloud migration projects.
- Sovereign data residency requirements:China's GB standards and NMPA-equivalent protocols force foreign vendors to establish domestic data centers, fragmenting platform economics.
Strategic Opportunities
- Underpenetrated secondary airports:Mid-tier facilities in India and Southeast Asia lack integrated departure control systems, creating white space for modular, subscription-based deployments.
- EU AI Act compliance services:Automated threat detection algorithms in security screening must meet transparency and audit requirements, opening advisory and certification revenue streams.
- Edge computing convergence with 5G:Low-latency passenger flow analytics at boarding gates enable real-time congestion management without full cloud dependency.
Industry Challenges
- Multi-vendor system interoperability:Airlines, ground handlers, and airport authorities operate incompatible data protocols, forcing expensive middleware development for unified operational dashboards.
- Cybersecurity certification timelines:Aviation-specific threat assessment frameworks from national regulators add 12-18 months to product launch schedules for connected baggage and passenger systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Information Systems Market |
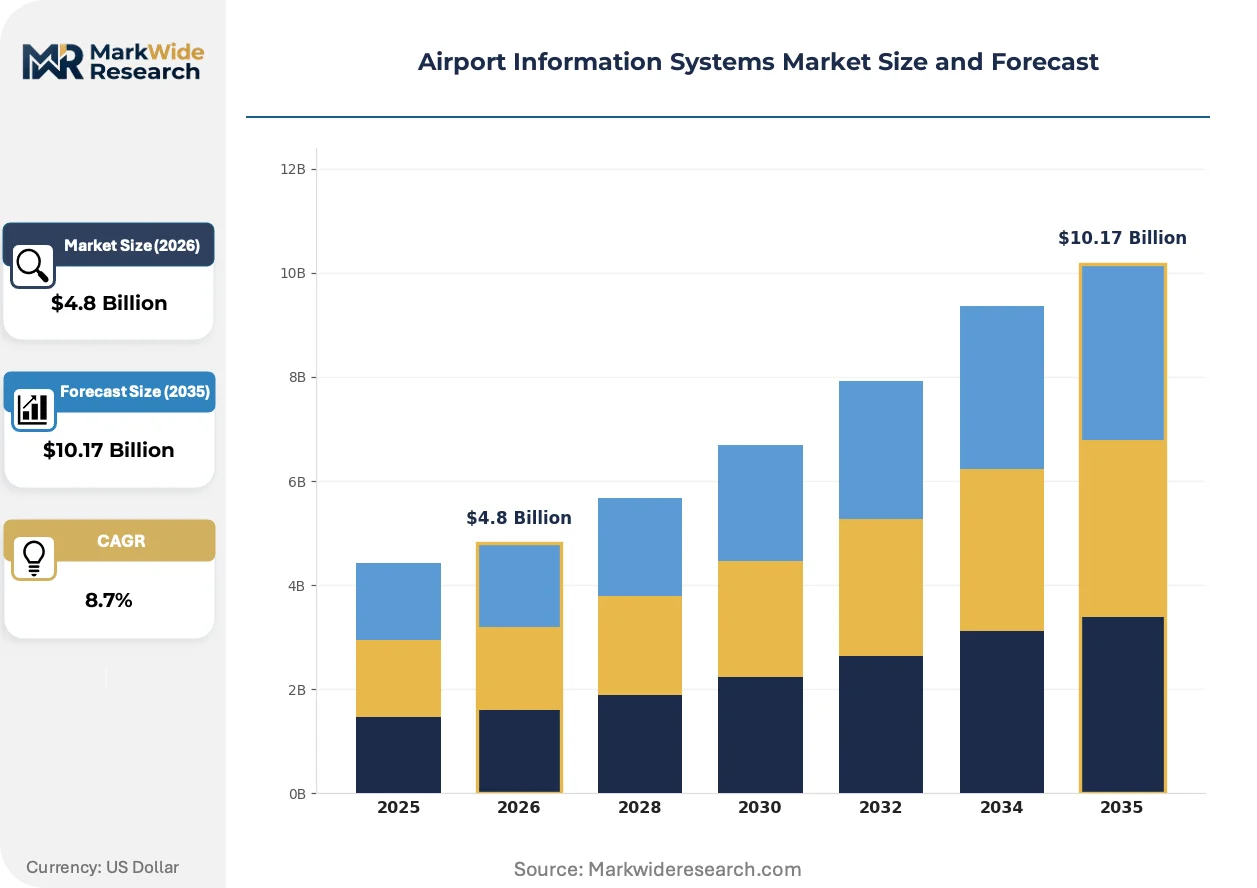
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Passenger Processing, Airport Security, Baggage Handling, Resource Management, Flight Information Display Technology: Biometrics, RFID, Cloud Computing, IoT, Artificial Intelligence, Data Analytics Application: Check-In, Boarding, Security Screening, Baggage Tracking, Ground Handling, Customer Support End User: Airlines, Airport Operators, Ground Services Providers, Regulatory Authorities |
| Companies Covered | SITA, Amadeus IT Group, Thales Group, Honeywell International, Indra Sistemas, IBM, Collins Aerospace, Northrop Grumman Corporation, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Information Systems Market Strategic Shifts & Innovations
Artificial intelligence applications are fragmenting across operational domains rather than consolidating into unified platforms, with distinct vendor specializations emerging for security screening, baggage handling, and passenger flow optimization. This specialization is compressing incumbent advantage while elevating niche technical capabilities.
Biometric identification technology is bifurcating between centralized government identity systems and airport-operated private databases. Hub carriers in the Middle East and Asia-Pacific are adopting government-integrated facial recognition for immigration touchpoints, while European operators under GDPR constraints favor decentralized, airport-controlled biometric tokens. This divergence is forcing platform vendors to engineer dual-track architectures that satisfy both compliance models without code duplication.
EU F-Gas Regulation phase-down schedules are accelerating replacement of hydrofluorocarbon-based cooling systems in automated baggage handling infrastructure. German and French airport operators face 2027 compliance deadlines for refrigerant-intensive tilt-tray sorters, redirecting capex toward magnetic levitation and friction-drive alternatives. Vendors with pre-certified low-GWP equipment are capturing specification mandates ahead of tender cycles.
Airline procurement departments are unbundling long-term service contracts from initial system purchases, compressing vendor revenue recognition into shorter performance-based engagements. North American network carriers now separate hardware acquisition from five-year software maintenance agreements, with penalty clauses tied to uptime thresholds. This shift transfers operational risk to system integrators while pressuring margins on installation and commissioning phases.
Airport Information Systems Market Segmentation
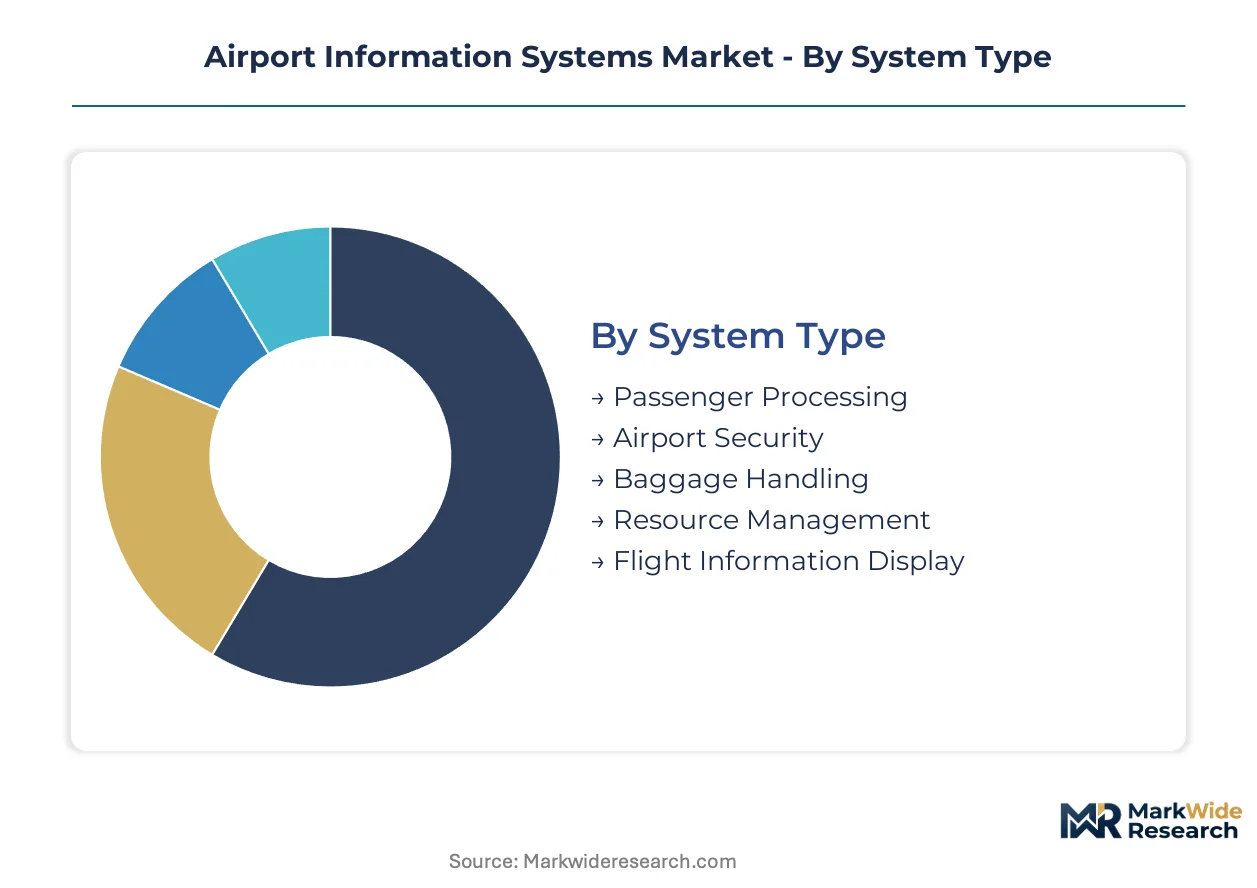
Segmentation reveals where procurement budgets concentrate and which technology layers face displacement risk from adjacent innovations. Understanding these fault lines clarifies where vendors must defend installed base versus attack white space.
System Type:
Passenger processing platforms face the most acute substitution pressure as biometric check-in and mobile boarding passes erode traditional hardware-dependent workflows.
- Passenger Processing:Check-in kiosks, self-service bag drops, and boarding gate automation form the largest installed base. Demand concentrates at Dubai International Airport and Frankfurt Airport as biometric boarding trials expand under ICAO digital travel credential mandates.
- Airport Security:Automated threat detection lanes with CT scanners and AI-assisted baggage screening represent the steepest technology refresh cycle. German airport operators under EU F-Gas Regulation pressure are prioritizing low-GWP refrigerant alternatives in integrated screening systems.
- Baggage Handling:Tilt-tray sorters and destination-coded vehicles move luggage through terminal environments. Magnetic levitation alternatives gain traction as hydrofluorocarbon phase-down deadlines approach.
- Resource Management:Gate allocation, stand planning, and ground service scheduling platforms optimize asset utilization.
- Flight Information Display:FIDS hardware and software distribute real-time schedule updates across terminal environments.
Passenger processing anchors the volume base while airport security gains share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive biometric infrastructure from subscription-based cloud analytics.
- Biometrics:Facial recognition, fingerprint scanning, and iris verification enable touchless passenger flow. Hub airports in China deploy government-integrated identity systems while European facilities favor decentralized tokens under GDPR constraints.
- Cloud Computing:SaaS deployment models compress implementation timelines for mid-tier airports lacking on-premise IT staff. India's secondary facilities represent concentrated demand as subscription economics displace perpetual licenses.
- Artificial Intelligence:Machine learning models predict baggage handling equipment failures and optimize passenger queue management.
- RFID:Baggage tracking tags enable real-time location monitoring through automated sortation systems.
- IoT:Sensor networks monitor environmental conditions and equipment health across terminal infrastructure.
- Data Analytics:Operational dashboards aggregate flight schedules, passenger flows, and resource status for coordinated decision-making.
Cloud computing anchors the volume base while biometrics expands most quickly.
Application:
Customer type divergence separates airline-controlled touchpoints from airport authority-managed processes.
- Security Screening:CT-based cabin baggage inspection and automated threat detection lanes require EU AI Act compliance for algorithmic transparency. German and French operators face the most stringent certification timelines.
- Check-In:Mobile applications, web platforms, and kiosk hardware compete for passenger preference. North American network carriers unbundle long-term service contracts from initial system purchases.
- Boarding:Biometric gates and automated document verification accelerate aircraft turnarounds.
- Baggage Tracking:IATA Resolution 753 compliance drives RFID and Bluetooth Low Energy tag deployment.
- Ground Handling:Turnaround management and load control systems coordinate ramp activities.
- Customer Support:Chatbots and virtual assistants handle routine passenger inquiries.
Check-in anchors the volume base while security screening climbs the fastest.
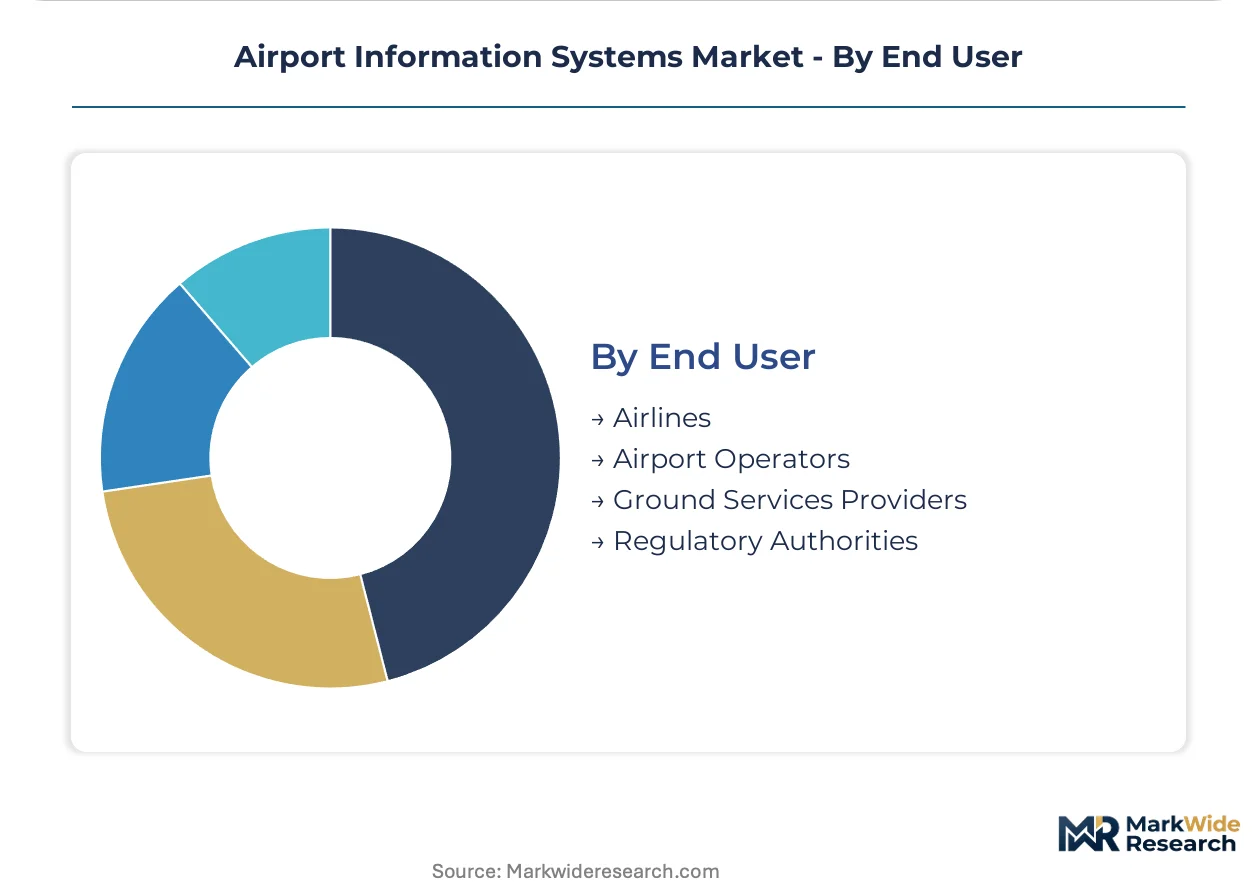
End User:
Maturity gaps separate technology-forward hub operators from budget-constrained secondary facilities.
- Airport Operators:Terminal authorities procure integrated platforms spanning passenger processing, baggage handling, and flight information systems. Procurement concentrates in the United States, Germany, and China where infrastructure modernization programs are active.
- Airlines:Network carriers invest in departure control systems and loyalty-integrated mobile applications. North American majors now separate hardware acquisition from performance-based software maintenance agreements.
- Ground Services Providers:Ramp handling companies require turnaround optimization and load control platforms.
- Regulatory Authorities:National aviation bodies mandate data-sharing standards and cybersecurity certification frameworks.
Airport operators anchor the volume base while airlines gain procurement influence at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation infrastructure deployment patterns diverge sharply by geography. The United States prioritizes FAA NextGen surface surveillance integration, Germany emphasizes EU F-Gas baggage system compliance, and China mandates sovereign data localization for biometric platforms.
United States
FAA NextGen mandates drive surface surveillance and data-sharing upgrades across hub airports. The FAA enforces 2025-2027 compliance deadlines for integrated tower automation systems. Dallas-Fort Worth International Airport deploys AI-driven predictive maintenance for baggage handling equipment under these specifications.
Germany
Frankfurt Airport and Munich Airport accelerate low-GWP refrigerant transitions in tilt-tray sorters. The EU F-Gas Regulation imposes 2027 phase-down deadlines for hydrofluorocarbon-dependent infrastructure. Bavaria-based system integrators capture specification mandates for magnetic levitation alternatives ahead of tender cycles.
China
Beijing Capital International Airport and Shanghai Pudong International Airport expand government-integrated biometric boarding under GB standards. NMPA-equivalent aviation safety protocols force foreign vendors to establish domestic data centers. The Yangtze River Delta concentrates cloud-native passenger processing procurement.
United Arab Emirates
Dubai International Airport validates autonomous baggage operations at scale through AI-driven equipment monitoring. The General Civil Aviation Authority aligns biometric trials with ICAO digital travel credential frameworks. Abu Dhabi International Airport trials touchless immigration corridors with federal identity system integration.
India
Secondary airports in Maharashtra and Karnataka lack integrated departure control systems, creating white space for modular SaaS deployments. The Bureau of Indian Standards issues localization requirements for aviation safety-critical software. Delhi Indira Gandhi International Airport pilots RFID baggage tracking under IATA Resolution 753 compliance programs.
Airport Information Systems Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in airport information systems. Tier-one vendors bundle communications infrastructure with passenger processing platforms, while mid-tier players concentrate on security screening or baggage handling subsystems. Three archetypes dominate: global communications backbone providers, airline reservation system integrators, and security technology specialists. Competitive moves center on biometric platform partnerships and cloud-native architecture licensing.
Among the integrated tier, SITA exemplifies the global communications backbone archetype through its passenger messaging network dominance at hub airports. Amadeus IT Group occupies a parallel position anchoring airline reservation and departure control integration. Thales Group represents the security-screening specialization vector with automated threat detection lane leadership. These three entities collectively illustrate how vendor positioning fragments across operational domains rather than consolidating into unified platforms.
| Leading Market Players |
|---|
| SITA |
| Amadeus IT Group |
| Thales Group |
| Honeywell International |
| Indra Sistemas |
| IBM |
| Collins Aerospace |
| Northrop Grumman Corporation |
| Siemens |
| Others |
Cost & Logistics Intelligence
Ninety-day hardware procurement cycles for biometric boarding gates concentrate vendor pricing power with German and Chinese system integrators who maintain captive component inventories. This lead-time compression rewards integrated suppliers while forcing airport operators toward performance-based SaaS contracts that shift operational risk onto vendors.
Pricing Analysis
Long-term offtake agreements dominate procurement for passenger processing platforms, with five-year software maintenance contracts unbundled from initial hardware acquisition. Price differentiation rests on certification tier—FAA NextGen compliance commands premium positioning against baseline ICAO-aligned systems. Cost compression in cloud-native deployments intensifies as North American network carriers impose penalty clauses tied to uptime thresholds. Secondary airports in India exhibit highest price sensitivity, while hub operators in the United Arab Emirates prioritize biometric integration speed over unit economics.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes inflates inbound logistics costs for CT scanner components and biometric sensor modules sourced from Chinese and South Korean manufacturers. Production gravity centers on Germany for magnetic levitation baggage sorters, the United States for AI-driven analytics engines, and China for government-integrated facial recognition systems. Single-source vulnerability concentrates in specialized aviation software engineering talent pools. Distribution runs through system integrators who bundle hardware, software, and multi-year service commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation infrastructure investment cycles are recovering as post-pandemic passenger volumes rebuild and regulatory compliance deadlines harden across the United States, Germany, and China.
For Market Incumbents: Consolidate biometric platform partnerships with government identity systems in China and the United Arab Emirates to preempt niche specialist encroachment. Deepen backward integration into cloud-native architecture development to capture SaaS migration budgets from mid-tier airports. Lock in long-term service contracts before airline procurement departments complete their shift toward performance-based engagements. For New Entrants and Emerging Players: Modular departure control systems for India's secondary airports represent the most penetrable white space, where subscription economics displace perpetual licenses. Target EU AI Act compliance advisory services for automated threat detection algorithms as German and French operators face stringent certification timelines. Lead with edge computing convergence offerings that enable real-time passenger flow analytics without full cloud dependency. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-driven infrastructure play because FAA NextGen mandates and EU F-Gas Regulation deadlines create non-discretionary procurement windows. Acquisition candidates should display pre-certified low-GWP equipment portfolios or established domestic data center footprints for China access. Watch biometric boarding trial outcomes at Dubai International Airport as the signal for autonomous operations scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Platform Integration | ICAO digital travel credential mandates force unified identity verification across check-in, boarding, and immigration touchpoints. |
| Cloud-Native Architecture Licensing | SaaS deployment models compress implementation timelines for India's secondary airports lacking on-premise IT staff. |
| Low-GWP Equipment Certification | EU F-Gas Regulation phase-down deadlines redirect German and French capex toward magnetic levitation baggage alternatives. |
| Domestic Data Center Establishment | China's GB standards and NMPA-equivalent protocols force foreign vendors to fragment platform economics through sovereign data localization. |
| AI-Driven Predictive Maintenance | Machine learning models for baggage handling equipment reduce unplanned downtime at Dubai International Airport validation scale. |
Research Approach
Two parallel data streams informed the analysis: structured conversations with airport IT directors, airline procurement officers, aviation software engineers, and ground handling operations managers; and secondary validation through FAA NextGen implementation filings, EU F-Gas Regulation compliance disclosures, ICAO digital travel credential framework documents, and IATA Resolution 753 baggage tracking adoption data. Bottom-up segmentation modeling triangulated against top-down market sizing from infrastructure modernization program budgets.
Across the analysis window, forecasts employed system-type segmentation by passenger processing, security screening, baggage handling, resource management, and flight information display; technology layering across biometrics, cloud computing, artificial intelligence, and IoT; and end-user categorization by airport operators, airlines, and ground services providers. CAGRs derived from procurement pipeline tracking and regulatory deadline mapping. Forecast inputs incorporated biometric boarding trial outcomes and cloud migration velocity indicators from hub airport deployments.
Forecasts assume regulatory continuity in FAA NextGen mandates, EU F-Gas Regulation phase-down schedules, and China's GB standards enforcement; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
North America Smart Airport Market
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
Airport Runway Foreign Object Debris (FOD) Detection Systems Market
Airport Technologies
Airport Baggage Conveyor System Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Airport Airside Service Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
Global Remote Towers Market
Airport Technologies
Airport RFID System Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market
Airport Technologies
Smart Airport 2.0 Market