
 Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market | 2026-2036
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market Insights
Multi-source procurement for exterior aircraft lighting components is realigning supply relationships across the value chain. Collins Aerospace leverages its integrated avionics heritage to dominate full-system contracts for OEM line-fit programs. Honeywell Aerospace Technologies sustains technology leadership through advanced optical sensor architectures that reduce false-positive proximity alerts. Safran Electronics & Defense anchors European manufacturing scale with specialized LED guidance light production for Airbus platforms.
Integrated proximity and taxiway guidance light systems on aircraft exteriors comprise externally mounted illumination and sensing assemblies that combine LED or xenon-based visible markers with photoluminescent or infrared detection technologies to alert ground personnel and pilots to aircraft position, wingtip clearance, and taxiway boundaries during low-visibility operations. These systems operate across wavelengths from visible white through infrared, with photoluminescent coatings providing passive illumination independent of electrical power. LED guidance lights occupy the largest installed base due to energy efficiency and extended service intervals, while infrared detection segments register the fastest structural expansion as airports deploy night-vision-compatible ground safety networks. Optical sensors command premium positioning within technology tiers because they enable real-time proximity measurement integrated with aircraft health monitoring architectures.
FAA airworthiness standards and EASA CS-25 certification requirements govern exterior lighting intensity, chromaticity, and failure-mode behavior, compelling manufacturers to maintain dual-qualification testing protocols. The EU AI Act and emerging machine-vision regulations are beginning to shape automated ground-collision avoidance systems that incorporate these light arrays as redundant signaling layers. Stakeholders must monitor how converging airframe electrification timelines and autonomous taxiing demonstrations redefine the functional specification for exterior guidance illumination before committing to next-generation platform designs.
Market Dynamics
Retrofit mandates from FAA airworthiness directives are compressing upgrade timelines for narrow-body fleets, forcing operators to accelerate exterior lighting modernization ahead of scheduled maintenance windows.
Growth Catalysts
- FAA Enhanced Visibility Standards:Airworthiness directives mandating improved exterior lighting chromaticity and intensity are compelling fleet-wide retrofits across US-registered commercial aircraft.
- Night-Vision Ground Operations:Infrared detection arrays compatible with airport night-vision infrastructure are expanding adoption among cargo operators conducting low-visibility taxiing.
- LED Service Interval Economics:Extended maintenance cycles for solid-state illumination are reducing total cost of ownership for low-cost carriers operating high-cycle narrow-body routes.
Market Restraints
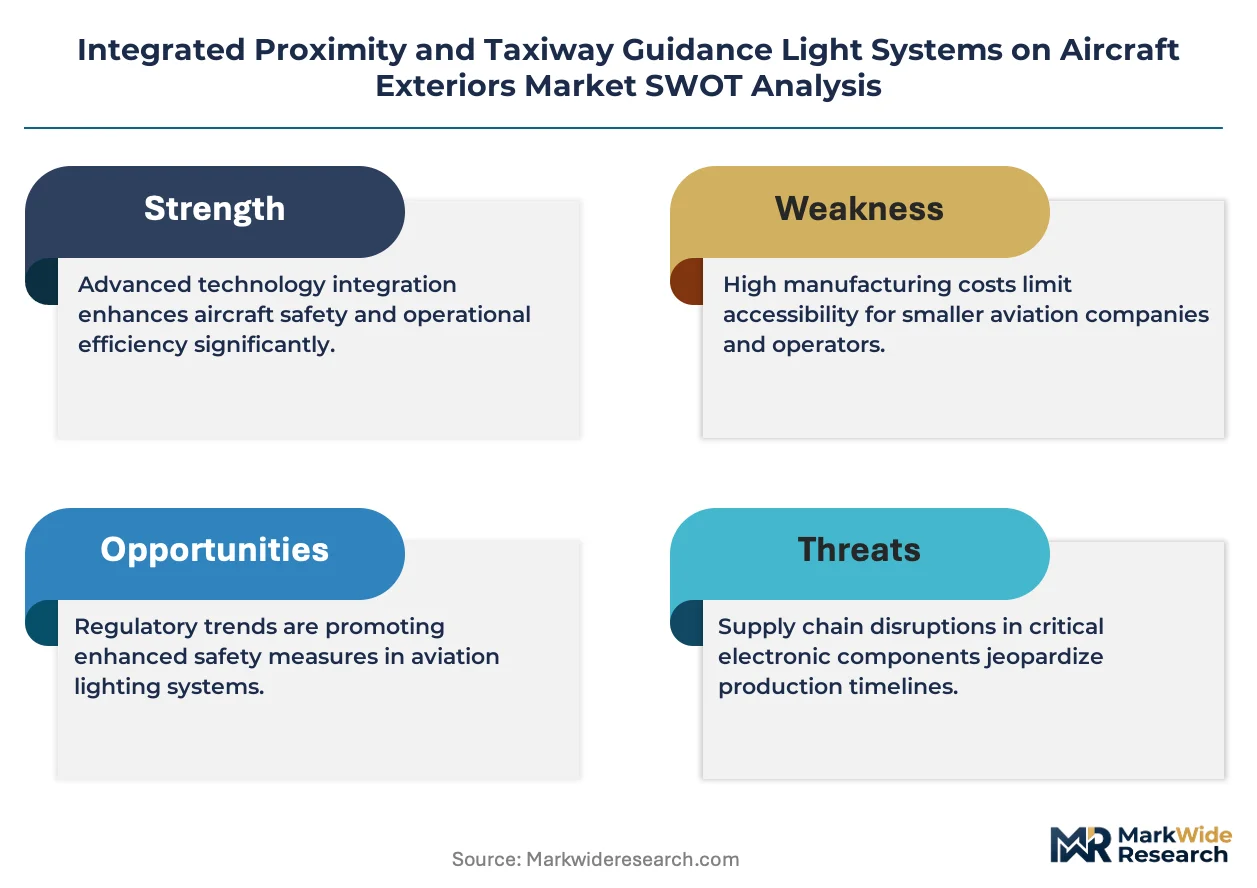
- Dual-Qualification Testing Burden:Simultaneous FAA and EASA CS-25 certification requirements are extending product development timelines and inflating validation costs for multi-market suppliers.
- Photoluminescent Coating Supply Concentration:Specialized rare-earth phosphor sourcing remains concentrated among limited chemical processors, creating input volatility for passive illumination components.
- Xenon Arc Displacement Pressure:Legacy strobe and beacon systems face accelerated obsolescence as LED architectures capture line-fit specifications, stranding installed base amortization schedules.
Strategic Opportunities
- Autonomous Taxiing Integration:Machine-vision-compatible exterior light arrays that serve as redundant signaling layers for automated ground-collision avoidance are opening specification windows for next-generation platforms.
- Airframe Electrification Convergence:Power-distribution architectures in electric propulsion demonstrators are creating demand for low-voltage LED guidance systems with integrated health monitoring.
- EU AI Act Compliance Pathways:Automated ground safety networks incorporating optical sensor fusion are qualifying for regulatory preference under emerging machine-vision governance frameworks.
Industry Challenges
- Optical Sensor Calibration Expertise:Shortage of technicians qualified to align infrared proximity arrays with aircraft attitude reference systems is constraining field installation capacity.
- Legacy 28VDC Integration Complexity:Retrofit programs must reconcile modern LED drivers with existing airframe electrical buses without triggering cascading avionics bus load recertification.
- Health Monitoring Architecture Standardization:Competing digital integration protocols between airframe OEMs are fragmenting the specification landscape for smart exterior lighting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market |
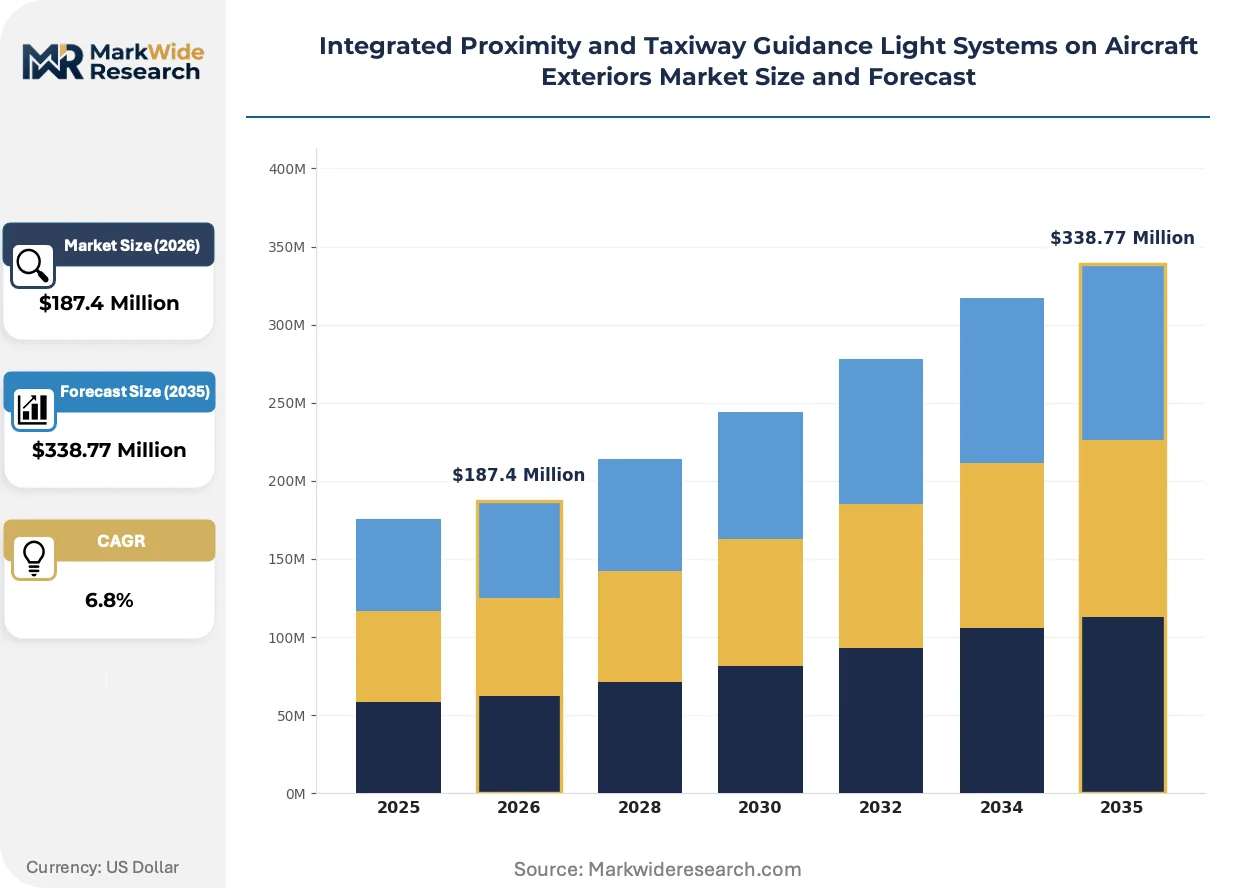
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Guidance Lights, Fiber Optic Markers, Halogen Beacons, UV Indicators, Xenon Flashers Technology: Photoluminescent Systems, Infrared Detection, Optical Sensors, Radio Frequency Identification, Ultrasonic Signaling Application: Pre-Flight Inspection, Ground Operations Safety, Runway Navigation, Aircraft Parking Assistance, Emergency Signaling End User: Air Traffic Controllers, Airport Maintenance Teams, Aircraft Manufacturing Firms, Aviation Safety Inspectors |
| Companies Covered | Collins Aerospace, Honeywell Aerospace Technologies, Safran Electronics & Defense, Astronics Corporation, Whelen Aerospace Technologies, Luminator Aerospace, Precise Flight, Universal Avionics, Oxley Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market Trends and Innovations
Active infrared detection is displacing passive photoluminescent markers as the dominant technology architecture for ground proximity alerting, reshaping supplier capability requirements and procurement specifications.
Solid-state LED illumination is overtaking xenon-based strobe systems in new aircraft programs. The technology delivers comparable candela output with fractional power draw and eliminates gas-discharge tube replacement cycles. Major narrow-body OEM line-fit specifications now specify LED exclusively, compressing the addressable market for legacy arc-source suppliers and redirecting aftermarket revenue toward semiconductor-based component ecosystems.
EASA CS-25 exterior lighting amendments are tightening chromaticity tolerances for anti-collision beacons and position lights. The regulatory revision is forcing component suppliers to recalibrate optical filter specifications and re-validate spectral output across temperature extremes. European-registered cargo operators and regional carriers are experiencing the steepest compliance cost escalation as they phase in conforming equipment ahead of mandatory adoption deadlines.
Airline technical procurement teams are consolidating vendor relationships around full-system integrators capable of delivering proximity sensing, guidance illumination, and health monitoring through single-source contracts. This behavior concentrates specification influence with avionics heritage suppliers and marginalizes discrete component specialists. The shift is most pronounced among US major network carriers executing fleet harmonization programs across merged operational entities.
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market Segmentation
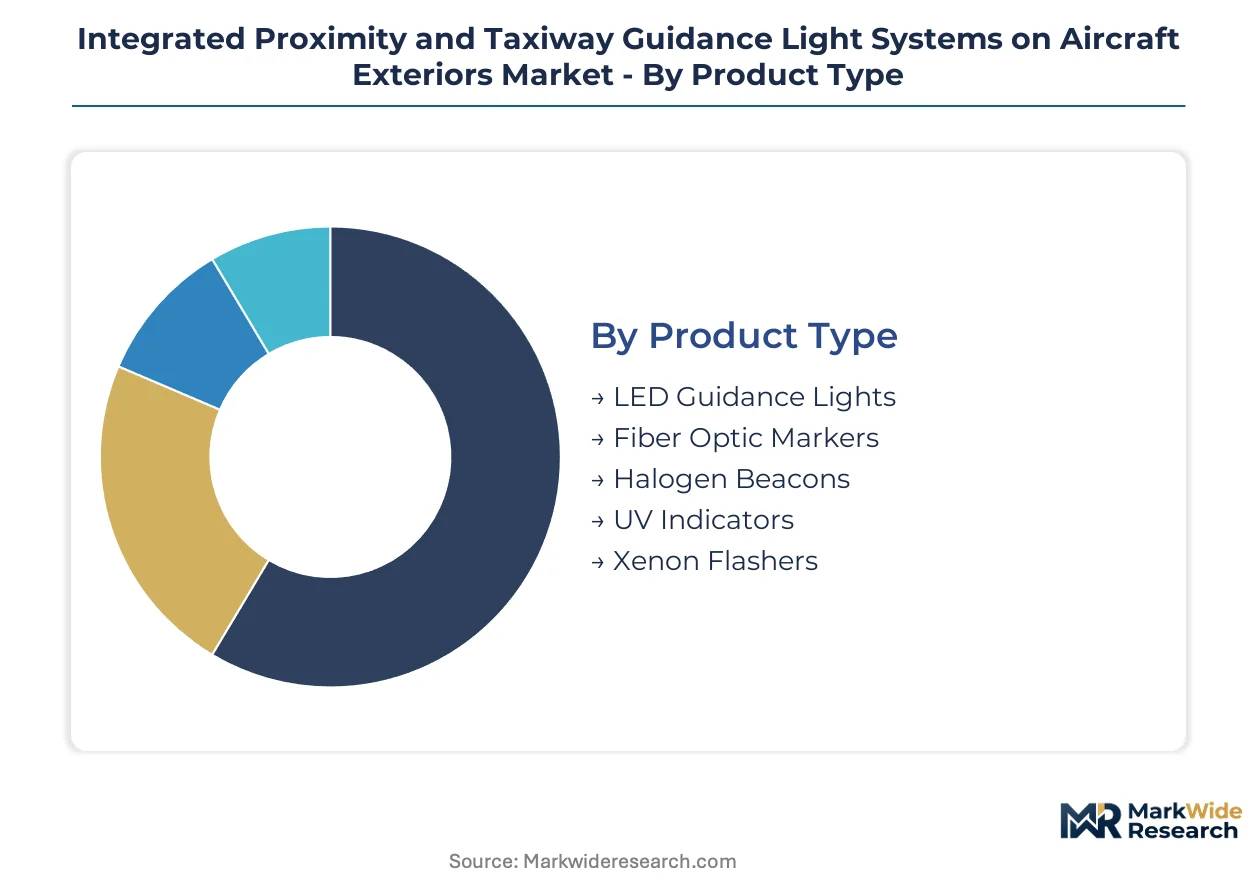
Segmentation reveals how specification authority concentrates among full-system integrators while component specialists compete for discrete procurement slots. Understanding these divisions exposes where technology transitions create procurement windows and where legacy lock-in preserves incumbent positions.
Product Type:
Supply concentration among semiconductor foundries and specialized optical coating houses shapes competitive dynamics across illumination architectures.
- LED Guidance Lights:Solid-state semiconductor arrays deliver candela output with fractional power draw versus legacy sources. Narrow-body OEM line-fit specifications in the United States now specify LED exclusively, compressing addressable market for gas-discharge alternatives and redirecting aftermarket revenue toward chip-scale component ecosystems.
- Fiber Optic Markers:Bundled silica waveguides transmit cockpit-generated light to exterior positions without electrical routing through wing structures. Airbus long-range platforms incorporate fiber architectures for lightning isolation, though installation complexity limits retrofit penetration among aging fleets.
- Halogen Beacons:Tungsten-filament sources persist in cargo aircraft operating under cost-constrained maintenance protocols.
- UV Indicators:Ultraviolet-emitting diodes serve ground crew verification of photoluminescent strip activation.
- Xenon Flashers:Gas-discharge tubes face accelerated obsolescence as LED capture rate climbs in new production.
Today's leader: LED Guidance Lights. Tomorrow's challenger: Fiber Optic Markers.
Technology:
Application context determines whether passive or active detection architectures prevail, with airport night-vision infrastructure investments tilting procurement toward sensor-based systems.
- Photoluminescent Systems:Rare-earth phosphor coatings absorb ambient radiation and re-emit visible light without electrical input. European hub airports maintain installed base for energy independence, though EASA CS-25 amendments are tightening chromaticity tolerances that force recalibration of optical filter specifications.
- Infrared Detection:Active emitter-detector pairs operating at near-infrared wavelengths enable night-vision goggle compatibility for ground personnel. Cargo operators conducting low-visibility taxiing at Memphis and Anchorage hubs are driving fastest structural expansion as airport authorities deploy compatible infrastructure.
- Optical Sensors:Solid-state proximity measurement integrated with aircraft health monitoring commands premium positioning.
- Radio Frequency Identification:Passive transponder interrogation supports automated gate docking.
- Ultrasonic Signaling:Acoustic ranging provides redundant collision avoidance in ground support equipment zones.
Photoluminescent Systems anchor current installed base. Infrared Detection gains share fastest.
Application:
Operational criticality varies by flight phase, with ground movement segments commanding higher specification scrutiny than static parking applications.
- Ground Operations Safety:Wingtip clearance alerting and taxiway boundary demarcation during low-visibility conditions demand highest reliability grades. FAA airworthiness directives mandating enhanced exterior lighting visibility standards are compressing upgrade timelines for US-registered narrow-body fleets.
- Pre-Flight Inspection:Walk-around verification of illumination integrity requires standardized intensity reference points. Maintenance teams at Delta and United technical operations centers are specifying automated health monitoring to reduce manual verification cycles.
- Runway Navigation:Threshold and centerline alignment cues for pilots during takeoff roll.
- Aircraft Parking Assistance:Gate docking precision markers for ground handlers.
- Emergency Signaling:Distress indication protocols for abnormal ground situations.
Ground Operations Safety captures specification investment. Pre-Flight Inspection represents automation opportunity.
End User:
Procurement authority fragmentation across operational and regulatory stakeholders complicates vendor relationship consolidation efforts.
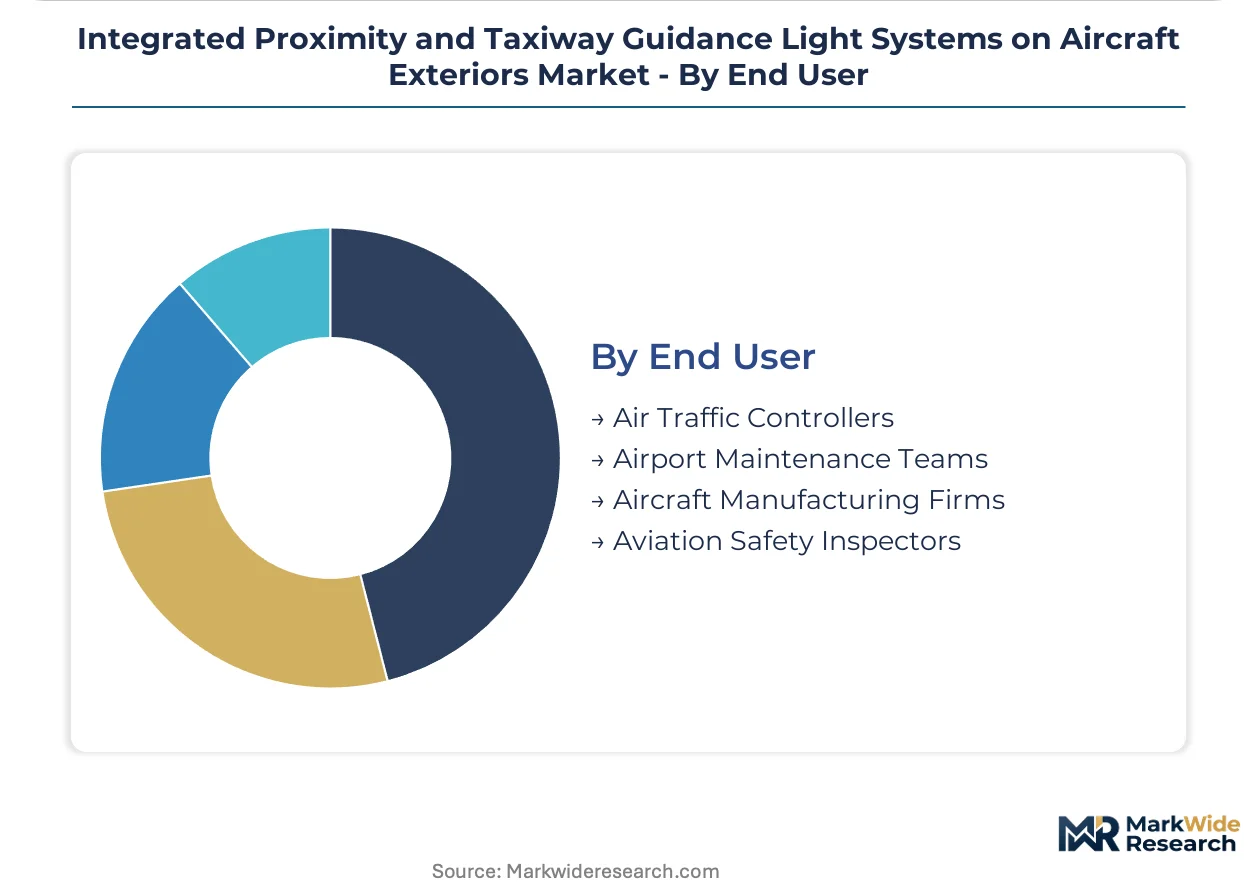
- Aircraft Manufacturing Firms:OEM line-fit specifications determine technology trajectory for 20-year service lives. Boeing and Airbus technical procurement teams are consolidating vendor relationships around full-system integrators capable of delivering proximity sensing, guidance illumination, and health monitoring through single-source contracts.
- Airport Maintenance Teams:Ground infrastructure operators specify airfield lighting compatibility requirements. Hub airports in the United States are prioritizing exterior aircraft lighting interoperability with their own LED runway edge and taxiway centerline systems.
- Air Traffic Controllers:Visibility standards influence operational minimums indirectly.
- Aviation Safety Inspectors:Regulatory compliance verification drives retrofit mandate timing.
Aircraft Manufacturing Firms hold specification authority. Airport Maintenance Teams gain influence through interoperability demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping supplier footprints as manufacturers relocate final assembly to jurisdictions with streamlined airworthiness certification pathways, particularly where FAA-EASA bilateral agreements reduce duplicate testing burdens.
United States
Hub airports in Atlanta, Chicago, and Dallas-Fort Worth are prioritizing ground safety infrastructure upgrades that drive specification authority for exterior lighting systems. FAA airworthiness directives mandating enhanced visibility standards are compressing retrofit timelines for narrow-body fleets operated by major network carriers. Boeing's technical procurement teams in Seattle and Charleston are consolidating vendor relationships around full-system integrators capable of delivering integrated proximity sensing and guidance illumination.
Germany
Lufthansa Technik's maintenance operations in Hamburg and Frankfurt are specifying automated health monitoring for pre-flight inspection protocols to reduce manual verification cycles. EASA CS-25 exterior lighting amendments tightening chromaticity tolerances are forcing component suppliers to recalibrate optical filter specifications. Airbus manufacturing facilities in Hamburg anchor European demand for specialized LED guidance light production integrated with A320 family line-fit programs.
France
Safran's electronics and defense operations in Paris and Toulouse exemplify European manufacturing scale for aerospace illumination systems. The country's national aviation regulator enforces EASA certification requirements while maintaining bilateral recognition protocols with FAA standards. Toulouse-Blagnac Airport's ground infrastructure operators are deploying night-vision-compatible lighting networks that demand infrared detection array interoperability.
United Kingdom
Heathrow Airport's technical procurement teams are mandating exterior aircraft lighting compatibility with LED runway edge and taxiway centerline systems. The UK Civil Aviation Authority applies EASA-derived standards with post-Brexit adaptation clauses that maintain alignment on exterior lighting intensity requirements. Oxford Group's specialized coating operations represent concentrated capability for photoluminescent component production serving European retrofit demand.
China
COMAC's C919 production ramp in Shanghai is creating specification windows for domestic suppliers qualifying under CAAC airworthiness pathways. The country's national aviation regulator is harmonizing exterior lighting standards with ICAO annexes while developing indigenous certification capacity. Xiamen Airlines and other operators are retrofitting narrow-body fleets with LED guidance systems to reduce maintenance cycles on high-utilization domestic routes.
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue autonomous taxiing integration and machine-vision-compatible architectures. The vendor base concentrates around three strategic archetypes: full-system integrators with avionics heritage, specialized LED component fabricators, and optical sensor technology specialists. Consolidation pressure favors single-source contractors capable of delivering proximity sensing, guidance illumination, and health monitoring through unified procurement channels. Dominant competitive moves include strategic partnerships between semiconductor foundries and airframe OEMs, plus portfolio diversification into infrared detection arrays for night-vision ground operations.
Within the full-system integrator tier, Collins Aerospace and Honeywell Aerospace Technologies exemplify technology leadership through integrated avionics platforms and advanced optical sensor architectures respectively. Safran Electronics & Defense anchors European manufacturing scale with specialized production capabilities for Airbus platform integration. These three entities represent the concentration of specification influence as airline technical procurement teams consolidate vendor relationships around single-source contracts for OEM line-fit and fleet harmonization programs.
| Leading Market Players |
|---|
| Collins Aerospace |
| Honeywell Aerospace Technologies |
| Safran Electronics & Defense |
| Astronics Corporation |
| Whelen Aerospace Technologies |
| Luminator Aerospace |
| Precise Flight |
| Universal Avionics |
| Oxley Group |
| Others |
Pricing and Supply Chain Analysis
LED semiconductor die shrinkage is simultaneously compressing unit manufacturing costs and concentrating procurement leverage among specialized foundries serving aerospace illumination tiers. This dual compression reshapes how tier-one integrators negotiate long-term supply agreements against the backdrop of FAA-EASA dual-qualification testing burdens.
Pricing Analysis
Direct-to-OEM channels command premium positioning through volume-scale discounts that compress distributor margins to single-digit percentages. Three-tier pricing structure across full-system integrators, component specialists, and aftermarket service providers reflects certification-grade differentiation, with EASA CS-25 qualified hardware carrying material premiums over FAA-only equivalents. Pricing pressure stems from low-cost carrier fleet harmonization programs demanding total cost of ownership reductions. Regional carriers exhibit highest price sensitivity; major network carriers prioritize single-source reliability over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Boeing and Airbus final assembly lines, bypassing distribution layers for line-fit specifications. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States; rare-earth phosphor processing for photoluminescent coatings rests on Chinese and German chemical processors. Supply chain risk centers on single-source vulnerability for aerospace-grade LED epitaxy wafers. Distribution runs through avionics integrators with airframe OEM certification heritage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory-arbitrage opportunities favor suppliers locating final assembly in jurisdictions with streamlined FAA-EASA bilateral recognition protocols, exploiting cost differentials between US-based qualification testing and European manufacturing scale.
For Market Incumbents: Extend health monitoring architecture standardization efforts to lock in specification influence before competing protocols fragment the smart exterior lighting landscape. Consolidate backward integration into semiconductor foundry partnerships to secure die supply against emerging entrant capacity plays. Prioritize certification investment in machine-vision-compatible infrared arrays as autonomous taxiing demonstrations reshape procurement criteria.
For New Entrants and Emerging Players: Digital-channel routes through airline technical procurement platforms offer lowest-friction access to retrofit specification windows outside OEM line-fit capture. Target cargo operator low-visibility taxiing upgrades at Memphis and Anchorage hubs as the most penetrable application segment. Pursue go-to-market angles emphasizing night-vision goggle compatibility as airport infrastructure investments create demand pull.
For Investors and Strategic Acquirers: Valuations sit cheapest among optical sensor technology specialists lacking full-system integration capabilities but holding irreplaceable calibration expertise. Long-term viability frames around 5-10 year autonomous ground operations deployment curves. Watch for FAA airworthiness directive expansion beyond narrow-body fleets as the inflection signal indicating addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine-Vision Array Development | Positions suppliers for Boeing and Airbus autonomous taxiing specification windows. |
| Dual-Qualification Testing Investment | Accelerates EASA CS-25 and FAA concurrent certification to compress product launch timelines. |
| Rare-Earth Phosphor Supply Agreement | Secures concentrated input streams for photoluminescent coating production against volatility. |
| Health Monitoring Platform Integration | Consolidates vendor relationships around single-source contracts for fleet harmonization programs. |
| Infrared Detection Array Partnership | Captures cargo operator demand at night-vision-equipped hub airports. |
Research Methodology
Direct dialogue with avionics procurement directors, airframe OEM platform engineers, airline technical operations managers, and FAA certification specialists grounded qualitative findings in operational reality. Secondary validation drew from FAA airworthiness directive filings, EASA CS-25 amendment notices, airframe OEM technical specification releases, and customs records of aerospace illumination component trade flows. Bottom-up triangulation across installed base estimates and top-down reconciliation against fleet modernization program disclosures ensured methodological robustness.
Bottom-up modeling segmented volume and value outputs across product type, technology architecture, application criticality, and end-user procurement authority throughout the projection horizon. CAGRs derived from regression analysis of historical fleet retrofit penetration rates and OEM line-fit specification capture trends. Industry-specific forecast inputs incorporated LED service interval economics and night-vision infrastructure deployment curves at major cargo hubs.
Regulatory amendment timing, semiconductor supply disruption events, and autonomous taxiing demonstration outcomes are the dominant revision risks to base-case assumptions. Forecasts reflect documented assumptions regarding airframe electrification convergence timelines and machine-vision governance framework maturation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Middle-East and Africa Airport Ground Handling Systems Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Airport Runway Foreign Object Debris (FOD) Detection Systems Market
Airport Technologies
Air Traffic Smart Tower Solutions Market
Airport Technologies
Smart Airport Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
Global Airport Baggage Handling System Market
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Airport RFID System Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Airport Interactive Kiosk Market
Airport Technologies
Asia-Pacific Airport Baggage Handling Systems Market
Airport Technologies
Asia-Pacific Airport Ground Handling Systems Market
Airport Technologies
Smart Airport 2.0 Market
Airport Technologies
Asia-Pacific Smart Airport Market