
 Airport Runway Foreign Object Debris (FOD) Detection Systems Market | 2026-2036
Airport Runway Foreign Object Debris (FOD) Detection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Runway Foreign Object Debris (FOD) Detection Systems Market Outlook
A shift from outsourced runway inspection contracts toward in-house automated detection networks is repositioning capital allocation across airport operators. Xsight Systems leverages millimeter-wave radar architectures to dominate high-throughput hub deployments. L3Harris Technologies sustains technology leadership through integrated command-and-control interfaces that bridge detection and air traffic coordination. QinetiQ competes on military base specialization, anchoring defense procurement channels with hardened field-proven platforms.
Airport runway foreign object debris detection systems combine electromagnetic sensors, optical imagers, and kinetic acoustic arrays to identify metallic and non-metallic hazards on paved surfaces in real time, typically operating at detection thresholds below two centimeters under variable visibility conditions. These installations serve the primary commercial purpose of preventing turbine ingestion damage, tire blowouts, and aborted takeoffs that carry catastrophic liability exposure. Radar systems capture the largest installed base among technology categories due to proven all-weather reliability, while camera systems gain share where airports prioritize visual confirmation workflows and legacy infrastructure integration. Integrated solutions command premium positioning within integration level segments by unifying detection, alerting, and maintenance ticketing into single-vendor architectures.
FAA Advisory Circular 150/5210-24 establishes minimum performance specifications for FOD detection equipment in the United States, directly shaping product certification requirements and procurement eligibility. EASA CS-ADR-DSN and ICAO Annex 14 extend parallel compliance frameworks across European and international jurisdictions, creating multi-standard engineering burdens for vendors seeking cross-border sales. Stakeholders must monitor evolving mandates for continuous runway condition reporting and assess whether cloud-based platform architectures can satisfy emerging cybersecurity and data sovereignty requirements without fragmenting operational integration.
Market Dynamics
Airport operators are consolidating runway safety infrastructure around integrated detection-to-response platforms that compress incident response latency from minutes to seconds. This operational imperative is reshaping vendor selection criteria and procurement timelines across major hub installations.
Growth Catalysts
- FAA Advisory Circular 150/5210-24:Mandated performance specifications for automated detection equipment are disqualifying legacy manual inspection contracts at US commercial airports, forcing capital redeployment toward certified sensor networks.
- Turbine ingestion damage liability:Catastrophic engine failure claims exceeding $20 million per incident are compelling hub airports to install real-time FOD monitoring as a risk transfer mechanism.
- Millimeter-wave radar maturation:All-weather detection reliability below two-centimeter thresholds is eliminating the seasonal downtime that plagued earlier electro-optical systems.
Market Restraints
- Capital intensity of hub-grade installations:Full-runway coverage systems require $3-8 million per installation, restricting procurement to Category X and IX airports with sufficient passenger volume to amortize investment.
- Supply concentration in RF componentry:Gallium nitride amplifier fabrication concentrates in East Asian foundries, exposing lead times to semiconductor trade policy volatility.
- Interference with primary surveillance radar:FAA frequency allocation constraints limit transmit power in Ka-band deployments, compressing detection range at certain airport geometries.
Strategic Opportunities
- Regional airport retrofit wave:Category III and IV airports in the United States currently operate without automated detection, representing a latent installed base as FAA enforcement extends beyond hub mandates.
- Cloud-native platform architectures:Software-as-a-service delivery models are lowering upfront capital barriers and enabling predictive maintenance algorithms that reduce sensor downtime.
- ICAO Annex 14 compliance deadlines:International airports in jurisdictions with lagging enforcement are accelerating procurement to meet 2025-2027 certification windows.
Industry Challenges
- Integration with legacy airfield lighting control systems:Proprietary protocols from 1990s-era installations require custom middleware development, extending deployment timelines by 8-14 months.
- Certified technician scarcity:FAA Part 139 runway safety personnel lack training on millimeter-wave calibration procedures, forcing vendors to embed field engineers in multi-year service contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Runway Foreign Object Debris (FOD) Detection Systems Market |
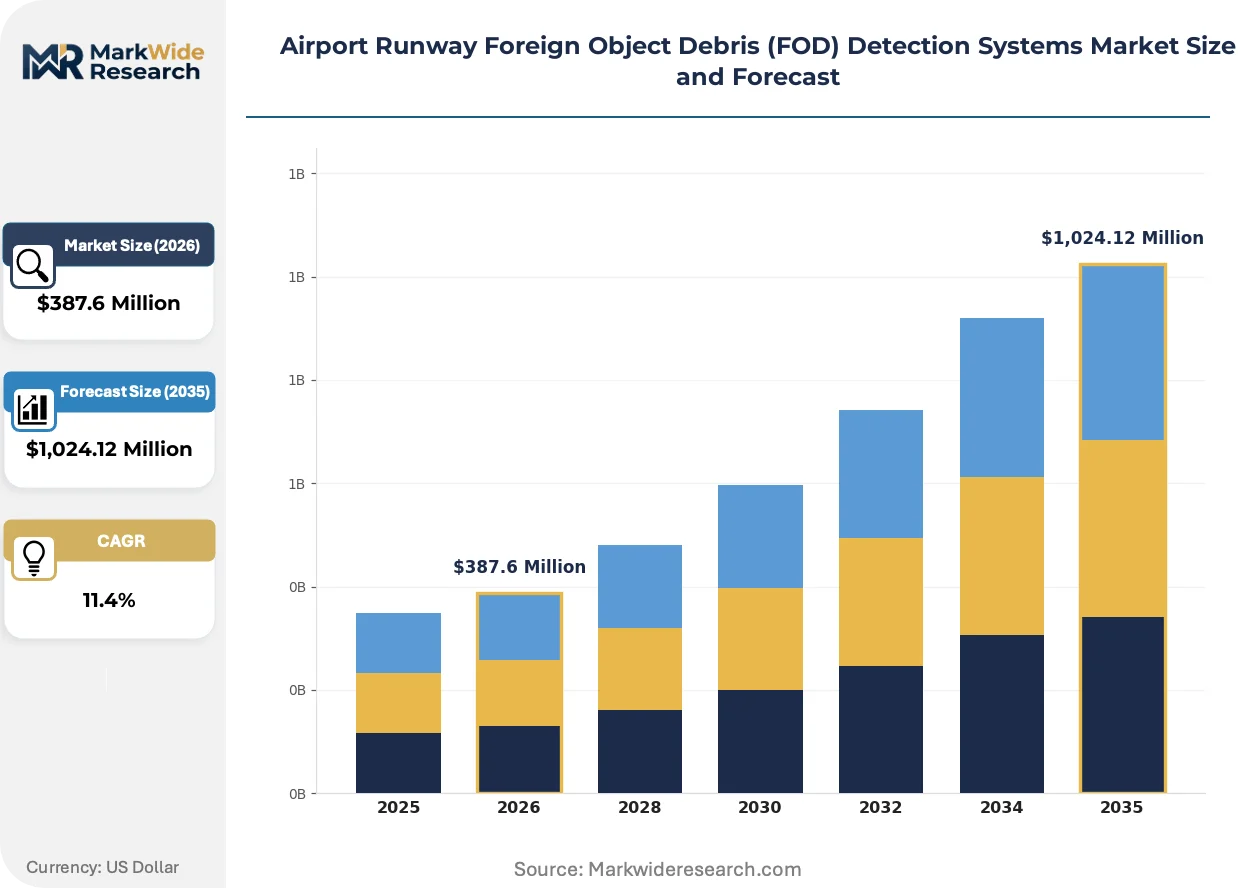
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar Systems, Camera Systems, Laser-Based Systems, Acoustic Sensors Application: Runway Monitoring, Taxiway Inspection, Safety Audits, Maintenance Operations End User: Airports, Aviation Authorities, Military Bases, Air Traffic Control Integration Level: Standalone Systems, Integrated Solutions, Cloud-Based Platforms, Mobile Applications |
| Companies Covered | Trex Aviation Systems, Pavemetrics, ADB SAFEGATE, L3Harris Technologies, Honeywell International Inc., QinetiQ, Stratech Group, Teledyne Technologies Inc., Xsight Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Runway Foreign Object Debris (FOD) Detection Systems Market Strategic Shifts
Sensor fusion architectures are displacing single-modality detection systems as airports demand redundant confirmation pathways that eliminate false-positive disruption to ground operations. This convergence is compressing vendor differentiation and elevating software analytics as the primary competitive battleground.
Millimeter-wave radar augmented by edge-computing inference engines is electrifying real-time classification capabilities, distinguishing metallic aircraft fragments from benign debris without human verification. Tier-one US hubs including Dallas-Fort Worth and Denver International are deploying these fused arrays across full runway lengths during 2024-2025 resurfacing windows. The technology is compressing alert-to-response cycles from 90 seconds to under 15 seconds, reshaping operational protocols for ground vehicle dispatch.
EASA CS-ADR-DSN certification requirements for continuous runway condition reporting are mandating data interoperability between FOD detection networks and airport collaborative decision-making platforms. European hub operators must demonstrate seamless sensor-to-tower information flows by 2026, forcing legacy vendors to retrofit open API architectures. Germany's Frankfurt Airport and Amsterdam Schiphol are piloting standardized data exchange protocols that will propagate across EU member state regulatory adoption.
Airport authorities are unbundling long-term inspection service contracts and bringing detection infrastructure in-house as depreciable capital assets. This ownership model shift displaces the outsourced runway patrol contracts that dominated 2010-2020 procurement patterns. The transition is most visible at US Category X hubs where FAA grant funding structures favor equipment capitalization over operational expenditure commitments.
Airport Runway Foreign Object Debris (FOD) Detection Systems Market Segmentation
Technology architecture and integration depth determine procurement economics for FOD detection infrastructure. Vendor positioning and airport capital allocation diverge sharply across these dimensions, shaping competitive dynamics and deployment timelines.
Technology:
Standardization dominates at the component level while system-level customization prevails in deployment configuration.
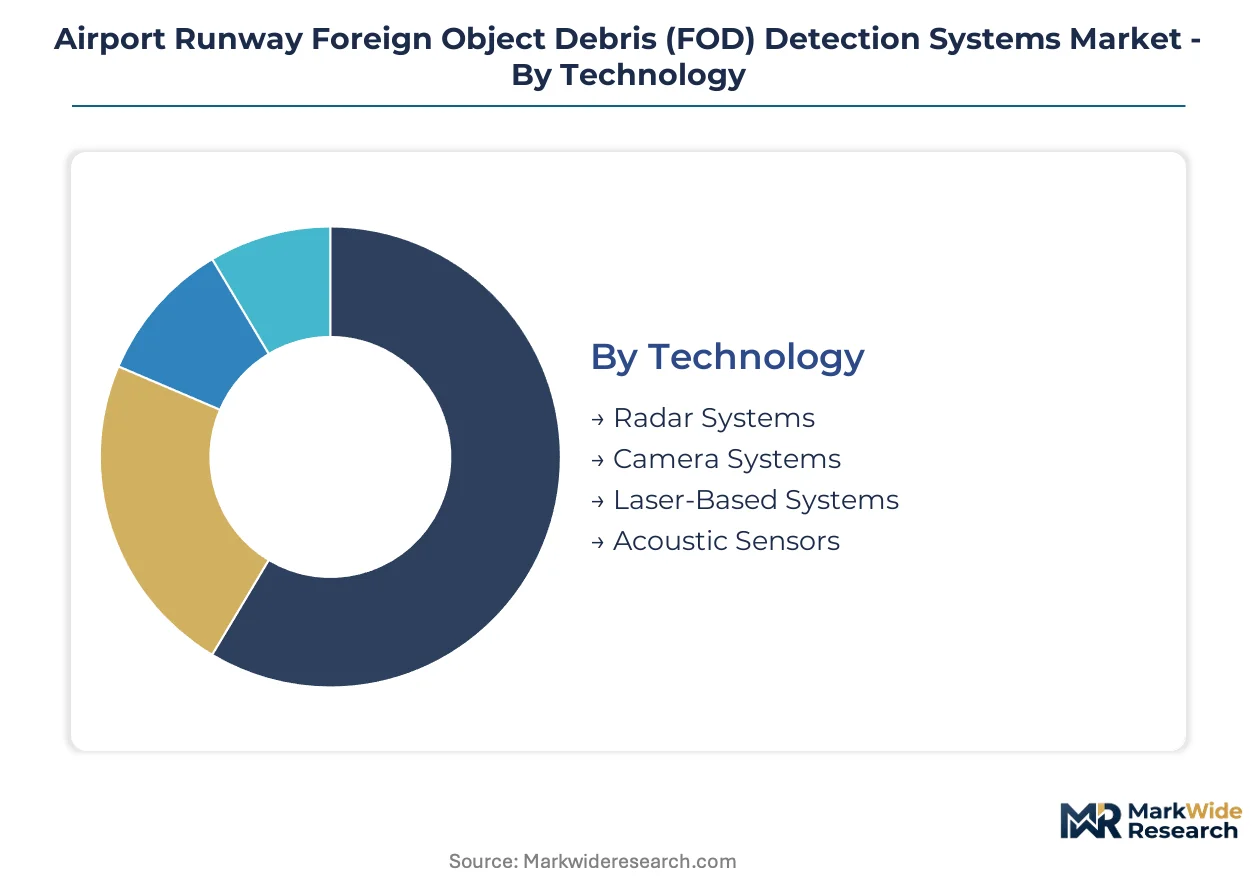
- Radar Systems:Millimeter-wave arrays operating in Ka-band frequencies deliver all-weather detection below two-centimeter thresholds. Demand concentrates at US Category X hubs where FAA Advisory Circular 150/5210-24 mandates certified performance under precipitation and low-visibility conditions.
- Camera Systems:Electro-optical imagers with infrared augmentation prioritize visual confirmation workflows and legacy infrastructure integration. European installations at Frankfurt Airport and Amsterdam Schiphol favor this modality where EASA CS-ADR-DSN emphasizes human-verifiable documentation.
- Laser-Based Systems:LiDAR scanners provide high-precision spatial mapping for foreign object localization.
- Acoustic Sensors:Kinetic detection arrays identify impact signatures from debris strikes on embedded runway surfaces.
Most installed capacity flows through Radar Systems. Expansion is steepest in Camera Systems.
Application:
Volume scales with flight operations intensity while margin concentrates in specialized compliance workflows.
- Runway Monitoring:Continuous real-time surveillance of active paved surfaces prevents turbine ingestion and tire damage during critical flight phases. US hub airports deploy full-length sensor arrays where catastrophic engine failure liability exceeds $20 million per incident.
- Taxiway Inspection:Periodic automated sweeps of movement areas adjacent to runways capture debris migration before runway incursion. Category IX airports in the United States prioritize this application for cost-effective risk reduction.
- Safety Audits:Retrospective data analysis for regulatory compliance documentation and insurance underwriting.
- Maintenance Operations:Scheduled pavement condition assessment integrated with resurfacing and repair workflows.
Runway Monitoring commands the dominant share of deployed sensor hours. Safety Audits are climbing the fastest as EASA and FAA extend continuous reporting mandates.
End User:
Procurement authority and funding mechanisms fragment across operational and regulatory stakeholders.
- Airports:Commercial operators own detection infrastructure as depreciable capital assets, displacing outsourced inspection contracts. US Category X and IX hubs drive procurement volume through FAA grant-eligible equipment capitalization.
- Aviation Authorities:National regulators specify certification requirements and operate reference installations for standard validation. The FAA maintains testbed facilities for Advisory Circular compliance verification.
- Military Bases:Hardened platforms with electromagnetic interference resistance serve expeditionary and fixed-wing operations.
- Air Traffic Control:Tower-integrated alerting systems require real-time data feeds for ground movement coordination.
Airports absorb the majority of direct capital expenditure. Military Bases present the steepest expansion trajectory as defense procurement channels accelerate field-proven platform deployment.
Integration Level:
Customer type dictates architectural preference between standalone simplicity and unified command ecosystems.
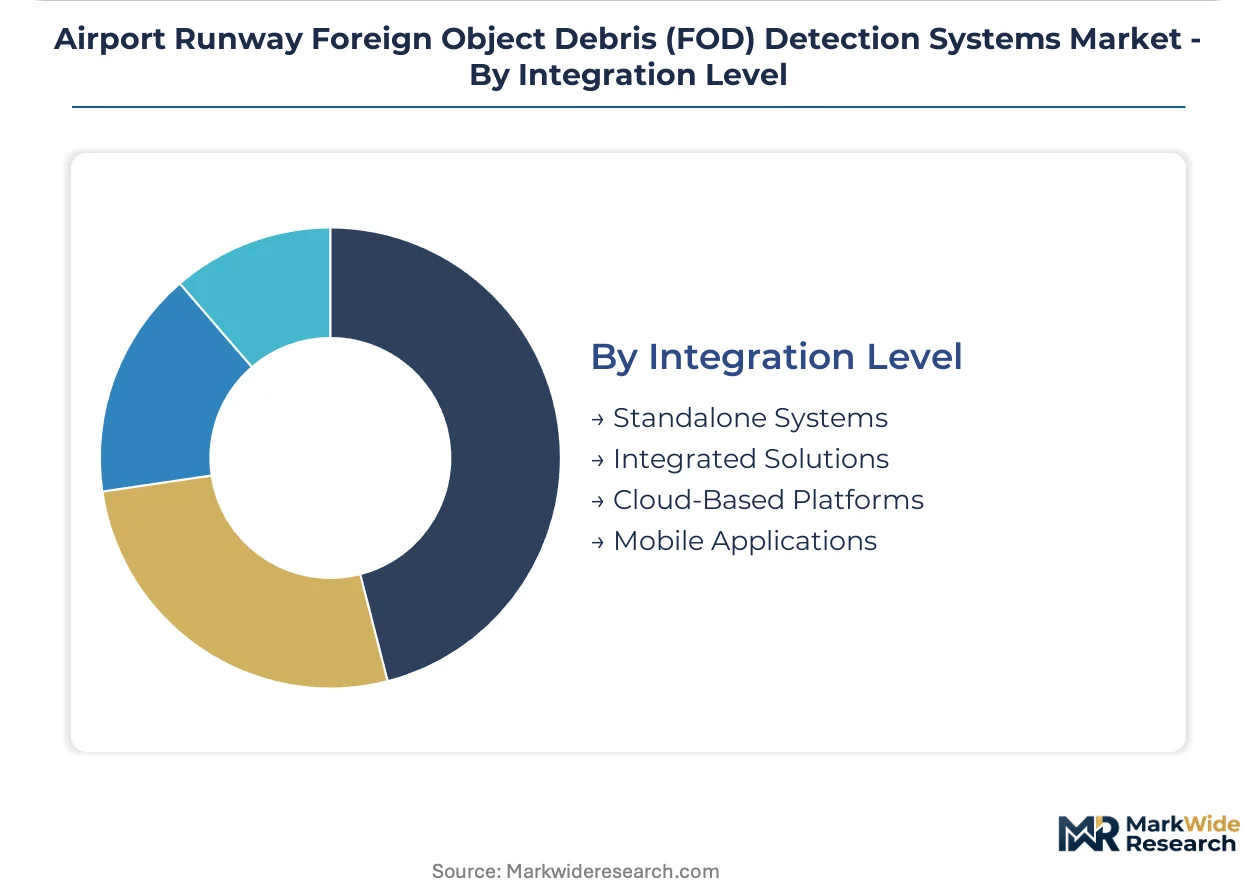
- Standalone Systems:Single-vendor sensor networks with dedicated alerting interfaces minimize deployment complexity. Regional US airports favor this approach where IT infrastructure and technical staffing constraints limit integration ambition.
- Integrated Solutions:Unified architectures combining detection, alerting, and maintenance ticketing command premium positioning. Tier-one US hubs deploy these systems to compress incident response latency from minutes to seconds.
- Cloud-Based Platforms:Software-as-a-service delivery reduces upfront capital barriers and enables predictive maintenance algorithms.
- Mobile Applications:Ground crew dispatch interfaces extend alerting reach beyond fixed control room installations.
Integrated Solutions capture the largest contract values. Cloud-Based Platforms are gaining share fastest as procurement patterns shift from capital expenditure to operational expenditure models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hub airports anchor procurement volume through FAA grant structures that favor capital equipment over operational contracts. Category X and IX facilities drive replacement cycles as Advisory Circular 150/5210-24 disqualifies manual inspection regimes.
United States
Dallas-Fort Worth and Denver International deploy full-runway sensor arrays during 2024-2025 resurfacing windows. FAA Advisory Circular 150/5210-24 mandates certified performance specifications that force capital redeployment from outsourced patrol contracts. Category X hubs in the Southeast and Mountain West concentrate deployment where turbine ingestion liability exceeds $20 million per incident.
Germany
EASA CS-ADR-DSN certification requirements mandate continuous runway condition reporting by 2026. Frankfurt Airport pilots standardized data exchange protocols that propagate across EU member state adoption. Bavaria and North Rhine-Westphalia host the densest hub concentrations where detection-to-tower integration compresses response latency.
United Kingdom
Heathrow and Gatwick prioritize integrated command-and-control architectures that bridge detection with air traffic coordination. The country's national aviation regulator enforces ICAO Annex 14 compliance deadlines accelerating 2025-2027 procurement windows. London and Southeast England concentrate deployment where passenger volume justifies $3-8 million hub-grade installations.
France
Charles de Gaulle and Orly retrofit legacy electro-optical systems with millimeter-wave radar augmentation for all-weather reliability. EASA frameworks extend parallel compliance burdens that shape multi-standard engineering requirements. Île-de-France anchors national procurement as the primary international gateway facing highest FOD risk exposure.
United Arab Emirates
Dubai International and Abu Dhabi International install hardened platforms for high-temperature operational environments. The country's civil aviation authority aligns with ICAO Annex 14 mandates ahead of 2025-2027 certification windows. Dubai anchors Gulf Cooperation Council demand as the region's busiest transit hub.
Airport Runway Foreign Object Debris (FOD) Detection Systems Market Competitive Environment
Global majors compete with regional champions across technology architecture and integration depth. The vendor base stratifies between millimeter-wave radar specialists, integrated platform providers, and military-hardened system fabricators. Three archetypes dominate: sensor-technology purists, command-and-control integrators, and defense-procurement channel anchors. M&A activity concentrates on software analytics capabilities while strategic partnerships bridge legacy airfield lighting integration gaps.
Within the integrated platform tier, L3Harris Technologies and Xsight Systems occupy positions that exemplify detection-to-response unification. QinetiQ anchors the defense-procurement specialist archetype with hardened field-proven platforms. Trex Aviation Systems, Pavemetrics, and ADB SAFEGATE represent regional technology champions competing on legacy infrastructure compatibility and visual confirmation workflows. Honeywell International Inc., Teledyne Technologies Inc., and Stratech Group sit within diversified industrial conglomerate structures that leverage cross-divisional air traffic management expertise.
| Leading Market Players |
|---|
| Trex Aviation Systems |
| Pavemetrics |
| ADB SAFEGATE |
| L3Harris Technologies |
| Honeywell International Inc. |
| QinetiQ |
| Stratech Group |
| Teledyne Technologies Inc. |
| Xsight Systems |
| Others |
Value Chain & Pricing Dynamics
Captive in-house production of millimeter-wave radar arrays anchors supply positions for tier-one vendors while compressing pricing power for component-dependent competitors. FAA certification requirements for Advisory Circular 150/5210-24 compliance concentrate procurement eligibility among vertically integrated fabricators who control gallium nitride amplifier supply.
Pricing Analysis
Input-cost pass-through from gallium nitride semiconductor foundries shapes contract economics for radar-centric deployments. Three-tier pricing structure across premium, standard, and economy levels separates full-runway integrated solutions from standalone sensor networks and mobile-augmented retrofit packages. Pricing pressure stems from cloud-native SaaS entrants undercutting perpetual license models with subscription-based operational expenditure structures. Regional airports in Category III and IV classifications exhibit highest price sensitivity, while US Category X hubs prioritize detection reliability over capital cost minimization.
Supply Chain Analysis
Dual-sourcing requirements for Ka-band RF components mandate multi-supplier qualification across Taiwan, South Korea, and Japan for gallium nitride foundry capacity. Millimeter-wave transceiver modules, edge-computing inference engines, and hardened environmental enclosures constitute critical input dependencies. Supply chain risk centers on semiconductor trade policy volatility exposing lead times to export control fragmentation. Distribution runs through direct vendor-airport procurement relationships with embedded multi-year service contracts displacing third-party systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between US hub airports facing FAA enforcement intensity and European facilities accelerating EASA CS-ADR-DSN compliance creates procurement timing advantages for vendors with dual-certification capabilities.
For Market Incumbents: Deploy software analytics capabilities as the primary differentiation lever against commoditizing sensor hardware. Acquire specialized middleware developers bridging proprietary airfield lighting protocols to compress deployment timelines threatened by integration complexity. Anchor defense procurement channels with hardened platform variants to offset margin compression in commercial airport SaaS transitions. For New Entrants and Emerging Players: Regional airport retrofit specialists represent the most penetrable channel partner type for cloud-native platform architectures targeting Category III and IV facilities. White-space concentrates in predictive maintenance algorithms and mobile ground crew dispatch interfaces. Pursue FAA grant-funded equipment capitalization programs as the dominant go-to-market mechanism displacing outsourced inspection contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where sensor-fusion software capabilities concentrate in standalone analytics vendors lacking detection hardware integration. Long-term viability favors platforms unifying millimeter-wave radar with edge-computing classification engines across the 5-10 year technology refresh window. Target acquisition profiles emphasize middleware specialists with certified air traffic control system interoperability. Watch for ICAO Annex 14 enforcement acceleration in Gulf Cooperation Council jurisdictions as the signal indicating procurement wave timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Unifies radar and optical modalities to eliminate false-positive disruption at Dallas-Fort Worth and Denver International. |
| Cloud-Native SaaS Transition | Converts upfront capital barriers into recurring revenue streams targeting regional airport retrofit demand. |
| Defense Procurement Channel Expansion | Deploys hardened platforms for electromagnetic interference resistance in expeditionary military base operations. |
| Legacy Lighting System Interoperability | Develops custom middleware reducing deployment timeline extensions from proprietary 1990s-era protocol conflicts. |
| EASA CS-ADR-DSN Certification Investment | Enables standardized data exchange protocols piloted at Frankfurt Airport to propagate across EU member states. |
Study Parameters
Bottom-up airport procurement modeling reconciled against top-down sensor network deployment tracking forms the analytical core of this study. Primary interviews with airport operations directors, FAA Part 139 safety personnel, millimeter-wave radar engineering leads, and air traffic control integration specialists combined with secondary validation from FAA Advisory Circular filings, EASA CS-ADR-DSN certification databases, ICAO Annex 14 compliance registries, and airport capital expenditure disclosures. Triangulation between vendor shipment records and airport operator installation confirmations ensures dimensional accuracy.
Input-output matrix framing connects millimeter-wave component supply volumes to installed runway coverage metrics across the projection horizon. Segmentation dimensions encompass technology architecture, integration level, application intensity, and end-user procurement authority. CAGRs derive from logistic adoption curves fitted to regulatory mandate enforcement schedules and resurfacing window timing. Forecast inputs incorporate gallium nitride foundry capacity utilization and cloud-native platform subscription conversion rates specific to aviation safety infrastructure.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor trade policy shifts and ICAO enforcement acceleration variance. Forecasts reflect documented assumptions regarding FAA grant funding continuity and EASA certification timeline adherence. Deviation in millimeter-wave radar frequency allocation constraints or gallium nitride export control expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Airport Airside Service Market
Airport Technologies
Airport RFID System Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
North America Smart Airport Market
Airport Technologies
Asia-Pacific Smart Airport Market
Airport Technologies
Asia-Pacific Airport Ground Handling Systems Market
Airport Technologies
Smart Airport Market
Airport Technologies
Helideck Monitoring System Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
Commercial Airport Baggage Handling Systems Market
Airport Technologies
Smart Airport 4.0 Market
Airport Technologies
Middle-East and Africa Airport Ground Handling Systems Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Aviation Beacons Technology Market