
 Smart Airport 2.0 Market | 2026-2036
Smart Airport 2.0 Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Airport 2.0 Market Analytics
The EU Green Deal's aviation decarbonization targets are shifting procurement criteria toward energy-efficient terminal systems. Siemens AG leverages its building automation portfolio to dominate European retrofit programs. Honeywell International Inc. anchors North American deployments through its command-and-control software integration. Thales Group competes on biometric border control specialization across multiple continents.
Smart Airport 2.0 denotes the next-generation airport ecosystem integrating Internet of Things sensors, artificial intelligence-driven analytics, and biometric identity verification across passenger touchpoints, with systems typically processing 10,000+ concurrent data streams per terminal to optimize flow, security, and commercial yield. Biometric Systems lead technology investment as facial recognition gates reduce boarding times by half versus manual checks. Security Management commands the largest application spend, though Revenue Management carries the highest margin pool as airports monetize passenger dwell-time data.
The FAA mandates cybersecurity resilience standards for airport critical systems, while EASA aligns with EU AI Act algorithmic transparency requirements for automated passenger screening. China's MIIT enforces GB standards for IoT device interoperability in aviation infrastructure. Stakeholders must weigh regulatory fragmentation against platform standardization when selecting system architectures for multi-jurisdiction deployments.
Market Dynamics
Biometric passenger processing systems are restructuring competitive positioning as airports replace legacy document checks with facial recognition gates. The EU AI Act's algorithmic transparency mandates and China's MIIT interoperability standards are forcing vendors to redesign system architectures for multi-jurisdiction compliance.
Growth Catalysts
- EU Green Deal Aviation Decarbonization Targets:Terminal energy efficiency mandates in France and Germany are accelerating procurement of smart building automation systems that reduce HVAC loads by integrating real-time passenger flow data.
- China's Dual Carbon Goals:Hub airports in Beijing and Shanghai are modernizing under MIIT smart infrastructure mandates, creating concentrated demand for IoT-enabled terminal operations platforms.
- Biometric Border Control Specialization:Automated passenger screening systems using facial recognition are reducing boarding times versus manual document verification, driving replacement cycles at major international gateways.
Market Restraints
- Semiconductor Supply Concentration:Edge computing hardware for real-time video analytics depends on advanced chip fabrication concentrated in Taiwan and South Korea, exposing deployment timelines to geopolitical disruption.
- GDPR Algorithmic Audit Requirements:The EU AI Act's mandatory transparency documentation for automated decision systems adds 12-18 months to biometric system certification timelines.
- Cybersecurity Insurance Cost Escalation:FAA resilience mandates for critical airport systems have tripled cyber liability premiums, compressing vendor margins on fixed-price retrofit contracts.
Strategic Opportunities
- India's Greenfield Airport Expansion:The country's PLI scheme for electronics manufacturing is attracting system integrators to establish local production of biometric gates and IoT sensors for Noida and Navi Mumbai airports.
- Revenue Management Data Monetization:Dwell-time analytics platforms that track passenger movement through retail zones are enabling airports to implement dynamic concession pricing with airlines and duty-free operators.
- Digital Twin Convergence:The integration of BIM (Building Information Modeling) with real-time sensor feeds is creating new service revenue streams for predictive maintenance of baggage handling and HVAC systems.
Industry Challenges
- Multi-Jurisdiction Compliance Fragmentation:Vendors deploying across the US, EU, and China must simultaneously satisfy FAA cybersecurity standards, EASA AI Act alignment, and MIIT GB interoperability protocols, multiplying engineering overhead.
- Legacy System Integration Complexity:Brownfield terminals require biometric gates to interface with 20-year-old passenger processing databases, forcing expensive middleware development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Airport 2.0 Market |
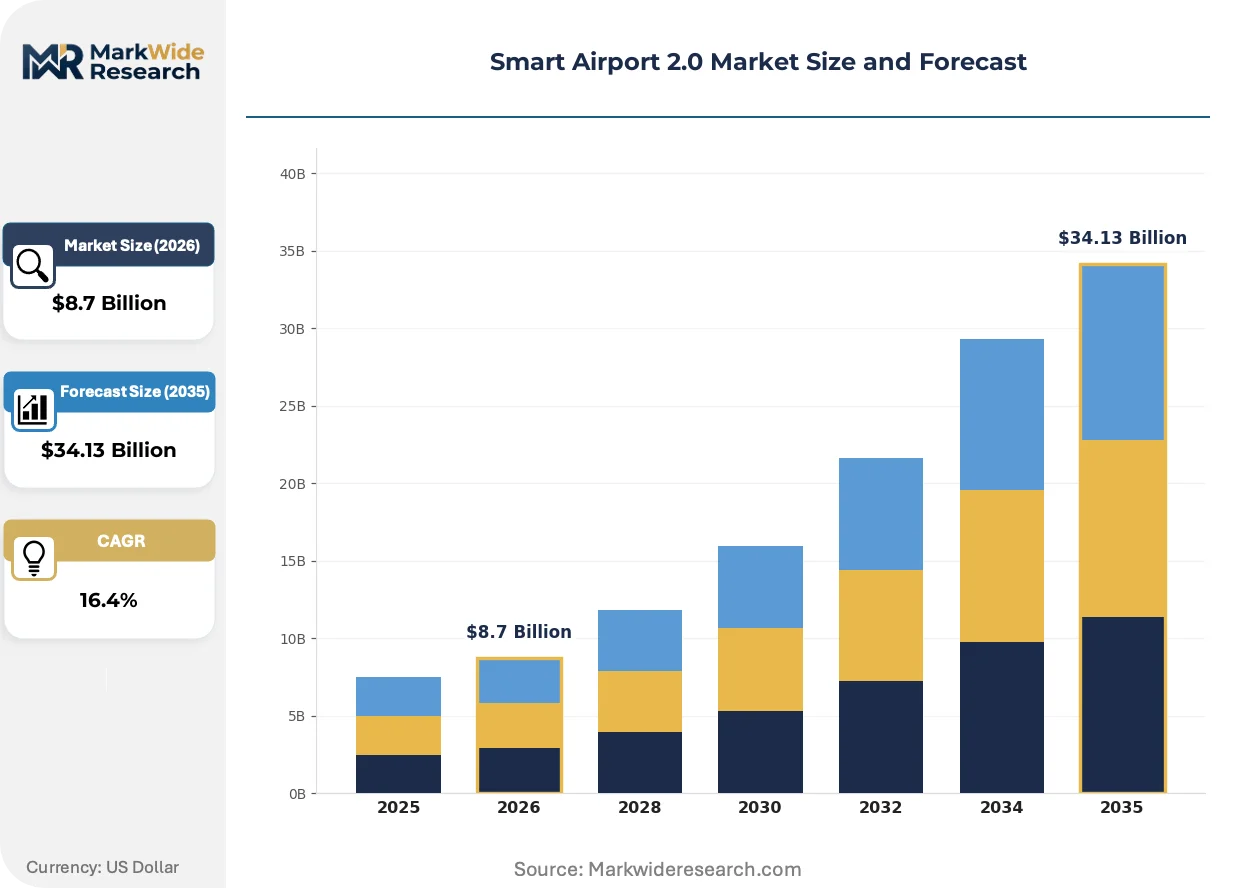
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biometric Systems, Flight Information Display Systems, Security Screening, Baggage Tracking Application: Passenger Processing, Security Management, Operations Optimization, Revenue Management End User: Airlines, Airport Authorities, Retailers, Ground Handlers Service Type: Consulting, System Integration, Maintenance, Training |
| Companies Covered | SITA, Siemens AG, Thales Group, Honeywell International Inc., Cisco Systems, IBM, Amadeus IT Group, Raytheon Technologies Corporation, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Airport 2.0 Market Evolving Landscape
Edge artificial intelligence is compressing decision latency in security screening while regulatory pressure on algorithmic accountability intensifies. Procurement patterns are shifting as airports consolidate vendor relationships to reduce integration risk.
Computer vision platforms with on-chip neural processing are electrifying baggage and passenger screening workflows. Dubai International Airport has deployed these systems for automated threat detection in hold luggage, eliminating centralized server bottlenecks. The technology is compressing hardware footprints and enabling decentralized processing architectures that reduce single points of failure.
The EU AI Act's risk-based classification system for biometric identification is forcing vendors to submit conformity assessments to notified bodies before deployment. High-risk applications including automated border gates now require algorithmic impact documentation and human oversight protocols. European hub airports in Amsterdam and Frankfurt are delaying procurement cycles to verify vendor compliance with these transparency obligations.
Airport authorities are consolidating supplier relationships from fragmented best-of-breed purchases to single-platform mandates. This behavioral shift displaces point solutions for security, operations, and commercial analytics with integrated command-and-control suites. The pattern is most visible in China, where MIIT procurement guidelines favor domestic system integrators offering end-to-end IoT platforms over foreign component vendors.
Smart Airport 2.0 Market Segmentation
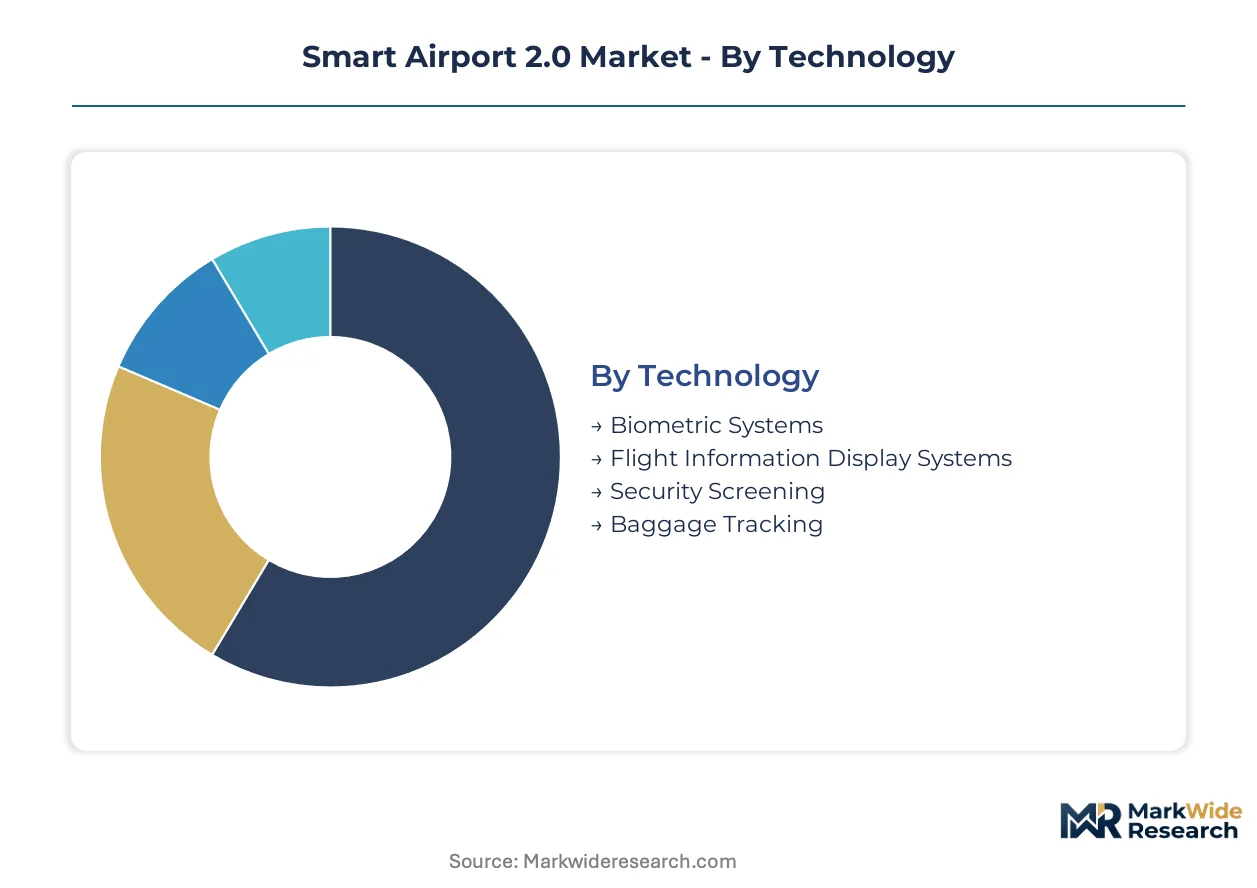
Smart Airport 2.0 procurement decisions hinge on interoperability requirements across legacy infrastructure and regulatory jurisdictions. Technology selection determines compliance pathways, while application prioritization reflects whether airports optimize for throughput, security, or commercial yield.
Technology:
Procurement teams evaluate total cost of ownership against passenger throughput gains when selecting core platforms.
- Biometric Systems:Facial recognition gates with liveness detection process passengers in under 3 seconds per individual. Hub airports in China deploy these under MIIT smart infrastructure mandates, though EU AI Act algorithmic transparency requirements extend certification timelines.
- Security Screening:Computer vision platforms with edge neural processing enable automated threat detection without centralized server bottlenecks. Dubai International Airport has eliminated hold luggage screening delays through these decentralized architectures.
- Flight Information Display Systems:IoT-enabled FIDS integrate real-time gate changes with passenger mobile applications.
- Baggage Tracking:RFID and Bluetooth Low Energy tags provide location telemetry through handling systems.
Biometric Systems lead on scale; Security Screening leads on momentum.
Application:
Capital allocation follows margin profiles, with data monetization applications commanding premium valuations.
- Security Management:Command-and-control software integrates video analytics, access control, and perimeter monitoring into unified dashboards. FAA cybersecurity resilience mandates for critical systems have tripled insurance premiums, compressing vendor margins on retrofit contracts.
- Revenue Management:Dwell-time analytics platforms track passenger movement through retail zones, enabling dynamic concession pricing with duty-free operators. This application carries the highest margin pool as airports monetize behavioral data.
- Passenger Processing:Biometric gates and automated boarding systems reduce document verification bottlenecks.
- Operations Optimization:Real-time sensor feeds optimize HVAC loads and baggage handling energy consumption.
Security Management dominates current spend; Revenue Management expands most quickly.
End User:
Stakeholder influence varies by procurement mechanism and operational control.
- Airport Authorities:Publicly owned hubs in France and Germany prioritize EU Green Deal compliance, procuring energy-efficient terminal automation. These entities control infrastructure procurement and vendor selection.
- Airlines:Network carriers drive biometric boarding investments to reduce turnaround times and improve on-time performance.
- Retailers:Duty-free operators subscribe to dwell-time analytics for merchandising optimization.
- Ground Handlers:Service providers adopt baggage tracking systems to meet SLA transparency requirements.
Airport Authorities lead on scale; Airlines lead on momentum.
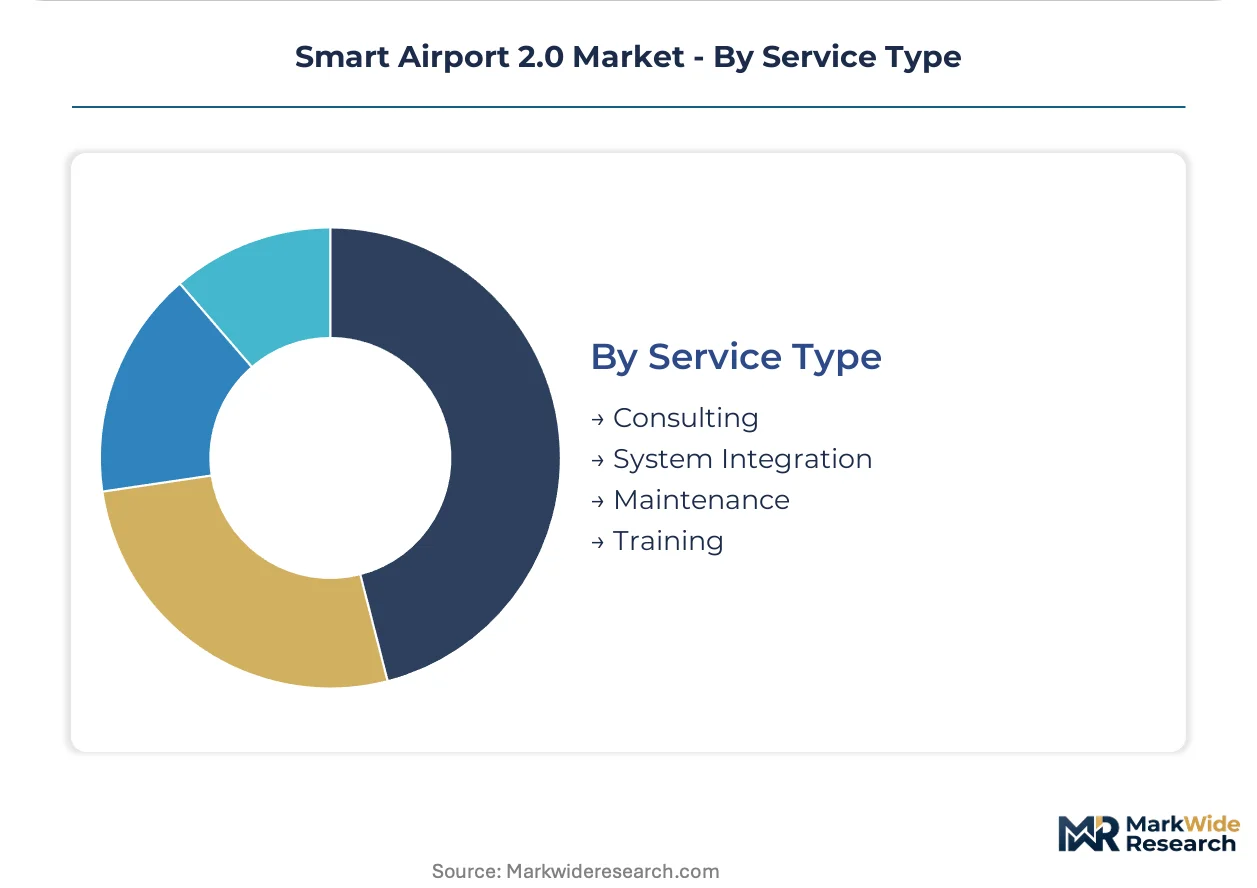
Service Type:
Contract structures shift from discrete installation toward lifecycle partnerships.
- System Integration:Middleware development for legacy database connectivity consumes 40% of brownfield deployment budgets. Vendors must interface biometric gates with 20-year-old passenger processing systems.
- Maintenance:Predictive service contracts using digital twin diagnostics reduce unplanned downtime for baggage handling equipment.
- Consulting:Compliance advisory supports multi-jurisdiction deployments across FAA, EASA, and MIIT regulatory frameworks.
- Training:Operator certification programs address EU AI Act human oversight mandates for automated border gates.
System Integration leads on scale; Maintenance leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aviation infrastructure automation originated in Western Europe during the 1990s hub modernization wave, then migrated to Asia-Pacific as passenger volume growth shifted eastward. Procurement patterns now diverge sharply by regulatory jurisdiction and carbon policy intensity.
China
Beijing Capital and Shanghai Pudong airports are retrofitting terminals under MIIT smart infrastructure mandates tied to dual carbon goals. GB standards for IoT device interoperability govern vendor qualification. The Yangtze River Delta cluster concentrates deployment of facial recognition gates and real-time passenger flow analytics.
United States
Hartsfield-Jackson Atlanta and Dallas-Fort Worth anchor demand for command-and-control software integration. FAA cybersecurity resilience standards for critical systems have reshaped procurement specifications. The Southwest corridor from Texas to Arizona hosts concentrated pilot programs for edge-computing security screening.
Germany
Frankfurt and Munich airports prioritize EU Green Deal terminal energy efficiency targets. EASA alignment with EU AI Act algorithmic transparency requirements extends biometric system certification timelines. Bavaria's industrial automation base supplies building management systems for HVAC load optimization.
India
Noida and Navi Mumbai greenfield projects are absorbing PLI scheme incentives for local electronics manufacturing. The national aviation regulator mandates biometric boarding infrastructure for new airport concessions. Maharashtra and Gujarat host emerging system integration clusters serving South Asian hub modernization.
United Arab Emirates
Dubai International Airport deploys computer vision platforms for automated hold luggage threat detection. The country's civil aviation authority fast-tracks pilot programs for decentralized processing architectures. Dubai's logistics corridor attracts vendors establishing Middle East technical support centers.
Smart Airport 2.0 Market Competitive Landscape
Capital-heavy system integrators compete with asset-light software specialists for procurement contracts. The vendor base organizes into three tiers: full-stack platform providers, component technology suppliers, and regional system integrators. Dominant competitive moves include strategic partnerships to satisfy multi-jurisdiction compliance requirements and portfolio diversification into predictive maintenance services.
Within the European automation tier, Siemens AG and Thales Group exemplify divergent specialization strategies—Siemens leveraging building automation heritage for terminal energy retrofits, Thales concentrating on biometric border control systems. Honeywell International Inc. occupies a position bridging North American command-and-control software with global security integration. These three anchors represent distinct archetypes: infrastructure automation incumbents, security-centric specialists, and diversified industrial conglomerates.
| Leading Market Players |
|---|
| SITA |
| Siemens AG |
| Thales Group |
| Honeywell International Inc. |
| Cisco Systems |
| IBM |
| Amadeus IT Group |
| Raytheon Technologies Corporation |
| Huawei Technologies |
| Others |
Value Network & Pricing Analysis
Airport authority consolidation of vendor relationships from fragmented best-of-breed purchases to single-platform mandates is compressing margins for point solution providers while rewarding full-stack integrators with pricing power through bundled service contracts.
Pricing Analysis
Project-based contracting with multi-year maintenance attachments dominates procurement for biometric passenger processing systems. Price differentiation hinges on EU AI Act certification tier and after-sales service bundling. Cost compression in retrofit segments is intensifying because legacy system integration complexity forces expensive middleware development for each deployment. Regional airport authorities exhibit highest price sensitivity versus major hub operators prioritizing throughput guarantees.
Supply Chain Analysis
Regional distribution centers in Singapore, Dubai, and Frankfurt anchor hub-and-spoke patterns for edge computing hardware deployment. Semiconductor fabrication concentrates in Taiwan and South Korea, with advanced neural processing units for computer vision platforms drawing from these sources. Single-source vulnerability in advanced chip fabrication exposes deployment timelines to geopolitical disruption. Distribution runs through system integrators with local technical support capabilities rather than direct manufacturer-to-airport relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Airport 2.0 market compounds steadily as regulatory mandates for biometric passenger processing and terminal energy efficiency create replacement cycles across installed base infrastructure.
For Market Incumbents: Deploy predictive maintenance service contracts as the priority lever. Incumbents should deepen backward integration into edge computing hardware supply to offset semiconductor concentration risk, while expanding digital twin diagnostics capabilities to capture recurring revenue streams from baggage handling and HVAC system uptime guarantees. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for establishing local production of biometric gates and IoT sensors serving Noida and Navi Mumbai greenfield projects. New entrants should target revenue management analytics as the most penetrable application, leveraging dwell-time data monetization partnerships with duty-free operators as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with regional system integrators possessing multi-jurisdiction compliance expertise across FAA, EASA, and MIIT frameworks. Long-term viability favors acquisition targets with established maintenance revenue streams and digital twin convergence capabilities. The signal to watch is procurement cycle delays at European hub airports verifying EU AI Act algorithmic transparency compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates fragmented security, operations, and commercial analytics into unified command-and-control suites for airport authorities. |
| Strategic Partnership | Enables vendors to satisfy multi-jurisdiction compliance requirements across FAA cybersecurity, EASA AI Act, and MIIT GB standards. |
| Acquisition of Specialist Firm | Adds biometric border control specialization or building automation heritage to fill portfolio gaps in full-stack offerings. |
| Geographic Expansion | Establishes Middle East technical support centers in Dubai's logistics corridor or Indian manufacturing under PLI incentives. |
| Product Launch | Introduces computer vision platforms with on-chip neural processing for decentralized threat detection without server bottlenecks. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Middle East, with primary inputs from each region combining structured interviews with airport procurement directors, system integration engineers, regulatory compliance officers, and airline operations executives alongside secondary validation through FAA airworthiness directives, EASA certification databases, MIIT GB standard filings, and airport authority capital expenditure disclosures. Bottom-up segment sizing triangulates against top-down infrastructure investment flows.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects. Segmentation dimensions modeled include technology type, application priority, end-user stakeholder influence, and service contract structure. CAGRs derive from regression analysis against passenger throughput growth, regulatory mandate implementation schedules, and replacement cycle timing for legacy infrastructure.
Revisions become necessary when semiconductor supply disruptions, EU AI Act enforcement intensity shifts, or geopolitical friction affecting multi-jurisdiction deployment feasibility materialize. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Advanced Airport Technologies Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Airport Airside Service Market
Airport Technologies
Middle-East and Africa Airport Ground Handling Systems Market
Airport Technologies
Airport RFID System Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Asia-Pacific Airport Baggage Handling Systems Market
Airport Technologies
Airport Information Systems Market
Airport Technologies
North America Smart Airport Market
Airport Technologies
Global Airport Baggage Handling System Market
Airport Technologies
Helideck Monitoring System Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Airport Baggage Conveyor System Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Air Traffic Smart Tower Solutions Market