
 Riot Control Vehicle Market | 2026-2036
Riot Control Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Riot Control Vehicle Market Outlook
Government procurement channels for riot control vehicles is fragmenting as national security agencies diversify vendor pools beyond traditional defense primes. Rheinmetall AG leverages its integrated armor systems and European law enforcement relationships to sustain long-term supply contracts. Tata Motors Limited anchors emerging-market demand through cost-competitive domestic production and government fleet partnerships. BAE Systems PLC differentiates via advanced survivability packages and established NATO country relationships.
A riot control vehicle is a purpose-built or retrofitted automotive platform engineered with ballistic-rated steel or composite armor, reinforced suspension systems, and integrated non-lethal deployment mechanisms designed to protect personnel while managing civil disturbances in high-threat environments. Armored vehicles dominate procurement budgets due to multi-mission versatility and crew protection requirements, while water cannons represent a mature segment with stable replacement cycles. Surveillance systems within the technology dimension are capturing expanding margin pools as real-time situational awareness becomes standard in tactical deployments.
Regulatory frameworks including NATO STANAG ballistic protection standards, U.S. NHTSA commercial vehicle safety mandates, and EU CE marking for automotive armor components collectively shape product certification pathways and cross-border market access. India's BIS armor-grade steel standards and CDSCO equipment certifications further constrain import-dependent suppliers while privileging domestic manufacturers. Stakeholders must monitor evolving lethal-to-non-lethal threshold definitions in national use-of-force statutes, as these policy boundaries will determine permissible technology integrations and fleet modernization priorities.
Market Dynamics
Ballistic protection standardization is compressing procurement cycles as NATO STANAG Level 2 requirements displace legacy commercial chassis platforms across metropolitan police fleets.
Growth Catalysts
- Urbanization-driven civil unrest patterns:Megacity police departments in India, Brazil, and Indonesia are mandating armored fleet upgrades to manage population density pressures and protest frequency.
- STANAG 4569 harmonization:NATO ballistic protection standards are creating cross-border certification efficiency, reducing vendor requalification costs for European defense integrators.
- Non-lethal payload integration:Acoustic deterrent systems and directed-energy modules are expanding vehicle mission profiles beyond passive protection into active crowd management.
Market Restraints
- Armor-grade steel supply concentration:Swedish and Ukrainian specialty steel mills control 60% of certified ballistic plate feedstock, exposing fabricators to geopolitical supply interruptions.
- Commercial chassis conversion limits:Heavy-duty truck platforms from Volvo and Mercedes-Benz carry proprietary electronic architectures that resist armor integration without factory authorization.
- Dual-use export control friction:U.S. ITAR and EU dual-use regulations impose 180-day licensing timelines on vehicles exceeding Level 1 protection, delaying emerging market deliveries.
Strategic Opportunities
- Indian indigenous manufacturing incentives:PLI scheme subsidies and BIS localization mandates are opening captive demand for domestic chassis-armor integrators.
- Surveillance-vehicle convergence:Drone launch platforms and mast-mounted sensor arrays are hybridizing riot control vehicles with tactical reconnaissance functions.
- Electrification retrofit pathways:Battery-electric commercial chassis from BYD and Tata Motors offer silent approach capabilities for urban deployment scenarios.
Industry Challenges
- Ballistic welder certification scarcity:AWS D1.8 structural welding credentials for armor-grade steel remain concentrated in defense contractor workforces, constraining production scaling.
- Legacy fleet integration complexity:Analog radio and mechanical turret systems in 1990s-era vehicles resist digital C4ISR upgrades without complete electronics replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Riot Control Vehicle Market |
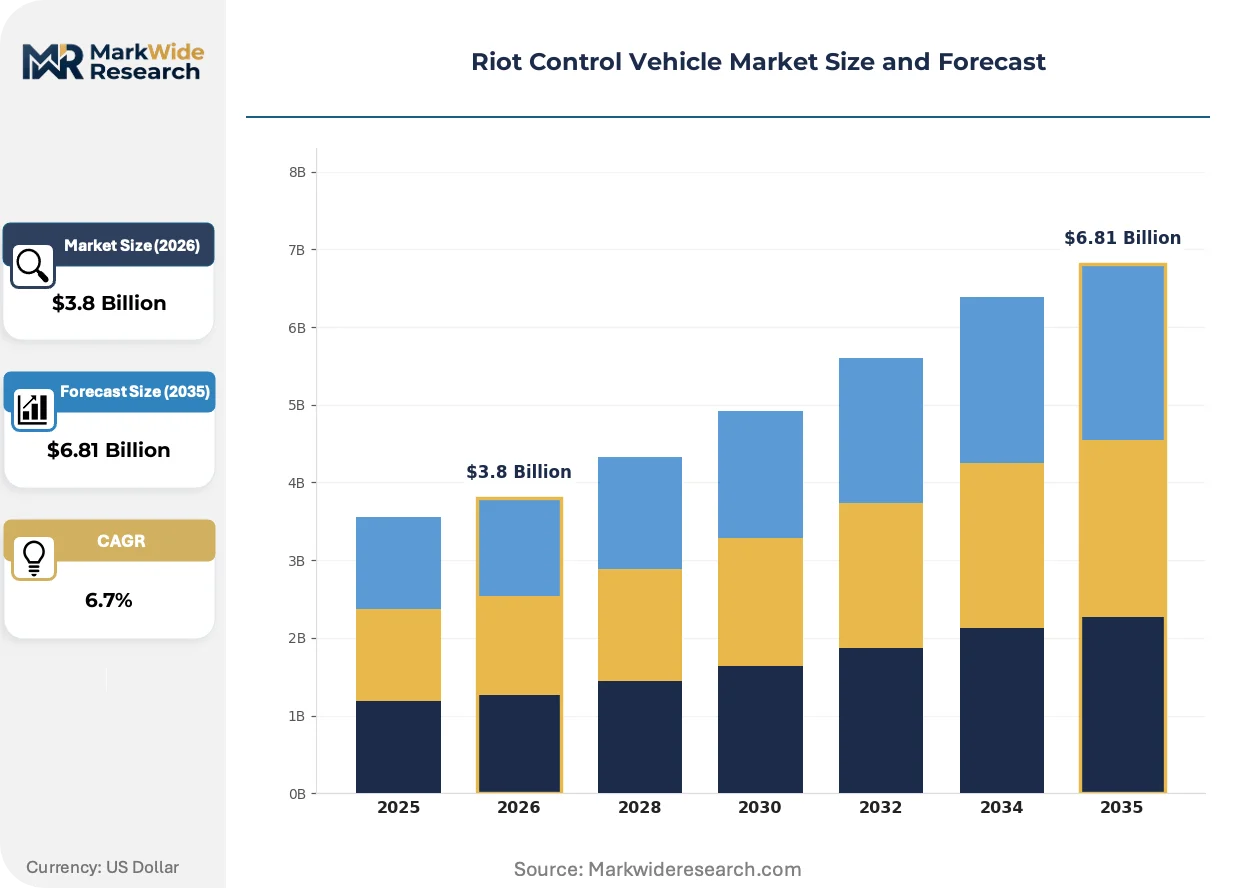
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Armored Vehicles, Water Cannons, Barricade Vehicles, Observation Units Technology: Non-lethal Weapons, Surveillance Systems, Communication Equipment, Control Systems End User: Police Forces, Military Units, Security Agencies, Private Contractors Deployment Mode: On-road, Off-road, Tactical Urban Environments, Emergency Response |
| Companies Covered | Rheinmetall AG, Tata Motors Limited, BAE Systems PLC, Terradyne Armored Vehicles Inc, Roshel INC, Oshkosh Defense LLC, General Dynamics Corporation, Centigon Security Group, INKAS Armored Vehicle Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Riot Control Vehicle Market Strategic Shifts
Active protection systems and autonomous mobility modules are converging with traditional armored platforms, reshaping how security forces conceptualize vehicle survivability and crew exposure.
Composite-ceramic armor laminates are hybridizing with conventional steel arrays to achieve STANAG Level 3 protection at 40% weight reduction. Metropolitan SWAT units in Germany and Australia are specifying these hybrid configurations for rapid deployment vehicles. This materials transition is compressing the addressable market for pure steel armor fabricators while elevating margin capture by composite subsystem specialists.
EU CE marking for automotive armor components is tightening traceability requirements across the supply chain. Component-level certification now mandates mill-test documentation from raw steel through finished plate, increasing compliance overhead for tier-two fabricators. French and Italian armor integrators are responding by consolidating supplier relationships to reduce audit complexity.
Lifecycle contracting is displacing transactional fleet procurement as municipal budgets prioritize operational expenditure predictability. Brazilian and South African police authorities now specify 10-year maintenance-included agreements rather than capital-acquisition-only tenders. This shift concentrates vendor selection on service network density rather than unit production cost.
Riot Control Vehicle Market Segmentation
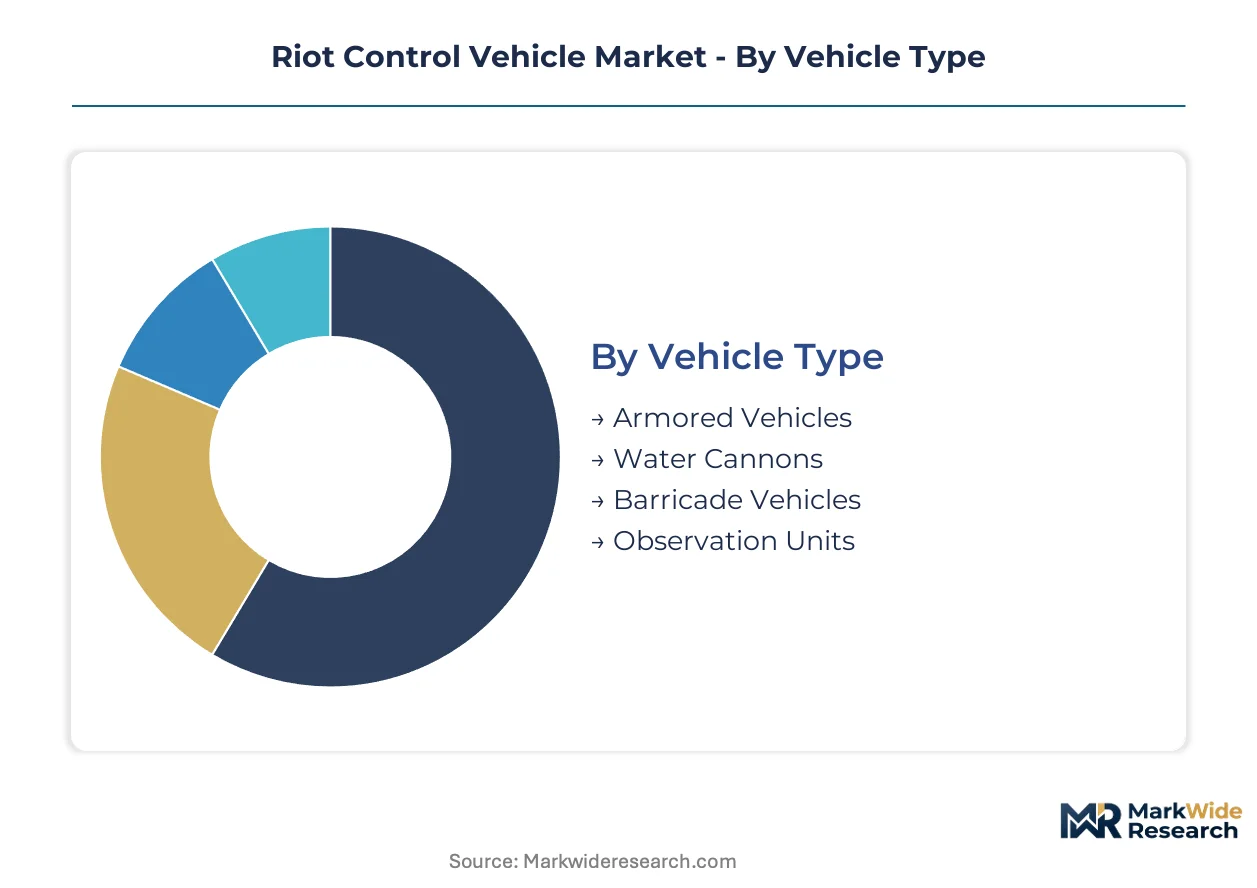
Segmentation in riot control vehicles reveals divergent maintenance intensities and procurement cycles across platform types. Armor integration complexity and non-lethal payload sophistication create distinct aftermarket service profiles that reshape vendor economics.
Vehicle Type:
After-sales service intensity varies dramatically across vehicle architectures, with ballistic protection systems demanding specialized welder recertification and armor plate replacement protocols.
- Armored Vehicles:Multi-mission platforms integrate STANAG-rated steel or composite arrays with reinforced suspension and crew protection modules. Police forces in São Paulo and Mumbai are mandating these configurations for high-threat crowd control scenarios where projectile resistance is non-negotiable.
- Water Cannons:Pump-pressure systems mounted on commercial chassis deliver crowd dispersal through high-volume liquid projection. Brazilian and Indonesian metropolitan departments drive replacement demand as aging fleets face pressure-vessel certification lapses.
- Barricade Vehicles:Heavy-duty push platforms with reinforced frontal structures clear obstacles and establish cordon lines.
- Observation Units:Elevated mast or drone-equipped variants extend situational awareness beyond line-of-sight constraints.
Armored vehicles hold the largest share; momentum sits with observation units as surveillance-vehicle convergence accelerates.
Technology:
Cost tier stratification separates mature mechanical systems from digitally integrated payloads requiring continuous firmware support.
- Surveillance Systems:Mast-mounted thermal cameras, drone launch platforms, and real-time video feeds transform vehicles into mobile command nodes. German SWAT specifications now require 360-degree situational awareness as standard equipment.
- Non-lethal Weapons:Acoustic deterrent arrays and directed-energy modules expand tactical options while reducing lethal force exposure. Australian and Canadian police authorities are piloting these payloads for escalation management.
- Communication Equipment:Encrypted radio and mesh-networking hardware resist jamming in contested electromagnetic environments.
- Control Systems:Integrated fire-control and mobility management computers coordinate multi-payload operations.
Surveillance systems dominate procurement margins; non-lethal weapons are climbing the fastest as use-of-force policy thresholds tighten.
End User:
Customer type determines procurement channel access and specification authority, with state security apparatuses wielding divergent technical requirements.
- Police Forces:Metropolitan departments in megacities drive volume demand with standardized fleet configurations. India's state police modernization programs and Brazil's BOPE units anchor regional procurement patterns.
- Military Units:National guard and internal security forces specify higher protection levels and cross-country mobility.
- Security Agencies:Specialized counter-terror and border protection units require rapid-deployment variants with modular payload bays.
- Private Contractors:Critical infrastructure protection firms operate under lighter regulatory constraints with commercial chassis conversions.
Police forces command the installed base; security agencies represent the steepest expansion trajectory as border militarization intensifies.
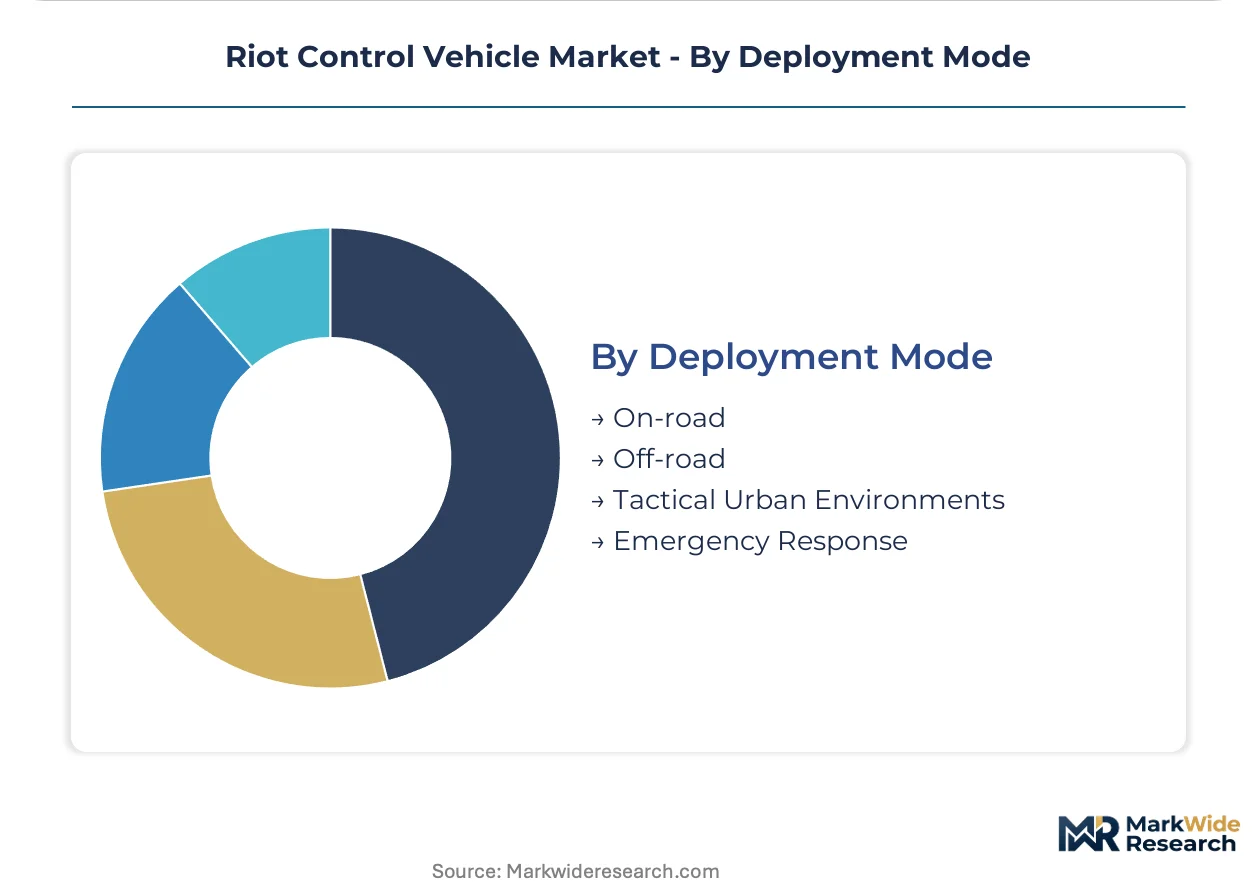
Deployment Mode:
Application context dictates chassis architecture, with urban density pressures forcing maneuverability trade-offs against protection depth.
- Tactical Urban Environments:Narrow-street maneuverability and elevated threat profiles demand compact armored configurations with 360-degree coverage. Jakarta and Lagos police specifications prioritize tight-turning radii for informal settlement access.
- Off-road:Extended suspension travel and all-terrain mobility serve rural patrol and border interdiction missions.
- On-road:Highway-speed pursuit and rapid response applications favor lighter protection on commercial truck platforms.
- Emergency Response:Multi-hazard configurations integrate fire suppression and medical evacuation capabilities for disaster scenarios.
Tactical urban environments absorb the dominant investment share; off-road configurations are gaining share fastest as peripheral security priorities harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kandla-Mundra port complex on India's western seaboard channels armor-grade steel imports and finished vehicle exports, anchoring South Asian supply chain connectivity for riot control platforms.
India
Maharashtra Police and Delhi Police modernization programs drive armored vehicle procurement for megacity crowd management. The PLI scheme and BIS armor-grade steel standards privilege Tata Motors and domestic chassis integrators over import-dependent rivals. Pune and Chennai manufacturing clusters host welding certification centers and ballistic testing facilities serving state security contracts.
Germany
Rheinmetall AG leverages integrated armor systems and established Bundespolizei relationships to sustain European law enforcement supply chains. KBA vehicle certification and NATO STANAG harmonization create cross-border procurement efficiency for defense integrators. Düsseldorf and Kassel industrial zones concentrate ballistic welder training programs and composite armor R&D.
United States
Metropolitan SWAT units and National Guard formations specify Level 2+ protection for urban civil disturbance scenarios. NHTSA commercial vehicle safety mandates and ITAR export controls shape domestic manufacturing and foreign sales licensing timelines. Michigan and Wisconsin defense corridors host armor integration facilities serving municipal police fleet renewals.
Brazil
BOPE tactical units and São Paulo state police anchor Latin American demand for water cannon replacements and armored rapid deployment vehicles. ANVISA equipment certification and federal public security grants structure procurement channel access. São Paulo and Rio de Janeiro metropolitan regions concentrate aftermarket service networks and pressure-vessel recertification workshops.
South Africa
Private security contractors and border protection units drive demand for commercial chassis conversions with modular payload bays. National arms control regulations and local content requirements constrain import dependency while privileging regional fabricators. Gauteng and Western Cape industrial zones host armored vehicle assembly and regional distribution hubs.
Riot Control Vehicle Market Competitive Environment
On the supply side, the industry is consolidating around integrated armor-chassis platforms and long-term service contracts. Defense primes and automotive OEMs compete through divergent cost structures and certification breadth. Three archetypes dominate: European integrated systems houses, emerging-market domestic champions, and North American defense contractors with survivability specialization. Competitive moves center on indigenous manufacturing partnerships and lifecycle contracting displacement of transactional fleet sales.
Among European integrated systems houses, Rheinmetall AG and BAE Systems PLC exemplify divergent strategic positioning within NATO-aligned procurement channels. Rheinmetall occupies a position anchored in continental law enforcement relationships and armor subsystem verticality. BAE Systems represents the transatlantic defense contractor archetype with established survivability package integration. Tata Motors Limited anchors the emerging-market domestic champion tier, leveraging cost-competitive production and government fleet partnerships to capture Indian state police modernization programs.
| Leading Market Players |
|---|
| Rheinmetall AG |
| Tata Motors Limited |
| BAE Systems PLC |
| Terradyne Armored Vehicles Inc |
| Roshel INC |
| Oshkosh Defense LLC |
| General Dynamics Corporation |
| Centigon Security Group |
| INKAS Armored Vehicle Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Kandla-Mundra port cost dynamics compress margins for armor-grade steel importers while amplifying price differentiation between NATO-certified integrators and commercial chassis converters. Supply concentration in Swedish and Ukrainian specialty mills feeds downstream tiering across procurement channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates STANAG Level 3 composite configurations from Level 2 steel arrays and commercial retrofits. Price differentiation hinges on ballistic certification grade and after-sales service bundling. Cost compression in economy tiers intensifies because Indian domestic manufacturers exploit PLI subsidies. State police modernization programs exhibit highest price sensitivity; security agencies with counter-terror mandates show least.
Supply Chain Analysis
Armor-grade steel feedstock draws from Swedish, Ukrainian, and Indian mills, with composite ceramic substrates sourced from German and Japanese specialty manufacturers. Raw material dependencies center on certified ballistic plate, proprietary welding consumables, and STANAG-rated suspension components. Single-source vulnerability concentrates in Ukrainian mill output disruptions. Distribution runs through defense procurement channels and municipal fleet tender platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against unmanned aerial systems and autonomous crowd management platforms that displace manned vehicle requirements. Incumbents must fortify position against technology leapfrogging.
For Market Incumbents: Entrench through captive armor-grade steel supply agreements with Swedish mills and backward integration into welding certification academies. Counter acoustic deterrent substitution threats by accelerating directed-energy payload R&D. Prioritize lifecycle contracting displacement of transactional sales to lock municipal procurement channels. For New Entrants and Emerging Players: Indian state police fleet modernization outside Maharashtra and Delhi represents the most penetrable entry point for domestic chassis integrators. Surveillance-vehicle convergence in Southeast Asian megacities offers secondary white-space. Pursue joint venture structures with established armor subsystem suppliers to bypass certification barriers. For Investors and Strategic Acquirers: Composite armor subsystem specialists with STANAG certification breadth and municipal service network density present optimal acquisition profiles. Long-term viability rests on electrification retrofit capabilities and drone integration readiness. Monitor Indian PLI scheme expansion announcements as inflection signal for emerging-market manufacturing gravity shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Ballistic Welder Certification Academy | AWS D1.8 credential pipelines address scarcity constraining production scaling across European and Indian manufacturing clusters. |
| Composite Armor Subsystem Acquisition | Ceramic-steel laminate specialists capture 40% weight reduction premiums from German and Australian SWAT specifications. |
| Lifecycle Contracting Transition | Ten-year maintenance-included agreements concentrate vendor selection on service network density in Brazilian and South African markets. |
| Electrification Retrofit Partnership | BYD and Tata Motors battery-electric chassis enable silent approach capabilities for urban tactical deployments. |
| Drone Launch Platform Integration | Mast-mounted sensor arrays hybridize riot control vehicles with reconnaissance functions demanded by security agencies. |
Study Parameters
Desk research of NATO STANAG technical specifications, national defense procurement databases, and automotive armor certification records preceded structured interviews with police fleet procurement officers, defense integrator program managers, ballistic welding certification instructors, and municipal budget directors. Secondary sources included customs trade data for armor-grade steel, BIS localization compliance filings, and EU CE marking audit documentation. Bottom-up vehicle deployment forecasts triangulated against top-down security expenditure allocations.
Assumptions held STANAG 4569 harmonization timelines and Indian PLI scheme continuation fixed while varying civil unrest frequency projections and armor-grade steel supply disruption scenarios. Segmentation modeling spanned vehicle type, protection level tier, technology payload sophistication, and end-user procurement channel. CAGRs derived from fleet replacement cycle analysis and security modernization budget trajectories. Industry-specific inputs incorporated ballistic welder certification pipeline capacity and composite armor laminate yield rates.
Practitioners should monitor Ukrainian mill output stability, Indian BIS standard revision schedules, and lethal-to-non-lethal policy threshold shifts for early signals requiring forecast adjustment. Cross-checking against national security expenditure white papers and municipal procurement tender databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Robotic Combat Vehicle (RCV) Market
Military Vehicles
Military Ground Robots Market
Military Vehicles
Destroyers Market
Military Vehicles
India Combat Vehicle Systems Market
Military Vehicles
Military Amphibious Vehicle Market
Military Vehicles
Military Unmanned Ground Vehicle Market
Military Vehicles
Main Battle Tank Market
Military Vehicles
Southeast Asia Defense Market
Military Vehicles
Japan Defense Market
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
Military Tank Container Market
Military Vehicles
Middle East Military Vehicles Market
Military Vehicles
Russia Defense Market
Military Vehicles
Combat Support Vehicle Market
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market