
 Commercial Airport Baggage Handling Systems Market | 2026-2036
Commercial Airport Baggage Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Airport Baggage Handling Systems Market Outlook
Modular subsystem bundling is expanding as airports seek scalable upgrades without full terminal overhauls. Daifuku Co., Ltd. leverages its manufacturing scale across Asian hub installations. BEUMER Group GmbH & Co. KG anchors European demand through specialized conveyor engineering. Vanderlande Industries B.V. competes on automated sorting integration for high-throughput terminals.
Commercial airport baggage handling systems comprise mechanized conveyor networks, automated guided vehicles, and destination-coded vehicle arrays engineered to transport luggage between check-in counters, security screening stations, and aircraft loading points at throughput rates exceeding 10,000 bags per hour. RFID tracking technology leads the technology segment due to real-time location accuracy requirements, while automated systems represent the fastest-growing category as airports replace legacy belt configurations with robotic sortation. Conveyor systems remain the mature revenue base, though margin pools concentrate in custom high-volume solutions for mega-hub expansions.
The FAA mandates specific fire-safety and accessibility standards for baggage handling infrastructure in US commercial airports, while the EU Green Deal and F-Gas Regulation impose energy-efficiency and refrigerant-phaseout requirements on motorized system components. EASA alignment with CE marking protocols shapes market access for European installations. Stakeholders must monitor evolving carbon-accounting rules and automation-certification thresholds as procurement criteria tighten across major hub redevelopment programs.
Market Dynamics
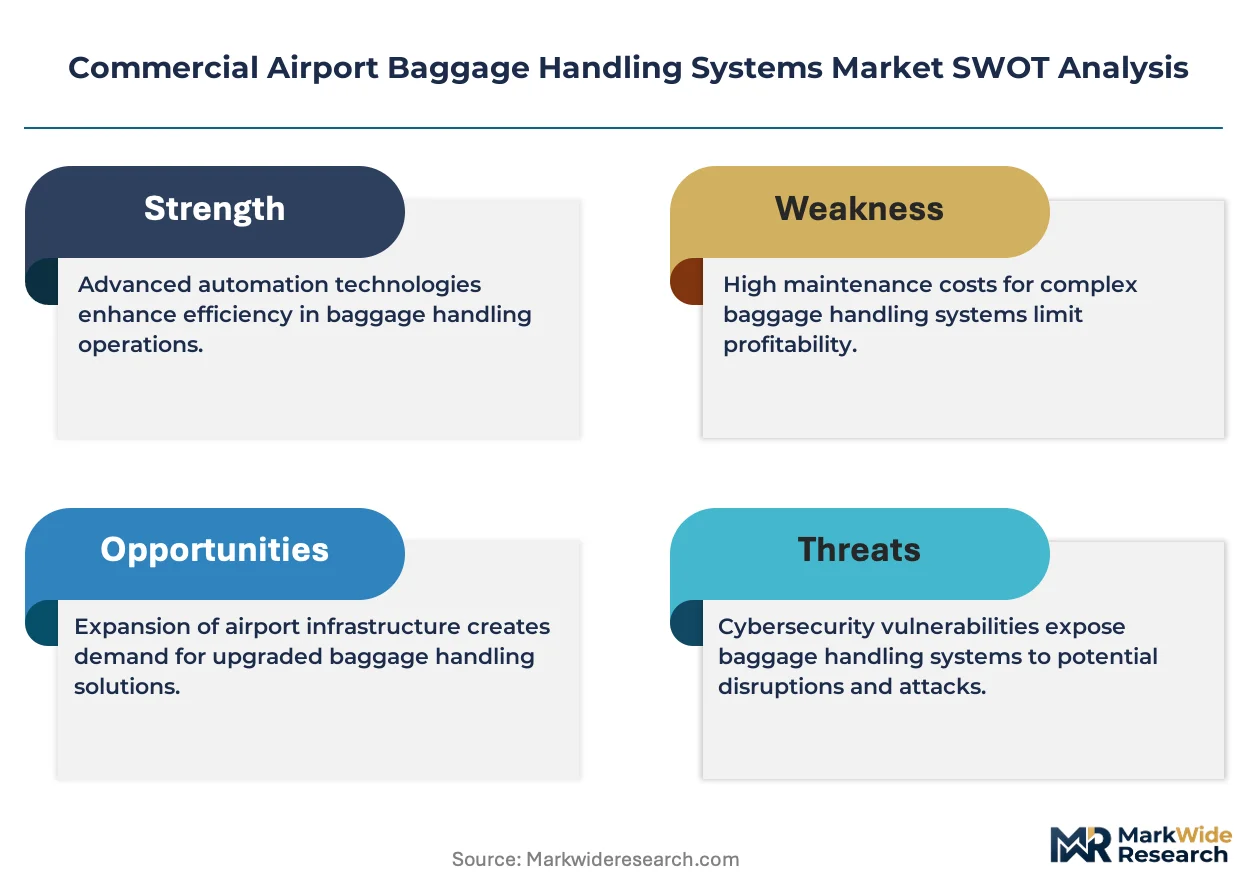
Airport operators are consolidating procurement around modular, scalable subsystem architectures that eliminate full-terminal reconstruction during capacity upgrades. This structural shift compresses vendor qualification cycles and rewards manufacturers with pre-integrated platform portfolios.
Growth Catalysts
- EU F-Gas Regulation phaseout:Mandated refrigerant transitions in motorized drive systems are forcing equipment refresh cycles at European hubs, creating replacement demand for compliant conveyor and sortation infrastructure.
- RFID real-time tracking mandates:Major carriers and ground handlers are specifying item-level baggage visibility as a contractual requirement, pulling investment into sensor-integrated handling networks.
- German mega-hub expansions:Frankfurt and Munich terminal redevelopments are bundling high-throughput automated sortation into integrated procurement packages, concentrating near-term order flow.
Market Restraints
- Steel and aluminum input volatility:Conveyor superstructure fabrication depends on commodity metal pricing that has swung unpredictably, squeezing fixed-price contract margins for system integrators.
- Specialized component supply concentration:Precision drive motors and high-speed diverters source predominantly from German and Japanese industrial automation suppliers, creating single-source vulnerability.
- Legacy belt infrastructure lock-in:Decades-old carousel and tilt-tray installations at mid-tier airports resist cost-justified replacement, slowing upgrade velocity outside flagship hub projects.
Strategic Opportunities
- Indian greenfield airport construction:Noida International and Navi Mumbai airport developments are specifying fully automated baggage handling from commissioning, bypassing legacy migration entirely.
- AI-powered predictive maintenance convergence:Machine learning analytics layered onto existing sensor networks enables condition-based servicing contracts that extend vendor revenue streams beyond hardware installation.
- US FAA fire-safety modernization incentives:Infrastructure grant programs tied to terminal improvement bonds are subsidizing compliant system upgrades at secondary hubs previously deferring capital investment.
Industry Challenges
- Mechatronics engineering talent scarcity:Integration of robotics, controls, and mechanical systems requires hybrid skill sets that outpace vocational training pipeline output in major manufacturing geographies.
- Multi-vendor system certification complexity:EASA and FAA interoperability approvals for mixed-manufacturer subsystems extend commissioning timelines and inflate project risk reserves.
- Retrofit integration with operational terminals:Phased cutover of live baggage streams during partial system replacement demands precision scheduling that compresses installation windows and inflates labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Airport Baggage Handling Systems Market |
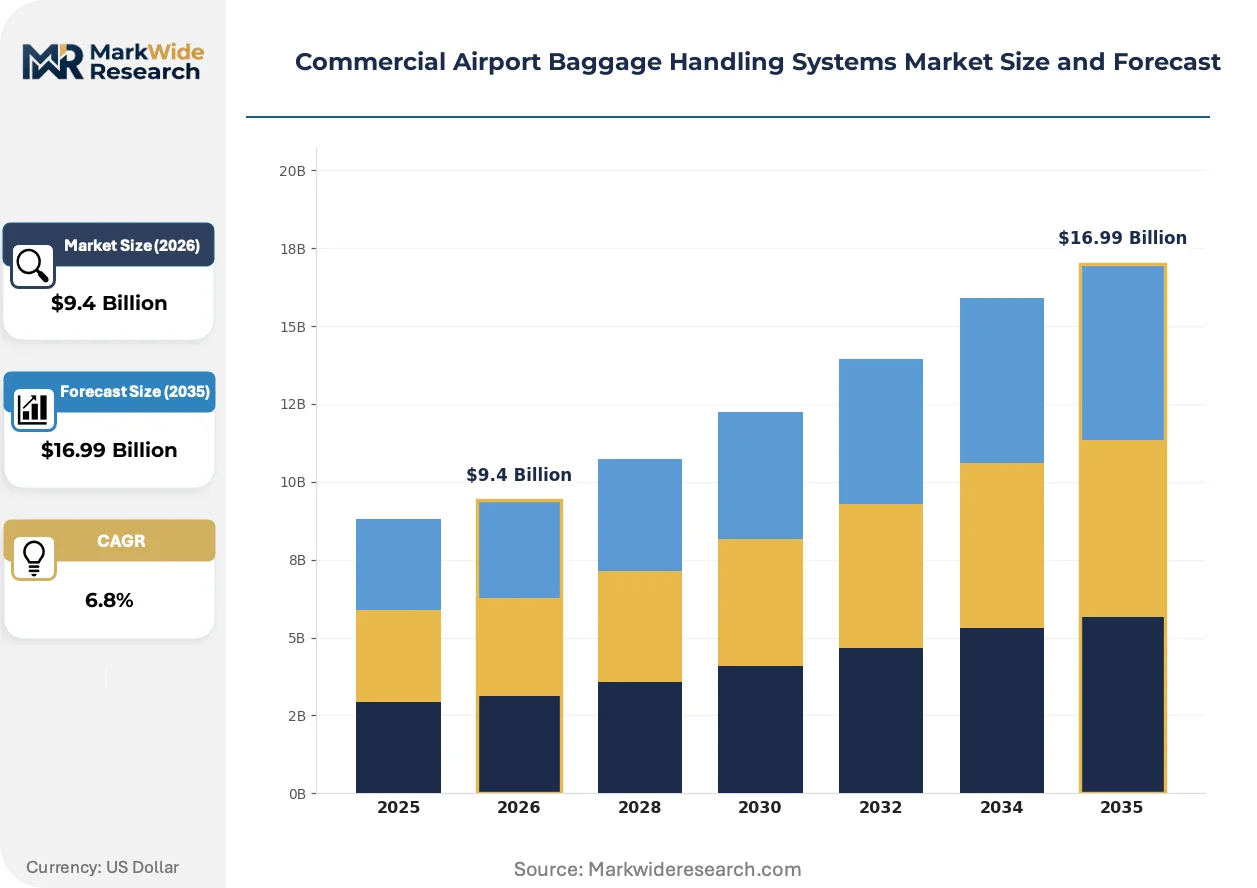
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Conveyor Systems, Automated Guided Vehicles, Destination Coded Vehicles, Baggage Sorting Systems End User: Airports, Ground Handling Companies, Airlines, Security Agencies Technology: RFID Tracking, Barcode Scanning, IoT Solutions, Automated Systems Capacity: High Volume, Medium Volume, Low Volume, Custom Solutions |
| Companies Covered | Daifuku Co., Ltd., Fives Group, BEUMER Group GmbH & Co. KG, Dematic GmbH, TGW Logistics Group GmbH, Vanderlande Industries B.V., Honeywell International Inc., Alstef Group, Siemens Mobility GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Airport Baggage Handling Systems Market Strategic Shifts
Autonomous mobile robotics and destination-coded vehicle arrays are restructuring how airports configure sortation density without fixed infrastructure expansion. These shifts compress capital deployment timelines and enable incremental capacity scaling.
Destination-coded vehicle systems are overtaking traditional tilt-tray sorters in high-throughput terminals by eliminating single points of mechanical failure and enabling dynamic route optimization. Dubai International and Singapore Changi have specified DCV arrays for new concourse installations. The technology is overtaking fixed-path mechanical sortation by reducing maintenance downtime and permitting 24/7 operational continuity during peak holiday surges.
The EU Green Deal's embodied carbon accounting requirements are reshaping equipment procurement specifications across European airport redevelopment programs. Lifecycle emissions assessments now factor into tender scoring alongside throughput metrics and total cost of ownership. German and French hub operators are prioritizing vendors with verified supply chain carbon disclosures, compressing qualification windows for manufacturers lacking environmental product declarations.
Airport authorities are unbundling long-term service contracts from initial system procurement, creating discrete competitive arenas for maintenance and upgrade work. This separation enables specialized aftermarket providers to compete against original equipment manufacturers for recurring revenue streams. The shift is most pronounced at US hubs where public procurement rules favor multi-vendor service competition over single-source lifecycle arrangements.
Commercial Airport Baggage Handling Systems Market Segmentation
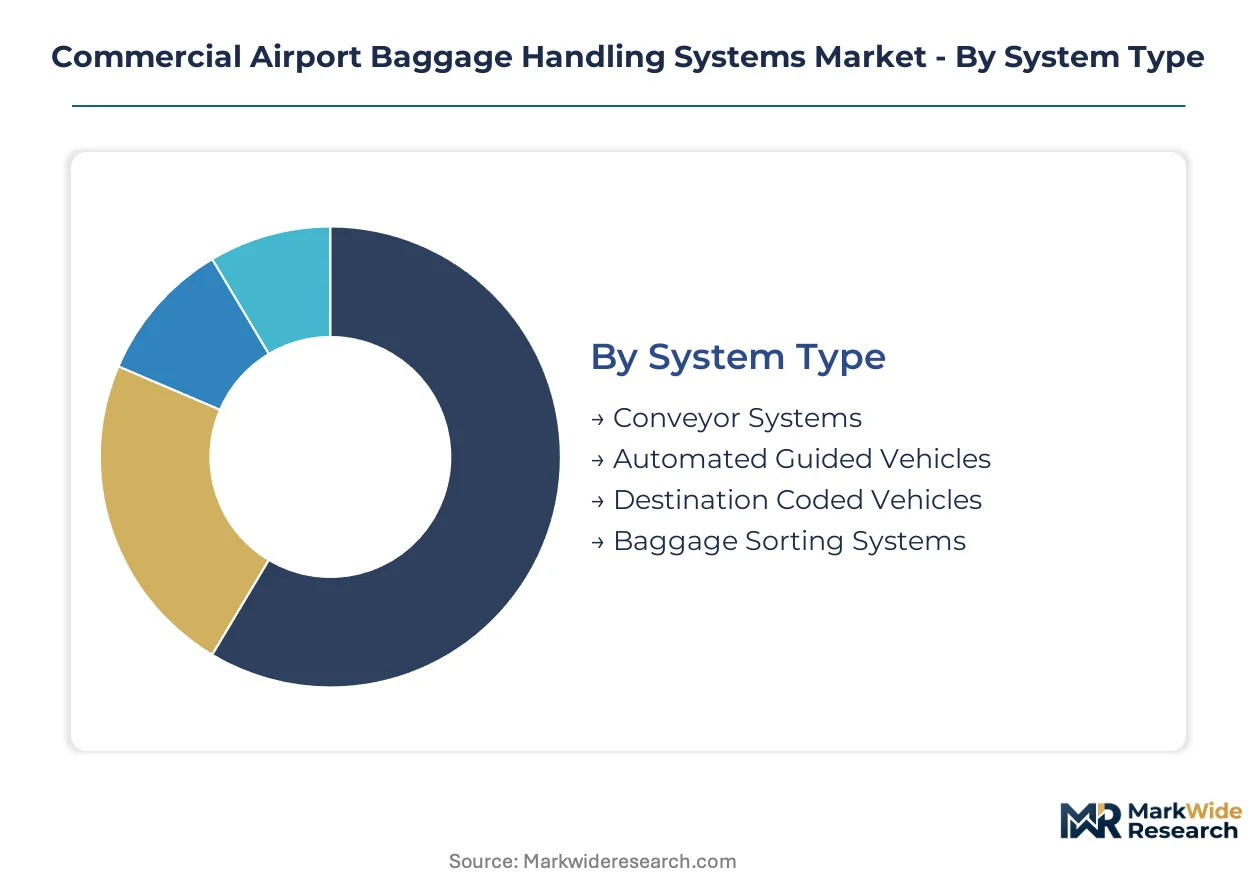
Baggage handling procurement splits across four structural dimensions that determine vendor qualification paths and margin profiles. System architecture choices lock airports into decade-long replacement cycles, while technology selections shape interoperability with carrier tracking mandates.
System Type:
Upgrade cycles favor modular architectures that slot into existing terminal footprints without full reconstruction.
- Conveyor Systems:Belt and roller configurations form the installed base across mid-tier terminals, with refurbishment demand concentrated in North American secondary hubs facing FAA fire-safety compliance deadlines. Steel superstructure fabrication costs have pressured integrator margins on fixed-price contracts.
- Destination Coded Vehicles:Autonomous tote-based transport eliminates single points of mechanical failure present in tilt-tray sorters. Dubai International and Singapore Changi have specified DCV arrays for new concourse installations, with German mega-hubs bundling these into integrated procurement packages.
- Automated Guided Vehicles:Mobile robotics enable flexible sortation density without fixed infrastructure expansion.
- Baggage Sorting Systems:Tilt-tray and cross-belt configurations remain prevalent at legacy installations.
Conveyor systems sit at the top of the volume ranking, with destination coded vehicles climbing the fastest.
End User:
Procurement authority fragmentation creates distinct competitive arenas with divergent technical specifications and contract structures.
- Airports:Terminal operators control capital budgets for greenfield and expansion projects, with German hub authorities bundling high-throughput automated sortation into integrated packages. EU Green Deal embodied carbon accounting now factors into tender scoring alongside throughput metrics.
- Ground Handling Companies:Swissport and dnata specify item-level baggage visibility as contractual requirements, pulling investment into sensor-integrated handling networks at their managed facilities.
- Airlines:Major carriers influence technology selection through baggage tracking mandate compliance.
- Security Agencies:Screening integration requirements shape conveyor routing specifications.
Airports dominate capital deployment, with ground handling companies gaining procurement influence fastest.
Technology:
Technology selection determines interoperability with carrier networks and regulatory tracking mandates.
- RFID Tracking:Item-level radio frequency identification delivers real-time location accuracy required by IATA Resolution 753 compliance. Major carriers now specify RFID-enabled handling infrastructure as a baseline contractual requirement at hub airports.
- Automated Systems:Robotic sortation and autonomous vehicle integration represent the steepest expansion trajectory as airports replace legacy belt configurations. Indian greenfield developments at Noida International and Navi Mumbai are specifying full automation from commissioning.
- Barcode Scanning:Optical character recognition remains cost-effective for low-volume terminals.
- IoT Solutions:Sensor networks enable predictive maintenance contracts extending vendor revenue streams.
RFID tracking commands the largest installed base, while automated systems expand most quickly.
Capacity:
Throughput tier determines equipment specification, vendor qualification, and service contract structure.
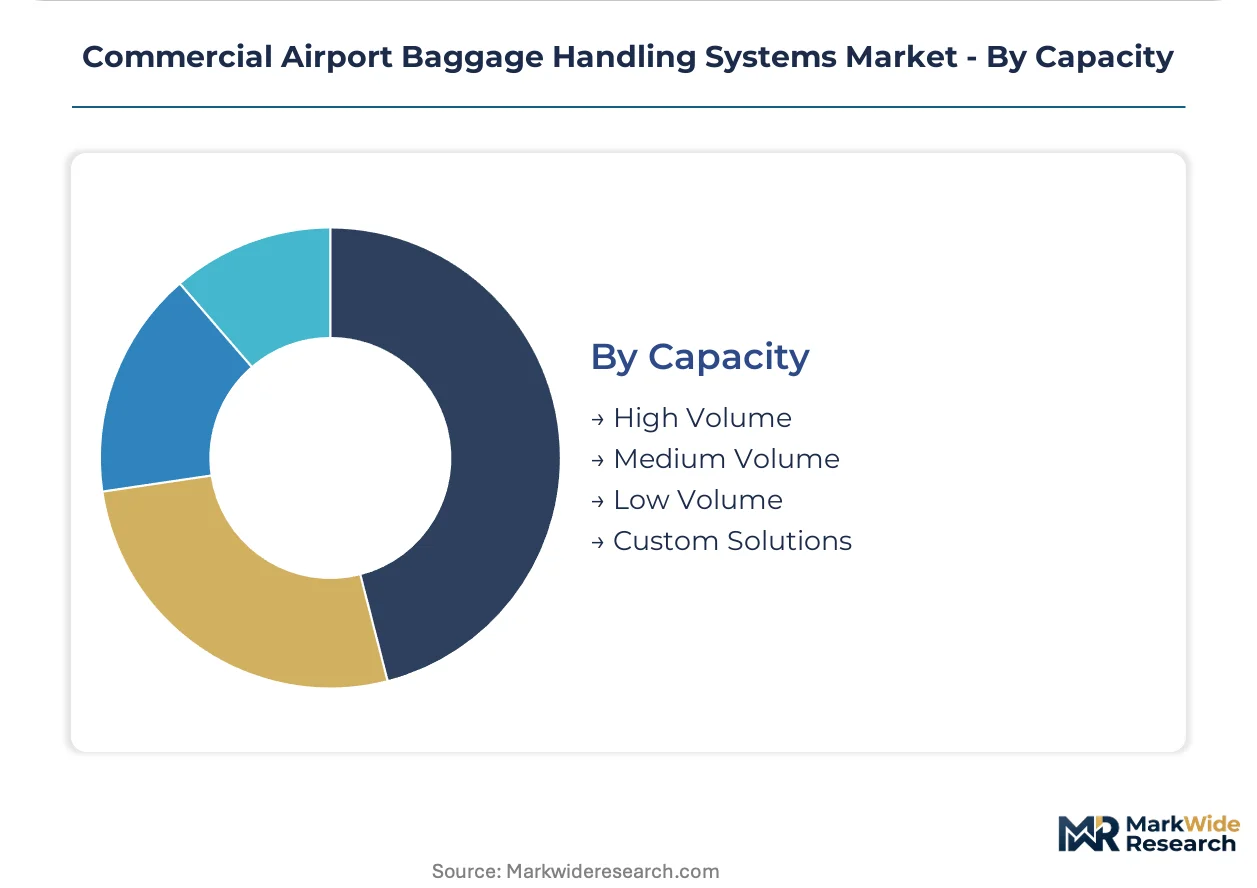
- High Volume:Systems engineered for throughput rates exceeding 10,000 bags per hour require custom conveyor engineering and precision drive motors sourced predominantly from German and Japanese suppliers. Frankfurt and Munich terminal redevelopments concentrate near-term order flow in this tier.
- Medium Volume:Standardized configurations serve secondary hubs with 3,000-8,000 bag hourly capacity requirements.
- Low Volume:Regional airports prioritize cost-efficient belt systems with minimal automation.
- Custom Solutions:Bespoke engineering addresses unique terminal geometries or peak surge requirements.
High volume solutions generate the largest revenue pool, with custom solutions gaining share fastest among retrofit projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial airport baggage handling systems trace their industrial lineage to German engineering clusters that pioneered mechanized conveyor networks in the 1970s. Frankfurt and Munich terminals became the proving grounds for automated sortation at scale. Today procurement concentrates at mega-hubs undergoing integrated redevelopment.
Germany
Frankfurt and Munich terminal redevelopments are bundling high-throughput automated sortation into integrated procurement packages. The EU F-Gas Regulation mandates refrigerant phaseouts in motorized drive systems, forcing equipment refresh cycles at major hubs. Bavaria's industrial automation corridor supplies precision drive motors and high-speed diverters to these flagship projects.
United States
The FAA mandates specific fire-safety and accessibility standards that are accelerating replacement demand at secondary hubs previously deferring capital investment. Infrastructure grant programs tied to terminal improvement bonds subsidize compliant system upgrades. Dallas-Fort Worth and Atlanta Hartsfield-Jackson anchor the largest retrofit pipelines.
India
Noida International and Navi Mumbai greenfield developments are specifying fully automated baggage handling from commissioning, bypassing legacy migration entirely. The country's national aviation regulator aligns with international certification protocols for new airport infrastructure. Maharashtra and Gujarat state aviation clusters concentrate these greenfield engineering contracts.
United Arab Emirates
Dubai International has specified destination-coded vehicle arrays for new concourse installations, eliminating single points of mechanical failure present in tilt-tray sorters. The national civil aviation authority enforces interoperability standards for automated ground handling systems. Dubai's aviation free zone clusters ground handling operators demanding item-level baggage visibility.
Singapore
Changi Airport's terminal expansions are integrating autonomous mobile robotics to compress capital deployment timelines and enable incremental capacity scaling. The national standards body coordinates with IATA tracking mandate compliance for sensor-integrated networks. The city-state's logistics engineering hub serves as a technology demonstration platform for Southeast Asian airport operators.
Commercial Airport Baggage Handling Systems Market Competitive Environment
Premium-margin players sit above commodity-margin players across the automation-integration spectrum, with tiered positioning determined by pre-integrated platform portfolios versus component supply. The vendor base spans three strategic archetypes: Asian manufacturing-scale integrators, European specialized conveyor engineers, and diversified industrial conglomerates with mobility divisions. Consolidation pressure concentrates around M&A targeting predictive maintenance capabilities and strategic partnerships bundling long-term service contracts with initial hardware procurement.
Within the European specialized engineering tier, BEUMER Group GmbH & Co. KG and Vanderlande Industries B.V. occupy positions anchored in continental hub installations. Daifuku Co., Ltd. represents the Asian manufacturing-scale archetype. These three exemplify how geographic origin and corporate structure shape competitive positioning without dictating specific strategic moves.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| Fives Group |
| BEUMER Group GmbH & Co. KG |
| Dematic GmbH |
| TGW Logistics Group GmbH |
| Vanderlande Industries B.V. |
| Honeywell International Inc. |
| Alstef Group |
| Siemens Mobility GmbH |
| Others |
Value Chain & Pricing Dynamics
Steel and aluminum commodity indices on the London Metal Exchange cascade directly through conveyor superstructure fabrication into three distinct pricing tiers for baggage handling systems. German hub operators absorb premium engineering costs for high-throughput automated sortation, while North American secondary airports face compressed margins on fixed-price refurbishment contracts.
Pricing Analysis
Project-based contracting with modular subsystem bundling separates integrated platform providers from component suppliers. Price differentiation hinges on CE marking certification tiers and after-sales service contract duration. Pricing pressure intensifies in the conveyor systems tier due to steel input volatility squeezing integrator margins. Regional airports exhibit highest price sensitivity, whereas German mega-hub authorities prioritize throughput reliability over unit cost.
Supply Chain Analysis
Mechatronics engineering talent scarcity in Germany and Japan constrains precision drive motor production capacity for high-volume installations. Component sourcing draws from German industrial automation corridors for diverters and Japanese suppliers for servo controls. Single-source vulnerability concentrates in specialized high-speed diverter manufacturing. Distribution runs through airport authority procurement departments with multi-year tender cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial airport baggage handling systems constitute a late-cycle quality market where EU Green Deal embodied carbon accounting is elevating procurement specifications toward verified environmental product declarations.
For Market Incumbents: Lock in long-term service contracts unbundled from initial hardware procurement to capture recurring revenue streams. Deepen backward integration into precision drive motor production to offset single-source vulnerability from German and Japanese suppliers. Prioritize predictive maintenance capability acquisition to defend against specialized aftermarket providers. For New Entrants and Emerging Players: Mid-tier North American secondary airports facing FAA fire-safety compliance deadlines represent an underserved buyer archetype with subsidized grant funding. Target retrofit integration services for legacy belt infrastructure replacement where incumbent OEMs lack flexible deployment capacity. Lead with AI-powered predictive maintenance offerings to bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where predictive maintenance software capabilities remain fragmented across specialized providers. Frame long-term viability around vendors with verified supply chain carbon disclosures qualifying for EU tender scoring. Monitor IATA Resolution 753 compliance adoption rates as the inflection signal for RFID-integrated infrastructure replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drive Motors | Captive supply of precision motors from Bavaria's automation corridor reduces single-source vulnerability. |
| Predictive Maintenance Platform Acquisition | Machine learning analytics layered onto sensor networks extends vendor revenue beyond hardware installation. |
| CE Marking Certification Investment | EASA alignment protocols shape market access for European airport redevelopment programs. |
| RFID Tracking Infrastructure Partnership | Major carriers specify item-level baggage visibility as contractual requirement at hub airports. |
| Green Manufacturing Transition | Environmental product declarations qualify vendors for EU Green Deal tender scoring. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged airport procurement directors, ground handling operations managers, conveyor system integrators, and regulatory compliance officers across major hub jurisdictions. Secondary validation drew from FAA airworthiness directives, EASA certification databases, EU F-Gas Regulation implementation reports, and IATA baggage tracking mandate documentation. Bottom-up installation data triangulated against top-down capital expenditure flows from airport authority bond disclosures.
Historical reference periods anchored volume and value projections across the analysis window. The modeling framework segmented by system architecture, technology integration level, throughput capacity tier, and end-user procurement authority. CAGRs derived from regression analysis against airport passenger traffic forecasts and regulatory compliance deadline clustering. Forecast inputs incorporated commodity metal price trajectory assumptions and automation certification threshold evolution.
Inputs from airport authority procurement databases and ground handler facility records were available through the study window; gaps in privately held maintenance contract terms introduce uncertainty bands around aftermarket revenue projections. Forecasts reflect documented assumptions regarding regulatory phaseout timelines and greenfield airport commissioning schedules. Material deviation in EU F-Gas Regulation enforcement intensity or FAA grant program appropriation levels warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Smart Airport 4.0 Market
Airport Technologies
Global Remote Towers Market
Airport Technologies
Europe Smart Airport Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
Airport Airside Service Market
Airport Technologies
Airport Baggage Conveyor System Market
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
Airport Interactive Kiosk Market
Airport Technologies
Airport Runway Foreign Object Debris (FOD) Detection Systems Market
Airport Technologies
Air Traffic Smart Tower Solutions Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Helideck Monitoring System Market
Airport Technologies
North America Smart Airport Market