
 Middle-East and Africa Airport Baggage Handling Systems Market | 2026-2036
Middle-East and Africa Airport Baggage Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Airport Baggage Handling Systems Market Foresight
Ground handling companies are rebalancing their capital allocation toward fully automated baggage handling infrastructure as passenger throughput recovers across Gulf hubs. BEUMER Group leverages its conveyor systems specialization to anchor major retrofit contracts in Saudi Arabia. Vanderlande Industries competes through its sortation technology leadership, while Siemens Logistics sustains geographic dominance with integrated control software for greenfield terminals.
Airport baggage handling systems comprise mechanized conveyor networks, automated sortation modules, and tracking interfaces designed to transport luggage between check-in, screening, and aircraft loading points at throughput rates exceeding 4,000 bags per hour. These systems integrate RFID tags, barcode scanners, and programmable logic controllers to minimize mishandled baggage and reduce aircraft turnaround times. Conveyor systems occupy the largest installed base across Middle-East and Africa airports, though sortation systems generate the fastest replacement cycle as legacy tilt-tray designs reach end-of-life. Automated systems command premium pricing over manual and barcode-based alternatives, with margin pools concentrating in integration services that tie hardware to airport operational databases.
UAE's General Civil Aviation Authority and Saudi Arabia's General Authority of Civil Aviation enforce baggage screening mandates that align with ICAO Annex 17 security standards, directly shaping demand for explosives detection-integrated handling lines. South Africa's Civil Aviation Authority applies SABS technical specifications for system reliability, creating compliance barriers for uncertified equipment suppliers. Stakeholders must monitor how IATA Resolution 753 baggage tracking mandates reshape RFID technology procurement timelines across African flag carriers with limited legacy infrastructure.
Market Dynamics
Greenfield airport construction across the Gulf Cooperation Council is rebalancing procurement toward automated sortation and integrated handling platforms, compressing replacement cycles for legacy tilt-tray systems.
Growth Catalysts
- ICAO Annex 17 security mandates:UAE's General Civil Aviation Authority and Saudi Arabia's General Authority of Civil Aviation enforce explosives detection-integrated handling lines, forcing wholesale infrastructure upgrades at major hubs.
- Conveyor system specialization:Retrofit contracts in Saudi Arabia anchor demand for mechanized networks capable of throughput rates exceeding 4,000 bags per hour.
- IATA Resolution 753 baggage tracking:The resolution reshapes RFID technology procurement timelines across African flag carriers with limited legacy infrastructure, creating immediate specification requirements.
Market Restraints
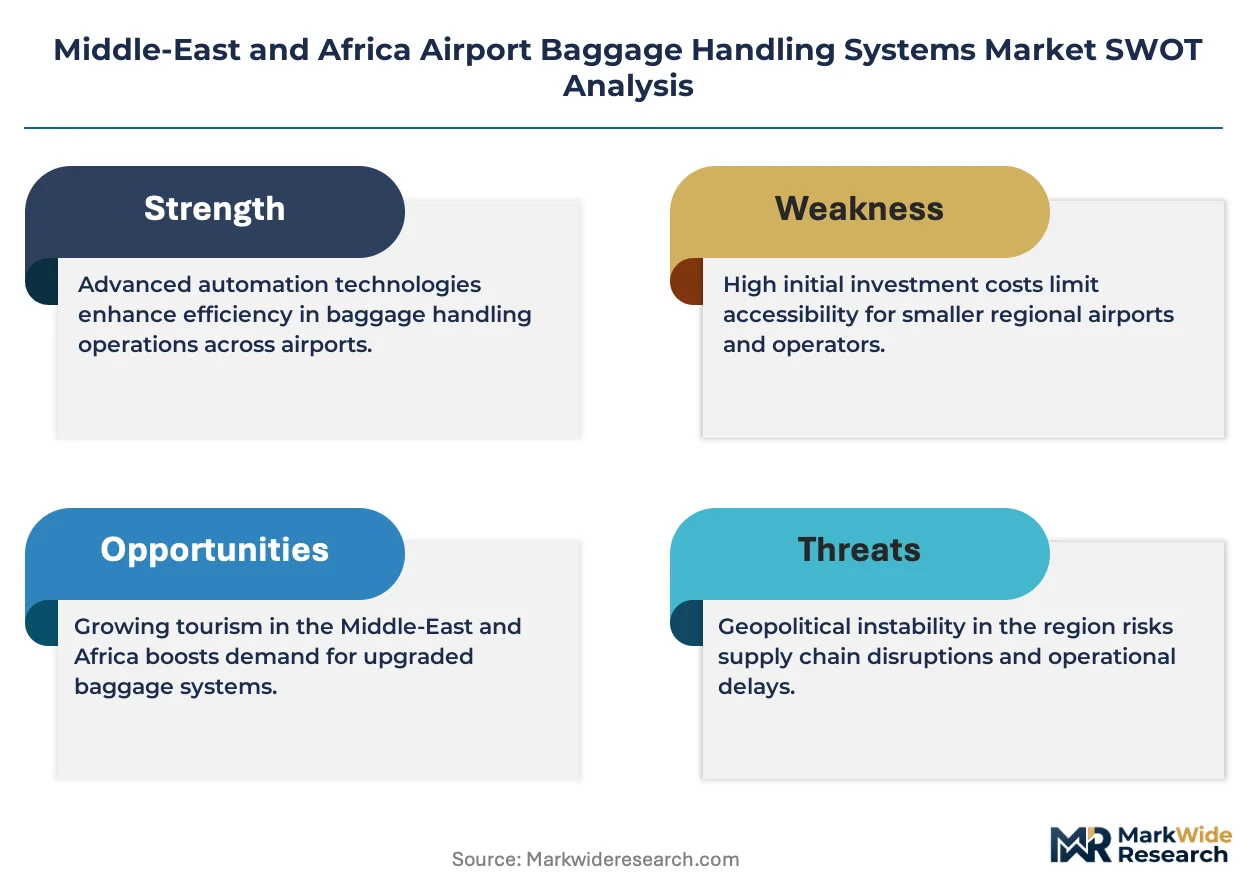
- Capital intensity of automated platforms:Premium pricing for automated systems over manual and barcode-based alternatives squeezes margin pools for ground handling operators with constrained balance sheets.
- Compliance barriers from SABS technical specifications:South Africa's Civil Aviation Authority applies reliability standards that exclude uncertified equipment suppliers from tender participation.
- Integration complexity with airport operational databases:Legacy terminal management systems at older African airports resist seamless connection to modern programmable logic controllers.
Strategic Opportunities
- Underpenetrated East African hubs:Addis Ababa Bole International and Nairobi Jomo Kenyatta International lack automated sortation depth, creating first-mover advantage for integrated platform vendors.
- RFID-barcode convergence:Hybrid tracking architectures bridge capability gaps for carriers transitioning from manual processes to full automation without stranded asset risk.
- After-sales service unbundling:Maintenance contracts for conveyor networks and sortation modules separate from initial hardware sales, generating recurring revenue streams.
Industry Challenges
- Skill scarcity in PLC programming:Airport authorities struggle to recruit technicians capable of troubleshooting programmable logic controllers across multi-vendor environments.
- Capex deployment timelines:Greenfield terminals in the UAE and Saudi Arabia demand synchronized installation of screening and handling lines, stretching contractor resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Airport Baggage Handling Systems Market |
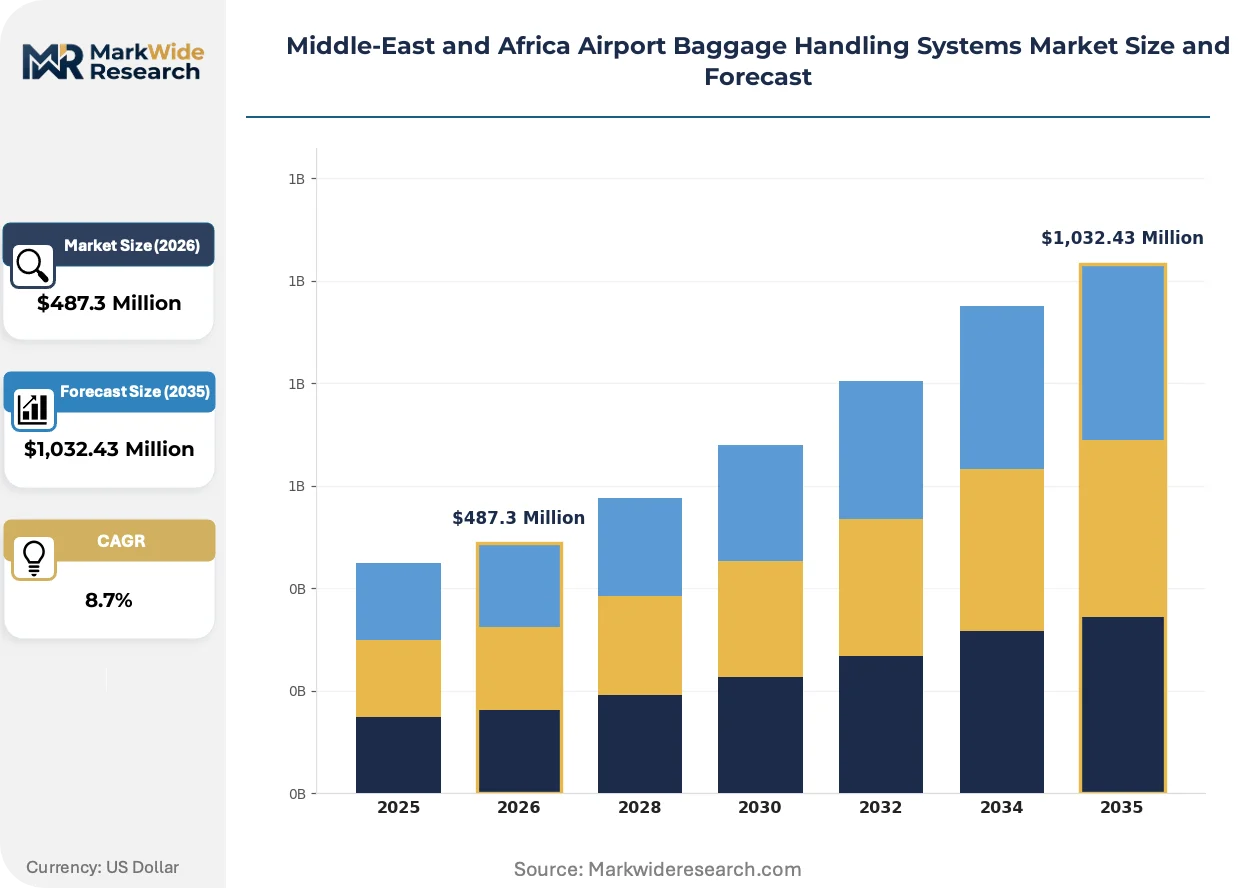
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyor Systems, Sortation Systems, Handling Equipment, Self-Service Kiosks End User: Airports, Airlines, Ground Handling Companies, Logistics Providers Technology: Automated Systems, RFID Tracking, Barcode Systems, Manual Systems Service Type: Maintenance Services, Consulting Services, Integration Services, Training Services |
| Companies Covered | BEUMER Group, Vanderlande Industries, Siemens Logistics, SITA, Alstef Group, Daifuku Co Ltd, Smiths Group, Pteris Global Limited, ADB SAFEGATE, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Airport Baggage Handling Systems Market Shifts & Advancements
Automated sortation modules are displacing legacy tilt-tray designs as Gulf hubs prioritize throughput density over incremental retrofit economics.
Independent carrier systems are absorbing baggage flow management from centralized airport authority control. Low-cost carriers at Dubai International and Abu Dhabi Zayed International deploy dedicated sortation footprints to protect on-time performance metrics. This fragmentation is absorbing capital that previously consolidated under single-terminal procurement budgets.
ICAO Annex 17 security standards are tightening explosives detection integration mandates across Middle-East and African airports. The UAE's General Civil Aviation Authority requires inline screening for all checked baggage, forcing hardware vendors to certify combined conveyor-detection units. Saudi Arabia's General Authority of Civil Aviation is accelerating parallel adoption timelines at secondary hubs.
Buyer concentration among Gulf sovereign wealth-backed airport operators is compressing vendor negotiation cycles. Dubai Airports and Abu Dhabi Airports negotiate multi-year framework agreements that bundle conveyor networks, sortation modules, and maintenance services. This aggregation is visible across UAE greenfield projects where single-source procurement dominates over competitive tendering.
Middle-East and Africa Airport Baggage Handling Systems Market Segmentation
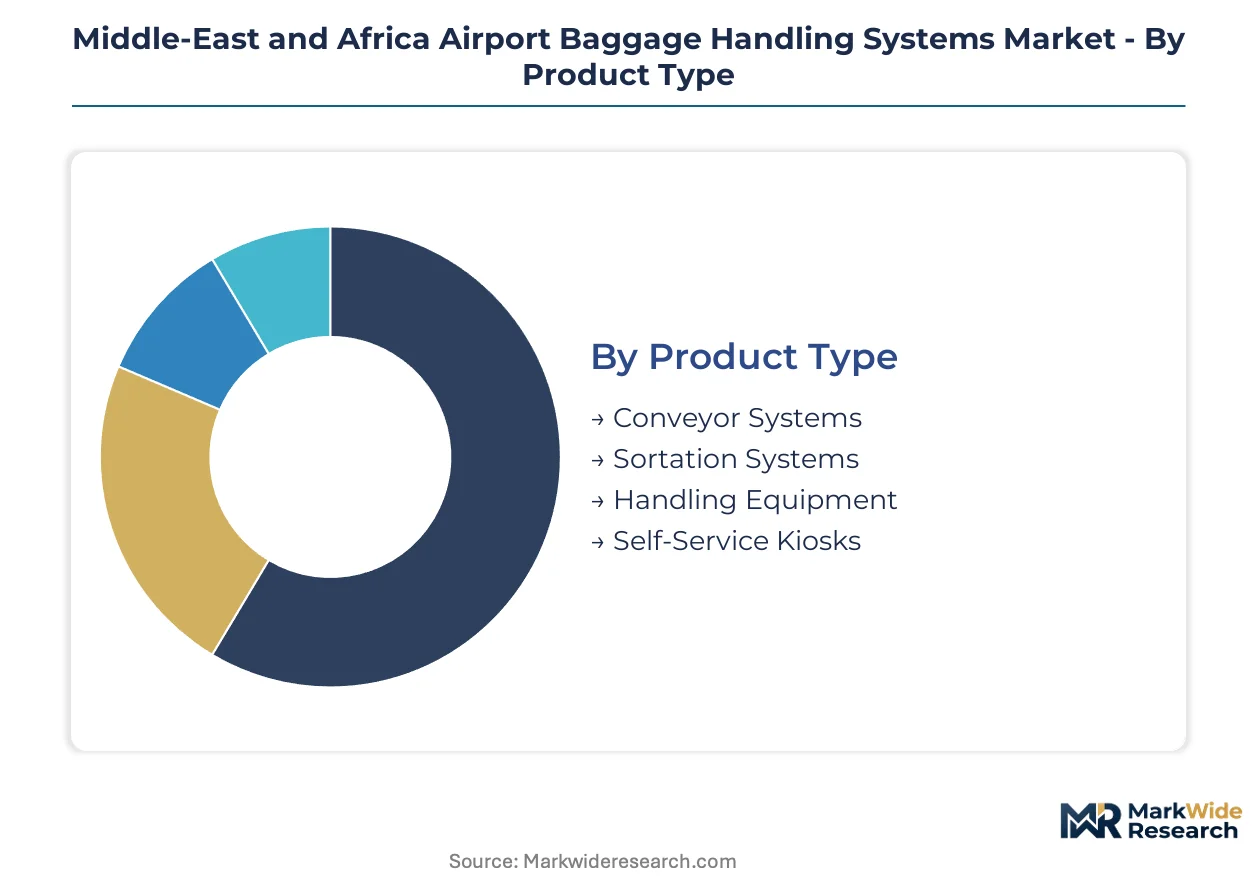
Segmentation in Middle-East and Africa airport baggage handling systems reveals how procurement decisions split between greenfield automation mandates and legacy retrofit constraints. Equipment buyers prioritize integration depth over standalone hardware, while service contracts increasingly unbundle from initial capital expenditure.
Product Type:
Customization intensity varies sharply across this category, from standardized conveyor modules to project-specific sortation configurations engineered for terminal footprints.
- Conveyor Systems:Mechanized belt and roller networks transport luggage between check-in, screening, and loading points at throughput rates exceeding 4,000 bags per hour. Demand concentrates in Saudi Arabia's retrofit market, where Riyadh and Jeddah terminals replace aging tilt-tray infrastructure under General Authority of Civil Aviation modernization directives.
- Sortation Systems:Automated tilt-tray and cross-belt modules direct bags to designated aircraft loading positions through programmable logic controllers. Procurement accelerates across UAE greenfield projects, with Dubai International and Abu Dhabi Zayed International specifying integrated sortation-screening lines to comply with ICAO Annex 17 explosives detection mandates.
- Handling Equipment:Mobile belt loaders, baggage carts, and container dollies supplement fixed infrastructure for apron operations.
- Self-Service Kiosks:Passenger-facing bag drop terminals reduce counter staffing requirements at high-volume terminals.
Most installed capacity flows through Conveyor Systems. Expansion is steepest in Sortation Systems.
End User:
Procurement authority in this category tracks the operational split between airport authority capital budgets and carrier-controlled ground handling assets.
- Airports:Terminal authorities specify integrated handling platforms combining conveyor networks, screening equipment, and operational databases. Investment concentrates in UAE sovereign wealth-backed operators, where Dubai Airports and Abu Dhabi Airports bundle multi-year framework agreements covering hardware and maintenance services.
- Airlines:Flag carriers and low-cost operators deploy dedicated sortation footprints to protect on-time performance metrics. Independent carrier systems absorb baggage flow management from centralized control at Dubai International and Abu Dhabi Zayed International, fragmenting capital pools that previously consolidated under single-terminal budgets.
- Ground Handling Companies:Third-party operators procure mechanized equipment under service contracts with airport authorities and airlines.
- Logistics Providers:Cargo-focused handlers invest in specialized handling lines for express freight and mail operations.
Capital deployment runs deepest through Airports. Carrier-controlled procurement is climbing the fastest.
Technology:
Technology selection in this category reflects a maturity gradient from legacy barcode infrastructure toward RFID-automation convergence.
- Automated Systems:Programmable logic controllers, robotic transfer mechanisms, and centralized control software minimize manual intervention. Demand concentrates at Gulf Cooperation Council greenfield terminals, where synchronized installation of screening and handling lines stretches contractor resource allocation across simultaneous projects.
- RFID Tracking:Radio-frequency identification tags enable real-time baggage location monitoring compliant with IATA Resolution 753. Procurement timelines accelerate across African flag carriers with limited legacy infrastructure, creating immediate specification requirements for ground handling operators serving Addis Ababa and Nairobi hubs.
- Barcode Systems:Optical scanning infrastructure persists at older terminals with constrained capital budgets.
- Manual Systems:Human-operated sorting and transport retains presence at secondary African airports with low passenger throughput.
Barcode Systems retain the largest installed base. RFID Tracking is gaining share fastest.
Service Type:
Margin extraction in this category shifts from hardware markups toward recurring revenue streams tied to operational continuity.
- Maintenance Services:Preventive and corrective contracts for conveyor networks, sortation modules, and control systems ensure terminal uptime. Demand concentrates in UAE framework agreements, where Dubai Airports and Abu Dhabi Airports unbundle multi-year service commitments from initial equipment procurement.
- Integration Services:Database connectivity, control software deployment, and vendor interoperability management tie hardware to airport operational systems. Procurement accelerates at African hubs struggling with legacy terminal management systems resistant to seamless PLC connection.
- Consulting Services:Capacity planning, workflow optimization, and compliance advisory support greenfield design and retrofit planning.
- Training Services:Technician certification and operator instruction address skill scarcity in PLC programming across multi-vendor environments.
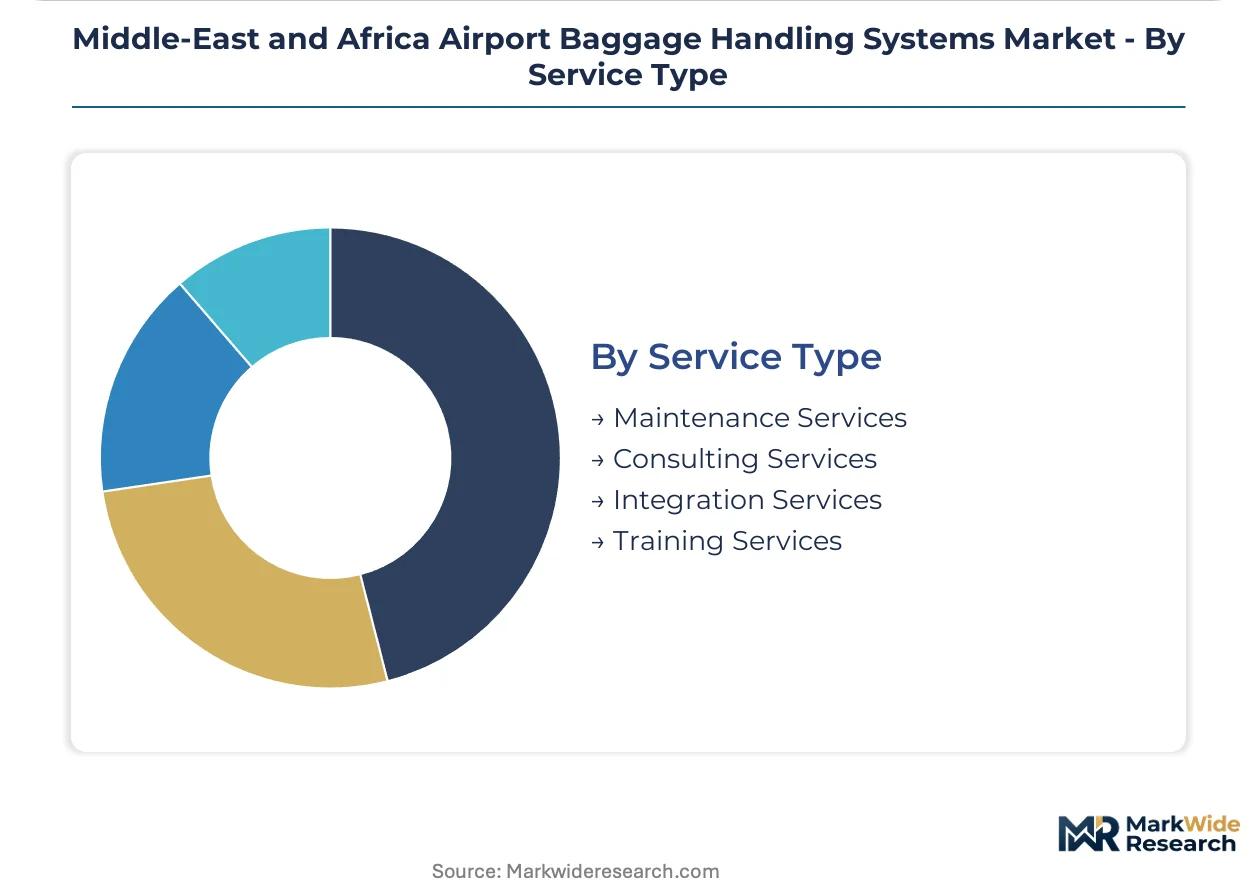
Revenue concentration sits with Maintenance Services. Integration Services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing procurement geography across the Middle-East and Africa as Gulf sovereign wealth funds absorb compliance costs that African operators cannot shoulder, concentrating automated system deployment in high-capacity hubs while legacy infrastructure persists elsewhere.
United Arab Emirates
Dubai International and Abu Dhabi Zayed International anchor regional capacity expansion with synchronized greenfield automation mandates. The General Civil Aviation Authority enforces ICAO Annex 17 explosives detection integration for all checked baggage, forcing hardware certification at combined conveyor-detection units. Dubai Airports bundles multi-year framework agreements that consolidate vendor relationships across both emirates.
Saudi Arabia
Riyadh and Jeddah terminals drive retrofit demand under General Authority of Civil Aviation modernization directives targeting legacy tilt-tray replacement. The authority's baggage screening mandates align with ICAO security standards while compressing replacement cycles for mechanized networks. NEOM Northwest and secondary hubs accelerate parallel adoption timelines as sovereign investment redirects toward integrated handling platforms.
South Africa
O.R. Tambo International and Cape Town International maintain the continent's most mature installed base despite constrained capital deployment. The Civil Aviation Authority applies SABS technical specifications for system reliability, creating compliance barriers that exclude uncertified equipment suppliers from tender participation. Johannesburg-Pretoria corridor concentrates maintenance demand as legacy PLC systems resist seamless database integration.
Ethiopia
Addis Ababa Bole International lacks automated sortation depth relative to Gulf benchmarks, creating first-mover positioning for integrated platform vendors. The Ethiopian Civil Aviation Authority is aligning with IATA Resolution 753 baggage tracking timelines, accelerating RFID specification requirements for ground handling operators. Flag carrier procurement absorbs capital that previously fragmented across multiple African hubs.
Kenya
Nairobi Jomo Kenyatta International represents East Africa's secondary automation frontier with limited legacy infrastructure complicating technology leapfrogging. The Kenya Civil Aviation Authority monitors ICAO Annex 17 adoption as regional security standards tighten. Mombasa secondary hub and emerging cargo corridors concentrate demand for hybrid tracking architectures bridging manual processes toward full automation.
Middle-East and Africa Airport Baggage Handling Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with conveyor system specialists dominating retrofit procurement while integrated platform vendors capture greenfield mandates. Market structure concentrates around three tiers: Gulf-based sovereign wealth-backed operators negotiating multi-year framework agreements, European engineering conglomerates with airport logistics divisions, and Asian material handling specialists penetrating through price-competitive modular offerings. Dominant competitive moves include bundling maintenance services into initial hardware contracts and forming strategic partnerships with explosives detection equipment vendors to satisfy integrated screening mandates.
Among European engineering conglomerates with dedicated airport logistics divisions, BEUMER Group, Vanderlande Industries, and Siemens Logistics exemplify distinct archetype positioning. BEUMER Group represents conveyor system specialization anchoring major retrofit contracts. Vanderlande Industries occupies a position exemplifying sortation technology leadership. Siemens Logistics sits within the integrated control software tier sustaining geographic dominance through programmable logic controller deployment.
| Leading Market Players |
|---|
| BEUMER Group |
| Vanderlande Industries |
| Siemens Logistics |
| SITA |
| Alstef Group |
| Daifuku Co Ltd |
| Smiths Group |
| Pteris Global Limited |
| ADB SAFEGATE |
| Others |
Supply & Pricing Matrix
Horizontal integration into explosives detection equipment partnerships anchors supply positioning for vendors serving Gulf Cooperation Council greenfield terminals, compressing procurement cycles while elevating pricing power through bundled screening-handling offerings. Dubai Airports and Abu Dhabi Airports leverage this consolidation to negotiate multi-year framework agreements that lock in service premiums alongside hardware margins.
Pricing Analysis
Direct-to-airport operator discounts dominate channel economics, with framework agreements eliminating distributor markups for sovereign wealth-backed buyers in the UAE and Saudi Arabia. Three-tier pricing structure across premium automated systems, mid-tier retrofit configurations, and economy manual alternatives differentiates offerings, with certification to ICAO Annex 17 standards commanding substantial premiums. Cost compression in mid-tier retrofit configurations is intensifying because legacy tilt-tray replacement cycles compress under General Authority of Civil Aviation mandates. Ground handling companies exhibit highest price sensitivity due to constrained balance sheets, while airport authorities with sovereign backing demonstrate lowest sensitivity.
Supply Chain Analysis
Certification gating through SABS technical specifications in South Africa and GCAA explosives detection mandates in the UAE creates qualification barriers that filter supplier pools. Manufacturing concentration rests on Germany, the Netherlands, and Japan for precision sortation modules and programmable logic controllers. Steel alloys, industrial sensors, and specialized conveyor belting constitute critical input dependencies. Single-source vulnerability runs through European engineering conglomerates controlling integrated control software IP. Distribution runs through direct vendor-airport authority relationships with limited intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compounding from IATA Resolution 753 baggage tracking mandates creates sustained demand visibility for automation vendors across African flag carriers with limited legacy infrastructure.
For Market Incumbents: Deploy multi-year service bundling to deepen airport authority relationships before competitive tendering opens. Lock in framework agreement renewals at Dubai Airports and Abu Dhabi Airports ahead of NEOM Northwest activation. Vertical integration into explosives detection certification protects margin pools against Asian modular specialists penetrating through price-competitive offerings. For New Entrants and Emerging Players: Begin with hybrid RFID-barcode tracking architectures targeting Addis Ababa Bole International and Nairobi Jomo Kenyatta International, where automation depth remains underdeveloped relative to Gulf benchmarks. Carrier-controlled procurement at Dubai International and Abu Dhabi Zayed International fragments capital pools previously consolidated under single-terminal budgets, creating entry points for dedicated sortation footprints serving low-cost operators. For Investors and Strategic Acquirers: Roll-up economics work for regional maintenance service providers because after-sales contract unbundling from initial hardware sales generates recurring revenue streams with limited capital intensity. Target specialists with captive relationships at O.R. Tambo International and Cape Town International, where SABS compliance barriers sustain incumbent positioning. Monitor General Authority of Civil Aviation procurement timelines for NEOM and secondary Saudi hubs as inflection signal for greenfield automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Framework Agreement Consolidation | Dubai Airports bundles multi-year contracts across both emirates, compressing vendor negotiation cycles. |
| Explosives Detection Integration | GCAA mandates inline screening certification, forcing hardware vendors into combined conveyor-detection units. |
| RFID Technology Procurement | IATA Resolution 753 accelerates specification requirements across African flag carriers with limited legacy infrastructure. |
| After-Sales Service Unbundling | Maintenance contracts for conveyor networks separate from initial hardware sales, generating recurring revenue streams. |
| East African Hub Penetration | Addis Ababa and Nairobi lack automated sortation depth, creating first-mover advantage for integrated platform vendors. |
Research Methodology
Bottom-up airport authority and ground handling operator modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with airport procurement directors, ground handling operations managers, civil aviation authority regulators, and system integration engineers combined with secondary validation against IATA operational statistics, ICAO safety audit reports, GCAA regulatory filings, and General Authority of Civil Aviation modernization directives. Trade data from UAE and Saudi Arabian customs authorities supplemented vendor revenue disclosures.
Historical trendline analysis across installed base replacement cycles and greenfield project pipelines established baseline growth parameters. Segmentation modeling covered product type, end user category, technology tier, and service type dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from trajectory fitting against passenger throughput recovery patterns and sovereign investment deployment schedules. Forecast inputs incorporated PLC programming skill scarcity constraints and synchronized installation resource allocation across simultaneous Gulf projects.
Caveats apply where ICAO Annex 17 adoption timelines or IATA Resolution 753 enforcement intensity could materially shift the outlook for African automation penetration. Forecasts reflect assumptions regarding sovereign wealth fund capital availability and contractor capacity constraints across overlapping greenfield mandates. A model refresh is warranted upon material change in General Authority of Civil Aviation procurement acceleration or Ethiopian Civil Aviation Authority tracking compliance deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Air Traffic Smart Tower Solutions Market
Airport Technologies
Smart Airport Market
Airport Technologies
Europe Smart Airport Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
North America Smart Airport Market
Airport Technologies
Global Remote Towers Market
Airport Technologies
Airport Airside Service Market
Airport Technologies
Smart Airport 4.0 Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
Commercial Airport Baggage Handling Systems Market
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
Middle-East and Africa Airport Ground Handling Systems Market