
 Airport RFID System Market | 2026-2036
Airport RFID System Market Size, Share, and Industry Trends Forecast 2026-2036
Airport RFID System Market Analysis
Market Context with Strategic Players
RFID systems engineering talent is collapsing across aviation technology vendors, constraining deployment timelines for next-generation baggage tracking infrastructure. Impinj leverages its RAIN RFID chip portfolio to anchor hardware supply for airport-grade tag programs. Zebra Technologies competes through end-to-end visibility platforms that integrate mobile computing with fixed RFID readers. SITA specializes in aviation-specific middleware that connects carrier operations with airport ground systems.
Technical Definition and Structural Segments
Airport RFID systems comprise radio-frequency identification hardware and software operating across UHF and microwave bands, typically encoding 96-bit to 256-bit EPC identifiers for real-time object tracking at read ranges from one centimeter to fifteen meters. These systems automate baggage sortation, ground support equipment location, and access control verification across terminal and airside zones. Passive RFID tags dominate unit volume in luggage tracking applications due to minimal per-unit cost, while active RFID commands premium positioning in high-value asset monitoring where extended read range and sensor integration justify elevated expenditure. Software and middleware segments capture disproportionate margin pools as airports prioritize system interoperability over standalone hardware procurement.
Regulatory Framework and Outlook
IATA Resolution 753, FAA airworthiness directives on ground equipment traceability, and EU GDPR provisions governing passenger data in tracking databases collectively shape product architecture and compliance investment. EASA certification requirements for electronic equipment deployed in safety-critical airport zones further filter vendor qualification. Stakeholders must monitor evolving interoperability standards between carrier-specific and airport-operated RFID networks as single-source dependencies create operational fragility.
Market Dynamics
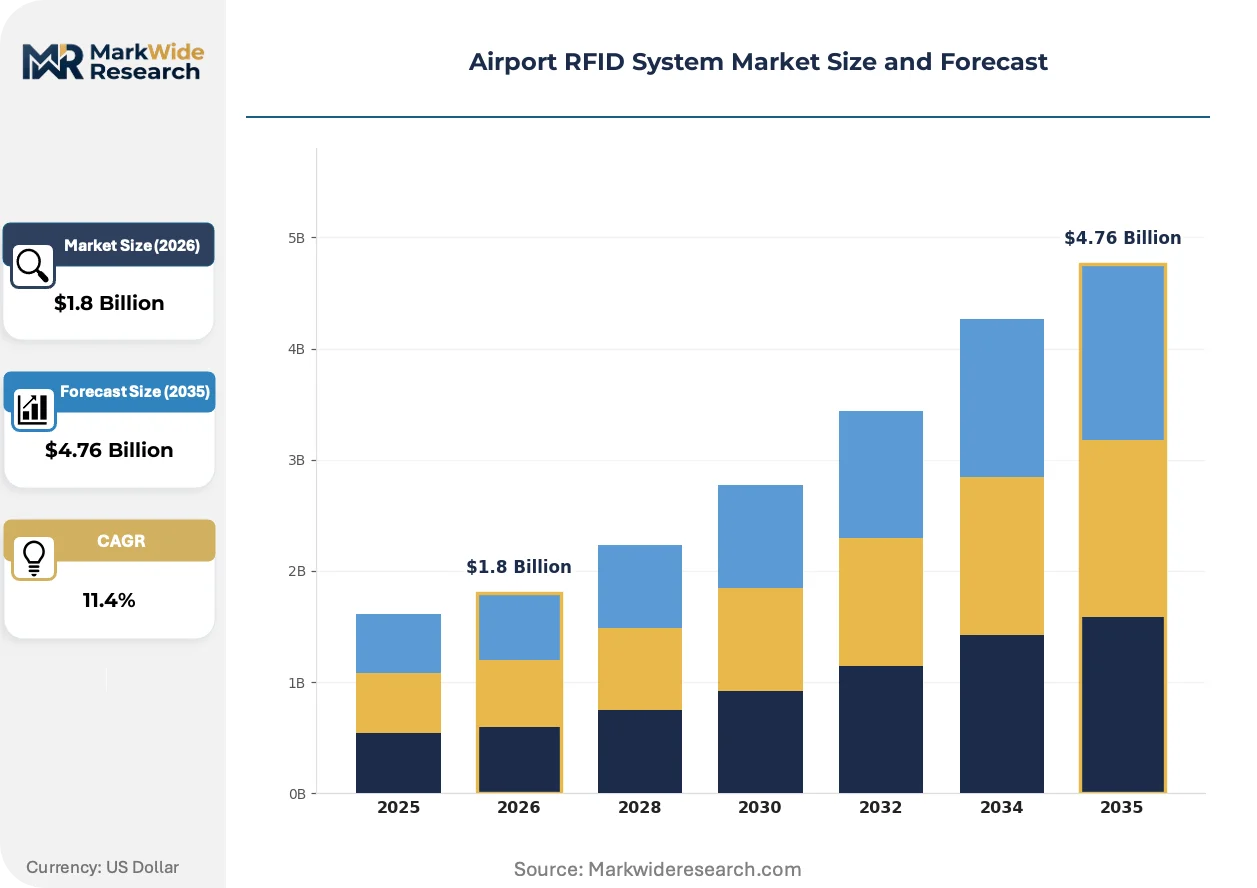
IATA Resolution 753's baggage tracking mandate is compressing carrier procurement cycles while simultaneously straining vendor engineering capacity, creating a structural bottleneck where compliance deadlines outpace deployment velocity across hub airports.
Growth Catalysts
- Resolution 753 Mandate:IATA's baggage tracking compliance requirement compels airlines to retrofit legacy infrastructure, generating sustained hardware and middleware demand across member carriers.
- Hub Modernization:Major airport expansions in the United States, China, and Germany are embedding RFID-native baggage handling systems rather than retrofitting aging mechanical sortation.
- Sensor Convergence:Integration of temperature and shock sensors into active RFID tags is opening high-value cargo monitoring applications beyond standard luggage tracking.
Market Restraints
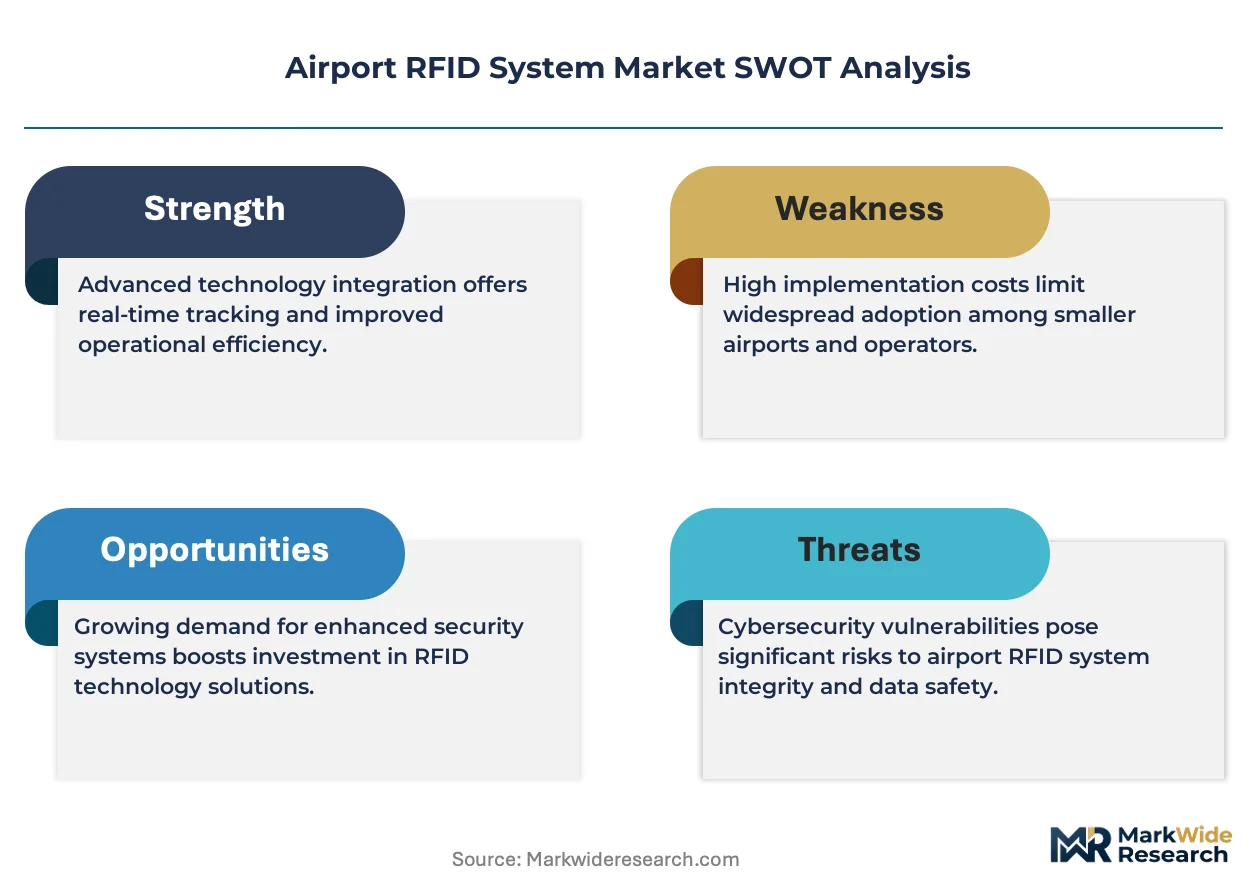
- Engineering Talent Scarcity:Aviation-grade RFID systems engineering expertise has contracted sharply, extending deployment timelines and inflating implementation costs for complex integrations.
- Passive Tag Margin Compression:UHF passive tags face commoditization pressure as Chinese manufacturers expand production capacity, squeezing hardware vendor profitability.
- EASA Certification Burden:European safety certification requirements for airside electronic equipment create multi-quarter approval delays that deter smaller vendors from market entry.
Strategic Opportunities
- India Airport Expansion:The country's greenfield airport construction under the UDAN regional connectivity scheme offers first-mover advantage for integrated RFID baggage system vendors.
- Ground Support Equipment Tracking:Untapped demand exists for active RFID deployment on tugs, dollies, and loaders where location visibility reduces aircraft turnaround delays.
- EU Green Deal Alignment:Carbon footprint tracking mandates for airport operations create demand for RFID-enabled asset lifecycle monitoring and fuel consumption verification systems.
Industry Challenges
- Middleware Integration Complexity:Carrier-specific operational databases rarely interoperate with airport ground handling systems, requiring costly custom API development for each deployment.
- RAIN RFID Certification Backlogs:GS1 EPCglobal compliance testing queues have lengthened substantially, delaying product launches for hardware vendors targeting 2025-2026 procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport RFID System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tags, Readers, Software, Middleware Application: Luggage Tracking, Personnel Tracking, Asset Management, Security Monitoring End User: Airports, Airlines, Ground Handlers, Security Agencies Technology: Active RFID, Passive RFID, Semi-passive RFID, NFC |
| Companies Covered | Impinj, Checkpoint Systems, SITA, Savi Technology, Avery Dennison, Zebra Technologies, NXP Semiconductors, GAO RFID, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport RFID System Market Emerging Trajectories
RFID technology stacks are fragmenting as airports demand edge computing capabilities at read points, shifting intelligence from centralized servers to distributed reader networks that process tag data locally.
Dual-frequency RFID tags combining UHF and NFC interfaces are supplanting single-protocol luggage tags at premium carriers, enabling both long-range automated sortation and passenger-facing mobile verification without infrastructure duplication. Lufthansa and Singapore Airlines have piloted these hybrid tags across select routes since 2023. The structural consequence is compressing middleware vendor margins as hardware absorbs functionality previously delivered through software layers.
FAA airworthiness directives on ground equipment traceability are mandating electronic records for all safety-critical assets operating within movement areas, forcing airports to deploy RFID-enabled maintenance logging systems that synchronize with carrier operational databases. This regulatory pressure is most acute at Category X airports in the United States where traffic density amplifies ground collision risks.
Airport procurement departments are consolidating vendor relationships from point-solution purchases to multi-year managed service agreements that bundle hardware, software, and ongoing tag supply. This behavioral shift is displacing traditional systems integrators who lack recurring revenue infrastructure. The transformation is most visible in Germany, where Fraport and Munich Airport have adopted outcome-based contracts tying vendor payments to baggage mishandling rate reductions.
Airport RFID System Market Segmentation
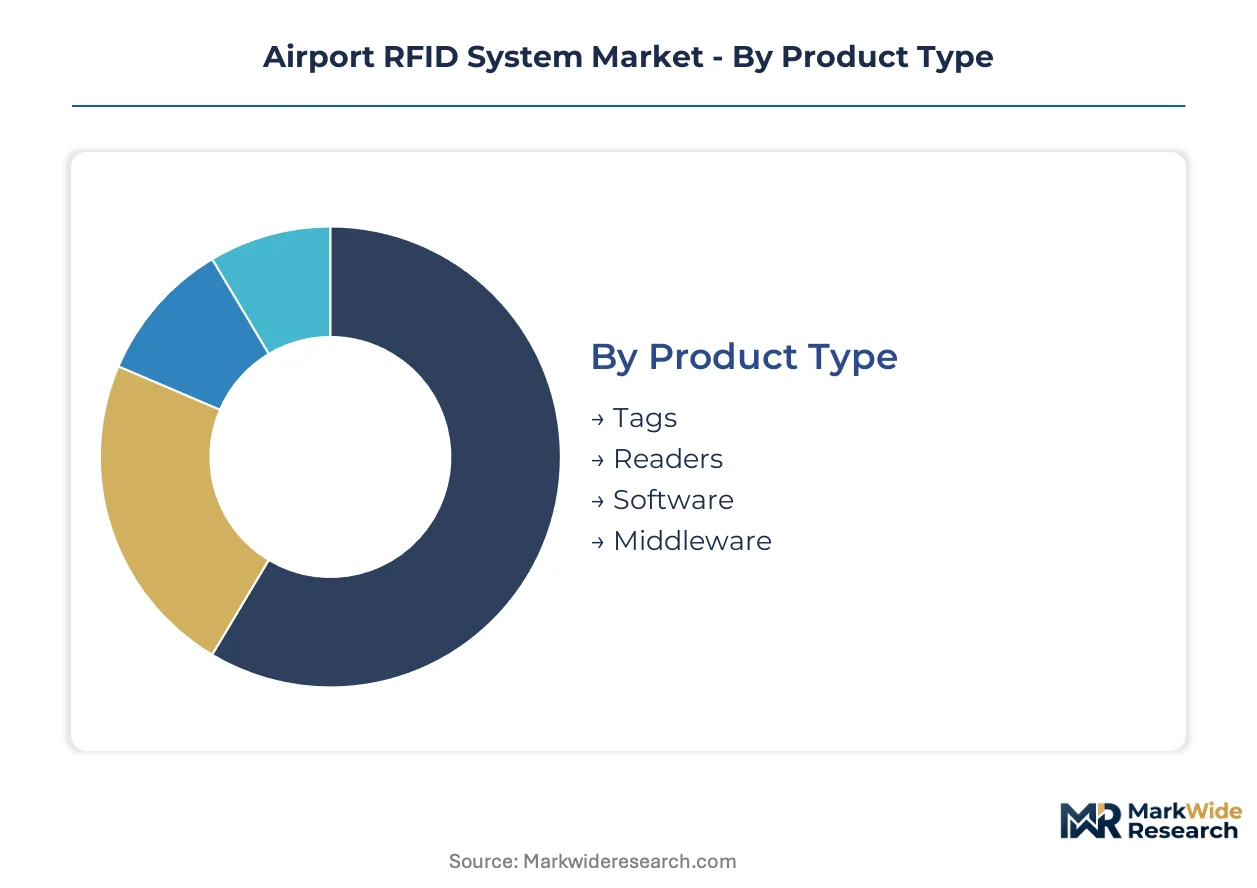
Segmentation in airport RFID systems reveals divergent margin structures across hardware and software layers. Procurement patterns differ sharply between carrier-mandated compliance spending and airport-led infrastructure modernization initiatives.
Product Type:
Software and middleware segments command disproportionate margin pools as airports prioritize system interoperability over standalone hardware procurement. Hardware vendors face commoditization pressure in high-volume tag production.
- Tags:Passive UHF tags encode 96-bit to 256-bit EPC identifiers for luggage tracking at minimal per-unit cost. Demand concentrates at major hub airports in the United States, China, and Germany where baggage volume justifies automated sortation investment. Chinese manufacturing expansion is compressing hardware margins.
- Readers:Fixed and handheld readers operate across UHF and microwave bands with read ranges from one centimeter to fifteen meters. Deployment is accelerating at Category X airports under FAA ground equipment traceability directives. EASA certification requirements create multi-quarter approval delays for new hardware entrants.
- Software:Aviation-specific platforms manage tag data aggregation and carrier-airport synchronization.
- Middleware:Integration layers connect carrier operational databases with airport ground handling systems.
The dominant share belongs to Tags, while Software is closing the gap fastest.
Application:
Cost tier differentiation separates high-frequency compliance-driven deployments from discretionary security investments. Luggage tracking absorbs the majority of carrier procurement budgets under IATA mandates.
- Luggage Tracking:Automated baggage sortation systems encode real-time location data across terminal and airside zones. IATA Resolution 753 compels member carriers to retrofit legacy infrastructure, generating sustained demand across hub airports. Dual-frequency tags combining UHF and NFC interfaces are supplanting single-protocol solutions at premium carriers.
- Asset Management:Ground support equipment monitoring uses active RFID with integrated temperature and shock sensors for high-value cargo applications. Deployment is expanding beyond standard luggage tracking as sensor convergence opens new use cases. FAA airworthiness directives mandate electronic maintenance records for safety-critical assets.
- Personnel Tracking:Access control verification systems manage credential validation across restricted zones.
- Security Monitoring:Perimeter and checkpoint surveillance applications represent discretionary airport capital expenditure.
Luggage Tracking maintains the largest installed base, though Asset Management is expanding most quickly.
End User:
Customer type determines procurement authority and budget cycle timing. Airlines drive compliance-mandated spending while airports control infrastructure integration decisions.
- Airlines:Carrier procurement focuses on baggage tracking compliance under IATA Resolution 753 deadlines. Retrofit investments are compressing implementation timelines while straining vendor engineering capacity. Lufthansa and Singapore Airlines pilot hybrid dual-frequency tags across select routes.
- Airports:Terminal operators embed RFID-native systems in greenfield expansions rather than retrofitting aging mechanical sortation. Fraport and Munich Airport have adopted outcome-based contracts tying vendor payments to baggage mishandling rate reductions.
- Ground Handlers:Third-party service providers operate equipment tracking systems under airport and carrier direction.
- Security Agencies:Government authorities deploy credential verification infrastructure at restricted access points.
Airlines account for the majority of current procurement volume, with Airports gaining share through greenfield construction.
Technology:
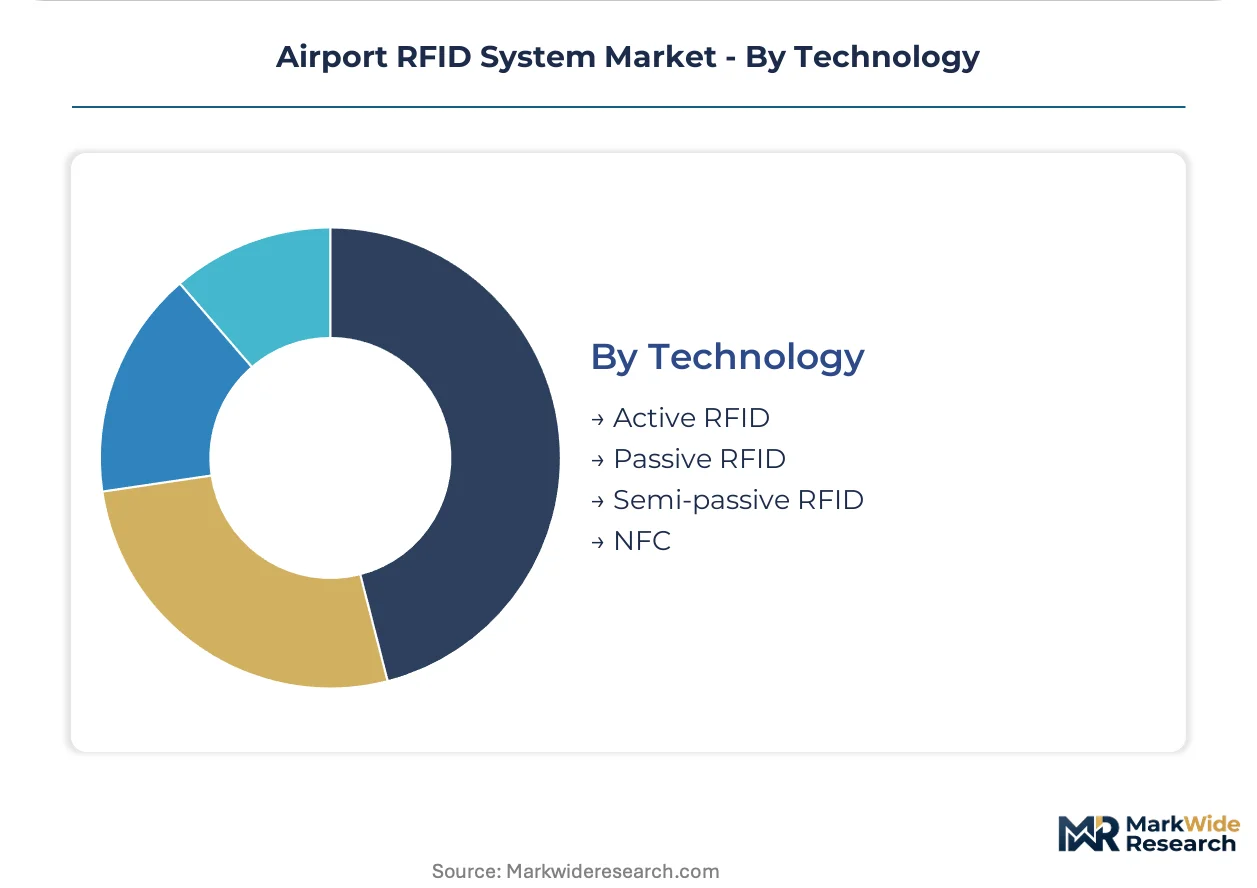
Maturity curves separate established passive UHF deployments from emerging active RFID applications requiring extended read range and sensor integration.
- Passive RFID:UHF passive tags dominate unit volume due to minimal per-unit cost in high-throughput luggage tracking. RAIN RFID certification backlogs at GS1 EPCglobal testing queues are delaying product launches for hardware vendors. Edge computing migration is shifting intelligence from centralized servers to distributed reader networks.
- Active RFID:Battery-powered tags command premium positioning where extended read range justifies elevated expenditure. Sensor integration for temperature and shock monitoring is opening high-value cargo applications beyond standard luggage tracking. Ground support equipment tracking represents untapped demand for active deployment on tugs, dollies, and loaders.
- Semi-passive RFID:Hybrid architectures combine battery-assisted response with passive backscatter for intermediate range applications.
- NFC:Near-field interfaces enable passenger-facing mobile verification without infrastructure duplication.
Passive RFID holds the dominant technology position, while Active RFID is gaining share fastest through sensor convergence applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA baggage tracking directives and IATA compliance deadlines anchor demand concentration in the United States, where carrier retrofit investments are compressing implementation timelines. Hub modernization across China and Germany is accelerating procurement of integrated RFID infrastructure as regulatory enforcement converges with capacity expansion.
United States
Category X airports in Atlanta, Chicago, and Dallas-Fort Worth are deploying RFID-enabled maintenance logging systems under FAA airworthiness directives for ground equipment traceability. The FAA mandates electronic records for all safety-critical assets operating within movement areas. Delta and United are retrofitting legacy baggage handling infrastructure at their Atlanta and Chicago hubs to meet IATA Resolution 753 deadlines.
China
Beijing Daxing and Shanghai Pudong are embedding RFID-native baggage systems in greenfield terminal expansions rather than retrofitting aging mechanical sortation. MIIT standards for radio-frequency equipment certification are filtering vendor qualification for airside deployments. Guangzhou Baiyun International Airport is consolidating vendor relationships into multi-year managed service agreements that bundle hardware, software, and ongoing tag supply.
Germany
Fraport and Munich Airport have adopted outcome-based contracts tying vendor payments to baggage mishandling rate reductions. EASA certification requirements for electronic equipment deployed in safety-critical airport zones create multi-quarter approval delays that filter vendor entry. Lufthansa is piloting dual-frequency RFID tags combining UHF and NFC interfaces across select routes from its Frankfurt hub.
India
Greenfield airport construction under the UDAN regional connectivity scheme is offering first-mover advantage for integrated RFID baggage system vendors. BIS certification requirements for imported electronic equipment are shaping procurement specifications for terminal automation. Bangalore and Hyderabad airports are embedding native RFID infrastructure in new terminals rather than retrofitting legacy mechanical systems.
Singapore
Changi Airport's Terminal 5 expansion is procuring edge-capable reader networks that process tag data locally rather than routing intelligence through centralized servers. The Civil Aviation Authority of Singapore enforces interoperability standards between carrier-specific and airport-operated RFID networks. Singapore Airlines is piloting hybrid dual-frequency tags enabling both automated sortation and passenger-facing mobile verification.
Airport RFID System Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the airport RFID system market, with hardware commoditization pressure squeezing margins at the tag production layer while software and middleware vendors capture disproportionate value pools. The specialist tier fragments across aviation-specific middleware providers, semiconductor fabricators, and end-to-end visibility platform vendors. Two dominant competitive moves are reshaping positioning: vendor consolidation into multi-year managed service agreements, and backward integration into captive chip supply to defend margin position against Chinese manufacturing expansion.
Among semiconductor specialists, Impinj and NXP Semiconductors anchor the RAIN RFID chip supply layer that underpins airport-grade tag programs. SITA occupies a position within the aviation-specific middleware tier, connecting carrier operational databases with airport ground handling systems. These three entities exemplify how vendor positioning stratifies between component supply, platform integration, and industry-specific software layers.
| Leading Market Players |
|---|
| Impinj |
| Checkpoint Systems |
| SITA |
| Savi Technology |
| Avery Dennison |
| Zebra Technologies |
| NXP Semiconductors |
| GAO RFID |
| Honeywell International |
| Others |
Supply Flow & Price Mechanics
Passive UHF tag substitution for legacy barcode systems simultaneously shifts production geography toward Chinese manufacturing clusters and compresses hardware margins across the aviation RFID value chain. This input replacement dynamic redistributes pricing power from component vendors toward integrated platform providers who bundle software layers with tag supply.
Pricing Analysis
Price spreads between EASA-certified and uncertified reader hardware exceed threefold across European procurement channels. Three-tier pricing structure across aviation-certified, industrial-grade, and consumer-tier levels reflects certification burden and read-range performance. Cost compression in passive tag production is intensifying because Chinese capacity expansion outpaces demand growth in luggage tracking applications. Low-cost carriers exhibit acute price sensitivity for standalone hardware, while hub airports prioritize total cost of ownership in multi-year managed service agreements.
Supply Chain Analysis
China and Taiwan anchor semiconductor fabrication for RAIN RFID chips, while Germany and the United States concentrate reader assembly and aviation-specific middleware development. The supply chain draws from silicon wafer processing, antenna substrate manufacturing, and embedded firmware development as core inputs. Single-source vulnerability concentrates in GS1 EPCglobal certification testing capacity, where backlogged queues delay product launches. Distribution runs through direct vendor relationships with airport procurement departments and carrier technology divisions, supplemented by aviation systems integrators in greenfield expansion markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as carrier compliance deadlines and airport modernization cycles desynchronize procurement timelines. The demand-side shift toward outcome-based contracts fragments buyer requirements across performance metrics rather than standardized product specifications.
For Market Incumbents: Fortify middleware integration capabilities through captive development of carrier-airport API templates that reduce deployment customization costs. Deepen upstream control over RAIN RFID chip supply through long-term foundry agreements with Taiwanese semiconductor fabricators, defending margin position against Chinese tag manufacturer vertical integration. For New Entrants and Emerging Players: EASA certification fast-track programs offer entry pathways for reader hardware vendors willing to absorb multi-quarter approval timelines. Ground support equipment tracking represents the most penetrable application segment, with active RFID sensor integration enabling differentiation from established luggage tracking vendors. Target outcome-based contracting expertise as the core go-to-market angle for airport procurement departments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed aviation software platforms that expanded through carrier compliance spending and now face contract renewal pressure. Five-to-ten year viability hinges on vendor ability to pivot from hardware-centric revenue toward recurring software and tag supply arrangements. Watch baggage mishandling rate performance guarantees as the signal indicating which managed service contracts will renew at expanded scope versus face recompetition.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Frequency Tag Development | Hybrid UHF-NFC architectures absorb middleware functionality previously delivered through software layers at Lufthansa and Singapore Airlines. |
| Edge-Capable Reader Networks | Distributed intelligence at read points reduces latency for Changi Airport Terminal 5 baggage sortation systems. |
| Managed Service Agreement Expansion | Fraport and Munich Airport outcome-based contracts tie vendor payments to measurable mishandling rate reductions. |
| Ground Support Equipment Tracking | Active RFID deployment on tugs and dollies addresses untapped demand for aircraft turnaround visibility at Category X airports. |
| EASA Certification Investment | Multi-quarter approval processes filter vendor entry and protect incumbent positioning in European safety-critical deployments. |
Methodological Framework
Desk research of IATA regulatory filings, FAA airworthiness directives, and airport procurement databases preceded structured interviews with airline technology procurement directors, airport operations executives, RFID systems integrators, and aviation middleware engineers. Secondary validation drew from EASA certification records, GS1 EPCglobal compliance testing queues, and carrier annual sustainability reports. Bottom-up tag volume estimates triangulated against top-down infrastructure investment forecasts across hub airport modernization programs.
Variance decomposition across product type, application, end user, and technology dimensions informed projection construction throughout the forecast period. Segment-level CAGRs were derived from deployment velocity modeling against IATA Resolution 753 compliance deadlines and greenfield airport construction pipelines. Forecast inputs incorporated engineering talent availability constraints, RAIN RFID certification backlogs, and regional regulatory enforcement intensity as aviation-specific variables.
Decision-makers should treat outputs as directional under assumptions of sustained IATA mandate enforcement and hub airport expansion continuity; material deviation in regulatory timelines or infrastructure investment would warrant model refresh. Recalibration cycles align with material shifts in carrier compliance spending, EASA certification requirement changes, and greenfield airport construction milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
Smart Airport 4.0 Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Airport Interactive Kiosk Market
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Middle-East and Africa Airport Ground Handling Systems Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
Smart Airport Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
North America Smart Airport Market
Airport Technologies
Smart Airport 2.0 Market
Airport Technologies
Airport Runway Foreign Object Debris (FOD) Detection Systems Market
Airport Technologies
Commercial Airport Baggage Handling Systems Market
Airport Technologies
Advanced Airport Technologies Market