
 Airport Airside Service Market | 2026-2036
Airport Airside Service Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Airside Service Market Insights
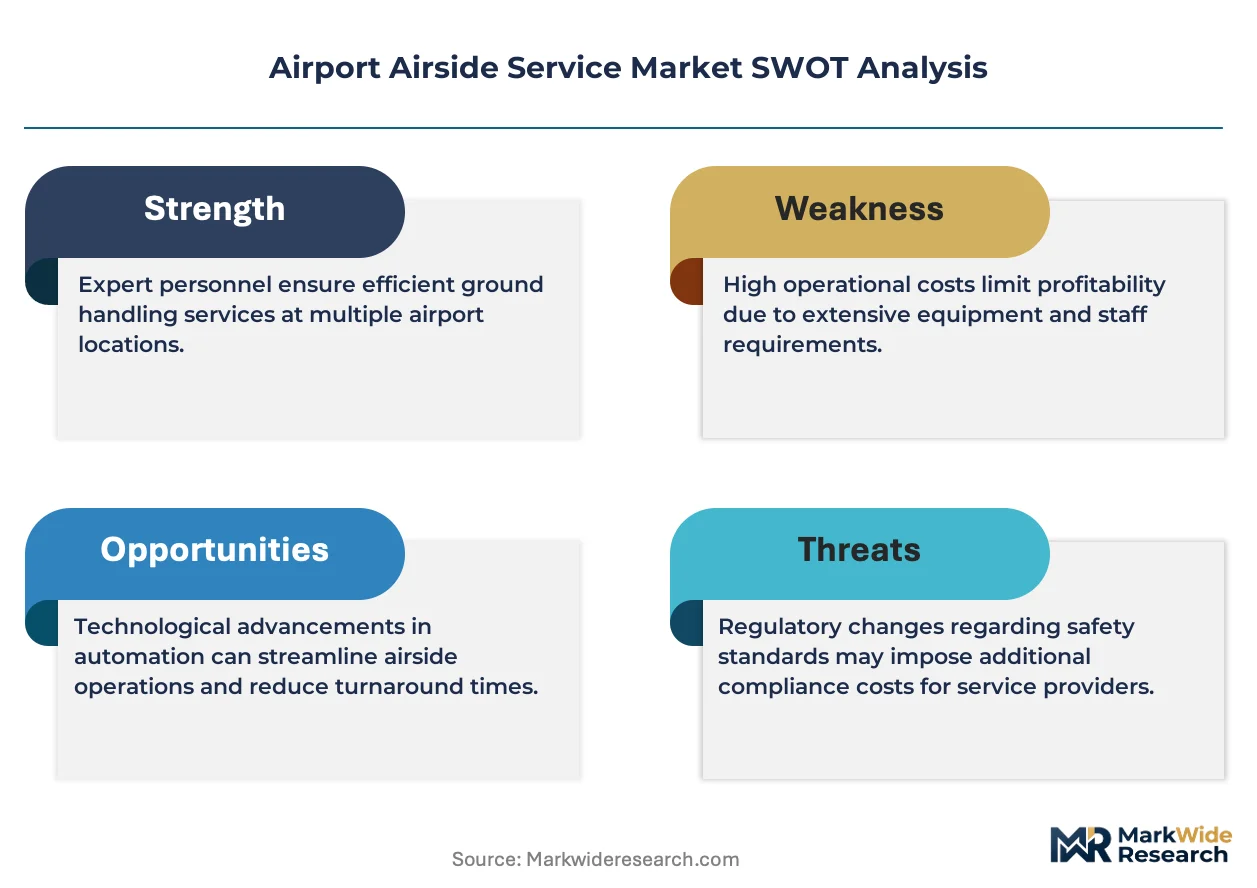
The Middle East is tilting toward super-hub expansion as Gulf states invest in parallel runway systems and centralized ground handling complexes. Dnata leverages its integrated service model across Dubai's dual-airport ecosystem. Honeywell International Inc. sustains technology leadership through airfield lighting and ground control automation systems. Worldwide Flight Services competes on scale, operating across six continents with standardized ramp protocols.
Airport airside service encompasses all aircraft-facing operations conducted on the restricted movement area, including ground handling, refueling, de-icing, and cargo loading, typically governed by IATA Safety Audit standards and airport slot coordination frameworks. Ground handling commands the largest revenue pool due to labor intensity and regulatory certification barriers, while aircraft maintenance captures premium margins from OEM-authorized service networks. Ramp services represent the fastest-growing segment as airports adopt electric tugs and autonomous baggage tractors to reduce turnaround times.
The FAA enforces strict Part 139 airside operating standards that shape equipment specifications and training protocols for US-based operators. EASA's Ground Handling Directive harmonizes safety requirements across EU member states, creating compliance costs that favor consolidated service providers. ICAO's aerodrome certification framework sets baseline standards that national regulators adapt locally. Stakeholders must monitor electrification mandates and carbon disclosure rules as airports begin embedding sustainability criteria into service procurement.
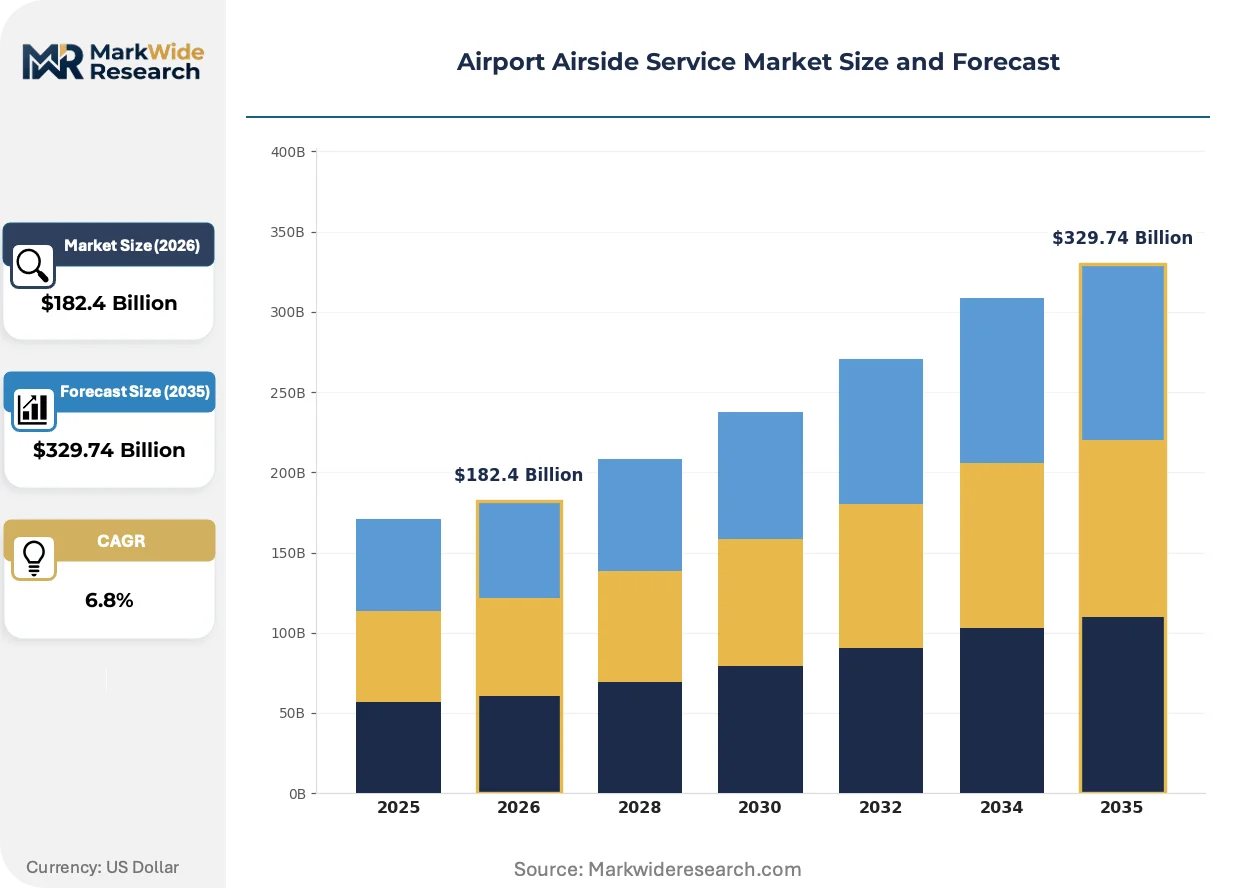
Market Dynamics
Automated baggage handling systems and electric ground support equipment are compressing turnaround times while FAA Part 139 mandates force capital replacement cycles across US airport operators.
Growth Catalysts
- ICAO Aerodrome Certification:Baseline safety standards adopted by national regulators in the UAE and Singapore are mandating equipment upgrades that expand service contract volumes.
- Dual-runway super-hubs:Dubai and Abu Dhabi are building centralized ground handling complexes that consolidate demand for integrated airside packages.
- Electrification mandates:Airport authorities in Germany and France are embedding carbon disclosure criteria into procurement rules, accelerating fleet replacement.
Market Restraints
- Labor certification barriers:IATA Safety Audit standards require specialized training programs that limit workforce scalability in emerging markets.
- Jet fuel price volatility:Refueling service margins compress when crude benchmarks spike, squeezing ground handling bundling economics.
- OEM-authorized network concentration:Aircraft maintenance revenue pools concentrate with manufacturer-captive service providers in the US and EU.
Strategic Opportunities
- Autonomous baggage tractors:Convergence of electric propulsion and LiDAR navigation is opening retrofit markets at mid-tier European airports.
- Saudi super-hub construction:King Salman International Airport development is creating greenfield service contracts outside established Gulf operator territories.
- EU Green Deal procurement rules:Sustainability-linked tender criteria favor service providers with certified carbon accounting systems.
Industry Challenges
- Ramp safety certification timelines:EASA Ground Handling Directive compliance requires 18-24 month accreditation cycles that delay contract starts.
- Legacy GSE integration:Diesel-powered tugs and belt loaders require phased replacement protocols that disrupt 24/7 operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Airside Service Market |
| Market Size in 2026 | $182.4 Billion |
| Market Size in 2035 | $329.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ground Handling, Refueling, Baggage Handling, Aircraft Maintenance, Ramp Services Equipment Type: Tugs, De-icing Machines, Fuel Trucks, Cargo Loaders, Passenger Stairs End User: Airlines, Cargo Operators, Charter Operators, Fixed Base Operators Application: Passenger Aircraft, Cargo Aircraft, Business Jets, Military Aircraft |
| Companies Covered | Acciona S.A., Dnata, United Aviation Services, BBA Aviation plc, Aviapartner Holding NV, Honeywell International Inc., Worldwide Flight Services (WFS), Singapore Airport Terminal Services Ltd, Aeromexico Servicios, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Airside Service Market Trends and Innovations
Digital twin platforms and predictive maintenance algorithms are redefining how airside operators manage asset utilization and downtime risk across high-volume hubs.
Autonomous guided vehicles are digitizing baggage flow orchestration. Dnata and Swissport are deploying sensor-equipped tractors at Dubai International and Zurich to reduce human error during peak banks. This technology is digitizing turnaround scheduling by enabling real-time position tracking that compresses gate allocation windows.
EU F-Gas Regulation is phasing out hydrofluorocarbon-based de-icing fluids. Equipment operators must retrofit spray systems for glycol alternatives before 2030 deadlines. German and Scandinavian airports are absorbing the highest compliance costs, driving consolidation toward integrated service providers with captive chemical supply chains.
Airlines are unbundling ground handling contracts from fueling and cargo services. Low-cost carriers at London Stansted and Berlin Brandenburg now source ramp services through spot-market platforms rather than legacy multi-year agreements. This pattern is most visible in European secondary airports where price transparency tools have proliferated.
Airport Airside Service Market Segmentation
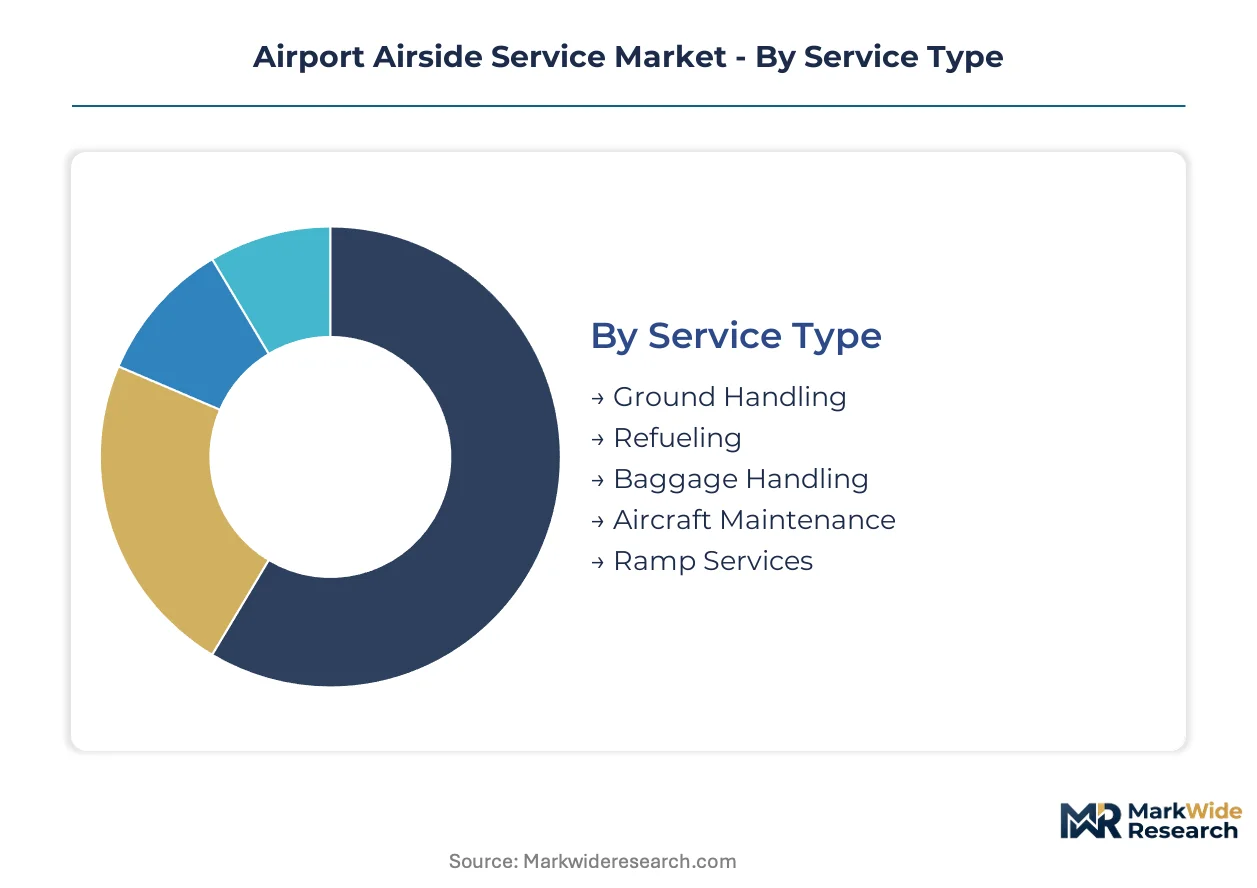
Airside service providers configure capabilities around four structural axes: service delivery mode, equipment deployment, customer contract type, and aircraft class served. Each axis carries distinct margin profiles and capital intensity requirements that shape competitive positioning across hub tiers.
Service Type:
Mature segments dominate revenue pools while emerging automation categories reshape operational economics.
- Ground Handling:Labor-intensive aircraft servicing including marshalling, cabin cleaning, and lavatory servicing under IATA Safety Audit certification. Demand concentrates at Dubai International and Singapore Changi where dual-runway super-hubs compress turnaround windows through integrated ramp protocols.
- Refueling:Into-plane fueling and hydrant system management governed by JIG standards and airline fuel consortium agreements. Jet fuel price volatility squeezes bundling economics when crude benchmarks spike, forcing operators toward spot-market pricing models.
- Baggage Handling:Automated sortation systems and manual transfer operations bridging terminal-to-aircraft flow. FAA Part 139 mandates are accelerating capital replacement cycles for US-based operators.
- Aircraft Maintenance:Line maintenance checks and AOG response services requiring OEM authorization networks. Revenue pools concentrate with manufacturer-captive providers in the US and EU due to certification barriers.
- Ramp Services:Electric tugs and autonomous baggage tractors reducing gate occupancy times. German and French electrification mandates are embedding carbon disclosure criteria into procurement rules.
Ground Handling retains volume leadership; Ramp Services holds the steepest expansion curve.
Equipment Type:
Cost tier stratification separates high-unit-value automation platforms from commoditized mechanical assets.
- Tugs:Conventional diesel and electric pushback tractors for aircraft repositioning. EU Green Deal procurement rules favor providers with certified carbon accounting systems for fleet replacement tenders.
- De-icing Machines:Glycol spray systems for ice removal during winter operations. EU F-Gas Regulation is phasing out hydrofluorocarbon-based fluids, requiring retrofit investments before 2030 deadlines.
- Fuel Trucks:Refueler vehicles and hydrant dispensers with integrated metering systems. German and Scandinavian airports absorb highest compliance costs for emission-controlled fleet standards.
- Cargo Loaders:Belt loaders and container/pallet loaders for freighter turnaround. King Salman International Airport development in Saudi Arabia is creating greenfield contract opportunities.
- Passenger Stairs:Mobile and fixed boarding stairs for apron-level embarkation. Mid-tier European airports are prioritizing electric retrofit markets over new capital deployment.
Fuel Trucks command the premium cost tier; Tugs are gaining share fastest through electrification mandates.
End User:
Customer type determines contract duration, pricing volatility exposure, and service bundling depth.
- Airlines:Full-service and low-cost carriers sourcing integrated ground handling packages. Unbundling trends at London Stansted and Berlin Brandenburg are shifting procurement toward spot-market platforms.
- Cargo Operators:Dedicated freighter airlines and integrators requiring specialized loading equipment. Dubai and Abu Dhabi super-hub construction is consolidating demand for centralized cargo handling complexes.
- Charter Operators:Ad-hoc flight providers with irregular scheduling patterns and premium service expectations.
- Fixed Base Operators:General aviation service providers at executive airports handling business jet traffic.
Airlines retain volume leadership; Cargo Operators hold the steepest expansion curve.
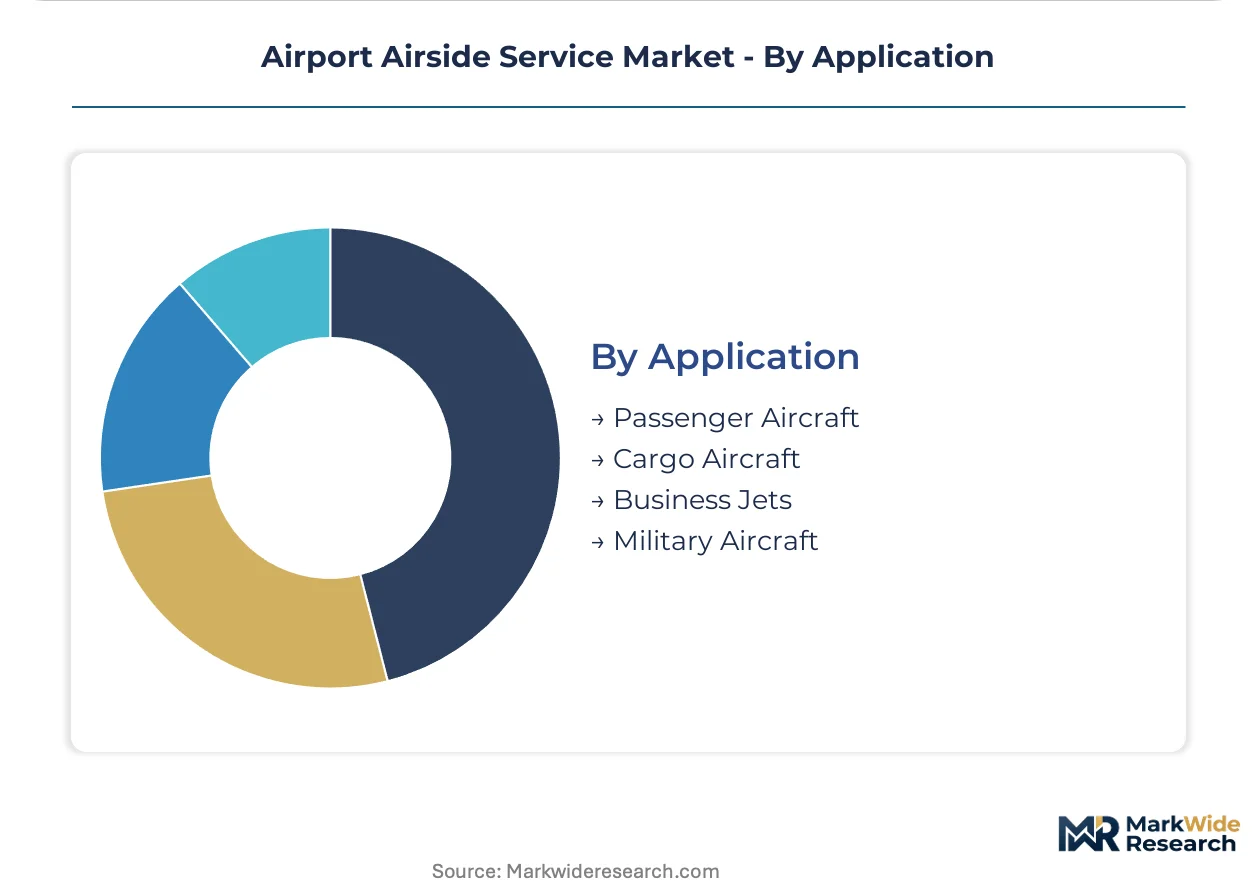
Application:
Volume concentration varies sharply across aircraft class, with wide-body operations driving equipment utilization economics.
- Passenger Aircraft:Narrow-body and wide-body commercial fleet operations at scheduled hubs. Dnata leverages integrated service models across Dubai's dual-airport ecosystem for this segment.
- Cargo Aircraft:Dedicated freighter and converted passenger-to-freighter operations. EASA Ground Handling Directive compliance creates 18-24 month accreditation delays for new market entrants.
- Business Jets:Private and corporate aviation requiring rapid turnaround and premium handling protocols.
- Military Aircraft:Government and defense operations with specialized security and fueling requirements.
Passenger Aircraft retains volume leadership; Cargo Aircraft holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dubai International Airport expansion and King Salman International Airport development anchor Middle Eastern super-hub construction. Dual-runway systems in the UAE and Saudi Arabia concentrate demand for integrated ground handling complexes. FAA Part 139 mandates and EASA Ground Handling Directive compliance reshape equipment procurement across North America and Europe.
United States
Full-service carriers expanding long-haul fleets intensify demand for automated baggage systems at Atlanta Hartsfield-Jackson and Dallas-Fort Worth. FAA Part 139 airside operating standards enforce strict equipment specifications and training protocols. Chicago O'Hare and Denver International anchor centralized ground handling procurement for legacy carrier networks.
United Arab Emirates
Dubai and Abu Dhabi super-hub capacity expansion drives integrated airside service packages across dual-airport ecosystems. MOHAP and GCAA aerodrome certification frameworks mandate equipment upgrades for centralized ground handling complexes. Dubai International and Al Maktoum International concentrate Dnata's integrated service model across parallel runway systems.
Germany
Electrification mandates from airport authorities embed carbon disclosure criteria into ground support equipment procurement. EU F-Gas Regulation phases out hydrofluorocarbon-based de-icing fluids, requiring retrofit investments before 2030. Frankfurt and Munich anchor compliance cost concentration for emission-controlled fleet standards and glycol alternative spray systems.
Saudi Arabia
King Salman International Airport development creates greenfield service contracts outside established Gulf operator territories. SFDA and GACA coordination shapes safety audit standards for new super-hub construction. Riyadh and Jeddah concentrate demand for cargo loading complexes and electric tug deployment at greenfield sites.
Singapore
ICAO aerodrome certification baseline standards mandate equipment upgrades that expand service contract volumes at Changi Airport. CAAS harmonizes safety requirements with IATA Safety Audit frameworks for ground handling operators. Singapore Changi anchors Southeast Asian demand for integrated ramp protocols and autonomous baggage tractor trials.
Airport Airside Service Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in equipment supply. The vendor base stratifies between consolidated service providers with multi-continent footprints and regional specialists serving single-airport contracts. Three archetypes dominate: integrated ground handling platforms, technology-led automation suppliers, and OEM-authorized maintenance networks. Competitive moves concentrate on strategic partnerships for super-hub access and fleet electrification mandates.
Among integrated service providers, Dnata and Worldwide Flight Services exemplify scale-driven platform operators spanning dual-runway ecosystems. Honeywell International Inc. anchors the technology tier through airfield lighting and ground control automation systems. These three names represent divergent strategic positions: Dnata leverages geographic concentration in the UAE, WFS competes on standardized protocols across six continents, and Honeywell sustains equipment leadership through regulatory-aligned product cycles.
| Leading Market Players |
|---|
| Acciona S.A. |
| Dnata |
| United Aviation Services |
| BBA Aviation plc |
| Aviapartner Holding NV |
| Honeywell International Inc. |
| Worldwide Flight Services (WFS) |
| Singapore Airport Terminal Services Ltd |
| Aeromexico Servicios |
| Others |
Pricing and Supply Chain Analysis
German and French electrification mandates for ground support equipment concentrate procurement leverage with OEM-captive service networks, pushing margin pools toward providers with certified carbon accounting systems and captive chemical supply chains for glycol-based de-icing alternatives.
Pricing Analysis
EASA Ground Handling Directive dictates the pricing tier structure across European airport service contracts. Three-tier pricing structure across premium, standard, and economy levels separates OEM-authorized maintenance networks from consolidated ramp operators and spot-market baggage handlers. Cost compression in standard-tier ramp services is intensifying because low-cost carriers at London Stansted and Berlin Brandenburg now source through digital procurement platforms. Cargo operators show least price sensitivity due to specialized equipment requirements and irregular scheduling premiums.
Supply Chain Analysis
Export controls on LiDAR navigation systems and electric propulsion components limit autonomous baggage tractor flows to mid-tier European airports. Manufacturing concentrates in Germany, China, and the United States for electric tugs and automated sortation equipment. Supply chains draw from lithium-ion battery cells, precision sensor arrays, and glycol chemical feedstocks. Single-source vulnerability sits with semiconductor-dependent navigation modules. Distribution runs through airport authority procurement departments and airline fuel consortium agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airport airside service demand tracks the cyclical recovery in long-haul fleet expansion by full-service carriers, with super-hub construction in the Gulf states extending the upcycle.
For Market Incumbents: Entrench position through backward integration into electric ground support equipment manufacturing and captive glycol supply chains for de-icing operations. Dnata's dual-airport ecosystem model in Dubai demonstrates how geographic concentration defends against spot-market platform disruption. Prioritize IATA Safety Audit certification investments to extend contract renewal timelines beyond 18-month EASA accreditation cycles. For New Entrants and Emerging Players: Pursue greenfield service contracts at King Salman International Airport development in Saudi Arabia, where established Gulf operator territories remain unclaimed. Autonomous baggage tractor retrofit markets at mid-tier European airports offer the most penetrable entry point. Lead with EU Green Deal procurement compliance and certified carbon accounting systems as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional ground handling specialists consolidating around single-airport contracts. Five-to-ten year viability hinges on electrification mandate compliance rather than fleet scale alone. Target acquisition archetype: integrated service providers with captive chemical supply chains and OEM maintenance authorizations. Watch for inflection in jet fuel price volatility as the signal for refueling service margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Program | EU Green Deal procurement rules at Frankfurt and Munich favor certified carbon accounting systems. |
| Autonomous Equipment Deployment | LiDAR-equipped baggage tractors at Dubai International compress gate allocation windows through real-time tracking. |
| Super-Hub Service Integration | Centralized ground handling complexes at King Salman International Airport consolidate demand outside established territories. |
| Chemical Supply Chain Backward Integration | EU F-Gas Regulation phase-out of hydrofluorocarbon fluids requires captive glycol alternative sourcing. |
| Digital Procurement Platform Launch | Spot-market platforms at London Stansted and Berlin Brandenburg displace legacy multi-year contract structures. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with airport operations directors, ground handling procurement managers, airline fleet planning executives, and GSE maintenance heads; and secondary validation through IATA Safety Audit documentation, EASA Ground Handling Directive filings, FAA Part 139 enforcement records, and airport authority procurement databases. Bottom-up service contract volume estimates triangulated against top-down super-hub capacity expansion projections.
Forecast inputs span equipment replacement cycles, regulatory compliance deadlines, and fleet electrification procurement timelines across the analysis window. Segmentation dimensions include service delivery mode, equipment deployment type, customer contract structure, and aircraft class served. CAGRs derive from equipment unit economics and labor cost trajectories. Industry-specific inputs incorporate jet fuel price volatility bands and EASA accreditation cycle durations.
Sensitivities concentrate around electrification mandate acceleration, autonomous equipment regulatory clearance delays, and super-hub construction timeline shifts. Forecasts reflect assumptions on long-haul fleet expansion rates and Gulf state infrastructure commitment levels. Material shifts in FAA or EASA ground handling enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Airport Baggage Conveyor System Market
Airport Technologies
Europe Smart Airport Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
Airport Information Systems Market
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
Airport Runway Foreign Object Debris (FOD) Detection Systems Market
Airport Technologies
Asia-Pacific Airport Baggage Handling Systems Market
Airport Technologies
Air Traffic Smart Tower Solutions Market
Airport Technologies
Airport RFID System Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
Airport Smart Lighting Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Smart Airport 4.0 Market