
 Small Satellite Market | 2026-2036
Small Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
Small Satellite Market Intelligence
Defense demand is rebalancing toward persistent tactical surveillance and broadband relay networks in low-Earth orbit. Lockheed Martin Corporation leverages its heritage in military payload integration to anchor classified constellation programs. SpaceX sustains cost leadership through reusable Falcon 9 cadence and in-house Starshield variants for national security clients. Planet Labs differentiates via daily global imaging coverage and automated analytics pipelines serving both defense and commercial agriculture verticals.
Small satellites are spacecraft with masses below 500 kilograms, typically employing standardized form factors such as CubeSat units of 10 cm × 10 cm × 10 cm and commercial off-the-shelf electronics to reduce unit costs and development cycles; they serve primarily to democratize space access for Earth observation, telecommunications, and scientific missions previously requiring billion-dollar platforms. CubeSat and NanoSat platforms dominate launch manifests due to their compatibility with rideshare aggregation and rapid iteration timelines, while Earth Observation commands the largest revenue pool as commercial operators and defense agencies seek revisit rates measured in hours rather than days. Rideshare launch integration is accelerating fastest as SpaceX Transporter missions and similar services collapse per-kilogram costs and compress booking lead times for university and startup payloads.
The Federal Communications Commission governs spectrum allocation and orbital debris mitigation for U.S. operators, while the FAA licenses commercial launch activities under Part 450 regulations; Europe's EASA and national space agencies enforce debris compliance through the EU Space Surveillance and Tracking framework, and China's MIIT coordinates frequency assignments with SAMR oversight of domestic constellation filings. Stakeholders must monitor evolving debris mitigation rules, as tighter post-mission disposal requirements will reshape platform design trade-offs and insurance costs across all jurisdictions.
Market Dynamics
Rideshare launch aggregation is compressing orbital access costs and compressing development cycles for university and commercial payload operators, forcing incumbents to restructure satellite manufacturing workflows around standardized form factors rather than bespoke platforms.
Growth Catalysts
- FCC Part 25 Licensing Reform:Streamlined spectrum allocation and orbital debris mitigation rules have collapsed entry timelines for commercial constellation ventures in the United States.
- Defense ISR Constellation Procurement:Persistent tactical surveillance requirements from military end-users are pulling multi-unit small satellite orders into fixed-price production contracts.
- Standardized CubeSat Form Factors:10 cm unit modularity enables rideshare slot aggregation across multiple launch providers, reducing per-kilogram costs for Earth observation startups.
Market Restraints
- Launch Provider Concentration:Heavy reliance on single-source reusable medium-lift vehicles creates capacity bottlenecks during military manifest priority windows.
- Radiation-Hardened Component Costs:Commercial off-the-shelf electronics face derating requirements for low-Earth orbit missions, inflating subsystem procurement expenses.
- Post-Mission Disposal Mandates:Tighter FCC and EASA debris mitigation rules are extending platform design cycles and elevating insurance premiums for extended missions.
Strategic Opportunities
- Automated Analytics Integration:Machine learning pipelines processing hyperspectral imagery are opening recurring-revenue service contracts in precision agriculture and carbon monitoring.
- India's IN-SPACe Framework:Private sector participation rules are unlocking domestic launch integration and ground station services for regional Earth observation constellations.
- Optical Inter-Satellite Links:Laser communications terminals are enabling real-time data relay without ground station dependency, creating premium service tiers for defense and maritime clients.
Industry Challenges
- Orbital Mechanics Talent Scarcity:Constellation design and station-keeping optimization require specialized astrodynamics expertise that outpaces university pipeline output.
- ITAR Compliance Complexity:Dual-use technology classifications create licensing friction for internationally sourced subsystems and foreign payload integration.
- Ground Segment Integration:Antenna network coordination across multiple jurisdictions demands sustained capital deployment that strains early-stage operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Satellite Market |
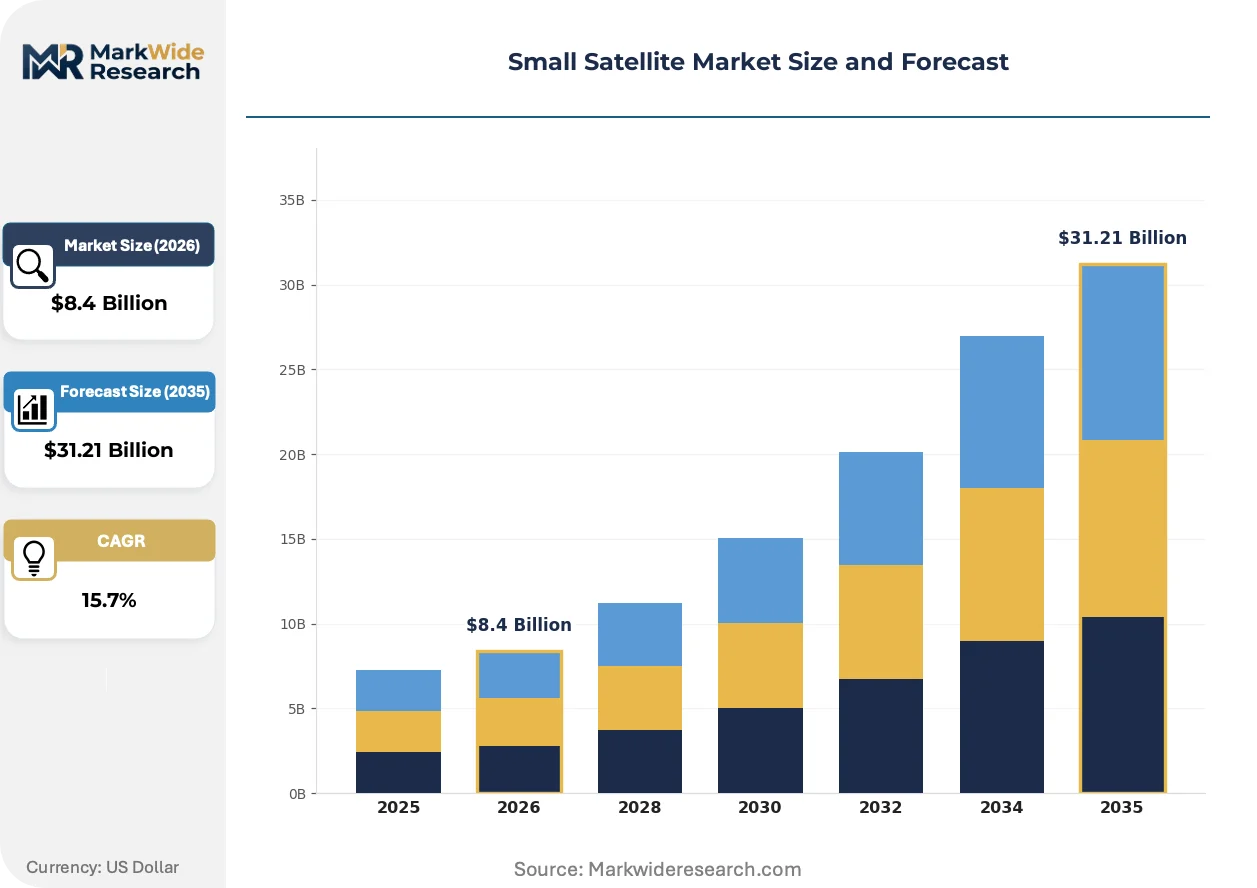
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $31.21 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: CubeSat, NanoSat, MicroSat, MiniSat, PicoSat Satellite Application: Earth Observation, Communication, Scientific Research, Technology Demonstration, Space Exploration Launch Vehicle Integration: Dedicated Launch, Rideshare, Secondary Payload, Piggyback, Air Launch End User Segment: Commercial Operators, Research Institutions, Defense Agencies, Educational Organizations, Non-Governmental Organizations |
| Companies Covered | China Aerospace Science and Technology Corporation, Lockheed Martin Corporation, SpaceX, Planet Labs, Northrop Grumman, Airbus Defence and Space, Thales Alenia Space, Dhruva Space, MDA Space, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Satellite Market Strategic Shifts & Innovations
Propulsion miniaturization and software-defined radio architectures are compressing satellite platform lifecycles while expanding mission flexibility. These shifts are redefining competitive differentiation around rapid iteration rather than heritage reliability.
Electric propulsion systems utilizing iodine-based thrusters are rewriting mission design economics for small satellite operators. Commercial Earth observation ventures are adopting these units to enable orbit-raising and deorbit maneuvers without toxic hydrazine handling infrastructure. This technology is rewriting the trade-off between platform mass budget and operational lifespan, allowing lighter dry masses to accommodate larger sensor payloads.
The European Union's Space Surveillance and Tracking framework is mandating conjunction assessment and collision avoidance capabilities for all member state operators. Industrial consequence includes mandatory onboard autonomy for maneuver execution without ground-in-the-loop delays. Small satellite manufacturers in Germany, France, and Italy are responding by integrating commercial SSA data feeds and automated thrusting algorithms into flight software baselines.
Subscription-based data licensing is displacing traditional per-image transactional sales in the Earth observation vertical. Agricultural commodity traders and insurance underwriters are driving this shift through requirements for continuous coverage rather than tasking-based acquisition. This pattern is most visible in North American and Australian markets where farm management software platforms integrate satellite-derived analytics into existing enterprise workflows.
Small Satellite Market Segmentation
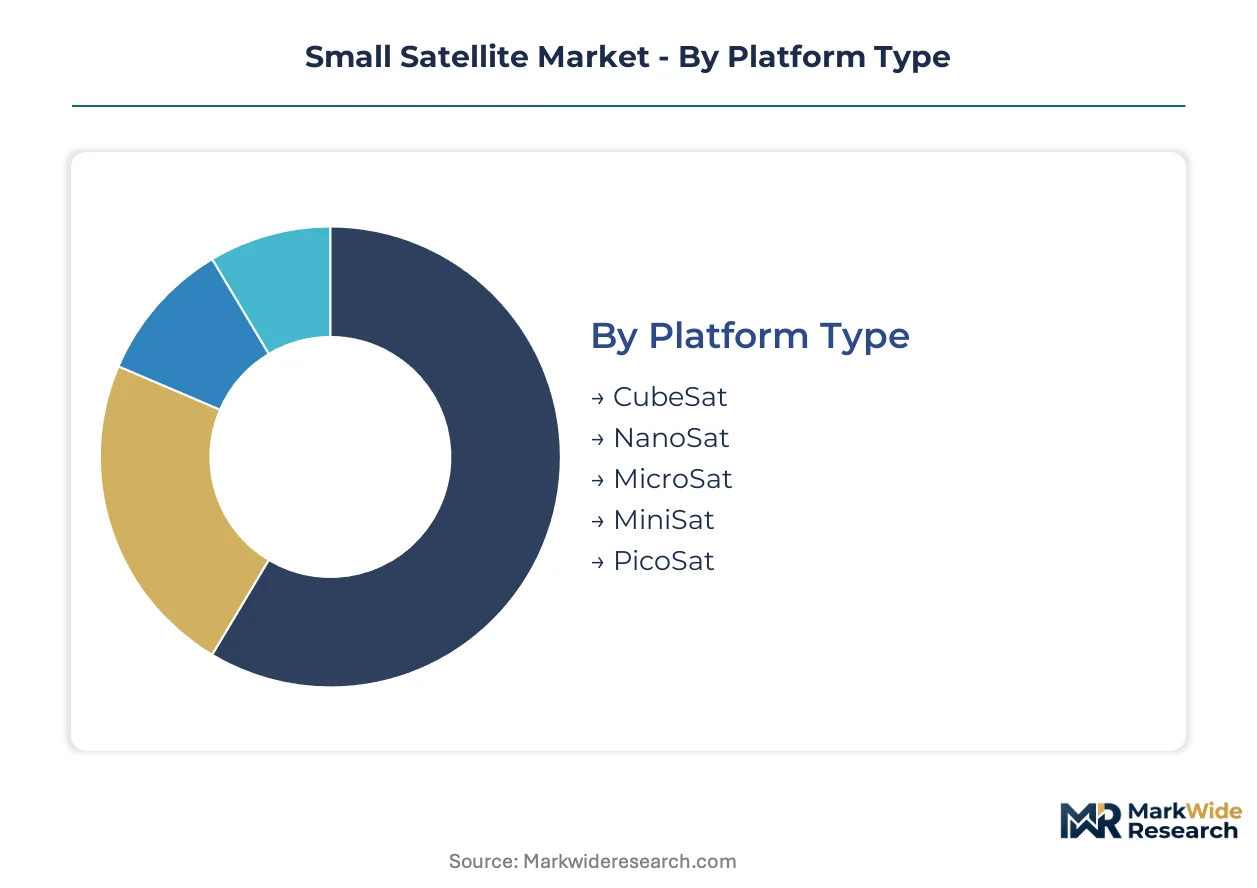
Segmentation in the small satellite market reveals how platform miniaturization, application specialization, and launch economics intersect to create distinct competitive arenas. Each dimension carries unique margin structures and regulatory exposures that shape vendor positioning.
Platform Type:
Customization intensity varies sharply across mass classes, from highly standardized CubeSat units to bespoke MiniSat configurations requiring dedicated engineering.
- CubeSat:Modular 10 cm unit architecture enables rapid prototyping and rideshare compatibility. Demand concentrates among university consortia and Earth observation startups in the United States, constrained by radiation-hardened component lead times.
- NanoSat:1-10 kg form factors balance sensor capacity with launch cost efficiency. Commercial operators in precision agriculture and maritime tracking favor these platforms for their revisit rate economics.
- MicroSat:10-100 kg designs accommodate synthetic aperture radar and hyperspectral payloads. Research institutions leverage these for climate monitoring missions requiring greater power budgets.
- MiniSat:100-500 kg platforms approach traditional small satellite territory with dedicated propulsion and thermal control. Defense agencies commission these for tactical communications constellations requiring hardened electronics.
- PicoSat:Sub-1 kg experimental units serve technology demonstration and educational markets. Educational organizations deploy these for orbital mechanics training with minimal regulatory overhead.
Leading the category by volume: CubeSat. Expanding most quickly: NanoSat.
Satellite Application:
Revenue concentration tracks data refresh frequency requirements, with continuous monitoring applications commanding premium pricing over episodic tasking.
- Earth Observation:Multispectral and hyperspectral imaging systems generate recurring revenue through subscription analytics. Agricultural commodity traders and insurance underwriters in North America and Australia drive uptake for crop yield forecasting.
- Communication:Low-Earth orbit broadband constellations and IoT relay networks serve maritime and aviation connectivity gaps. Defense agencies procure these for tactical beyond-line-of-sight communications in contested environments.
- Scientific Research:Atmospheric sensing and space weather monitoring missions support climate modeling and solar storm prediction. NASA and ESA anchor demand through competed mission opportunities.
- Technology Demonstration:On-orbit validation of novel propulsion, power, and communication subsystems de-risks future operational deployments. Venture-backed startups use these missions to attract Series B funding.
- Space Exploration:Lunar and deep-space small satellite missions extend platform utility beyond Earth orbit. These require specialized radiation tolerance and extended-link communications architectures.
Earth Observation dominates revenue share. Communication climbs fastest on constellation deployment timelines.
Launch Vehicle Integration:
Cost per kilogram and schedule certainty trade off across integration modes, with aggregation services compressing entry barriers for cash-constrained operators.
- Rideshare:SpaceX Transporter missions and similar aggregation services collapse per-kilogram costs through manifest optimization. Commercial Earth observation ventures in the United States and Germany rely on these for rapid constellation buildout.
- Dedicated Launch:Single-customer missions preserve schedule control and orbital parameter precision. Defense agencies pay premiums for classified payload security and priority manifesting.
- Secondary Payload:Opportunistic integration on missions with excess capacity suits technology demonstration payloads with flexible timing requirements.
- Piggyback:Deployment from larger satellite platforms enables distributed sensing architectures without independent propulsion. Scientific research missions exploit this for swarm-based measurements.
- Air Launch:Aircraft-based deployment from Virgin Orbit and emerging providers offers inclination flexibility and weather independence. Maritime surveillance operators value these for responsive orbital plane access.
Rideshare leads by mission count. Dedicated Launch retains highest revenue per kilogram.
End User Segment:
Procurement sophistication and contract structures diverge sharply between institutional anchor tenants and emergent commercial demand.
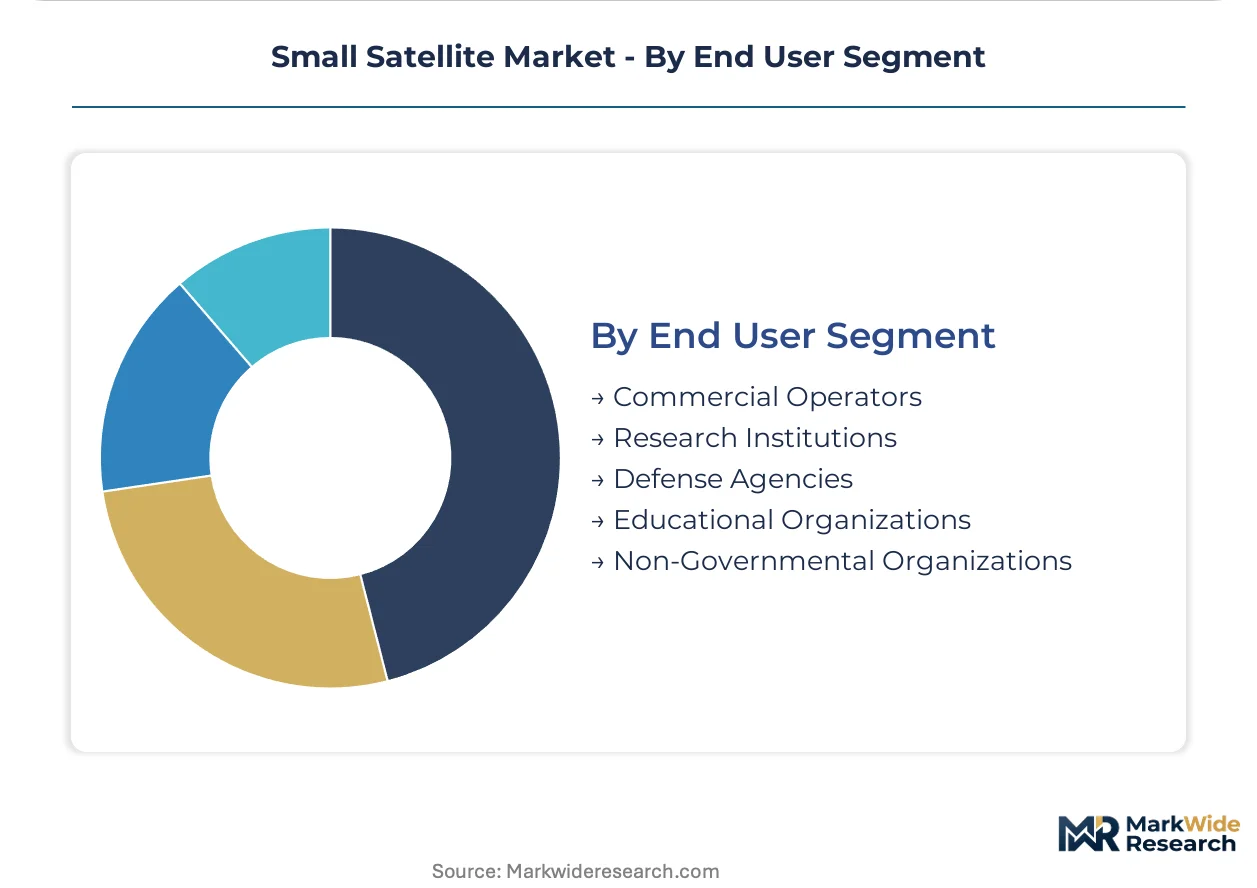
- Defense Agencies:Classified constellation programs with fixed-price production contracts and ITAR-controlled supply chains. Space Force procurement in the United States anchors this segment with multi-year commitments.
- Commercial Operators:Venture-backed Earth observation and communications ventures with recurring-revenue business models. These entities prioritize rapid iteration and software-defined payload architectures.
- Research Institutions:Government-funded climate and space science missions with competed peer-review selection processes. NASA Earth Science and ESA Earth Observation programs represent primary funding sources.
- Educational Organizations:University-led CubeSat programs emphasizing workforce development and technology demonstration. These missions face constrained budgets and rely heavily on rideshare opportunities.
- Non-Governmental Organizations:Environmental monitoring and disaster response applications with grant-dependent financing. Carbon monitoring and deforestation tracking represent emerging use cases.
Defense Agencies anchor contract value. Commercial Operators gain share fastest on venture deployment velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in established aerospace hubs, while launch demand concentrates in jurisdictions with streamlined spectrum licensing and defense procurement pipelines.
United States
Space Force contracts and venture-backed Earth observation ventures drive launch cadence. The FCC's streamlined Part 25 licensing collapsed entry timelines for commercial constellation operators. Los Angeles and Denver anchor production clusters where legacy defense contractors and startup ventures co-locate manufacturing facilities.
China
Domestic constellation filings for broadband and remote sensing pull volume demand from state-owned operators. MIIT coordinates frequency assignments with SAMR oversight tightening debris compliance standards. Beijing and Shanghai host design centers where state aerospace corporations integrate commercial off-the-shelf subsystems into standardized platforms.
Germany
Research institutions and commercial Earth observation ventures sustain platform demand for climate monitoring missions. EASA enforces debris mitigation through the EU Space Surveillance and Tracking framework. Munich and Bremen concentrate manufacturing where medium-sized enterprises supply propulsion and optical subsystems to constellation programs.
India
Regional Earth observation constellations and technology demonstration missions expand procurement from private operators. IN-SPACe framework rules unlocked domestic launch integration and ground station services. Bangalore and Hyderabad anchor clusters where startups leverage ISRO heritage infrastructure for rapid platform development.
Japan
Maritime surveillance and disaster response applications sustain government demand for rapid-revisit imaging. METI coordinates national space strategy with JAXA technology transfer programs. Tokyo and Nagoya host engineering centers where precision manufacturing capabilities support miniaturized sensor integration.
Small Satellite Market Key Industry Players
Top-tier vendors anchor classified defense constellations and high-cadence launch services, while mid-tier specialists concentrate on standardized platform manufacturing and subsystem supply. The vendor base stratifies across three archetypes: integrated primes with payload heritage, commercial launch providers with rideshare aggregation, and component specialists with radiation-hardened electronics. Dominant competitive moves include vertical integration into launch services and strategic partnerships for ground segment coverage.
Among integrated defense contractors, Lockheed Martin Corporation and Northrop Grumman exemplify the prime-tier archetype with classified constellation program anchors. SpaceX occupies a distinct position combining reusable launch cadence with in-house Starshield variants for national security clients. These three entities represent contrasting pathways: legacy payload integration, launch cost leadership, and hybrid service verticalization.
| Leading Market Players |
|---|
| China Aerospace Science and Technology Corporation |
| Lockheed Martin Corporation |
| SpaceX |
| Planet Labs |
| Northrop Grumman |
| Airbus Defence and Space |
| Thales Alenia Space |
| Dhruva Space |
| MDA Space |
| Others |
Cost & Logistics Intelligence
Venture-backed platform specialists and sovereign-backed launch providers anchor supply concentration, compressing pricing discipline through rideshare aggregation while fragmenting bargaining power across component tiers.
Pricing Analysis
Cost-down pressure on CubeSat platforms accelerates because SpaceX Transporter missions collapsed per-kilogram launch economics below five-figure thresholds. Three-tier pricing structure across dedicated launch, rideshare priority slots, and secondary payload standby positions separates defense agencies from commercial ventures from university consortia. Price differentiation hinges on ITAR certification requirements and guaranteed orbital parameter precision. Commercial Earth observation startups exhibit highest price sensitivity, while Space Force procurement tolerates premiums for classified payload security.
Supply Chain Analysis
Radiation-hardened electronics supply rests on defense-qualified foundries in the United States, commercial semiconductor packaging houses in Taiwan, and specialty solar cell manufacturers in Germany. Iodine-based propulsion systems draw from chemical processing clusters in France and Japan. Single-source vulnerability concentrates in radiation-tolerant FPGA supply. Distribution runs through prime contractors for defense programs and direct manufacturer relationships for commercial constellation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The small satellite sector sits in a propulsion-transition phase, with iodine-based electric thrusters displacing hydrazine systems and rewriting platform mass budgets.
For Market Incumbents: Acquire automated flight software capabilities to offset orbital mechanics talent scarcity threatening constellation design timelines. Consolidate ground station networks across multiple jurisdictions to reduce capital deployment burdens on early-stage operator balance sheets. Lockheed Martin and Northrop Grumman face margin compression from venture-backed analytics startups integrating machine learning pipelines into Earth observation subscriptions. For New Entrants and Emerging Players: The mid-tier pricing gap between premium defense-grade platforms and economy university CubeSats creates entry space for standardized NanoSat configurations serving precision agriculture. India's IN-SPACe framework offers the most penetrable regulatory environment for regional Earth observation constellations. Go-to-market positioning should emphasize subscription-based data licensing displacing per-image transactional sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor component specialists with radiation-hardened electronics capabilities in Germany and Japan during launch manifest priority bottlenecks. Long-term viability over a multi-year horizon depends on optical inter-satellite link integration for real-time data relay premiums. Monitor FCC debris mitigation rule tightening as the inflection signal for insurance cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Inter-Satellite Link Deployment | Laser communications terminals enable real-time data relay without ground station dependency for defense clients. |
| Iodine Propulsion System Integration | Non-toxic thrusters eliminate hydrazine handling infrastructure and reduce platform dry mass for larger payloads. |
| Automated Analytics Pipeline Development | Machine learning processing of hyperspectral imagery opens recurring-revenue contracts in carbon monitoring. |
| Ground Station Network Consolidation | Antenna coordination across jurisdictions strains early-stage balance sheets and favors scaled operators. |
| ITAR-Compliant Supply Chain Certification | Dual-use technology classifications create licensing friction for internationally sourced subsystems. |
Research Approach
Document review covered FCC Part 25 licensing records, Space Force procurement announcements, and ESA debris mitigation guidelines, complemented by interviews with constellation program managers, launch integration specialists, radiation-hardened component procurement leads, and Earth observation analytics directors. Secondary validation drew from FAA commercial launch databases, NASA Earth Science mission selections, and EU Space Surveillance and Tracking framework documentation. Bottom-up platform unit economics triangulated against top-down defense procurement budget allocations.
Unit shipment and revenue projections across the analysis window employed segmentation by platform mass class, application vertical, launch integration mode, and end-user procurement sophistication. CAGRs were derived from historical launch manifest growth rates and announced constellation deployment timelines. Industry-specific inputs included rideshare slot pricing trajectories, radiation-hardened component lead times, and subscription data licensing contract structures.
Inputs from classified defense program disclosures were available through the study window; gaps in specific Starshield contract values introduce uncertainty bands around national security revenue estimates. Forecasts reflect assumptions regarding FCC debris rule implementation timelines and IN-SPACe framework expansion velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Communication Satellite Launch Services Market
Satellite
Satellite Internet Market
Satellite
Satellite Transponder Market
Satellite
Middle East Satellite-Based Earth Observation Market
Satellite
China Satellite-Based Earth Observation Market
Satellite
China Satellite Imagery Services Market
Satellite
Airborne UHF-Band SATCOM Market
Satellite
Cubesat Market
Satellite
Satellite Broadband Market
Satellite
Satellite Payload Market
Satellite
Argentina Satellite-Based Earth Observation Market
Satellite
Remote Sensing Satellite Market
Satellite
All-Electric Propulsion Satellites Market
Satellite
India Satellite-Based Earth Observation Market
Satellite
Global Remote Sensing Services Market
Satellite
Low-Cost Satellite Market