
 Commercial Aircraft Leasing Market | 2026-2036
Commercial Aircraft Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Leasing Market Analysis
Premium-cabin specification tiers is collapsing into standardized configurations as lessors prioritize fleet fungibility and remarketing velocity. AerCap Holdings N.V. leverages its scale across wide-body and narrow-body platforms to sustain portfolio liquidity. SMBC Aviation Capital anchors its competitive position through concentrated exposure to next-generation single-aisle assets. BOC Aviation differentiates via direct manufacturer relationships and geographic diversification across Asia-Pacific and European flag carriers.
Commercial aircraft leasing denotes the provision of aviation assets under contractual arrangements where the lessor retains title while the lessee operates the equipment for defined periods, typically spanning 36 to 144 months with monthly rental payments indexed to LIBOR or SOFR benchmarks. The practice enables airlines to manage capacity without capital-intensive direct purchases, preserving liquidity for route expansion and operational expenditures. Operating lease structures command the largest share of new transactions as carriers seek off-balance-sheet treatment and residual risk transfer to lessors. Narrow-body aircraft generate the most competitive bidding among lessors due to liquid secondary markets and universal route applicability across low-cost and full-service carriers. Finance lease and sale-and-leaseback arrangements attract capital-constrained flag carriers requiring immediate liquidity injections while retaining operational control.
The FAA and EASA impose airworthiness and maintenance standards that lessors must embed in lease return conditions and technical acceptance protocols. ICAO's Carbon Offsetting and Reduction Scheme for International Aviation directly affects asset valuations by penalizing older-generation equipment and elevating demand for fuel-efficient replacements. Lessors must monitor how CORSIA phase-in timelines and EU ETS linkage reshape residual value curves and portfolio rebalancing cycles across their holdings.
Market Dynamics
ICAO's CORSIA phase-in is compressing residual values for older-generation wide-bodies while elevating lease rates for new-engine-option narrow-bodies, forcing lessors to accelerate portfolio turnover cycles.
Growth Catalysts
- India's UDAN scheme:Regional connectivity mandates are stimulating demand for 70-90 seat turboprop leases from regional carriers penetrating underserved secondary cities.
- SAF blending mandates:EU Green Deal aviation fuel requirements are accelerating lessor investment in next-generation assets compatible with higher sustainable aviation fuel concentrations.
- Vietnam's airport privatization:Long Thanh International Airport construction is unlocking fleet expansion capacity for Vietnamese carriers seeking operating lease structures.
Market Restraints
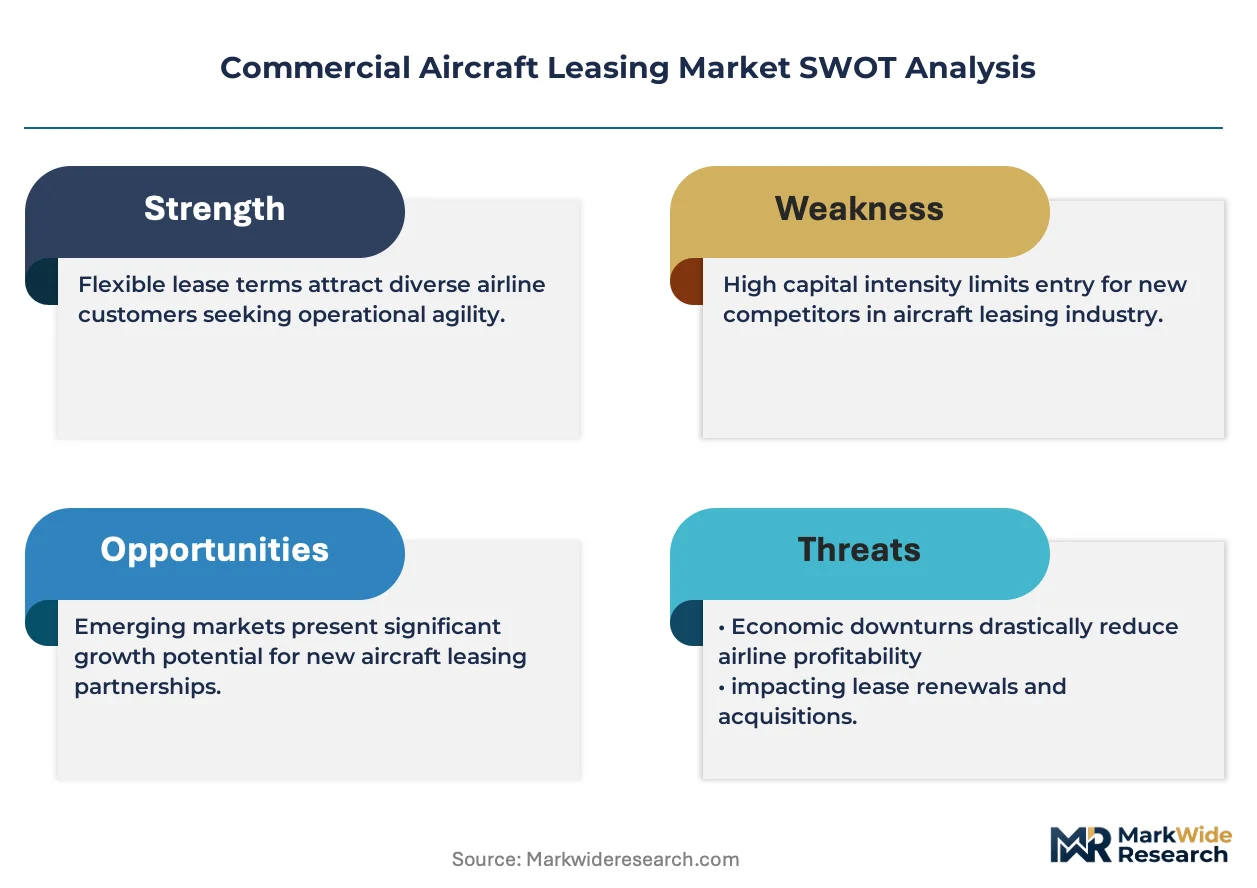
- Titanium supply concentration:Russian VSMPO-AVISMA dominance in aerospace-grade titanium creates input cost volatility and sanctions exposure for lessor-owned fleets requiring spare parts.
- EASA Part-147 training bottlenecks:Maintenance technician certification delays extend aircraft-on-ground periods and compress lessor yield during transition windows.
- Finance lease accounting changes:IFRS 16 implementation eliminated off-balance-sheet treatment advantages, reducing carrier appetite for traditional operating structures.
Strategic Opportunities
- Indonesia's LCC penetration:Lion Air Group and Citilink expansion into tertiary routes creates untapped demand for sale-and-leaseback transactions on A320neo family aircraft.
- Digital twin integration:Predictive maintenance platforms from GE Digital and Airbus Skywise are converging with blockchain lease records to enable usage-based rental pricing models.
- Japan's cargo conversion wave:Nippon Cargo Airlines and ANA Cargo are driving feedstock demand for P2F converted 767-300ERs as e-commerce volumes surge.
Industry Challenges
- Technical records standardization:IATA's Aircraft Leasing Guidance Material lacks universal adoption, creating due diligence friction during portfolio transfers between lessors.
- Green financing verification:Sustainability-linked loan structures require certified emissions data that engine OEMs are slow to provide for older lease portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Leasing Market |
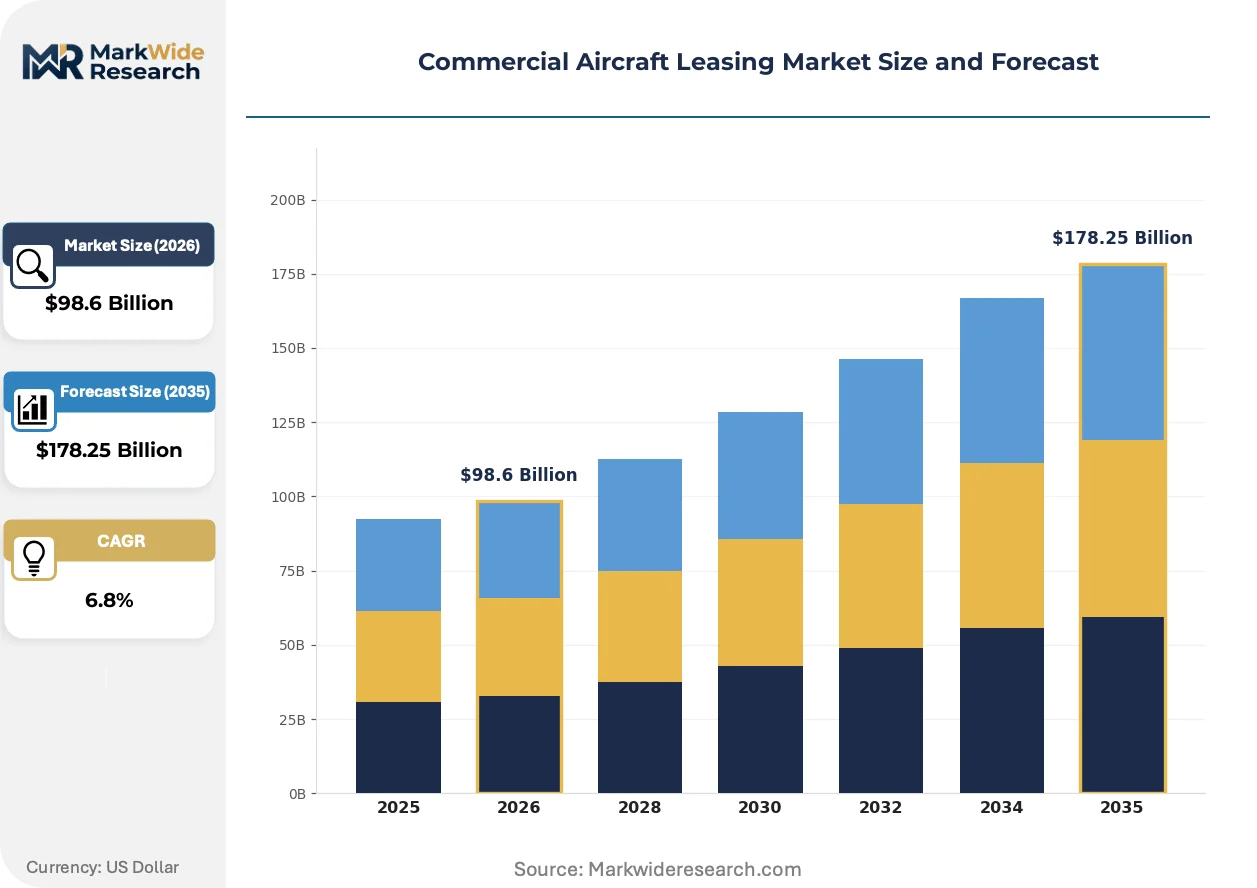
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lease Type: Operating Lease, Finance Lease, Sale and Leaseback, Wet Lease, Dry Lease Aircraft Type: Narrow-Body, Wide-Body, Regional Jets, Freighters, Business Jets Customer Category: Flag Carriers, Low-Cost Carriers, Charter Operators, Cargo Operators, Leasing Companies Lease Duration: Short-Term, Medium-Term, Long-Term, Flexible-Term |
| Companies Covered | Air Lease Corporation, BBAM Aircraft Leasing & Management, AerCap Holdings N.V., Dubai Aerospace Enterprise, ICBC Leasing, SMBC Aviation Capital, BOC Aviation, AviLease, Avolon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Leasing Market Emerging Trajectories
Asset management platforms are displacing spreadsheet-based lease administration as portfolio complexity exceeds manual tracking capacity, while sustainability metrics penetrate every stage of aircraft procurement.
Artificial intelligence-driven residual value forecasting is bifurcating lessor capabilities between scaled operators with proprietary data lakes and mid-tier competitors dependent on broker estimates. AerCap and SMBC Aviation Capital deploy machine learning models trained on 20-plus years of maintenance cost curves and part-out yields. This capability compression is widening bid-ask spreads in secondary trading and concentrating deal flow among data-rich participants.
EU ETS linkage with CORSIA baseline-setting is tightening emissions monitoring requirements for lessors with European-registered assets or lessees operating intra-EU routes. The European Commission's delegated acts now require verified CO2 reporting for leased aircraft above 5,700 kg maximum takeoff weight. Lessors with Dublin and Amsterdam offices face immediate compliance costs, while Asian-flagged competitors gain temporary arbitrage advantages in cross-border lease structuring.
Carrier procurement departments are consolidating vendor relationships and demanding bundled offerings spanning airframes, engines, and flight-hour support. Singapore Airlines and AirAsia Group now issue single RFPs covering 15-year operating leases with power-by-the-hour attachments. This vendor reduction is squeezing independent engine lessors and forcing airframe lessors into vertical partnerships with MRO providers across Southeast Asian hubs.
Commercial Aircraft Leasing Market Segmentation
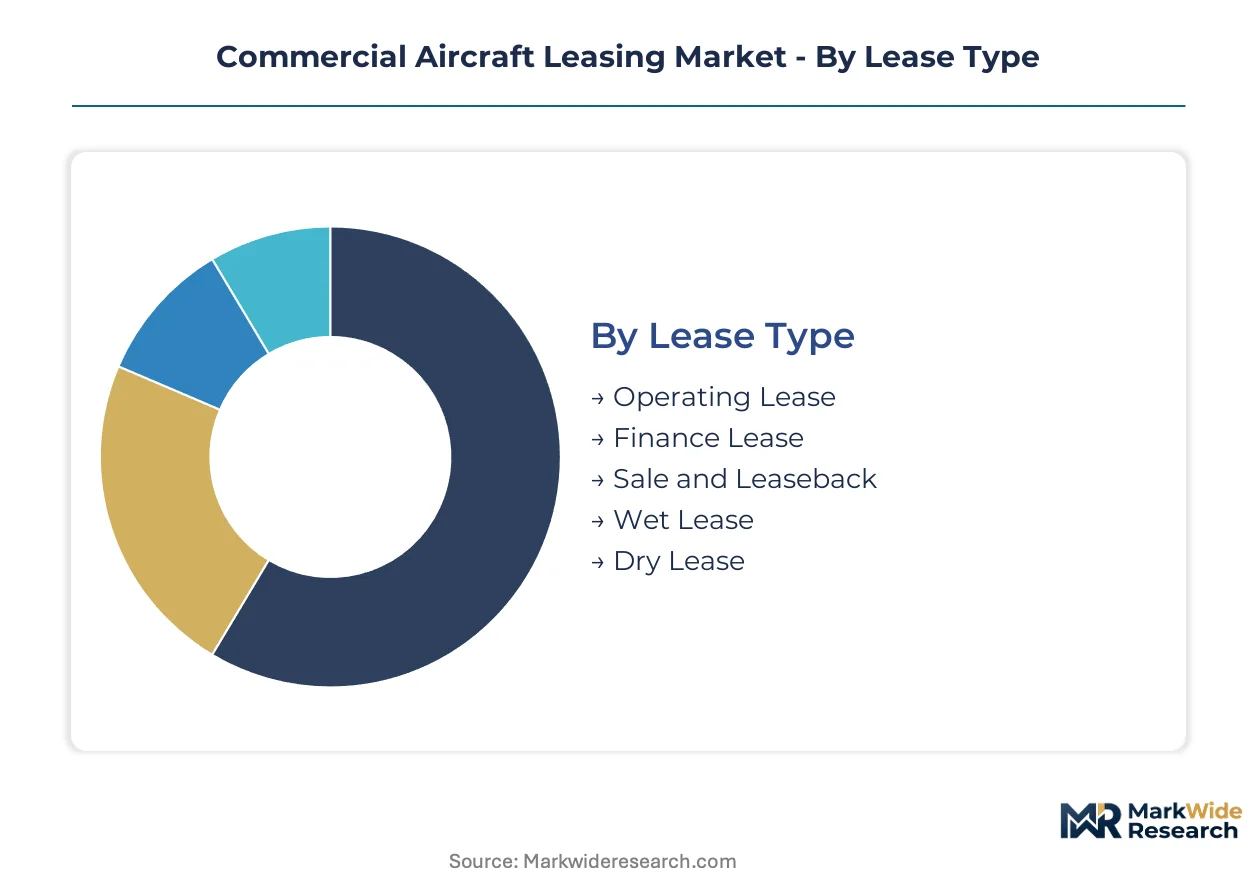
Aircraft leasing segmentation reveals how lessor portfolios balance liquidity against residual risk exposure. Structural differences in lease type and aircraft category determine financing costs, remarketing velocity, and regulatory compliance burdens across operator portfolios.
Lease Type:
Operating lease structures dominate cross-border transactions, while finance leases concentrate in domestic-flag carrier relationships where balance sheet treatment matters less than capital access.
- Operating Lease:Lessors retain residual value risk and title, enabling off-balance-sheet treatment for carriers. Demand concentrates in India and Vietnam as domestic aviation infrastructure scales rapidly, with UDAN scheme regional carriers seeking 36-60 month terms for turboprop assets.
- Finance Lease:Lessees assume depreciation and residual risk through capital lease structures. Flag carriers in capital-constrained markets favor these arrangements for immediate liquidity injections while retaining operational control over wide-body fleets.
- Sale and Leaseback:Airlines monetize owned assets to lessors, then lease back for operational use. Lion Air Group and Citilink in Indonesia deploy this structure to fund A320neo expansion into tertiary routes.
- Wet Lease:Lessors provide aircraft plus crew, maintenance, and insurance under ACMI arrangements. Charter operators and seasonal carriers deploy wet leases to cover Hajj pilgrimage peaks and European summer slot constraints.
- Dry Lease:Carriers receive airframe and engines only, supplying their own flight and ground crews. Low-cost carriers across Southeast Asia prefer dry leases for narrow-body fleets to maintain operational autonomy and crew cost discipline.
Operating lease commands the established base. The steepest expansion runs through sale-and-leaseback as carriers prioritize liquidity preservation over asset ownership.
Aircraft Type:
Cost tier stratification separates liquid narrow-body assets with universal route applicability from specialized wide-bodies facing compressed residual curves under CORSIA mandates.
- Narrow-Body:Single-aisle configurations from A320neo and 737 MAX families generate the most competitive lessor bidding due to liquid secondary markets. SMBC Aviation Capital anchors its competitive position through concentrated exposure to these next-generation assets.
- Wide-Body:Twin-aisle aircraft serve long-haul trunk routes but face residual value compression as ICAO carbon offset mandates penalize older-generation equipment. AerCap Holdings N.V. leverages its scale across both wide-body and narrow-body platforms to sustain portfolio liquidity.
- Regional Jets:70-90 seat turboprops and regional jets serve secondary city pairs below narrow-body economic thresholds. India's UDAN scheme stimulates dedicated demand for this segment from carriers penetrating underserved markets.
- Freighters:Converted and factory-built cargo aircraft feed e-commerce volume growth. Nippon Cargo Airlines and ANA Cargo drive feedstock demand for P2F converted 767-300ERs as Japanese e-commerce volumes surge.
- Business Jets:Corporate and VIP-configured aircraft operate outside scheduled airline networks. Charter operators and high-net-worth individuals source these through specialized lessors with dedicated maintenance support infrastructure.
Narrow-body assets command the established base. The steepest expansion runs through freighters as air cargo capacity struggles to match e-commerce growth trajectories.
Customer Category:
Application-based segmentation distinguishes network carriers with route authority constraints from price-sensitive operators pursuing unbundled service models.
- Flag Carriers:Full-service airlines with government ownership or historical route monopolies. Singapore Airlines issues bundled RFPs covering 15-year operating leases with power-by-the-hour engine support attachments.
- Low-Cost Carriers:Unbundled fare structures and high aircraft utilization define this segment. AirAsia Group consolidates vendor relationships and demands integrated offerings spanning airframes, engines, and flight-hour support across Southeast Asian hubs.
- Charter Operators:Seasonal and ad-hoc service providers serving tourism peaks, corporate travel, and government contracts. Wet lease structures dominate their procurement to match capacity with volatile demand patterns.
- Cargo Operators:Dedicated freight carriers and integrated express networks. Long Thanh International Airport construction in Vietnam unlocks fleet expansion capacity for cargo operators seeking operating lease structures.
- Leasing Companies:Specialized lessors and bank-affiliated platforms that acquire and sub-lease aircraft. BOC Aviation differentiates via direct manufacturer relationships and geographic diversification across Asia-Pacific and European flag carriers.
Flag carriers command the established base. The steepest expansion runs through low-cost carriers as unbundled service models capture rising middle-class air travel across Southeast Asia.
Lease Duration:
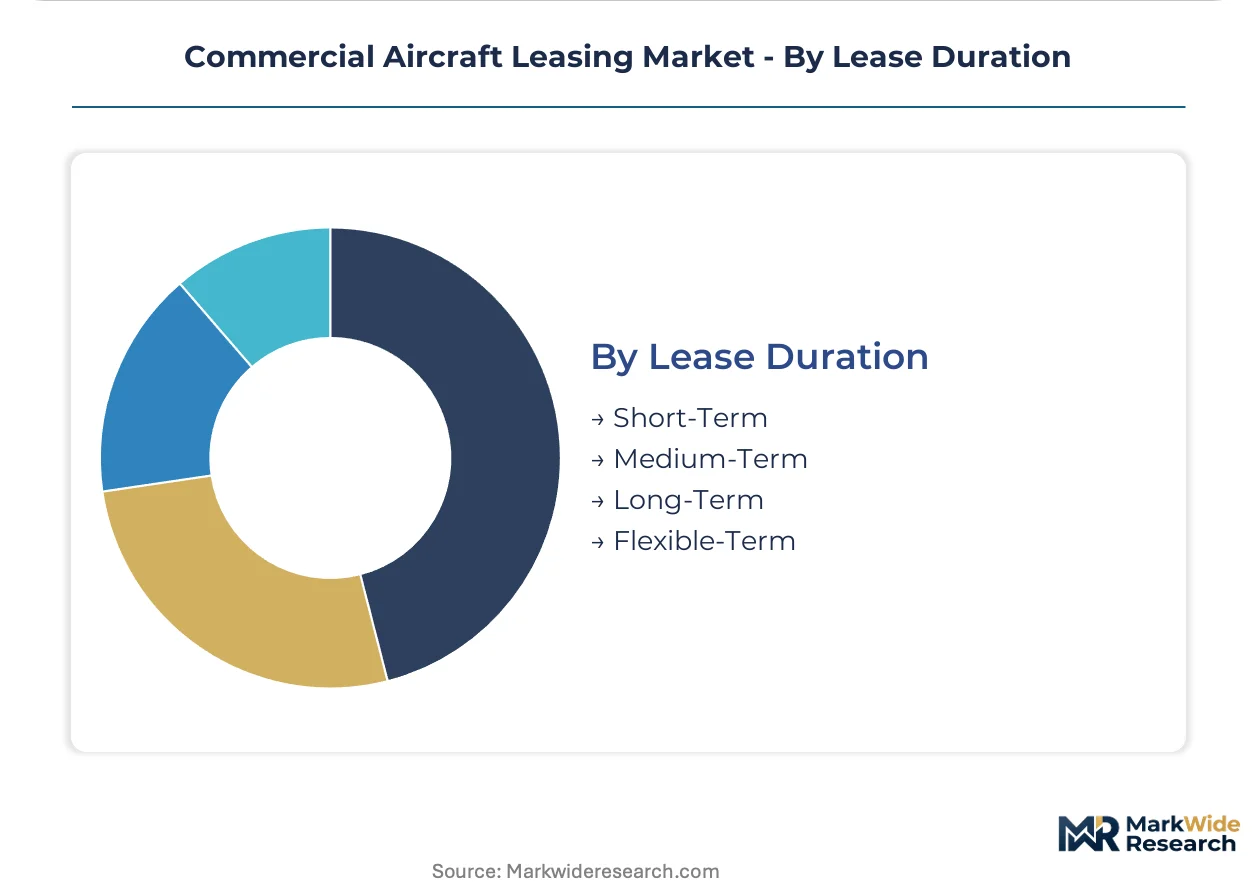
Volume concentration varies by maturity tier, with medium-term structures capturing the bulk of new transactions while flexible arrangements serve market entry and exit transitions.
- Short-Term:Sub-12 month arrangements cover seasonal peaks, new route testing, and maintenance bridging. Hajj operators and European summer charter carriers deploy these to avoid year-round fixed costs.
- Medium-Term:36-84 month contracts represent the standard operating lease structure. Monthly rental payments index to LIBOR or SOFR benchmarks, with return conditions embedded per FAA and EASA airworthiness standards.
- Long-Term:120-144 month commitments approach economic life limits and resemble finance lease economics. Carriers with stable route authorities and credit profiles negotiate these for new-generation narrow-bodies with predictable residual curves.
- Flexible-Term:Extension options, early return clauses, and purchase rights embedded in master lease agreements. These structures attract carriers facing regulatory uncertainty from CORSIA phase-in timelines and EU ETS linkage effects.
Medium-term structures command the established base. The steepest expansion runs through flexible-term arrangements as carriers seek to rebalancing cycles amid emissions policy volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital flows into commercial aircraft leasing tilt toward import-dependent aviation markets where carriers lack indigenous manufacturing capacity. Export concentration remains minimal given the asset-heavy nature of lessor operations.
India
UDAN regional connectivity mandates stimulate turboprop lease demand from carriers penetrating underserved secondary cities. The Directorate General of Civil Aviation enforces stringent airworthiness standards that lessors embed in technical acceptance protocols. Mumbai and Delhi anchor leasing activity as IndiGo and Air India expand narrow-body fleets through operating structures.
Vietnam
Long Thanh International Airport construction unlocks fleet expansion capacity for Vietnamese carriers seeking lease structures. The Civil Aviation Authority of Vietnam aligns with ICAO CORSIA timelines to shape emissions compliance requirements. Ho Chi Minh City concentrates lessor attention as VietJet and Vietnam Airlines negotiate next-generation single-aisle placements.
United States
Major carriers deploy sale-and-leaseback transactions to monetize owned assets while preserving liquidity for network restructuring. FAA airworthiness directives on 737 MAX return-to-service influence lease return condition negotiations. Miami and Los Angeles serve as technical acceptance hubs where lessors coordinate maintenance bridging for cross-border transitions.
Ireland
Dublin-based lessors leverage regulatory arbitrage from EU ETS compliance costs affecting European-registered assets. The Irish Aviation Authority maintains bilateral agreements with EASA that streamline technical records standardization. Shannon and Dublin offices concentrate portfolio management functions for Asia-Pacific and European flag carrier relationships.
Japan
Nippon Cargo Airlines and ANA Cargo drive feedstock demand for P2F converted 767-300ERs as e-commerce volumes surge. METI guidelines on sustainable aviation fuel blending influence lessor investment in next-generation asset compatibility. Tokyo anchors leasing documentation activity while Osaka-Kansai serves as maintenance transition coordination points.
Commercial Aircraft Leasing Market Vendor Landscape
Listed leaders compete with private specialists across balance sheet capacity and portfolio diversification dimensions. Consolidation around scaled platforms with manufacturer direct relationships has compressed mid-tier participation in primary transactions. Three archetypes dominate: bank-affiliated lessors leveraging captive financing, independent platforms optimizing remarketing velocity, and sovereign wealth-backed entities prioritizing long-dated yield. Competitive moves concentrate on portfolio rebalancing toward next-generation narrow-bodies and geographic diversification into Southeast Asian growth corridors.
Within the bank-affiliated tier, ICBC Leasing and BOC Aviation exemplify state-backed platforms with direct manufacturer relationships spanning Asia-Pacific flag carriers. SMBC Aviation Capital occupies a concentrated position in next-generation single-aisle assets. AerCap Holdings N.V. anchors the independent scale vector across wide-body and narrow-body platforms. These entities represent divergent approaches to residual risk management and remarketing infrastructure deployment.
| Leading Market Players |
|---|
| Air Lease Corporation |
| BBAM Aircraft Leasing & Management |
| AerCap Holdings N.V. |
| Dubai Aerospace Enterprise |
| ICBC Leasing |
| SMBC Aviation Capital |
| BOC Aviation |
| AviLease |
| Avolon |
| Others |
Supply Flow & Price Mechanics
Eighteen-month engine delivery backlogs from Pratt & Whitney and CFM International concentrate pricing power with OEMs while forcing lessors to absorb pre-delivery payment escalation clauses. This lead-time compression reshapes portfolio acquisition economics and squeezes yield margins across operating lease structures.
Pricing Analysis
Flag carrier procurement departments anchor lease rate negotiations through bundled RFPs spanning airframes, engines, and flight-hour support attachments. Pricing stratifies across new-generation narrow-bodies, current-generation assets, and end-of-life feedstock tiers based on CORSIA compliance status and residual value certainty. Cost compression in wide-body leasing runs from accelerated residual value decline as ICAO carbon offset mandates penalize older-generation equipment. Low-cost carriers exhibit highest price sensitivity due to unbundled fare structures and thin operating margins, while sovereign wealth-backed flag carriers prioritize fleet standardization over rate minimization.
Supply Chain Analysis
Titanium sponge processing concentration in Russia and Japan creates single-source vulnerability for lessor-owned fleets requiring aerospace-grade fasteners and engine components. Boeing and Airbus final assembly lines in the United States, France, and China draw from concentrated supplier bases for avionics, landing gear, and composite structures. Tariff exposure on Chinese-sourced aerostructures feeds from ongoing trade policy volatility between Washington and Beijing. Distribution runs through manufacturer-direct placements for new aircraft and specialized brokers for secondary market transitions, with Dublin and Singapore anchoring documentation and technical acceptance coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial aircraft leasing fragments across specialized lessor archetypes as carrier procurement consolidation creates tiered service gaps between scaled platforms and mid-tier operators. UDAN scheme regional connectivity mandates in India and Vietnam generate underserved demand niches for turboprop specialists and short-term operating lease providers.
For Market Incumbents: Consolidate portfolio management infrastructure around predictive maintenance data partnerships with GE Digital and Airbus Skywise to defend against AI-driven residual value forecasting advantages held by AerCap and SMBC Aviation Capital. Acquire technical records standardization capabilities to reduce due diligence friction during portfolio transfers, addressing IATA Aircraft Leasing Guidance Material adoption gaps that extend transaction timelines. For New Entrants and Emerging Players: Anchor in Indonesia's Lion Air Group and Citilink sale-and-leaseback pipeline for A320neo family placements, where incumbent concentration in next-generation narrow-bodies leaves tertiary route expansion underserved. Target wet lease structuring for Hajj pilgrimage operators and European summer charter carriers facing seasonal capacity gaps, deploying ACMI arrangements with embedded crew and maintenance provisions to differentiate from dry lease commodity providers. For Investors and Strategic Acquirers: Carve-out targets emerge from bank-affiliated lessors seeking to divest non-core aviation holdings amid Basel III capital constraint pressures. Long-term viability rests on portfolio exposure to CORSIA-compliant assets with verified emissions data and SAF blending compatibility. Monitor EU ETS delegated act enforcement timelines as inflection indicator for Dublin-registered lessor compliance cost advantages eroding against Asian-flagged competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Rebalancing Toward Next-Generation Narrow-Bodies | SMBC Aviation Capital concentrates exposure in A320neo and 737 MAX families to capture liquid secondary market demand. |
| Digital Twin Integration with Blockchain Lease Records | GE Digital and Airbus Skywise platforms enable usage-based rental pricing models that compress transition yield loss. |
| Direct Manufacturer Relationship Deepening | BOC Aviation leverages Boeing and Airbus partnerships to secure delivery slot priority and customization flexibility. |
| Sustainability-Linked Financing Structure Deployment | Green loan certification requires engine OEM emissions data that reshapes residual value curves across lease portfolios. |
| Geographic Diversification into Southeast Asian Growth Corridors | Vietnam's Long Thanh International Airport construction unlocks fleet expansion capacity for Vietnamese carrier placements. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with aircraft leasing executives, airline fleet planning directors, and aviation finance attorneys, combined with secondary validation against FAA airworthiness directives, EASA certification databases, and ICAO CORSIA implementation timelines. Lessors, MRO providers, and engine OEM technical sales teams supplied operational cost curves and part-out yield benchmarks. Trade flow data from customs authorities, lessor SEC filings, and manufacturer delivery disclosures enabled bottom-up fleet composition analysis cross-checked against top-down market sizing from aviation consultancy production forecasts.
Across the analysis window, the forecasting framework modeled lease transaction volumes by aircraft type, lease structure, customer category, and regional regulatory cluster. CAGRs derived from manufacturer delivery backlogs, carrier order conversion rates, and lessor placement velocity assumptions. Forecast inputs incorporated UDAN scheme regional connectivity mandate expansion timelines, EU ETS linkage effects on asset valuations, and titanium supply concentration risk scenarios affecting maintenance cost projections.
Decision-makers should treat outputs as directional under base assumptions of sustained middle-class air travel growth across Southeast Asia and phased CORSIA implementation without regulatory acceleration; material deviation in emissions policy stringency or macroeconomic contraction would warrant model refresh. Practitioners should keep alternative scenarios live as SAF blending mandate enforcement and Russian titanium supply disruption risks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Military Aircraft Market
Aircraft
Utility Aircraft Market
Aircraft
Europe Aviation Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
Electric Aircraft Market
Aircraft
Aircraft Flight Control System Market
Aircraft
Evtol Aircraft Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
Aircraft Cargo Container Market
Aircraft
Freighter Aircraft Market
Aircraft
Search and Rescue Aircraft Market
Aircraft
Military Helicopters Market
Aircraft
Aircraft Seals Market
Aircraft
Aerospace Winglet System Market
Aircraft
Aircraft Pushback Tugs Market
Aircraft
North America Aviation Market