
 Satellite Transponder Market | 2026-2036
Satellite Transponder Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Transponder Market Intelligence
Project finance structures with long-term capacity pre-commitments are reshaping competitive entry in satellite transponder services. Intelsat leverages its geostationary fleet scale to anchor enterprise and government contracts across multiple orbital slots. SES S.A. sustains differentiated positioning through its medium earth orbit O3b constellation, which competes on latency against traditional geostationary offerings.
A satellite transponder functions as a communication relay device aboard an orbital platform, receiving uplink signals in one frequency band, amplifying them through solid-state or traveling wave tube power amplifiers, and downconverting for retransmission to ground terminals. Its primary commercial purpose is to enable long-distance signal distribution for television broadcasting, maritime connectivity, and backhaul services where terrestrial infrastructure proves uneconomical. Ku-band transponders occupy the largest share of lease revenue given their established role in direct-to-home television distribution, while Ka-band capacity represents the fastest-expanding segment as high-throughput satellite designs displace legacy wide-beam architectures. Managed services are capturing disproportionate margin pools as operators bundle ground segment integration and network management with raw transponder capacity.
The FCC in the United States and India's TRAI are compressing C-band spectrum availability through reallocation mandates, forcing operators toward Ka-band and higher-frequency assets that demand redesigned ground terminals. The International Telecommunication Union coordinates orbital slot registration and interference standards, shaping market access for new constellation entrants and national operators alike. Stakeholders must monitor spectrum auction outcomes and national security screening thresholds for foreign satellite operators, as these will determine which fleet operators can secure anchor tenancy contracts in protected government and defense verticals.
Market Dynamics
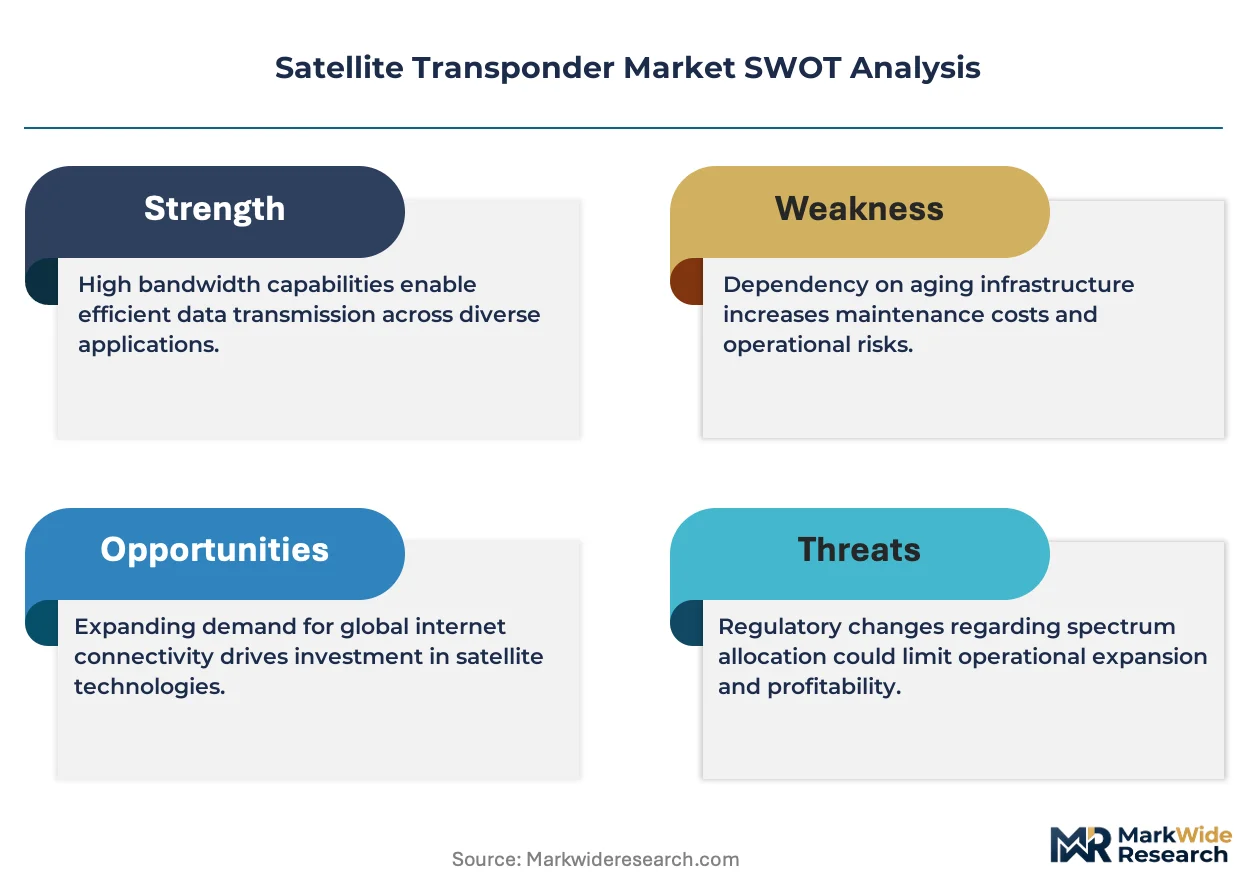
Spectrum reallocation mandates from the FCC and India's TRAI are compressing C-band availability and forcing operators toward Ka-band migration, fundamentally restructuring capacity economics and ground terminal requirements across the satellite transponder services sector.
Growth Catalysts
- Rural Broadband Programs:Brazil's government connectivity initiatives are accelerating transponder lease agreements to close infrastructure gaps in remote municipalities.
- Ku-band Expansion:Broadcasting companies in emerging markets are scaling Ku-band capacity for direct-to-home television distribution.
- High-Throughput Satellite Designs:Ka-band architectures are displacing legacy wide-beam systems, unlocking new enterprise and maritime connectivity contracts.
Market Restraints
- Ground Terminal Redesign Costs:Ka-band migration demands redesigned customer premises equipment, raising capital barriers for smaller operators.
- Orbital Slot Scarcity:The International Telecommunication Union's interference coordination rules limit market access for new constellation entrants.
- Solid-State Amplifier Supply:Traveling wave tube power amplifier manufacturing concentrates among a handful of specialized vendors.
Strategic Opportunities
- Managed Services Bundling:Ground segment integration and network management services are capturing disproportionate margin pools beyond raw capacity.
- Maritime Connectivity:Cruise lines and commercial shipping fleets are expanding demand for low-latency backhaul solutions.
- National Security Screening Thresholds:Foreign operator restrictions in the United States are creating protected anchor tenancy channels for domestic fleet operators.
Industry Challenges
- RF Engineering Talent:Specialized microwave and satellite communications expertise remains scarce relative to constellation deployment timelines.
- Legacy System Integration:Ka-band high-throughput satellites must interoperate with existing Ku-band ground infrastructure during transition periods.
- Interference Mitigation:Co-frequency coordination between geostationary and non-geostationary constellations complicates network planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Transponder Market |
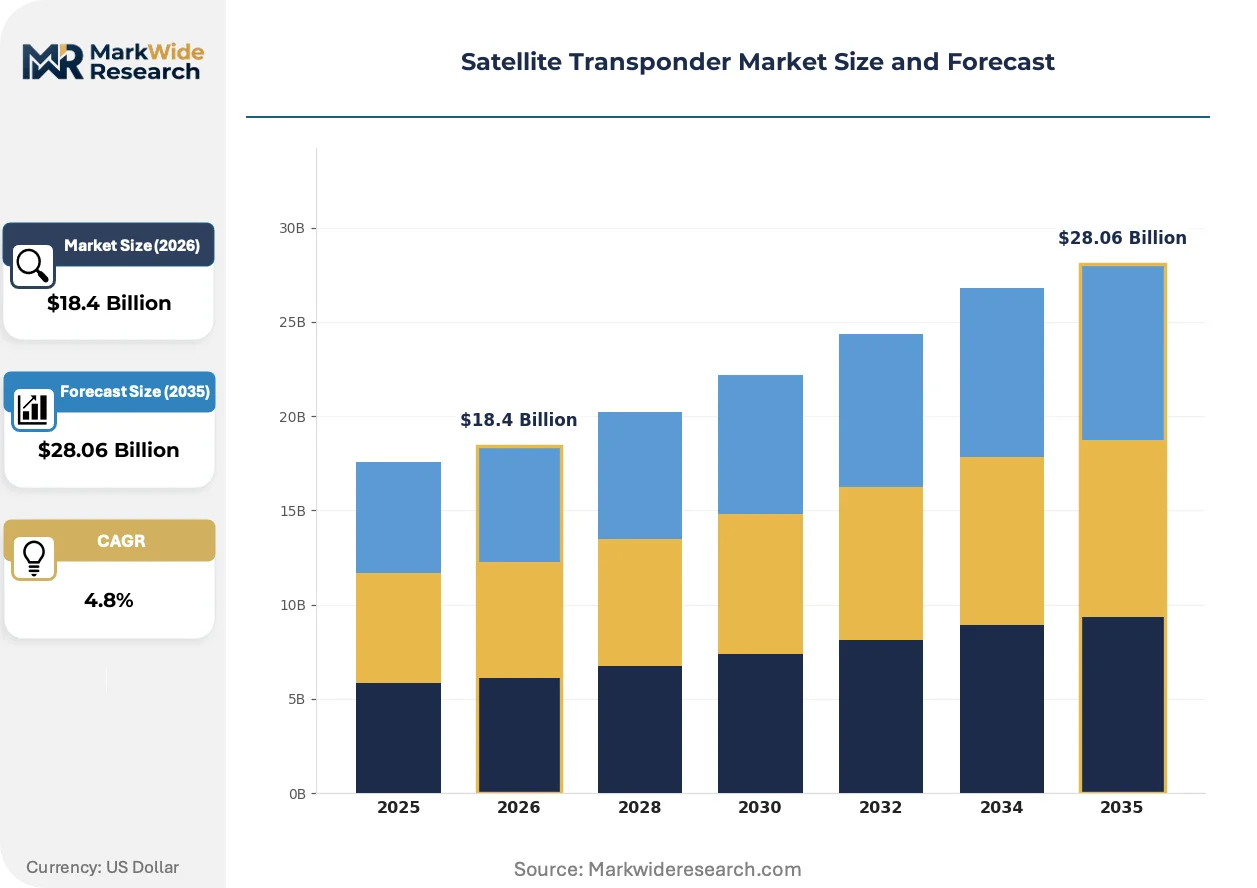
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $28.06 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ku-band, Ka-band, C-band, L-band Application: Broadcasting, Communication, Data Transfer, Government End User: Telecom Providers, Broadcasting Companies, Defense, Aerospace Service Type: Lease, Managed Service, Resale, Ancillary |
| Companies Covered | Viasat, EchoStar Corporation, Intelsat, Starlink, Iridium Communications, SES S.A., Telesat, Globalstar, Eutelsat Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Transponder Market Strategic Shifts & Innovations
Digital payload architectures and software-defined transponders are enabling dynamic bandwidth allocation, reshaping how satellite operators monetize orbital capacity and respond to demand fluctuations.
Software-defined radio transponders are collapsing the traditional hardware-locked frequency plan model. Maritime and aeronautical end-users are adopting these platforms fastest, drawn by real-time beam steering capabilities. This technology is collapsing the distinction between fixed satellite service and mobile satellite service business models.
The FCC's C-band clearing mandate is forcing accelerated spectrum repacking across the United States. Satellite operators must relocate services to compressed upper spectrum while maintaining service continuity for broadcast and government customers. Cable headends and radio observatories in the United States are bearing the highest retuning costs and timeline pressures.
Capacity buyers are consolidating procurement around long-term pre-commitment structures with embedded service-level agreements. Enterprise and government verticals are displacing spot-market leasing with managed network contracts that bundle transponder access, hub operation, and field maintenance. Brazil and India exhibit the strongest pivot toward outcome-based connectivity purchasing.
Satellite Transponder Market Segmentation
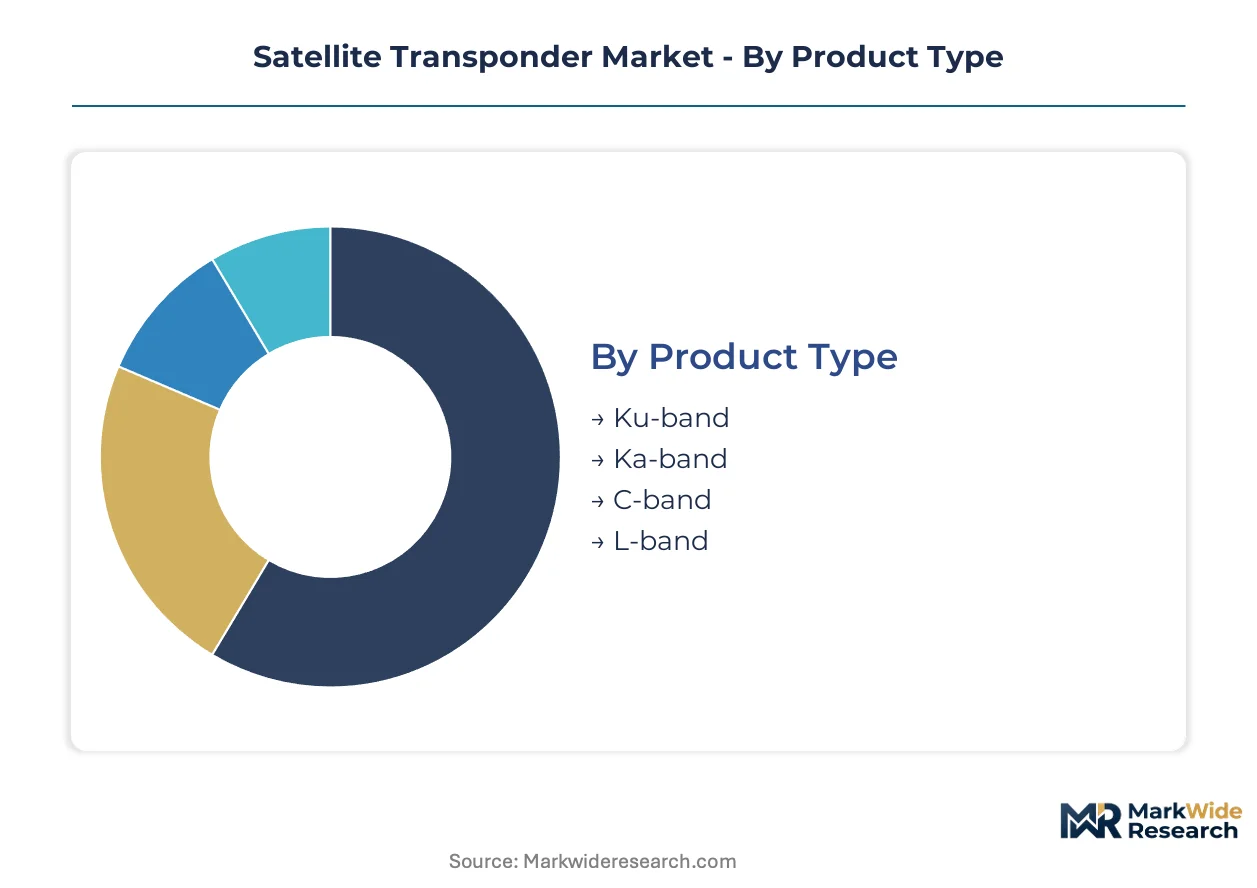
Satellite transponder markets segment across frequency bands, service models, and vertical applications that carry fundamentally different margin profiles and contract durations. Understanding these divisions reveals where capacity commoditizes versus where specialized engineering commands premium pricing.
Product Type:
Ku-band transponders turn over fastest on spot markets while Ka-band capacity locks into longer-term managed service agreements with embedded technology refresh clauses.
- Ku-band:These transponders operate in the 12-18 GHz range with established traveling wave tube amplifier technology. Broadcasting companies in Brazil and India are expanding Ku-band leases for direct-to-home television distribution as C-band spectrum compresses under regulatory mandates.
- Ka-band:High-throughput satellite designs in this 26.5-40 GHz band enable spot-beam architectures with frequency reuse. Rural broadband programs across multiple geographies are accelerating procurement of Ka-band capacity where terrestrial fiber deployment proves uneconomical.
- C-band:Traditional 4-8 GHz transponders face accelerated phase-out as the FCC and India's TRAI reallocate spectrum for terrestrial 5G services.
- L-band:Lower frequency 1-2 GHz transponders serve maritime and aeronautical mobile applications with superior signal penetration through weather and foliage.
Ku-band dominates installed base. Ka-band is where expansion concentrates.
Application:
Broadcasting applications carry the longest contract tenors while data transfer segments exhibit the most volatile spot-market pricing.
- Broadcasting:Direct-to-home television distribution remains the anchor revenue stream for geostationary fleet operators. Emerging market broadcasters in Brazil and India are pre-committing transponder capacity five to seven years forward to secure orbital slots.
- Communication:Enterprise backhaul and trunking services connect remote offices and cellular towers where fiber cannot reach. Maritime connectivity demand from cruise lines and commercial shipping fleets is climbing the fastest within this segment.
- Data Transfer:Cloud connectivity and internet exchange point extension services require low-latency paths that medium earth orbit constellations increasingly challenge.
- Government:Military and civilian agency contracts embed national security screening requirements that restrict foreign operator participation in the United States.
Broadcasting anchors revenue stability. Data transfer is where technology disruption concentrates.
End User:
Defense procurement cycles stretch across decade-long satellite service partnerships while telecom provider contracts reprice more frequently.
- Telecom Providers:Mobile network operators lease transponder capacity for rural base station backhaul and emergency network restoration. Brazilian carriers are expanding commitments under government connectivity mandates.
- Broadcasting Companies:Direct-to-home platform operators and cable headends require redundant capacity for signal distribution. The FCC's C-band clearing mandate is forcing these customers to absorb retuning costs and timeline pressures.
- Defense:Military end users demand protected frequency bands and anti-jam capabilities that command substantial premiums over commercial capacity.
- Aerospace:Commercial aviation connectivity providers integrate satellite links into passenger entertainment and cockpit communication systems.
Telecom providers dominate volume procurement. Defense is where margin expansion concentrates.
Service Type:
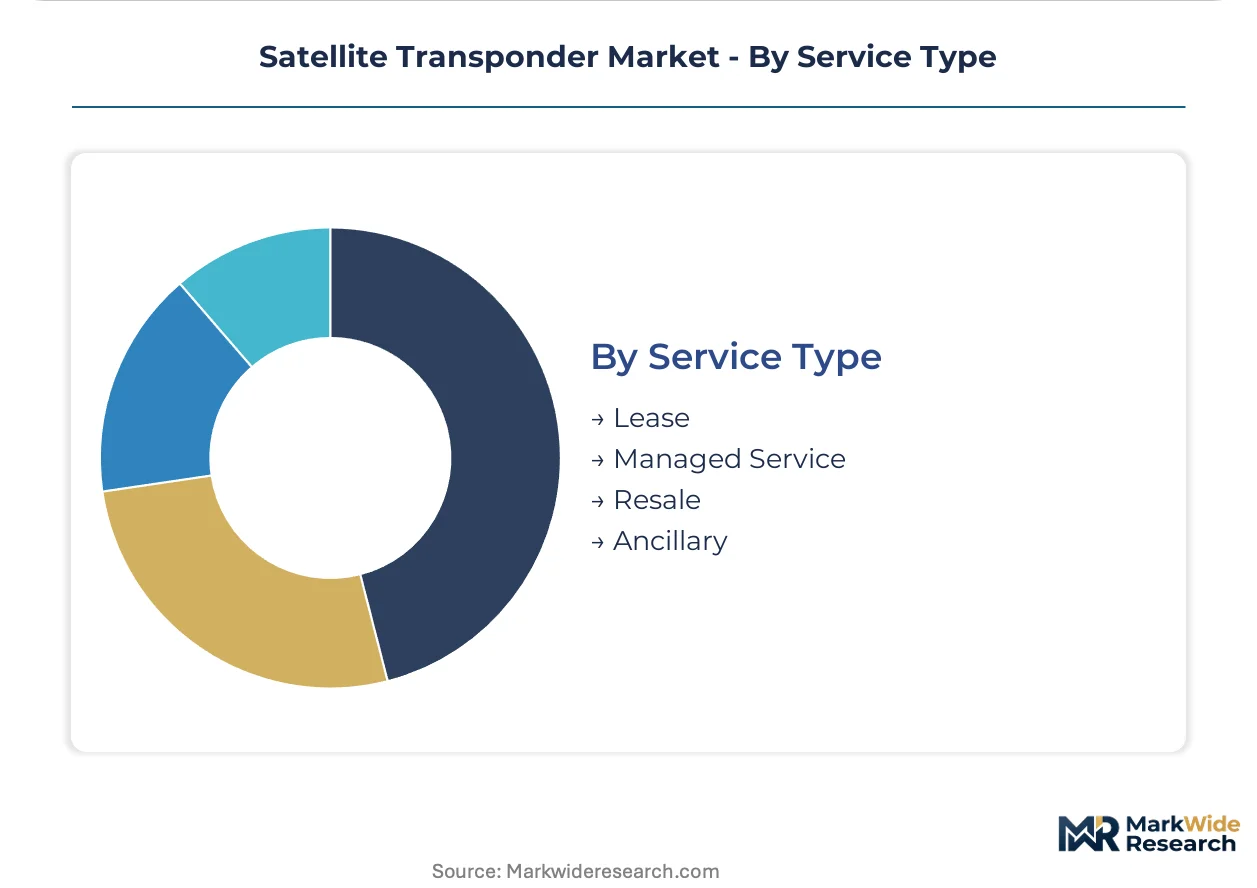
Raw lease arrangements commoditize fastest while managed services build sustainable differentiation through operational integration.
- Lease:Traditional transponder capacity agreements provide bandwidth without ground segment responsibility. Spot-market leasing faces pressure as enterprise buyers consolidate procurement around longer-term structures.
- Managed Service:Bundled offerings combine orbital capacity with hub operation, network management, and field maintenance. Brazil and India exhibit the strongest pivot toward outcome-based connectivity purchasing in this category.
- Resale:Capacity aggregators purchase wholesale transponder space and repackage for niche verticals or geographic markets.
- Ancillary:Professional services including frequency coordination, interference mitigation, and regulatory compliance support.
Lease structures dominate current revenue. Managed service is where strategic positioning concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transponder capacity flows from orbital slot holders toward ground infrastructure builders, with net importers clustering in emerging markets lacking indigenous fleet operators. Exporting economies anchor manufacturing and launch services while importing regions concentrate on downstream service integration.
United States
The FCC's C-band clearing mandate is compressing legacy spectrum availability while accelerating Ka-band ground terminal deployment. Government connectivity contracts embed national security screening thresholds that restrict foreign operator participation. California hosts the densest cluster of satellite manufacturers and network integrators, with Los Angeles-area facilities supplying payload components to geostationary fleet operators.
Brazil
Rural broadband gaps and government connectivity programs are accelerating transponder lease agreements across remote municipalities. ANATEL spectrum coordination rules shape market access for international fleet operators seeking anchor tenancy. São Paulo anchors the national broadcasting sector, where direct-to-home platform operators pre-commit capacity five to seven years forward to secure distribution rights.
India
TRAI reallocation mandates are pushing operators toward Ka-band migration as C-band availability compresses under 5G spectrum pressure. The Department of Space oversees orbital slot registration through the Indian National Satellite System framework. Gujarat and Karnataka host the principal ground segment manufacturing clusters, with Ahmedabad and Bengaluru facilities producing hub equipment for domestic and export markets.
Germany
Enterprise backhaul demand from automotive and industrial verticals is sustaining Ku-band capacity commitments despite Ka-band transition pressures. The national regulatory authority coordinates frequency assignments under EU spectrum harmonization directives. Bavaria concentrates the European satellite services sector, with Munich-area operators managing broadcast distribution contracts across Central and Eastern European markets.
United Arab Emirates
Government and defense verticals are expanding managed service procurement with embedded service-level agreements and technology refresh clauses. The national telecommunications regulator oversees spectrum coordination across C, Ku, and Ka bands for both commercial and sovereign applications. Dubai anchors the regional satellite services hub, with ground facilities serving maritime and aeronautical connectivity contracts spanning the Indian Ocean corridor.
Satellite Transponder Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying traveling wave tube amplifiers and solid-state power modules. The vendor base organizes around three tiers: geostationary fleet operators with multi-orbital slot holdings, medium earth orbit constellation deployers competing on latency, and ground segment integrators bundling hub operation with raw capacity. Competitive moves concentrate on long-term capacity pre-commitments with embedded service-level agreements and strategic partnerships linking satellite operators with terrestrial network providers.
Within the geostationary fleet tier, Intelsat and SES S.A. occupy positions as scale-driven incumbents anchoring enterprise and government contracts across multiple orbital slots. Viasat exemplifies the high-throughput satellite archetype, with Ka-band spot-beam architectures displacing legacy wide-beam systems in rural broadband and maritime connectivity verticals. These three entities represent the dominant competitive positioning patterns visible across the named player set.
| Leading Market Players |
|---|
| Viasat |
| EchoStar Corporation |
| Intelsat |
| Starlink |
| Iridium Communications |
| SES S.A. |
| Telesat |
| Globalstar |
| Eutelsat Communications |
| Others |
Cost & Logistics Intelligence
Intelsat's Luxembourg-anchored logistics corridor moves traveling wave tube amplifiers and solid-state power modules across Atlantic shipping lanes, with freight cost volatility feeding directly into Ka-band ground terminal pricing tiers and compressing margins for smaller operators unable to negotiate volume scale.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock capacity five to seven years forward. Price differentiation stems from certification grade under FCC and ITU interference standards plus geographic delivery cost to remote orbital ground stations. Pricing pressure stems from C-band spectrum compression forcing accelerated Ka-band migration with expensive terminal redesigns. Telecom providers exhibit highest price sensitivity due to thin rural broadband subsidy margins, while defense buyers absorb premiums for protected frequency bands and anti-jam capabilities.
Supply Chain Analysis
Extended payment terms from prime contractors are squeezing component vendors across the traveling wave tube amplifier tier. Manufacturing concentrates in the United States, France, and Japan for specialized microwave components. Raw material dependencies include gallium nitride substrates, high-purity aluminum for waveguides, and specialized ceramics for thermal management. Single-source vulnerability concentrates in traveling wave tube manufacturing where three specialized vendors supply the entire geostationary fleet tier. Distribution runs through direct OEM procurement channels with minimal intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as low-earth orbit constellations from SpaceX and Amazon's Project Kuiper erode the latency advantage that once protected geostationary positioning in maritime and enterprise backhaul verticals.
For Market Incumbents: Pre-empt defection to low-earth orbit alternatives by accelerating managed service bundling that embeds ground segment integration and field maintenance into long-term capacity commitments. Anchor orbital slot holdings through government connectivity contracts that exploit national security screening thresholds restricting foreign operator participation. Deepen backward integration into digital payload architectures to capture margin pools from software-defined transponder adoption.
For New Entrants and Emerging Players: Establish a beachhead in Brazil's rural broadband procurement channels where ANATEL spectrum coordination creates protected anchor tenancy windows for international fleet operators. Target maritime connectivity verticals where cruise lines and commercial shipping fleets demand low-latency backhaul solutions and exhibit weaker incumbent lock-in. Pursue outcome-based connectivity purchasing models that bundle hub operation with raw capacity to differentiate from commodity lease competitors.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy broadcasting conglomerates spinning off satellite distribution assets as C-band clearing mandates compress legacy revenue streams. Long-term viability hinges on constellation operators' ability to secure managed service margins rather than commodity capacity yields. Monitor FCC spectrum auction outcomes and national security screening threshold adjustments as inflection indicators for protected government vertical access.
| Strategic Initiative | Industry Significance |
|---|---|
| Ka-band Ground Terminal Deployment | Brazil's rural connectivity programs accelerate procurement of redesigned customer premises equipment. |
| Managed Service Bundling | Operators combining hub operation with raw capacity capture margin pools beyond commodity lease structures. |
| Digital Payload Architecture Investment | Software-defined transponders enable dynamic bandwidth allocation for maritime and aeronautical end-users. |
| Orbital Slot Pre-commitment Structures | Five-to-seven-year forward contracts secure distribution rights for emerging market broadcasters. |
| Spectrum Coordination Partnership | Collaboration with ANATEL and TRAI regulators shapes market access for international fleet operators. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with satellite fleet procurement executives, ground segment engineering directors, broadcast distribution managers, maritime connectivity specialists, and regulatory affairs leads at orbital slot holders. Secondary validation drew from FCC spectrum auction records, ITU orbital registration databases, ANATEL regulatory filings, customs data on amplifier component trade flows, and satellite operator SEC disclosures. Bottom-up capacity lease tracking across Ku-band, Ka-band, and C-band segments was triangulated against top-down fleet operator revenue segmentation.
Calibration against historical capacity deployment patterns and spectrum reallocation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include frequency band architecture, service model tier, vertical application, and end-user procurement cycle length. CAGRs were derived from lease rate trajectory analysis and capacity utilization assumptions tied to rural broadband program commitments. Forecast inputs incorporated TRAI and FCC mandate implementation schedules plus Brazilian government connectivity procurement pipelines.
Sensitivities concentrate around spectrum auction timing, launch vehicle availability constraints, and low-earth orbit constellation deployment acceleration. Forecasts reflect documented assumptions on regulatory implementation pace and technology transition cost absorption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global Maritime Satellite Communication Market
Satellite
M2M Satellite Communication Market
Satellite
Satellite Services Market
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
Europe Remote Sensing Satellites Market
Satellite
ASEAN Satellite Imagery Services Market
Satellite
All-Electric Satellites Market
Satellite
Commercial LEO Satellite Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
Satellite Imaging Market
Satellite
India Satellite-Based Earth Observation Market
Satellite
GEO Satellite Market
Satellite
Brazil Satellite-Based Earth Observation Market
Satellite
Global Commercial Satellite Broadband Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
Aviation Satellite Antenna Systems Market