
 Global Small Satellite Service Market | 2026-2036
Global Small Satellite Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Small Satellite Service Market Intelligence
Market Context
Defense contractor demand is decoupling from traditional large-satellite procurement, fragmenting across dozens of constellation-scale buyers. Boeing anchors North American service contracts through its integrated launch and ground-segment offerings. Planet Labs Inc. leverages its daily Earth-imaging cadence to sustain recurring revenue from agricultural and insurance clients. Thales Alenia Space competes across European institutional programs with dual-use communications payloads.
Technical Definition and Segment Structure
Small satellite service encompasses the full lifecycle support of spacecraft under 500 kg mass, spanning launch brokerage, orbital insertion, ground station access, and data product delivery for commercial and government operators. CubeSat and NanoSat platforms dominate unit volume due to standardized form factors and rideshare launch economics. Data Analytics services capture expanding margin pools as hyperspectral and synthetic aperture radar payloads generate higher-value downstream products. Earth Observation applications lead current revenue share, while Defense Surveillance represents the fastest-growing application segment as classified budgets shift toward proliferated low-Earth orbit architectures.
Regulatory Environment
The FCC governs spectrum allocation and orbital debris mitigation for U.S.-based operators, while the EU AI Act and CSRD increasingly shape data governance requirements for European analytics providers. China's MIIT and SAMR administer national frequency coordination and export control protocols for indigenous constellation deployments. Stakeholders must monitor evolving debris-remediation mandates from multiple national regulators as those rules will determine operational licensing continuity and insurance underwriting standards.
Market Dynamics
Defense procurement fragmentation is the dominant structural force reshaping small satellite service demand, as military buyers abandon single-platform contracts in favor of proliferated constellation architectures requiring continuous lifecycle support across dozens of orbital assets.
Growth Catalysts
- Streamlined FCC Licensing:The FCC's accelerated small satellite authorization timelines compress market entry cycles for U.S.-based operators, enabling faster constellation deployment and revenue generation.
- Dual-Use Payload Mandates:European institutional programs now require communications satellites to serve both civilian and defense applications, expanding service contract scopes for integrated ground-segment providers.
- Synthetic Aperture Radar:SAR payload miniaturization enables all-weather Earth observation capabilities that agricultural insurers and disaster response agencies now specify in procurement requirements.
Market Restraints
- Launch Capacity Bottlenecks:Rideshare availability concentrates on Western ranges and Chinese state-controlled sites, creating scheduling uncertainty for commercial operators without dedicated launch commitments.
- Spectrum Coordination Friction:ITU filing backlogs and national frequency allocation disputes delay operational licensing for cross-border data relay services.
- Debris Remediation Uncertainty:Evolving national end-of-life disposal mandates from the FCC and emerging EU space sustainability rules inflate insurance premiums and reserve capital requirements.
Strategic Opportunities
- India's NSIL Outsourcing:The Indian National Space Promotion and Authorization Centre is commercializing ground station access and launch integration services, opening procurement channels for foreign constellation operators.
- Hyperspectral Analytics Convergence:Fusion of hyperspectral imaging with machine learning pipelines creates premium data product tiers for precision agriculture and mineral exploration clients.
- Japan's GX Program:The Government of Japan's satellite constellation initiative for regional communications infrastructure mandates domestic-private partnership models for foreign service providers.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized expertise in phased-array antenna design and inter-satellite link protocols commands premium compensation, constraining ground-segment scaling for mid-size service providers.
- Legacy Ground System Integration:Defense clients require seamless interoperability with existing command-and-control architectures, forcing costly custom interface development for each new constellation contract.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Small Satellite Service Market |
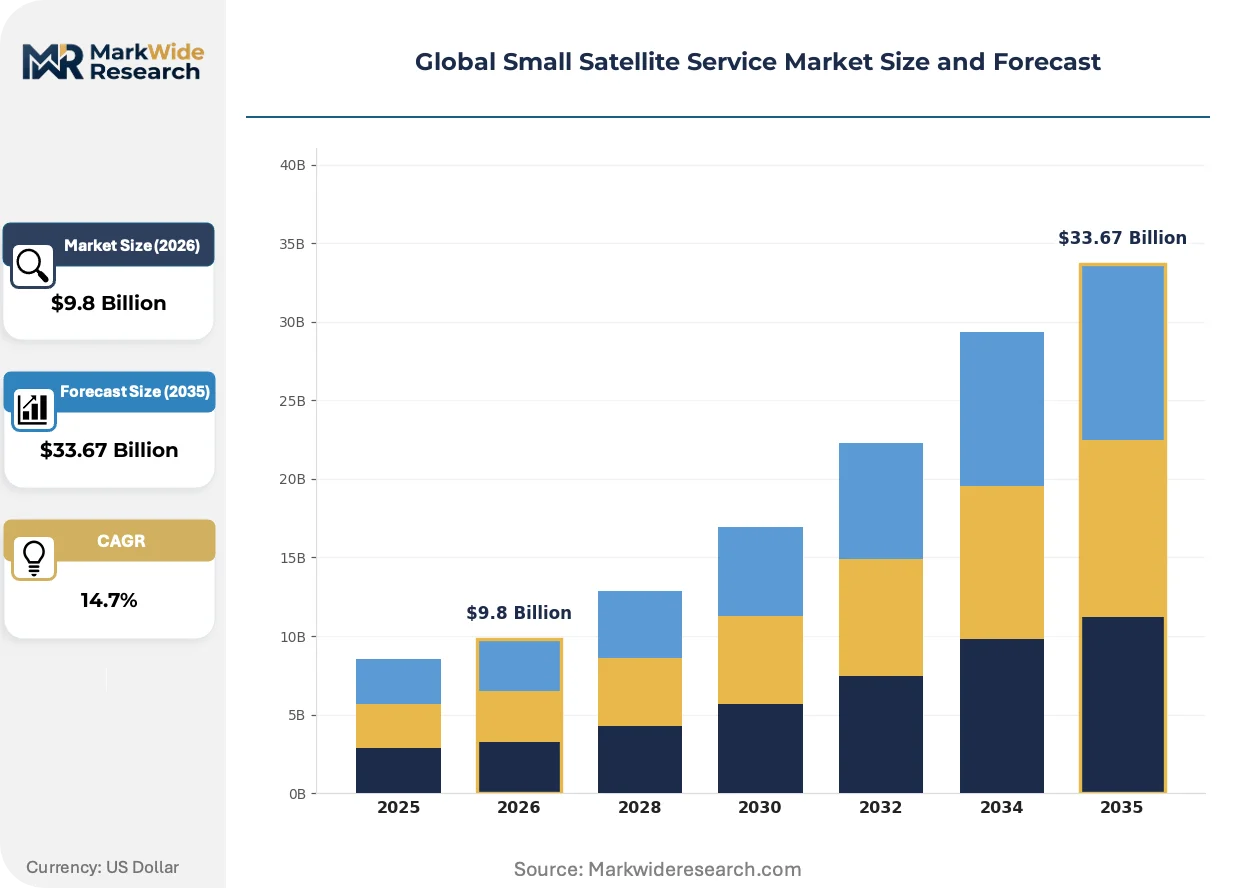
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $33.67 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Launch Services, Satellite Deployment, Data Analytics, Ground Station Operations, In-Orbit Support, Regulatory Consulting Application: Earth Observation, Communications, Scientific Research, Weather Monitoring, Defense Surveillance, Asset Tracking End User: Telecommunication Providers, Government Agencies, Research Institutions, Space Startups, Defense Contractors, Agricultural Firms Technology: CubeSat, NanoSat, MicroSat, Optical Payloads, RF Payloads, Propulsion Systems |
| Companies Covered | Boeing, Planet Labs Inc., Lockheed Martin Corporation, Surrey Satellite Technology Ltd, OHB SE, Northrop Grumman Corporation, Thales Alenia Space, Ball Aerospace, Airbus S.A.S., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Small Satellite Service Market Strategic Shifts & Innovations
Software-defined payload architectures are compressing hardware refresh cycles and enabling orbital reconfiguration without physical replacement, fundamentally altering how operators contract for satellite refresh and capability upgrades.
Software-defined radio payloads with field-programmable gate arrays are rewriting the economics of in-orbit service life. Defense agencies now specify reconfigurable frequency bands and waveforms as standard procurement requirements. This flexibility is compressing traditional satellite replacement timelines from seven years to three-year capability refresh contracts.
REACH chemical restrictions and emerging EU space sustainability regulations are mandating propellant and material substitutions across European-manufactured spacecraft. Suppliers must reformulate thermal control coatings and replace hydrazine-based propulsion systems. Smallsat builders in Germany and France are accelerating green propellant qualification programs to maintain institutional market access.
Buyers are unbundling launch services from multi-year data product subscriptions, forcing providers to compete on standalone orbital insertion pricing. Agricultural commodity traders and insurance underwriters now source imagery through API-first marketplaces rather than exclusive provider relationships. This disintermediation is most advanced in the United States, where Planet Labs and emerging competitors operate transparent pricing platforms.
Global Small Satellite Service Market Segmentation
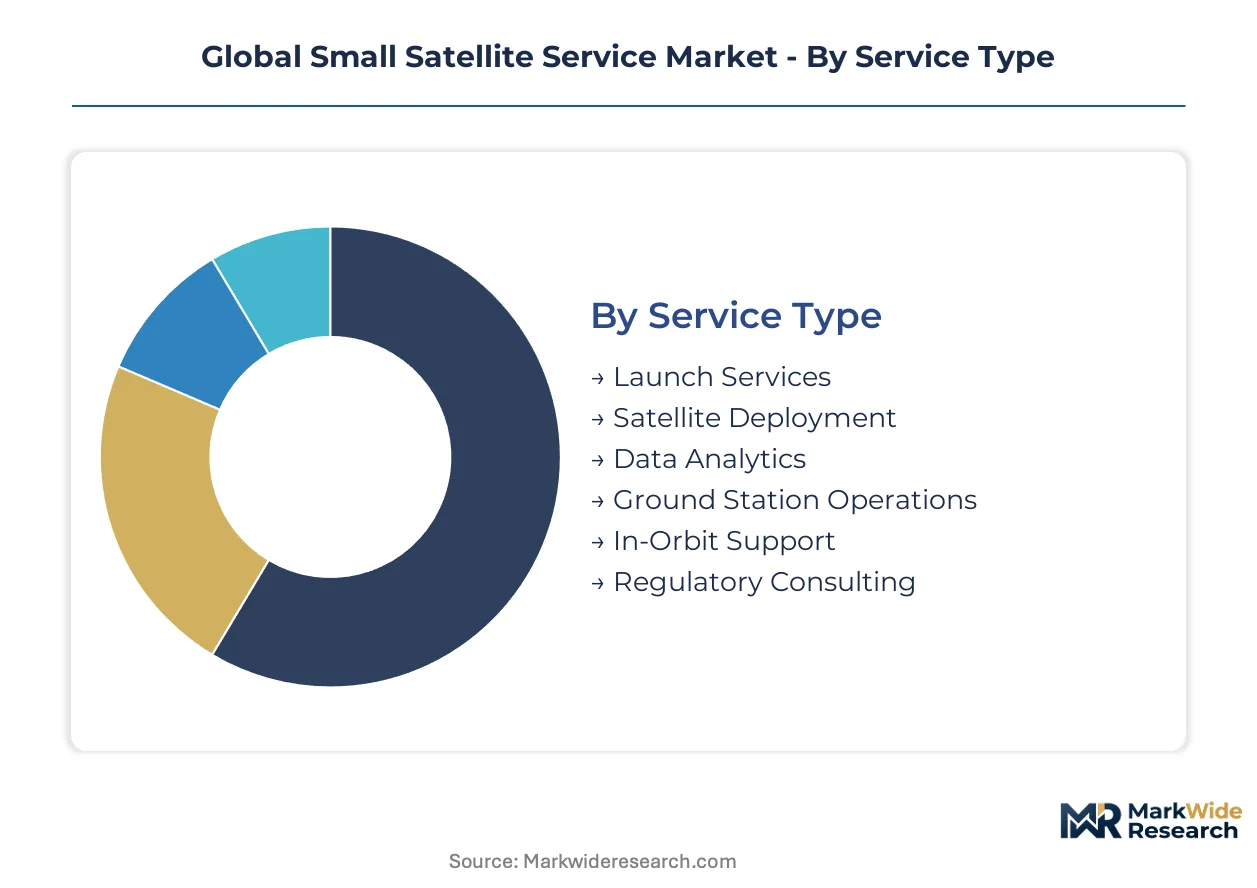
Service providers structure pricing and capability tiers around orbital mass class and data product sophistication. Procurement patterns diverge sharply between institutional buyers seeking bundled lifecycle contracts and commercial operators unbundling launch from analytics subscriptions.
Service Type:
Buyers select service bundles based on in-house ground infrastructure maturity and constellation operational complexity.
- Launch Services:Rideshare brokerage dominates unit economics for CubeSat operators, while dedicated small-lift vehicles command premium pricing for time-sensitive orbital insertion. Demand concentrates among U.S. and Chinese constellation deployers facing FCC and MIIT licensing deadlines.
- Data Analytics:Machine-learning pipelines transform raw hyperspectral and SAR imagery into actionable agricultural yield forecasts and insurance risk scores. European providers face CSRD data governance compliance costs that inflate service pricing relative to U.S. competitors.
- Satellite Deployment:End-to-end mission management from manufacturing integration through orbital handover.
- Ground Station Operations:Networked antenna access across polar and mid-latitude sites for continuous telemetry.
- In-Orbit Support:Collision avoidance maneuvering and end-of-life deorbit execution.
- Regulatory Consulting:ITU frequency coordination and national licensing navigation.
Volume sits with Launch Services; growth tilts toward Data Analytics.
Application:
Mission objectives determine payload specification, orbital altitude selection, and ground segment architecture requirements.
- Earth Observation:Daily revisit cadence drives agricultural commodity trading and catastrophe bond pricing. German and French operators lead institutional procurement through dual-use payload mandates.
- Defense Surveillance:Classified budgets are shifting toward proliferated low-Earth orbit architectures requiring continuous lifecycle support. SAR miniaturization enables all-weather tracking that legacy geostationary platforms cannot match.
- Communications:Narrowband IoT and broadband internet relay services.
- Scientific Research:Ionospheric monitoring and space weather prediction missions.
- Weather Monitoring:Atmospheric sounding and precipitation radar constellations.
- Asset Tracking:Maritime and aviation Automatic Identification System augmentation.
Earth Observation captures current revenue concentration; Defense Surveillance exhibits the steepest expansion trajectory.
End User:
Contracting authority and procurement cycle length vary dramatically across buyer categories.
- Government Agencies:National space agencies in the United States, China, and Germany increasingly outsource constellation operations to commercial service providers. Multi-year framework agreements favor established providers with demonstrated orbital heritage.
- Defense Contractors:Boeing and Thales Alenia Space anchor integrated service contracts spanning launch through ground-segment operations. Fragmented demand across dozens of constellation-scale buyers is reshaping vendor qualification requirements.
- Telecommunication Providers:Mobile network operators seeking satellite backhaul for remote coverage.
- Research Institutions:University-led CubeSat missions with limited operational budgets.
- Space Startups:Venture-funded constellation operators prioritizing speed-to-orbit.
- Agricultural Firms:Precision agriculture adopters sourcing imagery through API-first marketplaces.
Government Agencies dominate contract value; Space Startups are gaining share fastest.
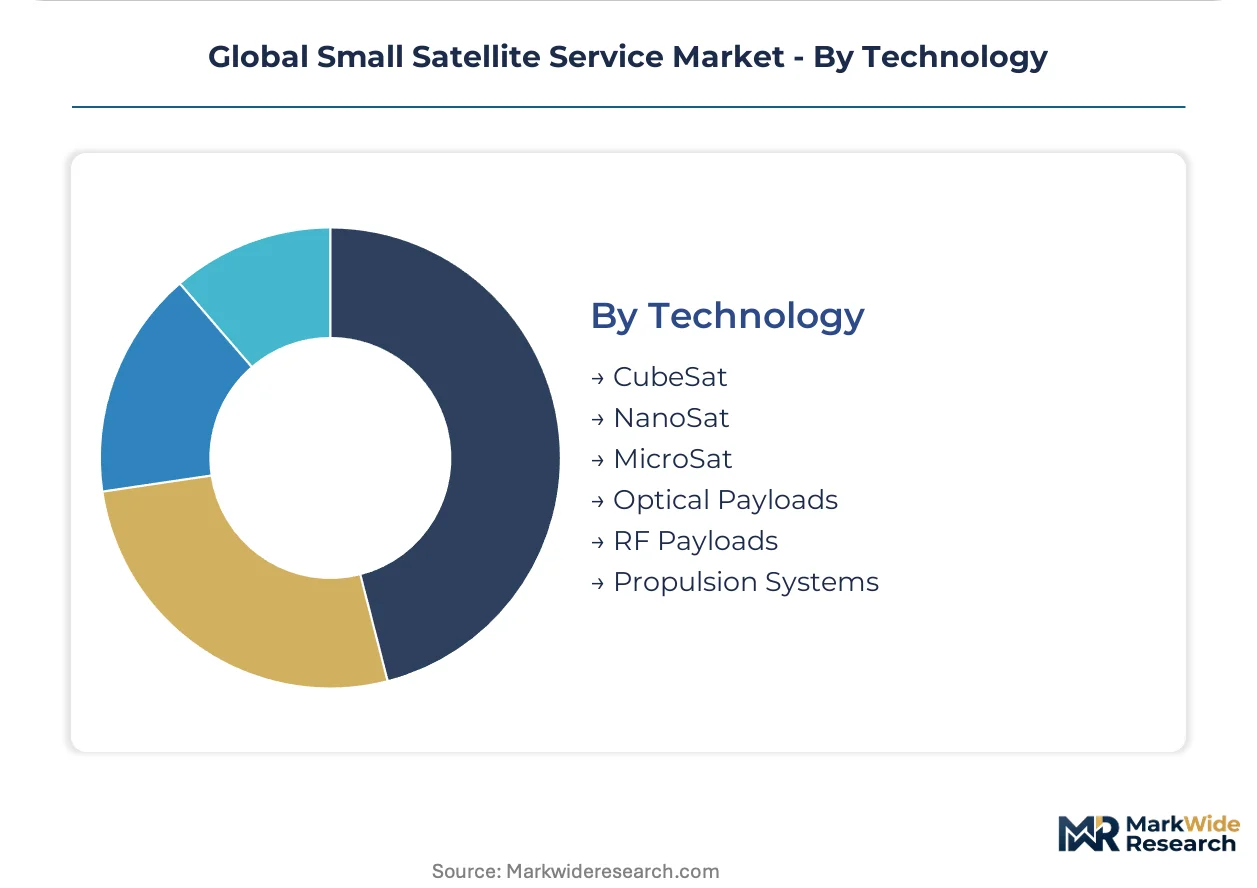
Technology:
Platform selection constrains payload mass, power budget, and orbital maneuvering capability.
- CubeSat:Standardized 1U-12U form factors enable rideshare launch economics and rapid constellation scaling. Planet Labs leverages daily imaging cadence from CubeSat swarms to sustain recurring revenue from agricultural and insurance clients.
- NanoSat:1-10 kg platforms balancing standardization with enhanced payload capacity. India's NSIL commercialization is opening procurement channels for foreign operators seeking cost-competitive launch integration.
- MicroSat:10-100 kg platforms accommodating larger optical apertures and propulsion systems.
- Optical Payloads:Multispectral and hyperspectral imagers for Earth observation.
- RF Payloads:Software-defined radios with reconfigurable frequency bands and waveforms.
- Propulsion Systems:Green propellant alternatives replacing hydrazine under REACH restrictions.
CubeSat holds unit volume leadership; RF Payloads climb the fastest on defense reconfigurability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement fragmentation concentrates demand in the United States, China, and Germany as national space agencies accelerate outsourcing to commercial operators. FCC licensing streamlines market entry timelines for U.S.-based constellation deployers. China's MIIT and SAMR administer frequency coordination protocols that govern indigenous expansion.
United States
Defense contractors fragment procurement across proliferated constellation architectures requiring continuous lifecycle support. The FCC governs spectrum allocation and orbital debris mitigation for domestic operators. Boeing anchors integrated service contracts spanning launch through ground-segment operations from its Colorado and California facilities.
China
National space agencies drive indigenous constellation deployments under state-controlled launch schedules. MIIT and SAMR administer frequency coordination and export control protocols for domestic manufacturers. Beijing and Shanghai host the principal design centers for commercial small satellite platforms serving regional communications infrastructure.
Germany
REACH chemical restrictions mandate propellant and material substitutions across European-manufactured spacecraft. OHB SE and Surrey Satellite Technology Ltd compete for institutional programs with dual-use communications payloads. Bavaria and Baden-Württemberg concentrate green propellant qualification programs to maintain market access.
India
The National Space Promotion and Authorization Centre commercializes ground station access and launch integration services for foreign operators. NSIL outsourcing opens procurement channels for constellation deployers seeking cost-competitive rideshare economics. Bengaluru and Ahmedabad host the principal integration facilities for commercial small satellite missions.
Japan
The Government's GX Program for regional communications infrastructure mandates domestic-private partnership models for foreign service providers. METI shapes procurement requirements for satellite backhaul and IoT connectivity services. Tokyo and Nagoya concentrate the principal ground segment and payload integration capabilities.
Global Small Satellite Service Market Key Industry Players
United States producers anchor the integrated service tier; European specialists hold institutional program positions through dual-use payload mandates. The vendor base fragments across defense contractors, commercial imagery providers, and ground-segment operators competing on orbital heritage and licensing speed. Three archetypes dominate: integrated launch-to-data conglomerates, pure-play analytics specialists, and regional ground-service providers. Competitive moves concentrate on M&A for orbital heritage acquisition and strategic partnerships for spectrum access.
Among U.S.-based integrated service providers, Boeing and Lockheed Martin Corporation occupy positions spanning launch brokerage through classified defense surveillance contracts. Planet Labs Inc. exemplifies the analytics-specialist archetype through its daily Earth-imaging cadence and API-first marketplace positioning. Thales Alenia Space anchors European institutional competitiveness from its integrated communications payload and ground-segment capabilities.
| Leading Market Players |
|---|
| Boeing |
| Planet Labs Inc. |
| Lockheed Martin Corporation |
| Surrey Satellite Technology Ltd |
| OHB SE |
| Northrop Grumman Corporation |
| Thales Alenia Space |
| Ball Aerospace |
| Airbus S.A.S. |
| Others |
Cost & Logistics Intelligence
Captive launch integration by Boeing and Lockheed Martin anchors both supply security and pricing power across the U.S. defense segment, insulating these providers from rideshare volatility while commanding premium mission-assurance contracts. This vertical control over launch brokerage and ground-segment operations creates tiered pricing separation that commercial operators cannot replicate without FCC licensing timelines compressing their market entry.
Pricing Analysis
Volume concentrates in rideshare launch brokerage with thin margins, while data analytics services capture expanding margin pools as hyperspectral and SAR payloads generate premium downstream products. Three-tier pricing structure across premium mission-assurance, standard rideshare, and economy CubeSat levels differentiates Boeing's integrated contracts from Planet Labs' API-first subscriptions. Pricing pressure stems from unbundling trends as agricultural commodity traders source imagery through transparent marketplaces rather than exclusive relationships. Government agencies exhibit lowest price sensitivity due to classified budget flexibility, while space startups face acute cost compression forcing trade-offs between launch timing and orbital precision.
Supply Chain Analysis
End-of-life deorbit execution and satellite refurbishment flows remain underdeveloped, creating stranded asset risk as FCC debris mandates tighten without established reverse-logistics infrastructure. Component manufacturing concentrates in the United States, China, and Germany, with propulsion systems and phased-array antennas drawing from specialized German and U.S. suppliers. Supply chain risk centers on single-source vulnerability for radiation-hardened electronics and ITU-coordinated frequency allocations. Distribution runs through defense contractor prime relationships and commercial API marketplaces diverging sharply by buyer archetype.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH chemical restrictions and FCC debris-mitigation mandates erect barrier-to-entry moats favoring incumbents with capital reserves for green propellant qualification and end-of-life insurance bonding.
For Market Incumbents: Hedge against launch capacity bottlenecks by securing dedicated small-lift vehicle commitments or backward integration into rideshare brokerage. Lockheed Martin and Boeing must defend against emerging pure-play analytics specialists by accelerating software-defined payload roadmaps that compress refresh cycles from seven years to three. Certification investment in dual-use payload mandates across European institutional programs offers channel control leverage unavailable to new entrants lacking orbital heritage. For New Entrants and Emerging Players: Software-defined radio reconfigurability offers a technology-first wedge against hardware-locked incumbents. India's NSIL commercialization presents the most penetrable geography for foreign constellation operators seeking cost-competitive launch integration without U.S. or Chinese regulatory friction. Target agricultural commodity traders through API-first marketplaces with hyperspectral yield-forecasting products that bypass exclusive provider relationships dominating defense segments. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated launch-to-data conglomerates acquiring pure-play analytics specialists for orbital heritage and customer base. Long-term viability favors providers with demonstrated FCC licensing speed and green propellant qualification completion ahead of REACH enforcement tightening. Watch ITU filing backlogs as the signal indicating regulatory chokepoint severity that could strand constellation deployment capital.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Payload Integration | Reconfigurable frequency bands compress refresh cycles for defense recontracting. |
| Green Propellant Qualification | REACH compliance maintains European institutional market access for OHB SE. |
| API-First Marketplace Launch | Planet Labs' transparent pricing disintermediates exclusive agricultural imagery relationships. |
| NSIL Partnership Formation | India's commercialized ground station access opens cost-competitive procurement channels. |
| Dual-Use Payload Certification | Thales Alenia Space leverages civilian-defense mandates for expanded service contract scopes. |
Research Approach
Multi-period observation of constellation deployment cadence, FCC licensing velocity, and defense procurement fragmentation anchored the trend analysis, supplemented by interviews with satellite mission directors, ground-segment engineers, defense procurement officers, and agricultural commodity trading analysts. Secondary validation drew from FCC authorization databases, ITU frequency coordination filings, ESA and NASA procurement records, and EU space sustainability regulatory drafts. Bottom-up triangulation across service-type revenue pools and top-down cross-check against national space agency budget disclosures ensured analytical consistency.
Segment-weighting by orbital mass class, payload technology, and end-user contracting authority structured the analytical framework across the projection horizon. Modeled dimensions included service type, application mission objective, end-user procurement cycle, and platform technology selection. CAGRs derived from fitted growth curves against historical deployment trajectories, with synthetic aperture radar miniaturization and software-defined payload adoption as satellite-specific demand drivers.
Several conditions sit outside the modeled scope, including abrupt ITU regulatory reclassification, major launch vehicle failures disrupting rideshare availability, and geopolitical suspension of cross-border frequency coordination. Forecasts reflect documented assumptions about debris-remediation mandate evolution and green propellant qualification timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Medium and Large Satellite Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
Saudi Arabia Satellite Imagery Services Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
US Satellite-Based Earth Observation Market
Satellite
Satellite Broadband Market
Satellite
Satellite Communications Service Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
Satellite GPS Receivers Market
Satellite
Asia-Pacific Satellite Bus Market
Satellite
China Satellite Communication Market
Satellite
Europe Remote Sensing Satellites Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
VSAT Maritime Satellite Communication Market
Satellite
North America Military Satellite Market