
 Satellite Broadband Market | 2026-2036
Satellite Broadband Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Broadband Market Insights
Buyer concentration among maritime operators and aviation companies is shifting as fleet-wide mandates replace vessel-by-vessel procurement. SpaceX leverages its vertically integrated launch capacity to sustain cost advantages in Low Earth Orbit deployment. Viasat anchors its position through high-throughput geostationary satellites serving defense and enterprise segments. Eutelsat Group competes across European and African markets with multi-orbit strategies.
Satellite broadband delivers high-speed internet connectivity via orbiting relay stations operating across geostationary, medium, and low Earth orbits, with terminal dishes typically ranging from 0.6 to 2.4 meters in diameter depending on frequency band and throughput requirements. The technology serves commercial and government users in locations where terrestrial fiber or cellular infrastructure proves economically unviable. Fixed broadband and enterprise connectivity segments dominate current revenue as rural households and remote offices seek reliable alternatives to underserved terrestrial networks. Low Earth Orbit technology represents the fastest-expanding architecture as constellation operators achieve manufacturing scale and launch cost reductions. Maritime connectivity occupies a concentrated margin pool where regulatory compliance and premium service tiers generate sustained pricing power.
The Federal Communications Commission governs spectrum allocation and orbital debris mitigation requirements in the United States, while the International Telecommunication Union coordinates cross-border frequency coordination and orbital slot registration globally. FCC licensing timelines and debris rules directly shape constellation deployment schedules and capital planning for operators. Stakeholders must monitor evolving national spectrum policies and orbital congestion management frameworks as launch cadence accelerates and interference disputes multiply across overlapping footprints.
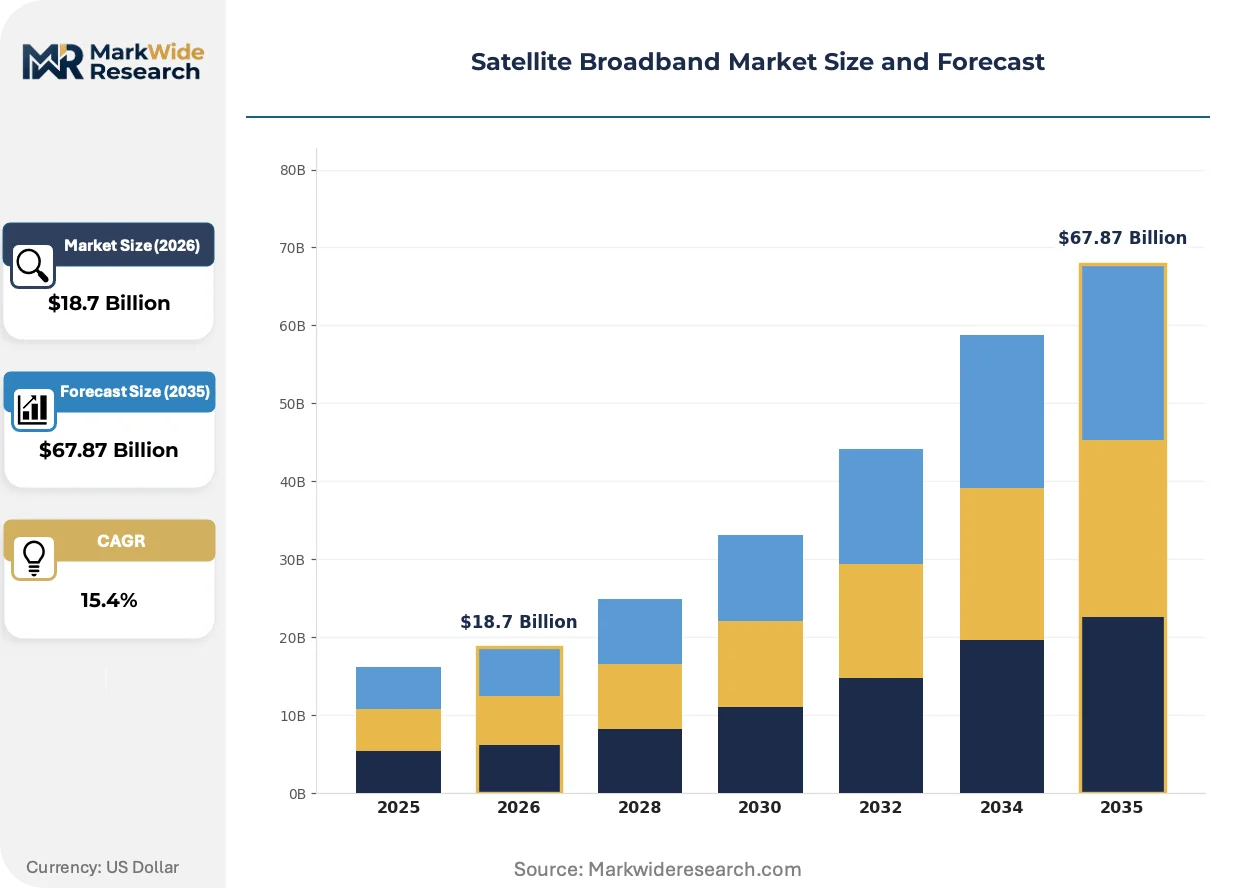
Market Dynamics
Low Earth Orbit constellations are compressing latency thresholds below 50 milliseconds, forcing legacy geostationary operators to restructure capacity pricing and terminal economics to defend subscriber retention across maritime and aviation verticals.
Growth Catalysts
- Maritime Labour Convention mandates:Crew welfare connectivity requirements under MLC 2006 amendments are compelling fleet operators to install satellite broadband across entire vessel portfolios, eliminating spotty coverage gaps.
- FCC Rural Digital Opportunity Fund:Subsidy allocations for unserved census blocks are accelerating terminal deployment in remote US communities where fiber economics fail.
- Phased array antenna advances:Solid-state electronically steered terminals are eliminating mechanical gimbals, reducing maritime and aviation integration costs while shrinking form factors.
Market Restraints
- Rocket launch capacity scarcity:Limited heavy-lift availability constrains constellation deployment cadence, extending time-to-orbit for operators competing for prime shell altitudes.
- Spectrum coordination delays:ITU notification and coordination procedures create multi-year licensing bottlenecks, particularly for Ku-band and Ka-band filings in crowded orbital planes.
- Terrestrial 5G fixed wireless substitution:Improved millimeter-wave coverage in semi-rural zones is capturing price-sensitive subscribers who would otherwise select satellite service.
Strategic Opportunities
- Defense and intelligence communities:Resilient beyond-line-of-sight communications for contested environments are driving classified procurement of proliferated LEO architectures with anti-jam capabilities.
- In-flight connectivity unbundling:Airlines are separating bandwidth procurement from passenger service delivery, creating direct relationships between satellite operators and loyalty program platforms.
- Direct-to-device integration:Convergence of satellite modems with unmodified smartphones is opening consumer messaging and emergency alert markets previously unreachable by dish-based terminals.
Industry Challenges
- Orbital debris remediation obligations:Post-mission disposal and active debris removal mandates are adding capital intensity to constellation business models, particularly for shells below 600 kilometers where atmospheric drag is insufficient.
- Interference management complexity:Co-frequency coordination between NGSO systems and incumbent geostationary networks requires sophisticated beam-steering algorithms and real-time ephemeris sharing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Broadband Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $67.87 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fixed Broadband, Mobile Broadband, Enterprise Connectivity, Maritime Connectivity, Aviation Connectivity Technology: Geostationary Orbit, Medium Earth Orbit, Low Earth Orbit, High Throughput Satellite, Very Small Aperture Terminal Application: Rural Connectivity, Disaster Recovery, Military Communications, Remote Enterprise Networks, Emergency Services End User: Telecom Service Providers, Government Agencies, Oil & Gas Operators, Maritime Operators, Aviation Companies |
| Companies Covered | SpaceX, Viasat, EchoStar Corporation, Amazon, Eutelsat Group, SES, Telesat, Singtel, Intelsat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Broadband Market Trends and Innovations
Terminal miniaturization and software-defined payloads are compressing the traditional trade-off between throughput density and mobility, enabling new use cases that were technically infeasible under legacy bent-pipe architectures.
Optical inter-satellite links are overtaking radio-frequency cross-connects as the dominant backbone technology for LEO constellations. SpaceX and Amazon's Kuiper are deploying laser terminals capable of terabit-per-second mesh networking, eliminating ground gateway dependencies for polar and oceanic coverage. This shift is overtaking the hub-and-spoke topology that previously dictated gateway placement and terrestrial backhaul investments.
The FCC's updated orbital debris mitigation rules are tightening post-mission disposal timelines and collision probability thresholds for licensed constellations. Operators must now demonstrate 90% reliability in deorbit capability within five years of mission completion, driving investment in propulsion redundancy and alternative disposal technologies. Small satellite manufacturers in the United States are responding by integrating higher-thrust propulsion modules and designing for controlled atmospheric reentry.
Fleet operators are consolidating bandwidth procurement under multi-year managed service agreements rather than transponder leases. Maritime and aviation buyers are shifting risk to operators by demanding committed information rates with penalty clauses, replacing the traditional megahertz-based contracting model. This pattern is most pronounced among European container lines and Middle Eastern flag carriers seeking operational expenditure predictability.
Satellite Broadband Market Segmentation
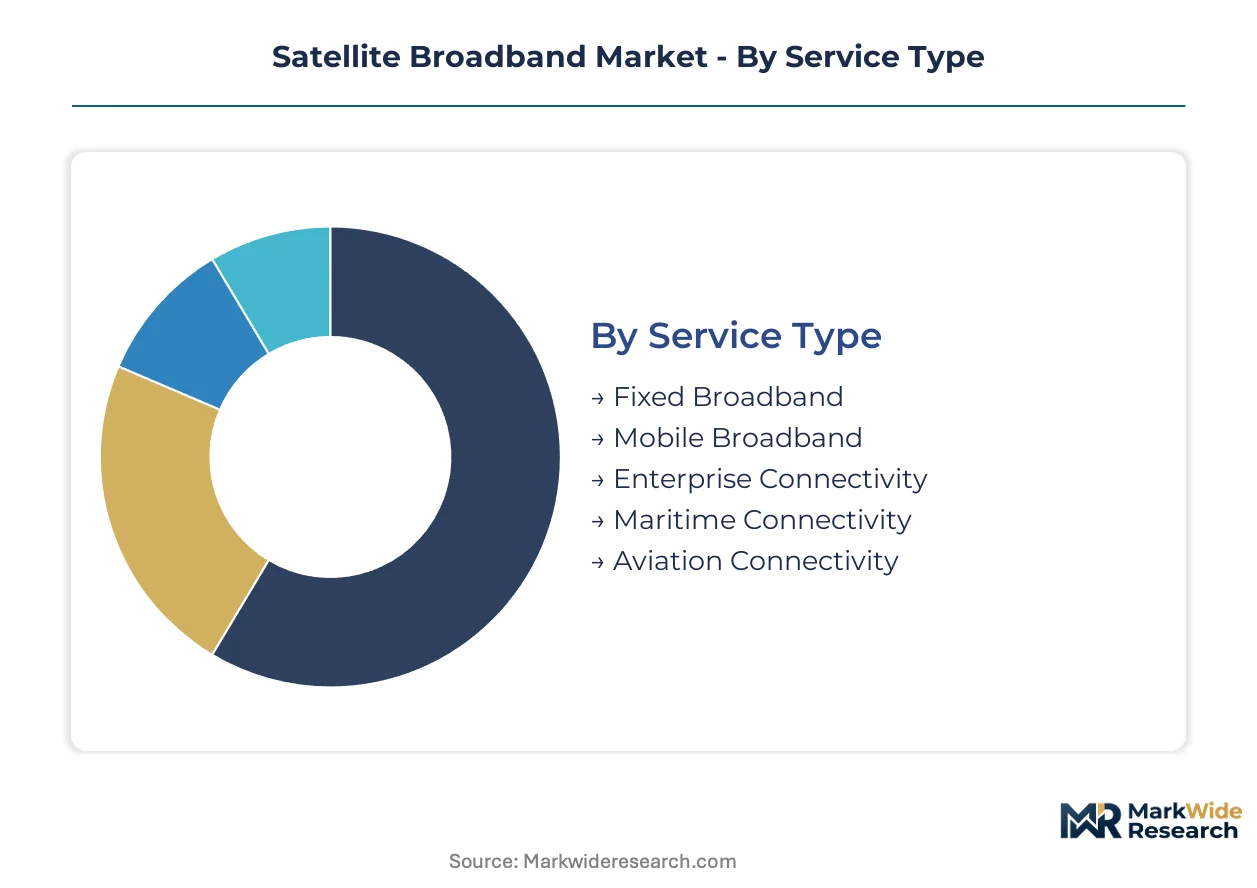
Satellite broadband operators calibrate capacity pricing and terminal specifications across distinct service tiers, each governed by unique latency tolerances, mobility requirements, and regulatory compliance obligations. Fleet procurement cycles and constellation deployment schedules create asynchronous upgrade windows that reshape competitive positioning within each segment category.
Service Type:
Replacement cycles vary dramatically across mobility-dependent services, with maritime and aviation mandates forcing synchronized fleet-wide upgrades that outpace discretionary consumer refresh rates.
- Fixed Broadband:Stationary terminal installations serving rural households and remote offices with dishes typically ranging from 0.6 to 1.2 meters. Demand clusters in United States census blocks where FCC Rural Digital Opportunity Fund subsidies offset terminal costs for unserved communities.
- Enterprise Connectivity:Dedicated bandwidth circuits with committed information rates for branch offices, mining camps, and energy facilities. Procurement concentrates under multi-year managed service agreements with penalty clauses replacing traditional megahertz-based contracts.
- Mobile Broadband:Portable terminals for recreational vehicles, expeditionary forces, and temporary event coverage. Military and humanitarian organizations drive specifications for rapid-deployment kits.
- Maritime Connectivity:Stabilized antenna systems for vessel fleets subject to Maritime Labour Convention crew welfare mandates. Regulatory compliance eliminates spot procurement, compelling container lines and tanker operators into uniform fleet installations.
- Aviation Connectivity:Phased-array terminals for commercial and business aircraft with stringent size, weight, and power constraints. Airlines are unbundling bandwidth procurement from passenger service delivery, creating direct satellite operator relationships.
Volume placements concentrate in Fixed Broadband; the faster expansion belongs to Maritime Connectivity.
Technology:
Cost tier separation between legacy orbital architectures and proliferated constellations determines capital efficiency and service economics for operators and subscribers alike.
- Low Earth Orbit:Constellations operating below 2,000 kilometers altitude delivering sub-50 millisecond latency through dense satellite shells. Manufacturing scale and reusable launch cadence are compressing per-satellite deployment costs, accelerating subscriber uptake for latency-sensitive applications.
- Geostationary Orbit:Satellites at 35,786 kilometers altitude providing persistent regional coverage with larger, higher-power payloads. Defense and enterprise segments sustain demand for high-throughput geostationary capacity despite latency limitations.
- Medium Earth Orbit:Intermediate altitude systems balancing coverage footprint with latency performance. O3b mPOWER and similar constellations serve maritime and aviation corridors with steerable beams.
- High Throughput Satellite:Spot-beam architectures multiplying capacity density over conventional wide-beam designs. Ka-band and Ku-band implementations dominate broadband delivery.
- Very Small Aperture Terminal:Compact dishes below 1.2 meters enabling rapid installation and lower subscriber acquisition costs. Consumer and small-business adoption depends on terminal miniaturization advances.
Subscriber additions cluster around Low Earth Orbit deployments; Geostationary Orbit retains the dominant share of current revenue.
Application:
Customer type differentiation separates price-sensitive rural households from premium-tier government and emergency services with dedicated spectrum and resilience requirements.
- Rural Connectivity:Residential internet access for communities where terrestrial fiber or cellular economics fail. United States distribution dominates due to FCC subsidy programs and geographic dispersion.
- Military Communications:Beyond-line-of-sight networks for contested environments with anti-jam and low-probability-of-intercept features. Classified procurement budgets are driving proliferated LEO architecture adoption.
- Disaster Recovery:Rapidly deployable emergency communications following terrestrial infrastructure failure. Humanitarian agencies and national emergency management authorities maintain standby capacity contracts.
- Remote Enterprise Networks:Private corporate networks for extraction, agriculture, and scientific operations in isolated locations. Oil and gas operators specify ruggedized terminals with extended temperature ranges.
- Emergency Services:First responder communications requiring priority access and hardened ground segments. Wildfire and hurricane response drives seasonal demand spikes.
Contract value concentrates in Military Communications; Rural Connectivity shows the steepest expansion trajectory.
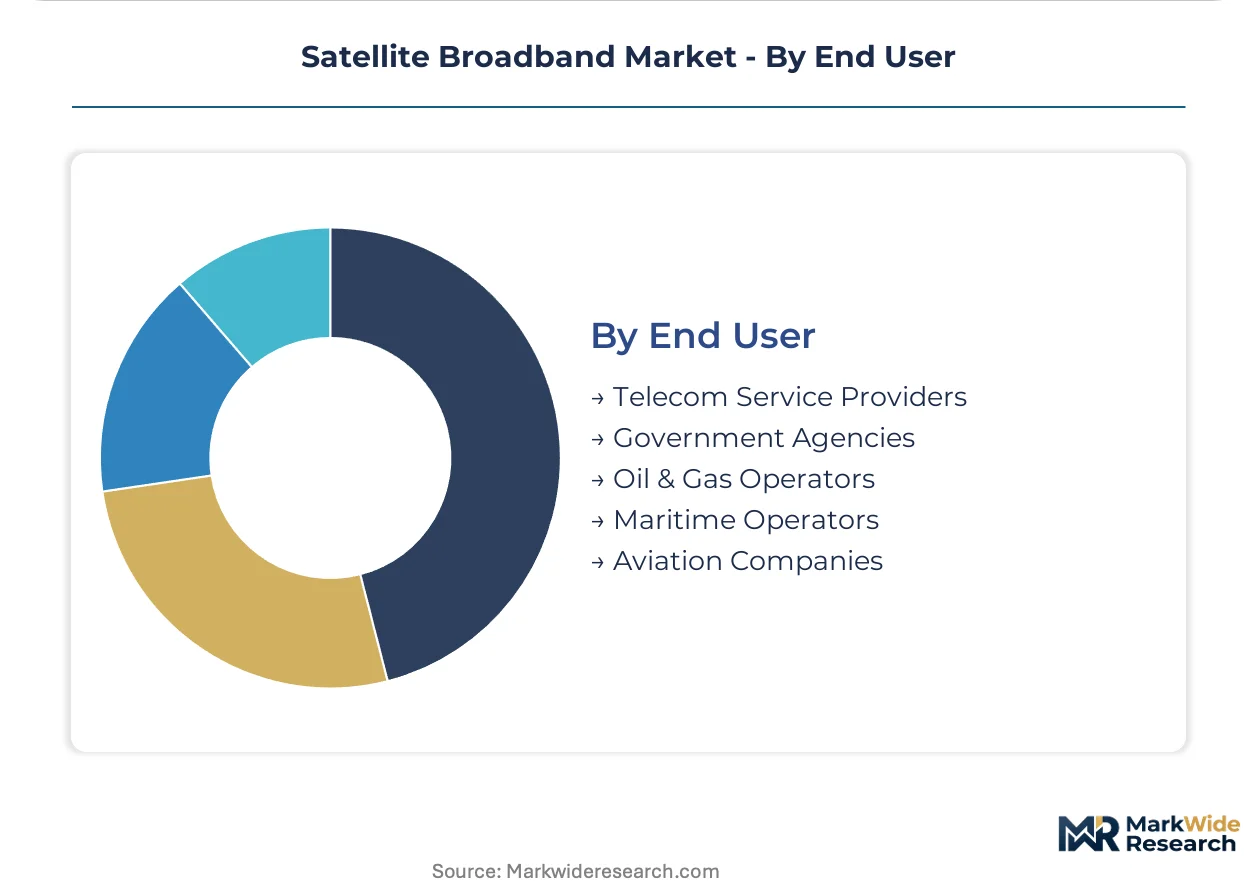
End User:
Supply concentration among constellation operators and terminal manufacturers shapes procurement leverage differently across government, corporate, and service provider channels.
- Telecom Service Providers:National operators reselling satellite capacity as wholesale backhaul or retail broadband under their own brands. Distribution partnerships determine market penetration in underserved regions.
- Government Agencies:Civilian and defense departments procuring dedicated capacity with sovereign control requirements. United States agencies dominate through classified and unclassified program offices.
- Maritime Operators:Container lines, tanker fleets, and cruise companies consolidating bandwidth procurement under fleet-wide managed services. European and Middle Eastern flag carriers lead contract restructuring.
- Oil & Gas Operators:Upstream and midstream companies connecting offshore platforms, pipelines, and remote camps. Exploration budgets dictate capital expenditure timing for network upgrades.
- Aviation Companies:Airlines and business jet operators integrating connectivity into loyalty programs and premium cabin services. Direct procurement relationships with satellite operators are displacing legacy integrator models.
Procurement volume clusters with Telecom Service Providers; Maritime Operators demonstrate the most rapid contract restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for satellite broadband concentrates in the United States, where regulatory subsidies and geographic dispersion create unmatched subscriber density. Europe and Asia-Pacific follow with distinct procurement patterns shaped by maritime mandates and sovereign connectivity programs.
United States
Rural digital inclusion programs and defense procurement anchor domestic demand. The FCC governs spectrum allocation through competitive auctions and enforces orbital debris mitigation timelines. Terminal deployment accelerates across the Mountain West and Great Plains where terrestrial fiber economics fail.
Germany
Maritime fleet operators headquartered in Hamburg and Bremen drive enterprise connectivity contracts under EU crew welfare directives. The national telecom regulator coordinates spectrum licensing with EU-wide harmonization frameworks. Manufacturing clusters in Bavaria produce phased-array terminals for aviation integration.
China
Sovereign constellation deployment and remote province connectivity programs sustain capital investment. The Ministry of Industry and Information Technology licenses orbital slots and coordinates ITU filings. Assembly lines in the Yangtze River Delta achieve manufacturing scale for small satellite production.
United Kingdom
Defense and emergency services procurement prioritizes resilient beyond-line-of-sight communications. Ofcom manages spectrum coordination with European neighbors and enforces orbital debris standards. Satellite operators cluster around Harwell and London for regulatory proximity and talent access.
Japan
Island geography and disaster resilience requirements sustain government-backed connectivity initiatives. METI coordinates industrial policy for domestic terminal manufacturing and constellation participation. Research consortia in the Kanto region advance optical inter-satellite link technologies.
Satellite Broadband Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue proliferated Low Earth Orbit architectures with manufacturing scale advantages. The market structures around three tiers: vertically integrated launch-and-service operators, geostationary incumbents with defense anchor contracts, and regional specialists with multi-orbit portfolios. Competitive moves concentrate on launch cadence acceleration and spectrum portfolio consolidation through ITU coordination filings.
Among vertically integrated operators, SpaceX exemplifies the launch-cost-advantaged archetype through captive heavy-lift capacity. Viasat occupies a position within the geostationary defense-focused tier, anchoring high-throughput capacity for sovereign customers. Eutelsat Group represents the multi-orbit regional specialist, spanning European and African markets with blended constellation strategies.
| Leading Market Players |
|---|
| SpaceX |
| Viasat |
| EchoStar Corporation |
| Amazon |
| Eutelsat Group |
| SES |
| Telesat |
| Singtel |
| Intelsat |
| Others |
Pricing and Supply Chain Analysis
Launch vehicle capacity pricing and satellite manufacturing cost indices cascade through constellation deployment economics, compressing terminal equipment pricing tiers while elevating managed service premiums for maritime and defense segments subject to FCC debris mitigation compliance costs.
Pricing Analysis
Volume placements concentrate in fixed broadband consumer tiers with thin hardware margins offset by recurring subscription revenue; enterprise and maritime segments command premium pricing through committed information rate guarantees and penalty-backed service level agreements. Price differentiation rests on latency performance tiers and orbital architecture certification, with sub-50 millisecond LEO services capturing 40-60% premiums over geostationary equivalents. Pricing pressure stems from reusable launch cadence compression and Starlink's vertically integrated cost structure forcing terminal subsidy escalation among competitors. Rural households under FCC Rural Digital Opportunity Fund subsidies exhibit highest price sensitivity; defense and intelligence communities demonstrate lowest elasticity due to sovereign resilience requirements.
Supply Chain Analysis
Workforce availability constraints in United States and European satellite manufacturing hubs are accelerating production automation and drawing engineering talent from legacy aerospace programs into constellation-focused ventures. Supply concentrates in California and Washington state for small satellite final assembly, with Bavaria and Tokyo serving phased-array terminal manufacturing clusters. Raw material dependencies center on gallium arsenide substrates for RF components, specialty aluminum-lithium alloys for satellite structures, and rare earth elements for propulsion systems. Single-source vulnerability pervades heavy-lift launch capacity where SpaceX Falcon 9 and Starship vehicles dominate deployable mass to orbit. Distribution runs through direct operator-to-enterprise contracts for maritime and aviation verticals, with consumer retail channels and telecom service provider partnerships covering residential fixed broadband.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The satellite broadband market operates as a cost-of-compliance arena where FCC orbital debris mitigation rules and ITU spectrum coordination timelines erect capital barriers that favor incumbent operators with established licensing portfolios and proven deorbit reliability.
For Market Incumbents: Hedge against LEO constellation overcapacity by securing anchor tenant contracts with defense and intelligence communities before proliferated architectures commoditize latency advantages. Accelerate backward integration into solid-state phased-array terminal manufacturing to capture hardware margins currently leaking to specialized suppliers. Prioritize multi-orbit service bundling that preserves geostationary revenue streams while meeting maritime customer demands for seamless coverage.
For New Entrants and Emerging Players: Regional telecom service providers in underserved African and Southeast Asian markets represent the most penetrable channel for wholesale capacity resale without direct constellation ownership. Direct-to-device messaging partnerships with unmodified smartphone OEMs open consumer reach without terminal subsidy burdens. Target emergency services and disaster recovery agencies with rapidly deployable rapid-deployment kit offerings that bypass established maritime and aviation procurement cycles.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated launch-and-service operators with demonstrated orbital deployment cadence and ITU filing priority dates. Long-term viability hinges on spectrum portfolio depth and debris rule compliance track records rather than terminal subscriber scale alone. Monitor ITU coordination dispute filings as the critical inflection signal for competitive positioning shifts among NGSO constellation operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Optical Inter-Satellite Link Deployment | Terabit-per-second laser mesh networking eliminates gateway dependencies for polar and oceanic coverage zones. |
| Phased Array Terminal Manufacturing Scale-Up | Solid-state electronically steered antennas reduce maritime integration costs while shrinking form factors for aviation. |
| Multi-Orbit Service Architecture | Blended LEO-GEO-MEO offerings preserve enterprise revenue while addressing latency-sensitive application demand. |
| Defense and Intelligence Partnership | Classified procurement of proliferated LEO architectures with anti-jam capabilities anchors resilient beyond-line-of-sight communications. |
| Direct-to-Device Modem Integration | Convergence with unmodified smartphones opens consumer messaging markets previously unreachable by dish-based terminals. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this satellite broadband market assessment, with primary interviews conducted among constellation operations executives, maritime fleet procurement directors, aviation connectivity integrators, and FCC licensing specialists. Secondary sources encompassed ITU satellite network filings, FCC auction and debris mitigation rulemaking dockets, Eutelsat and SES annual disclosures, and launch manifest databases. Bottom-up terminal deployment estimates across rural census blocks and fleet installation schedules were reconciled with top-down capacity revenue projections from operator disclosures.
Data-stream reconciliation across subscriber activation records, transponder lease rates, and managed service contract values informed the analytical framework across the projection horizon. Segmentation modeling incorporated service type, orbital architecture, end-user category, and regional regulatory cluster dimensions. CAGRs were derived from constituent year-on-year growth trajectories rather than endpoint fitting, with launch cadence assumptions and spectrum coordination timeline probabilities serving as industry-specific sensitivity inputs.
Caveats apply where ITU coordination delays, launch vehicle failures, or terrestrial 5G fixed wireless coverage expansion could materially shift the outlook for subscriber uptake and pricing power. Forecasts embed assumptions regarding reusable launch cost trajectories and phased-array terminal manufacturing yield improvements that may prove optimistic or conservative. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
North America Remote Sensing Satellites Market
Satellite
Italy Satellite Imagery Services Market
Satellite
Flat Panel Satellite Antenna Market
Satellite
Asia-Pacific Small Satellite Market
Satellite
Israel Satellite Communications Market
Satellite
Satellite Compass Market
Satellite
Global LEO Satellite Market
Satellite
Latin America Satellite Connectivity Market
Satellite
Cubesat Market
Satellite
Broadband Satellite System Market
Satellite
Germany Satellite Communications Market
Satellite
Brazil Satellite-Based Earth Observation Market
Satellite
Global Commercial Satellite Broadband Market
Satellite
Global Maritime Satellite Communication Market
Satellite
Satellite Antenna Market
Satellite
Mexico Satellite Connectivity Market