
 Airborne UHF-Band SATCOM Market | 2026-2036
Airborne UHF-Band SATCOM Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne UHF-Band SATCOM Market Analysis
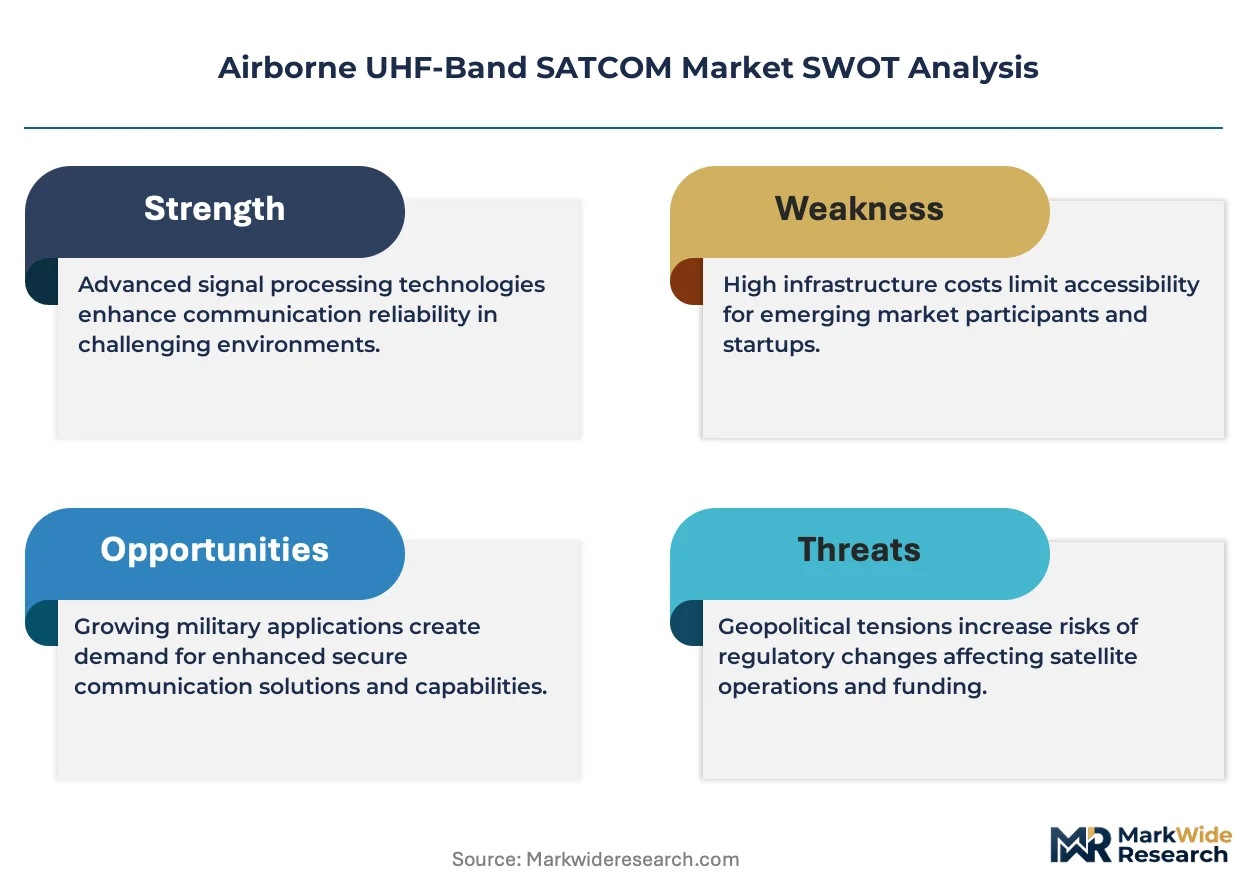
Military end-use is expanding as airborne ISR and tactical transport fleets prioritize resilient beyond-line-of-sight communications. L3Harris Technologies leverages its software-defined radio portfolio to anchor positions in NATO-compatible terminal systems. Thales Group sustains European defense relationships through specialized waveform integration for national fighter programs. Northrop Grumman dominates U.S. military satellite relay contracts with hardened payload designs.
Airborne UHF-band SATCOM denotes ultra-high frequency satellite communication systems operating between 300 MHz and 3 GHz, engineered for tactical aircraft with omnidirectional antennas that maintain links despite platform maneuvering and atmospheric attenuation. Terminal systems command the largest revenue share due to platform retrofit cycles across aging transport and patrol fleets, while amplifiers represent the fastest-growing component category as solid-state GaN devices displace traveling-wave tube technology. Signal processing units concentrate margin pools where embedded encryption and anti-jam firmware differentiate supplier offerings.
FCC spectrum allocations and NATO STANAG standards shape U.S. and European product certification pathways, while the International Telecommunication Union coordinates cross-border UHF satellite frequency coordination for military and emergency bands. Australia's Defence Department mandates TACSAT interoperability under Five Eyes alignment, tightening vendor qualification requirements. Stakeholders must monitor software-defined architecture roadmaps and allied spectrum harmonization negotiations to secure long-term platform integration slots.
Market Dynamics
Software-defined radio architectures are compressing hardware refresh cycles across military airborne platforms, forcing terminal suppliers to decouple waveform updates from physical hardware swaps.
Growth Catalysts
- NATO STANAG 4205:Allied interoperability mandates are accelerating terminal standardization across member air forces, creating procurement pull-through for certified suppliers.
- Beyond-line-of-sight ISR:Intelligence-surveillance-reconnaissance aircraft require resilient satellite links for contested airspace operations, expanding addressable platform counts.
- Gallium nitride amplifiers:Solid-state GaN devices are displacing traveling-wave tube technology, enabling smaller form factors that unlock retrofit opportunities on aging tactical transports.
Market Restraints
- Traveling-wave tube dependency:Legacy amplifier supply chains concentrate in specialized defense contractors with limited surge capacity, creating single-source vulnerability.
- Spectrum coordination friction:FCC and ITU frequency allocation negotiations create multi-year certification delays for new terminal designs.
- High-assurance encryption costs:NSA Type-1 certification requirements impose seven-figure non-recurring engineering costs that exclude mid-tier suppliers.
Strategic Opportunities
- Australia TACSAT modernization:Five Eyes alignment mandates are opening qualification pathways for NATO-certified suppliers into a historically captive domestic market.
- Software-defined waveform convergence:Integration of MUOS and legacy UHF channels onto common hardware platforms is enabling multi-mission terminal architectures.
- Commercial satellite backhaul:Dual-use terminals capable of military and commercial satellite handoff are penetrating emergency response and border patrol applications.
Industry Challenges
- Embedded firmware talent scarcity:Anti-jam signal processing expertise concentrates in cleared defense contractors with limited labor mobility.
- Platform integration complexity:Retrofitting terminals onto 1970s-era C-130 and P-3 airframes requires structural modification and electromagnetic interference remediation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne UHF-Band SATCOM Market |
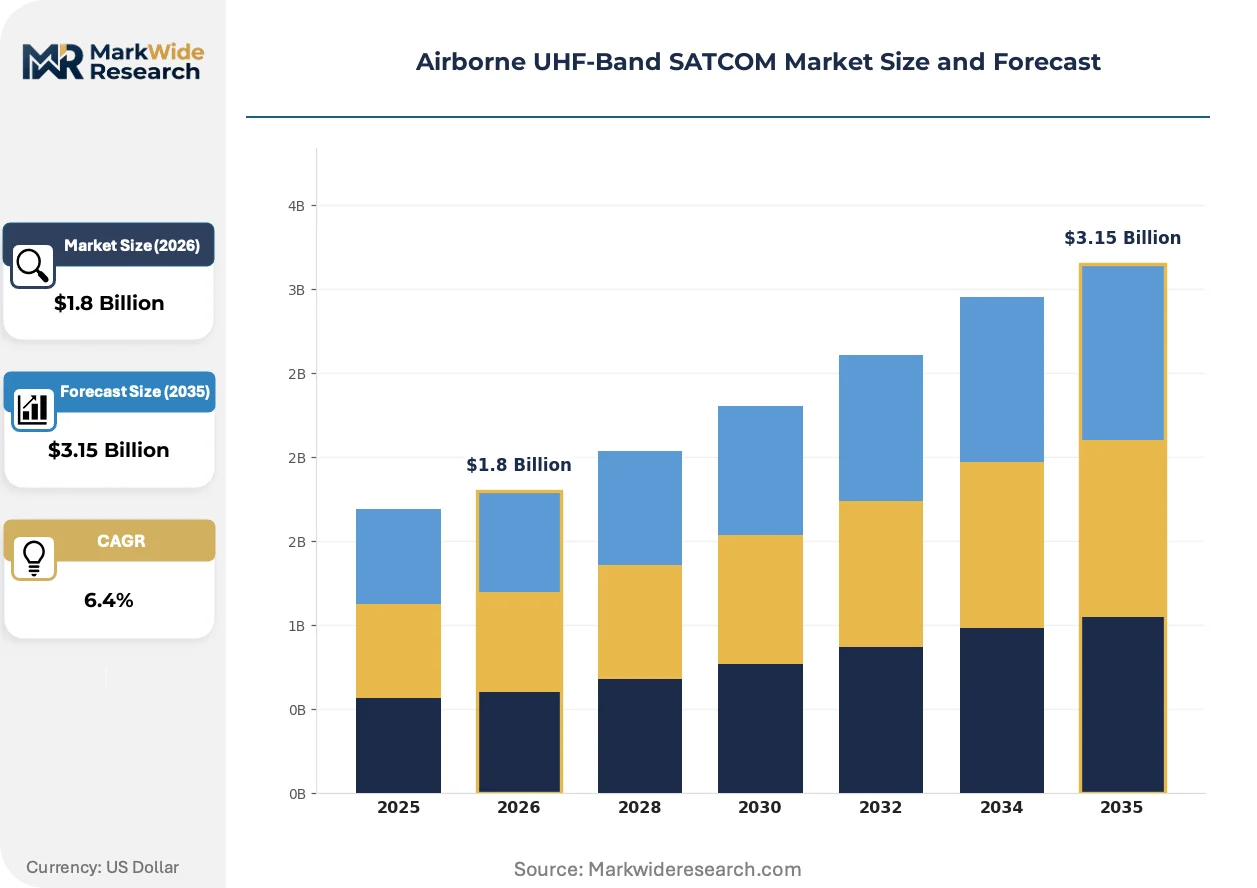
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terminal Systems, Ground Stations, Amplifiers, Modems End User: Military, Commercial Aviation, Government, Private Operators Component: Antenna, Transmitter, Receiver, Signal Processing Unit Application: Data Transfer, Voice Communication, Video Transmission, Emergency Services |
| Companies Covered | L3Harris Technologies, Thales Group, Northrop Grumman, General Dynamics Corporation, Viasat, Cobham, Aselsan, Collins Aerospace, Raytheon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne UHF-Band SATCOM Market Emerging Trajectories
Waveform virtualization and modular antenna designs are collapsing the traditional boundary between terminal hardware and signal processing, enabling faster capability insertion without airframe recertification.
Software-defined radio cores are unifying multiple UHF satellite waveforms onto single hardware platforms. Military transport and patrol aircraft operators are mandating these flexible architectures in new procurements. This unification is compressing supplier margins on dedicated single-waveform terminals while expanding attach rates for firmware upgrade subscriptions.
FCC Part 25 spectrum proceedings are tightening out-of-band emission limits for airborne terminals. Equipment manufacturers face retesting costs for existing certified products. U.S. military procurement offices are responding by specifying pre-compliant designs in forthcoming terminal solicitations.
Consolidated platform prime contracting is concentrating terminal procurement decisions under Lockheed Martin, Boeing, and Northrop Grumman airframe divisions. Independent radio suppliers must embed their products into these primes' mission system architectures. This concentration is most visible in U.S. Air Force mobility and special operations aircraft programs.
Airborne UHF-Band SATCOM Market Segmentation
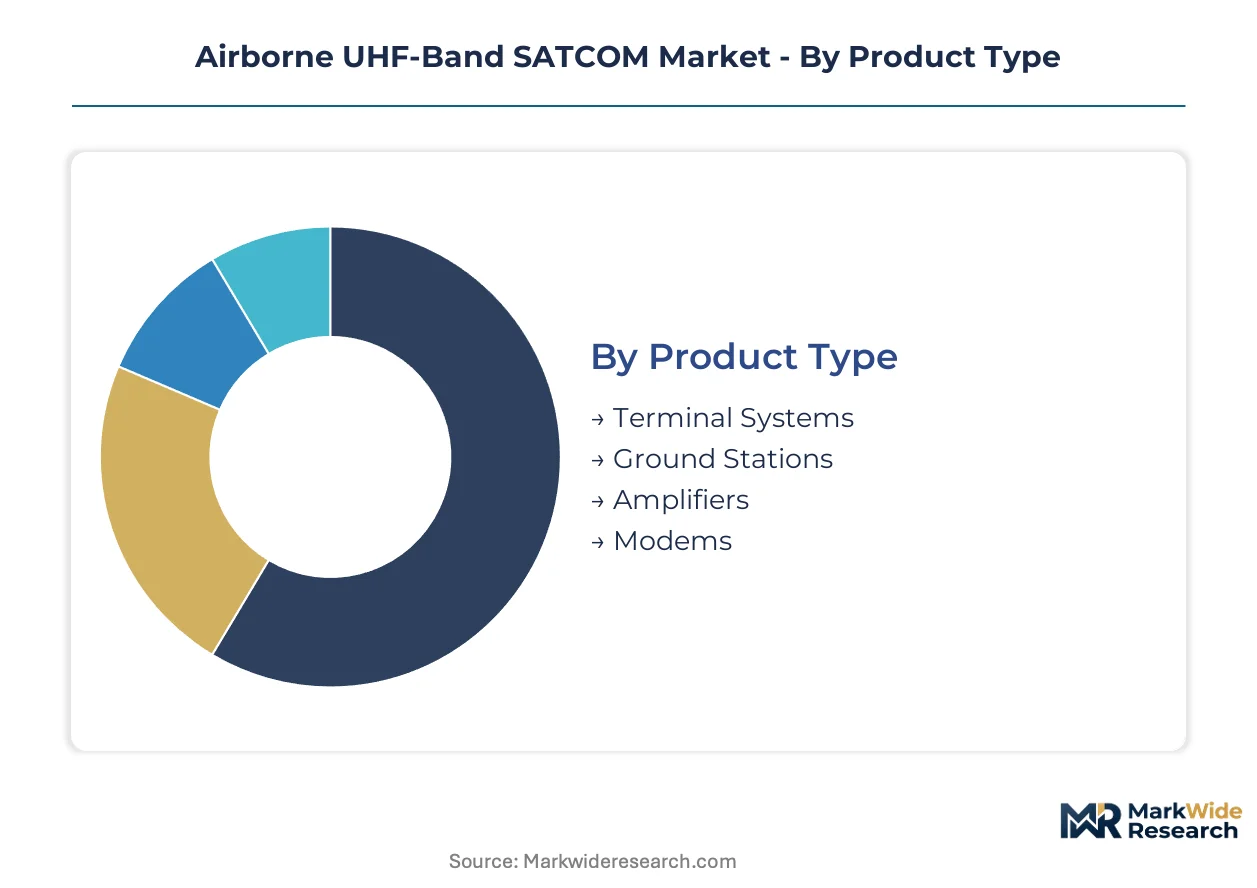
Segmentation in airborne UHF-band SATCOM reveals how procurement decisions fragment across platform types, operational missions, and certification tiers. Understanding these divisions exposes where hardware refresh cycles concentrate and where software-defined architectures unlock retrofit opportunities.
Product Type:
Supply concentration in terminal manufacturing favors vertically integrated suppliers capable of delivering NATO STANAG-certified systems with embedded encryption modules.
- Terminal Systems:Integrated airborne units combining antenna, transceiver, and processing hardware into airframe-mountable enclosures. Military ISR platforms and tactical transport fleets in the United States, United Kingdom, and Australia drive procurement as beyond-line-of-sight communication requirements harden.
- Amplifiers:Power amplification modules using solid-state GaN devices to replace legacy traveling-wave tube technology. Smaller form factors and improved thermal management enable retrofit installations on aging C-130 and P-3 airframes where space and weight constraints previously blocked upgrades.
- Ground Stations:Fixed and transportable earth stations providing satellite link aggregation and network management for airborne fleets. Demand concentrates in national military communication hubs and coalition interoperability nodes.
- Modems:Signal modulation-demodulation units handling waveform processing for multiple UHF satellite constellations. Software-defined architectures allow firmware updates without hardware replacement, compressing refresh cycles.
Terminal systems absorb the bulk of installed capacity; amplifiers are expanding most quickly as solid-state technology unlocks platform retrofit opportunities.
End User:
Cost tier stratification separates fully certified military systems from commercial aviation equipment with reduced encryption and anti-jam capabilities.
- Military:Defense operators requiring NSA Type-1 encryption, anti-jam waveforms, and hardened designs for contested electromagnetic environments. Procurement flows through prime contractors Lockheed Martin, Boeing, and Northrop Grumman for integration into mission system architectures.
- Commercial Aviation:Airlines and cargo operators seeking passenger connectivity and operational communications over oceanic and remote routes. FCC Part 25 certification requirements and ITU frequency coordination create multi-year approval timelines for new terminal designs.
- Government:Non-military state agencies including coast guard, border patrol, and emergency response units. Australia's Defence Department TACSAT interoperability mandates under Five Eyes alignment tighten vendor qualification requirements.
- Private Operators:Corporate flight departments and specialized mission contractors operating modified business jets and surveillance aircraft. Dual-use terminals capable of military and commercial satellite handoff penetrate this segment for flexibility.
Military end users command premium pricing tiers; government operators are gaining share fastest as homeland security and emergency response budgets expand.
Component:
Margin pools concentrate in signal processing units where embedded encryption and anti-jam firmware differentiate supplier offerings from commodity hardware.
- Signal Processing Unit:Embedded computing modules executing waveform virtualization, error correction, and cryptographic functions. Anti-jam signal processing expertise concentrates in cleared defense contractors with limited labor mobility, creating capability scarcity.
- Antenna:Omnidirectional and phased-array radiating elements optimized for UHF band propagation and platform aerodynamics. Modular designs are collapsing the boundary between terminal hardware and antenna systems.
- Transmitter:Radio frequency chains converting baseband signals to UHF satellite uplink frequencies. Gallium nitride power devices enable higher efficiency in smaller packages.
- Receiver:Downconversion and digitization electronics capturing satellite downlink signals amid interference and fading. Sensitivity specifications determine operational link margins for maneuvering platforms.
Signal processing units capture the highest value-add; antenna modules are climbing the fastest as platform integration complexity drives demand for standardized form factors.
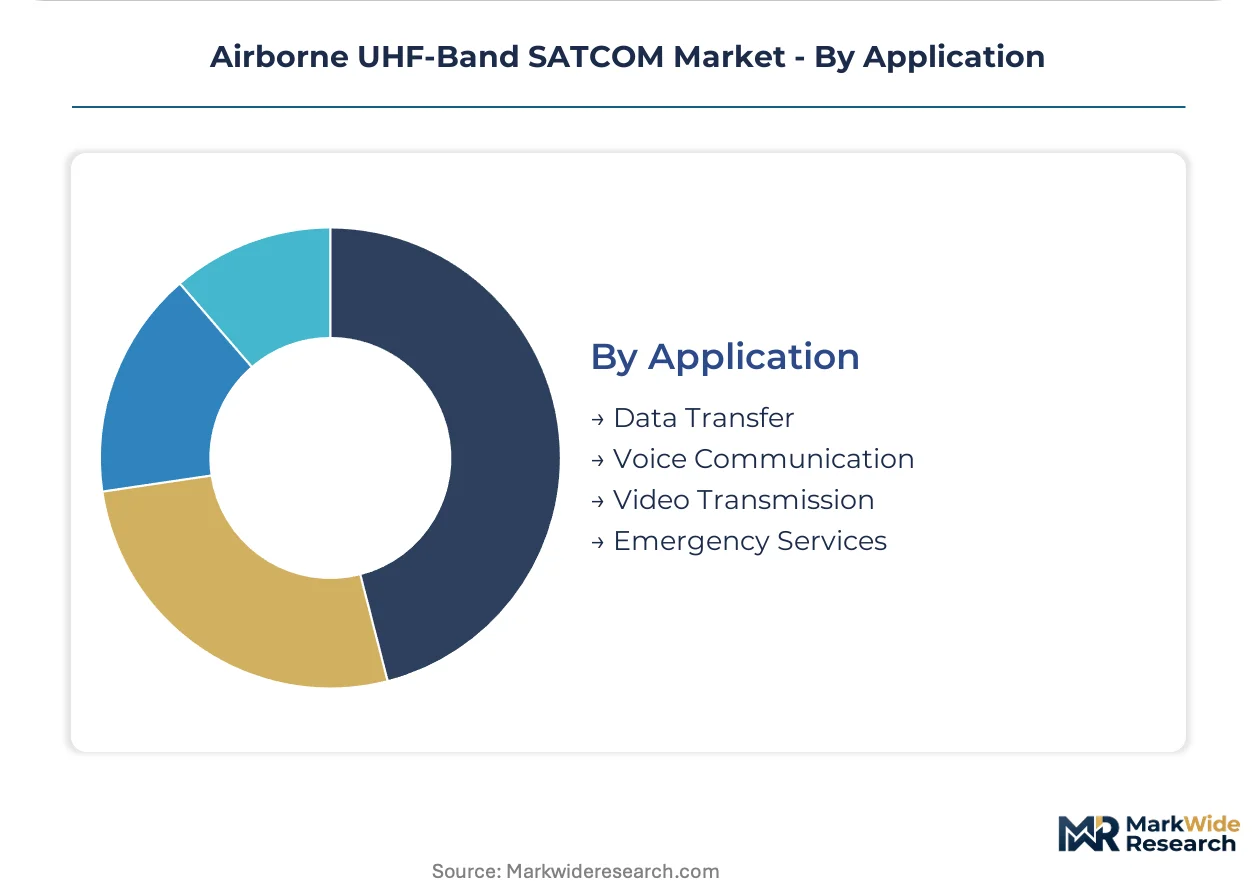
Application:
Application segmentation tracks how bandwidth allocation and latency requirements shape terminal specification priorities across operational scenarios.
- Data Transfer:Tactical datalink and sensor payload transmission for ISR platforms. Intelligence-surveillance-reconnaissance aircraft require resilient satellite links for contested airspace operations.
- Voice Communication:Secure audio channels for command and control coordination. NATO interoperability standards and software-defined radio integration reshape procurement requirements.
- Video Transmission:Full-motion video relay from airborne sensors to ground stations. Bandwidth intensity drives demand for higher-order modulation schemes.
- Emergency Services:Disaster response and search-and-rescue communications when terrestrial infrastructure fails. Dual-use military-commercial terminals penetrate border patrol and emergency response applications.
Data transfer dominates current platform specifications; emergency services are gaining share fastest as climate-driven disaster response requirements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of airborne UHF-band SATCOM terminals concentrates in the United States and France, while operational demand spreads across allied air forces in Australia, the United Kingdom, and Germany. Component sourcing for solid-state amplifiers draws from South Korean and Japanese semiconductor foundries. Installation and integration services cluster near major military airframe overhaul facilities.
United States
U.S. Air Force mobility commands and special operations units drive terminal procurement for C-130 and C-17 retrofit programs. FCC Part 25 spectrum proceedings tighten out-of-band emission limits, forcing retesting of certified products. San Antonio hosts concentrated depot-level maintenance operations where terminal integration occurs during programmed airframe overhauls.
United Kingdom
Royal Air Force ISR platforms and tactical transport fleets prioritize NATO STANAG 4205 interoperability for coalition operations. Ministry of Defence procurement offices mandate software-defined radio architectures in new terminal solicitations. Basing infrastructure at RAF Waddington concentrates signals intelligence platform modification work.
Australia
Defence Department TACSAT modernization programs open qualification pathways for NATO-certified suppliers under Five Eyes alignment. The country's national telecommunications regulator coordinates military frequency allocations with ITU frameworks. Edinburgh Defence Precinct near Adelaide hosts concentrated aerospace integration capabilities for P-8 and Wedgetail platforms.
Germany
Luftwaffe A400M and C-160 replacement programs generate demand for multi-mission terminal architectures. Bundesamt für Ausrüstung, Informationstechnik und Nutzung der Bundeswehr oversees military equipment certification pathways. Munich-area defense electronics clusters supply signal processing subsystems to integrators across Europe.
Airborne UHF-Band SATCOM Market Vendor Landscape
Top-tier vendors anchor prime contractor relationships with Lockheed Martin, Boeing, and Northrop Grumman airframe divisions, while mid-tier specialists concentrate on waveform firmware and amplifier subsystems. The vendor base stratifies across three tiers: systems integrators with NSA Type-1 certification, component suppliers with NATO STANAG credentials, and emerging challengers from allied defense industrial bases. Two dominant competitive moves are reshaping positioning: consolidation of platform procurement decisions under airframe primes, and vertical integration of software-defined radio cores into multi-mission terminal architectures.
Among U.S.-based defense conglomerates, L3Harris Technologies, Northrop Grumman, and General Dynamics Corporation occupy positions across the systems integration tier. L3Harris exemplifies the software-defined radio specialist archetype with its programmable waveform portfolio. Northrop Grumman anchors military satellite relay contracting through hardened payload design capabilities. General Dynamics represents the diversified defense electronics fabricator with breadth across terminal and ground station segments.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Thales Group |
| Northrop Grumman |
| General Dynamics Corporation |
| Viasat |
| Cobham |
| Aselsan |
| Collins Aerospace |
| Raytheon Technologies |
| Others |
Supply Flow & Price Mechanics
NATO STANAG 4205 certification mandates are compressing supplier qualification timelines and forcing procurement offices to accept premium pricing for pre-certified terminal architectures. This specification pressure elevates costs for encryption-embedded systems while squeezing margins on commodity amplifier modules.
Pricing Analysis
Lead-time premiums dominate contract negotiations as defense procurement offices prioritize rapid fielding over cost optimization. Three-tier pricing structure across NSA Type-1 certified, NATO STANAG-compliant, and commercial-grade equipment reflects encryption assurance levels. Price differentiation stems from certification tier and waveform software bundling. Cost compression in commercial aviation terminals is intensifying because FCC Part 25 retesting requirements are absorbing engineering budgets. Government operators exhibit highest price sensitivity due to fixed homeland security appropriations, while military special operations units demonstrate lowest sensitivity given mission-critical requirements.
Supply Chain Analysis
Domestic-content thresholds in U.S. defense procurement and Australia's TACSAT localization mandates are reshaping component sourcing toward qualified domestic integrators. Gallium nitride semiconductor fabrication concentrates in the United States, Japan, and South Korea. Terminal assembly draws from U.S. and French defense electronics clusters, while traveling-wave tube production rests on a single-source supplier base. Single-source vulnerability in legacy amplifier supply chains creates procurement risk for aging platform sustainment. Distribution runs through prime contractor mission system divisions at Lockheed Martin, Boeing, and Northrop Grumman.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-jam signal processing expertise scarcity props pricing power for cleared defense contractors with embedded firmware capabilities. Capacity constraints in NSA Type-1 certification pathways limit supplier expansion.
For Market Incumbents: Extend software-defined radio architecture roadmaps to capture firmware upgrade subscription revenue streams. Lock in prime contractor embedding agreements before platform procurement decisions consolidate further under airframe divisions. Counter emerging GaN amplifier specialists by securing exclusive foundry relationships with South Korean semiconductor fabricators. For New Entrants and Emerging Players: Enter via Australia's TACSAT modernization programs where Five Eyes alignment is opening qualification pathways for NATO-certified suppliers. Target government emergency response segments with dual-use terminals capable of military-commercial satellite handoff. Pursue commercial satellite backhaul partnerships as the primary go-to-market channel. For Investors and Strategic Acquirers: Re-rating potential sits with waveform firmware specialists given software-defined architecture convergence compressing hardware refresh cycles. Long-term viability favors suppliers with embedded encryption development pipelines and prime contractor channel access. Monitor FCC spectrum allocation proceedings as the signal indicating certification timeline compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Core Integration | Unifies MUOS and legacy UHF channels onto common hardware platforms for multi-mission flexibility. |
| GaN Amplifier Supply Agreement | Locks in solid-state device sourcing from South Korean foundries for retrofit program participation. |
| Prime Contractor Embedding Partnership | Secures mission system architecture slots before C-130 and P-3 terminal procurement decisions finalize. |
| NSA Type-1 Certification Investment | Opens military procurement channels requiring seven-figure non-recurring engineering expenditure barriers. |
| Australia TACSAT Qualification Pathway | Exploits Five Eyes alignment mandates penetrating historically captive domestic supplier relationships. |
Methodological Framework
Defense procurement databases, FCC equipment authorization filings, and NATO standardization documents formed the secondary backbone of this analysis. Primary interviews with military communications program officers, terminal systems engineering leads, prime contractor procurement managers, and GaN semiconductor foundry executives supplied operational validation. Bottom-up platform retrofit counts across C-130, C-17, P-3, and P-8 fleets were triangulated against top-down defense budget appropriation analysis.
Historical trendline analysis of terminal procurement cycles informed projection modeling across the analysis window. Segmentation dimensions included product type, end-user certification tier, component value-add level, and application bandwidth intensity. CAGRs were derived from fitted growth curves adjusted for platform fleet age profiles and software-defined architecture transition timelines. Forecast inputs incorporated NATO STANAG adoption trajectories and allied spectrum harmonization negotiation status.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated software-defined radio deployment or prolonged FCC certification delays. Projections reflect assumptions regarding defense budget continuity and allied interoperability commitment durability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Connectivity Market
Satellite
UK Satellite Connectivity Market
Satellite
United States Satellite Communications Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
Japan Satellite Connectivity Market
Satellite
Europe Satellite Launch Vehicle Market
Satellite
Europe Remote Sensing Satellites Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Germany Satellite Connectivity Market
Satellite
Europe Satellite Manufacturing Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
High Altitude Pseudo Satellites Market
Satellite
High-Throughput Satellite Market
Satellite
Latin America Satellite Connectivity Market
Satellite
Europe Satellite IoT Market
Satellite
North America Small Satellite Market