
 Global Aerospace Maintenance Chemical Market | 2026-2036
Global Aerospace Maintenance Chemical Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerospace Maintenance Chemical Market Foresight
Defense contractors is collapsing the historical dominance of commercial airlines as the primary buyer archetype for aerospace maintenance chemicals. Henkel AG & Co. KGaA leverages its adhesive and sealant portfolio to anchor European defense supply chains. Exxon Mobil Corporation sustains a leading position in aviation lubricants through captive refining and additive chemistry expertise. PPG Industries differentiates via coating-adjacent chemical systems that protect structural airframe components.
Aerospace maintenance chemicals encompass specialized formulations including cleaning agents, lubricants, sealants, and corrosion inhibitors engineered to withstand extreme thermal cycles, pressure differentials, and material compatibility constraints inherent to turbine engines and composite airframes. These chemicals serve the essential industrial purpose of preserving airworthiness, extending component life cycles, and ensuring operational safety across fixed-wing and rotary-wing platforms. Cleaning agents command the largest volume share due to mandatory pre-inspection surface protocols, while corrosion inhibitors represent the fastest-expanding margin pool as operators extend aircraft utilization periods amid fleet renewal delays. Sealants retain structural importance in fuel tank and pressure vessel applications, though growth rates trail specialty protective chemistries.
REACH restricts substance authorization for cadmium-based corrosion compounds and perchlorate-containing cleaners across European maintenance operations. The FAA mandates material compatibility testing under 14 CFR Part 43, while EPA oversight governs volatile organic compound emissions from solvent-based formulations used in US hangar environments. Stakeholders must monitor evolving substance restriction timelines and qualification testing burdens that determine market access across jurisdictions.
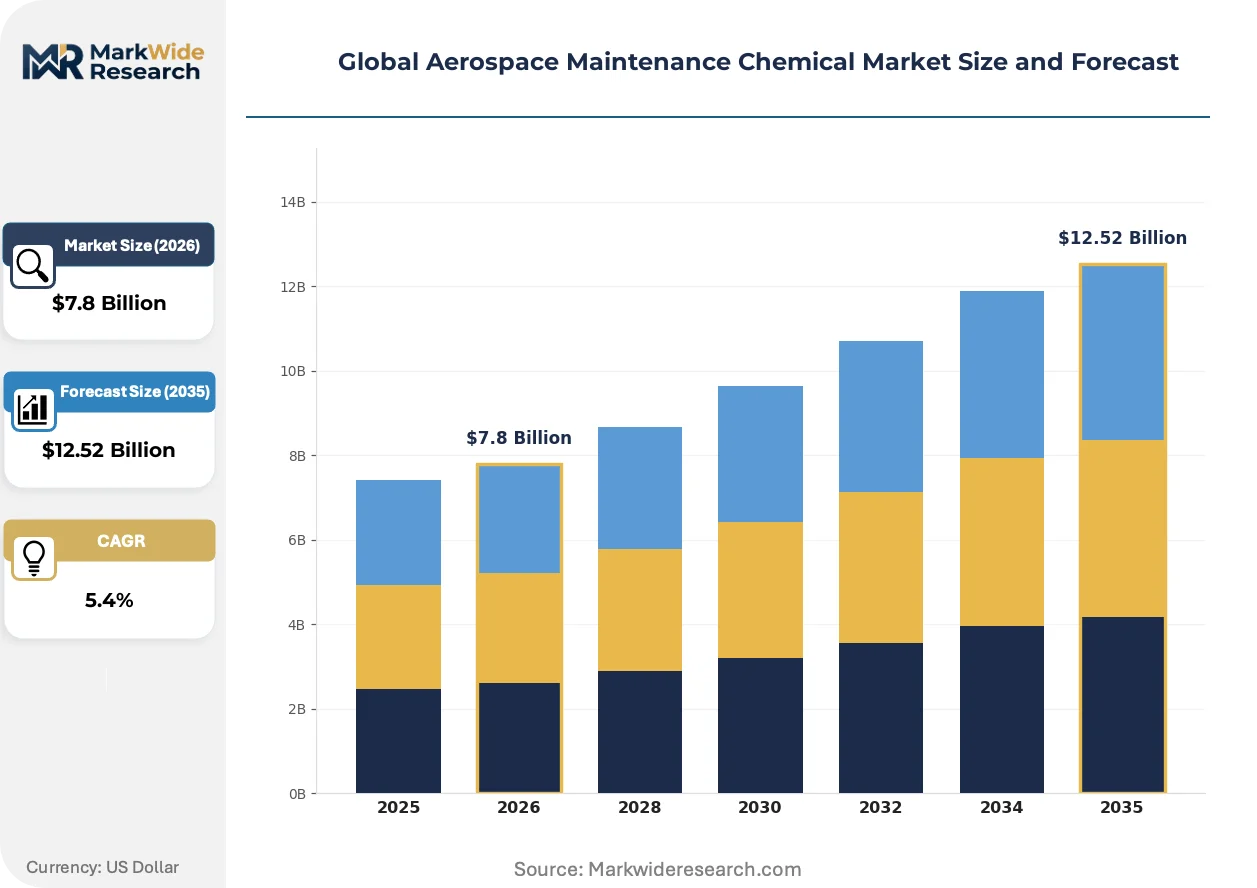
Market Dynamics
Defense procurement of corrosion inhibitors and advanced lubricants for fighter jet fleets is collapsing the historical commercial aviation dominance in aerospace maintenance chemical demand, while REACH and EU AI Act compliance requirements in Europe are elevating formulation standards and testing protocols.
Growth Catalysts
- REACH substance authorization protocols:Cadmium-based corrosion compound restrictions across European maintenance operations are forcing reformulation investments that expand addressable market for compliant specialty chemistries.
- Fighter jet fleet modernization:Defense contractors are expanding procurement of corrosion inhibitors and advanced lubricants, creating sustained demand independent of commercial aviation cycles.
- Composite airframe penetration:Material compatibility constraints inherent to turbine engines and carbon fiber structures require specialized cleaning agents and sealants with exacting thermal cycle performance.
Market Restraints
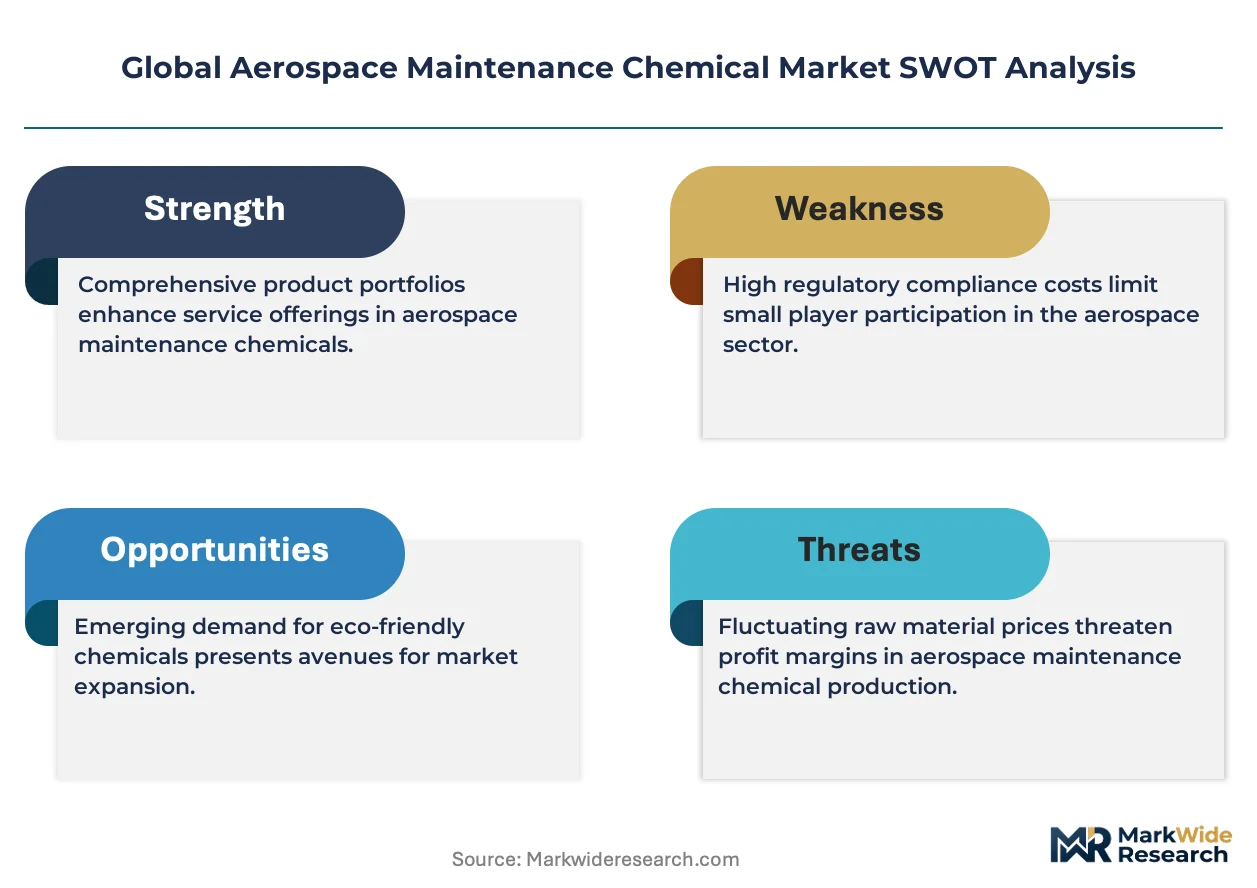
- Specialty additive cost volatility:Captive refining advantages concentrate with integrated petroleum majors, squeezing formulation margins for independent chemical suppliers dependent on spot market feedstocks.
- German supply concentration:Lufthansa Technik and Airbus maintenance hubs drive specialized chemical consumption, creating geographic demand vulnerability and procurement leverage asymmetry.
- Perchlorate cleaner substitution timeline:EPA oversight of volatile organic compound emissions from solvent-based formulations in US hangar environments compresses viable product shelf life before mandated phase-out.
Strategic Opportunities
- India defense aviation expansion:Underpenetrated maintenance infrastructure for indigenous fighter programs creates first-mover positioning for corrosion inhibitor suppliers meeting DGFT import substitution frameworks.
- FAA 14 CFR Part 43 material compatibility testing:Regulatory qualification burdens deter commodity entrants, protecting margin pools for incumbent specialists with established airworthiness certification dossiers.
- Digital formulation archives:Convergence of additive chemistry expertise with blockchain traceability systems enables outcome-based chemical performance contracts replacing transactional volume sales.
Industry Challenges
- Airworthiness certification timeline compression:FAA and ECHA parallel qualification pathways for novel corrosion inhibitors extend time-to-revenue for reformulated products beyond typical R&D amortization windows.
- Legacy fleet chemical inventory interoperability:Extended aircraft utilization periods amid fleet renewal delays force maintenance operators to manage multi-generational sealant and lubricant specifications with incompatible application protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerospace Maintenance Chemical Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cleaning Agents, Lubricants, Sealants, Corrosion Inhibitors, Solvents, Adhesives Application: Surface Preparation, Component Cleaning, Engine Maintenance, Structural Protection, Hydraulic System Care, Electrical Contacts Cleaning End User: Commercial Airlines, Defense Contractors, Maintenance Repair Organizations, Aircraft Manufacturers, Private Jet Operators, Unmanned Vehicle Operators Packaging Type: Drums, Aerosol Cans, Bottles, Bulk Containers, Cartridges, Tins |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Exxon Mobil Corporation, Eastman Chemical Company, Arrow Solutions, The Dow Chemical Company, Florida Chemical Supply, Aerochemicals, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerospace Maintenance Chemical Market Shifts & Advancements
Synthetic ester base stocks and ionic liquid lubricant additives are actively displacing mineral oil formulations in turbine engine applications, while regulatory substance restriction timelines are compressing product development cycles and forcing anticipatory compliance investments.
Bio-derived synthetic ester base stocks with superior thermal oxidative stability are displacing Group III mineral oil formulations in high-performance turbine lubricants. Military aviation procurement offices in Germany and the United States are mandating these chemistries for next-generation fighter engine platforms. This displacement is compressing addressable volume for conventional petroleum-derived products while expanding margin capture for additive package specialists with captive esterification capabilities.
REACH authorization requirements for cadmium-based corrosion compounds and perchlorate-containing cleaners are forcing complete formulation architecture rebuilds across European MRO operations. Industrial consequence includes mandatory substitution testing protocols that extend qualification timelines and elevate R&D recovery thresholds. German maintenance hubs at Lufthansa Technik and Airbus Hamburg are responding by consolidating supplier relationships with integrated chemical houses possessing in-house toxicology and environmental fate assessment capabilities.
Performance-based chemical service contracts are displacing transactional volume purchasing across major airline maintenance divisions. Lufthansa Technik and comparable Tier-1 MRO providers are unbundling chemical supply from application labor, instead contracting guaranteed surface protection outcomes with penalty clauses for corrosion-related component removal. This behavioral shift is most visible in Germany and the United States, where fleet utilization metrics and extended lease return inspections create quantifiable financial exposure for inadequate chemical performance.
Global Aerospace Maintenance Chemical Market Segmentation
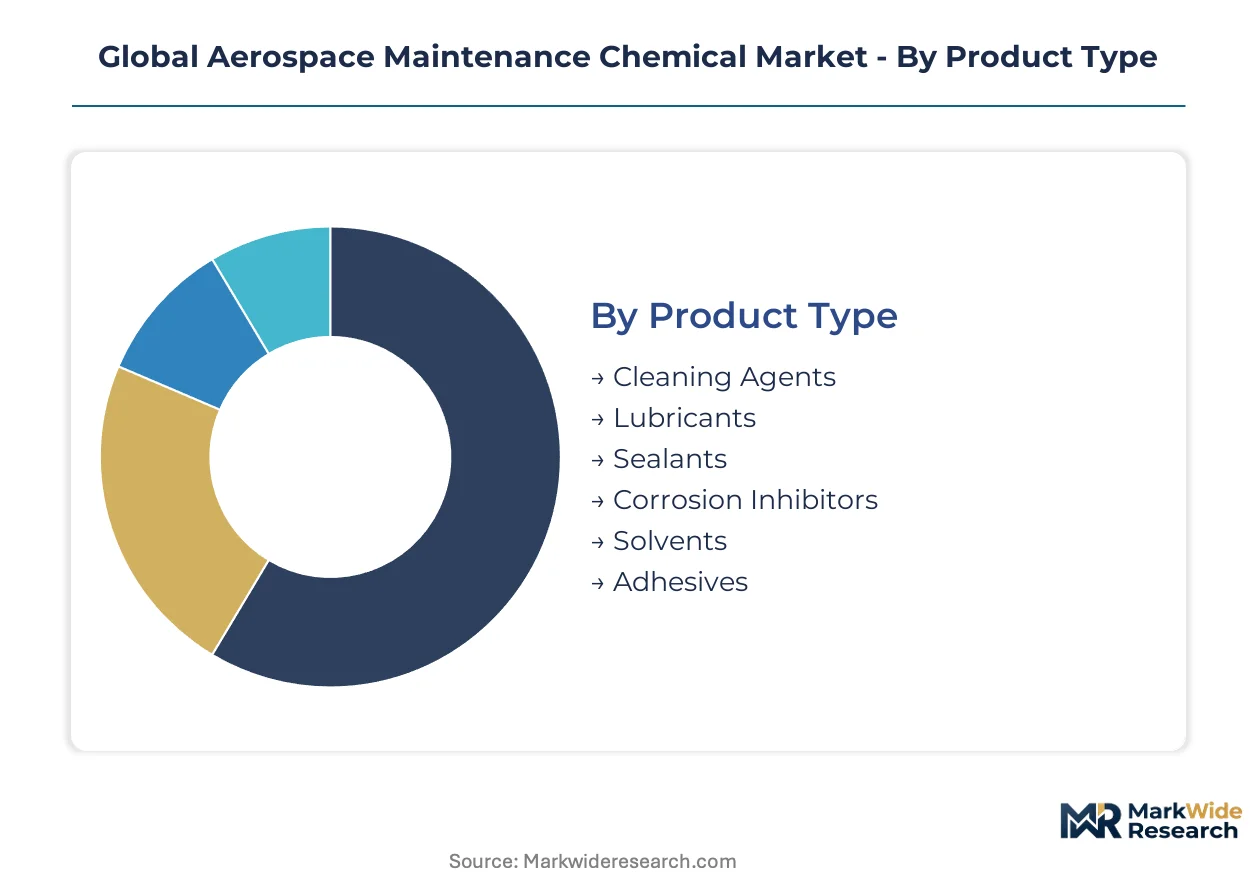
Aerospace maintenance chemicals flow through highly specialized procurement channels where regulatory compliance and performance certification determine supplier eligibility. Segment boundaries reflect distinct technical specifications, application protocols, and end-user purchasing behaviors that shape formulation development priorities.
Product Type:
Channel mix varies sharply across product categories, with cleaning agents and lubricants dominating direct airline procurement while corrosion inhibitors and sealants route through OEM-authorized distributor networks.
- Cleaning Agents:Alkaline aqueous solutions and solvent blends formulated for turbine engine degreasing and pre-inspection surface protocols. Mandatory FAA 14 CFR Part 43 compliance for commercial carriers at Delta Air Lines and United Airlines maintenance bases drives specification rigidity and long-term supply contracts.
- Lubricants:Synthetic ester base stocks and ionic liquid additives engineered for thermal oxidative stability in high-performance turbine applications. Defense procurement offices in Germany and the United States mandate these chemistries for next-generation fighter engine platforms, creating insulated demand cycles independent of commercial aviation volatility.
- Sealants:Polysulfide and polythioether compounds for fuel tank and pressure vessel sealing.
- Corrosion Inhibitors:Cadmium-free formulations replacing legacy compounds under REACH authorization timelines.
- Solvents:Low-VOC alternatives for hangar surface preparation and component rinsing.
- Adhesives:Structural bonding agents for composite airframe repair and assembly.
By volume, Cleaning Agents leads. By growth pace, Corrosion Inhibitors is climbing the fastest.
Application:
Cost tier stratification separates high-value engine maintenance formulations from commodity surface preparation chemicals, with price multiples of 4-8x between specification grades.
- Engine Maintenance:High-temperature lubricants and thermal barrier coatings requiring OEM qualification testing. Rolls-Royce and Pratt & Whitney authorized service centers in Singapore and the United Kingdom enforce proprietary chemical specifications that lock out unapproved suppliers.
- Structural Protection:Corrosion prevention systems for aluminum and composite airframes exposed to salt-laden atmospheres. Extended lease return inspection protocols at Lufthansa Technik Hamburg and ST Engineering Singapore drive outcome-based contracting with guaranteed surface protection metrics.
- Surface Preparation:Degreasing and etching agents for pre-coating substrate conditioning.
- Component Cleaning:Precision solvents for avionics and hydraulic part refurbishment.
- Hydraulic System Care:Phosphate ester fluids and conditioning additives for flight control systems.
- Electrical Contacts Cleaning:Non-residue solvents for connector and switch maintenance.
Engine Maintenance commands premium pricing. Structural Protection is gaining share fastest as fleet utilization periods extend.
End User:
Customer type determines procurement leverage, with defense contractors consolidating volumes through long-term supply agreements while Maintenance Repair Organizations fragment demand across multiple supplier relationships.
- Defense Contractors:Corrosion inhibitors and advanced lubricants for fighter jet fleet sustainment. Lockheed Martin and BAE Systems procurement offices in the United States and United Kingdom specify military-grade formulations with traceability requirements that favor integrated chemical houses.
- Maintenance Repair Organizations:Full-spectrum chemical portfolios for third-party airline servicing. AAR Corporation and Lufthansa Technik operations in Germany and the United States unbundle chemical supply from labor, contracting guaranteed performance outcomes with penalty clauses.
- Commercial Airlines:High-volume cleaning agent and lubricant consumption for in-house maintenance.
- Aircraft Manufacturers:Sealants and adhesives for production line assembly and delivery preparation.
- Private Jet Operators:Specialized formulations for corrosion-prone intermittent-use aircraft.
- Unmanned Vehicle Operators:Lightweight, low-toxicity chemistries for drone maintenance protocols.
Commercial Airlines leads by current volume. Defense Contractors is expanding most quickly as military aviation procurement accelerates.
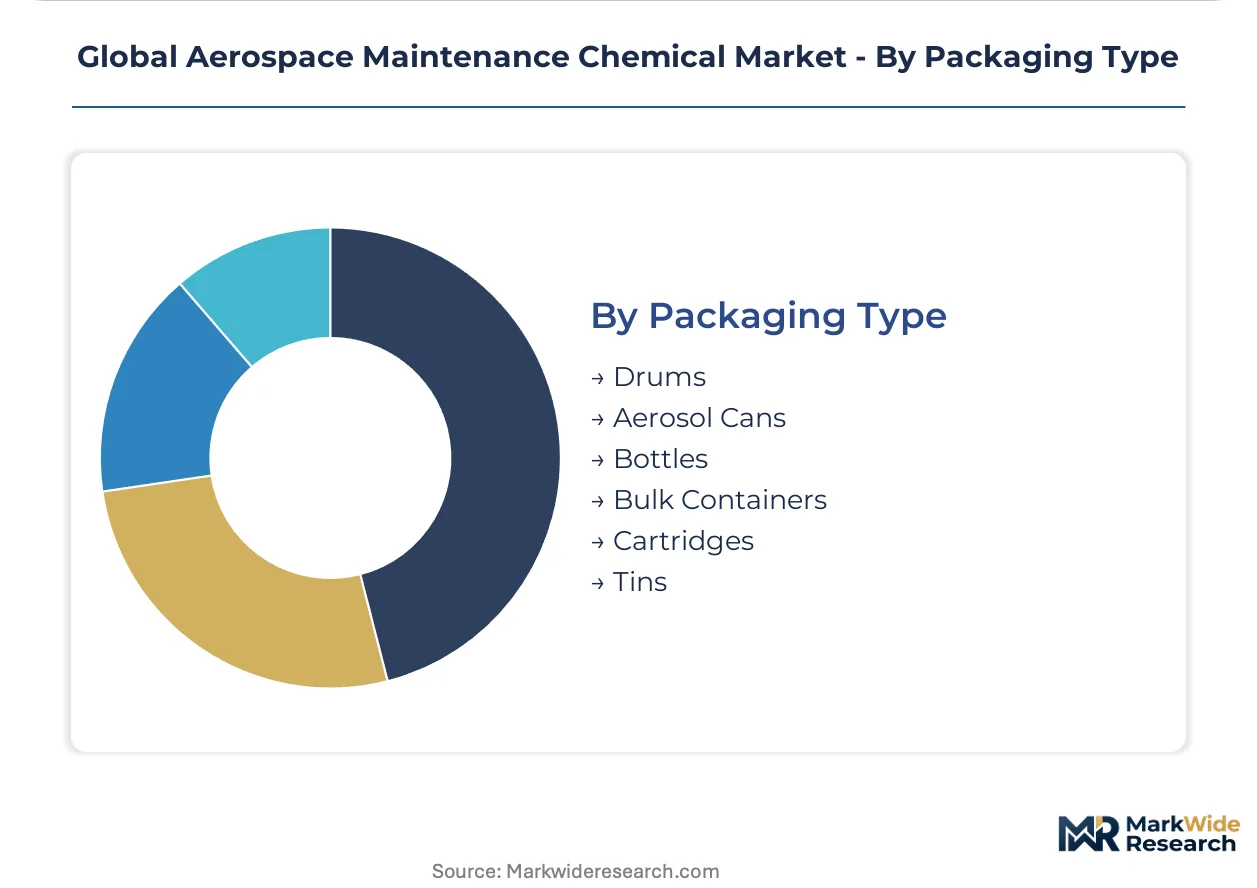
Packaging Type:
Supply concentration in drum and bulk container formats reflects the economics of high-volume airline and MRO consumption, while aerosol and cartridge formats serve dispersed field maintenance applications.
- Drums:55-gallon steel containers for cleaning agents and solvents at major maintenance hubs. Lufthansa Technik Hamburg and Airbus Toulouse facilities specify UN-certified drum specifications with integrated dispensing systems for hangar efficiency.
- Bulk Containers:Intermediate bulk containers and tanker deliveries for lubricant and hydraulic fluid replenishment. Singapore Changi and Dubai International airport fueling and chemical storage infrastructure supports just-in-time bulk delivery to airline technical operations centers.
- Aerosol Cans:Portable formulations for line maintenance and field repair access.
- Bottles:Precision-dispense containers for adhesives and touch-up sealants.
- Cartridges:Pre-measured sealant and adhesive delivery systems for controlled application.
- Tins:Small-format packaging for specialty greases and corrosion inhibitors.
Drums dominate current shipment volumes. Bulk Containers is advancing fastest as airport chemical infrastructure modernizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense contractors in the United States and Germany now command procurement volumes that rival commercial airline purchasing, while REACH compliance timelines in Europe and FAA certification requirements in North America reshape supplier qualification burdens across national boundaries.
United States
Lockheed Martin and BAE Systems procurement offices specify military-grade corrosion inhibitors with traceability requirements that favor integrated chemical houses. EPA oversight governs volatile organic compound emissions from solvent-based formulations in US hangar environments. Greater Seattle and Dallas-Fort Worth maintenance hubs concentrate demand for synthetic ester lubricants serving next-generation fighter engine platforms.
Germany
Lufthansa Technik Hamburg and Airbus operations drive specialized chemical consumption for extended lease return inspection protocols. REACH authorization requirements for cadmium-based compounds force complete formulation architecture rebuilds across European MRO operations. The Hamburg-Toulouse aerospace corridor anchors supplier consolidation with integrated chemical houses possessing in-house toxicology assessment capabilities.
United Kingdom
Rolls-Royce authorized service centers enforce proprietary chemical specifications that lock out unapproved suppliers from high-temperature lubricant procurement. ECHA substance restriction timelines compress product development cycles for reformulated corrosion inhibitors. Derby and Bristol aerospace clusters concentrate demand for OEM-qualified thermal barrier coatings and engine maintenance formulations.
Singapore
ST Engineering and Singapore Changi airport technical operations centers unbundle chemical supply from labor, contracting guaranteed surface protection outcomes with penalty clauses. Changi airport fueling and chemical storage infrastructure supports just-in-time bulk delivery to airline maintenance divisions. The city-state's position as Asia-Pacific MRO hub concentrates procurement leverage for intermediate bulk container lubricant replenishment.
India
Indigenous fighter programs create first-mover positioning for corrosion inhibitor suppliers meeting DGFT import substitution frameworks. Underpenetrated maintenance infrastructure for defense aviation expansion elevates addressable market for qualified specialty chemistry providers. Bengaluru and Hyderabad defense manufacturing clusters concentrate demand for military-grade formulations with domestic content requirements.
Global Aerospace Maintenance Chemical Market Competitive Landscape
Player mix skews toward integrated petroleum majors and specialty chemical houses with captive additive chemistry expertise. The vendor base separates into three tiers: multinational conglomerates with refining integration, mid-cap specialists with airworthiness certification dossiers, and regional distributors serving fragmented MRO procurement. Consolidation pressures favor integrated houses with in-house toxicology capabilities. Competitive moves center on anticipatory REACH compliance investments and performance-based service contract structures that displace transactional volume sales.
Within the integrated petroleum major tier, Exxon Mobil Corporation anchors aviation lubricant supply through captive refining advantages. Among specialty chemical houses, Henkel AG & Co. KGaA and PPG Industries exemplify divergent positioning—Henkel leverages adhesive and sealant portfolios for European defense supply chains, while PPG occupies a position in coating-adjacent chemical systems for structural airframe protection. Eastman Chemical Company and The Dow Chemical Company sit within the diversified chemical conglomerate archetype, representing formulation breadth that spans multiple aerospace maintenance categories without segment-specific dominance.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Exxon Mobil Corporation |
| Eastman Chemical Company |
| Arrow Solutions |
| The Dow Chemical Company |
| Florida Chemical Supply |
| Aerochemicals |
| PPG Industries |
| Others |
Supply & Pricing Matrix
Long-term performance-based contracts with indexed raw material pass-through clauses lock in supply access for Tier-1 MRO providers while anchoring price visibility across volatile additive chemistry feedstocks. Lufthansa Technik and comparable operators in Germany unbundle chemical procurement from application labor, substituting guaranteed corrosion protection outcomes for transactional volume purchasing.
Pricing Analysis
Cost-plus arrangements with feedstock indexation to Group III mineral oil and synthetic ester base stock benchmarks dominate lubricant procurement for defense aviation programs. Three-tier pricing structure across OEM-qualified, MRO-standard, and line-maintenance economy levels separates specification grades with 4-8x price multiples. Cost compression in commodity cleaning agents intensifies because REACH-compliant reformulation investments concentrate margin capture with integrated chemical houses. Defense contractors exhibit lowest price sensitivity due to traceability mandates, while independent regional MROs face acute margin pressure from spot market feedstock exposure.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp chemical corridors and container availability constraints across Hamburg-Bremerhaven trade lanes elevate inbound logistics costs for European MRO hubs. Manufacturing gravity centers on Germany, the United States, and Singapore, with specialty additive production anchored in Ludwigshafen and Houston clusters. Formulation draws from captive esterification capabilities, ionic liquid additive packages, and cadmium-free corrosion compound precursors. Single-source vulnerability concentrates in REACH-authorized specialty chemical intermediates. Distribution runs through OEM-authorized distributor networks for corrosion inhibitors and sealants, while cleaning agents and lubricants flow direct to airline procurement divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment moat where airworthiness certification dossiers create switching costs that protect incumbent positions across multi-year fleet sustainment cycles.
For Market Incumbents: Fortify certification barriers by deepening toxicology and environmental fate assessment capabilities in-house, responding to ECHA substance restriction timelines that extend qualification pathways beyond typical R&D amortization windows. Expand captive esterification capacity to offset feedstock cost volatility from integrated petroleum majors. Consolidate supplier relationships with German MRO hubs facing mandatory reformulation investments under REACH authorization protocols. For New Entrants and Emerging Players: Differentiate on blockchain-enabled traceability systems that enable outcome-based performance contracts displacing transactional volume sales. Target underpenetrated India defense aviation maintenance infrastructure for indigenous fighter programs, positioning against DGFT import substitution frameworks. Pursue white-label formulation partnerships with established airworthiness certification holders to bypass FAA 14 CFR Part 43 qualification burdens. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists possessing established airworthiness certification dossiers and in-house REACH compliance capabilities rather than commodity formulation houses exposed to spot market feedstock volatility. The acquisition target archetype combines captive additive chemistry expertise with performance-based service contract portfolios at Lufthansa Technik or comparable Tier-1 MRO providers. Monitor fighter jet fleet modernization procurement acceleration as inflection indicator for defense aviation chemical demand decoupling from commercial aviation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Ester Base Stocks | Captive esterification capabilities insulate margin capture from petroleum major feedstock pricing power. |
| REACH Compliance Investment Acceleration | Anticipatory toxicology assessment capabilities secure supplier status with Hamburg and Toulouse aerospace clusters. |
| Performance-Based Service Contract Expansion | Outcome-based corrosion protection guarantees at Lufthansa Technik displace transactional volume purchasing. |
| India Defense Aviation Market Entry | DGFT import substitution frameworks create first-mover positioning for qualified corrosion inhibitor suppliers. |
| Blockchain Traceability System Deployment | Digital formulation archives enable penalty-clause contracting with guaranteed surface protection metrics. |
Research Methodology
Desk research of customs trade databases, ECHA substance restriction filings, and FAA airworthiness directives preceded structured interviews with MRO procurement directors, defense aviation program managers, specialty chemical R&D leads, and OEM authorized service center operators. Secondary validation drew from SEC 10-K disclosures of integrated petroleum majors, ACC and Cefic chemical industry reports, and airline technical operations expenditure patterns. Bottom-up volume estimates across product categories triangulated against top-down market sizing from defense procurement disclosures and commercial fleet utilization data.
Variance decomposition across product type, application tier, end-user archetype, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by price realization trends across OEM-qualified and MRO-standard specification grades. Modeled inputs incorporated fighter jet fleet modernization procurement schedules, REACH authorization phase-out timelines, and synthetic ester displacement curves in turbine lubricant formulations.
The analysis sits within stated boundaries; outcomes outside sustained defense aviation procurement acceleration, REACH compliance timeline adherence, or synthetic ester cost parity achievement would require recalibration. Forecasts reflect documented assumptions regarding fleet utilization extension patterns and regulatory qualification burden trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
Southeast Asia Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market
Aircraft Maintenance and MRO Solutions
Airplane Pushback Tug Market
Aircraft Maintenance and MRO Solutions
Aerospace and Defense MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
United States Airframe MRO Market
Aircraft Maintenance and MRO Solutions
Military Aviation Maintenance, Repair, and Overhaul Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market