
 Small Off-Road Engines Market | 2026-2036
Small Off-Road Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Small Off-Road Engines Market Intelligence
The gap between premium four-stroke fuel-injected engines and commodity carbureted two-stroke units is repositioning procurement patterns across the supply chain. Honda Motor Co., Ltd. leverages its overhead cam architecture to sustain pricing power in lawn and garden applications. Briggs & Stratton anchors the North American replacement engine channel through extensive service-dealer networks. Loncin Motor Co., Ltd. competes aggressively on cost in compact construction equipment for emerging markets.
Small off-road engines are compact internal combustion or electric powerplants typically rated below 25 horsepower, designed for non-highway mobile equipment and outdoor power tools. These engines employ air-cooled cylinder blocks, cast-iron liners, and splash or pressurized lubrication systems to deliver rotational power to pumps, blades, augers, and drivetrains in environments where emissions compliance and noise suppression matter. Gasoline engines still dominate installed base volumes, though electric engines are capturing the fastest growth in municipal and residential lawn equipment where noise ordinances and battery swapping infrastructure mature. Four-stroke technology leads in agricultural machinery and portable generators due to torque characteristics and fuel efficiency requirements, while fuel injection systems are displacing carburetor platforms in regions with stringent evaporative emission rules.
EPA Phase 3 standards and CARB regulations in the United States enforce evaporative emission controls and exhaust limits that filter which engine architectures reach commercial viability. The EU F-Gas Regulation and Stage V non-road emission framework shape product development priorities for equipment exported to Europe. Stakeholders must monitor how battery energy density improvements and fast-charging standards alter the total cost of ownership calculus against established small-displacement combustion platforms.
Market Dynamics
EPA Phase 3 emission standards and CARB small off-road engine regulations are compressing the commercial viability of carbureted two-stroke architectures while elevating fuel-injected four-stroke platforms. Equipment manufacturers face simultaneous pressure to redesign powertrains and absorb compliance costs without losing price-competitive positions in the replacement engine channel.
Growth Catalysts
- Professional Landscaping Services:Landscape contractors in the United States are expanding equipment fleets as outdoor maintenance services professionalize and property management companies outsource groundskeeping.
- CARB Regulatory Stringency:California Air Resources Board regulations on evaporative emissions are forcing technology upgrades that create replacement demand for compliant engine platforms.
- Battery Swapping Infrastructure:Municipalities with noise ordinances are deploying battery-swapping stations for electric lawn equipment, accelerating electrification in residential and commercial segments.
Market Restraints
- Aluminum Alloy Cost Volatility:Engine block and cylinder head casting costs fluctuate with aluminum commodity markets, squeezing margins on air-cooled engine production.
- Supply Concentration in Precision Fuel Injection:High-pressure fuel injector and ECU sourcing concentrates among a limited supplier base in Germany and Japan, creating procurement bottlenecks.
- Energy Density Limitations:Lithium-ion battery packs for equivalent power output weigh substantially more than gasoline tanks, constraining runtime in commercial cutting applications.
Strategic Opportunities
- India Compact Construction Equipment:Infrastructure investment and rural mechanism are driving demand for cost-optimized engines in mini-excavators and plate compactors.
- EU Stage V Export Compliance:Engine architectures meeting European non-road emission frameworks gain preferential access to high-margin agricultural machinery markets.
- Telematics-Enabled Fleet Management:Integration of engine diagnostics with equipment rental platforms allows usage-based pricing and predictive maintenance contracts.
Industry Challenges
- Calibration Engineering Talent Scarcity:Fuel injection system tuning and emissions control software development require specialized skill sets in short supply across the Midwest manufacturing corridor.
- Dual-Certification Timeline Compression:Simultaneous EPA and CARB approval processes extend product launch cycles and strain engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Off-Road Engines Market |
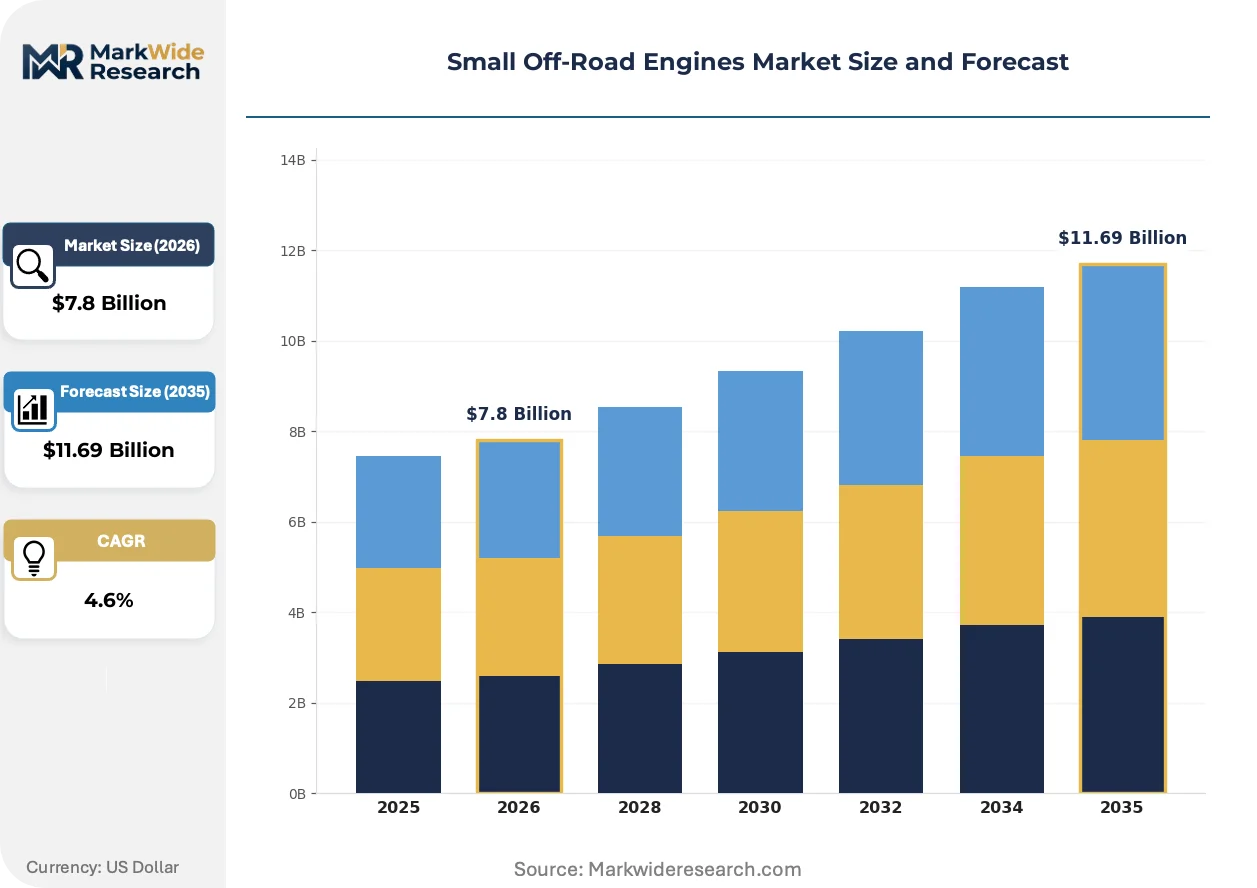
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline Engines, Diesel Engines, Electric Engines, Hybrid Engines, Hydrogen Engines Application: Lawn & Garden Equipment, Construction Equipment, Agricultural Machinery, Marine Equipment, Portable Generators Technology: Two-Stroke Engines, Four-Stroke Engines, Fuel Injection, Carburetor Systems, Air-Cooled Engines End User: Equipment Manufacturers, Landscape Contractors, Farm Operators, Recreational Vehicle Builders, Rental Services |
| Companies Covered | Honda Motor Co., Ltd., Briggs & Stratton, Kawasaki Heavy Industries, Ltd., Kohler Co., Kubota Corporation, Yamaha Motor Co., Ltd., Yanmar Co., Ltd., Loncin Motor Co., Ltd., Motorenfabrik Hatz GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Off-Road Engines Market Strategic Shifts & Innovations
Powertrain electrification and connected equipment architectures are redrawing competitive boundaries between traditional engine manufacturers and battery system suppliers. Technology roadmaps now converge on modular platforms that accommodate both combustion and electric power sources.
Electronic fuel injection with closed-loop oxygen sensing is expanding into mid-displacement lawn and garden engines previously served by carburetors. Residential equipment buyers in noise-sensitive suburbs are accepting modest price premiums for fuel-injected models. This architecture shift is expanding into the replacement engine aftermarket as independent service dealers retrofit older equipment.
The EU F-Gas Regulation and Stage V non-road emission framework are tightening particulate and NOx limits for engines exported to European agricultural markets. Manufacturers must redesign combustion chambers and exhaust aftertreatment for sub-25 horsepower categories. Compact tractor and portable generator segments face the steepest compliance cost increases, accelerating platform consolidation among export-oriented suppliers.
Equipment rental fleets are unbundling maintenance contracts from capital leases and charging separately for engine-hour-based service. National rental chains in the United States are consolidating purchasing power and demanding standardized diagnostic ports across supplier brands. This procurement restructuring is most advanced in Sun Belt states where year-round equipment utilization supports subscription-style service models.
Small Off-Road Engines Market Segmentation
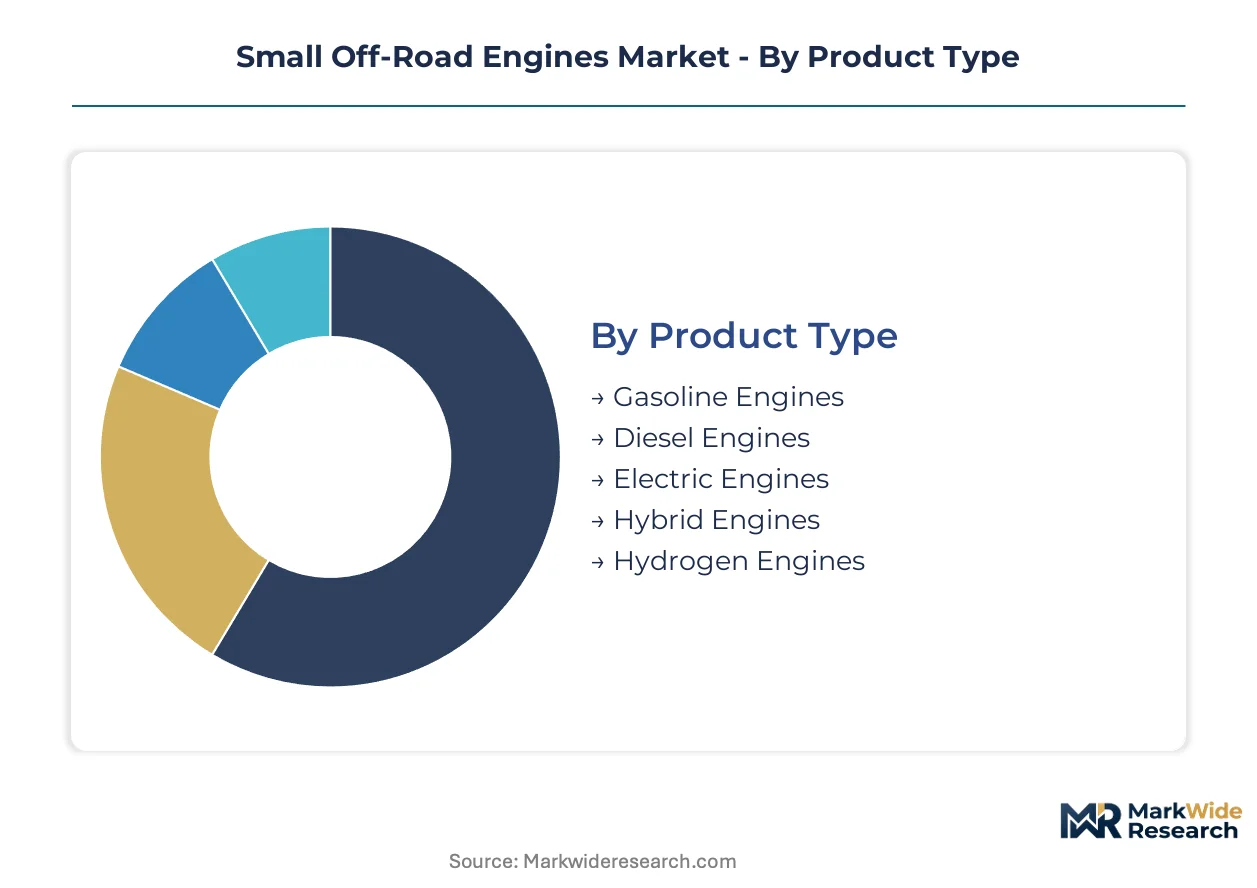
Segmentation in the small off-road engines market reveals how emissions compliance, power density requirements, and end-use duty cycles fragment procurement patterns across equipment categories. Technology choices and fuel types diverge sharply between residential lawn applications and commercial construction environments.
Product Type:
Standardization dominates high-volume gasoline platforms while customization concentrates in emerging alternative fuel architectures seeking regulatory shelter.
- Gasoline Engines:Air-cooled single-cylinder and V-twin configurations deliver power densities suited to handheld equipment and compact utility vehicles. Landscape contractors in Florida and Texas specify these for extended runtime in commercial mowing fleets where refueling infrastructure is ubiquitous.
- Diesel Engines:Compression-ignition architectures with cast-iron blocks provide torque characteristics essential for mini-excavators and plate compactors. Demand concentrates in India compact construction equipment where fuel efficiency and durability outweigh first-cost premiums.
- Electric Engines:Brushless DC motors with lithium-ion battery packs eliminate evaporative emissions compliance burdens entirely.
- Hybrid Engines:Series-hybrid configurations pair small displacement combustion generators with electric traction motors.
- Hydrogen Engines:Prototype spark-ignition platforms using compressed hydrogen storage target municipal fleet conversions.
Most installed capacity flows through gasoline engines. Expansion is steepest in electric engines.
Application:
Volume concentration follows seasonal equipment utilization patterns, with geography determining which applications sustain year-round production schedules.
- Lawn & Garden Equipment:Walk-behind mowers, riding tractors, and handheld trimmers constitute the largest addressable volume segment. Sun Belt states with twelve-month growing seasons support the densest dealer service networks and fastest replacement cycles for commercial landscapers.
- Construction Equipment:Mini-excavators, skid-steer loaders, and compaction equipment demand higher displacement ranges with robust filtration for dusty environments. Rental services in Arizona and Nevada drive fleet standardization around telematics-compatible powertrains.
- Agricultural Machinery:Compact tractors and utility vehicles require PTO compatibility and torque reserve for implement work.
- Marine Equipment:Outboard motors and personal watercraft applications prioritize corrosion-resistant materials and sealed ignition systems.
- Portable Generators:Backup power units for residential and commercial emergency use emphasize low total harmonic distortion and stable frequency regulation.
Construction equipment absorbs the highest per-unit engine value. Lawn and garden applications deliver the steepest volume expansion trajectory.
Technology:
Regulatory phase-outs of carbureted two-stroke designs are compressing technology roadmaps toward fuel-injected four-stroke architectures.
- Two-Stroke Engines:Crankcase-scavenged designs with total-loss lubrication persist in handheld equipment where power-to-weight ratios dominate. EPA Phase 3 evaporative emission limits are constraining commercial viability to specialized applications with limited runtime hours.
- Four-Stroke Engines:Overhead valve and overhead cam configurations with pressurized lubrication dominate agricultural machinery and portable generators. Fuel efficiency advantages and torque characteristics align with extended duty cycles in commercial cutting and tilling operations.
- Fuel Injection:Port and direct injection systems with closed-loop oxygen sensing enable precise mixture control for emission compliance.
- Carburetor Systems:Float-type and diaphragm carburetors face regulatory obsolescence in California markets.
- Air-Cooled Engines:Finned cylinder block designs eliminate radiator weight and leakage risk for mobile equipment.
Air-cooled four-stroke platforms carry most current production volume. Fuel injection systems are climbing the fastest in share.
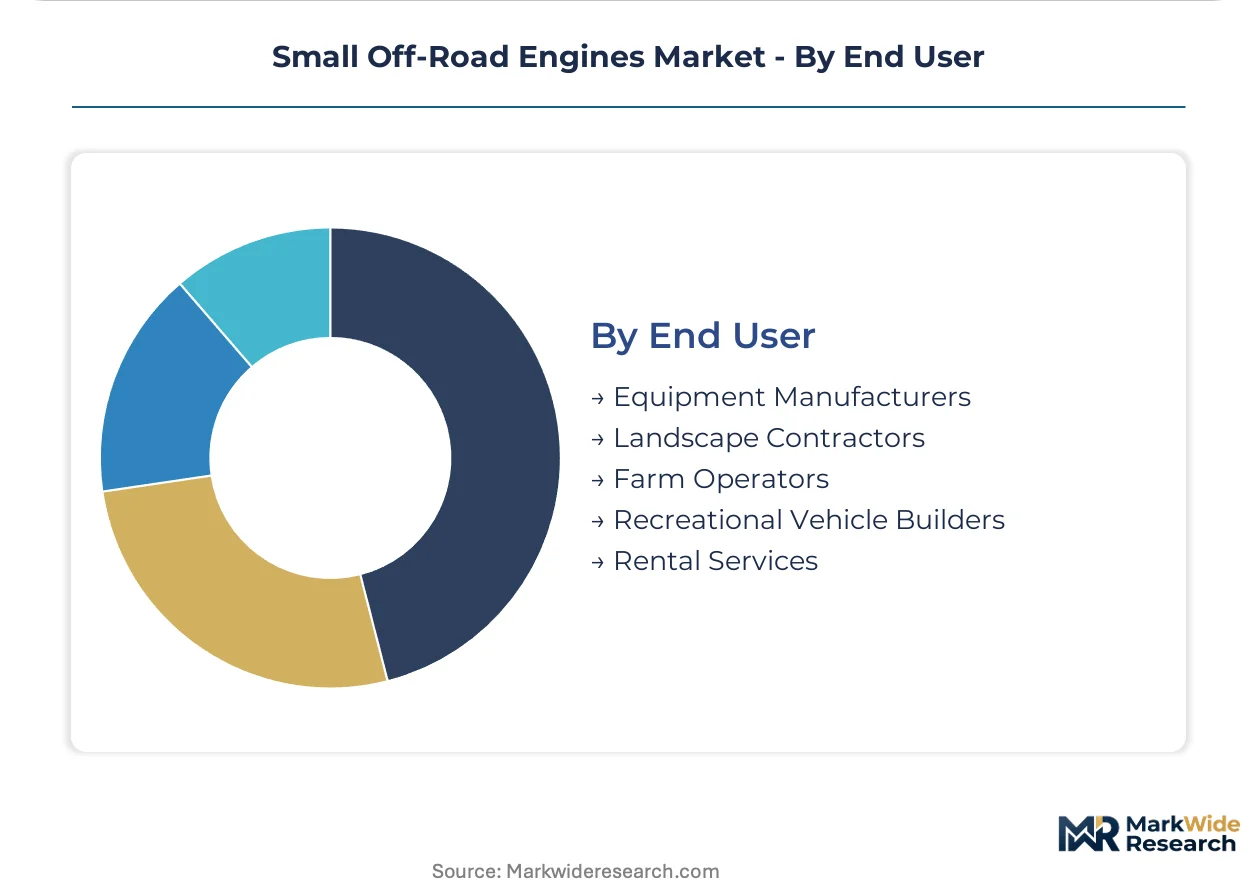
End User:
Procurement authority fragments between original equipment manufacturers specifying new platforms and independent service dealers controlling replacement engine channels.
- Equipment Manufacturers:OEMs integrate engines into finished machines with branded cowlings and control interfaces. Briggs & Stratton anchors North American supply relationships through engineering collaboration on mounting configurations and exhaust routing.
- Landscape Contractors:Commercial groundskeeping operations purchase replacement engines and short-block assemblies through authorized dealer networks. Fleet standardization around common service intervals reduces parts inventory complexity for multi-crew operations.
- Farm Operators:Owner-maintained agricultural equipment drives demand for direct-replacement engines with minimal control system integration.
- Recreational Vehicle Builders:Side-by-side and ATV manufacturers specify powertrains with CVT compatibility and suspension mounting provisions.
- Rental Services:National equipment rental chains consolidate purchasing power and demand standardized diagnostic ports across supplier brands.
Equipment manufacturers specify the majority of new engine placements. Rental services are gaining share fastest in demand aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the largest installed base of small off-road engines, while China dominates manufacturing scale for cost-optimized platforms. Regulatory divergence between EPA Phase 3 standards and EU Stage V frameworks is fragmenting product development roadmaps across geographies.
United States
Landscape contractors in Florida and Texas are expanding commercial mowing fleets to serve year-round growing seasons. EPA Phase 3 emission standards and CARB regulations in California are compressing the viability of carbureted two-stroke architectures. Engine distribution concentrates in the Midwest manufacturing corridor where service-dealer networks anchor replacement parts logistics.
Germany
Agricultural machinery exporters are redesigning compact tractor powertrains to meet EU Stage V particulate and NOx limits. The F-Gas Regulation shapes evaporative emission control requirements for equipment sold across European markets. Precision fuel injection component suppliers cluster in Baden-Württemberg, creating procurement bottlenecks for ECU and injector sourcing.
China
Infrastructure investment and rural mechanization are driving demand for mini-excavators and plate compactors in inland provinces. GB standards and MIIT directives govern non-road mobile machinery emissions compliance for domestic and export markets. Manufacturing gravity centers on Chongqing and Shandong where Loncin Motor Co., Ltd. and regional fabricators optimize casting and machining costs.
India
Compact construction equipment deployment is accelerating across highway projects and urban infrastructure builds. The CEA and BIS frameworks regulate engine emissions for agricultural and construction applications. Engine assembly operations concentrate in Maharashtra and Gujarat where cost-optimized four-stroke platforms serve domestic and African export markets.
Japan
Marine equipment and recreational vehicle manufacturers specify corrosion-resistant powertrains for outboard motor applications. METI directives and JIS standards govern small engine performance and durability certification. Industrial clusters in Shizuoka and Hamamatsu anchor precision machining capabilities for overhead cam architectures.
Small Off-Road Engines Market Key Industry Players
Top-tier vendors anchor premium fuel-injected platforms, while commodity carbureted suppliers compete on replacement engine pricing. The market structure reflects a bifurcation between emission-compliant architectures and legacy two-stroke production. Strategic archetypes include overhead cam specialists, air-cooled V-twin manufacturers, and cost-optimized single-cylinder fabricators. Competitive moves concentrate on vertical integration into fuel injection component sourcing and telematics-enabled fleet service contracts.
Among Japanese-headquartered manufacturers, Honda Motor Co., Ltd. and Yamaha Motor Co., Ltd. occupy positions emphasizing precision engineering and recreational equipment heritage. Briggs & Stratton exemplifies the North American replacement engine channel archetype through extensive service-dealer network coverage. Loncin Motor Co., Ltd. represents the China-based cost-optimization model serving emerging market construction equipment demand.
| Leading Market Players |
|---|
| Honda Motor Co., Ltd. |
| Briggs & Stratton |
| Kawasaki Heavy Industries, Ltd. |
| Kohler Co. |
| Kubota Corporation |
| Yamaha Motor Co., Ltd. |
| Yanmar Co., Ltd. |
| Loncin Motor Co., Ltd. |
| Motorenfabrik Hatz GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
National equipment rental chains in the United States are consolidating purchasing power and demanding standardized diagnostic ports, which locks in contract-based long-term offtake pricing with volume-scaled discounts. This buyer concentration shifts pricing power toward fleet operators who bundle engine-hour-based maintenance contracts separately from capital leases.
Pricing Analysis
Bundled service contracts dominate premium fuel-injected platforms while unbundled transactional pricing persists in commodity carbureted replacement engines. Price differentiation rests on EPA Phase 3 certification grade and after-sales diagnostic support breadth. Cost compression in two-stroke carbureted tiers is intensifying because CARB regulatory obsolescence narrows addressable demand. Landscape contractors show highest price sensitivity in handheld equipment, while agricultural OEMs accept premiums for EU Stage V-compliant architectures.
Supply Chain Analysis
Container freight volatility from Asia to North America is compressing margins on cast-iron cylinder block shipments. Manufacturing gravity draws from China, India, and Japan, with precision fuel injection components sourced from Germany. Aluminum alloy and high-pressure injector sourcing create single-source vulnerability in ECU procurement. Distribution runs through Midwest service-dealer networks anchoring replacement parts logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The small off-road engines market functions as a stable compounder where regulatory-driven replacement cycles sustain predictable demand. EPA Phase 3 and CARB stringency ensure continuous technology refresh obligations across installed bases.
For Market Incumbents: Deploy telematics-enabled fleet management platforms to capture recurring service revenue from rental chain consolidation. Deepen backward integration into fuel injection component sourcing to reduce procurement bottlenecks from German and Japanese suppliers. Anchor channel control through exclusive service-dealer network expansion in Sun Belt states where year-round utilization supports subscription pricing.
For New Entrants and Emerging Players: Municipal fleet managers with noise ordinance compliance mandates represent the most penetrable buyer archetype for electric powertrain platforms. Target battery-swapping infrastructure partnerships in California and Florida suburbs where residential electrification accelerates fastest. Pursue white-label engine supply to compact construction equipment OEMs serving India infrastructure builds.
For Investors and Strategic Acquirers: Precision fuel injection specialists are the most active acquirer category in this space, seeking calibration engineering talent scarce across the Midwest manufacturing corridor. Long-term viability hinges on platform modularity accommodating both combustion and electric architectures. Watch battery energy density improvements against gasoline tank weight advantages as the critical inflection signal for commercial cutting electrification.
| Strategic Initiative | Industry Significance |
|---|---|
| Fuel Injection Platform Migration | Closed-loop oxygen sensing enables EPA Phase 3 compliance in mid-displacement lawn engines. |
| Telematics Integration | Engine-hour diagnostics support usage-based pricing for Sun Belt rental fleet contracts. |
| Battery Swapping Infrastructure | Municipal station deployment accelerates electric lawn equipment adoption in noise-restricted suburbs. |
| EU Stage V Certification Investment | Particulate aftertreatment redesign unlocks high-margin agricultural machinery export access. |
| Backward Integration into ECU Sourcing | In-house production of engine control units reduces dependency on concentrated German suppliers. |
Research Approach
Multiple input streams — structured interviews with engine calibration engineers, procurement leads at rental fleet operators, and aftermarket service dealers — were reconciled against customs data, EPA certification filings, and equipment registration databases. Bottom-up unit shipment estimates from OEM production schedules were cross-validated with top-down replacement cycle modeling across the analysis window.
Historical volume trajectories were cross-referenced against expert panel assessments of regulatory phase-in timelines. Segmentation dimensions modeled include fuel type, technology architecture, application duty cycle, and end-user procurement authority. CAGRs were derived from installed base turnover rates and compliance-driven replacement elasticity, with aluminum commodity price volatility and fuel injection component lead times incorporated as sensitivity inputs.
Underlying measurement precision varies by segment; electric powertrain forecasts carry tighter precision than hydrogen prototype projections. Forecasts reflect assumptions about battery energy density improvement curves and CARB regulatory enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off-Highway Vehicle Engine Market
Off Road Vehicles
Off Highway Hybrid Vehicles Market
Off Road Vehicles
Global Off-Highway Vehicle Telematics Market
Off Road Vehicles
All-Terrain Vehicle Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
Off-Highway Vehicle Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
Four-Wheel Drive Vehicles Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
All-Terrain Vehicle (ATV) Engines Market
Off Road Vehicles
Electric Off-Road Vehicles Market
Off Road Vehicles
Global Automotive Off Highway Engine Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market