
 Off-Road Vehicles Cooling Fan Market | 2026-2036
Off-Road Vehicles Cooling Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Road Vehicles Cooling Fan Market Outlook
OEM-direct supply contracts is reshaping how cooling fan manufacturers reach off-road vehicle builders. Denso Corporation leverages its thermal systems expertise to anchor long-term agreements with major powersport brands. BorgWarner Inc. competes through specialized electric fan architectures designed for severe-duty cycles. MAHLE GmbH extends its automotive cooling portfolio into off-road applications with modular platform designs.
Off-road vehicles cooling fans are forced-air heat exchangers engineered to maintain engine and hydraulic fluid temperatures within operational thresholds across dusty, high-vibration environments; typical units withstand ambient temperatures exceeding 120°C while delivering airflow rates from 2,000 to 8,000 CFM depending on engine displacement. Electric fan technology leads product type demand as electrified auxiliary systems replace mechanical belt drives for efficiency gains. Military vehicle applications command premium thermal management specifications, while recreational ATV and UTV segments drive volume through aftermarket replacement cycles.
EPA Tier 4 Final emissions regulations in the United States and Euro Stage V standards in Europe mandate tighter engine thermal control, directly expanding cooling system capacity requirements for diesel-powered off-road equipment. NHTSA and ISO 16750-3 vibration standards further shape product durability benchmarks for fan assemblies. Stakeholders must monitor electrification roadmaps from construction and agricultural equipment OEMs, as hybrid powertrain architectures will redefine thermal load profiles and fan control strategies.
Market Dynamics
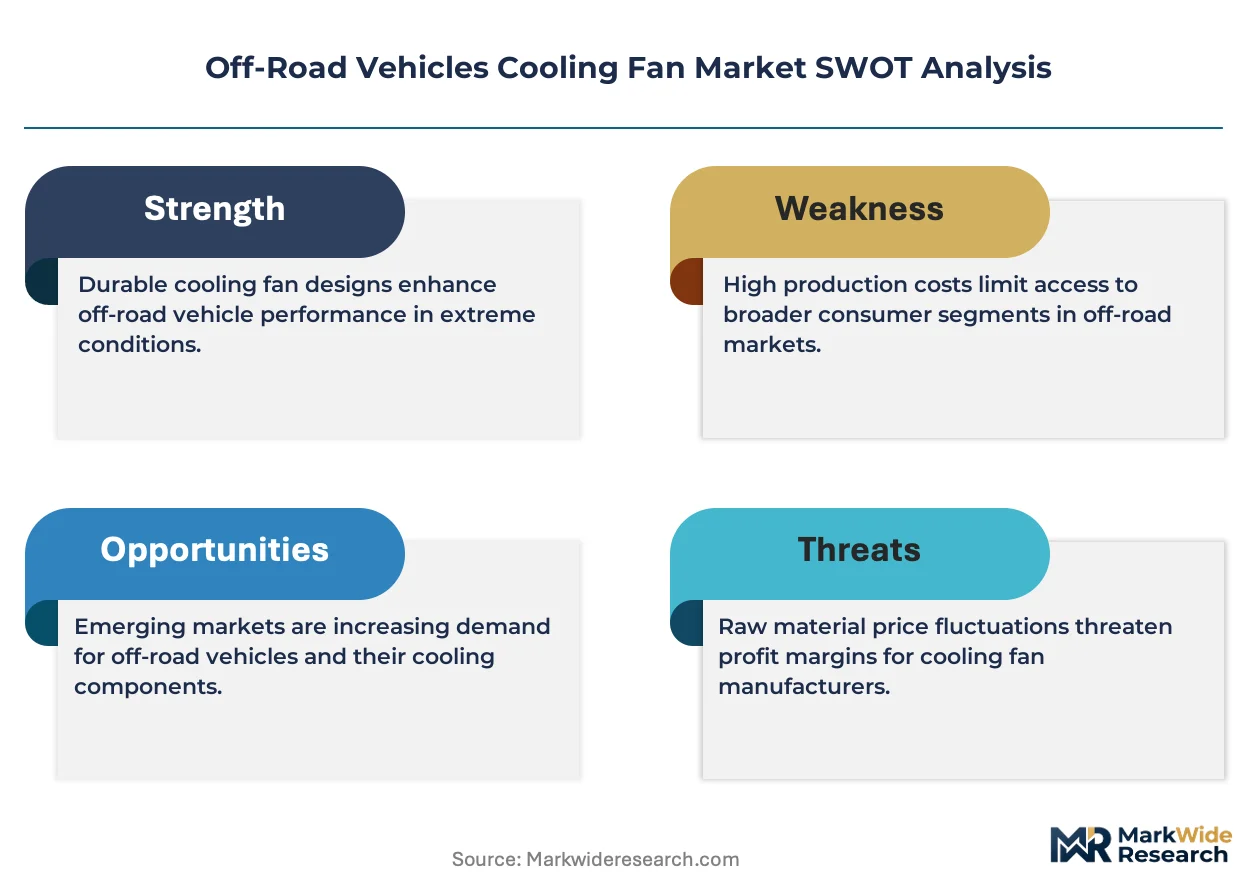
Electrification of auxiliary systems is compressing mechanical belt-drive architectures across off-road vehicle platforms, forcing cooling fan suppliers to reengineer motor control electronics and thermal interfaces for severe-duty cycles.
Growth Catalysts
- EPA Tier 4 Final:Diesel engine emissions mandates in the United States force heavier thermal loads, expanding cooling system capacity requirements for construction and agricultural equipment.
- Defense procurement:Military vehicle modernization programs specify premium thermal management for armored platforms operating in extreme ambient conditions.
- Electric fan architectures:Brushless DC motor technology replaces mechanical drives, enabling variable-speed control that optimizes power consumption across load profiles.
Market Restraints
- Raw material volatility:Copper and rare-earth magnet prices fluctuate unpredictably, squeezing margins on electric fan motor assemblies.
- Supplier concentration:High-performance motor controller semiconductors concentrate among East Asian foundries, exposing supply continuity risk.
- Technical durability thresholds:ISO 16750-3 vibration standards demand extended validation cycles that extend product qualification timelines.
Strategic Opportunities
- Hybrid powertrain integration:Converging electric cooling systems with battery thermal management creates bundled system opportunities for construction equipment OEMs.
- Aftermarket digital channels:Direct-to-fleet e-commerce platforms bypass traditional distribution tiers for replacement fan assemblies.
- Indian defense modernization:Indigenous armored vehicle programs under the Ministry of Defence create localized sourcing mandates for thermal subsystems.
Industry Challenges
- Embedded software complexity:CAN bus integration and motor control algorithms require automotive-grade firmware capabilities unfamiliar to legacy mechanical suppliers.
- Multi-standard certification:Simultaneous compliance with NHTSA, ISO, and military specifications fragments engineering resources across parallel validation tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Road Vehicles Cooling Fan Market |
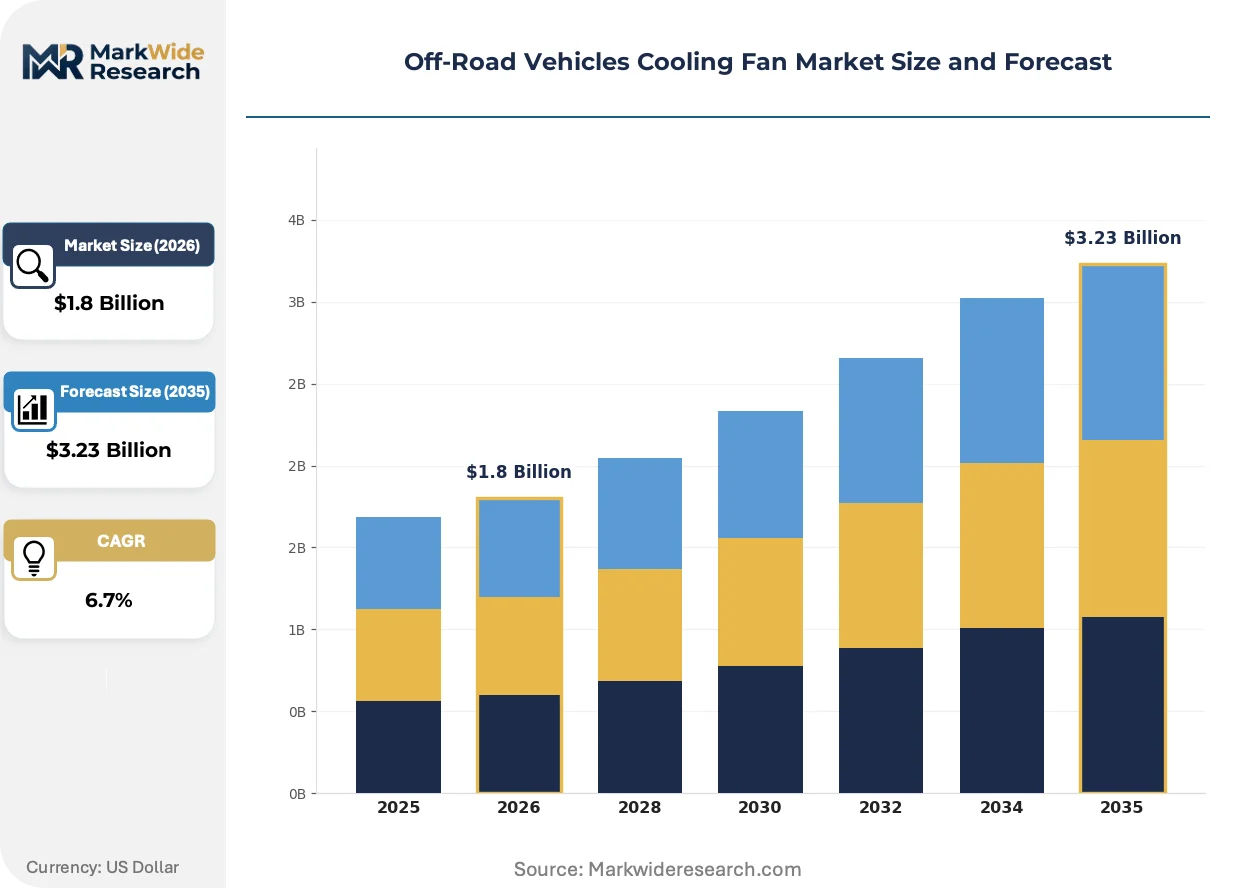
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Fan, Centrifugal Fan, Electric Fan, Belt-driven Fan Application: ATV, UTV, Dirt Bikes, Military Vehicles End User: Recreational Users, Commercial Fleets, Military Organizations, OEMs Technology: Mechanical, Electric, Hybrid, Thermostatic |
| Companies Covered | MAHLE GmbH, Gentherm Incorporated, Denso Corporation, SPAL Automotive S.R.L., Marelli Holdings Co., Ltd., Valeo SA, Nidec Corporation, AMETEK Inc., BorgWarner Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Road Vehicles Cooling Fan Market Strategic Shifts
Active thermal management intelligence is displacing passive airflow designs, with sensor networks and predictive algorithms now governing fan operation in real-time response to engine load and ambient conditions.
Smart variable-speed electric fans with integrated temperature sensing and ECU communication protocols are rendering obsolete fixed-ratio mechanical clutch fans across severe-duty off-road applications. Mining truck and construction equipment OEMs in Australia and Canada specify these systems for high-altitude operations. The shift compresses aftermarket replacement cycles while elevating electronic content value per unit.
EU Stage V emissions standards mandate closed crankcase ventilation and exhaust gas recirculation, adding parasitic thermal loads that demand supplemental cooling capacity. European agricultural machinery manufacturers respond with dual-fan architectures separating engine and charge-air cooling circuits. The regulatory pressure accelerates modular platform development to accommodate divergent regional emission tiers.
Fleet operators now unbundle aftermarket service contracts from original equipment purchases, procuring replacement cooling fans through independent distributors with lifecycle cost guarantees. This procurement fragmentation pressures OEM-captive suppliers while elevating third-party certification importance. The pattern concentrates in North American utility vehicle fleets with standardized maintenance protocols.
Off-Road Vehicles Cooling Fan Market Segmentation
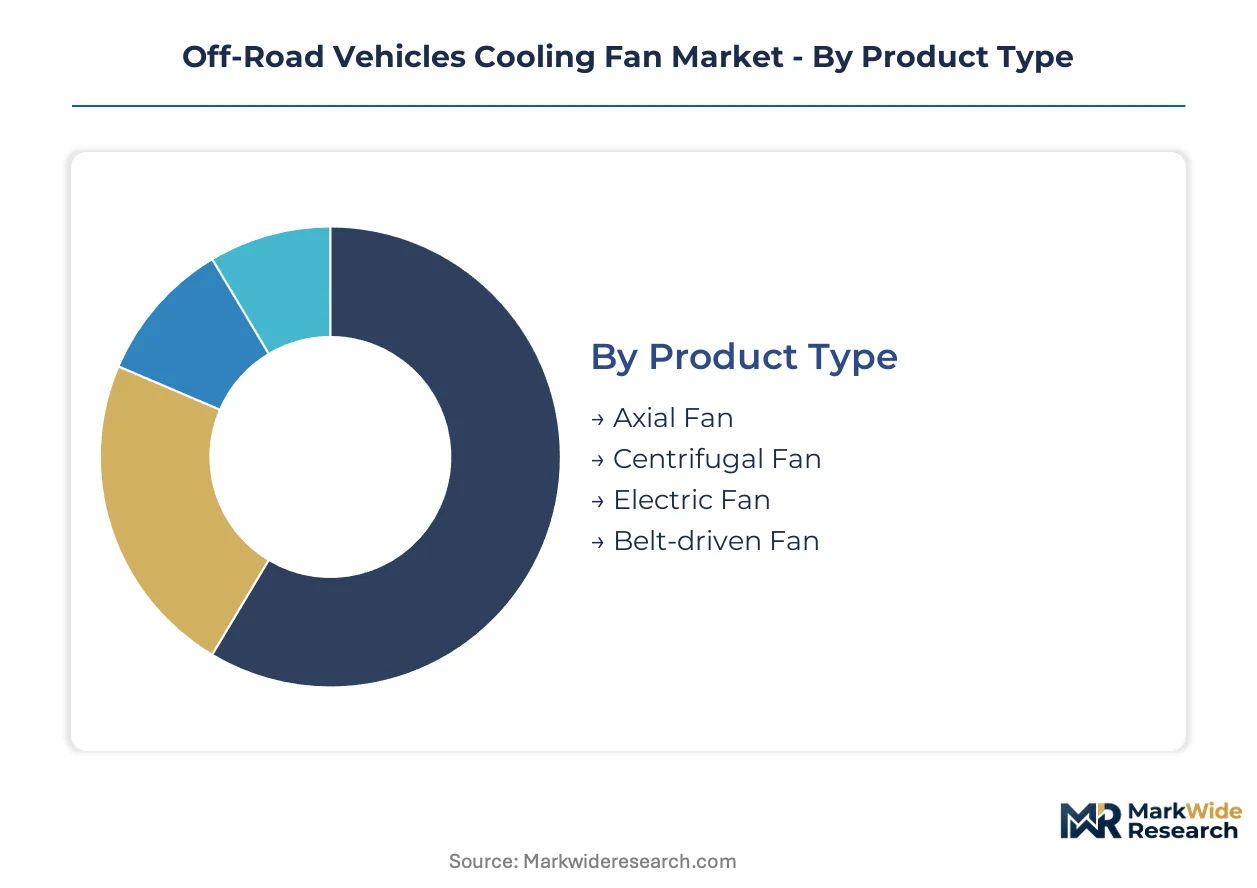
Cooling fan segmentation in off-road vehicles reflects divergent thermal loads across powertrain architectures and duty cycles. Product type selection directly determines parasitic power draw, service intervals, and compatibility with electrified auxiliary systems now displacing mechanical drives.
Product Type:
The use-case spectrum spans lightweight recreational machines through armored military platforms, each imposing distinct airflow, packaging, and durability requirements.
- Electric Fan:Brushless DC motor assemblies with integrated motor controllers enable variable-speed operation tied to engine ECU signals. Demand concentrates in United States recreational ATV and UTV segments where EPA Tier 4 Final thermal loads favor precise thermal control over mechanical efficiency losses.
- Axial Fan:Bladed impellers arranged parallel to airflow axis deliver high-volume, low-pressure cooling suited to compact engine bays. Mining and construction equipment in Australia and Canada specify these units for high-altitude operations where air density reductions demand maximum airflow rates.
- Centrifugal Fan:Radial impeller designs generate higher static pressure for ducted cooling circuits in armored vehicle applications.
- Belt-driven Fan:Mechanical clutch fans persist in cost-sensitive utility vehicle segments with standardized maintenance protocols.
Established volume favors belt-driven architectures; emerging adoption favors electric fan platforms with embedded intelligence.
Application:
Cost tier separation distinguishes premium military specifications from high-volume recreational replacement cycles.
- Military Vehicles:Armored platforms operating in ambient temperatures exceeding 120°C require redundant cooling circuits with ballistic protection ratings. United States defense procurement programs specify these systems for extreme-condition deployment, with validation cycles extending past ISO 16750-3 vibration thresholds.
- UTV:Side-by-side utility vehicles with cargo and towing duties generate sustained thermal loads across variable terrain. North American fleet operators drive aftermarket volume through unbundled service contracts procuring replacement fans via independent distributors.
- ATV:All-terrain vehicles prioritize compact packaging and weight reduction for recreational trail riding.
- Dirt Bikes:Lightweight two-wheel applications favor minimal cooling mass with high-rpm durability.
Military applications command premium pricing tiers; UTV segments generate highest replacement frequency.
End User:
Customer type determines procurement channel structure and lifecycle cost evaluation frameworks.
- OEMs:Original equipment manufacturers negotiate multi-year supply agreements with thermal system specialists for platform-integrated designs. Powersport brands in the United States anchor demand through direct sourcing contracts specifying modular platform compatibility.
- Commercial Fleets:Utility vehicle operators with standardized maintenance protocols unbundle aftermarket service from original equipment purchases. These buyers procure replacement assemblies through direct-to-fleet e-commerce channels with lifecycle cost guarantees.
- Recreational Users:Individual owners replace failed components through dealer networks or independent distributors.
- Military Organizations:Defense procurement offices specify thermal subsystems through formal acquisition programs with localized sourcing mandates.
OEM-direct contracts concentrate engineering resources; fleet procurement fragments distribution tiers toward third-party certification.
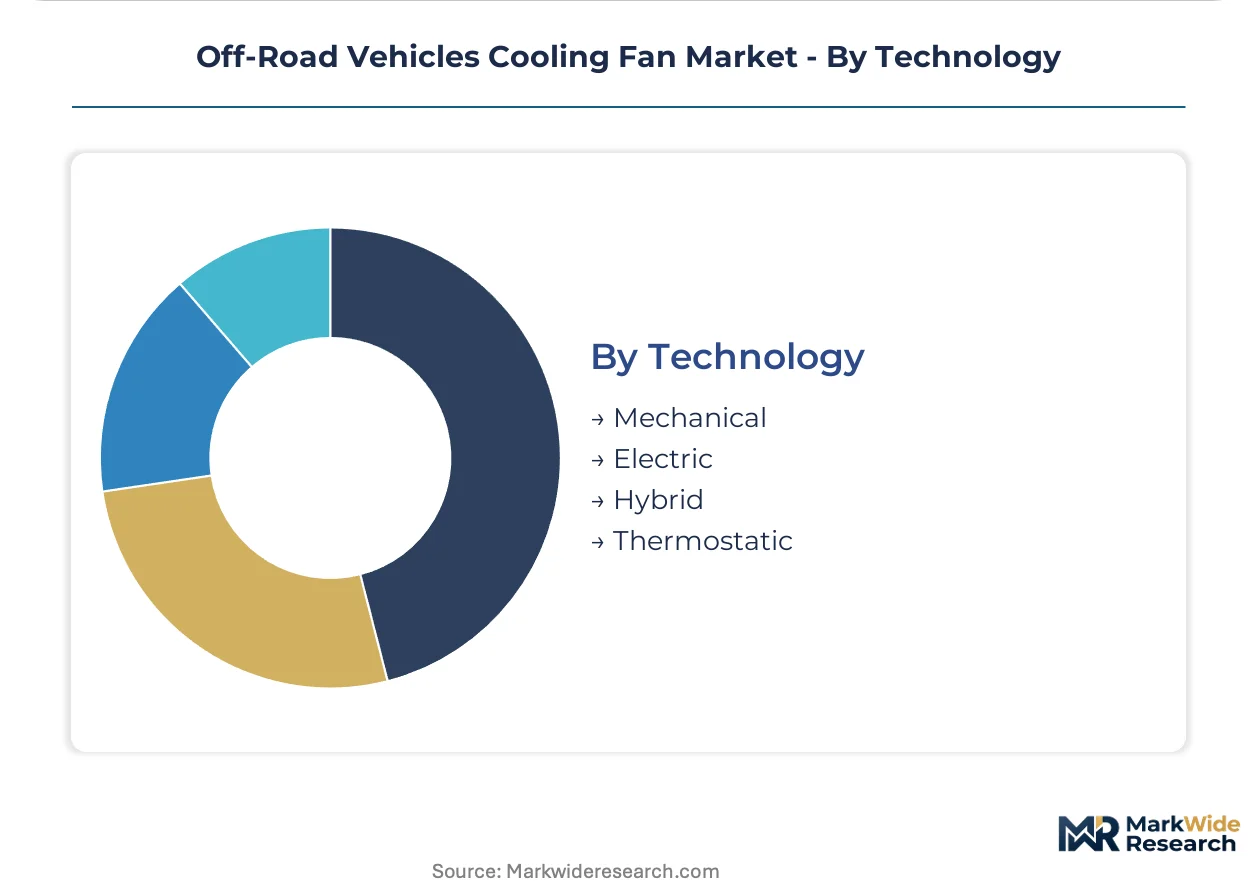
Technology:
Maturity gradients separate legacy mechanical architectures from electrified control strategies now penetrating severe-duty segments.
- Electric:Sensor-integrated fan systems with CAN bus communication and predictive thermal algorithms displace passive designs across construction and agricultural equipment. EU Stage V emissions mandates in Europe accelerate this transition by adding parasitic thermal loads requiring variable-speed response.
- Hybrid:Combined mechanical-electric architectures preserve belt-drive reliability while adding auxiliary electric boost for peak thermal events. These systems gain share in Indian defense modernization programs where indigenous armored vehicle specifications demand localized subsystem sourcing.
- Mechanical:Fixed-ratio clutch fans persist where electrification cost premiums exceed operational efficiency gains.
- Thermostatic:Bimetallic actuation provides rudimentary temperature-responsive engagement without electronic control.
Mechanical technology retains installed base; hybrid architectures are climbing the fastest in defense and heavy-equipment segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States defense procurement channels while European agricultural OEMs squeeze supplier margins through modular platform standardization. Tier 4 Final compliance costs in North America sustain premium thermal system valuations. Euro Stage V implementation across Germany and France forces dual-fan architectures that fragment supplier engineering resources.
United States
Defense procurement programs and recreational powersport sales generate dual demand channels for high-performance cooling systems. EPA Tier 4 Final emissions mandates force heavier thermal loads on diesel-powered construction and agricultural equipment. The Midwest industrial corridor around Detroit and Chicago anchors OEM-direct supply relationships with thermal system specialists.
Germany
European agricultural machinery manufacturers drive specification of modular cooling platforms compatible with divergent regional emission tiers. EU Stage V standards mandate closed crankcase ventilation and exhaust gas recirculation, adding parasitic thermal loads. The Baden-Württemberg engineering cluster around Stuttgart concentrates development of dual-fan architectures separating engine and charge-air circuits.
China
Construction equipment electrification roadmaps redefine thermal load profiles for hybrid powertrain architectures. GB standards and MIIT regulations shape domestic certification requirements for severe-duty cooling systems. The Yangtze River Delta manufacturing belt around Shanghai hosts subsystem suppliers integrating CAN bus motor controls for export-platform compatibility.
India
Indigenous armored vehicle programs under the Ministry of Defence create localized sourcing mandates for military-grade thermal subsystems. BIS certification requirements and PLI scheme incentives accelerate domestic production of high-performance fan assemblies. The Tamil Nadu defense industrial corridor near Chennai anchors fabrication facilities serving indigenous platform development.
Australia
Mining truck OEMs specify smart variable-speed electric fans for high-altitude operations where air density reductions demand maximum airflow rates. ISO 16750-3 vibration standards and extreme ambient temperature requirements shape product durability benchmarks. The Western Australia mining equipment cluster around Perth drives aftermarket replacement cycles through unbundled fleet service contracts.
Off-Road Vehicles Cooling Fan Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying motor assemblies and impeller castings. The vendor base organizes around three archetypes: diversified thermal system conglomerates with automotive heritage, dedicated electric fan specialists with severe-duty expertise, and regional fabricators serving aftermarket replacement cycles. Competitive positioning hardens through multi-year OEM-direct agreements and captive supply relationships with construction equipment builders.
Within the diversified conglomerate tier, Denso Corporation and BorgWarner Inc. exemplify platform integrators leveraging automotive thermal expertise for off-road verticals. MAHLE GmbH anchors the European engineering tradition with modular platform designs. These three occupy positions where electrification roadmaps and defense procurement specifications converge, representing archetypes of scale-driven system supply, specialized electric architectures, and modular portfolio extension respectively.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Gentherm Incorporated |
| Denso Corporation |
| SPAL Automotive S.R.L. |
| Marelli Holdings Co., Ltd. |
| Valeo SA |
| Nidec Corporation |
| AMETEK Inc. |
| BorgWarner Inc. |
| Others |
Value Chain & Pricing Dynamics
East Asian foundry concentration for high-performance motor controller semiconductors concentrates upstream margin capture among chip fabricators, leaving downstream cooling fan assemblers exposed to input cost volatility while OEM-direct contract structures lock in long-term pricing for tier-one suppliers.
Pricing Analysis
Configured-to-order pricing for military-grade thermal systems commands substantial premiums over standard electric fan platforms for recreational ATV segments. Three-tier pricing structure across premium, standard, and economy levels separates ballistic-rated redundant circuits from commercial-duty single-fan architectures. Cost compression in the recreational tier intensifies because aftermarket distributors consolidate procurement volume. Fleet operators exhibit highest price sensitivity through unbundled service contracts, while defense procurement offices demonstrate lowest sensitivity due to mission-critical specifications.
Supply Chain Analysis
Extended payment terms from construction equipment OEMs force supply-chain finance facilities upon mid-tier motor assembly suppliers, compressing working capital cycles. Manufacturing concentrates in China, Germany, and the United States for impeller casting and motor winding operations. Copper windings, rare-earth magnets, and injection-molded housings constitute critical input dependencies. Single-source vulnerability for brushless DC motor controllers concentrates risk among Taiwanese and South Korean semiconductor foundries. Distribution runs through OEM-captive channels for original equipment, with independent distributors capturing aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric cooling architectures face substitution pressure from integrated thermal management systems that consolidate battery, cabin, and powertrain cooling into unified loops, forcing discrete fan suppliers to defend component relevance.
For Market Incumbents: Insulate platform-integrated supply relationships by deepening backward integration into motor controller firmware development, countering the threat of full-system thermal specialists absorbing fan functions. Anchor long-term agreements with construction equipment OEMs electrifying auxiliary systems, using ISO 16750-3 certification investment as a contractual lock-in mechanism.
For New Entrants and Emerging Players: Indian defense modernization programs under the Ministry of Defence represent the most penetrable entry point, with localized sourcing mandates creating white-space for domestic fabrication capabilities. Aftermarket digital channels for North American utility vehicle fleets offer secondary white-space through direct-to-fleet e-commerce bypassing traditional distribution tiers. Pursue BIS certification paired with PLI scheme qualification as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive thermal specialists seeking off-road vertical expansion. Five-to-ten year viability hinges on electrification roadmap convergence with defense procurement specifications. Target acquisition archetypes include electric fan specialists with severe-duty validation capabilities and embedded software competencies. The signal to watch is hybrid powertrain architecture announcements from construction equipment OEMs, indicating thermal load profile shifts that favor integrated system suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Controllers | Captures margin pools from East Asian semiconductor foundries while securing supply continuity for EPA Tier 4 Final compliance. |
| Dual-Fan Architecture Development | Addresses EU Stage V parasitic thermal loads for European agricultural machinery manufacturers in Germany and France. |
| CAN Bus Firmware Investment | Enables ECU communication protocols required by smart variable-speed electric fan specifications from mining truck OEMs. |
| Indian Defense Localization | Satisfies Ministry of Defence sourcing mandates for indigenous armored vehicle programs under PLI scheme incentives. |
| Aftermarket Digital Platform Launch | Bypasses fragmented distribution tiers for North American utility vehicle fleet operators with unbundled service contracts. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with thermal system engineers at construction equipment OEMs, procurement leads at powersport manufacturers, aftermarket distribution managers, defense acquisition officers, and motor controller semiconductor specialists. Secondary validation drew from EPA Tier 4 Final regulatory filings, Euro Stage V implementation documentation, Ministry of Defence procurement notices, ISO 16750-3 vibration standard protocols, and customs trade data for copper and rare-earth magnet flows. Bottom-up unit economics triangulated against top-down market sizing across product type, application, and end-user dimensions.
Calibration against historical adoption curves for electric fan architectures in automotive applications anchored the projection framework. Segmentation modeling spanned product type, application, end user, and technology maturity gradients across the analysis window. CAGRs were derived from regression analysis of equipment production forecasts and replacement cycle frequencies. Industry-specific inputs included defense procurement pipeline visibility, agricultural machinery electrification roadmaps, and mining fleet utilization rates from Australian and Canadian operations.
Stress conditions across rare-earth magnet price volatility, semiconductor supply disruption scenarios, and regulatory timeline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EPA enforcement continuity and defense budget appropriation patterns. Macroeconomic contraction, trade restriction escalation, or breakthrough solid-state thermal management technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off-Highway Engine Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
All-Terrain Vehicle (ATV) Engines Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
All-Terrain Vehicle Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
US Off-Road Vehicles Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
Electric Off-Road Vehicles Market
Off Road Vehicles
Off-Road Vehicle Market
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Mining Vehicle Attachments Market
Off Road Vehicles
Global Electric Off-Highway Equipment Market