
 China Automotive Parts Aluminum Die Casting Market | 2026-2036
China Automotive Parts Aluminum Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive Parts Aluminum Die Casting Market Outlook
Aftermarket service revenue is fragmenting as OEMs internalize lifecycle value from aluminum die-cast components. Nemak leverages its captive casting-to-assembly pipeline to sustain margin capture across powertrain architectures. Ryobi Die Casting anchors its position through high-pressure die-casting specialization for transmission valve bodies. Lijia Group competes on scale economics in engine block production for domestic OEM programs.
China automotive parts aluminum die casting involves injecting molten aluminum alloys at pressures exceeding 1,000 bar into hardened steel molds to produce near-net-shape components with wall thickness below 3 millimeters, primarily serving weight reduction targets in vehicle structures. Engine Components retains the largest volume share but Electric Vehicles within the Application dimension represents the fastest-growing demand pool as thermal management housings and battery tray castings multiply. Raw Casting commands thinner margins while Machining and Surface Finishing stages concentrate value-added recovery, particularly for Tier-1 Suppliers serving OEM direct-sourcing programs.
China's MIIT enforces GB standards for aluminum alloy automotive castings while SAMR monitors market concentration under anti-monopoly frameworks, collectively pressuring foundries toward automated inspection and traceability systems. The country's dual carbon goals from MEE are accelerating energy audits and scrap-recycling mandates across die-casting facilities. Stakeholders must monitor how NEV platform standardization reshapes casting complexity requirements and tooling amortization cycles.
Market Dynamics
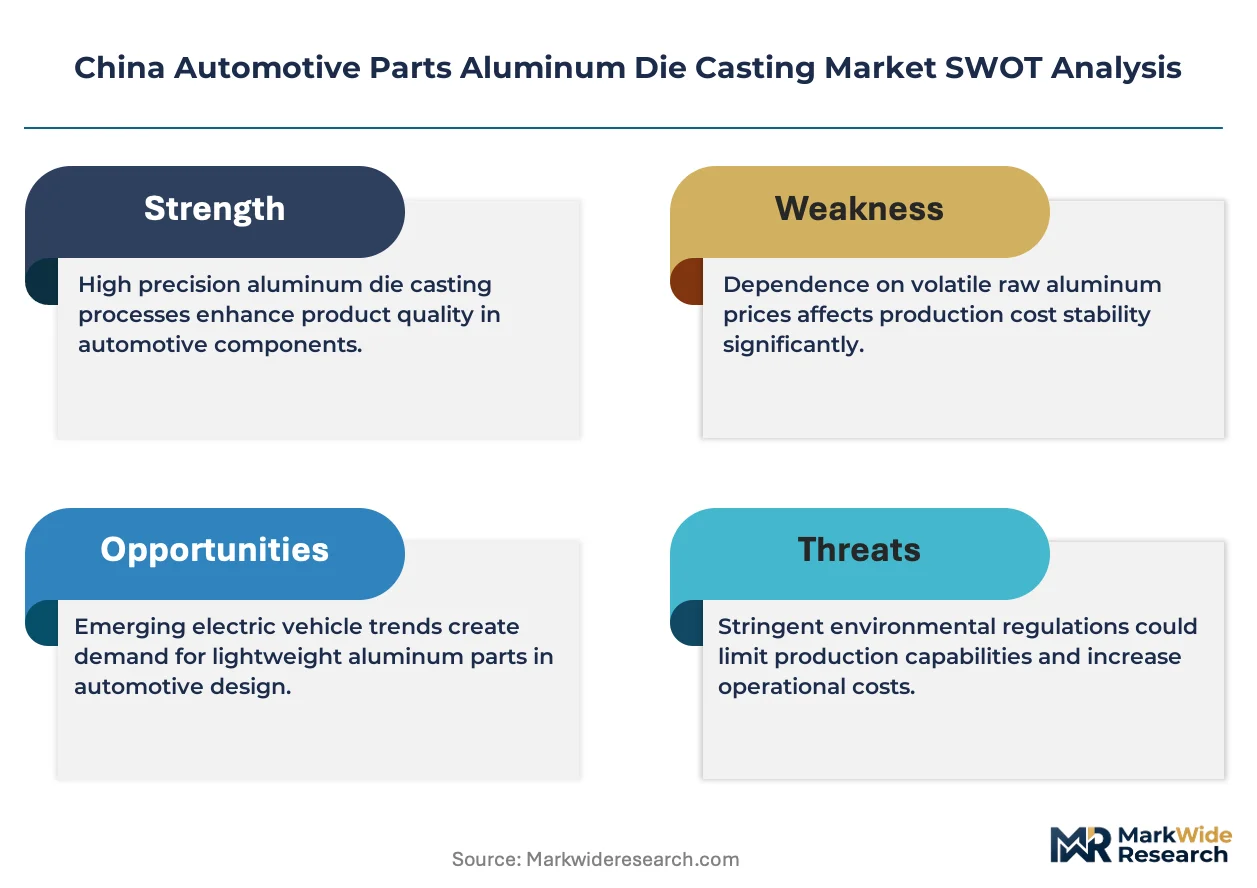
China's dual carbon goals from MEE are compressing foundry energy intensity targets while NEV platform standardization simultaneously reshapes casting complexity requirements across the Yangtze River Delta cluster.
Growth Catalysts
- NEV mandate timelines:MIIT enforcement of new energy vehicle production quotas is pulling aluminum die-cast battery tray and thermal housing demand through domestic OEM supply chains.
- Structural battery pack architectures:Cell-to-pack designs are eliminating modular intermediates and expanding single-piece casting opportunities for integrated floor pans.
- Yangtze River Delta concentration:Shanghai-Jiangsu-Zhejiang logistics density is reducing tooling transfer costs and accelerating prototype-to-production cycles for Tier-1 programs.
Market Restraints
- Primary aluminum price volatility:LME aluminum fluctuations are compressing raw casting margins and forcing foundries into forward hedging instruments they lack sophistication to manage.
- High-pressure die-casting equipment concentration:Core machinery supply concentrates among German and Japanese capital equipment makers, exposing Chinese foundries to euro-yen currency risk and extended lead times.
- Wall thickness limitations:Current high-pressure processes cannot reliably achieve sub-2mm sections for certain electronics enclosure applications, ceding share to magnesium and polymer alternatives.
Strategic Opportunities
- GB standards alignment for export:MIIT certification harmonization with EU REACH and US EPA automotive material standards is opening aftermarket access for certified Chinese castings in European and North American rebuild channels.
- Scrap-recycling mandate arbitrage:MEE energy audit requirements are creating first-mover advantage for foundries installing in-house remelt furnaces to capture closed-loop aluminum economics.
- Integrated die-cast-to-assembly modules:OEM direct-sourcing programs are inviting Tier-1 suppliers to assume machining and surface finishing stages previously retained captive, expanding value-capture scope.
Industry Challenges
- Process simulation talent scarcity:MAGMASOFT and FLOW-3D computational fluid dynamics expertise concentrates among senior engineers nearing retirement, constraining new tool design velocity.
- Multi-cavity tool qualification timelines:SAMR traceability documentation requirements are extending PPAP-equivalent approval cycles from 12 to 18 weeks for complex powertrain housings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Parts Aluminum Die Casting Market |
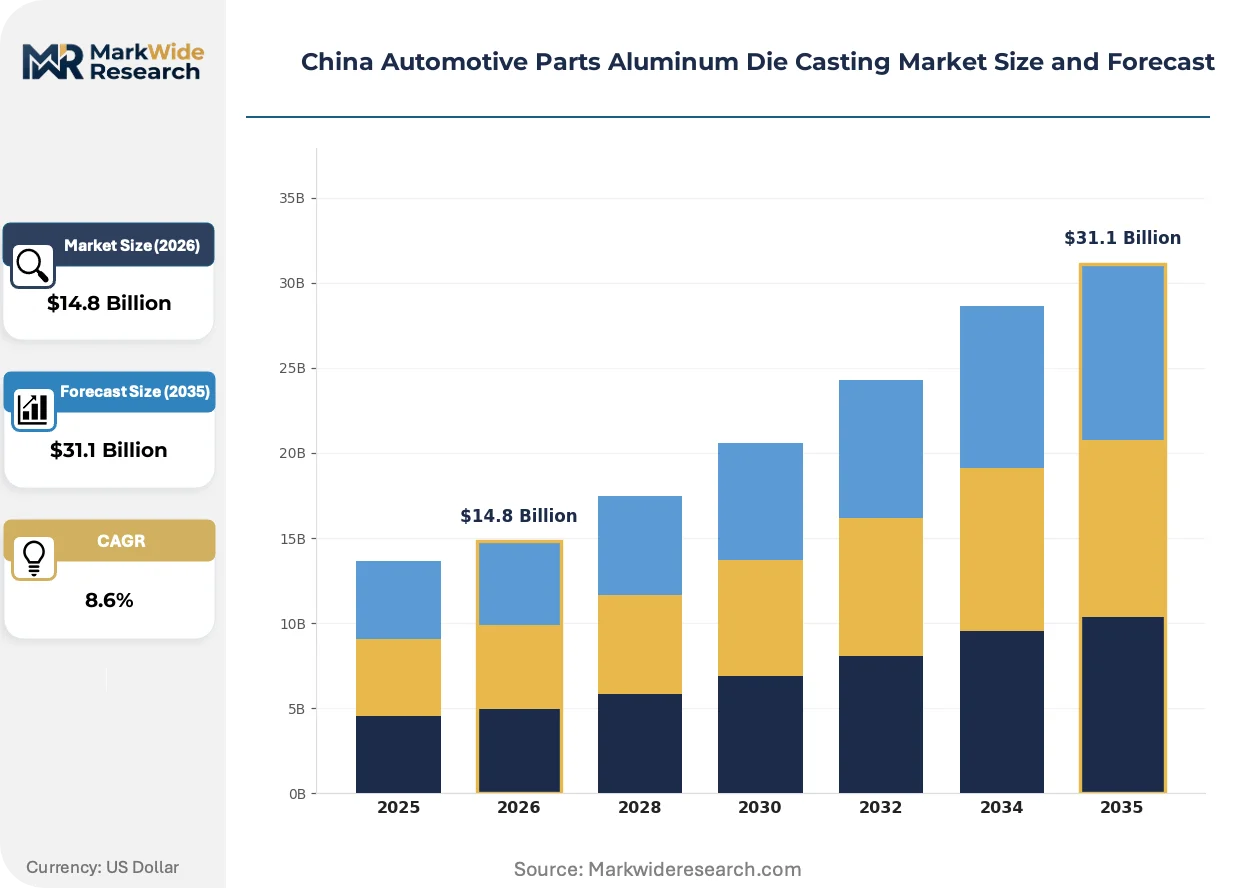
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Parts, Chassis Parts, Body Panels Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Heavy-Duty Trucks Manufacturing Stage: Raw Casting, Machining, Surface Finishing, Assembly End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Nemak, Ryobi Die Casting, Linamar Corporation, Alcoa Inc, Rheinmetall AG, KSPG AG, GC Precision Mold Co., Ltd., Lijia Group Co., Ltd., Dalian Yaming Automotive Parts Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Parts Aluminum Die Casting Market Strategic Shifts
Molten aluminum processing is undergoing simultaneous pressure, thermal, and digital transformation. Three developments are compressing legacy process boundaries and rewiring competitive capability requirements across Chinese foundries.
Large-scale integrated die-casting is collapsing the multi-component assembly paradigm for rear vehicle structures. Tesla's gigacasting approach has triggered replication efforts among domestic NEV platforms. BYD and NIO are accelerating 6,000-ton-plus press adoption to consolidate 70-plus stampings into single aluminum castings, compressing body-in-white line investment and factory footprint requirements.
MEE carbon audit protocols are forcing real-time energy monitoring retrofits across die-casting facilities. Foundries must now install granular electricity and natural gas metering tied to production lots. The thermal management housing segment faces the steepest compliance burden as these components require extended molten metal holding times that concentrate energy exposure.
Direct OEM contracting is displacing traditional Tier-2 supply hierarchies in battery tray programs. CATL and BYD Cell are establishing preferred foundry lists with dedicated capacity allocations. Zhejiang-based casting specialists are responding by investing in CNC machining centers to capture finishing value previously retained by Tier-1 distributors.
China Automotive Parts Aluminum Die Casting Market Segmentation
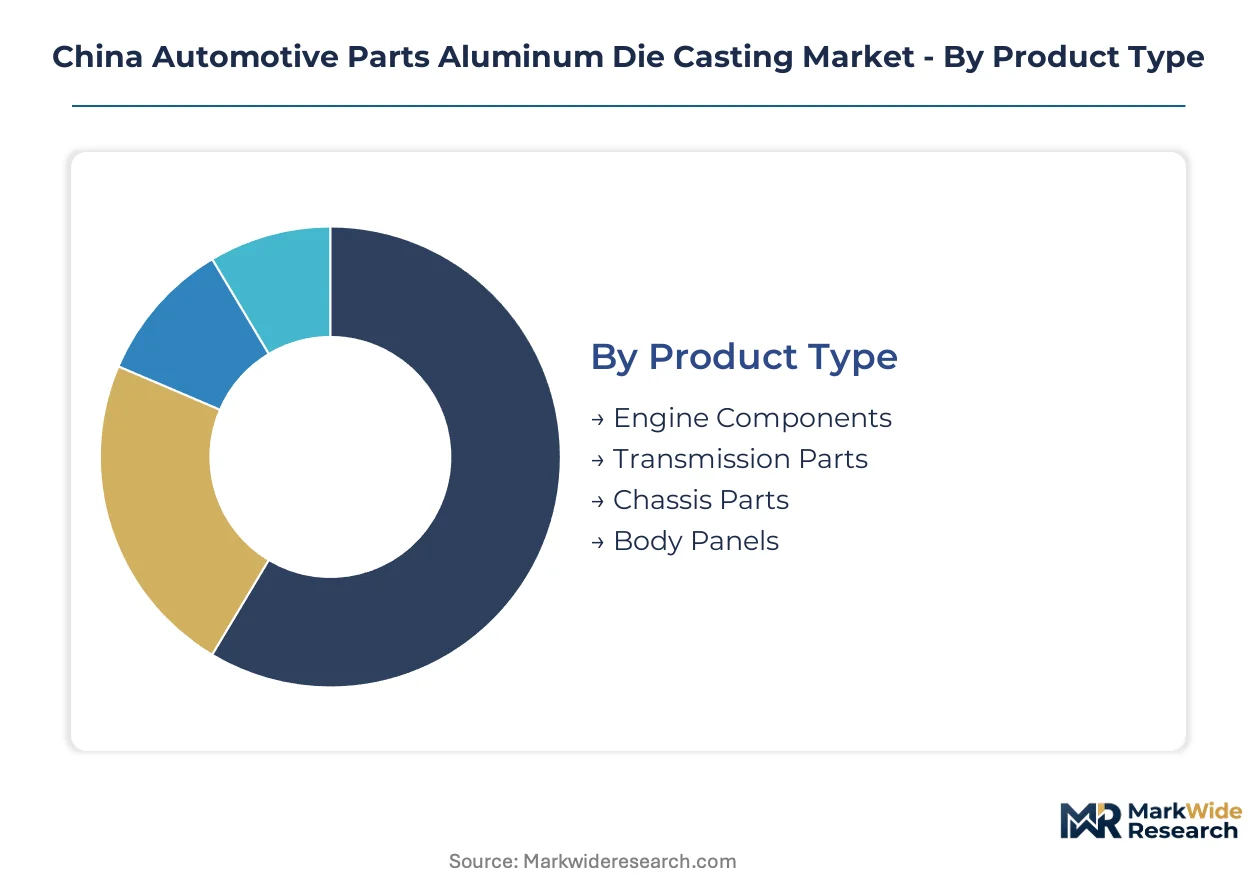
Die-cast aluminum component specifications diverge sharply across powertrain architectures, forcing foundries to maintain parallel tooling portfolios. Segmentation discipline separates commodity casting programs from integrated module opportunities that concentrate margin recovery.
Product Type:
Component complexity and thermal loading requirements fragment manufacturing capabilities across the four product categories.
- Engine Components:Cylinder heads, blocks, and covers demand A380 alloy with iron-content controls for elevated-temperature creep resistance. Yangtze River Delta foundries dominate this segment through long-running contracts with SAIC and Geely powertrain divisions, though ICE volume contraction is compressing tooling amortization schedules.
- Transmission Parts:Valve bodies, clutch housings, and gear cases require tighter dimensional tolerances (CT6-CT7 per GB/T 6414) and post-cast porosity sealing. Demand concentrates in dual-clutch and hybrid transmission programs where BYD and Great Wall are expanding in-house casting capacity.
- Chassis Parts:Control arms, knuckles, and subframe nodes absorb road-load stresses through A356-T6 heat treatment protocols.
- Body Panels:Closure inners and structural reinforcements prioritize cosmetic surface quality over mechanical properties.
Engine Components commands the established base. The steepest expansion runs through Body Panels as gigacasting adoption accelerates.
Application:
Vehicle electrification is rewiring demand composition across passenger, commercial, and heavy-duty platforms.
- Passenger Vehicles:Sedan and SUV programs generate the highest casting volumes but face platform consolidation pressure as NEV architectures reduce component counts per vehicle.
- Electric Vehicles:Battery trays, motor housings, and inverter enclosures require large-format castings with integrated cooling channels. CATL and BYD Cell procurement specifications are forcing foundries to adopt 4,000-ton-plus press capacity and real-time X-ray inspection protocols.
- Commercial Vehicles:Van and light-truck programs sustain steady demand for transmission housings and suspension nodes.
- Heavy-Duty Trucks:Diesel engine blocks and transmission cases retain thicker-wall designs that resist high-pressure die-casting migration.
Passenger Vehicles anchors volume throughput. Electric Vehicles is climbing the fastest as thermal management casting complexity multiplies.
Manufacturing Stage:
Value capture potential concentrates in post-casting operations that OEMs are selectively reinternalizing.
- Raw Casting:Molten metal injection and solidification yield near-net shapes with surface finishes typically at Ra 6.3-12.5. Foundries in Jiangsu province dominate this stage but face margin compression from LME aluminum volatility and MIIT energy audit compliance costs.
- Machining:CNC finishing of mounting surfaces, bores, and sealing faces concentrates dimensional accuracy recovery. Tier-1 suppliers are defending this stage through dedicated machining center investments that lock in OEM direct-sourcing relationships.
- Surface Finishing:Shot blasting, chemical conversion coating, and anodizing prepare castings for assembly integration.
- Assembly:Module-level integration of cast housings with bearings, seals, and sensors captures the highest value-added per kilogram.
Raw Casting holds the volume base. Assembly is gaining share fastest as OEMs push module-level sourcing accountability downward.
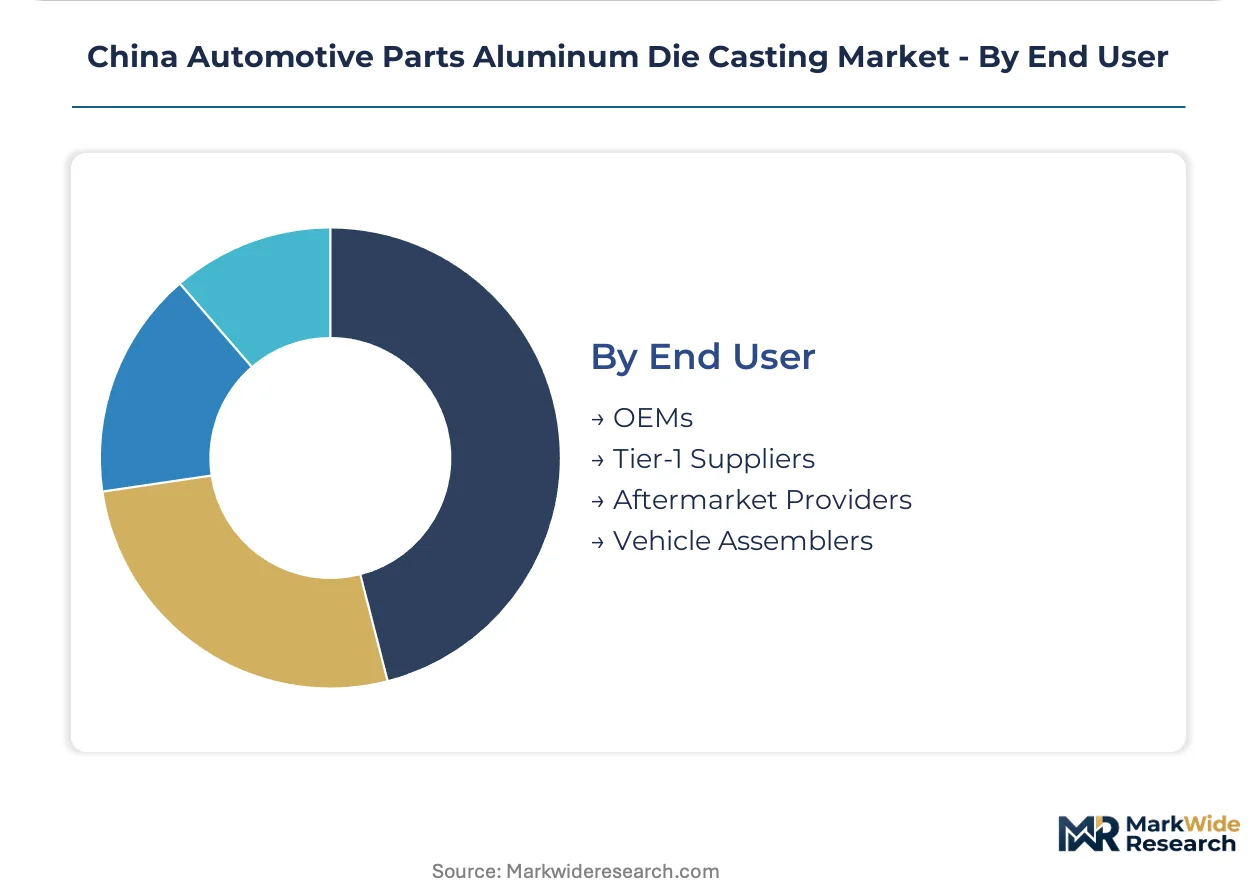
End User:
Procurement authority is concentrating among vertically integrated vehicle manufacturers and captive Tier-1 distributors.
- OEMs:Direct foundry contracting for battery trays and structural castings is displacing traditional supply hierarchies. BYD, NIO, and Li Auto maintain approved supplier lists with dedicated capacity allocations that freeze out speculative casting investments.
- Tier-1 Suppliers:Bosch, Denso, and domestic equivalents like HASCO retain machining and assembly stages while outsourcing raw casting to Zhejiang and Jiangsu specialists.
- Aftermarket Providers:Rebuild channels for engine and transmission components face sourcing constraints as OEMs restrict technical documentation access.
- Vehicle Assemblers:Contract manufacturers without captive casting capabilities depend on spot-market purchasing with limited quality traceability.
Tier-1 Suppliers control the intermediary layer. OEMs are expanding share fastest through direct battery program casting awards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across China's die-casting demand clusters. Yangtze River Delta OEMs prioritize logistics efficiency over unit cost, while interior province buyers remain highly elastic to aluminum price fluctuations.
Yangtze River Delta
Shanghai-Jiangsu-Zhejiang concentration absorbs premium casting programs for NEV thermal management. MIIT dual carbon audit protocols force real-time energy monitoring across 400-plus registered foundries. Ningbo and Taizhou clusters specialize in 4,000-ton press capacity for battery tray monocoques serving CATL direct-sourcing contracts.
Pearl River Delta
Guangdong province demand concentrates in electronics-adjacent automotive applications requiring sub-3mm wall precision. GB standards alignment with EU REACH accelerates export certification for Shenzhen and Dongguan specialists. Foshan's aluminum processing corridor integrates remelt furnaces to capture closed-loop scrap economics under MEE mandates.
Beijing-Tianjin-Hebei
Capital region procurement prioritizes defense-adjacent and heavy commercial vehicle castings with thicker-wall specifications. SAMR anti-monopoly monitoring constrains foundry consolidation among state-owned vehicle assemblers. Tianjin port logistics advantage supports raw aluminum import hedging for cost-sensitive engine block programs.
Sichuan-Chongqing
Western China automotive hub leverages hydroelectric power pricing to offset aluminum smelting energy intensity. Chongqing's NEV platform standardization pulls large-format casting demand away from coastal suppliers. Chengdu foundries specialize in transmission valve body precision work for joint-venture transmission programs.
Shandong Peninsula
Weifang and Yantai clusters sustain ICE engine component volume through long-running contracts with domestic OEM powertrain divisions. Provincial environmental regulators enforce stricter effluent standards than national baselines, accelerating aqueous cleaning system adoption. Local foundries defend position through scale economics in A380 alloy cylinder head production.
China Automotive Parts Aluminum Die Casting Market Competitive Environment
Captive casting-to-assembly pipelines and independent raw casting specialists split the market into distinct capability tiers. Consolidation pressure concentrates among mid-scale Jiangsu and Zhejiang foundries lacking integrated machining capacity. Three archetypes dominate: multinational Tier-1 suppliers with captive assembly integration, domestic scale players serving engine component contracts, and regional specialists in high-pressure precision transmission work. Competitive moves center on press capacity expansion above 6,000 tons and backward integration into aluminum remelt operations.
Within the multinational tier, Nemak and Ryobi Die Casting exemplify integrated supply chain positioning. Lijia Group anchors the domestic scale archetype through long-running OEM program relationships. These three entities represent contrasting strategic postures: captive pipeline control, high-pressure specialization, and volume-driven engine block economics.
| Leading Market Players |
|---|
| Nemak |
| Ryobi Die Casting |
| Linamar Corporation |
| Alcoa Inc |
| Rheinmetall AG |
| KSPG AG |
| GC Precision Mold Co., Ltd. |
| Lijia Group Co., Ltd. |
| Dalian Yaming Automotive Parts Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
German and Japanese high-pressure die-casting equipment manufacturers anchor upstream supply, concentrating margin capture downstream among foundries with captive machining and assembly pipelines. LME aluminum volatility feeds directly into raw casting tier compression, while OEM direct-sourcing programs reallocate value pools toward integrated module suppliers.
Pricing Analysis
Aftermarket service revenue tiers drive lifetime value recovery as OEMs internalize lifecycle economics from aluminum die-cast components. Three-tier pricing structure across premium certified, standard production, and economy spot-market levels separates foundries by MIIT traceability compliance and GB standards alignment. Pricing pressure stems from primary aluminum volatility forcing Jiangsu raw casting specialists into forward hedging instruments. Tier-1 suppliers with machining integration exhibit lowest price sensitivity; spot-market vehicle assemblers face highest elasticity.
Supply Chain Analysis
Export-control regimes on large-format press technology constrain Chinese foundry access to 6,000-ton-plus capacity from German and Japanese capital equipment makers. Supply concentrates in China for molten aluminum processing, Germany for precision tooling, and Japan for high-pressure injection systems. Raw material dependencies rest on primary aluminum ingots, hardened steel mold alloys, and ceramic refractory linings. Single-source vulnerability runs through European press manufacturers. Distribution feeds from Yangtze River Delta foundry clusters through Tier-1 supplier machining centers to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM procurement consolidation into direct-sourcing programs is shifting buyer power toward vertically integrated vehicle manufacturers, fragmenting traditional Tier-2 supply hierarchies.
For Market Incumbents: Build captive casting-to-assembly pipelines by investing in 4,000-ton-plus press capacity and CNC machining centers to defend against OEM direct-sourcing displacement. Secure backward integration into aluminum remelt furnaces under MEE scrap-recycling mandates to capture closed-loop economics. Lock in long-term cathode contracts with CATL and BYD Cell through dedicated capacity allocations. For New Entrants and Emerging Players: Build out precision transmission valve body capabilities for dual-clutch and hybrid programs where BYD and Great Wall are expanding in-house casting gaps. Target Chongqing NEV platform standardization demand for large-format thermal management housings. Enter through machining and surface finishing specialization with real-time X-ray inspection protocols to bypass raw casting margin compression. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Jiangsu and Zhejiang mid-scale foundries lacking integrated machining capacity. Five-to-ten year viability favors specialists with 6,000-ton press deployment and OEM-approved supplier status. Watch for NEV platform standardization announcements as inflection signals for tooling amortization cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Large-Format Press Capacity Expansion | 6,000-ton-plus adoption enables gigacasting replication for BYD and NIO rear floor structures. |
| Backward Integration into Aluminum Remelt | MEE energy audit compliance creates first-mover closed-loop economics for Yangtze River Delta foundries. |
| Machining Center Investment | CNC finishing capability locks in OEM direct-sourcing relationships previously retained by Tier-1 distributors. |
| GB Standards Export Certification | MIIT harmonization with EU REACH opens European aftermarket rebuild channels for certified castings. |
| Real-Time Energy Monitoring Retrofit | Granular metering tied to production lots satisfies MEE carbon audit protocols for thermal management housing segments. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MIIT regulatory filings, SAMR anti-monopoly documentation, and aluminum trade flow data. Interviews with Tier-1 supplier procurement officers, OEM platform engineers, foundry operations directors, and aftermarket distributors combined with bottom-up production surveys and top-down vehicle production database triangulation. Secondary sources include customs records, GB standards certification registries, and energy audit disclosure filings.
Forecast inputs span vehicle class, propulsion architecture, content per vehicle, and regional production cluster segmentation. CAGRs derive from production volume trajectories mapped against aluminum intensity per platform across the analysis window. Specific inputs include NEV mandate timeline enforcement schedules, dual carbon goal compliance cost curves, and gigacasting adoption rates among domestic OEMs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery cell manufacturers into captive casting would shift outcomes. Material shifts in LME aluminum volatility regimes, MIIT energy audit stringency, or NEV platform standardization acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Connecting Rods Market
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
Norway Passenger Vehicles Lubricants Market
Automotive Parts
Japan Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Automotive Fuel Nozzle Market
Automotive Parts
Automotive Fuel Delivery System Market
Automotive Parts
Electric Coolant Pump Market
Automotive Parts
Friction Pads Market
Automotive Parts
Automotive Brake Fluid Market
Automotive Parts
Engine Oil Market
Automotive Parts
Global Automotive Engine Valves Market
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market