
 Electric Vehicle Cold Plates Market | 2026-2036
Electric Vehicle Cold Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Cold Plates Market Insights
Software-defined thermal management is shifting how cold plate vendors monetize hardware, with subscription-based performance optimization and predictive maintenance bundles now accompanying base component sales. Dana leverages its integrated powertrain expertise to anchor long-term supply agreements with North American OEMs. MAHLE competes through R&D intensity in active cooling architectures, while Sanhua Holding Group dominates manufacturing scale for aluminum cold plate exports from China.
An electric vehicle cold plate is a heat exchanger component, typically machined from aluminum alloys with internal micro-channel geometries below 1 mm fin spacing, designed to absorb and dissipate thermal loads from battery modules, inverters, and electric motors. Its primary purpose is maintaining cell temperatures within 15–35°C to prevent thermal runaway and preserve cycle life. Aluminum leads material selection for cost-sensitive high-volume programs, while copper occupies premium performance tiers where conductivity thresholds exceed 380 W/m·K. Active cooling systems represent the fastest-growing type segment as power densities in 800V architectures escalate thermal loads beyond passive dissipation limits.
The EU F-Gas Regulation and China's GB standards for battery thermal safety are mandating redundant cooling pathways, directly expanding cold plate unit counts per vehicle. EPA vehicle emissions rules and NHTSA battery safety guidelines in the United States are similarly tightening thermal management compliance thresholds. Stakeholders must monitor how 800V platform proliferation and solid-state battery thermal profiles reshape cold plate specifications before committing to long-term tooling investments.
Market Dynamics
The 800V platform transition is compressing thermal management timelines as OEMs redesign battery architectures around higher power densities and faster charging protocols.
Growth Catalysts
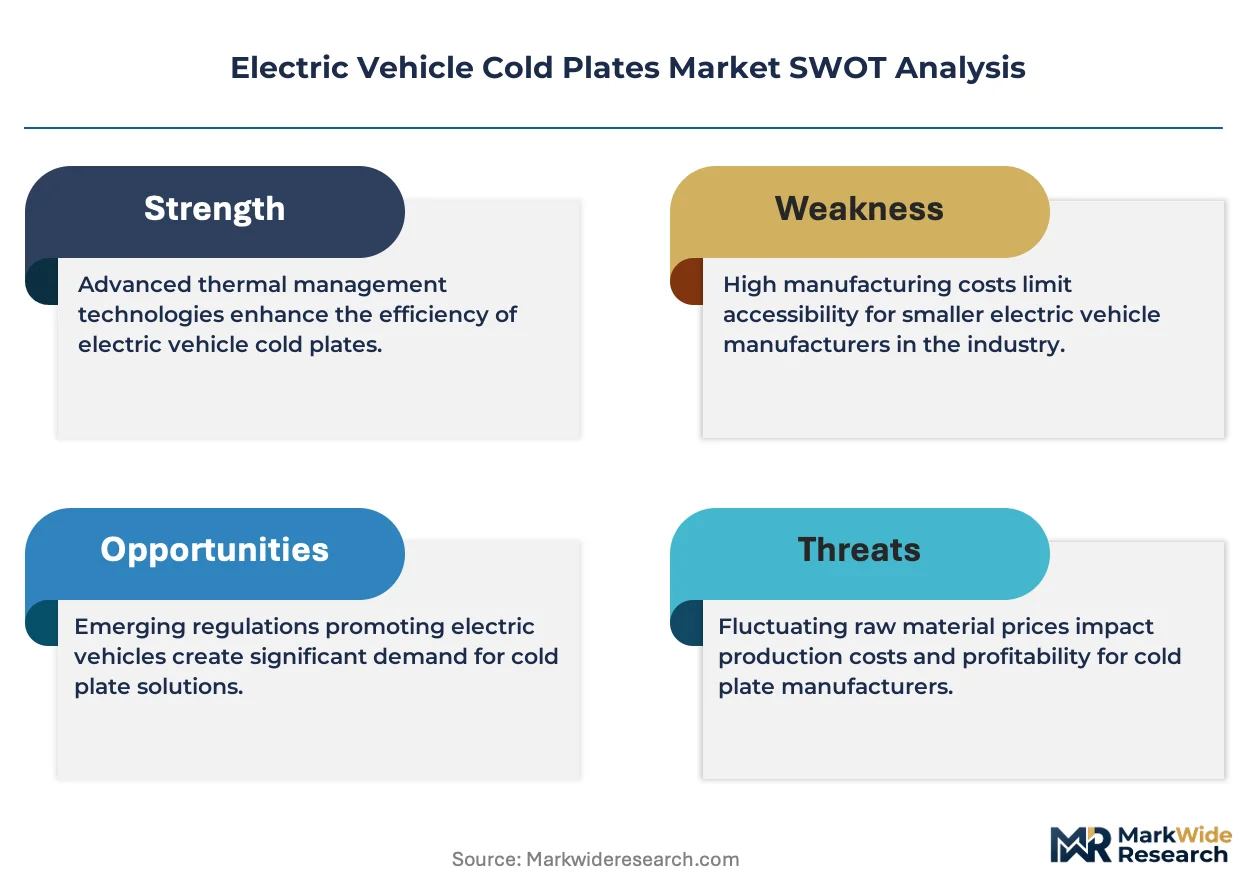
- EU F-Gas Regulation:Mandates for redundant cooling pathways in commercial EVs are doubling cold plate unit counts per vehicle, expanding addressable hardware volumes.
- 800V battery architectures:Power density escalation in premium passenger and heavy-duty segments is pushing thermal loads beyond passive dissipation limits, forcing active cooling adoption.
- Yangtze River Delta cluster:Concentrated EV manufacturing in Jiangsu and Zhejiang provinces is generating localized procurement pull for aluminum cold plate suppliers.
Market Restraints
- Aluminum price volatility:Input cost swings for 6061 and 6063 alloy billets compress margin buffers for high-volume cold plate manufacturers.
- Micro-channel machining bottlenecks:Sub-millimeter fin spacing requirements limit qualified supplier bases to precision CNC and extrusion specialists with capital-intensive tooling.
- Copper substitution ceiling:Conductivity thresholds above 380 W/m·K lock premium applications to copper alloys, fragmenting material standardization and procurement scale.
Strategic Opportunities
- India PLI scheme for automotive:Production-linked incentives for EV component manufacturing are attracting cold plate tooling investments to Tamil Nadu and Gujarat corridors.
- Solid-state battery thermal profiles:Reduced cooling intensity requirements in next-generation cell chemistries are opening design space for lighter, lower-cost plate geometries.
- Software-defined thermal management:Predictive maintenance and performance optimization subscriptions are creating recurring revenue streams alongside hardware sales.
Industry Challenges
- Micro-channel machining talent scarcity:Precision fluid dynamics engineering and CNC programming skills are concentrated among aging workforces in Germany and Japan.
- Multi-standard certification timelines:Parallel validation against China's GB standards, EU F-Gas requirements, and US NHTSA guidelines extends product launch cycles.
- Legacy thermal architecture integration:Retrofitting cold plates into existing battery pack designs without full platform redesigns creates packaging and flow distribution compromises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Cold Plates Market |
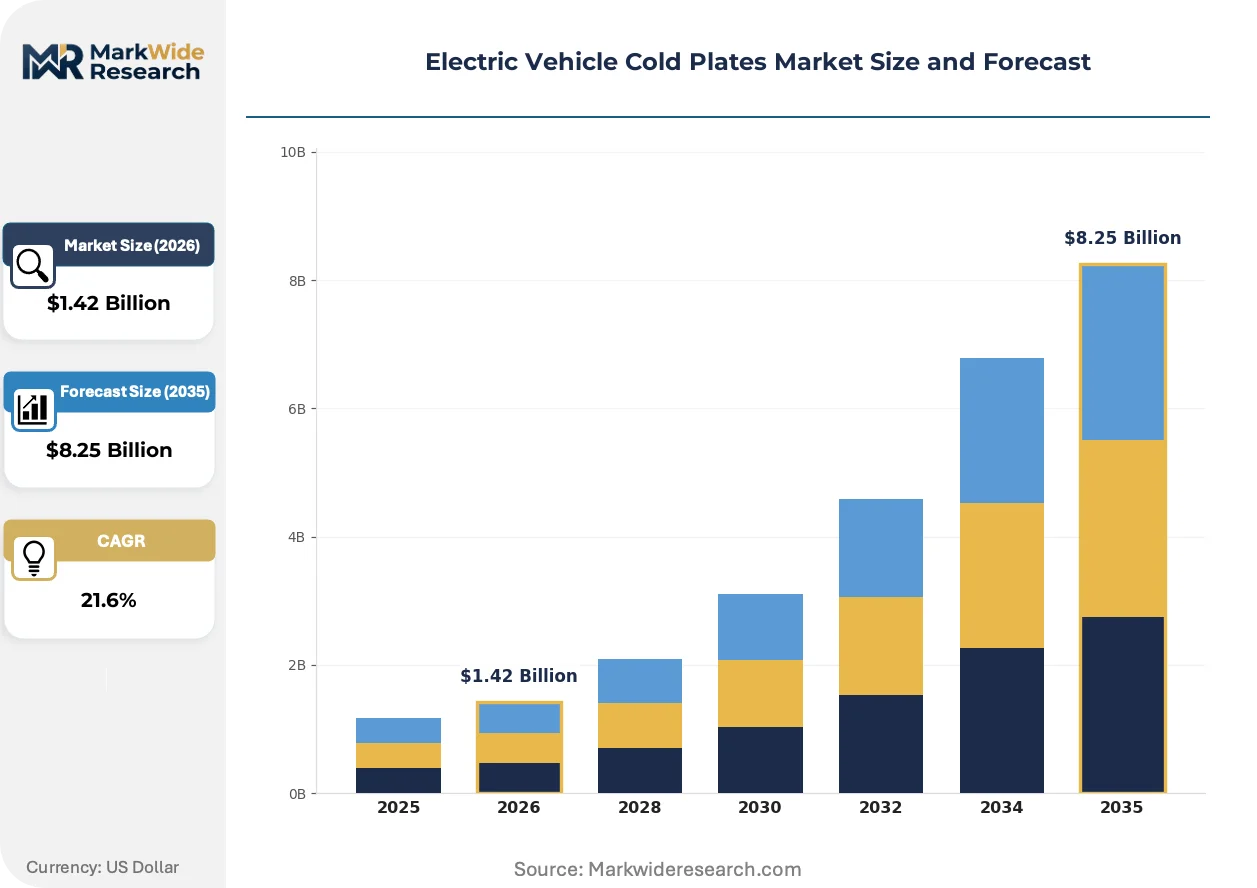
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 21.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Passive, Active, Hybrid, Custom Material: Copper, Aluminum, Graphite, Composites Application: Battery Cooling, Power Electronics, Thermal Management, HVAC End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators |
| Companies Covered | Valeo, Dana, MAHLE, Boyd Corporation, ESTRA Automotive, Sanhua Holding Group, Zhejiang Yinlun Machinery, Nabaichuan Holding, BorgWarner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Cold Plates Market Trends and Innovations
Additive manufacturing is reshaping cold plate production economics by enabling conformal cooling geometries that subtractive machining cannot achieve. Three developments are compressing competitive timelines.
Topology-optimized aluminum cold plates with internal lattice structures are integrating into 800V inverter cooling modules. European and North American OEMs are qualifying these designs for 2026 platform launches. The technology is integrating thermal and structural functions, eliminating separate mounting hardware and reducing pack mass.
China's NMPA battery safety mandates are mandating redundant cooling loops with independent monitoring systems. The regulation forces dual-circuit cold plate architectures in commercial vehicles above 3.5 tonnes. Heavy-duty truck manufacturers in Shandong and Hubei provinces are accelerating supplier qualification for compliant designs.
Long-term supply agreements are displacing spot purchasing for cold plate volumes. North American OEMs are locking aluminum extrusion capacity through 2028 to secure machining slots at tier-one thermal suppliers. The shift is most visible in Michigan and Ontario manufacturing corridors where battery plant co-location is driving just-in-sequence delivery requirements.
Electric Vehicle Cold Plates Market Segmentation
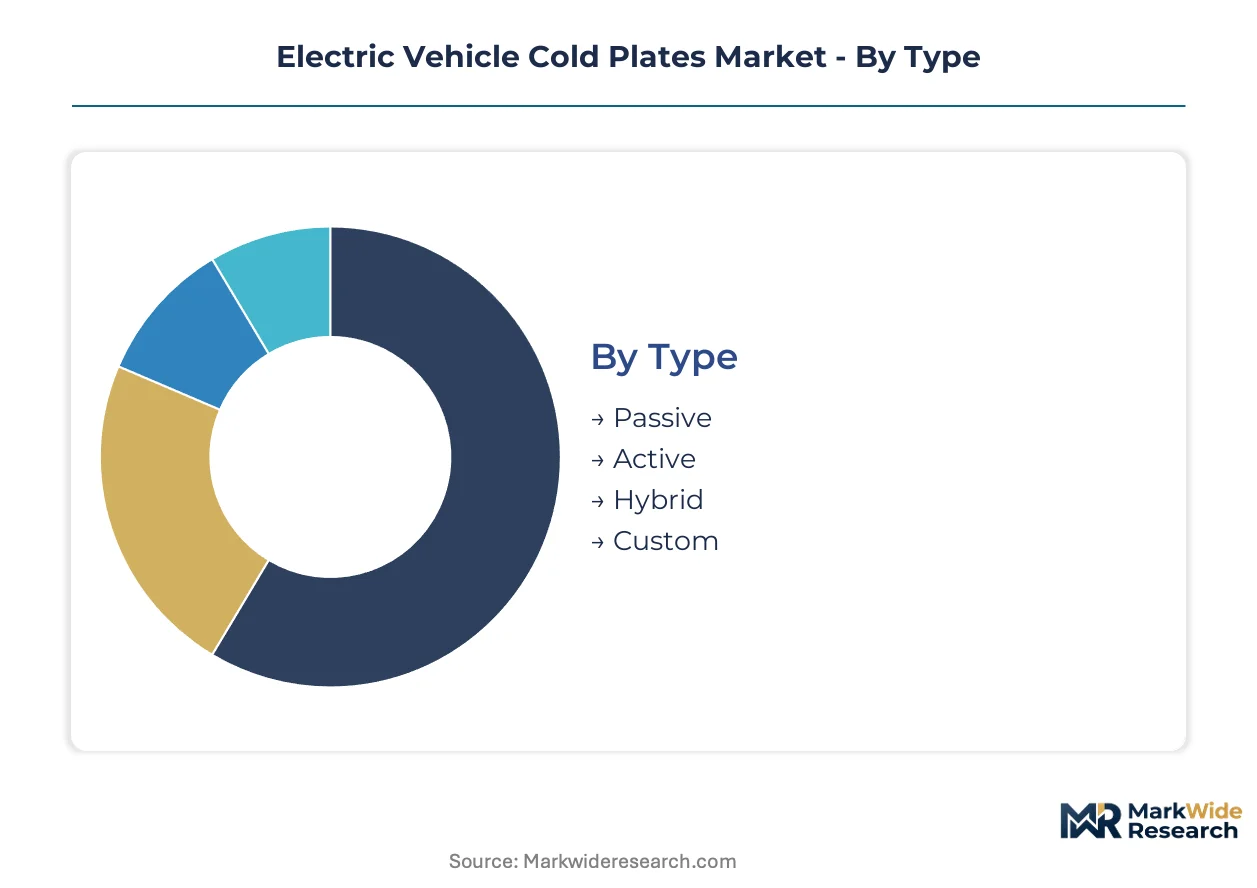
Cold plate specifications diverge sharply across vehicle architectures, with 800V platforms demanding active cooling while entry-level EVs retain passive solutions. Material selection and channel geometry must align precisely with cell chemistry thermal profiles and OEM pack integration constraints.
Type:
Standardization dominates high-volume passenger programs, while custom-engineered solutions command premium positioning in heavy-duty and performance segments.
- Passive:Aluminum extrusions with natural convection fins serve cost-optimized battery modules in compact urban EVs. China's Jiangsu province manufacturers dominate output for domestic OEMs targeting sub-400V architectures where thermal loads remain moderate.
- Active:Pump-driven liquid circulation through micro-channel geometries handles 800V battery heat rejection and fast-charging protocols. German passenger EV manufacturers and heavy-duty truck builders in Michigan are accelerating procurement as power densities exceed 4 kW/L.
- Hybrid:Combines passive baseplates with active boost circuits for intermittent peak loads. Fleet operators in California favor these for delivery vans with stop-and-go thermal cycling patterns.
- Custom:Topology-optimized designs with conformal cooling channels for solid-state battery pre-production platforms. Limited to European and North American OEM validation programs.
Leading the category by volume: Passive. Expanding most quickly: Active.
Material:
Conductivity thresholds and weight targets create a cost-performance trade-off matrix that fragments procurement strategies across vehicle tiers.
- Aluminum:6061 and 6063 alloys with 180-205 W/m·K thermal conductivity anchor mass-market production. Yangtze River Delta extruders supply China's NEV manufacturers under price-sensitive annual contracts.
- Copper:C11000 alloy delivering 380+ W/m·K conductivity occupies inverter cooling and premium performance tiers. Japanese thermal specialists control precision machining capacity for these applications.
- Graphite:Anisotropic sheets for directional heat spreading in pouch cell configurations. Korean battery makers evaluate these for next-generation cell-to-pack architectures.
- Composites:Aluminum-graphite hybrids and polymer-matrix materials targeting weight reduction in aviation-influenced EV designs. Emerging qualification phase with German luxury OEMs.
Dominant by procurement tonnage: Aluminum. Steepest expansion trajectory: Composites.
Application:
Functional integration depth varies with thermal architecture complexity, from discrete battery modules to consolidated vehicle-level thermal systems.
- Battery Cooling:Direct-contact cold plates with dielectric fluid channels maintain 15-35°C cell windows. Commercial vehicle mandates from China's NMPA are doubling unit counts per pack through redundant loop requirements.
- Power Electronics:IGBT and SiC inverter cooling demands sub-millimeter channel precision for heat flux above 100 W/cm². German automotive suppliers lead qualification for 800V traction inverters.
- Thermal Management:Integrated vehicle-level systems consolidating battery, cabin, and motor cooling. Simplified architectures are gaining traction in Indian PLI-funded manufacturing corridors.
- HVAC:Refrigerant-coupled plates for heat pump integration in cold-climate EVs. Nordic market specifications are driving adoption in Norwegian and Finnish fleet procurements.
Highest unit volume: Battery Cooling. Gaining share fastest: Power Electronics.
End User:
Procurement authority concentration shapes contract structures, from captive vertical integration to outsourced tier-one supply with just-in-sequence delivery.
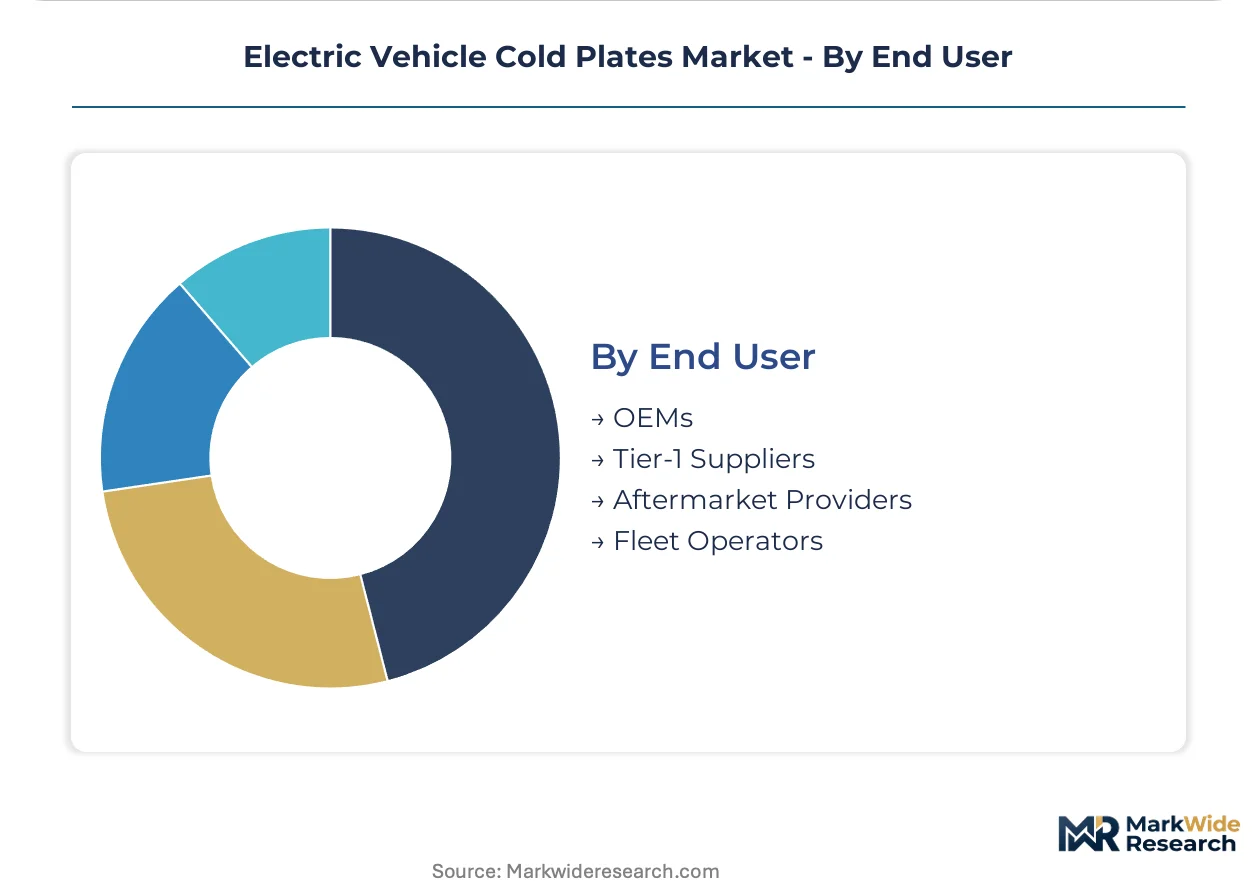
- OEMs:Direct specification of cold plate geometry and material for proprietary battery platforms. Vertical integration into thermal hardware is accelerating among North American and European manufacturers.
- Tier-1 Suppliers:Modular cold plate subsystems integrated into complete battery thermal management systems. Dana and MAHLE are anchoring long-term supply agreements with dedicated machining capacity.
- Aftermarket Providers:Replacement plates for battery refurbishment and thermal system upgrades. Limited scale outside warranty extension programs in California and Germany.
- Fleet Operators:Direct procurement for commercial vehicle retrofits and custom upfit configurations. Municipal bus operators in Shenzhen and Los Angeles specify redundant cooling for duty-cycle reliability.
Controlling procurement value: OEMs. Emerging fastest: Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of cold plate hardware while Germany and the United States consume premium thermal management systems for their domestic EV programs. Production concentrates in aluminum extrusion corridors serving battery OEMs, with demand pull coming from vehicle assembly clusters pursuing 800V architectures.
China
Yangtze River Delta EV manufacturers in Jiangsu and Zhejiang provinces drive aluminum cold plate procurement at scale. NMPA battery safety mandates require redundant cooling loops in commercial vehicles above 3.5 tonnes. Shandong and Hubei heavy-duty truck builders are accelerating supplier qualification for dual-circuit architectures.
Germany
Passenger EV manufacturers specify micro-channel precision for 800V traction inverters and battery modules. EU F-Gas Regulation mandates redundant cooling pathways that expand hardware counts per vehicle. Bavarian and Baden-Württemberg automotive corridors anchor thermal supplier R&D and machining qualification programs.
United States
Michigan and Ontario battery plant co-location drives just-in-sequence delivery requirements for cold plate suppliers. EPA vehicle emissions rules and NHTSA battery safety guidelines tighten thermal management compliance thresholds. Midwest manufacturing corridors concentrate procurement authority among OEMs pursuing captive thermal hardware integration.
India
Production-linked incentives for EV component manufacturing attract cold plate tooling investments to Tamil Nadu and Gujarat corridors. BIS standards and the PLI scheme accelerate localization of thermal management hardware. Domestic passenger EV programs and commercial vehicle electrification create dual demand streams for aluminum extrusion suppliers.
Japan
Precision machining capacity for copper alloy cold plates serves premium conductivity applications above 380 W/m·K. METI industrial policy supports thermal management R&D for next-generation solid-state battery platforms. Kanto and Kansai manufacturing clusters concentrate fluid dynamics engineering expertise for micro-channel geometries.
Electric Vehicle Cold Plates Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the cold plate value chain. Integrated powertrain suppliers and dedicated thermal specialists split procurement relationships with OEMs. Three archetypes dominate: aluminum extrusion scale players, precision machining specialists, and integrated thermal system providers. Capacity expansion and long-term supply agreement anchoring represent the primary competitive moves as OEMs lock machining slots through 2028.
Among European-based integrated suppliers, Valeo and MAHLE occupy positions spanning thermal system design to component manufacturing. Dana represents North American powertrain-anchored competition with backward integration into thermal hardware. Sanhua Holding Group exemplifies Chinese scale-driven manufacturing for aluminum cold plate export programs. These three anchors illustrate how geographic production advantages and customer relationship depth create differentiated competitive positions.
| Leading Market Players |
|---|
| Valeo |
| Dana |
| MAHLE |
| Boyd Corporation |
| ESTRA Automotive |
| Sanhua Holding Group |
| Zhejiang Yinlun Machinery |
| Nabaichuan Holding |
| BorgWarner |
| Others |
Pricing and Supply Chain Analysis
North American OEM procurement concentration anchors long-term contract pricing for aluminum cold plates, with just-in-sequence delivery requirements compressing spot market liquidity and amplifying volume-tier discounts for dedicated machining capacity.
Pricing Analysis
Margin tightening in standard aluminum extrusion tiers reflects Yangtze River Delta oversupply and annual contract renegotiation cycles. Three-tier pricing structure across premium, standard, and economy levels separates copper-alloy precision machined plates from 6061 aluminum commodity volumes and hybrid composite prototypes. Cost-down pressure on passive cooling architectures accelerates because Jiangsu manufacturers compete for domestic NEV program share. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while German passenger EV manufacturers absorb premiums for micro-channel active cooling qualification.
Supply Chain Analysis
GB standards and EU F-Gas Regulation certification gates fragment qualified supplier bases, extending product launch timelines for dual-circuit architectures. Manufacturing concentrates in China, Germany, and Japan, with aluminum billet supply drawing from Australian and Indonesian smelter output. Micro-channel machining capacity rests on precision CNC tooling concentrated in Bavarian and Kansai industrial clusters. Single-source vulnerability persists for sub-millimeter fin spacing extrusion dies. Distribution runs through Tier 1 thermal system integrators co-located with battery plant corridors in Michigan and Ontario.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric vehicle cold plates market is becoming a vertical-integration race, with OEMs pursuing captive aluminum extrusion capacity to secure machining slots and compress thermal hardware lead times.
For Market Incumbents: Extend long-term supply agreement coverage through dedicated tooling investments in Tamil Nadu and Gujarat corridors to preempt India PLI scheme localization. Lock precision CNC capacity for 800V platform qualification programs before micro-channel machining talent scarcity intensifies. Backward integration into aluminum billet sourcing mitigates 6061 alloy price volatility exposure. For New Entrants and Emerging Players: Enter via aftermarket refurbishment channels for California and Germany warranty extension programs, where battery thermal system upgrades face limited incumbent presence. Target fleet operator direct procurement for municipal bus retrofits in Shenzhen and Los Angeles, where redundant cooling specifications create specification gaps. Qualify conformal cooling designs through additive manufacturing partnerships with European OEM validation programs. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision machining specialists with GB standards and EU F-Gas Regulation dual certification in German automotive corridors. Five-to-ten year viability hinges on 800V platform proliferation sustaining active cooling content growth. Watch solid-state battery thermal profile disclosures as inflection indicator for cooling intensity reduction risk.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement Anchoring | Locks aluminum extrusion capacity at Yangtze River Delta suppliers for North American OEM just-in-sequence requirements. |
| Micro-channel Machining Capacity Expansion | Addresses bottlenecks for sub-millimeter fin spacing demanded by 800V traction inverter cooling specifications. |
| Dual-Certification Investment | Accelerates product launch timelines for NMPA and EU F-Gas Regulation compliant commercial vehicle architectures. |
| Additive Manufacturing Qualification | Enables topology-optimized conformal cooling geometries for solid-state battery pre-production platforms. |
| Software-Defined Thermal Management Bundling | Creates recurring revenue streams through predictive maintenance subscriptions alongside hardware component sales. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and thermal system R&D directors. NMPA battery safety mandate documentation, EU F-Gas Regulation implementation guidance, and aluminum alloy customs import records provided validation anchors. Bottom-up cold plate unit estimates by vehicle architecture triangulated against top-down thermal management system value assessments.
Granularity-level modeling addressed type, material, application, and end-user dimensions across the projection horizon, with vehicle class and propulsion architecture as automotive-specific cross-cuts. CAGRs derived from segment-level unit growth and value-per-vehicle content trajectories. Forecast inputs incorporated 800V platform rollout assumptions, solid-state battery thermal profile evolution, and regional regulatory compliance threshold adjustments.
Revisions become necessary when NMPA or EPA thermal management mandates tighten beyond modeled scenarios, or when aluminum price volatility exceeds historical bands. Forecasts reflect documented assumptions regarding machining capacity expansion rates and OEM captive integration decisions. A model refresh is warranted upon material change in solid-state battery commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Solar Car Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
Poland E-Bike Market
Electric Vehicles
China Solar E-Bike Market
Electric Vehicles
Global EV Relay Market
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market
Electric Vehicles
Asia-Pacific Electric Bus Battery Pack Market
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
EV Transmission System Market
Electric Vehicles
Automotive Battery Pack Compression Pad Market
Electric Vehicles
E-Bike Market
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market
Electric Vehicles
Belgium E-Bike Market
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
US Electric Mobility Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market